EU and India agree comprehensive free trade agreement

The European Union and India have concluded a comprehensive free trade agreement, marking a significant step in strengthening economic relations between the two markets after negotiations that began in 2007 and were repeatedly suspended.

According to Sonali Chowdhry, trade expert at DIW Berlin, the agreement comes at a strategically important moment for both sides. India is expected to maintain strong economic growth in the coming years and is projected to become one of the world’s three largest economies by the end of the decade, increasing the importance of EU access to the Indian market.

Trade relations between the European Union and India are already extensive, with more than 170,000 buyer-supplier relationships between companies on both sides. The agreement aims to deepen these ties by reducing tariffs and non-tariff barriers across a range of sectors.

For EU exporters, the deal is expected to improve market access in industries such as automotive, engineering and beverages. At the same time, Indian exports including pharmaceuticals, IT services and textiles are set to benefit from improved access to the EU market.

Beyond direct trade effects, Chowdhry notes that the agreement also has a broader systemic role. By establishing binding commitments on transparency and market access, the agreement is intended to enhance predictability in international trade at a time when global trade rules are increasingly under pressure. In this context, the EU–India agreement is seen as a counterweight to rising protectionist trends and a measure to support the stability of the global trading system.

Source: DIW Berlin

Colliers Romania: 2026 will be a year of adjustment, repositioning and strategic decisions

After several years of rapid growth followed by corrections, Romania’s real estate market is entering a phase of slower development amid fiscal pressures and continued geopolitical uncertainty. According to Colliers’ report Top 10 forecasts for the Romanian real estate market in 2026, the year ahead will be defined by adjustment and repositioning rather than expansion, with disciplined investment and strategic selectivity becoming more important than scale.

Colliers sees 2026 as a year of stabilisation and preparation for the next growth cycle, not a rapid recovery. While economic conditions remain challenging, infrastructure investment, a gradual return of private capital and uneven performance across segments may still create opportunities for investors with a medium-term horizon.

Romania’s economy is expected to grow by just over 1% in 2026, broadly in line with 2025, though risks remain elevated. Fiscal consolidation, political complexity and an unstable external environment will weigh on growth, while EU funds and a potential easing of monetary policy from the second quarter could provide limited support. Any improvement in Romania’s sovereign outlook is more likely towards the end of the year, contingent on consistent implementation of fiscal measures.

Transport infrastructure could be one of the main positive drivers in 2026, with over 300 kilometres of motorways and express roads potentially delivered if current timelines are maintained. These EU-funded projects are expected to boost the attractiveness of secondary cities, ease pressure on Bucharest and unlock new development locations, although administrative and political risks remain.

Inflation is expected to resume a downward trend, allowing for a gradual easing of monetary policy. The National Bank of Romania may cut the policy rate by around one percentage point, potentially starting in the second quarter. Colliers notes that lower rates are likely to stabilise market sentiment rather than trigger a sharp rebound in demand.

The budget deficit remains a key vulnerability. Reducing it from an estimated 7.7% of GDP in 2025 towards around 6% in 2026 will be challenging, making fiscal predictability and disciplined implementation critical for investor confidence and financing costs.

The office market enters 2026 in a landlord-favourable position due to limited new supply and high development costs. After no new office deliveries in Bucharest in 2025, projects are gradually returning, but volumes remain insufficient to ease the shortage of high-quality space. Demand is increasingly focused on energy-efficient, well-located buildings, supporting upward pressure on prime rents and widening the gap with older stock.

The industrial and logistics sector is expected to remain resilient, supported by infrastructure expansion and more diversified demand. While leasing volumes may ease from the 2025 peak, interest from manufacturing, strategic industries and Asian investors is increasing. High construction and financing costs may constrain new supply, supporting rents for well-located assets.

Retail is expected to remain stable despite pressure on consumer spending. Romania’s structural undersupply of modern retail space continues to support medium-term growth, particularly in secondary and mid-sized cities. Around 240,000 sqm of new retail space is forecast for delivery in 2026, the highest level since 2011.

Investment activity could begin to recover gradually in 2026 as yields stabilise in Western Europe and risk appetite improves. Prime assets may see modest yield compression, while the gap between high-quality and secondary properties is expected to widen further.

Colliers also anticipates a stronger land market, with renewed interest in plots for residential, industrial and retail developments. Cash-rich investors and flexible structures, including joint ventures, are expected to play a larger role.

The residential market will remain under pressure due to insufficient supply. High construction costs, financing constraints and administrative delays continue to limit new deliveries, while demand remains resilient in major cities. As a result, price pressure is expected to persist, and interest in PRS projects is likely to increase, driven by strong rental demand and reduced housing affordability.


Stress and physical strain emerge as growing challenges in office workplaces

Employee stress is increasingly being recognised as an organisational issue rather than an individual concern, as companies face the combined effects of fast-paced work environments, constant digital exposure and limited opportunities for recovery. Recent research indicates that almost half of employees in Poland experience stress on a daily basis, with the share rising to more than half among younger workers entering the labour market.

Studies cited by ManpowerGroup suggest that work-related stress now affects a broad cross-section of employees, regardless of role or seniority. Many workers also struggle to regenerate outside working hours, often replacing one form of stimulation with another through prolonged use of digital devices and social media.

Physical strain adds to this pressure. Long periods of sitting, limited movement and constant sensory input are common features of office work and are increasingly linked to health complaints. Research on sedentary work shows that more than two-thirds of office employees experience lower back pain, while a large majority report that such discomfort negatively affects their concentration and productivity.

In response, employers are reassessing the role of workplace benefits. While traditional offerings such as basic healthcare packages or sports cards remain widespread, surveys indicate that many employees consider existing benefit schemes outdated or underused. Data referenced by Pluxee show that a significant proportion of benefit budgets do not translate into meaningful support for staff, despite employees broadly associating benefits with improved wellbeing.

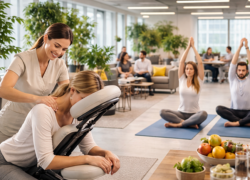
As expectations shift, particularly among younger generations, there is growing interest in solutions that provide immediate and practical relief during the working day. Companies seeking to encourage more frequent office attendance are increasingly experimenting with on-site initiatives such as short massage sessions, yoga classes or organised meals, which do not require additional time outside working hours.

Experts point out that the most effective approaches tend to be part of a wider wellbeing strategy rather than isolated actions. Programmes combining ergonomic advice, stress management workshops and regular micro-breaks are seen as more likely to deliver lasting benefits. Some larger organisations have introduced coordinated wellbeing initiatives that link physical care with broader health awareness campaigns.

Practitioners working directly with companies report that many employees show clear signs of overstimulation. According to Marta Miłosz-Sikorska, owner of the Holi Bali massage studio in Łódź, short in-office treatments often provide employees with their first genuine pause of the day, allowing them to disengage briefly from constant demands and return to work with improved focus.

Surveys indicate that employee benefits play a role in employer perception, with a large share of workers stating they would recommend their workplace based on the benefits offered. While measures such as workplace massage or yoga are not a solution to all stress-related issues, they are increasingly viewed as practical tools that support recovery and resilience. For employers, such initiatives represent a tangible investment in employee health and engagement, while for staff they may serve as an additional incentive to spend time in the office and strengthen workplace relationships.

Panattoni secures €42m loan for Szczecin Trzebusz II logistics project

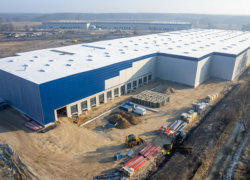
Panattoni has obtained financing of €42 million from BNP Paribas Bank Polska to support the construction of two warehouse buildings within the Panattoni Park Szczecin Trzebusz II development.

The investment is currently under construction. The first phase includes a warehouse with a total area of 25,500 sq m, of which 15,500 sq m has been pre-leased to Rohlig SUUS Logistics. A second building, providing an additional 36,000 sq m of warehouse space, is planned as the next stage of the project.

According to Panattoni, the financing will support the further expansion of its logistics portfolio in the Szczecin region, where the company has already delivered close to 900,000 sq m of industrial space. The developer views the project as part of its longer-term strategy in Western Pomerania.

Panattoni Park Szczecin Trzebusz II is located in the eastern part of Szczecin, approximately 15 kilometres from the city centre and around 160 kilometres from Berlin. The site benefits from access to the S3 expressway and the A6 motorway, providing connections to both domestic and international transport routes. The proximity of the Port of Szczecin is also cited as a logistical advantage.

The development is planned in line with Panattoni’s standard specifications and is expected to seek BREEAM certification at the Excellent level.

Housing completions in Poland expected to rise modestly in 2026

The number of newly completed apartments delivered by residential developers in Poland is expected to increase in 2026, following a recovery that began last year after a period of declining output. Industry estimates suggest that completions could reach around 140,000 units this year, compared with approximately 134,000 units delivered in 2025.

The improvement comes after two weaker years, as development activity slowed in response to rising interest rates and shifting demand conditions. The higher number of apartments completed in 2025 reflected projects that were launched roughly two years earlier, when market conditions were more favourable. Last year’s outcome therefore marked a turning point, with completions rising by around eight percent compared with the previous year.

The outlook for 2026 is linked mainly to the strong level of construction starts recorded in 2024, when developers initiated a large number of projects. Given typical construction timelines, these schemes are now moving toward completion, supporting expectations of a further increase in housing supply. If realised, the projected volume would bring the market closer to the levels seen during the peak years earlier in the decade.

In 2025, developers began construction on nearly 130,000 apartments. This result was achieved despite relatively high borrowing costs and an unusually large stock of homes already available for sale, factors that encouraged a more cautious approach among investors. Compared with the previous year, the number of new projects launched declined, reflecting the absence of extraordinary demand stimuli and a more balanced, market-driven pace of activity.

Recent months have brought some easing of financing conditions and signs of renewed buyer interest, which may help sustain development activity in the near term. However, maintaining such high levels of output over a longer period could prove challenging, given the still-elevated supply of unsold units in some markets.

Looking further ahead, industry representatives expect the number of newly launched residential projects to stabilise rather than grow sharply, with annual figures likely to remain broadly in line with current levels. This reflects a balance between gradually improving demand and the need to absorb the existing housing stock.

At the same time, the number of building permits issued last year declined compared with 2024, pointing to a more measured pipeline of future projects. Developers have increasingly focused on selling completed or near-complete apartments rather than expanding aggressively into new schemes, a trend particularly visible among smaller companies and in cities where supply has risen rapidly.

Overall, the residential market is entering 2026 with signs of stabilisation rather than rapid expansion. While the expected increase in completed apartments indicates a healthier development cycle, the sector remains shaped by cautious planning, selective investment and close attention to demand conditions.

Improving liquidity in Poland’s tourism sector ahead of winter holidays

Poland’s tourism industry is entering the winter holiday season with signs of improving financial stability, as overdue debts among hotels and travel agents continue to decline. According to the latest data from BIG InfoMonitor and the BIK, the total outstanding liabilities of hotels and tourist agencies remain close to PLN 1 billion, but the overall trend points to a gradual reduction. At the same time, consumer sentiment remains cautious, with households increasingly prioritising savings over discretionary spending.

Data from the registries show that overdue debt in the hotel sector declined by around seven percent year on year, while liabilities among travel agents fell by approximately 3.5 percent. Hotels are entering the winter season with outstanding obligations totalling PLN 842.4 million, a level that reflects continued improvement compared with previous years. Despite this progress, the sector still faces challenges related to payment discipline, as the share of companies struggling with timely settlement of liabilities remains higher than the economy-wide average.

An analysis of developments over the past three years highlights a gradual stabilisation of the tourism sector’s financial position. At the end of November 2023, overdue hotel debt stood at PLN 938.2 million. A year later, the total declined to PLN 905.1 million, although the number of indebted entities increased. The most recent data from November 2025 show a clearer improvement, with arrears falling to PLN 842.4 million and the number of indebted hotels decreasing. Even so, between 7.5 and 8 percent of hospitality companies continue to face payment difficulties, compared with around 4.5 to 5 percent across the broader economy.

Regional data indicate uneven conditions across the country. In regions closely associated with winter tourism, such as Silesia and Lower Silesia, the tourism sector’s outstanding debt remains relatively high, at PLN 92.5 million and PLN 84.2 million respectively. However, the downward trend seen in recent years has allowed businesses in these areas to enter the season with greater confidence. In Małopolska and Podkarpacie, regions popular with winter sports enthusiasts, outstanding liabilities are lower, amounting to PLN 37.3 million and PLN 18.7 million respectively. Although Podkarpacie still records a relatively high share of companies with arrears, the situation has improved compared with previous years, suggesting a gradual rebuilding of financial stability even in more challenged areas.

A similar pattern can be observed among travel agents and tour operators. While demand for travel is spread more evenly throughout the year, peak periods such as winter holidays still translate into higher booking volumes and improved cash flow. After a difficult 2024, when the number of agencies with overdue liabilities increased, the latest figures show a recovery. Outstanding debt among travel agents now totals PLN 71.7 million, and the number of indebted entities has fallen, pointing to a gradual improvement in the sector’s financial position.

According to Paweł Szarkowski, President of the Management Board of BIG InfoMonitor, the data suggest that the tourism industry has moved beyond a survival phase and entered a period of gradual stabilisation. He noted that companies have increasingly been able to use the recovery in demand to strengthen their balance sheets, rather than merely financing day-to-day operations, and that the simultaneous reduction of debt in both hotels and travel agencies indicates that restructuring measures introduced after the difficult year of 2024 have had a lasting effect.

On the demand side, however, consumer behaviour remains cautious. Research commissioned by BIG InfoMonitor shows that many households are weighing travel plans against the need to build financial reserves. Around one in three respondents plans to save money for potential future difficulties, while 30 percent intend to travel this year and a further quarter have yet to make a decision. Savings have become a central theme for 2026, with more than one fifth of respondents planning to set aside larger sums than last year, often by cutting everyday expenses. For many households, winter trips and short holidays are increasingly seen as discretionary spending that can be reduced or postponed in favour of building a financial buffer.

This cautious approach reflects broader expectations about personal finances. A significant share of respondents expects their financial situation to remain unchanged in 2026, which directly influences decisions on travel and leisure. As a result, consumers are more likely to opt for cheaper accommodation, limit additional attractions or shorten trips.

Waldemar Rogowski, chief analyst at BIG InfoMonitor, said that today’s tourists are increasingly analysing costs and planning travel with greater care. In his view, the lack of expectations for a significant improvement in household finances means that while travel remains an important part of lifestyle choices, financial security is taking precedence. This, he added, poses a challenge for the tourism industry, which must respond not only with attractive offers but also with greater cost transparency and predictability.

Czech business and consumer confidence in January broadly stable, consumer sentiment declines

Confidence in the Czech economy remained largely unchanged in January 2026, with the composite economic sentiment indicator holding at the same level recorded in December, according to the Czech Statistical Office release based on the latest Business Cycle Surveys. The overall confidence indicator stayed at 100.2 points, slightly above its long-term average, reflecting a balance between modest gains in business sentiment and weaker consumer confidence.

The business confidence indicator increased marginally in January, rising by 0.6 points to 98.6, while the consumer confidence indicator declined by 2.8 points to 108.2. Among business sectors, sentiment improved in selected services, industry and trade, but fell in construction.

Specifically, confidence among service providers strengthened modestly in January, while industry and trade recorded smaller increases. In contrast, businesses in the construction sector reported a decline in confidence compared with December. The data suggest that firms in some sectors are more optimistic about near-term conditions, even as challenges persist in others.

Consumer confidence weakened during the month, with a larger share of households expressing expectations that the overall economic situation in the Czech Republic would deteriorate over the next year. At the same time, there was a slight increase in the share of households expecting an improvement in their own financial situation over the coming 12 months and a small rise in the proportion who view their current finances as worse than a year earlier. The number of consumers planning to forgo major purchases in the next year also increased.

The January survey results reflect data collected in mid-January and form part of the Czech Statistical Office’s ongoing monitoring of business and consumer attitudes. The surveys are used to gauge short-term economic trends and contribute to broader assessments of economic conditions in the Czech Republic.

The release also notes a change in the base period used to calculate the long-term average of the confidence indices. For 2026, the long-term average is calculated from January 2003 through December 2025, and this adjustment will be maintained in future January releases.

The next Business Cycle Surveys release is scheduled for 24 February 2026.

Source: CSO

Prague office completions fall to lowest level since records began

Developers in Prague completed just 26,600 sq m of new office space in 2025, marking the lowest annual volume since systematic monitoring began in 1993. Despite the limited supply, demand for office leasing last year exceeded the five-year average by eight percent, according to data compiled by the Prague Research Forum, which aggregates market information from leading real estate consultancies. By comparison, 72,800 sq m of office space was delivered in the Czech capital in 2024.

Only two office projects were completed in Prague during the final quarter of 2025. These included the PernerKarlín development, which delivered 9,300 sq m of space, and the reconstruction of the Panorama Airport Building, adding a further 2,000 sq m. In total, five office projects were completed during the year, compared with eight in 2024.

At the end of 2025, Prague’s total modern office stock stood at approximately 3.94 million sq m. A further 36,700 sq m of new office space is expected to be completed in 2026.

Construction activity is set to increase in the coming years, with around 263,300 sq m of office space currently under development and scheduled for completion between 2026 and 2028. Although this represents the highest volume of office construction since 2019, more than 60 percent of the space under construction has already been pre-let or occupied.

According to Petr Kareš, Head of Tenant Representation at iO Partners, the market currently offers only a limited amount of newly available office space. At the same time, some tenant companies are streamlining their operations and returning surplus space to the market. He added that several new development projects are in preparation and are expected to become available towards the end of 2027 and in the first half of 2028.

Construction started on two office schemes in Prague during the final quarter of last year. Passerinvest Group began work on the Orion building in Prague 4, which will provide 19,300 sq m of office space. Meanwhile, Mount Capital launched another phase of the E Factory redevelopment in Prague 9, where an additional 5,200 sq m of office space is planned.

Although overall leasing activity in 2025 was above average, demand weakened towards the end of the year. In the fourth quarter, office leasing volumes fell by 19 percent compared with the previous quarter and by 24 percent year-on-year. Tenant demand was concentrated primarily in Prague 5, followed by Prague 2 and Prague 1. Manufacturing companies accounted for more than 20 percent of the total leased area in the final quarter, ahead of pharmaceutical and healthcare occupiers.

Prime office rents in Prague remained unchanged in the last quarter of 2025. In the city centre, headline rents for new office space ranged between €29 and €30 per sq m per month. In inner-city locations, rents stood at €19.50 to €20.50 per sq m, while offices on the outskirts of Prague were offered at €15.50 to €16.50 per sq m.

Source: CTK

Prague tops Eastern Europe in cost of living ranking

Prague has been identified as the most expensive city in Eastern Europe in terms of overall cost of living, according to data from the Numbeo. The ranking combines everyday household expenses with housing and rental costs, offering a broader view of the long-term financial demands of living in individual cities. Bratislava and Warsaw followed Prague in the regional comparison, while Budapest ranked noticeably lower.

The combined index reflects prices of food, services, transport, restaurants and energy, while also factoring in rent levels. By linking daily expenses with housing costs, the index aims to show how financially demanding it is to live in a city over time, rather than focusing solely on short-term consumer spending.

According to analysts, housing plays a decisive role in Prague’s position at the top of the ranking. David Eim, analyst at Cheetah Finance, pointed to the long-term shortage of new residential construction in Prague and other large cities, which has failed to keep pace with demand. This imbalance, he said, has driven up both property prices and rents, increasing pressure on household budgets.

While the differences in basic living costs across the region’s cities are relatively moderate, the inclusion of housing costs clearly pushes Prague ahead of its peers. Lukáš Raška, an analyst at Port, said that expensive housing and related costs account for a substantial share of household expenditure in the Czech capital. In his view, rents and property prices in Prague have risen faster than wages for a prolonged period, while the supply of new apartments remains limited. As a result, even households with comparatively higher incomes spend an above-average share of their budgets on housing.

Other Czech cities such as Brno, Ostrava and Plzeň ranked significantly lower than Prague in the combined index, suggesting that high living costs are concentrated primarily in the capital rather than across the country as a whole. Daniel Horňák, analyst at Bidli, noted that Prague has long been the most expensive city in the region in terms of both owner-occupied and rental housing. He also highlighted that four Czech cities appear among the twelve most expensive in Eastern Europe, underlining the strong concentration of price pressures in larger urban centres.

At the same time, Horňák added that the rental market in Prague may be approaching its limits for further growth, while other regions could still see room for increases.

Numbeo operates as a global database on the cost of living and quality of life, drawing on millions of price observations submitted by contributors worldwide. Its datasets cover housing prices, consumer costs, transport, healthcare and other indicators, allowing for international and regional comparisons.

Source: CTK

Czech apartment rents rise 16% year-on-year in the fourth quarter

Rents in the Czech Republic rose by 16 percent year-on-year to an average of CZK 19,529 in the fourth quarter of 2025, according to an analysis by UlovDomov.cz. Compared with the third quarter, rents increased by a further four percent. The data also show that, in many cases, monthly mortgage payments for purchasing an apartment remain almost twice as high as the cost of renting.

According to Michal Hrbatý, director of UlovDomov.cz, the figures confirm continued upward pressure on rents in larger cities, particularly for smaller apartments with layouts of 1+kk and 2+kk. These units are most in demand among individuals, couples and students. The strongest percentage increases were recorded in Brno, Ostrava and Olomouc, especially for newer and smaller apartments.

In Prague, rents increased by between seven and 13 percent compared with the fourth quarter of 2024. On a quarter-on-quarter basis, however, rents in the capital were mostly lower. A similar pattern was observed in Brno, where rents rose by one to 17 percent year-on-year, while prices remained largely stable compared with the previous quarter.

Ostrava saw a more differentiated development. Rents for modern and smaller apartments increased markedly on a quarter-on-quarter basis, with 2+kk and 3+kk units rising by around 14 percent. In contrast, rents for layouts such as 1+1, 2+1 and 3+1 declined by between two and seven percent.

At the end of 2025, the average rent for a 2+kk apartment stood at around CZK 23,800 in Prague and approximately CZK 20,000 in Brno. In Ostrava, such an apartment rented for about CZK 15,290, while average rents reached CZK 16,510 in Olomouc and CZK 14,370 in Plzeň. For 1+kk apartments, average rents ranged from roughly CZK 9,860 in Ostrava to about CZK 17,700 in Prague. Larger 3+kk apartments were rented for around CZK 20,000 in Olomouc and Plzeň, while in Prague the average reached approximately CZK 34,000.

Despite rising rents, purchasing an apartment remains significantly more expensive on a monthly basis. According to the analysis, mortgage payments were still between 1.2 and 1.9 times higher than monthly rent. The average price per square metre of a renovated apartment in good condition was around CZK 151,100 in Prague and approximately CZK 118,000 in Brno. Repayment of a mortgage covering 90 percent of the purchase price over 30 years, at an average interest rate of 5.32 percent, would amount to about CZK 45,400 per month in Prague and roughly CZK 35,500 in Brno.

The smallest gap between rental and ownership costs was recorded in Ostrava, where monthly mortgage payments exceeded rents by around 20 to 30 percent.

Source: CTK

front page info
LATEST NEWS