Czech consumer confidence declines in January as business sentiment edges higher

Confidence in the Czech economy remained broadly unchanged in January, with the overall confidence indicator holding at 100.2 points, the same level as in December, according to the Czech Statistical Office (ČSÚ). A modest improvement in business confidence was offset by a decline in consumer sentiment. Overall confidence remains slightly above its long-term average.

Analysts said the latest figures are consistent with expectations of continued economic growth in 2026 at a pace similar to last year.

“The aggregate confidence indicator does not suggest any reversal of the positive trend in individual sectors,” said Petr Dufek, chief economist at Creditas Bank. At the same time, he added, the data do not point to a surge in demand or inflationary pressures. “The January results are in line with economic growth of just over two percent expected this year.”

The business confidence indicator rose by 0.6 points month-on-month to 98.6 points in January, while consumer confidence fell by 2.8 points to 108.2 points.

Among businesses, confidence declined only in the construction sector, where it dropped by 4.7 points compared to December. In contrast, confidence increased in selected services by 1.3 points, in industry by 0.5 points and in trade by 0.3 points. According to Jiří Obst, head of the ČSÚ’s short-term surveys department, the slight improvement was supported by lower inventories in industry, a more positive assessment of the economic situation in retail, and higher demand in selected services.

Despite the improvement in business sentiment, analysts noted that the industrial sector continues to lag behind other parts of the economy. “Manufacturing companies are still struggling with weak demand,” said Miroslav Novák, chief analyst at Citfin. “While business confidence in construction and market services has generally increased over the past two years, confidence in industry has effectively stagnated.”

Consumer confidence weakened at the start of 2026, mainly due to growing concerns among households about the overall economic situation in the Czech Republic over the next 12 months. At the same time, a slightly higher share of households expects an improvement in their own financial situation. The proportion of respondents who assessed their current financial position as worse than a year ago also rose marginally. In addition, more households reported that they do not plan to make major purchases in the coming year.

The month-on-month decline in consumer confidence was stronger than expected, according to Vít Hradil, chief economist at Investika. He suggested that concerns about potential international trade tensions, including statements by US President Donald Trump on import tariffs, may have influenced respondents during the survey period.

Compared with January 2025, the overall confidence indicator, as well as both the business and consumer indicators, remain at higher levels.

Source: CTK

Industrial zone planned near Starý Sedlo in cooperation between SUAS GROUP and Accolade

A new industrial zone is planned near Starý Sedlo in the Sokolov region, following the signing of a joint venture agreement between landowner SUAS GROUP and investment group Accolade Holding. The project is expected to cover 38.4 hectares and focus on the development of low-emission industrial halls. If permitting proceeds as planned, construction could begin in early 2027.

The project is intended to support the economic transformation of the Sokolov region, which has been affected by the decline of brown coal mining. According to the partners, the site is aimed at attracting companies from manufacturing, research and development, logistics and technology sectors, with the objective of diversifying the regional economy and creating skilled employment.

Under the joint venture, SUAS GROUP and Accolade will jointly prepare the site and seek tenants for the planned facilities. The first phase is expected to deliver approximately 170,000 sq m of gross leasable area.

Accolade has an established presence in the Karlovy Vary Region, having developed industrial zones in Cheb, Ostrov and Karlovy Vary. The group has also expressed interest in participating in the planned Strategic Business Zone in Cheb, although the city ultimately decided to continue preparations in cooperation with the state.

“The joint venture with SUAS GROUP allows us to move forward with the first project in this location, with a total rentable area of around 170,000 sq m,” said Milan Kratina, Executive Director of Accolade. “Our aim is to develop a modern industrial complex that contributes to the local and regional economy.”

David Chládek, Managing Director of SUAS Real Estate, said that the agreement enables the start of project design and permitting, alongside negotiations with potential tenants.

The area between Sokolov and Starý Sedlo could ultimately offer up to 170 hectares for industrial development. While the site was previously considered by the government for inclusion among strategic industrial locations, priority was eventually given to the Cheb industrial park, with Starý Sedlo remaining as a reserve option for future investors.

The land, currently used for agricultural purposes, is owned by Sokolovská uhelná and its affiliated company SUAS GROUP. The project was previously listed as a strategic initiative of the Karlovy Vary Region under the Fair Transformation programme, but SUAS GROUP later withdrew from the subsidy scheme, citing restrictive conditions.

The planned industrial zone, known as Staré Sedlo North, is located northeast of Sokolov near the E49 European road. Karlovy Vary lies approximately 20 km away, Cheb around 30 km, Plzeň about 80 km and Prague roughly 150 km. The proximity to the German border is also considered a logistical advantage.

Brno court to reassess ministry’s procurement in building permit digitalisation

The Regional Court in Brno will again review whether the Ministry for Regional Development acted lawfully when awarding one of the contracts linked to the digitalisation of the building permit process. The reassessment follows a ruling by the Supreme Administrative Court (NSS), which upheld appeals filed by the ministry during the previous electoral term and returned the case to the lower court for further examination.

According to the current leadership of the ministry, the NSS decision concerns procedural aspects of how the case was handled by the courts and administrative bodies, rather than responsibility for the technical or organisational problems that accompanied the launch of the digital system.

The dispute centres on a March 2024 decision by the Office for the Protection of Competition (ÚOHS), which prohibited the ministry from fulfilling a contract for a software environment intended to enable data and information sharing within the digital building permit system. ÚOHS concluded that the contract had been awarded through a negotiated procedure without prior publication, an exceptional method permitted only under narrowly defined conditions.

While the antimonopoly authority acknowledged that the ministry faced extremely urgent circumstances, it determined that these were largely self-inflicted. According to ÚOHS, the ministry had previously set unlawful conditions in an open tender, which contributed to subsequent delays and forced it into a time-pressured procurement process. The Regional Court initially dismissed the ministry’s lawsuit against the ÚOHS decision but must now reassess the case in light of the NSS ruling.

In its decision, the NSS stated that the ministry could not be regarded solely as a passive party responding to external pressures. The Regional Court is expected to examine whether the ministry acted as a reasonable and informed contracting authority, whether changes to the digital building permit architecture resulted from its own initiative or external influences, how legislative changes affected the process, and whether any administrative shortcomings played a role.

The disputed contract was awarded while the ministry was led by Ivan Bartoš (Pirates). The appeal to the NSS was filed during the tenure of his successor, Petr Kulhánek (STAN). The ministry is currently headed by Zuzana Mrázová (ANO).

In a statement issued following the ruling, the Ministry for Regional Development said the NSS decision should not be interpreted as questioning the existence of problems in the digitalisation of the building permit process. According to the ministry, those problems stem from decisions and procedures adopted by previous leaderships, which it says undermined system functionality and created legal uncertainty.

The digital building permit system was launched in 2024 and was accompanied by significant operational difficulties, drawing criticism from local authorities, developers and opposition parties. The controversy ultimately led to Bartoš’s dismissal from government and the departure of the Pirate Party from the governing coalition. The ÚOHS has also examined other contracts related to the digitalisation project in separate proceedings.

Source: CTK

Teta drugstore opens new store in Filadelfie shopping arcade

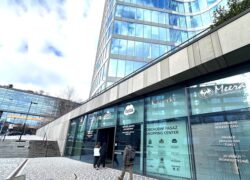
Teta drugstore has opened a new store in the shopping arcade of the Filadelfie building in the Brumlovka district of Prague 4. The unit occupies approximately 290 sq m and expands the range of everyday retail services available to employees working in the building as well as residents in the surrounding area.

The store offers a standard selection of drugstore goods, cosmetics, perfumes and household care products. It also provides photo printing services through CEWE, which are available in selected Teta locations.

Teta is one of the largest drugstore chains in the Czech Republic, operating a nationwide network of stores focused on everyday consumer needs. According to the company, the new location aligns with its strategy of placing outlets in modern office and mixed-use developments.

“The Filadelfie shopping arcade is an attractive location for us, which fits well with Teta’s strategy of developing stores in modern administrative centres. We want to be as close as possible to our customers and offer them a convenient shopping experience with a high-quality range of drugstore products,” said Martin Linhart, Director of Expansion at Teta drugstores.

The Filadelfie office building forms part of the wider Brumlovka development and combines office space with a ground-floor shopping arcade offering services for tenants and the public.

REALOGIS reports higher take-up in Hamburg’s logistics and industrial market in 2025

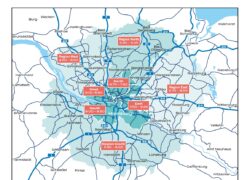
According to REALOGIS Unternehmensgruppe, take-up in Hamburg’s owner-occupier and leasing market for logistics and industrial properties reached 335,000 sqm in 2025. This represents an increase of 22% compared with 275,000 sqm recorded in 2024, although the result remains 17% below the five-year average of 406,000 sqm.

The five largest transactions were concluded by Körber Technologies, Mickeleit, Scan Global Logistics Group, Garpa Garten & Park Einrichtungen GmbH and Heinrich Dehn. Together, these deals accounted for around 32% of total take-up during the year.

Commenting on the figures, Stefan Imken, Managing Director of REALOGIS Immobilien Hamburg GmbH, noted that the rise in take-up should be viewed as an indication of stabilisation rather than a return to peak market conditions. He added that a gradual recovery is expected in 2026, supported by steady to improving demand from logistics and industrial occupiers and largely stable rental growth.

Rental levels in Hamburg remained broadly stable in 2025. Prime rent stood at €8.30 per sqm at year-end, slightly above the €8.25 per sqm recorded a year earlier. After peaking at €8.40 per sqm in mid-2025, prime rents eased modestly in the second half of the year. Average rents increased to €6.40 per sqm at the end of 2025, compared with €6.25 per sqm in 2024, having reached €6.50 per sqm in mid-year.

Market activity continued to focus mainly on existing buildings. A total of 224,300 sqm was leased in existing stock, accounting for 67% of take-up, compared with 84% in the previous year. New-build space accounted for 110,700 sqm, or 33% of total take-up, with the vast majority of this volume attributable to developments on brownfield sites. Transactions in new buildings on former brownfield land reached 109,200 sqm, while greenfield developments played only a marginal role, accounting for just 1,500 sqm.

Leasing activity again dominated the market. Tenants were responsible for 274,700 sqm, representing 82% of total take-up, while owner-occupiers accounted for the remaining 60,300 sqm. By building type, big-box logistics space led the market with 175,000 sqm, followed by other standalone properties and business parks.

From a regional perspective, Hamburg South emerged as the most active submarket in 2025, recording 141,400 sqm of take-up and a 42% market share. This marked a significant rebound compared with 2024, when the area had seen limited activity. Hamburg East followed closely with 131,900 sqm, while the West and North recorded considerably lower volumes.

By occupier sector, logistics and distribution companies clearly dominated demand, accounting for 209,900 sqm, or 63% of total take-up. Manufacturing occupiers accounted for 52,000 sqm, while retail and wholesale users leased 44,700 sqm. Within the retail and wholesale segment, demand was evenly split between e-commerce and traditional retail operators.

Demand was strongest for large units above 10,001 sqm, which together accounted for 131,000 sqm, followed by transactions in the 5,001 to 10,000 sqm range. Smaller units below 1,000 sqm represented only a small share of overall activity, continuing a trend toward larger space requirements among occupiers.

Romania’s Flex Office Market: Small Today, Structurally Set for Acceleration

A CIJ EUROPE Q&A with Tudor Popp, Managing Partner, Beyond Space

Romania’s flexible office market remains modest in absolute terms, but the latest Beyond Space, Flex Office Market Romania Q4 2025 study suggests that this is precisely what makes it structurally compelling. With coworking representing only around 2% of total office stock in Bucharest, compared to over 5% in London and nearly 4% in Barcelona, the market remains significantly underpenetrated by European standards. Yet the structural demand drivers, hybrid work models, corporate flexibility requirements and landlord-led diversification strategies, are already firmly in place.

The report’s central conclusion is clear: Romania is no longer debating whether flex offices work, but how fast they will scale. Large occupiers are increasingly using coworking not as a temporary bridge solution, but as a strategic extension of their real estate footprint, particularly for teams of 20 to 100 people, regional hubs and market-entry scenarios. White-labelled offices, where companies operate fully branded spaces powered operationally by coworking platforms, are also emerging as a preferred model for enterprises seeking corporate identity without long-term lease risk.

From a landlord perspective, flex space is evolving from a perceived risk to a value-creation instrument. Developers are increasingly integrating coworking into office campuses and mixed-use projects through partnerships or management models, positioning flex not as a competing product, but as an amenity, tenant-mix strategy and service-driven revenue layer.

While Bucharest remains the anchor market with an estimated 80,000 sqm of flexible office space, secondary cities such as Cluj-Napoca, Timișoara and Iași are where the long-term growth narrative becomes more structurally interesting. Limited supply, active tech ecosystems and SME demand suggest latent rather than absent demand dynamics.

At a conceptual level, the study frames a deeper shift: office value is moving from cost per square metre to value per person. In this context, flex offices are not competing with conventional leases on price, but on experience, speed, adaptability and human performance — positioning hospitality, wellbeing and community as productivity infrastructure rather than lifestyle extras.

CIJ EUROPE spoke with Tudor Popp, Managing Partner at Beyond Space, about the structural transformation of Romania’s flex office market, persistent misconceptions, and why the next growth phase will be driven as much by landlords as by occupiers.

CIJ EUROPE: If you had to point to one misconception about flex offices in Romania that the market still hasn’t shaken off, what would it be, and why does it matter?

Tudor Popp: There are several stubborn misconceptions, but they all come from the same misunderstanding of what coworking actually is. Some see coworking as a temporary fix until you’re “big enough” for a proper office. That’s like saying taxis are for people who can’t afford cars — you’re ignoring flexibility and convenience. Others picture hipsters on beanbags in cluttered, noisy open spaces. And then there’s the corporate crowd who think “flex” just means serviced offices with shorter lease terms.

All of these miss the point entirely. Coworking isn’t about what you can or cannot afford, it’s not about design gimmicks, and it’s not just smaller offices with flexible contracts. It’s a fundamentally different operating philosophy — one that prioritizes hospitality, adaptability, experience, community and wellbeing over fixed assets and transactional space. Some of the world’s most valuable companies choose coworking not because they don’t have other options, but because the model delivers something traditional leases simply can’t.

CIJ EUROPE: Looking ahead three to five years, which segment of demand will shape the Romanian flex office market the most: corporates, startups or landlords, and why?

Tudor Popp: The next years won’t be shaped by one segment alone, they’ll be defined by the convergence of all three. Landlords are increasingly building flex into their core offering rather than treating it as a niche add-on. Corporates are moving from pilot programs to strategic adoption as hybrid work becomes permanent. And startups continue to drive innovation in how space is used.

However, if I had to emphasize the most important one, it’s the landlords, because once building owners embed flex as standard infrastructure rather than outsourcing it, the entire market dynamic will shift.

CIJ EUROPE: Bucharest still lags behind Western European cities in coworking penetration. Do you see that as a structural limitation or as untapped upside?

Tudor Popp: It’s partly structural. Bucharest lacks the abundance of characterful buildings you see in Berlin, Barcelona, London or Lisbon. Large, monotonous floorplates in sterile buildings and a shortage of high-quality refurbishments of historical or industrial assets mean fewer spaces with the kind of soul and texture that make compelling coworking environments.

But it’s also behavioral. Before the pandemic especially, there was a corporate herd mentality, everyone was mimicking Google’s office aesthetic without understanding the culture or work philosophy behind it. Ping-pong tables and bright colors don’t create innovation; they’re symptoms of something deeper that you can’t just copy-paste. Bean bags and breakout spaces became checkbox items rather than intentional tools, which is exactly how we ended up with so many spaces that maybe look innovative but feel lifeless.

The good news is that this conservative mindset is breaking down, and the supply constraint is actually an opportunity. Developers who plan for smaller floorplates, natural light and meaningful design will capture disproportionate value.

CIJ EUROPE: From your experience, what separates flex spaces that genuinely perform over time from those that struggle once the initial novelty wears off?

Tudor Popp: The critical difference is understanding that you’re not running a managed office or a “business center” — you are building a community and an experience. Managed offices are just spaces: four walls, a desk, Wi-Fi, a reception desk, a kitchenette. They’re transactional, soulless and uninspiring. They don’t help people do better work or feel better while doing it — they just provide a location. And they do not help member companies attract or retain talent.

Flex spaces that genuinely perform over time reject that entire premise. They recognize they’re in the business of human experience, not square metre management. That means obsessive attention to community, to programming, to design that responds to how people work, think and connect. It means prioritizing wellbeing. Once the novelty wears off, what remains? In a managed office: nothing. In a real coworking space: a reason to come back every day that has nothing to do with your “flexible” lease terms.

CIJ EUROPE: If a developer or occupier takes just one strategic lesson from your study, what should it be when planning their next office decision?

Tudor Popp: Stop optimizing for cost per square metre and start optimizing for value per person. The future of offices is diverse, adaptive and experience-driven. Whether you’re a developer or an occupier, the winners will be those who design for flexibility and human experience first, then work backward to the financials. If your decision-making process starts and ends with spreadsheet efficiency metrics, you’re designing for a world of work that’s already disappearing.

CIJ EUROPE: the message from the Beyond Space Q4 2025 study is clear: Romania’s flex office sector may still look small on paper, but its fundamentals mirror where Western European markets stood several years ago. With hybrid work now structurally embedded and occupiers prioritising agility over permanence, flex space is positioned to move from the margins to a standard component of Romania’s office landscape over the next three to five years.

© 2026 cij.world

Cordia begins construction of Centropolitan residential project in Bucharest

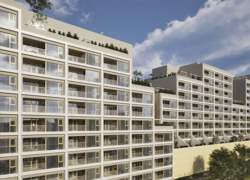
Cordia Romania, part of the Futureal Group, has acquired an 8,179 sqm land plot in Bucharest, located near Bucharest Mall and close to Alba Iulia Square. The site was purchased from Bog’Art Place and benefits from an issued building permit. Construction has now started on Centropolitan, a residential project comprising 274 apartments and approximately 3,345 sqm of retail space.

The land transaction was completed in September 2025. Cordia Romania was advised by Crosspoint Real Estate, international associate of Savills in Romania, together with the law firm Stratulat Albulescu.

Centropolitan will include one- to five-room apartments with sizes ranging from 42 to 156 sqm, most of which will feature terraces. The project also provides a range of shared amenities for residents, covering around 350 sqm, including a residents’ lounge, gastro bar, children’s play area, spaces for teenagers, coworking facilities, and fitness and yoga areas.

The development is planned as a mixed-use scheme, combining residential and retail functions. Its location places daily services and leisure options within short walking distance. Bucharest Mall is located nearby, while Alba Iulia Square and Unirii Square can be reached within a few minutes, supported by existing public transport connections and surrounding urban infrastructure.

Nicholas Brinckmann and Richard Apfelbacher appointed Managing Directors of BF.infrafinance

BF.infrafinance GmbH has appointed its co-founders Nicholas Brinckmann and Richard Apfelbacher as Managing Directors. The company, established in October 2025 as a joint venture between BF.direkt and the Fox Group, focuses on structuring debt solutions for logistics real estate developments on behalf of institutional investors.

BF.infrafinance’s mandate is to set up debt structures, primarily via Luxembourg vehicles, including funds and separate account mandates and to provide the resulting capital to property developers. The company reports a project pipeline with an aggregate loan volume of around €1.4 billion, of which approximately €300-400 million is currently under detailed review.

The firm is currently concentrating on whole-loan lending, with loan-to-cost ratios of up to 85%. Planned investment vehicles are expected to have maturities of six to eight years, while individual loans will typically run for about 24 months. Pricing is expected to reflect mid- to upper-single-digit annual interest rates, depending on project quality and planning status.

BF.infrafinance has assembled a team with experience across loan underwriting and servicing, including cash-flow management, covenant monitoring, reporting, collateral administration and compliance.

Richard Apfelbacher brings more than 20 years of investment experience. Prior to joining BF.infrafinance, he was Managing Partner at Sienna Real Estate (formerly L’Etoile Properties), where he led the expansion of the Germany platform and contributed to growth in assets under management across office, logistics and hospitality properties in Europe. He also serves on the advisory committee of the investment arm of an international logistics developer.

Nicholas Brinckmann previously spent nearly two decades as CEO of HANSAINVEST Real Assets (now SICORE Real Assets) and as Managing Director of HANSAINVEST Hanseatische Investment GmbH, both part of the Signal Iduna group. In those roles, he oversaw international real assets in 18 countries, including logistics portfolios of around €1.0 billion, and was responsible for establishing more than ten regulated investment vehicles. Earlier in his career, he held senior positions at MEAG MUNICH ERGO AssetManagement GmbH and Union Investment Real Estate GmbH.

Przystanek Karkonosze expands regional retail offer in Lower Silesia

Przystanek Karkonosze, a retail park developed by Redkom Development, opened in August 2025 and has since become an established part of the retail landscape in the Karkonosze region, an area traditionally dominated by local retail formats.

The scheme is located in Miłków, directly on a provincial road and at the junction of routes connecting Karpacz, Szklarska Poręba, Kowary and Jelenia Góra. This positioning provides convenient access for both local residents and visitors, supporting steady footfall throughout the year.

Przystanek Karkonosze offers approximately 15,400 sqm of gross leasable area. While the project’s architecture reflects its mountain surroundings, from a commercial perspective its wider catchment is of particular importance. The retail park attracts not only local customers but also international visitors, especially from the Czech Republic and Germany, who form a significant customer group in the region.

Key traffic generators at the site include Lidl Polska and a stand-alone McDonald’s restaurant with a drive-thru, both contributing to consistent daily customer flows.

The tenant mix has continued to evolve, with MR.DIY among the most recent openings. Other tenants include Lidl, Half Price, 4F, Martes Sport, Wojas, Sinsay, Ochnik, CCC, Rossmann, Pepco, Worldbox, Diverse, Action, New Yorker, Media Expert, TEDi and Douglas, alongside smaller service units such as a travel agency and a press shop.

Leasing at Przystanek Karkonosze is managed by Redkom Development in cooperation with Mallson Polska, with a focus on securing well-known retail brands across multiple categories.

Between 2023 and 2025, Redkom Development delivered more than 60,000 sqm of retail park GLA in Poland. Completed projects include Park Glinianka (now BIG Łubna) near Warsaw, Ozimska Park in Opole, Comfy Park Bielik in Bielsko-Biała and Przystanek Karkonosze near Karpacz. The developer is currently working on further schemes scheduled to open in 2026, totalling approximately 90,000 sqm of GLA, including projects in Bydgoszcz, Dzierżoniów, Lublin, Otwock and Białystok.

Logivest advises DSV on lease of approx. 9,000 sqm logistics space in northern Munich

Integrated logistics real estate advisor Logivest has advised Danish transport and logistics group DSV on the long-term lease of an existing property comprising close to 9,000 sqm of warehouse and office space in Garching, north of Munich.

DSV had been seeking a suitable location in the northern Munich area for one of its clients. Logivest identified an appropriate property in the Garching-Hochbrück industrial estate. The building benefits from direct proximity to federal roads B471 and B13, providing efficient access to the A9 and A92 motorways as well as the A99 Munich orbital motorway.

“Overall, we are seeing continued growth in demand for existing logistics properties,” said Alexander Dempfle, Consultant Industrial and Logistics Letting at Logivest in Munich. “Garching-Hochbrück offers high-quality space and benefits from its strategic position in the Munich metropolitan area, with strong links to the city centre, surrounding municipalities and Munich Airport.”

The property provides more than ten loading docks equipped with dock levellers, alongside ample external manoeuvring space to support efficient logistics operations.

DSV is scheduled to take possession of the facility in January 2026.

front page info
LATEST NEWS