Romania’s Property Market Faces Mounting Pressure as Cadastre Disruption Persists

Romania’s real estate and construction sectors are experiencing growing disruption as the prolonged outage of the National Agency for Cadastre and Land Registration (ANCPI) continues to delay essential property registration services. What initially appeared to be a cybersecurity incident has evolved into a wider challenge affecting businesses, financial institutions, investors and public infrastructure projects.

The Romanian College of Surveyors has urged the Government and Parliament to introduce emergency measures aimed at reducing the economic impact of the interruption, warning that thousands of professionals are unable to complete projects or receive payment despite continuing to meet their financial obligations. Comunicat Colegiul Geodezilor 31.07.2026.docx

Property Transactions Grind to a Halt

The interruption of ANCPI’s digital services has significantly slowed the processing of cadastral documentation required for property transfers, mortgage approvals and land registration. Without access to these systems, surveyors cannot finalise technical documentation, while notaries, developers and lenders are unable to complete many transactions that depend on official land records.

Industry organisations estimate that more than 10,000 authorised surveyors and companies are directly affected by the disruption. Although fieldwork and technical surveys can continue in many cases, projects cannot advance through the administrative stages needed for completion and payment. Comunicat Colegiul Geodezilor 31.07.2026.pdf

Government authorities have confirmed that the outage resulted from a cyberattack targeting ANCPI’s IT infrastructure. Officials have stated that the country’s central cadastral database remains intact, but rebuilding affected systems and restoring full digital services has proven to be a complex process.

Cash Flow Challenges Intensify

For surveying firms, the operational disruption has quickly become a financial one.

Many companies have already incurred the costs of carrying out surveys, employing staff, purchasing equipment and travelling to project sites. However, because completed work cannot be officially processed through ANCPI, invoices cannot be issued and revenues remain frozen.

At the same time, businesses continue to face payroll expenses, tax liabilities, loan repayments and equipment leasing costs. Professional organisations warn that prolonged delays could result in liquidity problems, reduced employment and the suspension of business operations across the sector.

Ripple Effects Across the Economy

The consequences extend well beyond surveying companies.

Property developers cannot complete acquisitions, banks face delays in mortgage approvals, infrastructure schemes encounter administrative bottlenecks and local authorities experience slower progress on public investment projects. Architects, engineers, legal professionals and construction contractors are also encountering delays as projects wait for the completion of mandatory cadastral procedures.

As a result, the interruption is beginning to affect multiple parts of Romania’s investment environment, particularly where land registration forms a prerequisite for financing, permitting or construction.

Industry Calls for Temporary Relief

In response to the ongoing disruption, the Romanian College of Surveyors has proposed a series of temporary measures designed to protect businesses until normal operations resume.

Among its requests are official recognition that project delays stem from circumstances outside the control of professionals, extensions to administrative and contractual deadlines, temporary suspension of penalties linked to missed deadlines, deferred tax obligations and financial support for firms experiencing significant revenue losses.

The organisation has also proposed temporary procedures that would allow documentation to be processed through alternative channels, together with a coordinated recovery programme to manage the large backlog expected once ANCPI’s systems become fully operational again. Comunicat Colegiul Geodezilor 31.07.2026.docx

Recovery Will Extend Beyond System Restoration

Even after digital services resume, industry participants expect processing times to remain under pressure as thousands of delayed applications enter the system simultaneously. Managing that backlog efficiently will be critical to limiting further disruption to the property market.

Authorities continue working to restore ANCPI’s digital infrastructure, while cybersecurity specialists investigate the incident and strengthen system resilience against future attacks.

The episode has highlighted how dependent Romania’s real estate sector has become on digital public services. For investors, developers and financial institutions, the challenge now extends beyond restoring technology to ensuring that administrative processes can return to normal without creating prolonged delays for property transactions and investment activity.
Japan’s Property Market Enters a New Chapter as Growth Becomes Increasingly Localised

Japan’s real estate market is no longer moving in a single direction. Instead, it is evolving into a collection of distinct regional markets, where economic strength, population trends and investment activity increasingly determine local performance.

The country’s largest metropolitan areas continue to attract businesses, residents and international capital, while many smaller cities and rural communities are facing declining populations and weakening housing demand. This growing divergence is reshaping investment strategies and influencing where developers, lenders and institutional investors choose to allocate capital.

Metropolitan Areas Continue to Attract Investment

Tokyo remains the dominant force in Japan’s property market. Strong employment, extensive infrastructure investment and a steady flow of domestic migration have helped maintain demand for residential, office and mixed-use developments despite higher construction costs.

Large-scale regeneration projects in districts such as Yaesu, Toranomon, Shibuya and Shinagawa are creating new commercial centres that combine workplaces, housing, hotels, retail and public spaces. These developments continue to strengthen the capital’s appeal for both occupiers and investors.

Other major cities, including Osaka, Fukuoka and Nagoya, are also benefiting from corporate expansion, tourism and infrastructure improvements, although growth remains more moderate than in Tokyo.

Premium Housing Maintains Momentum

Demand for quality residential property has remained resilient in central Tokyo, where limited development land and rising construction costs continue to support pricing.

Luxury apartments have attracted attention from both Japanese buyers and overseas investors seeking stable assets in an established legal and financial environment. The comparatively weak yen has further increased Japan’s appeal to international purchasers looking for long-term investment opportunities.

While overseas buyers remain most active in the premium segment, domestic purchasers continue to account for the majority of housing transactions across the wider market.

Rental Market Regains Strength

Japan’s rental sector has also entered a period of gradual change. In central Tokyo, population growth and limited housing supply have contributed to stronger rental performance than the market experienced during much of the previous decade.

Institutional investors continue to increase allocations to multifamily residential assets, attracted by high occupancy rates and improving rental income. The sector has become one of the country’s most stable real estate investment classes, particularly for long-term income-focused investors.

Outside the largest cities, however, rental markets remain considerably weaker, reflecting slower population growth and lower household formation.

Regional Japan Faces Different Challenges

Away from the country’s major metropolitan areas, demographic trends continue to influence property performance.

Many regional municipalities are experiencing population decline as younger residents relocate in search of employment and educational opportunities. This has reduced housing demand in numerous communities and contributed to a growing inventory of vacant residential properties.

Local governments are responding through redevelopment initiatives, renovation grants and programmes designed to attract new residents, entrepreneurs and remote workers. While these measures have achieved positive results in selected locations, reversing long-term demographic trends remains a significant challenge.

At the same time, some regional cities are benefiting from new economic drivers. Semiconductor investment in Kyushu, tourism growth in Hokkaido and redevelopment projects in several provincial centres demonstrate that regional success increasingly depends on the strength of local industries rather than broader national trends.

Sustainability Shapes Future Development

Environmental performance is becoming a more important consideration throughout Japan’s property sector. Developers are placing greater emphasis on energy-efficient buildings, carbon reduction and resilient design, while investors increasingly evaluate long-term operating costs alongside financial returns.

Modern buildings that combine sustainability with earthquake-resistant construction are attracting stronger investor interest than ageing assets that require extensive upgrades. Consequently, refurbishment projects have become an important part of Japan’s property market, extending the life of existing buildings while improving their environmental performance.

Infrastructure Remains a Competitive Advantage

Japan’s extensive transport network continues to support real estate values in well-connected locations. New railway stations, urban regeneration schemes and improvements to public transport are helping create opportunities for both commercial and residential development.

Areas with strong accessibility continue to outperform locations where transport links and employment opportunities are more limited, reinforcing the importance of connectivity in investment decisions.

Outlook

Japan’s property market is entering a period where success will depend less on nationwide trends and more on local economic fundamentals.

Major metropolitan areas are expected to remain the primary destinations for investment, supported by redevelopment, international capital and resilient occupier demand. Selected regional cities with expanding industries are also likely to generate attractive opportunities.

Meanwhile, communities facing population decline will increasingly focus on regeneration, adaptive reuse and improving the quality of existing housing rather than expanding supply.

For investors, the Japanese market is becoming increasingly selective. The strongest prospects are likely to be found in locations that combine economic growth, modern infrastructure and sustainable development, while areas lacking these advantages may continue to face slower growth and weaker demand. Rather than one national property story, Japan is evolving into a market where local dynamics will determine long-term success.

Source: © CIJ.World Japan Research & Analysis Team

Europe’s Carbon Border Policy Forces Indian Exporters to Adapt

The European Union’s climate policies are beginning to reshape international trade, with Indian manufacturers among those facing new commercial realities. As Europe tightens environmental standards on imported goods, exporters selling carbon-intensive products into the EU will need to meet stricter reporting requirements while remaining competitive in one of their most important overseas markets.

The EU introduced its Carbon Border Adjustment Mechanism (CBAM) to ensure that imported products face a carbon cost comparable to goods produced within the bloc. The policy aims to discourage companies from shifting production to countries with less demanding environmental regulations while supporting Europe’s long-term objective of reducing greenhouse gas emissions.

The framework currently applies to sectors such as iron and steel, aluminium, cement, fertilisers, hydrogen and electricity. Following an initial reporting phase, the system is now moving towards full implementation, making emissions data an increasingly important part of international trade.

Steel Industry Faces the Greatest Challenge

Among India’s export industries, steel is expected to experience the largest impact. Many Indian steel plants continue to rely on production methods with relatively high carbon emissions, making exports more vulnerable to additional costs linked to Europe’s carbon pricing system.

Several economic studies suggest that Indian steel shipments to the European market could decline once the mechanism is fully reflected in trading costs. While estimates differ depending on the assumptions used, researchers generally agree that higher carbon-related costs will reduce the competitiveness of some Indian producers compared with manufacturers operating lower-emission facilities.

For companies that depend heavily on European customers, maintaining market share may increasingly depend on improving production efficiency and reducing the carbon footprint of manufacturing operations.

Aluminium Producers Also Under Pressure

The aluminium sector faces similar challenges. Producing primary aluminium requires large amounts of electricity, meaning the environmental impact varies significantly depending on the energy source used during production.

Facilities powered by cleaner energy sources are likely to be in a stronger competitive position than those relying on fossil fuel-generated electricity. As European buyers become more focused on embedded emissions, manufacturers with lower-carbon production processes could gain a commercial advantage.

Environmental Data Becomes a Business Requirement

The new rules place considerable emphasis on accurate emissions reporting. Exporters will need to provide detailed information about the carbon emissions associated with individual products rather than relying on broad sustainability commitments.

For many businesses, this means investing in emissions monitoring systems, independent verification and digital reporting processes. These additional requirements create new administrative and financial costs, particularly for companies that have not previously measured emissions at a detailed operational level.

European importers are also expected to place greater value on suppliers capable of providing reliable environmental data. As a result, transparency is becoming an important factor alongside price, quality and delivery performance when selecting manufacturing partners.

Smaller Businesses Could Feel a Greater Impact

Large industrial groups generally have greater financial resources to invest in emissions monitoring, specialised staff and cleaner production technologies. Smaller exporters, however, may find the transition more difficult.

Many small and medium-sized manufacturers already operate under pressure from higher financing costs, inflation and volatile raw material prices. Additional compliance expenses could further reduce profit margins and make participation in European supply chains more challenging.

This may encourage smaller businesses to collaborate with industry associations, technology providers and government-supported programmes to improve reporting capabilities while sharing compliance costs.

Limited National Impact but Significant Sectoral Effects

Although CBAM has attracted considerable attention, economists generally expect its effect on India’s overall economy to remain relatively modest because the mechanism covers only selected industries.

However, the impact is unlikely to be evenly distributed. Companies operating in sectors directly affected by the policy could experience higher production costs, tighter margins and increased competition, while businesses outside the covered industries may notice little immediate change.

For export-oriented manufacturers, the challenge is less about the national economy and more about protecting profitability within specific product categories where Europe remains an important customer.

Opportunity Through Modernisation

While the policy creates short-term challenges, it also provides an incentive for manufacturers to modernise operations. Investment in cleaner production technologies, renewable energy, improved energy efficiency and digital emissions monitoring can strengthen long-term competitiveness, not only in Europe but across global markets where sustainability requirements continue to increase.

Industrial companies that move quickly to improve environmental performance may find themselves better positioned to secure international contracts as buyers increasingly consider carbon intensity alongside traditional commercial factors.

As climate-related regulations become more closely linked with international trade, environmental performance is evolving from a compliance issue into a strategic business consideration. For Indian exporters, adapting to these new expectations may prove essential for maintaining access to one of the world’s largest and most valuable export markets.

Source: © CIJ.World India Research & Analysis Team

Poland Introduces Sweeping New Insurance Distribution Rules

The Polish Financial Supervision Authority (Polish FSA) has adopted a comprehensive new set of recommendations governing insurance distribution, marking the most significant overhaul of the country’s regulatory framework in more than a decade.

Published on 29 June 2026, the new guidance replaces the regulator’s 2014 distribution guidelines and expands the framework from 12 recommendations to 29. The measures will take effect from 1 July 2027, while specific provisions relating to the savings component of life insurance products will be introduced a year later, on 1 July 2028.

Broader Impact Across the Insurance Market

Although the recommendations are formally directed at insurance companies, their practical impact extends well beyond insurers. The new rules will also affect insurance intermediaries operating in Poland, including agents and brokers based in other European Union member states that provide services in the Polish market either through local branches or under the EU’s freedom to provide services regime.

Recommendations covering intermediary oversight, remuneration, support and compliance obligations are expected to reshape relationships between insurers and their distribution networks, making Poland’s approach one of the more far-reaching within the European insurance sector.

Stronger Focus on Customer Value

A central element of the new framework is the requirement that insurance products deliver demonstrable value to customers.

The Polish FSA expects insurers to ensure that the expected value of claims and benefits remains proportionate to premiums paid. In general, products should generate expected claims and benefits worth at least 30% of anticipated gross premiums, while lower-cost insurance products are subject to a minimum threshold of 20%.

This value-based assessment, previously associated primarily with certain credit protection insurance products, will now apply across a much broader range of insurance products and distribution channels. Several specialist products, including large-risk insurance, annuities, insurance guarantees and selected pension products, remain outside the scope of these requirements.

For life insurance products that include an investment or savings element, regulators have also introduced a maximum annual cost impact threshold of 2.65%.

New Rules for Remuneration

The recommendations introduce enhanced governance over remuneration structures for employees, agents and distributors.

Insurance companies are expected to establish remuneration policies that promote customer interests rather than purely sales-driven objectives. Variable compensation and incentive schemes should increasingly incorporate qualitative performance indicators alongside commercial targets.

Suggested assessment criteria include customer complaints, satisfaction surveys, mystery shopping results, policy cancellations, reasons for rejected claims and outcomes of legal disputes, reflecting a stronger emphasis on service quality and customer outcomes.

Greater Oversight of Insurance Agents

The updated framework strengthens insurers’ responsibilities for supervising their distribution partners.

Beyond monitoring legal compliance and registration requirements, insurers are expected to provide agents with ongoing guidance, training and operational support. The recommendations also encourage corrective actions before disciplinary measures are imposed, creating a more structured framework for cooperation between insurers and intermediaries.

The regulator has also clarified that agents should have a clear basis for requesting assistance from insurers where necessary.

More Flexible Customer Needs Assessment

The Polish FSA has adopted a more practical approach to assessing customers’ insurance needs than originally proposed during consultations.

If customers decline to provide information needed for a needs assessment, insurers must explain the consequences of withholding that information rather than automatically preventing the sale. Companies are also required to maintain appropriate documentation demonstrating that recommended policies match customer requirements, while retaining flexibility over how those records are created across different distribution channels.

For policy renewals, insurers may continue using previously collected customer information provided customers are informed and given the opportunity to update their details.

In cases involving third-party or group insurance contracts, insurers must obtain sufficient information from the policyholder to assess the needs of the insured individuals or groups.

Renewals Face Additional Scrutiny

Before renewing policies or offering cover for a new policy period, insurers will be expected to review whether any product changes could affect the suitability of coverage for customers based on their previously assessed needs.

Industry Preparation Begins

The recommendations will operate under a “comply or explain” approach. Insurers choosing not to implement specific recommendations must notify the Polish FSA by 15 July 2027 and explain how they intend to meet the regulator’s supervisory objectives through alternative measures.

With implementation less than a year away, insurers are expected to begin reviewing product governance, distribution practices, remuneration structures and internal compliance frameworks to ensure readiness before the new regime comes into force.

While formally aimed at insurance companies, the breadth of the recommendations means that intermediaries, including cross-border operators active in Poland, are also expected to experience significant operational and compliance changes under the new framework.

Japan’s Rental Housing Market Gains Momentum as Long-Term Investment Focus Grows

Japan’s residential rental sector is strengthening its position as one of the country’s most resilient real estate asset classes, supported by changing demographics, evolving housing preferences and sustained investor interest. Rather than being driven by short-term market fluctuations, demand is increasingly underpinned by long-term structural trends that continue to reshape the country’s housing landscape.

Major metropolitan areas, particularly Tokyo, remain at the centre of this growth. Population movement towards large cities, combined with smaller household sizes and changing lifestyle choices, continues to support demand for professionally managed rental accommodation. At the same time, purchasing a home has become less of an immediate priority for many younger residents, extending the period during which they remain in the rental market.

These trends have encouraged developers and investors to expand the supply of modern rental communities designed specifically for long-term occupancy. New projects are increasingly incorporating energy-efficient features, improved communal facilities and layouts that better reflect the needs of today’s tenants, differentiating them from much of Japan’s ageing residential stock.

The investment appeal of the sector has also strengthened. Rental housing has consistently demonstrated stable occupancy and dependable income generation, characteristics that continue to attract both domestic institutions and overseas investors seeking lower-risk real estate assets. Compared with more cyclical property sectors, residential investments have generally shown greater resilience during periods of economic uncertainty.

Location remains one of the defining factors behind successful developments. Properties situated close to railway stations, business districts and established urban amenities continue to command strong demand from tenants, while redevelopment around transport corridors is creating new opportunities across Japan’s largest metropolitan regions.

The tenant base itself has become increasingly diverse. Young professionals, couples, families, students, expatriates and older residents all contribute to demand for rental accommodation, providing landlords with a broad and relatively stable occupancy profile. This diversity helps reduce reliance on any single demographic group and supports consistent leasing activity.

Another factor supporting the market is the ongoing replacement of older residential buildings. Much of Japan’s existing rental stock was developed decades ago and no longer meets the expectations of tenants seeking higher environmental standards, better amenities and improved living environments. Redevelopment is therefore playing an increasingly important role in modernising the country’s rental housing supply.

Institutional capital continues to view Japan favourably because the country’s residential market combines relatively predictable rental income with an established legal framework and access to financing that remains competitive by international standards. These factors have reinforced confidence even as interest rates have gradually begun to normalise.

Although Japan continues to face long-term demographic challenges, conditions in its largest urban centres tell a different story. Continued migration into major cities, combined with changing household formation and sustained demand for rental accommodation, is helping to support new residential investment despite a declining national population.

As investors continue to prioritise stable income-producing assets, Japan’s professionally managed rental housing market is expected to remain a key destination for capital. Ongoing redevelopment, improving housing quality and sustained urban demand are likely to keep the sector among the country’s strongest-performing areas of real estate over the coming years.

Source: © CIJ.World Japan Research & Analysis Team

Europe’s Clean Industry Strategy Offers Insights for India’s Manufacturing Transition

As governments around the world seek to strengthen economic resilience while lowering emissions, industrial policy has returned to the centre of long-term planning. Europe has spent the past several years reshaping its manufacturing landscape through a combination of regulatory reforms, investment support and supply chain initiatives designed to accelerate the production of low-carbon technologies. While India’s economic priorities differ, Europe’s experience offers several practical lessons as the country expands its own clean manufacturing ambitions.

The European Union’s industrial transformation has evolved beyond climate objectives alone. Policymakers increasingly view domestic manufacturing capacity as essential for economic competitiveness, energy security and reducing dependence on imported technologies and critical raw materials. This broader strategy has been reinforced through legislation aimed at accelerating investment in strategic industries, streamlining project approvals and encouraging greater production of technologies such as batteries, solar equipment, wind components, electrolysers and carbon capture systems.

The approach reflects a growing recognition that reducing emissions requires more than ambitious environmental targets. It also depends on creating the conditions that allow manufacturers to invest with confidence while ensuring that supporting infrastructure, skilled labour and financing are available.

India is pursuing many of the same objectives through programmes supporting renewable energy manufacturing, battery production, electric mobility and green hydrogen. The country’s industrial base, expanding domestic market and relatively young workforce provide opportunities to develop competitive supply chains in sectors expected to experience significant global growth over the coming decades.

One of the strongest lessons from Europe is the importance of policy stability. Large industrial projects often require substantial capital and may take years before becoming operational. Investors therefore place considerable value on predictable approval processes, transparent regulations and long-term policy consistency. Delays involving environmental permits, land acquisition, electricity connections or transport infrastructure can increase costs and discourage investment.

Creating a more coordinated approval system could help India accelerate industrial development while maintaining environmental standards. Greater alignment between central and state authorities would also improve certainty for manufacturers planning large-scale facilities.

Europe’s experience also highlights the importance of creating demand alongside expanding manufacturing capacity. Building factories alone does not guarantee commercial success if markets for cleaner products remain limited or uncertain. Public procurement, product standards and certification frameworks can help encourage early adoption of lower-emission materials and technologies while allowing industries to scale production.

India has already introduced standards for classifying lower-emission steel and continues to expand policies supporting clean energy technologies. Similar approaches could encourage wider adoption of sustainable construction materials, electric public transport, energy storage systems and other products that contribute to industrial decarbonisation.

Infrastructure remains another critical factor. Manufacturing clusters require reliable electricity, transport links, ports, water supplies and digital connectivity. Emerging industries such as green hydrogen add further requirements, including renewable power generation, electrolysers, storage facilities and distribution networks capable of supporting industrial users.

Coordinated investment across these areas can reduce operating costs and improve competitiveness by allowing multiple companies to benefit from shared infrastructure rather than developing separate facilities.

Developing a skilled workforce represents another long-term challenge. As manufacturing technologies become more advanced, employers require technicians, engineers and specialists capable of operating increasingly sophisticated production systems. Expanding technical education, vocational training and industry partnerships can help ensure that workforce development keeps pace with industrial investment.

Innovation also plays an important role. Continued collaboration between universities, research institutions and manufacturers can accelerate the commercialisation of new technologies while strengthening domestic expertise in strategic industries.

Although Europe’s policy framework cannot be directly replicated, its experience demonstrates that industrial transformation depends on far more than financial incentives alone. Regulatory efficiency, infrastructure planning, workforce development, research capabilities and market creation all contribute to building a competitive manufacturing sector.

For India, the challenge is to integrate these elements into a coherent long-term strategy that supports economic expansion while reducing industrial emissions. Success will depend not only on attracting investment but also on creating an environment where businesses can scale production, innovate and compete internationally. As global demand for clean technologies continues to increase, countries that successfully align industrial policy with economic development are likely to strengthen both their manufacturing base and their position within future supply chains.

Source: © CIJ.World India Research & Analysis Team

Diehl Aviation Opens New Production Facility in Craiova

Diehl Aviation has officially opened a new production facility in Craiova, Romania, at a site developed by Global Vision.

Global Vision managed the development of the project, including negotiating and signing the long-term lease agreement with Diehl Aviation, overseeing construction from the shell-and-core phase through to the interior fit-out, and arranging the project’s financing.

To support the development, Global Vision Investment Fund (GVIF) secured a €12.7 million financing package from Banca Comercială Română (BCR), comprising a development loan and an additional top-up facility. The project also includes a rooftop photovoltaic system designed to reduce energy costs and support the tenant’s sustainability objectives.

Sorin Preda, Founder and CEO of Global Vision, said the investment reflects the company’s focus on developing long-term industrial assets for established occupiers. He added that Diehl Aviation’s new facility strengthens the company’s industrial portfolio while contributing to Romania’s manufacturing sector.

The facility is located within Craiova Business Park and provides approximately 12,000 sqm of space on a 33,500 sqm site, including 2,500 sqm of Class A office accommodation. The plant will manufacture components for commercial aircraft programmes.

Concentrix Opens New Headquarters in Pipera

The American outsourcing company Concentrix will move its Romanian headquarters to the Oregon Park complex, in the Pipera area, starting this fall, following one of the largest office rental transactions this year, according to market sources.


Concentrix’s Romanian headquarters is to be moved to a new 5,200 square meter office space in the Oregon Park complex, which will accommodate around 500 workstations. The American giant will move into the spaces previously occupied by Oracle.


“I can confirm that there are advanced discussions regarding a possible relocation to Oregon Park in the third quarter, but the contract has not yet been signed. For this reason, and given the confidentiality specific to such agreements, we cannot confirm at this time specific details related to space, number of workstations and other associated plans, until final validation by the legal departments of both parties,” Carmen Pufan, Associate Director, Regional Marketing CEE at Concentrix, told Profit.ro.

After completing the transaction with Concentrix, the investment fund Lion’s Head Investments will reach a 100% occupancy rate with the Oregon Park complex it owns.


Source: Profit.ro

LPP Logistics Opens New Warehouse near Bucharest  

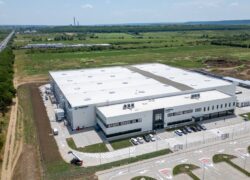
LPP Logistics, the company that provides logistics for the Reserved, Cropp, House, Mohito and Sinsay brands, is expanding its operational capacities in South-Eastern Europe by opening a distribution center near Bucharest.


The unit, with an area of ​​56,000 sqm, serves the LPP Group stores in Romania, Bulgaria and Greece. An additional advantage of the location is its proximity to the port of Constanta, which streamlines the organization of deliveries by sea.


The launch of the new center also marks the completion of the reconstruction of the logistics infrastructure following the fire that occurred at the warehouse last year.


“The launch of the new distribution center just one year after the decommissioning of the previous warehouse demonstrates the operational efficiency of LPP Logistics and the ability of our team to quickly rebuild the infrastructure essential for business continuity. An important aspect is that we did not limit ourselves to restoring previous capacities, but launched a modern unit prepared for the future expansion of the LPP Group, especially the Sinsay brand. Currently, we are already able to simultaneously serve over 450 stores, and following the planned expansion, we will double this capacity,” said Sebastian Sołtys, CEO of LPP Logistics.

Ghai Sant Ram Acquires a Plot of Land in Pipera for Residential Project

British investor Ghai Sant Ram is expanding his real estate portfolio in Romania through a new strategic acquisition completed via Ghai Family Holding in northern Bucharest. The investor acquired from George Becali a plot of approximately 30,000 square metres, located near Pipera Plaza, where he intends to develop a residential project comprising approximately 650 apartments.


The purchase price was approximately EUR 14.3 million, and the land was acquired together with the building permit for a large-scale real estate development. The transaction was brokered by CGA Home Consulting.


Details of the development’s exact configuration, apartment mix, number of parking spaces, amenities, total investment value and construction timetable will be announced once the technical stages have been completed.


With 1,188 apartments at IVORY RESIDENCE, 699 at HORIZON CITY and 650 planned for the new Pipera development, Ghai Sant Ram’s residential portfolio in Romania exceeds 2,500 units.

front page info
LATEST NEWS