Office development activity resumes in Bucharest as projects under construction exceed 200,000 sqm

Office development activity in Bucharest increased over the past year, with the volume of projects currently under construction surpassing 200,000 sqm of gross leasable area, the highest level recorded since 2021. At least eight new office buildings are expected to be delivered by the end of 2028, according to the Bucharest Office Marketbeat Q4 2025 report published by Cushman & Wakefield Echinox.

The renewed construction activity follows two years of limited deliveries, which totalled approximately 15,000 sqm and corresponded to a single completed building. No new office projects were finalised in Bucharest in 2025, marking the first year without new deliveries in the city’s modern office market.

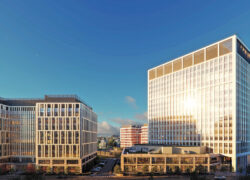
The largest scheme currently under construction is the second phase of Timpuri Noi Square, developed by Vastint in the central submarket. Other ongoing developments include ARC Project in the Grozăvești–Politehnica area, developed by PPF Real Estate with 30,000 sqm; Promenada Offices, part of the Promenada Mall extension in the Floreasca–Barbu Văcărescu submarket, developed by NEPI Rockcastle with 23,400 sqm; One Technology District in Dimitrie Pompeiu by One United Properties with 20,600 sqm; AFI Central Tower, a redevelopment of the former Bucharest Financial Plaza by AFI Europe with 28,000 sqm; and U-Center 3 by Forte Partners with 16,300 sqm. The most recently announced project is Green Court D, a 17,000 sqm building to be developed by Globalworth.

Limited deliveries in the past two years, combined with an increase in net demand excluding renegotiations, contributed to a decline in the vacancy rate to 12.1 percent, compared with 14.2 percent in the fourth quarter of 2024, representing the lowest level since the third quarter of 2020. The reduction in available space also contributed to rental growth in submarkets with constrained supply.

Gross take-up in Bucharest reached 85,000 sqm in the fourth quarter, while total leasing activity for 2025 amounted to 282,200 sqm, a decrease of 23 percent compared with 2024. Net take-up represented 53 percent of total demand, up from 44 percent the previous year.

In the Central Business District, prime rents increased by approximately 5 percent, reaching €21–22 per sqm per month, with higher values reported in smaller boutique projects. In other areas, benchmark rents ranged between €15–18.50 per sqm per month in central and semi-central locations and €9–13.50 per sqm per month in peripheral areas for existing buildings. Asking rents in projects currently under construction generally ranged between €18–22 per sqm per month, reflecting technical specifications and construction costs.

Bucharest’s modern office stock totals 3.43 million sqm, accounting for roughly 15 percent of office space among Central and Eastern European capital cities. Warsaw leads the region with 28 percent, followed by Budapest with 20 percent, Prague with 18 percent, Sofia with 11 percent, and Bratislava with 8 percent.

Mădălina Cojocaru, Partner, Office Agency at Cushman & Wakefield Echinox, said: “The tenants’ selection criteria currently extend well beyond the traditional parameters of space efficiency. Access to public transportation, proximity to residential areas, and a well developed network of services have become critical decision making factors. Equally important is the community which forms around a building, as well as the willingness of property managers to implement events and initiatives which activate and enrich the common areas. The office has evolved from a purely operational location into an ecosystem designed to support collaboration, organizational culture, and the everyday employee experience. Against this backdrop, the renewed activity in office development provides companies with the opportunity to secure spaces that not only meet functional requirements but also enhance their positioning and attractiveness as employers.”

Photo: Timpuri Noi Square developed by Vastint
Saudi and Badie Investment to launch SAR 500 million real estate fund for Riyadh tower project

Kamco Invest – Saudi and Badie Investment announced a partnership to establish a SAR 500 million real estate investment fund to develop the “Badie Tower” project along Riyadh’s Sports Boulevard.

The planned development is one of six towers permitted along the 135-kilometre Sports Boulevard corridor. The site is located opposite Imam Mohammad Ibn Saud Islamic University and is intended to include a metro station entrance connecting the Yellow and Purple lines within the building. The design is planned in accordance with the Sports Boulevard’s Salmaniyah urban code and will incorporate transport and infrastructure elements. The project forms part of wider urban development initiatives linked to Saudi Arabia’s Vision 2030 programme.

Mohammed Al-Faris, Chief Executive Officer of Kamco Invest – Saudi, said: “This partnership marks an important step in Kamco Invest – Saudi’s expansion strategy as we continue to pursue high-quality, institutionally structured opportunities within the Kingdom. The Sports Boulevard is a transformative national project, and our participation in developing Badie Tower reflects our commitment to investing in landmark assets that deliver long-term value to our clients while contributing to Saudi Arabia’s urban evolution.”

He added: “The project’s unique location, infrastructure integration, and scarcity value create a compelling investment proposition. Through this partnership, we aim to provide institutional and high-net-worth investors access to differentiated real estate opportunities aligned with the Kingdom’s long-term growth and diversification agenda. Expanding our clients’ access to alternative investment opportunities further supports their unique objectives, enabling us to structure customized solutions that suit their diverse investment needs and risk appetite.”

Dr. Abdulaziz Alangari, Chief Executive Officer of Badie Investment, said: “Badie Tower represents a rare opportunity to develop an architectural icon within one of the world’s most ambitious urban initiatives. Our collaboration with Kamco Invest – Saudi brings together investment expertise and development vision to deliver a landmark project that enhances quality of life and supports Riyadh’s transformation into a global destination.”

Dr. Alangari added: “We are committed to creating a development that integrates smart infrastructure, connectivity, and design excellence. This partnership reinforces our shared vision of building sustainable, future-ready assets that serve both investors and the wider community.”

According to the companies, the fund structure is intended to attract institutional and high-net-worth investors and forms part of Kamco Invest’s ongoing expansion in Saudi Arabia, with a focus on real estate and alternative investments aligned with national economic diversification goals.

Premium Point and Premium Plaza receive LEED Existing Buildings Platinum certification

BuildGreen and GTC announced that the Premium Point and Premium Plaza office buildings in Bucharest’s Piața Victoriei area have obtained LEED v4.1 Existing Buildings certification at Platinum level.

Premium Plaza, with a gross leasable area of 8,468 sqm, and Premium Point, with 6,354 sqm, are office buildings located in the Central Business District and have been part of GTC’s portfolio since 2016. Both properties were inaugurated in 2008 and 2009.

“The certifications obtained by Premium Point and Premium Plaza are a successful example of how Bucharest’s built environment can evolve and adapt”, said Răzvan Nica, CEO and Founder of BuildGreen. “GTC’s investments in optimizing the two buildings, inaugurated more than 15 years ago, resulted in achieving LEED Existing Buildings at Platinum level and demonstrate how the involvement of responsible developers with a well-established ESG policy contributes to the sustainable strengthening of Bucharest’s existing office hubs,” he added.

According to the companies, the certification followed upgrades aimed at improving energy performance and reducing consumption compared with similar buildings. Indoor environmental quality was also assessed, including air quality measurements and fresh-air rate calculations in line with international standards.

“As the first commercial developer in CEE to publish a comprehensive ESG report, GTC has consistently focused on sustainable development, recognizing our responsibility toward the environment, our immediate surroundings, and the local communities we are part of. This achievement also means that all GTC assets in Romania are now LEED certified. In Bucharest, we own four office buildings with a total leasable area of 62,000 sqm, each holding a LEED certificate at Gold or Platinum level – confirming the high quality of our portfolio on the office market,” said Gabriela Cîrstea, Asset Manager at GTC Romania.

Premium Point received the maximum score in the Water Performance category following measures to reduce water consumption, while Premium Plaza recorded high results in Waste Management due to improvements in separate collection and recycling systems.

The certification process lasted approximately three months and included on-site inspections and documentation reviews. Assessments covered indoor air quality testing, an ASHRAE audit of building systems such as HVAC, lighting and building management systems, as well as the analysis of energy, water and waste data over a 12-month period. Occupant feedback on mobility and in-building experience was also collected, alongside technical documentation related to refrigerants, procurement policies, material safety and ventilation standards.

Sonae Sierra’s German centre portfolio closes 2025 with higher occupancy and leasing activity

The shopping centre portfolio managed by Sonae Sierra in Germany recorded higher occupancy, leasing activity and retail turnover in 2025, according to company data. As of 31 December 2025, the 19 centres managed on behalf of third-party owners were almost 95 percent let, with annual footfall up 1 percent and tenant turnover increasing by more than 6 percent year-on-year.

During the year, Sonae Sierra signed a total of 360 leases and renewals covering 108,400 sqm across the portfolio. This included 172 new leases for approximately 35,000 sqm and 188 renewals totalling about 73,400 sqm.

In October 2025, Sonae Sierra completed the acquisition of REM, the management division of Unibail-Rodamco-Westfield in Germany. Following the transaction, the company became the second-largest manager of third-party shopping centres in the country. The German portfolio now comprises 19 centres with a combined gross leasable area of around 1 million sqm and annual visitor numbers exceeding 130 million, according to the company.

“The encouraging figures show that we are managing a very efficient and stable portfolio in Germany. We will keep all centres on track for success in line with the owners’ business objectives, manage them in a value-adding manner and further leverage their potential,” said Christine Hager, Director of Property Management in Germany and member of the management board at Sonae Sierra. “The positive development of the locations confirms once again that the acquisition of the management division was the right step to implement our expansion strategy and take a leading market position.”

Dirk von der Ahé, Head of Leasing in Germany at Sonae Sierra, added: “Our locations are attractive to retailers and in high demand. Our innovative leasing concepts, our experience and creativity in developing individual solutions for the needs of tenants and owners have led to leasing successes. We will continue to enhance the quality of the visitor experience in the centres through strong leasing and utilisation concepts, thereby creating added value for tenants, owners and customers.”

Following the integration of REM, Sonae Sierra employs around 250 staff in Germany and provides centre and property management services including operations, leasing, marketing and project management. The expanded portfolio includes centres such as Riem Arcaden and Pasing Arcaden in Munich, Spandau Arcaden in Berlin, Köln Arcaden, Düsseldorf Arcaden and Breuningerland in Sindelfingen and Ludwigsburg.

Photo: Christine Hager, Director of Property Management in Germany and member of the management board at Sonae Sierra

Germany’s energy transition advances, but pace remains below targets

The expansion of renewable energy in Germany has picked up speed but remains insufficient to meet the country’s legally defined 2030 targets, according to the latest Energy Transition Monitor published by the German Institute for Economic Research (DIW Berlin). The report reviews developments in key technologies in the second half of 2025 and concludes that progress in electricity generation has not yet been matched by comparable advances in heating and transport.

While installed capacity for photovoltaics, onshore wind power and electricity storage increased noticeably, the uptake of renewable electricity in buildings and mobility continued to lag. “We are currently seeing progress in many areas of the energy transition, but overall we are not yet seeing the pace that would be desirable for climate protection and energy sovereignty,” said study author Wolf-Peter Schill, head of the “Transformation of the Energy Industry” research department at DIW Berlin.

Capacity growth still below 2030 requirements

In terms of installed capacity, Germany remains short of its medium-term objectives. By the end of 2025, photovoltaic installations reached 117 gigawatts out of the 215 gigawatts targeted for 2030 under the Renewable Energy Sources Act (EEG), slightly above the halfway mark. Onshore wind power achieved close to 60 percent of its 2030 goal, while offshore wind capacity remained further behind.

According to the monitor, photovoltaics is currently closest to the pace required to meet the 2030 target, operating at around 88 percent of the necessary expansion rate. Onshore wind has also improved its trajectory in recent quarters, although the overall build-out remains below the level required to close the gap within five years.

Sector coupling progressing unevenly

The report notes incremental progress in linking renewable electricity with heating and transport, often referred to as sector coupling. Heat pumps accounted for 48 percent of new heating installations in the second half of 2025, the highest share recorded to date. Registrations of electric vehicles increased for both passenger cars and trucks, but overall penetration remains limited. In the past six months, roughly one in five newly registered cars in Germany was fully electric.

“With a view to the goal of climate neutrality by 2045, we need to accelerate significantly, especially in the areas of heat pumps and electric vehicles,” Schill said.

Flexibility improves, but challenges persist

The DIW analysis also points to modest improvements in electricity system flexibility. The number of hours with negative wholesale power prices declined in the second half of 2025, suggesting a better balance between supply and demand. At the same time, capacity additions in large-scale battery storage increased. Despite these developments, the institute considers further expansion of storage and demand-side flexibility necessary to stabilise the grid as renewable generation grows.

Call for consistent policy direction

DIW Berlin argues that current conditions – including technological progress, falling costs and more efficient approval procedures – are favourable for accelerating the transition. However, the report highlights what it describes as mixed political signals from the federal government.

“If the expansion of renewables is slowed down, there is a risk of an unhealthy cycle,” Schill warned. He added that even though electricity demand is currently rising more slowly than previously expected, partly due to moderate growth in electric vehicles and heat pumps, insufficient renewable capacity today could result in supply constraints in the future.

Beyond climate policy, the study links the energy transition to industrial competitiveness and geopolitical considerations. Reducing reliance on imported oil and gas through electrification and renewable generation could lower exposure to fossil-fuel markets. “Politicians should take advantage of the favourable conditions and vigorously promote both the expansion of renewable energies and sector coupling – instead of putting the brakes on,” Schill said.

Dekpol Deweloper prepares first residential project on Lake Garda

Dekpol Deweloper has secured a plot of land in Toscolano-Maderno on Italy’s Lake Garda in the Lombardy region and is completing the final steps before signing the purchase agreement. The transaction concerns land with a valid building permit intended for the construction of a residential apartment complex.

“For some time now, we have been observing growing customer interest in holiday projects outside Poland. We treat our first project in Italy as a natural complement to our offer, which remains strongly focused on the domestic market, which is still our number one priority in the investment apartment segment. The project on Lake Garda is the next step in the development of our business and a response to the needs of some of our customers looking for properties in the most attractive locations in Europe,” says Michał Skowron, President of the Management Board of Dekpol Deweloper. “The town of Toscolano-Maderno combines unique landscape values with access to infrastructure conducive to active recreation. In the immediate vicinity of the plot, which offers views of Lake Garda, there are local restaurants, golf courses, an extensive network of cycle paths and trekking trails leading to Monte Pizzocolo.”

According to the developer, the design phase will reference the surrounding urban and natural context, with the project intended to align with local architectural character and spatial planning principles.

“Premium projects are not just about aesthetics or prestige, but about having a real impact on quality of life. At Dekpol Deweloper, we think about the architecture and function of a project as early as the land purchase stage. In Toscolano-Maderno, we want to design buildings that naturally fit into the identity of the place, its history and the landscape of Lake Garda. It will be architecture rooted in the regional context, yet contemporary in terms of standards and functionality,” says Paulina Czurak-Czapiewska, architect and member of the management board of Dekpol Deweloper.

Dekpol Deweloper said it plans to present the first visualisations of the Lake Garda project in the coming months.

Warsaw office market ends 2025 with record leasing volumes and constrained supply

The Warsaw office market closed 2025 with historically high tenant activity, limited new supply and a continued decline in vacancy, according to BNP Paribas Real Estate Poland’s Review – Warsaw Office Market, Q4 2025. Lease renegotiations dominated transactions throughout the year, while developers delivered the lowest quarterly volume of new space in the final three months.

Total modern office stock in Warsaw reached 6.23 million sqm by the end of December, representing an annual increase of just under 90,000 sqm. New deliveries in 2025 amounted to 88,700 sqm, with no new office buildings completed in Q4 as several projects shifted into early 2026. The largest schemes delivered during the year were The Bridge (47,000 sqm) and Office House (27,800 sqm), both located in central zones. Refurbished projects also contributed additional space, including approximately 10,000 sqm at the Lipowy Park complex. 

Tenant activity reaches highest level on record

Leasing volume totalled 794,000–795,000 sqm in 2025, up around 7% year-on-year, marking the strongest annual result recorded for the Warsaw office market. The fourth quarter alone accounted for nearly 310,000 sqm, a 69% increase compared with Q3 and the highest quarterly figure of the year.

“The transaction structure in 2025 was dominated by lease renewals. For many companies, this was a decision made almost out of necessity, as the market currently offers very few viable relocation options. On top of that, fit-out costs often create a significant barrier to changing headquarters. Tenant activity was strongest in the City Centre zone, which accounted for 32% of the total leasing volume. The second most active area was Służewiec, with a 23% share,” notes Wiktoria Weilandt, Director, Office Agency Department, BNP Paribas Real Estate Poland.

BNP Paribas data indicates that renewals represented 50–51% of gross leasing volume over the year, while new leases accounted for roughly 40%. In Q4 alone, renewals made up 64–65% of activity, with new leases at just over 31%. Pre-lets represented 7.4% of total transactions across the last four quarters.

Among the largest transactions of the year were Santander Bank’s 24,500 sqm pre-let at The Bridge, Polkomtel’s 22,680 sqm renewal in Służewiec, and AstraZeneca’s 22,500 sqm renewal and expansion at Postępu 14. In Q4, additional significant deals included a confidential tenant securing over 16,000 sqm at Eurocentrum Office Complex Delta and multiple public-sector renewals exceeding 9,000–12,000 sqm. 

Sector-wise, demand was led by banking, insurance and investment firms (15%), followed by business services (14%), manufacturing (13%) and IT products and services (12%), with public institutions accounting for around 10% of leased space.

Supply remains limited despite projects under construction

While annual deliveries were modest, the development pipeline expanded slightly. By the end of 2025, approximately 199,000–200,000 sqm of office space was under construction for delivery between 2026 and 2028. More than 60% of this pipeline is concentrated in central zones and about one-third in the Central Business District.

Key schemes under construction include AFI Tower (50,000 sqm), Upper One (35,500 sqm) and the V-Tower refurbishment (30,800 sqm), alongside projects such as Studio A and Skyliner II. Analysts note that securing large contiguous units exceeding 1,000 sqm remains challenging despite the overall availability of space. 

Vacancy continues to decline

At the end of December 2025, approximately 560,000–565,000 sqm of office space was available in Warsaw, translating into a vacancy rate of 9.1%, down 1.5 percentage points year-on-year and 0.6 points quarter-on-quarter. The decline was driven by limited new supply, building withdrawals for alternative uses and stronger tenant demand in the second half of the year.

Central locations recorded a vacancy rate of around 6.1%, compared with 11.6% outside the city centre. The highest concentration of vacant space remained in Służewiec, where availability exceeded 18%, while the CBD and City Centre West maintained vacancy levels near 6%. Newer buildings performed better, with vacancy below 5% in properties under five years old, compared with more than 11% in assets older than ten years. 

Rental growth supported by scarcity of prime space

Prime headline rents continued to rise in 2025, supported by constrained supply in central zones. Average prime asking rents across Warsaw reached approximately EUR 30 per sqm per month, while in the CBD headline rents climbed to around EUR 29 per sqm per month and EUR 26–27 per sqm per month in the wider City Centre.

“The highest growth dynamics were recorded in locations directly adjacent to the city centre. Limited supply of new developments combined with stable demand continues to fuel upward pressure. Market forecasts indicate that in 2026, prime headline rents may reach EUR 32 per sqm per month, and in the most prestigious locations — even EUR 34–35 per sqm per month,” emphasizes Małgorzata Fibakiewicz, Senior Director, Head of Office Agency Department, BNP Paribas Real Estate Poland.

With only a limited volume of new office space expected to be delivered in 2026, analysts anticipate continued competition for high-quality central offices and further upward pressure on rents in prime assets.

Source: BNP Paribas Real Estate Poland

Develia becomes Premium Sponsor of WTS Sparta Wrocław

Develia has signed a sponsorship agreement with the WTS Sparta Wrocław speedway club, joining the organisation as a Premium Sponsor. The company said the partnership reflects its long-term presence in Wrocław and its involvement in local initiatives.

Develia, a residential developer headquartered in Wrocław, has operated in the city and other major Polish markets for two decades. Under the agreement, the company will support the club through financial sponsorship and brand visibility at sporting events.

“Wrocław is a city with which we are connected on a daily basis – both professionally and privately. We have been supporting Sparta from the stands for years and following its successes. Today, we want to add our sponsorship support to this,” said Andrzej Oślizło, President of the Management Board of Develia, adding, “We believe that regardless of the result on the track, the most important thing is the feeling we want to give our customers and fans: It’s good to be home.”

WTS Sparta Wrocław is a speedway club competing in the Polish league system and has won the Polish Team Championship five times. The club regularly places among the top teams in the national competition.

“We are proud to announce the start of our cooperation with one of the largest companies in this industry in Poland. We are connected not only by Wrocław, but also by a shared vision of development, professionalism and ambition. I am convinced that together with the Develia brand, we will bring a lot of joy to the residents of the region, while achieving our business goals,” said Andrzej Rusko, President of WTS Sparta.

As part of the partnership, the Develia logo will appear on team uniforms, stadium banners, LED screens and selected areas of the venue. The agreement also предусматривает brand presence in the club’s communications and activities linked to sporting events.

SVN Credit brokered EUR 326.5 million in loans in 2025 as Romania’s mortgage market reached EUR 10.9 billion

SVN Credit Romania brokered loans totalling EUR 326.5 million in 2025, an increase of 40.7 percent compared with the previous year. More than two-thirds of this amount consisted of mortgage loans. The company reported approximately EUR 250 million in mortgage financing, corresponding to nearly 3,100 loans, while consumer loans accounted for around EUR 60 million. Corporate financing and leasing advisory services covered 110 transactions with a combined value of EUR 16.5 million.

The growth in activity was also linked to the company’s territorial expansion, with 12 new regional offices opened during 2025, bringing its national network to 32 offices. SVN Credit stated that its 2026 plans include further expansion into smaller cities, with new offices already opened this year in Târgu Mureș and Focșani.

Romania’s mortgage market reached a new high in 2025, with total loans granted at national level amounting to EUR 10.9 billion, according to National Bank of Romania statistics compiled by SVN Credit. This represented an 18.4 percent increase compared with 2024. Loans issued specifically for home purchases totalled EUR 5.1 billion, or 46.7 percent of the overall mortgage volume, while the remainder consisted of refinancing, restructuring, reconversion and transfer loans. The value of new home-purchase mortgages was also a record, rising 13 percent from EUR 4.5 billion recorded in 2024.

“The mortgage market is increasingly accessible for those who want to buy a home through a mortgage loan: 2026 started with decreasing interest rates and on the fixed segment we already have an average fixed interest rate that dropped below 5%. Consumers should be attentive not only to potential decreases in the key interest rate but also to the existing offers – or to use the services of a credit broker, which are free in Romania – offers that are increasingly advantageous in a context of competition between financial institutions. In addition, IRCC will record another slight decrease in the second quarter, to about 5.57%. In this context, 2026 has all the premises to bring results at least as good the previous year,” said Cătălin Marin, Managing Partner of SVN Romania | Credit & Financial Solutions.

The increase in mortgage lending occurred alongside a decline in residential transactions. According to data from the National Agency for Cadastre and Land Registration, the number of homes sold in Romania decreased by 5.3 percent in 2025 compared with the previous year. Based on SVN calculations, mortgages registered in 2025 represented approximately 57 percent of all residential units sold, up from 51 percent in 2024. These figures include refinancing and restructuring loans as well as personal loans secured by property.

SVN Credit Romania operates as a broker for mortgage and consumer loans on the local market. Its affiliated real estate consultancy, SVN Romania, reported residential sales of more than 1,700 homes in 2025 with a combined value exceeding EUR 280 million, alongside land, commercial and office transactions. SVN International Corp. operates over 200 offices worldwide with more than 2,200 consultants and administrative staff.

Czech Commercial Real Estate Investment Hits Record in 2025 Amid Limited New Supply

Investment activity in the Czech commercial real estate market reached a historic high in 2025, with total transaction volumes exceeding previous peak levels and more than doubling year-on-year, according to market analyses by international advisory firms. The surge in capital inflows was accompanied by one of the lowest levels of new office construction in recent years, reinforcing demand for existing assets across key segments.

Market data from several brokerage houses indicate that total annual investment volumes approached €4–4.5 billion, surpassing the previous record set in the mid-2010s. Domestic investors played a dominant role in transactions, accounting for the majority of deployed capital, particularly in the second half of the year.

Large mixed-use and retail-anchored complexes were among the most significant deals recorded during the period, while office properties continued to attract steady interest. According to quarterly investment overviews, offices represented roughly one quarter of overall transaction volume, reflecting sustained demand for prime and well-located assets despite higher financing costs.

At the same time, the development pipeline remained subdued. Prague’s office market recorded one of its lowest annual completion volumes in modern history, contributing to tightening vacancy conditions in central and established business districts. Analysts attribute the limited new supply to a combination of elevated construction costs, stricter financing conditions and lengthy permitting processes, factors that have slowed the launch of new commercial projects.

The imbalance between strong investment demand and constrained new deliveries has supported pricing levels for existing properties and maintained competitive conditions for high-quality assets. Advisory firms note that while investor sentiment remained cautious due to macroeconomic uncertainty and interest-rate dynamics, the Czech market continued to benefit from its relative stability, transparent legal framework and liquidity compared with several neighbouring markets.

Overall, 2025 marked a year in which record capital deployment coincided with historically low new construction volumes, shaping a market environment characterised by limited supply and continued investor focus on established income-producing properties.

front page info
LATEST NEWS