Czech retail sales accelerate in May as consumer spending strengthens

Retail sales in the Czech Republic, excluding motor vehicle sales and repairs, increased 4.7% year-on-year in May 2026, accelerating from a revised 0.8% increase in April, according to the Czech Statistical Office (CZSO).

On a month-on-month basis, retail sales rose 1.3%.

Growth was driven by stronger sales of non-food goods and food, while fuel sales declined.

Sales of non-food goods increased 7.4% year-on-year, while food sales rose 2.9%. Fuel sales fell 0.8% compared with May 2025.

Among individual retail categories, clothing and footwear retailers recorded the strongest performance, with sales rising 15.7% year-on-year. Non-specialised stores predominantly selling non-food goods reported growth of 7.8%, while internet and mail-order retailers increased sales by 11.6%.

Sales at non-specialised food retailers rose 3%, while specialised food stores recorded growth of 2.6%. By contrast, retailers of computer and communication equipment reported a 5.4% decline in sales.

Sales and repairs of motor vehicles increased 4.6% year-on-year and were 1% higher than in April.

Separately, the Czech Republic recorded a CZK 9.9 billion trade surplus in May, according to preliminary CZSO data.

Exports increased 5.6% year-on-year to CZK 415.6 billion, while imports rose 6% to CZK 405.7 billion. The surplus was CZK 1 billion lower than in May 2025.

The trade balance benefited from stronger exports of machinery, electrical equipment and fabricated metal products, while trade in coke and refined petroleum products had a negative impact on the overall result.
Slovak retail sales edge higher in May as specialised stores outperform

Retail turnover in Slovakia increased by 0.9% year-on-year in real terms in May 2026, supported by stronger sales in specialised retail stores, according to the Statistical Office of the Slovak Republic.

Four of the nine retail trade categories recorded year-on-year growth after adjusting for inflation, while overall performance was held back by weaker results from e-commerce and large grocery retailers.

The strongest contribution came from specialised stores selling other goods, including pharmacies, drugstores, clothing and footwear retailers, and household fuel outlets, where turnover rose 6.2% compared with May 2025.

Double-digit growth was also recorded by DIY, furniture and electronics retailers, as well as stores specialising in sporting goods, books, toys, computers and information technology equipment.

By contrast, online and mail-order retailers recorded a 13% decline in turnover, while sales at hypermarkets and supermarkets fell 3% year-on-year. These segments account for a significant share of Slovakia’s retail market.

On a seasonally adjusted basis, retail turnover increased 0.1% from April.

For the first five months of 2026, retail turnover rose 0.2% year-on-year in real terms, with five of the nine retail segments recording growth.

Outside retail, accommodation providers posted the strongest annual increase, with turnover rising 19.7% in real terms during May. Wholesale turnover increased 8.2% in current prices.

Meanwhile, turnover in the sale and repair of motor vehicles declined 12.5% in real terms, while food and beverage service activities recorded a 3% decrease.

Compared with April, seasonally adjusted turnover increased 14.4% in accommodation and 10% in food service activities. Motor vehicle sales and repairs fell 2.7%, while wholesale turnover edged down 0.3%.

During the first five months of 2026, accommodation turnover increased 19.4% year-on-year, wholesale grew 5.7%, while turnover in motor vehicle sales and repairs declined 8.6% and food service activities fell 2.4%.

Czech inflation slows to 1.5% in June, preliminary data show

Annual consumer price inflation in the Czech Republic slowed to 1.5% in June 2026 from 2.1% in May, according to a preliminary estimate published by the Czech Statistical Office (CZSO).

On a month-on-month basis, consumer prices declined 0.3% in June. The CZSO is scheduled to publish the final inflation figures on 10 July.

June recorded one of the lowest inflation rates of the year, exceeded only by February’s reading of 1.4%. Inflation reached its highest level of 2.5% in April.

Services remained the main source of price growth, with prices increasing 4.5% year-on-year. Prices for alcoholic beverages and tobacco also rose significantly, up 4.3% compared with June 2025.

Food and non-alcoholic beverage prices recorded the largest annual decline, falling 3.4%. Prices of unprocessed food decreased 2.1%, while processed food prices declined 0.6%.

Energy prices, including motor fuels, fell 1% year-on-year, compared with a 1.8% annual increase recorded in May. Goods prices also edged lower, declining 0.4% after posting an increase in the previous month.

Inflation remained above 2% for most of the second half of 2025, reaching 2.9% in June last year. During the first half of 2026, however, inflation moderated and remained below the Czech National Bank’s 2% inflation target for most months.

According to economists, the moderation in inflation during the early part of the year was supported in part by the transfer of renewable energy support payments from households to the state.

When Polish Capital Finds Greater Opportunity in Britain Than at Home

One of Poland’s wealthiest entrepreneurs, Michał Sołowow, plans to invest £35 billion to develop a fleet of 14 BWRX-300 small modular reactors (SMRs) across three sites in the United Kingdom. The project, led by SGE, aims to deliver 4.2 GW of generating capacity, enough to power the equivalent of around eight million homes for more than 60 years.

The UK has actively sought to attract private investment into advanced nuclear technologies through its Advanced Nuclear Framework, which supports privately led nuclear projects while combining regulatory oversight with government-backed support mechanisms where appropriate. This approach has encouraged developers to bring forward privately financed nuclear proposals alongside public initiatives.

The contrast with Poland is notable.

Sołowow has spent several years developing SMR technology through SGE, formerly Synthos Green Energy. In Poland, however, the company’s deployment strategy became closely linked with the state through the creation of the Orlen Synthos Green Energy joint venture with Orlen.

What was initially presented as a strategic partnership later became the subject of reported disagreements over governance, project control, investment strategy and the allocation of responsibilities between the private and state-owned partners. The project also attracted scrutiny from prosecutors and state institutions, although the related proceedings were ultimately discontinued without establishing wrongdoing. These events nevertheless highlighted the challenges that can arise when large strategic investments combine private capital with state-controlled enterprises.

The experience has contributed to a broader debate about the role of private investment in strategic sectors.

Poland faces a growing need for reliable, low-emission electricity to support industrial competitiveness, data centres, advanced manufacturing and broader economic growth. Renewable energy will remain an important part of the energy mix, but continued investment in electricity grids, storage capacity and dispatchable generation will also be required. Nuclear energy, including SMRs, is widely viewed as one potential source of stable baseload power.

Small modular reactors are not a short-term solution. Projects still require regulatory approval, financing, suitable sites, public acceptance and comprehensive safety oversight before construction can begin.

The UK model illustrates that governments can encourage private investment while maintaining strong regulatory control. Rather than acting primarily as project developers, governments can establish clear regulatory frameworks, ensure rigorous safety standards and provide predictable investment conditions.

For Poland, the key policy question is how to balance strategic oversight with an investment environment that allows private capital to participate effectively. As Polish companies increasingly pursue opportunities abroad, the debate over whether domestic regulatory and institutional frameworks are sufficiently attractive for long-term private investment is likely to become increasingly important.

Source: WEI

REALOGIS secures new tenant for CityLink logistics property in Dortmund

REALOGIS Immobilien Düsseldorf GmbH has secured a new tenant for a logistics property owned by CityLink in Dortmund.

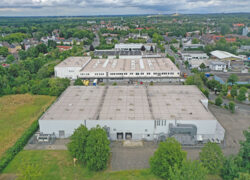
The property, located at Strümpenbusch 3 in the Oestrich industrial estate, was acquired by CityLink in 2021 through REALOGIS. The new lease follows the expiry of the previous tenancy agreement, ensuring the building’s continued long-term occupancy.

LAMPAG GmbH has signed a lease as the sole occupier of the property. The company is part of the internationally active Alu Group and manufactures Schüco windows, doors and façade systems.

Built in 1990 on a site of approximately 15,000 sqm, the logistics property provides around 5,950 sqm of lettable space, including approximately 4,530 sqm of warehouse space and 1,420 sqm of office accommodation across the ground and first floors.

The site also includes approximately 3,000 sqm of external space that can be used for car and truck parking as well as outdoor storage.

Nhood appoints Tomasz Oktaba as Development Projects Director in Poland

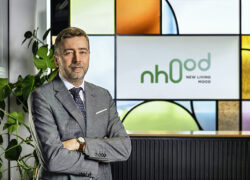
Nhood has appointed Tomasz Oktaba as Development Projects Director in Poland, strengthening its local development team.

In his new role, Oktaba will oversee the management and delivery of the company’s development projects in Poland and lead the local Development team.

He brings 25 years of experience in the real estate sector, covering project management, development processes and investment delivery across multiple asset classes. During his career, he has worked with international developers, investment funds and advisory firms.

Before joining Nhood, Oktaba served as Director of Project Management at Accolade Group, where he was responsible for the technical and development management of the company’s Polish investment portfolio, coordinating key development processes and overseeing new projects.

Earlier in his career, he held positions at JLL, CBRE, Dubai World, Prologis, First Property Group and Mace Group. He has also operated his own consultancy focused on project management, investment monitoring and technical due diligence.

At Mace Group, Oktaba was involved in the delivery of major Warsaw developments including Złote Tarasy and Rondo 1.

At Nhood, he will be responsible for the delivery of the mixed-use Wilanów Park project and for managing the company’s Development department in Poland. He will work closely with Marcin Klammer, Expansion Director for Central and Eastern Europe, who is responsible for the development of new projects across the region. Oktaba will also be part of the international development structure led by Sebastien Beurel.

Oktaba graduated from the Faculty of Civil Engineering at the Warsaw University of Technology. He holds construction management licences, is a LEED Green Associate and a Certified Commercial Investment Member (CCIM).

Hungary adopts new rules on UBO transparency and AIF regulation

Hungary has adopted Act XVIII of 2026, introducing changes to anti-money laundering (AML) requirements and the regulation of alternative investment fund managers (AIFMs) as part of legislation linked to the country’s access to European Union funding.

The new law amends both Hungary’s AML legislation and the country’s Alternative Investment Fund Managers Act, expanding transparency requirements for ultimate beneficial ownership (UBO) while simplifying certain regulatory procedures for closed-ended alternative investment funds (AIFs).

Under the revised AML framework, the definition of a UBO has been broadened to include additional individuals who exercise effective control over an entity, including those holding preferential voting rights, rights to appoint board members or supervisory board members, or entitlement to at least 25% of an entity’s profits or assets.

For closed-ended AIFs, the legislation introduces additional UBO criteria covering individuals with decisive influence over investment policy, asset allocation, risk management or key governance decisions, including the ability to amend fund rules, replace the fund manager or initiate the fund’s termination. Where no individual can be identified under the new criteria, the manager of the AIFM will be treated as the UBO.

The legislation also introduces enhanced due diligence requirements for financial institutions and other regulated entities providing services to closed-ended AIFs. These institutions will be required to review fund documentation, ownership structures, capital commitments and investor bases, while assessing complex structures such as parallel funds, holding companies and cross-border investment arrangements that could obscure beneficial ownership.

The law strengthens cooperation between Hungary’s Financial Intelligence Unit and the Integrity Authority by allowing the financial intelligence authority to initiate proceedings relating to the supervision of EU-funded projects.

In addition, reporting requirements for Hungary’s UBO register have been updated for closed-ended AIFs, with the first reports under the revised framework due for September 2026. Access to the register will also be extended to additional parties, including media organisations and entities engaged in contractual negotiations with relevant legal persons or arrangements.

The amendments to Hungary’s AIFM legislation simplify several supervisory procedures. Registration of closed-ended AIFs will require additional documentation to be submitted to the National Bank of Hungary, including depositary agreements and fund rules.

However, prior approval from the National Bank of Hungary will no longer be required for amendments to the fund rules of closed-ended AIFs or for mergers by absorption where the fund rules already authorise such actions. In addition, AIFMs will no longer need prior regulatory approval to acquire qualifying holdings, a requirement that will remain applicable only to UCITS management companies.

Alternative investment fund managers must comply with the new requirements by 30 September 2026. The legislation entered into force three days after its publication in the Hungarian Official Gazette.

Source: CMS

Crosspoint: Bucharest residential market recovers in H1 2026

Bucharest’s residential market showed signs of recovery during the first half of 2026, with stronger transaction activity in the second quarter reducing the decline recorded earlier in the year, according to Crosspoint Real Estate.

Citing data from the National Agency for Cadastre and Real Estate Publicity (ANCPI), Crosspoint said apartment transactions in Bucharest were down 16.6% year-on-year during the first quarter. However, activity rebounded in the second quarter, with transactions increasing by 2.2% in April, nearly 16% in May and more than 26% in June compared with the same months in 2025.

As a result, residential transactions in Bucharest totalled just over 21,000 units during the first six months of the year, representing a year-on-year decline of 1.7%. Across the wider Bucharest-Ilfov metropolitan area, 25,634 homes were sold, down 1.3% from the first half of 2025.

According to Crosspoint, the market is becoming increasingly differentiated by location, supply and housing segment rather than expanding uniformly across the city.

The largest number of transactions was recorded in Sectors 3 and 1. Sector 3 also led new housing deliveries between 2022 and 2025, with 11,447 completed units, while Sector 1 recorded the lowest level of new supply during the same period, with 4,627 completed homes. Crosspoint attributed the limited supply in Sector 1 to planning restrictions, high land prices and urban planning requirements, while demand has remained strong.

The consultancy said buyers are placing greater emphasis on location and access to infrastructure, including schools, healthcare, public transport and green spaces, rather than focusing solely on purchase price. Demand remains strongest in areas such as Theodor Pallady in Sector 3 and northern Bucharest, while more affordable southern and western districts have seen comparatively weaker demand.

Following an estimated 20% increase in new-home prices during 2025, price growth moderated in the first half of 2026. The average net residential price in Bucharest exceeded €2,600 per sqm, representing an increase of around 5% since December 2025.

Average asking prices ranged between €1,850 and €2,200 per sqm in western and southern districts, €2,600 to €2,900 per sqm in eastern Bucharest and more than €3,650 per sqm in northern areas. Crosspoint noted that neighbourhoods with constrained supply continued to record stronger price growth than areas with more abundant housing stock.

The report also highlighted broader market conditions influencing buyer behaviour, including inflation, labour market pressures, changes to VAT on residential property and the implementation of Romania’s Law 207/2025, which introduced additional buyer protection measures and stricter financing requirements for off-plan residential developments.

According to Crosspoint, these factors have contributed to more selective purchasing decisions, with buyers placing greater importance on long-term value, location and project quality.

BF.direkt survey shows weaker sentiment among German real estate lenders in Q2 2026

Sentiment among commercial real estate lenders in Germany weakened during the second quarter of 2026, according to the latest BF.Quartalsbarometer published by BF.direkt AG in cooperation with the Handelsblatt Research Institute.

The index fell by 9.74 points quarter-on-quarter to -25.97, indicating a lower willingness among lenders to provide financing. The survey was conducted between 8 and 16 June 2026.

According to the survey, 46.15% of respondents said financing conditions had deteriorated compared with the previous quarter, up from 27.27% in the first quarter. In addition, 23.08% reported a decline in new lending activity, compared with no respondents reporting a decrease in Q1.

The survey also found a shift towards smaller loan transactions. Lending volumes increased for loans below €10 million, while financing activity for transactions between €50 million and €100 million, as well as those exceeding €100 million, declined.

Risk management departments also played a greater role in lending decisions during the quarter. Around 26.92% of respondents said credit decisions were primarily driven by risk departments, compared with 9.10% in the previous quarter, while none indicated that new lending teams had the primary influence over lending decisions.

The survey also pointed to reduced competition among banks for financing transactions. Approximately 26.92% of respondents reported lower interbank competition, compared with 5.88% in the previous quarter. At the same time, 30.77% reported an increase in non-performing loans, up from 18.18% in the first quarter.

Despite the weaker sentiment, lending parameters remained relatively stable. Average loan-to-value (LTV) ratios for existing properties stood at 64.2%, while average loan-to-cost (LTC) ratios for development projects were 66.3%.

Financing margins varied by asset class. For standing assets, average margins ranged from 135 basis points for residential properties to 184.3 basis points for logistics assets. For development projects, margins ranged from 252.7 basis points for residential schemes to 301.1 basis points for office developments.

According to BF.direkt, the survey reflects a more cautious lending environment, with banks becoming increasingly selective in new financing while debt funds continue to provide financing for projects that no longer meet some banks’ lending criteria.

The Quartalsbarometer for Q2 2026 is available for download in German language under the following link: https://www.bf-direkt.de/

Panattoni appoints Sharad Gohil as CEO and Managing Director of its India business

Panattoni has appointed Sharad Gohil as Chief Executive Officer and Managing Director of Panattoni India, as the company expands its operations in the country’s industrial, logistics and digital infrastructure sectors.

Gohil brings more than 25 years of experience in real estate investment, asset management, capital raising and fund management across Europe and the Asia-Pacific region. During his career, he has completed more than US$4 billion in transactions spanning the industrial, logistics, office, residential, retail and hospitality sectors.

Before joining Panattoni, Gohil served as Chief Executive Officer of IndoSpace Capital Asia, where he oversaw a business with more than US$3.2 billion in assets under management. He was responsible for raising capital for development and core funds and managing the platform’s investment performance.

Earlier in his career, he held senior investment and asset management positions with Apollo Global Management, Citigroup Property Investors and AXA Real Estate Investment Managers.

Panattoni entered the Indian market in 2022 and has since launched several projects, including Panattoni Park NH71 in the Delhi-NCR region, a logistics park in Kochi and an aerospace-focused manufacturing hub in Hyderabad.

In his new role, Gohil will lead the company’s growth strategy across India’s logistics, manufacturing, e-commerce and digital infrastructure sectors, including data centres. Panattoni said it intends to expand its presence across the country’s major industrial corridors and logistics hubs, supported by its global development platform and investment partnerships.

Robert Dobrzycki said India is a strategic growth market for the company and that Gohil’s experience in platform development, capital raising and investment management will support Panattoni’s long-term expansion plans in the country.

front page info
LATEST NEWS