Galeria Katowicka expands tenant mix and completes store modernisations

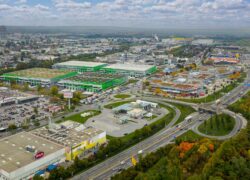
Galeria Katowicka added three new brands and completed a series of store relocations and refurbishments during the first half of 2026 as part of its ongoing leasing and asset management strategy.

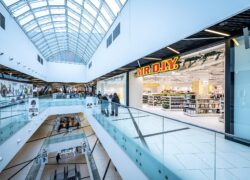
The shopping centre welcomed MR. DIY, Ploom and Wólczanka to its tenant mix. MR. DIY, making its debut at the centre, occupies approximately 850 sqm, introducing a non-food discount retail format offering household, DIY and everyday consumer products.

Wólczanka also returned to the centre after an absence of several months.

Several existing tenants expanded or relocated within the scheme. Rituals moved to a larger unit, increasing its store by approximately 80 sqm, while W.Kruk expanded by around 60 sqm. Ryłko also relocated its store to another floor within the shopping centre.

Galeria Katowicka said the refurbishment programme reflects broader retail design trends that emphasise warmer, more open store environments, with increased use of natural materials, softer lighting and simplified product displays.

Among the completed refurbishments, Tatuum opened its largest store in Poland, occupying nearly 400 sqm. Bershka expanded its premises and introduced its latest store concept, joining other Inditex brands already operating updated formats at the centre.

Other retailers completing refurbishment projects included Etam, Rossmann, Smoke, Swiss, Świat Książki, Verona and Ziaja, many of which also increased storefront visibility by introducing higher shopfronts and redesigned façades.

According to the shopping centre, the latest changes continue a programme that began in 2024. During 2025, the centre added 11 new brands, while 36 existing tenants upgraded or relocated their stores to reflect updated retail concepts and operational requirements.
Radisson Blu Hotel Complex Bucharest refinanced with €123 million facility

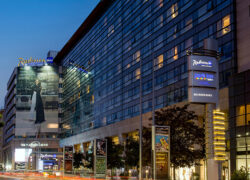
Revetas Capital and funds managed by Cerberus Capital Management have completed a €123 million refinancing of the Radisson Blu Hotel Bucharest complex.

The refinancing facility was underwritten by Deutsche Pfandbriefbank AG (pbb), which acted as sole arranger and lender. According to the parties, the transaction is the largest financing completed for a single hotel asset in Romania.

The financing closed at the end of June 2026, less than five months after the refinancing process began.

The Radisson Blu Hotel Complex comprises the Radisson Blu Hotel Bucharest and the Park Inn by Radisson Bucharest Hotel & Residence, providing a combined 835 rooms across interconnected buildings with a total gross built area of approximately 86,000 sqm. The property also includes conference facilities, restaurants, fitness amenities and entertainment venues centred around a shared courtyard.

Since 2019, the owners have invested more than €30 million in refurbishing the complex, including upgrades to guest rooms, meeting facilities, restaurants and other public areas. The refinancing also consolidates the property’s previous financing arrangements into a single facility.

According to Revetas Capital, the transaction demonstrates continued interest from international institutional lenders in the Romanian hospitality sector. The company noted that pbb, which does not have a retail banking presence in Romania, provided the entire financing facility.

The Radisson Blu Hotel Bucharest received the title of Romania’s Leading Business Hotel at the World Travel Awards in both 2023 and 2024. In 2025, it also became the first five-star hotel in Bucharest to achieve a BREEAM In-Use Excellent certification.

Wolf Theiss acted as legal adviser to the borrower, while Kinstellar advised Deutsche Pfandbriefbank. Sentient served as technical adviser to the lender.

US port fees on Chinese-built ships could reduce trade while benefiting some exporters

Planned US port fees on Chinese-built ships could reduce both US imports and exports while reshaping global trade flows, according to a new study by the German Institute for Economic Research (DIW Berlin).

The study, based on global ship registry and vessel tracking data, examines the potential impact of proposed US port charges due to take effect in November. The measures are intended to reduce dependence on Chinese-built vessels and support the domestic US shipbuilding industry.

According to DIW Berlin, Chinese-built ships are now deeply integrated into global maritime trade, with around half of newly built commercial vessels worldwide constructed in China. By comparison, the European Union’s share of global shipbuilding has declined from approximately 17% three decades ago to less than 3%.

The researchers estimate that the proposed fees would reduce US imports by around 0.2% and exports by 0.3%, reflecting higher transport costs.

The report suggests export-oriented emerging economies would experience the largest impact. Countries including Costa Rica, Vietnam and Pakistan could see exports to the United States decline by more than 8% under the modelled scenario.

The European Union could also be affected, with around three-quarters of its external trade transported by sea. According to the study, Finland, Denmark and Poland would face the largest reductions in exports to the US, with estimated declines of 5.0%, 4.4% and 3.0%, respectively.

By contrast, the study identifies Germany and South Korea as potential beneficiaries. Their exports to the United States could increase by around 2%, reflecting lower dependence on Chinese-built vessels and an opportunity to gain market share from more heavily affected exporters.

The report also highlights broader geopolitical implications. According to the authors, competition between the United States, China and the European Union is increasingly extending beyond traded goods to include maritime transport, shipping capacity, ports and supply chain infrastructure.

The study notes that the European Commission has proposed a new alliance for maritime industrial value chains aimed at strengthening European shipbuilding, promoting investment in innovative vessel technologies and expanding export financing for low-emission shipping.

The authors argue that Germany, as one of Europe’s largest exporting economies and home to major shipping companies and ports, could play a larger role in the development of the EU’s maritime industrial strategy.

German automotive industry faces structural transformation amid rising competition

Germany’s automotive industry is undergoing a structural transformation driven by the shift to electric vehicles, increased competition from Chinese manufacturers and changing consumer preferences, according to a new market assessment by Atradius.

The report cites forecasts from Oxford Economics that German automotive production will decline by 2.6% in 2026, followed by a further 1.8% contraction in 2027.

According to Atradius, German manufacturers face growing pressure as competition increasingly centres on software, battery technology and digital capabilities rather than traditional engineering strengths. The report argues that Chinese electric vehicle manufacturers have gained competitive advantages through vertically integrated supply chains, economies of scale and shorter product development cycles.

Atradius says these factors are contributing to weaker sales and profitability for some German manufacturers, alongside workforce reductions and production restructuring.

The report also highlights increasing pressure on automotive suppliers, particularly lower-tier component manufacturers. It notes that electric vehicles typically require significantly fewer components than vehicles powered by internal combustion engines, increasing the challenges for suppliers whose businesses remain focused on conventional powertrain technologies.

According to Atradius, companies that have not diversified their product portfolios or invested in technologies linked to electric mobility face greater restructuring risks. At the same time, the insurer notes that some suppliers are successfully adapting their operations and remain well positioned for the transition.

The report argues that regulatory requirements, including stricter carbon dioxide emissions standards, are accelerating the industry’s transformation. It also suggests that administrative procedures and data protection requirements have slowed progress in areas such as autonomous driving and digital mobility technologies.

Atradius further notes that government incentives for electric vehicles have had mixed results, while trade measures designed to protect European industry could increase input costs and contribute to international trade tensions.

Looking ahead, the report says Germany’s automotive sector will continue to face significant competitive challenges. By comparison, Oxford Economics forecasts 1.9% growth for China’s automotive industry in 2026.

Atradius concludes that companies with specialised technologies, strong partnerships in areas such as battery storage and successful business transformation strategies are likely to be better positioned as the sector continues to evolve.

The report also points to changing consumer behaviour, with purchasing decisions increasingly influenced by affordability, digital features and sustainability considerations. According to Atradius, consumers are also showing a greater preference for vehicle leasing over outright ownership.

REWE Group and LEH-Allgäu sign agreement for future operation of Feneberg stores

REWE Group, the self-administration of Feneberg Lebensmittel GmbH and LEH-Allgäu GmbH have signed an investor agreement setting out a proposed long-term solution for Feneberg’s retail network following the retailer’s insolvency proceedings.

Feneberg Lebensmittel GmbH entered self-administered insolvency proceedings on 1 April 2026.

The agreement provides a framework for the future operation of a substantial proportion of Feneberg’s 72 stores by LEH-Allgäu and REWE Group. The transaction remains subject to merger control approval and must also be implemented through an insolvency plan requiring approval from the company’s creditors. According to the parties, the court-appointed creditors’ committee has already approved the proposal.

The companies said the objective is to preserve the long-term operation of the stores, maintain employment and support local food retail provision across the Allgäu region and southern Germany.

Under the proposed arrangement, employees transferring to stores operated by REWE Group are expected to retain their existing employment contracts. LEH-Allgäu also stated that it intends to continue the employment contracts of staff working in the stores it will operate.

The parties said the agreement is intended to provide a long-term future for the Feneberg business while supporting regional economic development and maintaining local food retail services.

The transaction will not be completed until it receives approval from the relevant competition authorities and creditors under the insolvency process.

Scandic signs long-term lease for third hotel in Frankfurt

Scandic Hotels Group has signed a long-term lease agreement with Union Investment for a hotel property near Frankfurt Trade Fair and the Skyline Plaza shopping and convention centre.

The hotel, which has been part of the UniInstitutional European Real Estate open-ended real estate fund managed by Union Investment since 2008, was operated by Mövenpick Hotels & Resorts until the end of June 2026.

Before reopening in 2027 under the Scandic brand, the property will undergo refurbishment and be adapted to the operator’s brand and operational standards. The redevelopment will include upgraded guest rooms, updated interior design, the use of sustainable materials and improvements to guest facilities throughout the hotel.

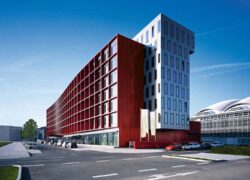
Following the refurbishment and reconfiguration of the existing building, the hotel will offer 296 rooms, an all-day restaurant and bar, a 100 sqm outdoor terrace and meeting and exhibition facilities. The conference area will comprise five meeting rooms with a combined area of approximately 500 sqm.

The agreement expands the existing relationship between Scandic and Union Investment in Germany. The companies also work together on the Scandic Hamburg Emporio, which opened in 2012 and marked Scandic’s entry into the German hotel market.

The Frankfurt property will become Scandic’s third hotel in the city, further expanding the group’s presence in one of Europe’s major financial and business centres.

MLP Group raises additional €100 million through green bond tap issue

MLP Group has raised an additional €100 million through a tap issuance of its existing Senior Green Notes, increasing the total size of the bond series to €400 million.

The additional notes were issued at 102.5% of their principal amount, resulting in a yield to maturity of 5.28%. Interest on the notes will be paid semi-annually.

The transaction expands the bond series originally issued in October 2024, when MLP Group raised €300 million.

According to the company, the proceeds will be used to finance and refinance projects that meet the eligibility criteria set out in its Green Financing Framework. Until the funds are fully allocated to eligible green assets, the proceeds may also be used to finance new developments, acquire land and cover costs associated with the issuance.

MLP Group said it is currently undertaking projects with a combined value of more than €300 million across several European markets. These include developments at MLP Business Park Munich, MLP Idstein near Frankfurt, MLP Hamburg East, MLP City Park Vienna, MLP Rzeszów, MLP Bieruń and further phases of MLP Pruszków.

The company stated that more than 60% of its current capital expenditure programme is allocated to projects in Germany, reflecting its focus on Europe’s largest logistics and industrial property market.

The additional notes carry the same terms and interest rate as the existing series. Following the expiry of the 40-day distribution compliance period, the new notes will be consolidated with the outstanding bonds and treated as a single series.

MLP Group intends to apply to list the additional notes on the Official List of the Luxembourg Stock Exchange and admit them to trading on its Euro MTF Market. The company said no listing prospectus has been prepared or approved for the tap issuance.

Report calls on RE:UK to strengthen real estate sector’s influence through housing and policy leadership

Housing should become the central focus of the UK’s newly formed Real Estate:UK (RE:UK) as it seeks to rebuild the real estate sector’s influence with government, investors and the public, according to a new discussion paper published by three former senior figures from the British Property Federation (BPF).

The paper, The Delivery Mandate: How Real Estate:UK can earn influence, was authored by Andrew Teacher, Peter Cosmetatos and Ian Fletcher.

RE:UK was established through the merger of the British Property Federation, the Association of Real Estate Funds (AREF) and the Investment Property Forum (IPF), bringing together organisations representing property owners, investors, fund managers and advisers.

The authors argue that the UK real estate sector has become less influential in public policy debates and public discussion in recent years, and that RE:UK has an opportunity to strengthen the industry’s role by demonstrating how long-term property investment can contribute to addressing national economic and social priorities.

The report recommends placing housing at the centre of RE:UK’s policy agenda, arguing that institutional investment could help increase housing delivery where planning policies, regulation and investment conditions provide sufficient certainty.

According to the paper, the contribution of real estate extends beyond residential development. The authors argue that institutional capital can also support investment in healthcare facilities, research and development, logistics infrastructure, data centres, defence assets, advanced manufacturing and urban regeneration.

Rather than focusing primarily on industry lobbying, the report recommends that RE:UK position itself as a partner in helping government address wider economic and social challenges. It also encourages the organisation to engage proactively with policymakers during the development of regulation, rather than responding only after legislative proposals have been finalised.

The authors further argue that well-designed regulation can improve market standards, enhance consumer confidence and distinguish professional operators from weaker parts of the market that have contributed to reputational challenges for the sector. They also recommend establishing a permanent in-house capability that combines communications, public affairs, policy expertise and research to support evidence-based engagement with policymakers and other stakeholders.

The report further recommends broadening RE:UK’s membership to reflect today’s investment landscape, including pension funds, overseas investors, private capital and specialist real estate operators. It concludes that the organisation should make housing the foundation of its public policy agenda, engage earlier in regulatory discussions, balance external advocacy with effective internal delivery, and build trust and credibility before seeking greater influence.

The discussion paper was published ahead of RE:UK’s inaugural annual conference, where industry leaders are expected to discuss the future direction of the UK’s real estate sector.

EBA consults on simplifying EU Taxonomy disclosures for banks and investment firms

The European Banking Authority (EBA) has launched a public consultation on proposals to simplify selected disclosure requirements under the EU Taxonomy framework for banks and investment firms.

The consultation, which opened on 1 July 2026, seeks feedback on changes designed to reduce the reporting burden while maintaining the transparency and comparability of sustainability-related disclosures. Responses can be submitted until 12 August 2026, with a public hearing scheduled for 16 July.

The proposals form part of a broader European Union initiative to streamline sustainability reporting. In March 2026, the European Commission asked the European Supervisory Authorities to provide advice on selected key performance indicators (KPIs) contained in the Taxonomy Disclosures Delegated Act.

Among the proposed changes are simplified KPIs covering banks’ fees and commissions, trading book activities and off-balance-sheet exposures. For investment firms, the EBA proposes introducing a simplified “other services” KPI intended to make reporting requirements easier to apply.

The consultation also proposes aligning grandfathering provisions with the EU Green Bond Regulation, providing additional guidance on group-level Taxonomy disclosures and clarifying how operating expenditure (OpEx) KPIs reported by non-financial companies should be treated when used by financial institutions.

According to the EBA, the objective is to simplify reporting requirements without reducing the usefulness of sustainability disclosures for investors and other market participants.

The proposals could affect banks’ and investment firms’ reporting processes, including data collection, KPI calculations, governance arrangements and internal controls. Banking groups operating across multiple jurisdictions may also need to review their consolidated reporting processes in light of the proposed guidance on group-level disclosures.

Institutions relying on sustainability information provided by non-financial counterparties are expected to assess how operating expenditure data is sourced, validated and incorporated into their own Taxonomy reporting.

Following the consultation, feedback will be used to support the European Commission’s review of the Taxonomy Disclosures Delegated Act, which forms part of the EU’s sustainable finance framework.

Source: Deloitte

Too Hot for a Beer? Extreme Heat Is Reshaping Europe’s Drinks Market

Europe’s increasingly frequent heatwaves may be changing consumer drinking habits in ways that challenge long-held assumptions within the beverage industry. While warm weather has traditionally been associated with stronger alcohol sales, emerging research suggests that extreme temperatures can produce the opposite effect.

A recent study by researchers from the University of California, ETH Zurich and North Carolina State University found that alcohol purchases generally increase as temperatures rise, but only up to a certain point. Once temperatures climb above roughly 32°C, demand begins to level off or decline, particularly in regions where extreme heat is less common. Although the research analysed U.S. retail sales, industry experts say the findings are becoming increasingly relevant in Europe as prolonged heatwaves become more frequent.

The shift reflects a broader change in consumer behaviour. During periods of extreme heat, many people reduce outdoor activities, spend more time in air-conditioned spaces and choose beverages that are perceived as more refreshing or hydrating. Public health authorities across Europe also advise limiting alcohol consumption during heatwaves because alcohol contributes to dehydration and makes it more difficult for the body to regulate temperature.

The changing pattern is prompting beverage manufacturers to review their product strategies. Several producers are expanding their portfolios of alcohol-free beer, low-alcohol drinks, soft drinks and other alternatives as consumers seek lighter options during periods of prolonged high temperatures. Industry analysts say the trend is likely to continue as extreme weather events become more common.

The impact, however, is not uniform across the hospitality sector. Some pubs, restaurants and bars continue to benefit from increased customer numbers during warm weather, particularly where shaded outdoor areas or air-conditioned interiors are available. In many cases, consumers are changing what they drink rather than avoiding hospitality venues altogether.

Climate change is also creating broader challenges for beverage producers. More frequent heatwaves can disrupt agricultural production, increase energy consumption and place upward pressure on production costs, while periods of extreme weather may also reduce disposable income and alter consumer spending patterns. These factors are encouraging companies to diversify product ranges and strengthen supply chain resilience.

According to the Copernicus Climate Change Service, Europe is warming faster than any other continent, with heatwaves expected to become both more frequent and more intense. As a result, beverage producers are increasingly treating climate adaptation as a long-term commercial issue rather than simply a seasonal challenge.

front page info
LATEST NEWS