CIJ.WORLD Announces Africa Expansion as Part of Global Editorial Growth Strategy

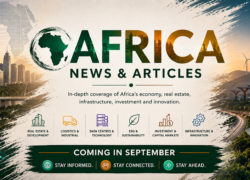
CIJ.WORLD has announced the launch of Africa News & Articles, a new monthly editorial section dedicated to one of the world’s most dynamic and rapidly evolving investment regions. Launching in September 2026, the initiative represents the next stage in the publication’s long-term strategy to become a leading global source of commercial real estate, investment and business news.

For more than three decades, CIJ has been recognised for its coverage of Central and Eastern Europe’s commercial property markets. As global investment has become increasingly interconnected, the publication has evolved beyond its regional roots, expanding its editorial focus to provide readers with a broader understanding of the international forces shaping property markets, infrastructure development, capital flows and economic growth.

The launch of Africa follows the successful expansion of CIJ.WORLD’s editorial coverage into Asia, where readers now have access to dedicated articles on India, Japan and other emerging and established economies. This broader perspective allows investors, developers and business leaders to compare opportunities across regions while understanding how global trends influence local markets.

The new Africa section will deliver original reporting and in-depth analysis on commercial real estate, logistics, industrial development, infrastructure, data centres, technology, sustainability, capital markets and economic policy. Rather than focusing solely on transactions, the editorial approach will examine the wider investment landscape, highlighting the structural changes driving growth across the continent and the opportunities emerging for international investors and businesses.

Africa has become an increasingly important destination for global capital as governments continue to invest in transport networks, energy infrastructure, manufacturing, digital connectivity and urban development. Expanding populations, accelerating urbanisation and improving business environments are creating new opportunities across sectors, making the continent an increasingly important part of the global investment conversation.

The expansion comes at a time of strong international growth for CIJ.WORLD. Recent audience figures show more than 30,000 active monthly readers, generating over 100,000 content interactions from readers in more than 100 countries. While Central and Eastern Europe remains the publication’s core market, its readership now extends across Asia, North America, the Middle East and other major investment regions, reflecting the increasingly global nature of commercial real estate and cross-border investment.

Robert Fletcher, CEO and Editor-in-Chief of CIJ.WORLD, said the Africa launch is only one part of a much broader transformation of the publication.

“Commercial real estate is no longer a regional industry – it is a global investment ecosystem. Capital, technology, sustainability and innovation move across borders faster than ever before, and our readers need journalism that reflects that reality. Africa is the next step in our journey, not the final destination.”

He added that CIJ.WORLD’s ambition is to create a platform that enables professionals to follow investment trends across continents rather than through isolated regional publications.

“Over the next twelve months we will continue expanding our editorial footprint, connecting markets, investors and ideas from every major region of the world. Our ambition is to build one of the world’s leading digital platforms for commercial real estate, investment, infrastructure and business intelligence while maintaining the trusted, independent journalism that has defined CIJ for more than three decades. Whether our readers are following opportunities in Warsaw, Tokyo, Mumbai, Johannesburg or New York, they should be able to find reliable, insightful reporting in one place – CIJ.WORLD.”

Looking beyond Africa, CIJ.WORLD has committed to a continuous programme of international expansion over the next twelve months. Additional countries and regional markets will be introduced progressively, creating a publication that offers readers a comprehensive view of commercial real estate and investment opportunities around the world. The objective is not simply to increase geographic coverage but to build a genuinely global editorial platform where professionals can follow the economic, political and market developments influencing investment decisions across multiple continents.

Alongside daily news reporting, CIJ.WORLD will continue to expand its original research, market analysis, executive interviews, conference coverage and sector-focused articles spanning office, industrial, logistics, retail, hospitality, residential, infrastructure, technology, ESG, artificial intelligence, data centres and capital markets. The publication also plans to increase its coverage of economic policy, foreign investment, manufacturing, energy and urban development, recognising that these sectors increasingly influence commercial property markets worldwide.

The addition of Africa represents another important milestone in CIJ.WORLD’s evolution from a respected Central and Eastern European publication into an international business media platform. As investors increasingly look beyond traditional markets and compare opportunities across continents, access to trusted, independent and globally connected reporting has never been more valuable.

With the launch of Africa News & Articles in September and further international expansion planned throughout the coming year, CIJ.WORLD continues its evolution toward becoming a truly global destination for commercial real estate, investment and business news—bringing together regional expertise with worldwide market intelligence for the benefit of investors, developers, financial institutions, governments and business leaders around the globe.
Water Security Is Becoming the Next Big Challenge for India’s Real Estate Market

For decades, India’s real estate market has been shaped by familiar considerations such as location, connectivity, pricing and infrastructure. Today, another factor is steadily moving to the forefront-water security. As rapid urbanisation places increasing pressure on natural resources, the availability of reliable water supplies is becoming a key determinant of where cities grow, how properties are valued and whether developments remain financially sustainable.

Climate scientists have repeatedly warned that water scarcity is no longer a distant environmental concern but an immediate challenge affecting many regions around the world. In India, where urban populations continue to expand rapidly, declining groundwater reserves, shrinking lakes and wetlands, and increasing pressure on municipal water systems are creating new risks for developers, investors and homebuyers alike.

Urban Growth Is Intensifying Water Stress

Many Indian cities have experienced decades of rapid construction with limited attention given to preserving natural water resources. Expansion over lakes, wetlands and recharge zones, combined with extensive concrete development, has reduced the ability of cities to replenish groundwater during the monsoon season.

At the same time, rising populations and growing commercial activity have significantly increased daily water demand. In several metropolitan regions, existing infrastructure is struggling to keep pace, forcing greater dependence on groundwater extraction, water tankers and long-distance supply networks.

This changing landscape means that water availability is becoming an important consideration alongside transport links and neighbourhood amenities when evaluating new residential and commercial developments.

The Financial Impact on Real Estate

Water shortages increasingly affect the economics of property development throughout a project’s lifecycle.

Construction activities require significant quantities of water for concrete production, curing, dust control and other site operations. Where municipal supplies are limited, developers often face additional costs associated with transporting water or arranging temporary supply infrastructure, increasing overall project expenditure.

After completion, buildings located in water-stressed areas may continue to experience higher operating costs. Dependence on tanker deliveries, deeper borewells, water treatment systems and recycling facilities can increase maintenance expenses, reducing the long-term profitability of commercial properties and affecting returns for investors.

Water availability is also becoming an important factor for purchasers and tenants. Residential buyers are placing greater emphasis on reliable water supplies before making purchasing decisions, while businesses increasingly favour office developments that can demonstrate resilient utility infrastructure. Properties with frequent supply interruptions may experience slower sales, reduced occupancy and weaker long-term value growth.

Financial institutions are also beginning to consider environmental risks more closely when assessing property investments. As climate-related risk analysis becomes more sophisticated, developments located in highly water-stressed areas could face greater scrutiny from lenders and insurers, potentially influencing financing costs over the coming years.

Reputation and Regulatory Considerations

Water-related issues can also create legal and reputational challenges for developers.

Projects that affect natural drainage systems, wetlands or existing water bodies may encounter regulatory delays, public opposition or litigation. Growing public awareness of environmental sustainability means that communities increasingly expect new developments to minimise their impact on local water resources rather than adding further pressure to already constrained systems.

As environmental standards continue to evolve, developers may also face stricter requirements regarding water conservation, wastewater treatment and sustainable infrastructure.

Building More Water-Resilient Communities

The industry is gradually recognising that water management must become an integral part of project planning rather than an afterthought.

Developers can improve resilience by conducting detailed water availability assessments before acquiring land and by providing greater transparency regarding long-term water supply strategies. Incorporating rainwater harvesting, groundwater recharge systems, efficient plumbing fixtures and smart water monitoring technologies can significantly reduce overall consumption.

Greywater recycling and on-site sewage treatment plants are becoming increasingly important in larger residential communities and commercial campuses, allowing treated water to be reused for landscaping, cooling systems and other non-potable purposes. Working closely with municipal authorities and surrounding communities can also strengthen local water infrastructure while reducing pressure on public supply networks.

Looking Ahead

Water security is rapidly becoming one of the defining issues for India’s urban future. As cities continue to expand, the ability of developments to secure reliable and sustainable water supplies will play an increasingly important role in investment decisions, project approvals and long-term property values.

For India’s real estate sector, adapting to this reality is no longer simply an environmental responsibility. It is becoming a business necessity. Developers that integrate water-efficient design, sustainable infrastructure and responsible resource management into their projects are likely to be better positioned to meet evolving market expectations while supporting more resilient urban growth in the years ahead.

Source: © CIJ.World India Research & Analysis Team

Jackson Walker uses AI to capture legal expertise and standardise decision-making

Rather than asking lawyers to become expert prompt engineers, Texas law firm Jackson Walker LLP is using artificial intelligence to capture the judgement of experienced partners and turn it into structured workflows that can be reused across the firm.

Speaking at AI4 2026 in Las Vegas, Greg Lambert, Chief Innovation Officer at Jackson Walker LLP, outlined how the firm is moving beyond individual AI prompts towards playbooks that embed legal expertise into repeatable processes.

The session, titled From Prompts to Playbooks: Turning Your Best Lawyers’ Judgement into AI Workflows, focused on how law firms can scale institutional knowledge while maintaining professional oversight.

Jackson Walker is a Texas-based full-service law firm with approximately 550 lawyers and around 380 professional staff. Lambert said the firm’s role is not to replace legal judgement but to make existing expertise easier to apply across matters and practice groups.

AI becomes part of everyday legal practice

The firm currently uses several AI platforms alongside established legal research services.

These include Harvey for drafting, document review and summarisation, Microsoft Copilot integrated with Microsoft 365, legal research platforms Westlaw Precision and Lexis+ AI, as well as pilot projects using Anthropic’s Claude Enterprise to develop more advanced agentic workflows.

Lambert stressed that specialised legal research platforms remain essential despite improvements in general-purpose AI.

“General models are getting better, but they are not legal research tools,” he said, noting that authoritative legal databases remain necessary to reduce the risk of inaccurate citations and hallucinated case law.

Adoption driven by practice groups rather than mandates

Instead of requiring lawyers to adopt AI, Jackson Walker introduced the technology gradually.

The firm initially licensed around 100 Harvey users before expanding adoption incrementally as interest grew.

Today, more than 600 employees have access to Harvey, with approximately 84% using the platform each week, according to figures presented during the session.

Rather than measuring success by the number of users alone, Lambert said the firm identified influential lawyers within each practice group, worked with them to solve specific business problems using AI, and then relied on those early users to encourage wider adoption.

This approach generated demand across the organisation without requiring mandatory implementation.

Converting experience into reusable knowledge

Lambert argued that many experienced lawyers already possess structured decision-making processes built over decades of negotiating contracts, reviewing documents and advising clients.

The challenge is extracting that knowledge in a way that others can use.

Instead of asking lawyers to create AI prompts from scratch, Jackson Walker analyses historical document revisions and identifies recurring legal positions taken by experienced partners.

These patterns are then converted into structured rule sets before being reviewed and edited by the lawyers themselves.

“The playbooks already exist,” Lambert said. “They’re contained in years of document mark-ups and negotiated agreements.”

One example involved a commercial real estate finance partner whose previous loan agreement negotiations were analysed.

The firm reviewed six completed transactions and identified approximately 90 recurring negotiating positions across seven key sections of borrower-side loan agreements.

After review by the partner, those positions were refined into a 49-rule playbook capturing standard negotiating positions, acceptable fallback language and circumstances where the firm would recommend walking away from a transaction.

The completed playbook could then be used by junior lawyers reviewing similar agreements while still allowing experienced partners to exercise judgement where required.

Supporting associates as well as AI

Lambert said the resulting playbooks have also become valuable training resources.

Rather than relying entirely on traditional mentoring, associates can review the reasoning behind common negotiating positions before working on live matters.

The playbooks are written in plain language and integrated into Microsoft Word, allowing lawyers to compare new documents against established guidance and identify clauses that comply with, differ from or fall outside accepted practice.

The same methodology is now being applied across multiple practice areas, including commercial contracts and transactional work.

Document management becomes an AI resource

The firm’s document management systems, including iManage and NetDocuments, have become an important source of institutional knowledge.

AI can search previous work while respecting ethical barriers that prevent lawyers from accessing confidential matters outside their authorised client work.

Lambert described one example where lawyers needed information about a serial litigant.

Instead of relying on firm-wide emails asking whether colleagues had previously encountered the individual, AI searched historical records and identified four lawyers with relevant experience, including one who had already prepared an internal memorandum outlining legal strategies used in earlier cases.

The information was retrieved within minutes rather than requiring manual searches across the organisation.

Measuring outcomes rather than usage

Lambert cautioned that user adoption alone provides only a partial measure of AI success.

While weekly usage statistics indicate whether staff are engaging with the technology, they do not show whether AI is improving business performance.

Instead, Jackson Walker focuses on operational measures including turnaround times, matter progression and revenue generation.

The firm also monitors governance, document access controls and AI operating costs to ensure that automation delivers measurable value rather than simply increasing computing expenses.

Building systems instead of prompts

Looking ahead, Lambert expects legal AI to move away from individual prompting towards structured systems built around established workflows.

Rather than asking lawyers to become increasingly sophisticated AI users, future systems are likely to guide them through familiar legal processes, automatically requesting the documents and information needed for each matter while applying established playbooks behind the scenes.

He also argued that clients are becoming more receptive to AI-assisted legal work, particularly where efficiency enables firms to handle additional matters without compromising quality.

For Lambert, the long-term opportunity lies less in teaching every lawyer to write better prompts than in capturing decades of professional judgement and making it consistently available across the organisation.

The approach reflects a broader shift taking place across professional services, where AI is increasingly being used to standardise expertise and improve knowledge sharing rather than simply automate individual tasks.

© 2026 cij.world

AI boom puts chips, data centres and energy at centre of global infrastructure race

The rapid expansion of artificial intelligence is turning computing capacity, semiconductor production and electricity supply into increasingly important constraints on economic growth, according to a discussion between former Intel chief executive Pat Gelsinger and OpenAI Head of Compute Sachin Katti at AI4 2026 in Las Vegas.

The discussion focused on the physical infrastructure required to support increasingly powerful AI models and the scale of investment needed across semiconductor manufacturing, data centres, electricity generation and communications networks.

AI4 2026 was held at The Venetian in Las Vegas from 4–6 August, bringing together technology companies, investors and corporate executives focused on the commercial development of artificial intelligence. The conference programme identifies Katti as OpenAI’s Head of Compute and Gelsinger as a general partner at Playground Global and former CEO of Intel.

Gelsinger argued that virtually every major development in AI ultimately depends on semiconductor capacity. While software models attract much of the public attention, the computing infrastructure underneath them is becoming one of the industry’s most significant economic and physical requirements.

He described semiconductors as the underlying fuel of an increasingly token-driven digital economy, pointing to the extraordinary technical complexity and capital requirements involved in producing advanced chips.

The challenge is no longer simply designing faster processors. New semiconductor fabrication plants can require investments running into tens of billions of dollars and take years to develop, while the most advanced manufacturing processes depend on highly specialised equipment, materials and supply chains concentrated among a relatively small number of global companies.

Companies such as TSMC and semiconductor-equipment manufacturer ASML have consequently become critical participants in the expansion of AI infrastructure.

Gelsinger argued that semiconductor companies have so far captured a substantial share of the economic value generated by the current AI investment cycle as demand for processors, advanced memory and manufacturing equipment continues to rise.

However, the next stage of the market could increasingly depend on improving efficiency rather than simply adding more computing power.

Current AI systems consume significant amounts of electricity and require enormous quantities of high-bandwidth memory and supporting infrastructure. Gelsinger said today’s generation of graphics processors remains relatively inefficient when measured against the amount of energy required to generate AI workloads.

Future chip designs are therefore likely to focus increasingly on reducing energy consumption, bringing memory physically closer to processing units and improving the amount of useful computing delivered for every watt of electricity consumed.

Katti similarly emphasised that the challenge facing AI companies extends well beyond semiconductor availability.

Building large-scale AI infrastructure requires simultaneous development of data centres, electricity connections, communications networks, cooling systems and computing equipment. Constraints at any one of these points can delay the deployment of new AI capacity.

The availability of power is becoming particularly important.

Gelsinger argued that the potential scale of AI infrastructure investment will ultimately be limited by how much electricity economies can produce and deliver to locations where new computing facilities are being constructed.

“You are fundamentally an energy entity,” he said of the emerging AI economy, arguing that companies cannot install billions of dollars of processors unless sufficient electricity is available to operate them.

That connection between AI and electricity generation is already beginning to reshape investment strategies across the global data-centre market.

Technology companies and data-centre developers are increasingly examining long-term electricity contracts, renewable energy projects, nuclear generation and on-site power solutions as they seek more reliable access to electricity.

For the property industry, this is changing the criteria used when selecting locations for large computing campuses. Land availability remains important, but access to high-capacity electricity networks, fibre infrastructure and cooling resources is increasingly determining where projects can realistically be developed.

Katti also highlighted the time required to bring new infrastructure into operation. Semiconductor development cycles can stretch across several years, while obtaining land, planning approvals and grid connections for large data centres can create additional delays.

Accelerating these development cycles will therefore become an important part of expanding global computing capacity.

At the semiconductor level, Gelsinger expects improvements in architecture and memory integration to significantly reduce the cost of AI inference over time.

Today’s processors frequently face limitations caused not by computing capability itself but by the speed at which information can be transferred between processors and memory. Bringing larger amounts of memory closer to computing units could substantially improve performance while reducing the infrastructure required for individual workloads.

Specialised processors may also become increasingly important, although both speakers cautioned against designing chips too narrowly around today’s AI architectures.

AI models are changing rapidly and semiconductor development cycles remain comparatively long. A processor optimised for a particular generation of models could potentially reach commercial production after the underlying algorithms have already changed.

This creates an unusual investment challenge for both semiconductor manufacturers and data-centre operators: infrastructure with multi-decade investment horizons is being developed for a technology whose underlying architecture can change within months.

The discussion also highlighted the growing strategic importance of semiconductor manufacturing.

Advanced chip production remains concentrated among a small number of companies and locations, creating concerns among governments and technology groups about supply-chain resilience. The complexity of rebuilding semiconductor manufacturing ecosystems means that simply investing additional capital cannot immediately create new production capacity.

Companies such as TSMC and ASML developed their technological positions over several decades, supported by networks of specialised suppliers, engineers and manufacturing expertise.

Nevertheless, the scale of investment now flowing into AI is creating incentives to expand production, develop alternative semiconductor architectures and improve manufacturing techniques.

Gelsinger said the economics of AI infrastructure will ultimately have to improve substantially if the technology is to expand to the scale currently anticipated by the industry.

The amount of capital flowing into processors, data centres and energy infrastructure is already enormous, and he suggested that future AI infrastructure investment could eventually become significant enough to be measured as a share of global economic output.

For real estate and infrastructure investors, the implications extend well beyond the technology industry.

The AI boom is increasingly linking the future of data centres with electricity generation, semiconductor manufacturing, industrial development and communications infrastructure. Markets capable of providing land, power, connectivity and predictable permitting processes are therefore likely to become increasingly competitive locations for new computing investment.

The next phase of AI development may consequently depend as much on factories, electricity networks and real estate as on advances in software.

As Gelsinger and Katti argued in Las Vegas, the race to develop more powerful artificial intelligence is rapidly becoming a race to build the physical infrastructure capable of running it.

© 2026 cij.world

AI Success Depends on Infrastructure, Not Just Adoption, Enterprise Leaders Told

Companies that succeed with artificial intelligence will not necessarily be those that adopt the technology first or impose the strictest controls, but those that build the organisational and technical foundations needed to support it safely, delegates heard during a keynote presentation at AI4 2026 in Las Vegas.

The presentation argued that enterprise AI has entered a new phase in which employees are increasingly deploying generative AI tools to solve business problems, often without formal approval from their organisations. Rather than viewing this trend solely as a governance issue, the speakers suggested it reflects growing demand for faster decision-making and more efficient workflows across large enterprises.

According to findings from a survey of 900 chief executives from companies with annual revenues exceeding USD 500 million across eight countries, 96% believe employees are already using generative AI without formal approval, while 42% said they believe at least half of their workforce is doing so. The survey results were presented by the speakers during the session and were not independently verified.

The keynote compared today’s AI adoption with the widespread introduction of spreadsheet software more than four decades ago. Business users rapidly embraced spreadsheets to solve operational problems before many IT departments had established governance frameworks, a pattern the speakers suggested is now repeating itself with AI agents.

Unlike spreadsheets, however, AI systems increasingly perform actions beyond analysing data. Modern AI agents can communicate with customers, automate workflows, generate reports, access corporate information and interact with enterprise systems, increasing the potential impact of errors or poorly governed deployments.

One demonstration highlighted how a single incorrect data reference in an AI-generated business dashboard could produce convincing visualisations while leading decision-makers to entirely inaccurate conclusions. The example was used to illustrate the growing importance of transparency and verification as organisations expand AI adoption.

The speakers argued that traditional IT operating models, developed when enterprise technology was scarce and highly centralised, are struggling to keep pace with the rapid adoption of AI across business units. Instead of positioning IT primarily as an approval authority, organisations were encouraged to evolve IT into a provider of secure platforms, governance, identity management, access controls and operational oversight.

A central theme of the presentation was that AI ownership should increasingly reside with the business teams responsible for operational outcomes. Under this approach, departments deploying AI agents would also become responsible for measuring productivity, return on investment and ongoing performance, in much the same way they manage human resources and operational budgets.

The keynote also highlighted the growing challenge of AI visibility inside large organisations. One example described a global manufacturer that initially believed it had approximately 40 production AI agents before a broader assessment identified more than 400 operating across different business functions, many without clear ownership or central oversight. While the example was anecdotal, it reflected a broader concern within the enterprise AI sector regarding so-called “shadow AI” deployments.

To address these challenges, the presenters called for organisations to establish enterprise-wide AI management capabilities, including visibility into which agents are operating, who owns them, what systems they can access, how much they cost and how effectively they perform.

The presentation concluded that successful AI strategies will depend less on restricting adoption and more on creating governance frameworks that allow business users to innovate while maintaining security, accountability and operational control.

As enterprise AI adoption accelerates, many organisations are shifting their focus from deciding whether employees should use AI to determining how that use can be managed responsibly, securely and at scale.

© 2026 cij.world

CNN outlines how AI changed its reporting on the Epstein files

CNN journalists used artificial intelligence, automated data collection and document-search tools to examine the large volume of material released by the US Department of Justice in connection with Jeffrey Epstein, while retaining human verification for editorial decisions, according to a presentation at AI4 2026 in Las Vegas.

The session, titled How Journalists Used AI to Cover the Epstein Files, featured Ryan Struyk, CNN Director of AI Innovation, senior reporter Marshall Cohen and senior data editor Matt Stiles. AI4’s current speaker programme confirms Struyk’s role as CNN’s Director of AI Innovation.

The presentation offered a practical example of how AI is beginning to change investigative journalism without necessarily replacing the traditional work of reporters.

Cohen compared the Epstein documents with previous large government releases, including Hillary Clinton’s State Department emails, the Mueller report and transcripts from the congressional investigation into the January 6 attack on the US Capitol.

In those cases, newsrooms often divided hundreds or thousands of pages between teams of journalists and reviewed them manually. The scale of the Epstein material made that approach increasingly difficult.

CNN therefore used Google Pinpoint as one of its principal tools for organising and searching the collection. Pinpoint can use optical character recognition and other technologies to search scanned documents, images, handwritten material, audio and other records while automatically identifying frequently mentioned people, organisations and locations. Google has subsequently added generative AI functions allowing journalists to query documents while linking responses back to the underlying source material.

For CNN, one of the immediate advantages was being able to place large volumes of material within a searchable environment rather than relying on individual journalists to keep separate records of names, references and relationships appearing across the documents.

Cohen said the technology helped reporters identify communications between individuals and begin mapping relationships contained in the files. Journalists then carried out the conventional reporting process of checking the original records, establishing context, contacting those mentioned and requesting responses before publication.

That distinction was central to the presentation.

CNN said it does not treat AI-generated findings as finished journalism. Instead, the systems are used to narrow large datasets, locate potentially relevant material and accelerate technical work that would otherwise absorb significant newsroom resources.

Building a system to capture millions of files

Stiles described a separate engineering challenge: acquiring the material itself.

The Justice Department did not provide the files as a single straightforward download. According to the CNN presentation, records were spread across large numbers of individual links and pages, requiring the newsroom to construct an automated system capable of detecting releases, downloading files, recording what had been collected and identifying gaps.

CNN first created a monitoring process using Python that checked the relevant Justice Department pages at regular intervals. When the structure or content of the page changed, the system sent an alert to the newsroom through Slack.

Once new material appeared, CNN used a combination of web crawling and systematic requests to identify and retrieve the underlying files.

Stiles said AI coding assistants helped the data team build and modify parts of this infrastructure quickly, including dealing with changes to website behaviour and maintaining logs of downloaded material.

The logging system was particularly important because journalists needed to know which records CNN had obtained and which remained outstanding.

It also allowed the newsroom to identify material that had subsequently disappeared from the Justice Department website while retaining a record of files already downloaded.

Rather than allowing AI to determine the conclusions of the investigation, CNN used it largely as an engineering and research assistant.

Stiles described the approach as similar to having additional junior developers available to help write scrapers, test systems and consider possible technical problems, while journalists and engineers remained responsible for the architecture and verification.

AI finds redaction problems

One of the more significant reporting outcomes came from material that traditional document-search tools could not easily examine.

The Justice Department release included photographs and video as well as conventional documents. CNN worked with AI visual-search company Visual Layer to examine more than 100,000 images contained within the released material.

That analysis identified images that appeared to contain information that should have been redacted, including images of children and documents containing personal identifying information.

CNN subsequently reported that more than a dozen photographs remained publicly accessible without appropriate redactions for nearly a month. After CNN contacted the Justice Department, the affected files were removed and replaced with redacted versions, according to CNN’s reporting.

CNN’s February reporting said the material included unredacted images of minors as well as passports and driving licences containing information such as identification numbers, addresses and dates of birth. The Justice Department told CNN at the time that it was continuing to address victim concerns, personally identifiable information and files requiring further redaction.

The example illustrates a potentially important application of AI in journalism: using machine-search capabilities to find accountability stories within datasets too large for practical manual examination.

Human experience still determines what is news

The CNN team was also clear about where the technology failed.

Cohen said one of the most basic questions in journalism remained difficult for AI to answer: what is actually new?

The Epstein case has generated court proceedings, criminal investigations, civil cases and extensive reporting over almost two decades. Millions of newly released records can therefore include a mixture of previously undisclosed material and documents that have already been public for years.

An AI system may locate a name, email or document, but it cannot necessarily determine whether the information represents a genuine new development.

That required reporters with long-standing knowledge of the case, including journalists who had followed previous Epstein proceedings and the trial of Ghislaine Maxwell.

The presentation also referred to the wider reporting community. Journalists could identify potentially important material surfaced by other reporters, search CNN’s own document collection to locate the original record and then independently examine and verify it.

This combination of machine search and human institutional knowledge was presented as more useful than asking AI simply to summarise an enormous collection.

Accuracy remains the limit

The session repeatedly returned to the risks of using AI in reporting where errors can have serious consequences.

The Epstein material is particularly sensitive because merely appearing in an email, address book, photograph or government record does not itself demonstrate wrongdoing.

CNN therefore said human review remained necessary throughout the process.

The newsroom tracked where files originated, logged downloads, tested collection systems and reviewed the source material behind potential stories.

That approach is consistent with the design of tools such as Pinpoint, where AI-generated responses can be traced back to the original documents rather than being treated as independent evidence.

AI expands what data teams can attempt

The practical effect, according to Stiles, was not eliminating reporters or data journalists but expanding the scale of projects a newsroom could reasonably attempt.

Systems that previously might have required days of development could sometimes be constructed or modified within hours. When websites changed or downloads failed, AI coding tools could help engineers develop and test alternative approaches more quickly.

The underlying journalistic standards, however, remained unchanged: reporters still needed to establish what a document meant, whether information was previously known, whether allegations were supported and what responses should be included.

Recent work by Stiles also shows that his role remains centred on conventional data journalism. In July, he was among the CNN journalists producing mapping and data visualisations following the Kumamoto earthquake in Japan, using geographic and seismic data to explain the scale and location of the event.

The Epstein project therefore offers a useful indication of where AI may have its strongest immediate impact in large newsrooms.

Rather than automatically producing articles, the technology is increasingly being used further upstream: monitoring government sources, acquiring records, processing scans, recognising entities, searching images, writing data-processing code and finding connections that reporters can subsequently investigate.

For journalism, that may prove more consequential than automated writing. The technology reduces the amount of time spent locating information, but the judgement over whether that information is new, accurate and newsworthy remains with journalists.

© 2026 cij.world

Poland’s Hotel Sector Cuts Debt as Tourism Recovery Strengthens HoReCa Finances

Poland’s hospitality industry is showing signs of financial recovery ahead of the peak summer travel season, with hotels leading a reduction in overdue debt across the wider HoReCa sector. While the improvement points to stronger liquidity, operators continue to face rising labour and operating costs that could test the sustainability of the recovery later in the year.

According to the latest data from the BIG InfoMonitor Register of Debtors and the BIK database, outstanding liabilities across the accommodation and food service sector stood at PLN 1.88 billion at the end of May 2026. This represents a 7.5% decline compared with a year earlier, while 401 businesses were removed from the register after resolving their financial difficulties.

The strongest improvement came from the accommodation sector. Hotels and similar lodging providers reduced their overdue liabilities by more than PLN 170 million, bringing total outstanding debt down to PLN 689 million. Catering businesses also recorded progress, lowering their overdue obligations by more than PLN 5 million to just over PLN 69 million.

Restaurants, however, continue to face more difficult trading conditions. Outstanding debt among restaurants and other food service operators increased by more than PLN 24 million over the past year, reaching almost PLN 902 million, making the segment the largest contributor to financial stress within the HoReCa industry.

Industry analysts believe the improvement has come at an important moment, with businesses entering the busiest period of the tourism season in a stronger financial position. Summer demand is expected to support occupancy levels and generate higher revenues, but companies remain cautious about the months that follow.

The sector continues to face mounting cost pressures. Higher wages, increasing utility bills and more expensive day-to-day operations are weighing on profitability, while many employers also face difficulties recruiting seasonal staff. In tourist destinations, businesses increasingly need to offer additional benefits such as accommodation and meals to attract employees, further increasing operating expenses.

Consumer behaviour is adding another layer of uncertainty. Research cited by BIG InfoMonitor suggests that many Polish households are adjusting their holiday plans because of higher living costs, often choosing shorter trips, destinations closer to home or lower-cost travel options. Although domestic tourism remains active, these changes could limit spending on accommodation and food services.

Separate surveys among small and medium-sized businesses indicate that rising operating costs remain the biggest concern for many service-sector companies. Nearly one-third of businesses are considering price increases in an effort to protect profitability rather than expand margins.

Industry observers warn that the true measure of the sector’s recovery will come after the summer holiday season. Strong occupancy during July and August is expected to improve short-term cash flow, but businesses will need careful financial management to maintain liquidity once seasonal demand weakens.

The latest figures nevertheless suggest that Poland’s hospitality sector has made meaningful progress in rebuilding its financial position since the pandemic. Whether that improvement can be sustained will depend on operators’ ability to balance higher costs with changing consumer spending patterns while maintaining profitability beyond the peak tourism season.

Poland’s Online Retail Success Masks Mounting Financial Pressure

Poland’s e-commerce industry continues to expand, but behind the impressive sales figures many online retailers are facing increasing financial strain. While more consumers are shopping online than ever before, rising fulfilment costs, tighter competition and changing customer expectations are making it harder for businesses to maintain healthy profit margins.

The latest market figures illustrate the contrast. Poland’s online retail market generated almost PLN 92 billion in sales during 2025, with internet purchases accounting for an increasing share of total retail spending. Yet, despite this growth, overdue liabilities among companies operating in the sector reached nearly PLN 462 million by the end of May 2026, continuing an upward trend from the previous year.

More than 5,600 online retail businesses are currently recorded with overdue financial obligations, highlighting that stronger revenues are not necessarily translating into stronger balance sheets.

Industry specialists say the challenge lies in the changing economics of e-commerce. Consumers now expect rapid deliveries, convenient payment options, simple returns and continuous communication throughout the purchasing process. While these services have become essential for remaining competitive, they require significant investment in logistics, technology and customer support.

As price competition remains intense, many retailers have limited scope to pass higher operating costs on to customers. This has left numerous businesses generating greater turnover while operating with increasingly narrow margins, placing additional pressure on cash flow.

The competitive landscape is also changing as shoppers become more deliberate in their purchasing decisions. Recent consumer research indicates that many Polish buyers now plan purchases more carefully, spend more time comparing offers and increasingly prioritise product quality over impulse buying. This behaviour forces retailers to compete not only on price but also on service quality and overall shopping experience.

Logistics has become one of the sector’s defining challenges. Industry research shows that delivery delays remain a common source of customer dissatisfaction, while poor returns experiences can permanently damage customer loyalty. For many retailers, maintaining efficient fulfilment operations has become just as important as attracting new customers.

The combination of rising operational expenses and demanding service standards means that online retailers must continually invest in warehouse operations, delivery networks, automation and digital infrastructure simply to remain competitive. These investments can improve long-term efficiency but also increase short-term financial pressure, particularly for smaller operators.

Analysts believe the sector’s long-term prospects remain positive as online shopping continues to gain popularity. However, sustainable growth will increasingly depend on operational efficiency rather than sales growth alone. Businesses capable of balancing customer expectations with disciplined cost management are expected to be better positioned as competition within Poland’s expanding e-commerce market continues to intensify.

Source: InfoMonitor

Contracts of Mandate Link Young Workers and Pensioners in Poland’s Labour Market

Contracts of mandate are increasingly serving two very different groups in Poland’s labour market: young people entering employment for the first time and older workers who want to remain professionally active after reaching retirement age.

According to experimental data from Statistics Poland (GUS), around 1.4 million people were working exclusively under contracts of mandate and similar arrangements at the end of 2024. The analysis was conducted separately from the 14.1 million people working in the national economy, excluding individual agricultural holdings.

Personnel Service argues that the arrangement has evolved beyond its traditional association with students. For younger workers, it often provides a relatively easy entry point into employment, while for pensioners it offers a more flexible way to continue working without returning to a full-time position.

Krzysztof Inglot, labour market expert and founder of Personnel Service, said the contract now effectively links the beginning and the end of working life. He also pointed to the flexibility of the arrangement as one of its main attractions for both employers and workers.

The occupational structure differs significantly by age and gender.

Among women aged over 60 working solely under contracts of mandate, the largest group was employed in cleaning roles in offices, hotels and related facilities, accounting for 12.6%. This was followed by workers in family support, social assistance and social work at 8.8%, domestic personal care at 7.6%, and nurses without specialisation or still in training at 6.7%.

Among men aged over 65, security work was the most common occupation. Employees protecting people and property represented 15.5% of the group. Other significant roles included simple occupations not classified elsewhere, senior management positions, passenger and van drivers, bus and tram drivers, and other security-related jobs.

For younger workers, the pattern is different. Women aged up to 26 are concentrated mainly in retail and hospitality. Shop assistants and cashiers account for 13.5% of young women working only under mandate contracts, while other sales positions represent a further 3.1%. Waitressing, cleaning work and beauty services are also among the most common occupations.

Young men are more strongly represented in transport, logistics and manual work. Passenger and van drivers account for 6.4%, while warehouse workers represent 6.3%. Other common jobs include simple industrial roles and postal or related occupations.

The figures highlight how flexible employment arrangements are increasingly being used at both ends of the age spectrum. For employers, older workers can help address labour shortages by bringing experience into sectors such as security, transport, care and services. At the same time, younger workers provide an important recruitment pool for retail, logistics and hospitality.

However, Personnel Service warns that the growing dependence on older workers in some occupations also points to a longer-term challenge. If businesses do not invest in younger staff and ensure that knowledge and skills are transferred between generations, labour shortages in selected professions could become more severe.

The latest data therefore suggest that contracts of mandate are no longer simply a temporary form of work associated with students. They are increasingly becoming part of a broader labour market model in which flexibility allows younger people to enter employment and older workers to remain economically active for longer.

Flexible Work Is Reshaping Europe Unevenly as Central and Eastern Europe Follows Different Paths

Flexible working is becoming an established part of Europe’s labour market, but the pace of change remains highly uneven between countries. New Eurofound research shows that while remote and hybrid work have become common in parts of northern and western Europe, several Central and Eastern European markets continue to rely much more heavily on traditional workplace models.

Across the EU, the share of employees working from home at least occasionally has risen sharply since 2015. The increase has been particularly strong in countries where digital work was already relatively advanced, while some eastern and south-eastern markets have changed only modestly. Eurofound’s findings suggest that access to flexible work is increasingly linked to employee control over working hours, workplace culture and national labour rules rather than simply technological capability.

For the office market, this matters because hybrid working is not developing as one uniform European model. Occupiers in some countries are adapting portfolios around a workforce accustomed to remote work several days a week, while employers elsewhere continue to depend primarily on physical workplaces. The result is a more fragmented European office market in which workplace strategy increasingly needs to reflect local employment habits.

Czechia stands out within the region

Among the five Central and Eastern European markets examined, Czechia has moved furthest towards more flexible working patterns. Eurofound identifies the country alongside Austria, Belgium, Germany, Estonia and the Nordic markets as one where a relatively high share of workers combine flexible schedules with greater control over their working hours. ef24032en.pdf

The proportion of Czech employees working from home at least occasionally increased by around 13 percentage points between 2015 and 2024, a substantial shift compared with the pre-pandemic period.

Czech legislation also allows teleworkers a degree of freedom in organising their working time, subject to legal limits and agreed availability requirements. Employers are also required under national rules to cover certain teleworking-related costs.

For office landlords and developers, this suggests that Czechia is likely to experience stronger structural demand for hybrid workplace concepts than some neighbouring markets. Occupiers increasingly need offices designed around collaboration, meetings and employee experience rather than full-time desk occupancy.

Slovakia has moved towards hybrid work, but more gradually

Slovakia has also recorded a meaningful increase in remote working, with the proportion of employees working at least partly from home rising by approximately 11 percentage points between 2015 and 2024. ef24032en.pdf

However, the country remains below the levels seen in northern and western Europe. Eurofound’s broader comparison places Slovakia among markets where employee control over working schedules is relatively limited compared with countries such as Sweden, Finland or the Netherlands.

Slovak rules allow teleworkers some flexibility in organising working time, and national legislation also addresses reimbursement of teleworking costs.

This creates a workplace environment in transition. Hybrid working has expanded, but conventional office attendance remains comparatively important, potentially supporting more stable demand for office space than in Europe’s most remote-work-oriented markets.

Poland combines changing regulation with relatively limited autonomy

Poland sits somewhere between the Czech and south-eastern European models. The country has introduced new rules allowing certain employees to request flexible working arrangements, including telework and adjusted schedules, as part of wider post-pandemic labour reforms.

At the same time, Eurofound’s 2024 data place Poland relatively low in terms of employee control over working hours compared with many western and northern EU countries.

Employers in Poland are legally required to address teleworking costs, with compensation generally determined through lump sums, reimbursement or arrangements established between employers and employees.

For Poland’s large office markets, particularly Warsaw, Kraków and Wrocław, the findings point towards an increasingly mixed model. Hybrid work is established in many professional and technology businesses, but office attendance remains structurally stronger than in markets such as the Netherlands or Sweden.

Hungary remains one of the less flexible markets

Hungary has experienced much less change in remote working behaviour. Eurofound reports that the share of employees working from home remained at around 7%, showing virtually no increase between 2015 and 2024.

The country is also among the EU markets with relatively low levels of employee control over working schedules. Earlier EU labour force data showed fewer than one in ten full-time employees in Hungary had significant autonomy over when they started and finished work.

Hungary has nevertheless introduced legal changes allowing some groups, particularly employees with caring or work-life balance needs, to request teleworking arrangements. National law also allows teleworkers some flexibility over their working schedules within agreed limits.

The gap between legal flexibility and actual workplace practice suggests that physical offices are likely to remain particularly important in Budapest’s corporate environment.

Romania remains one of Europe’s least remote-working markets

Romania records the lowest level of homeworking among the five countries and one of the lowest in the EU. Eurofound data show that only around 4% of employees worked from home at least sometimes in 2024, with virtually no change compared with 2015.

EU labour force data similarly showed Romania among the countries with the lowest levels of both teleworking and employee control over working hours.

However, Romania has been relatively active on the legislative side. Reforms introduced since 2021 provide employees with the right to request remote work and require employers to justify refusals. Certain employees caring for children also have stronger rights to telework.

Romanian legislation also gives teleworkers a degree of freedom in organising their working time, although actual adoption remains limited.

For Bucharest’s office sector, this suggests that hybrid working is likely to develop more slowly than in Prague or major western European markets. Physical workplaces therefore remain central to corporate operations, even as employers gradually introduce greater flexibility.

The wider workplace challenge

The Eurofound research also highlights that flexibility is not automatically beneficial. Employees working remotely or under highly flexible schedules are more likely to experience irregular hours, work during personal time and receive business-related communication outside normal working hours.

The impact can be significant. Among employees who are never contacted about work outside their normal hours, only 10% report a poor fit between work and personal commitments. That proportion increases to 36% among employees contacted every day outside working hours.

This helps explain why the debate around hybrid work is increasingly shifting from location to management. Greater flexibility works best when employees retain meaningful control over their schedules and organisations establish boundaries around workload, availability and working hours.

The regulatory response is also becoming more developed. Since the pandemic, Central and Eastern European countries have introduced new rules covering remote work, flexible scheduling and employee rights, although approaches differ considerably between jurisdictions.

For Europe’s commercial real estate market, these differences mean there is unlikely to be a single post-pandemic office model. Czechia is moving comparatively quickly towards hybrid working, Slovakia and Poland are following a more gradual transition, while Hungary and Romania remain much more dependent on traditional office-based work.

The long-term implication is not necessarily lower office demand across the region, but greater differentiation between workplaces. Buildings capable of supporting collaboration, flexible attendance and employee wellbeing are likely to become increasingly competitive, while markets with lower levels of remote working may retain stronger demand for conventional office capacity for longer.

front page info
LATEST NEWS