Electricity Infrastructure Emerges as Key Factor in India’s Industrial and Data Centre Property Expansion

India’s expanding data centre and manufacturing sectors are placing greater demands on electricity infrastructure, with access to reliable power becoming an increasingly important consideration for commercial and industrial property development. While land availability, transport connections and proximity to major markets remain central to investment decisions, the capacity of local electricity networks is playing a larger role in determining where new facilities can be developed and how quickly they can become operational.

The shift is particularly evident in data centres, advanced manufacturing plants and specialised logistics facilities, where electricity requirements are considerably higher than those of conventional warehouses or commercial buildings. For developers and investors, the availability of suitable land must increasingly be assessed alongside the cost, reliability and timing of electricity connections.

India’s data centre industry illustrates the scale of this change. Industry estimates indicate that operational capacity reached approximately 1.5 gigawatts in 2025, compared with estimates ranging from 375 to 520 megawatts in 2020. Forecasts suggest that capacity could increase to between 4.5 and 6.5 gigawatts by 2030, supported by demand for cloud computing, artificial intelligence, financial technology and digital services.

This expansion is creating additional requirements for electricity distribution networks and supporting infrastructure. Data centres operate continuously and depend on stable electricity supplies to maintain their computing and cooling systems. Electricity is also one of their largest operating expenses, with industry estimates suggesting that energy can account for approximately 60–70% of operating costs in some facilities.

As a result, the availability of sufficient electricity capacity can influence development decisions before construction begins. Large data centre projects may require dedicated substations, additional transformers, backup systems and the ability to increase power consumption as facilities expand. Where the existing network cannot accommodate these requirements, developers may face additional investment costs or longer delivery schedules.

Mumbai remains one of India’s principal data centre markets, accounting for approximately one-quarter of the country’s facilities. Its established telecommunications networks, financial services industry and concentration of corporate occupiers have supported investment in digital infrastructure. However, the development of larger campuses is also encouraging activity across the wider metropolitan region, including Navi Mumbai, Thane and surrounding locations.

These areas can offer larger development sites and opportunities to accommodate additional technical infrastructure. Electricity availability is one consideration alongside land costs, fibre connectivity and the potential for future expansion. The movement towards peripheral locations therefore reflects a combination of property and infrastructure requirements rather than evidence of a general relocation caused by electricity shortages.

Similar considerations are becoming increasingly relevant to India’s manufacturing sector. Semiconductor production, electronics assembly, pharmaceutical facilities and electric vehicle battery manufacturing require dependable electricity supplies to maintain production processes and protect sensitive equipment. Interruptions or fluctuations in supply can result in production losses, equipment disruption and additional operating expenses.

India’s Electronics Manufacturing Clusters 2.0 programme reflects the importance of coordinating industrial investment with infrastructure development. By December 2025, the government had approved 11 electronics manufacturing cluster projects and two common facility centre projects covering approximately 4,400 acres across 10 states.

The programme is intended to support manufacturing investment through planned industrial infrastructure and shared facilities. However, approved projects are at different stages of development, and the availability of land does not necessarily mean that electricity connections and supporting utilities are ready for immediate industrial occupation.

For manufacturers evaluating new locations, this distinction can influence investment schedules. A development may offer suitable land, transport access and government incentives but still require substantial work to provide the electricity capacity needed for production. Delays in completing these connections can affect factory construction, equipment installation and the commencement of operations.

Electricity infrastructure is also becoming an important consideration for India’s industrial corridor developments. Projects such as the Visakhapatnam–Chennai Industrial Corridor are intended to encourage manufacturing investment through improved transport connections and industrial infrastructure. Their development will also require coordination with electricity providers to accommodate additional demand from factories and supporting facilities.

The challenge is not limited to the amount of electricity generated nationally. Local transmission and distribution capacity determines whether individual industrial locations can obtain the power they require. Even where sufficient generation is available, additional substations, network connections or distribution upgrades may be necessary before large industrial projects can operate.

India’s logistics property sector is experiencing similar changes, although electricity requirements vary considerably between occupiers. According to CBRE, industrial and logistics leasing across eight major Indian markets reached approximately 27.1 million square feet during the first half of 2025, representing a 63% increase compared with the corresponding period in 2024.

Third-party logistics operators accounted for approximately 32% of leasing activity, followed by e-commerce companies at 25% and engineering and manufacturing occupiers at 19%. The figures reflect continued expansion in distribution networks and industrial operations, although the increase in leasing cannot be attributed directly to electricity demand.

Nevertheless, the growing use of warehouse automation, refrigeration and electric vehicle charging is changing the technical requirements of certain logistics properties. Automated distribution centres require electricity for handling equipment and inventory systems, while cold-storage facilities depend on continuous power to maintain controlled temperatures.

These requirements can create significant differences between otherwise similar industrial buildings. A conventional storage warehouse may operate with relatively limited electricity consumption, whereas an automated or temperature-controlled facility may require considerably greater capacity and more extensive backup arrangements.

For developers, anticipating these requirements during the planning stage can reduce the need for expensive alterations when a property is leased. Industrial buildings with sufficient electricity capacity may also be better suited to occupiers seeking to introduce automation or expand their operations.

The increasing use of renewable electricity adds another consideration to industrial property investment. Companies operating data centres and manufacturing facilities are examining renewable energy procurement as part of their efforts to manage electricity costs and environmental commitments.

However, access to renewable electricity does not remove the need for reliable grid infrastructure. Solar and wind generation fluctuate, while many industrial operations require continuous supply. Businesses must therefore consider how renewable electricity arrangements can be combined with dependable network connections, storage or other supporting systems.

Electricity tariffs, transmission charges and state-level regulations can also influence the financial attractiveness of different locations. For energy-intensive occupiers, differences in electricity costs may affect long-term operating expenses and investment decisions.

These developments have implications for industrial land values and property investment strategies. Sites with confirmed electricity availability and sufficient capacity for future expansion may offer advantages over locations where substantial infrastructure upgrades are required.

However, the extent to which these advantages translate into higher rents or land prices remains dependent on local market conditions, occupier requirements and the availability of comparable properties. There is insufficient evidence to conclude that electricity-ready industrial sites consistently command a measurable premium across India.

The more immediate consideration for investors is the effect on development costs and project delivery. Additional electricity infrastructure can increase capital expenditure, while uncertainty over connection schedules may delay the completion or occupation of a facility.

As India’s digital economy and manufacturing base continue to expand, electricity infrastructure is likely to become a more prominent element of industrial property planning. The requirements of data centres, advanced factories and specialised logistics facilities are placing greater emphasis on coordination between developers, occupiers, electricity suppliers and public authorities.

For India’s commercial real estate market, the availability of land and transport infrastructure will remain important, but the ability to secure dependable electricity within a predictable timeframe could increasingly influence where major industrial investments are located. Developers able to align property construction with the delivery of essential power infrastructure may be better positioned to attract occupiers and manage the financial risks associated with large-scale projects.

Source: © CIJ.World India Research & Analysis Team
Romanian Wind Farm Development Secures €367 Million in Bank Financing

Rezolv Energy has arranged financing of up to €367 million for a 292.5 MW wind power project in Romania’s Constanța County. The development, known as Dunarea East, is expected to enter operation in early 2029, adding to the country’s electricity generation capacity.

The funding agreement involves six financial institutions, including Société Générale, Erste Group Bank, Raiffeisen Bank International together with Raiffeisen Bank S.A., Mizuho Bank Europe, Raiffeisenlandesbank Niederösterreich-Wien and the European Bank for Reconstruction and Development (EBRD). Denmark’s Export and Investment Fund (EIFO) is supporting the transaction, while the EBRD’s involvement is backed by an InvestEU guarantee.

The project received a Contract for Difference under Romania’s second renewable energy auction in 2025, covering 211 MW of the planned generating capacity. Rezolv Energy has also agreed to supply electricity to international retailer Ahold Delhaize under a long-term corporate purchasing arrangement. These agreements reduce some of the uncertainty surrounding future revenue and provide lenders with greater visibility over the project’s ability to meet its financial obligations.

The transaction follows three previous financing agreements secured by Rezolv Energy for renewable electricity developments in Romania. The company arranged up to €291 million for the first phase of the VIFOR wind farm, up to €331 million for its second phase and up to €561 million for the Dama Solar project. Together with Dunarea East, the four financing packages amount to approximately €1.55 billion in potential borrowing.

Rezolv Energy is backed by investment groups Actis and Mubadala. Its existing Romanian wind portfolio includes the 461 MW VIFOR development in Buzău County, where the first 192 MW phase began commercial operation in October 2026. The remaining 269 MW is under construction, with completion expected in 2027.

Once Dunarea East begins operating, Rezolv Energy’s combined wind generation capacity in Romania is expected to exceed 760 MW. The additional electricity supply will form part of Romania’s expanding renewable energy infrastructure, although the eventual contribution to the national electricity system will depend on actual generation and operating conditions.

The financing arrangements illustrate how large renewable energy developments increasingly depend on a combination of commercial lending, public financial guarantees and long-term electricity sales agreements. Such structures can reduce exposure to fluctuations in wholesale electricity prices, although construction costs, delivery schedules and operational performance remain important financial considerations.

For Romania’s construction and infrastructure sectors, the project represents another substantial investment in electricity generation facilities. The development will require construction works and associated technical infrastructure in Constanța County, with completion currently planned for early 2029.

The agreement also indicates continued participation by international banks in financing Romanian renewable energy projects. However, the announced €367 million represents the maximum financing available under the agreement rather than an amount necessarily disbursed at signing.

UK Housing Market Slows as Higher Mortgage Costs Weigh on Buyers and Developers

Britain’s residential property market is facing renewed pressure from rising borrowing costs, weaker buyer interest and a large number of homes available for sale. In a trading statement published on 6 November 2026, property platform Rightmove reported declining buyer enquiries and fewer agreed sales, alongside continued difficulties in the new-build sector. The findings provide an indication of changing market conditions, although they are based on the company’s own market monitoring rather than official national housing statistics.

Rightmove reported that buyer demand had declined by 10%, while agreed property sales were 9% lower. The company attributed the weaker activity partly to uncertainty over interest rates and household finances. It also noted that the number of homes available for purchase remained unusually high, increasing competition between sellers. At 31 October 2026, its average house-price measure was 0.3% below the corresponding level a year earlier. This reflects advertised property prices rather than the amounts ultimately paid when transactions are completed.

Mortgage financing has become a more significant obstacle for prospective purchasers. According to Rightmove, the average quoted interest rate for a five-year fixed mortgage increased from 5.0% on 30 June to 5.5% on 31 October 2026. The increase followed changes in financial-market expectations and preceded further concerns about borrowing costs in 2027. Higher mortgage rates can reduce household purchasing budgets and increase monthly repayments, particularly for first-time buyers and existing homeowners approaching the end of fixed-rate agreements.

The effects are also being felt by residential developers. Rightmove reported that the number of active new-home developments represented on its platform was 6% lower at 31 October than at the end of December 2025. This measure concerns developments marketed through the company and should not be interpreted as a direct reduction in national construction output or housing completions. Nevertheless, the decline indicates a challenging environment for housebuilders seeking to attract purchasers and maintain development activity.

The government’s proposed Your First Home initiative has provided some encouragement to developers, according to Rightmove, but its implementation remains a determining factor. The scheme is expected to begin during the second quarter of 2027, with any meaningful effect on housebuilding volumes unlikely until later that year. For developers, the timing of support measures is important because decisions about land acquisition, construction starts and project financing often need to be made well before homes become available for sale.

Conditions in the rental market were comparatively stronger. Rightmove reported an increase in enquiries for each available rental property, while advertised rents were 2.9% higher than a year earlier. These figures indicate continued competition among prospective tenants, although they do not measure changes in rents paid under existing tenancy agreements. The contrast between rental interest and weaker purchasing activity may be relevant to investors in professionally managed rental housing, but the company did not establish a direct causal relationship between the two trends.

Despite the difficult residential market, Rightmove expects its own financial results to improve. The company forecasts revenue growth of 6% to 7% in 2026, with underlying operating profit increasing by at least 3%. It has raised its expected growth in underlying earnings per share from at least 5% to at least 7%. For 2027, Rightmove anticipates revenue growth broadly similar to 2026 and underlying operating profit growth of between 4% and 7%, supported by additional digital services, operational improvements and cost management.

For developers, lenders and residential investors, the latest statement highlights the continuing importance of mortgage affordability and consumer confidence in determining housing-market activity. Reduced buyer interest may influence the timing of new residential projects, while sustained rental demand could support investment in alternative housing models. However, Rightmove’s measures should be considered alongside official transaction statistics, construction data and household earnings before drawing wider conclusions about the direction of the UK housing market.

CIJ Interview: ITB targets faster turnover at Devina with 9.9% buyer entry and demand-led phasing

ITB Development is using Devina in Bratislava’s Devínska Nová Ves to pursue a residential strategy built around lower initial buyer payments, tighter development margins and construction phases released according to actual market absorption.

In an interview with CIJ.World, Filip Matovič, COO of ITB Development, says buyers at Devina are required to pay just 9.9% of the apartment price initially, with the remaining 90.1% generally payable following occupancy approval. Buyers with additional capital can also opt for ITB’s Profit 5.5% investment product, currently offering a return of 5.5% per annum. These funds and the return can subsequently be used towards the apartment purchase, in accordance with the agreed terms.

CIJ.World: Devina is significantly larger than many of ITB Development’s previous projects, with more than 600 units planned across three phases. How are you deciding the pace at which each phase should be released and built?

Filip Matovič: This was the first time we succeeded in acquiring quite a large piece of land, which gave us considerable flexibility in planning. From the beginning, we knew we wanted to create something similar in philosophy to Čerešne, with residential buildings designed around families, greenery and community. We designed the project from the outset to be flexible in terms of phasing. There are three principal phases, but each can also be divided into smaller stages. The first phase consists of three buildings with around 223 apartments. Instead of bringing all three buildings to the market simultaneously, we started sales with the first building. This allows us to see how quickly the market absorbs the apartments before releasing the next one. The important advantage is that we prepared the permitting for the wider development, so we can add another stage to sales and construction relatively quickly when demand supports it. Sales began in September, and after a little more than a month we are very satisfied with demand. Based on the response so far, we expect to introduce the next building relatively soon.

CIJ.World: So market absorption, rather than simply a predetermined construction timetable, determines when you deploy capital into the next stage?

Filip Matovič: Yes. Market absorption is one of the main factors. You can decide to construct everything at once, but that can create problems on the sales side if the local market cannot absorb that number of apartments. We therefore look at every location individually. It is not really a question of our construction capacity because capacity can be increased. The important question is how quickly apartments can be sold in that particular location. We already know, for example, that we can sell more apartments within a phase at Čerešne because it is an established residential project and the surrounding Dúbravka market is larger than Devinska Nová Ves. In another strong location, such as Petržalka, the market could potentially absorb a much larger number of apartments in one stage. This flexibility means we are ready to accelerate subsequent stages as demand grows, while keeping the pace of development aligned with the market.

CIJ.World: Devina combines relatively accessible pricing with ceiling heating and cooling, heat pumps, photovoltaics and substantial communal amenities. With construction costs remaining under pressure, how have you protected the specification without making the apartments unaffordable?

Filip Matovič: A significant part comes from the knowledge accumulated through previous projects. Because we controlled a large site from the beginning, we could position and design the buildings efficiently. When you acquire a smaller plot and have to maximise the number of apartments within tight constraints, you often have to make compromises to satisfy orientation, sunlight and other requirements, and those compromises can increase construction costs. Here, the characteristics of the site allowed us to optimise the shapes and sizes of the buildings and approach procurement very precisely. We also have experience with technologies such as ceiling heating and cooling. We understand the costs and how to implement these systems efficiently, so providing a higher technical standard does not necessarily have to create an excessive construction-cost premium. There is no magic solution. It comes down to efficiency and the knowledge gained from previous developments.

CIJ.World: You have also indicated that ITB is prepared to accept a lower margin on Devina. Why?

Filip Matovič: We are looking at how quickly we can deliver the project and achieve turnover. Rather than simply trying to maximise the margin, we can decrease the margin somewhat if that helps us move through the project faster and achieve quicker capital turnover. The design of Devina helps us do that because the buildings are relatively efficient and repeatable. The first phase contains three similar buildings.

We have applied the knowledge and experience gained from our previous developments, including Čerešne, to make the project efficient from the outset. Because we were able to plan the entire site as a whole, we could coordinate building layouts, technical solutions and construction methods across the development. The first phase, for example, consists of three buildings that share key design principles and technical solutions. This creates efficiencies in construction and procurement and allows us to respond more quickly to demand.

CIJ.World: Buyers initially provide only 9.9% of the purchase price, with most of the balance payable after occupancy approval. How does that work alongside ITB’s own construction financing?

Filip Matovič: Our financing structure is generally straightforward. We provide our own equity at the beginning and then use bank financing once the required sales conditions have been achieved. Across our projects, the initial buyer installment is generally between 10% and 15%, with the remaining 85% to 90% paid after the occupancy permit. For Devina, we decided on 9.9%. There is actually a marketing reason behind the figure: Devina is our ninth project, so we wanted to work with the two nines. We agreed with the bank that we could go slightly below the usual 10% threshold. It does not fundamentally change our equity requirement. The project is principally financed through our equity and bank financing.

CIJ.World: Why is reducing that initial payment important in the present residential market?

Filip Matovič: The market standard for the initial instalment can be around 15%, while some developments require buyers to provide 20% or even more. We wanted to create an opportunity for customers who might find it difficult to provide 15% immediately, so they can secure an apartment at Devina with 9.9%. For example, if an apartment costs €200,000, the required initial payment is just under €20,000. At the same time, some buyers have more equity available. If that customer has €40,000, for example, they can provide the required amount and place additional money with us. We calculate interest on that additional amount, currently at 5.5%, and when the apartment is ready, the buyer can use those funds together with the accumulated return towards the final apartment payment. From our perspective, we see it primarily as an additional service for the customer.

CIJ.World: What price levels did you introduce when sales started?

Filip Matovič: When we launched sales in September, we started at relatively accessible levels. For example, three-room apartments were available from €256,000. Naturally, buyers looking at a new price list tend to focus first on the lowest-priced apartments, and those units have already sold. When we introduce the next building within the first phase, however, we expect to bring another selection of apartments to the market at attractive entry prices.

CIJ.World: Who is actually buying? Did you expect demand primarily from local owner-occupiers, employees in western Bratislava or investors?

Filip Matovič: Across our developments, our main focus is on people who are actually going to live in the apartments. We are primarily looking at families. Our apartments can be somewhat above the market average because we try to provide a higher standard, whether through materials, larger windows or technical features such as ceiling heating and cooling. Because of that positioning, we are generally not the first choice for pure investment buyers. Across our projects, investors typically account for less than 10% of purchasers, and we expect Devina ultimately to follow the same pattern. Devinska Nová Ves is also quite a distinctive part of Bratislava. We expected a significant proportion of demand to come from local buyers. The second important group is people who may not currently live there but work nearby, including employees connected with the Volkswagen plant, while investors represent the third group. At the beginning of sales, the investor percentage is always higher because investors react quickly to a new price list and calculate the potential return. At Devina, our first five buyers were investors. After that, we increasingly began seeing people looking for apartments in which they actually intend to live.

CIJ.World: Mortgage affordability remains challenging. What makes a residential development work under these conditions?

Filip Matovič: You have to have the right product. It starts with the land. You need infrastructure, appropriate zoning and sufficient development capacity, but you also need a site where the buildings and apartments can be positioned efficiently. We receive many offers for development land in Bratislava. Sometimes the headline price looks reasonable and the zoning initially appears suitable, but when you analyse the site you discover problems. The orientation may make it difficult to satisfy sunlight requirements, for example, or you can have a well-oriented site where the zoning only permits industrial development. Finding the right land is fundamental. With Devina, our objective was never to create a luxury development. We wanted a good-quality product for people who can afford it. Even when mortgage costs are higher, there is still demand if you combine the right price with good quality. Once buyers have decided on the general location, a difference of five minutes between competing projects may become less important. The product itself then becomes a major factor. That is where we compete, through the apartments, architecture, greenery, communal spaces and sense of community.

CIJ.World: If demand remains strong, how quickly could you complete the entire development?

Filip Matovič: It will ultimately depend on the market and the speed of sales. Construction of the first phase is expected to start next year, and we assume approximately two and a half years for delivery. If demand remains strong and allows us to move quickly from one phase to another, the entire development could potentially be completed by around 2031. But flexibility is important. The first three buildings are defined, while the timing of the following stages will depend on market absorption. If demand is strong, we can accelerate. If the market becomes more difficult, we have the ability to postpone subsequent phases.

CIJ.World: What did you learn from Čerešne that has materially changed how you are approaching Devina?

Filip Matovič: We started Čerešne more than ten years ago. Our focus was on four main elements: quality design, quality construction, greenery and community. We discovered that this matched what buyers wanted, but we also learned a great deal about how people actually use their apartments. In the first phase of Čerešne, for example, we created many different layouts and put considerable effort into making apartments individual. Over time, we realised that customers do not necessarily need so many variations. There are layouts that simply work very well. From phase to phase, we therefore improved the layouts and became much more precise about what customers value, and we have applied those lessons to Devina. Terraces are another example. Buyers want outside space, but they do not necessarily want the largest possible terrace if it substantially increases the purchase price. The objective is to provide enough outside space, storage and room for children while keeping the apartment compact enough to remain affordable. We have also carried forward the elements that worked particularly well at Čerešne, including landscaped common areas, places for children and shared greenery.

CIJ.World: Is creating larger multi-phase neighbourhoods now something ITB wants to replicate elsewhere?

Filip Matovič: Yes. We are constantly looking for locations where we can develop projects over several stages. Our focus remains primarily on creating places where people live rather than developments dominated by apartments purchased purely for investment. One of the most encouraging things at Čerešne is seeing people remain within the neighbourhood as their lives change. Someone may initially buy a smaller apartment and later buy a larger one in a subsequent phase rather than leaving. We also see residents buying apartments for their parents or children, and friends moving into the neighbourhood following recommendations. That tells us the community concept works, and it is something we want to reproduce elsewhere.

CIJ.World: How large can such a development become while still retaining a genuine community?

Filip Matovič: When Čerešne is completed, it will have close to 1,000 apartments. Depending on household sizes, that could mean roughly 2,500 to 3,000 residents, effectively the population of a small village. For us, that remains a scale at which you can still create a genuine community. If I had to identify an approximate optimum for this type of neighbourhood, around 1,000 homes can still work very well. Within an individual building, however, the considerations are different. For a family-oriented project, you do not want people to feel overcrowded. There needs to be air, space and a sense of freedom. We are preparing another project with a partner that could contain approximately 300 to 400 apartments in one building or development stage. It is closer to Bratislava city centre and aimed at a different customer. We would describe that project as more premium rather than luxury. Ultra-luxury residential development is not our core business. We want to develop good apartments for people to live in.

CIJ.World: If we return in three or four years, what would constitute success for Devina?

Filip Matovič: Our ambition is to create a successful residential community with quality construction, good amenities and a higher standard while maintaining a price that remains attractive to the market. We have given ourselves a difficult task because delivering all of those things together is not easy. But I hope that when we sit down again in three or four years and look at what has been completed, we will be able to say that we succeeded in that mission.

Source: © CIJ.World


Green House Development Reports Early Apartment Sales at Warsaw’s Ciszewska Street Project

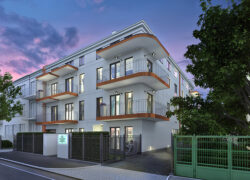
Green House Development has reported that almost a quarter of the homes planned at its Ciszewska 12 project in Warsaw have been sold, as construction continues on the residential building in the Włochy district. The development will contain 19 apartments and is scheduled for completion in May 2027.

The four-storey building will provide apartments measuring between 32 and 64 sqm. Work is currently taking place below ground level, where a parking area for residents is being constructed. The developer states that construction is proceeding according to its original timetable.

The reported sales level represents approximately four to five apartments, although the company has not provided an exact figure. No information has been released regarding transaction prices, the total value of the development or the proportion of purchases financed through mortgages.

The project is being constructed as a single residential building rather than a larger housing complex. Its design incorporates features associated with Warsaw’s older apartment buildings, including decorative balcony elements and metal railings, alongside contemporary construction methods. Each apartment will have either a balcony or access to a private garden.

The development is located on Ciszewska Street in Włochy, an established residential district containing a mixture of housing and local services. The surrounding area includes schools, shops and other neighbourhood facilities, with transport connections to central Warsaw.

Buyers will also have access to an optional apartment finishing service provided through Decoroom. Underground parking is included in the building’s design.

The project provides a relatively small addition to Warsaw’s residential supply, where development activity ranges from individual apartment buildings to large housing estates. Its limited number of units means that a small number of transactions can account for a significant share of the total apartments available.

Green House Development expects construction to be completed in May 2027, when the 19 apartments are scheduled to become available for occupation.

PLN 115 Million Transformer Factory Opens in Łódź as Industrial Investment Continues

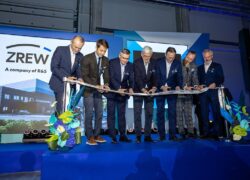
A new power transformer manufacturing facility has opened in Łódź following the completion of a PLN 115 million investment developed by Panattoni for ZREW Transformatory. The factory, officially opened on 3 November 2026, is expected to employ approximately 200 people and will allow the manufacturer to increase its production capacity.

ZREW has operated in Łódź for almost 70 years, and the new facility represents an expansion of its existing manufacturing activities. The company expects the investment to double its production capacity and enable the manufacture of larger electrical transformers used in power transmission and distribution networks.

The building was designed to accommodate industrial processes involving equipment weighing more than 200 tonnes. Its production areas contain 16 overhead cranes with a combined lifting capacity of 360 tonnes, while an external gantry crane and an internal air-cushion transportation system allow large components to be moved between manufacturing and testing areas.

The factory also includes high-voltage testing chambers, electromagnetic protection systems and a dedicated drying installation for transformer components. Parts of the building reach 20 metres in height, while selected floors are designed to support loads of up to 210 tonnes. Office and employee facilities form part of the development.

JLL advised ZREW during the location selection and commercial negotiations. The project qualifies for investment support through the Łódź Special Economic Zone and is expected to undergo BREEAM assessment, with an Excellent certification rating targeted.

The completion comes amid continued demand for industrial property in Central Poland. According to JLL, industrial and logistics demand in the region reached approximately 545,000 sqm, placing it third nationally. The vacancy rate stood at 4.8%, below the Polish average, indicating relatively limited availability of existing industrial accommodation.

Approximately 163,000 sqm of industrial space was under construction in the region, with only 10% being developed without a committed occupier. The figures indicate that new supply is largely responding to established business requirements rather than anticipated demand from unidentified tenants.

The ZREW development reflects the changing composition of industrial investment in Łódź, where manufacturing has expanded beyond the city’s historical textile industry into electrical equipment, household appliances and pharmaceuticals. It also demonstrates how manufacturing projects can require substantially different property specifications from conventional warehouse developments.

For Poland’s industrial property market, the investment provides an example of demand for specialised production facilities linked to electricity infrastructure. With most new industrial construction in Central Poland already associated with identified occupiers, the project illustrates the role of manufacturing requirements in shaping the region’s development pipeline.

Skanska’s Central European Property Activity Continues as Development Profits Face Pressure

Skanska reported improved financial results for the third quarter of 2026, with higher construction revenue and an increase in new contracts offsetting weaker performance in parts of its property development business. Central Europe continued to provide opportunities for commercial property transactions and residential construction, while market conditions elsewhere remained less favourable.

The Swedish construction and property development group generated revenue of SEK 49.4 billion (approximately €4.50 billion) between July and September 2026, compared with SEK 43.7 billion (approximately €3.99 billion) during the corresponding period last year. Operating profit increased by 52% to SEK 2.07 billion (approximately €189 million), up from SEK 1.36 billion (approximately €124 million) in the third quarter of 2025.

Construction operations accounted for most of the improvement. Revenue from this division reached SEK 46 billion (approximately €4.19 billion), compared with SEK 42.2 billion (approximately €3.85 billion) a year earlier. Operating profit increased to SEK 2.28 billion (approximately €208 million), while the operating margin improved from 4.2% to 5.0%.

The value of new construction contracts reached SEK 68 billion (approximately €6.20 billion) during the quarter, compared with SEK 39.9 billion (approximately €3.64 billion) in the corresponding period of 2025. By the end of September, Skanska had outstanding construction contracts valued at SEK 328.3 billion (approximately €29.94 billion), representing around 22 months of work at current production levels.

Investment in data centres, semiconductor manufacturing facilities and infrastructure projects contributed to the increase in construction activity. These sectors have become increasingly important sources of revenue for international construction companies as demand for conventional commercial developments continues to vary between markets.

The company’s residential development business reported weaker results, with revenue declining to SEK 1.54 billion (approximately €140 million) from SEK 1.76 billion (approximately €160 million). The division recorded an operating loss of SEK 369 million (approximately €33.6 million), compared with a profit of SEK 131 million (approximately €11.9 million) a year earlier.

The residential result included SEK 340 million (approximately €31 million) in reductions to the recorded value of certain land holdings and SEK 143 million (approximately €13 million) in goodwill impairments. These adjustments were associated with changes to the company’s development priorities and weaker performance in parts of its Nordic residential operations.

Housing activity also slowed during the quarter. Skanska sold 323 homes, compared with 383 in the third quarter of 2025, while construction began on 270 homes, down from 572 a year earlier. At the end of September, the company had 2,882 homes under construction, with 56% already sold. The number of completed but unsold homes declined to 298 from 486 a year earlier.

Conditions in Central Europe remained more favourable than in several Nordic residential markets. Skanska reported continued demand for housing in the region and stronger profitability from its Central European residential projects. One new residential development was launched during the quarter, while the company maintained a positive assessment of opportunities in the region over the coming year.

Commercial property development recorded an improvement in financial performance, with revenue increasing to SEK 3.25 billion (approximately €296 million) from SEK 1.75 billion (approximately €160 million) a year earlier. Operating profit reached SEK 171 million (approximately €15.6 million), reversing a loss of SEK 397 million (approximately €36.2 million) in the third quarter of 2025.

Central Europe contributed to this performance through the sale of two office developments, one in Warsaw and another in Budapest. These transactions indicate that investment demand remains present for selected office properties in the region, although activity continues to depend on building quality, rental income and individual market conditions.

Skanska also commenced development of the first phase of Nowy Format in Kraków during the quarter. The decision to proceed with a new office project comes as the company reports improving leasing conditions in Central Europe, supported by demand from occupiers and a relatively limited volume of new office accommodation entering the market. This combination has contributed to higher rents in certain locations, although conditions differ between cities and individual properties.

Despite the improvement in commercial development earnings, the division recorded SEK 378 million (approximately €34.5 million) in property impairments, primarily associated with completed buildings in the United States that remain unsold. These adjustments reduced the financial benefit from property disposals and demonstrate the continuing effect of weaker investment conditions on development valuations.

At the end of September, Skanska had 17 commercial development projects under construction, providing a combined 271,000 sqm of lettable space. These projects were approximately 57% complete, with 54% of their accommodation leased. The company’s portfolio also included 17 completed properties covering 446,000 sqm, of which 82% was leased.

New leasing activity declined to 22,000 sqm during the quarter from 77,000 sqm in the corresponding period of 2025. The reduction highlights the importance of securing tenants before completion or disposal, particularly for developers seeking to limit the financial exposure associated with vacant commercial accommodation.

Skanska estimated the potential market value of its commercial development portfolio at SEK 48.4 billion (approximately €4.41 billion) upon completion, including approximately SEK 4.6 billion (approximately €419 million) in unrealised development gains. These figures reflect current valuation assumptions and anticipated project outcomes rather than profits already received through completed transactions.

The company’s financial position strengthened during the reporting period. Operating cash flow reached SEK 2.84 billion (approximately €259 million), compared with SEK 40 million (approximately €3.6 million) a year earlier. Adjusted interest-bearing net receivables increased to SEK 11.6 billion (approximately €1.06 billion) at the end of September, compared with SEK 8.7 billion (approximately €793 million) at the end of June.

Skanska’s outlook for Central Europe remains relatively positive, particularly in residential development and the office leasing market. The company expects housing demand to continue supporting development opportunities, while limited new office supply and tenant requirements for modern accommodation are contributing to rental growth in selected commercial locations.

The third-quarter results illustrate the different conditions affecting construction and property development across international markets. Infrastructure and technology investment are supporting construction revenue and new contracts, while residential and commercial development remain more dependent on local demand, financing conditions and the ability to sell completed properties at acceptable prices.

For Poland and the wider Central European region, Skanska’s office transactions and new development activity suggest that investment and construction opportunities remain available despite the difficulties affecting other parts of the group’s property portfolio. However, lower residential construction starts, reduced commercial leasing volumes and continuing asset impairments indicate that the wider recovery in European property development remains uneven.

Currency reference: All euro equivalents have been calculated using the SEK/EUR exchange rate recorded on 5 November 2026 at 08:54 CET, when SEK 1 equalled €0.0911899, or approximately SEK 10.9661 to €1. The conversions are provided for comparison and are not the historical exchange rates applicable to the financial reporting periods.

New Retail Agreement Reduces Vacant Space at Regensburg Shopping Complex

Silverton Group has secured German drinks retailer trinkgut for a commercial property in Regensburg, Bavaria, adding another occupier to a shopping complex that continues to have space available for lease. The agreement covers approximately 1,300 sqm at Langobardenstrasse 2, where Silverton oversees the property on behalf of an investment fund.

The incoming retailer will establish a drinks store occupying around 800 sqm of sales space, with the remainder of the leased premises used for associated activities. Preparations for the new premises are expected to begin in spring 2027, ahead of a planned opening in November 2027.

The agreement brings previously unused accommodation into the property’s leasing programme for the first time. Although the space has been included within the development since its construction, it has not previously generated income from an operating tenant. The new agreement is expected to increase the proportion of occupied accommodation once trinkgut begins trading.

Completed in 2002, the property occupies approximately 23,200 sqm of land and contains around 16,100 sqm of space available to commercial tenants. Existing businesses include sporting goods retailer Decathlon, furniture company Seats and Sofas, and pet supplies chain Fressnapf.

Following the latest agreement, approximately 2,700 sqm remains available for occupation, equivalent to around 17% of the property’s total lettable area. This indicates that further leasing activity will be necessary to improve occupancy across the development.

The arrival of trinkgut will introduce a drinks-focused business alongside the existing retailers, potentially increasing the variety of customer visits to the location. The agreement also provides the property manager with an opportunity to bring part of the previously unused accommodation into commercial operation without undertaking a wider redevelopment.

For investors in established retail properties, reducing unused space remains an important element of maintaining income and managing operating expenses. Bringing additional tenants into existing buildings can improve cash flow, although the financial outcome depends on agreed rents, tenant incentives and the cost of preparing premises for occupation.

Silverton has not disclosed the length of the agreement, rental payments or the financial arrangements associated with the new store. No information was provided regarding potential tenants for the remaining available accommodation.

The latest transaction forms part of the ongoing management of the Regensburg property, where leasing existing space remains the principal opportunity to increase occupancy and support future rental income.

Poland’s Online Retail Expansion Reshapes the Outlook for Logistics Property

Poland’s online retail sector is expected to maintain steady expansion over the next five years, creating new opportunities for logistics operators and property developers while changing how retailers organise their distribution networks. Research by PMR Market Experts by Hume’s indicates that internet sales could increase by approximately 8% annually through 2031, although the consequences for warehouse demand are likely to be more complex than the headline growth figure suggests.

The forecast comes as Poland’s logistics property market continues to expand, supported by domestic consumption, international trade and investment in distribution infrastructure. However, the relationship between rising online sales and demand for industrial space is changing as retailers seek greater efficiency, faster deliveries and improved control over operating costs.

According to PMR, Poland’s online retail market is entering a more mature phase following several years of rapid expansion by international shopping platforms. Foreign online retailers attracted significant numbers of Polish consumers through competitive pricing and extensive product ranges, but changes in purchasing habits and trading conditions could increasingly favour established domestic businesses.

International online sales recorded particularly strong growth between 2022 and 2025, with average annual increases approaching 20%. However, this pace is expected to moderate as consumers become more selective and retailers adapt to changing costs and competitive pressures.

For the property sector, the geographical location of goods and the organisation of delivery networks may become increasingly important. Retailers seeking to reduce delivery times and improve service reliability could place greater emphasis on distribution facilities located within Poland, particularly those offering access to major population centres and established transport corridors.

The country already has one of Central Europe’s largest modern warehouse markets. According to CBRE, Poland’s industrial and logistics property stock reached approximately 38 million square metres at the end of June 2026, representing annual growth of 5.5%. New development activity continued during the first half of the year, with more than 1.2 million square metres completed and approximately 1.3 million square metres under construction at the end of the period.

Leasing activity has remained substantial. Savills reported approximately 3.51 million square metres of gross warehouse demand during the first six months of 2026, while new leases and expansions accounted for around 2.1 million square metres. E-commerce businesses represented an estimated 30% of this net demand, demonstrating the sector’s continuing importance to the logistics property market.

At the same time, the national warehouse vacancy rate stood at approximately 6.6% at the end of June, according to BNP Paribas Real Estate. This indicates that Poland retains a substantial amount of available modern space, even as occupiers continue to seek facilities that meet increasingly demanding operational requirements.

The next stage of online retail development may therefore generate different patterns of property demand from those experienced during the sector’s earlier expansion. Rather than continually increasing the number of distribution centres, some retailers are concentrating operations in larger facilities capable of handling greater volumes through automation and improved stock management.

Modern warehouses are increasingly expected to accommodate sophisticated sorting equipment, automated storage systems and more intensive use of available floorspace. Reliable electricity supplies, building efficiency and access to skilled labour are also becoming important considerations when companies assess new locations.

These developments could influence investment decisions across Poland’s established logistics regions, including Warsaw, Łódź, Poznań, Wrocław and Upper Silesia. Each offers different advantages in terms of consumer access, transport connections, labour availability and the ability to serve wider European markets.

Facilities located close to major cities may benefit from demand for shorter delivery times, particularly among retailers handling frequent orders and consumer returns. Larger distribution centres serving national and international networks are likely to remain concentrated around major motorway connections and established industrial locations.

Nevertheless, stronger online retail sales should not automatically be interpreted as an equivalent increase in warehouse requirements. Growth in transaction values can result from higher prices or changes in consumer spending rather than additional goods moving through distribution systems. Similarly, improvements in warehouse technology can allow operators to process more orders without occupying significantly more space.

This distinction is particularly relevant for developers considering speculative construction. Future demand will depend not only on the expansion of online shopping but also on how retailers balance the cost of holding inventory, transportation expenses, delivery expectations and investment in technology.

The composition of online spending is also changing. PMR expects categories including household products, pet supplies and jewellery to record particularly strong growth during the forecast period. These activities have different storage and distribution requirements, potentially creating opportunities for specialised logistics facilities rather than simply increasing demand for conventional warehouse buildings.

Consumer participation is expected to broaden as well. PMR forecasts that nearly 87% of Polish internet users aged between 16 and 74 will make online purchases by 2031, with older consumers contributing to further market expansion. This suggests that online retail is becoming increasingly embedded in everyday household spending rather than remaining concentrated among younger customers.

For traditional retail property owners, these developments present both challenges and opportunities. Shopping centres and retail parks are adapting to consumers who increasingly combine physical shopping with digital purchasing. Stores can serve as collection and return points, while established retail networks may offer online operators an additional means of reaching customers without relying exclusively on home deliveries.

The growing integration of physical and online retail could also encourage investment in smaller distribution facilities, collection infrastructure and operational space associated with existing retail properties.

Poland’s role in European distribution networks adds another dimension to the outlook. Its central location, extensive road infrastructure and established logistics industry provide opportunities for companies serving customers across several markets. However, competition for occupiers remains significant, and future investment decisions will be influenced by development costs, labour conditions and the availability of suitable facilities.

The anticipated expansion of online retail provides a positive underlying indicator for Poland’s logistics industry, but it does not guarantee a corresponding increase in newly occupied warehouse space. Much will depend on whether companies choose to expand their physical networks, consolidate existing operations or invest in technology that increases the capacity of current facilities.

For commercial property investors and developers, the emerging opportunity lies in understanding how distribution requirements are evolving. Buildings capable of supporting efficient operations, adaptable layouts and modern logistics technology may become increasingly attractive as retailers respond to a more competitive and demanding consumer market.

Poland’s online retail sector appears set for another period of growth, but its influence on commercial property will be determined as much by changes in supply-chain organisation and operational efficiency as by the overall increase in consumer spending.

CIJ Awards Romania 2026: Four Interior Finishes Companies Reflect Changing Design and Construction Standards

Romania’s interior finishes industry is evolving as property developers, architects and investors place greater emphasis on material quality, design flexibility, technical performance and the long-term value of completed buildings. Beyond the supply of decorative products, companies operating in this sector are increasingly involved in technical specification, project coordination, customised manufacturing and the integration of materials into residential and commercial developments. These developments are reflected in the four nominations for Best Interior Finishes Company of the Year at the CIJ Awards Romania 2026.

This year’s nominees are Delta Studio, Fabrica de Profile (FDP), Pinum Doors & Windows and Quadra Casa. Although the companies operate within the same broad industry, their business models differ considerably. Delta Studio combines interior products with design and implementation services, FDP specialises in architectural decorative profiles and manufacturing, Pinum focuses on doors, windows and flooring, while Quadra Casa provides premium architectural finishes and technical solutions for property developments.

Delta Studio celebrates 30 years in the Romanian market in 2026, having developed an integrated interior fit-out business serving developers, architects, designers and private clients. The company operates showrooms in Bucharest, Cluj-Napoca, Iași, Ploiești, Pitești and Brașov, supported by an online platform. Its product portfolio includes ceramics, sanitaryware, furniture and decorative finishes, alongside proprietary brands Dalet, Keramyth and Formmat.

An important part of Delta Studio’s business model is its involvement throughout the interior completion process, from initial consultation and product selection to design, procurement and implementation. This approach is intended to simplify coordination between the different stages of interior fit-out, particularly for residential developers and purchasers seeking completed properties rather than unfinished accommodation.

During the past year, the company introduced Ready to Move In, a turnkey concept designed to take a residential property from interior planning to occupation within a proposed 30-day delivery period. Delta Studio has also developed a digital platform through which clients and project teams can monitor progress and coordinate design decisions. These initiatives demonstrate a strategy focused on combining physical products with services and digital project management, although the submission does not provide figures showing how many projects have been completed through the new model.

Fabrica de Profile (FDP) represents the manufacturing and architectural detailing segment of the industry. Established in 2011 by Dan Panciu, the Romanian-owned company specialises in decorative architectural profiles used across classical, contemporary and modern interiors. Its products are applied in both new developments and existing buildings, including residential and commercial properties.

FDP’s nomination places particular emphasis on domestic production capacity and investment in manufacturing technology. The company reported turnover exceeding €4.6 million in 2025 and invested more than €2.5 million in relocating its production operations to a new facility in Balotești. According to the submission, the investment has doubled manufacturing capacity, providing additional resources for domestic growth and international expansion.

The company has also introduced oneFDP.com, a digital design platform developed internally to help users visualise architectural details and decorative solutions. By uploading an image of an interior, users can explore design options and identify profiles suited to the space. FDP reports investing more than €500,000 in its digital platform and internally developed enterprise resource planning system. These developments illustrate how manufacturers of traditional architectural components are incorporating digital tools into product selection and design workflows.

The nomination highlights the potential value of combining manufacturing expertise with digital specification services. However, while the expansion of production capacity and investment in technology are measurable achievements, the longer-term commercial impact will depend on utilisation, customer adoption and the company’s ability to convert additional capacity into sustainable growth.

Pinum Doors & Windows, part of the Nusco Group, has operated in Romania since 1992 and has established a national distribution network of more than 20 showrooms. Its product range covers doors, windows and flooring, combining domestic manufacturing with international design partnerships and customised architectural solutions.

The company’s nomination focuses on the relationship between interior design and the functional performance of building components. Its Sara and Sara Plus door collections incorporate contemporary detailing, concealed hinges and magnetic locking systems, while the Filomuro range uses concealed frames to create visually integrated wall and door surfaces. Pinum also supplies pivot doors and customised aluminium joinery, addressing both aesthetic requirements and the technical needs of modern buildings.

A significant development is the company’s planned manufacturing expansion at Moara Vlăsiei. Pinum reports an investment exceeding €14 million, supported in part by €10 million in financing from Banca Transilvania. The new factory is intended to double annual production capacity and support further growth in domestic and export markets.

The investment also includes plans to incorporate solar panels to cover part of the facility’s electricity requirements. Alongside its development of joinery solutions intended to meet nearly zero-energy building standards, this reflects an emphasis on the relationship between product performance, manufacturing efficiency and environmental considerations. The submission does not, however, provide quantified energy savings or a confirmed operational performance record for the new factory.

Pinum’s partnerships with Italian design brands, including Rimadesio, Barausse and Alias, provide another element of its commercial positioning. The company operates a Rimadesio showroom in Romania and works with architects and designers on customised interior solutions. Its nomination illustrates how manufacturers and distributors can combine industrial production, technical specification and premium design to serve different segments of the property market.

Quadra Casa approaches the interior finishes sector primarily through material expertise, technical consultancy and project-specific implementation. The company works with architects, designers, developers and investors to coordinate the selection and application of premium finishes across residential, hospitality, retail and commercial properties.

Its portfolio includes ceramics, large-format surfaces, sanitaryware, bathroom products, flooring and architectural finishes sourced from international manufacturers. Rather than concentrating exclusively on product distribution, Quadra Casa positions its services around the integration of different materials into coordinated design and construction solutions.

An important aspect of the company’s business model is its involvement in technical specification and installation. The selection of interior finishes requires consideration of durability, compatibility, maintenance requirements and the conditions in which materials will be used. Quadra Casa’s submission emphasises its role in addressing these requirements alongside architects and contractors, helping translate design concepts into completed interiors.

The company also provides solutions for exterior finishes and ventilated façades, extending its expertise beyond internal decorative materials. This wider technical capability is relevant to developments where architectural continuity and material performance must be considered across both internal and external building elements.

Quadra Casa reports recognition through consecutive Real Estate Awards for Excellence in Interior Design Solutions in 2023, 2024 and 2025. While these distinctions indicate previous industry recognition, the nomination provides limited quantitative information on recent revenue growth, investment, project delivery volumes or measurable performance improvements. Its submission is therefore more strongly focused on specialist expertise, product quality and the breadth of its project services.

Taken together, the four nominations illustrate different approaches to creating value within Romania’s interior finishes market. Delta Studio emphasises integrated design and turnkey services, FDP combines specialist manufacturing with digital innovation, Pinum focuses on product development and industrial expansion, while Quadra Casa concentrates on technical consultancy and the coordination of premium materials.

The differences between these business models are important when considering the wider construction industry. Interior finishes influence not only the appearance of completed properties but also their durability, maintenance requirements, functionality and perceived quality. For residential developers, the availability of coordinated interior solutions can support project delivery and purchaser expectations. In commercial properties, material selection and technical execution can influence operating costs, tenant experience and the long-term performance of interior spaces.

Digitalisation is becoming increasingly visible across the sector, particularly in design visualisation, project management and product specification. Delta Studio and FDP both highlight digital platforms intended to simplify decisions and improve coordination. However, the commercial effectiveness of these technologies will ultimately depend on customer adoption, practical usability and their contribution to delivery efficiency.

Manufacturing investment is another distinguishing feature of the nominations. FDP and Pinum report substantial commitments to expanding production capacity, reflecting confidence in future demand for architectural components and building products. These investments also introduce considerations relating to operational efficiency, production costs, export competitiveness and the ability to maintain product quality as output increases.

For the CIJ Awards Romania 2026 jury, the Best Interior Finishes Company of the Year category presents a comparison between businesses with different areas of specialisation and levels of involvement in the construction process. Relevant considerations include product quality, technical expertise, innovation, manufacturing capabilities, project execution, customer service and demonstrated contributions to the property industry. Financial performance, completed investments and measurable improvements in service delivery can provide additional evidence when assessing company achievements.

The nominations also underline the importance of distinguishing between completed accomplishments and future business plans. New factories, digital platforms and service concepts may strengthen a company’s competitive position, but their long-term value depends on successful implementation and measurable results. Equally, companies specialising in consultancy and technical execution should be assessed on the quality and complexity of their delivered work rather than manufacturing scale alone.

The Best Interior Finishes Company of the Year category reflects the growing contribution of specialist suppliers, manufacturers and technical partners to Romania’s real estate market. As developers seek to differentiate their projects through quality, functionality and design, the companies responsible for selecting, producing and implementing interior materials remain an important part of the development and construction process.

The winner will be determined through the CIJ Awards Romania 2026 judging process, with the professional jury accounting for 61% of the final result and online voting representing the remaining 39%. The successful nominee will also qualify for the HOF Awards 2027, where leading real estate companies and projects from participating markets will compete for further regional recognition.

front page info
LATEST NEWS