Frankfurt’s Aqua Tower Nears Full Occupancy Following SPARK Lease

Union Investment has secured a new twelve-year lease at Frankfurt’s Aqua Tower, bringing occupancy at the property to 99% and reinforcing the appeal of modern office accommodation in the city’s financial district. SPARK, a provider of corporate meeting, event and hospitality facilities, has taken approximately 2,000 sqm across the building’s first and second floors, with operations beginning in early October 2026.

The agreement introduces a business focused on combining technology, meeting facilities and corporate hospitality within the office environment. SPARK’s concept is designed to accommodate professional gatherings, collaborative activities and business events, reflecting changing expectations surrounding how commercial premises are used. The transaction also demonstrates how office buildings can attract occupiers whose activities extend beyond conventional workplace accommodation.

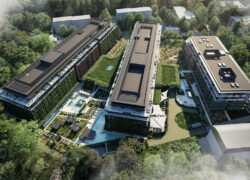
Aqua Tower forms part of FOUR Frankfurt, a major mixed-use development comprising four high-rise buildings in the heart of the city’s banking district. The tower provides approximately 24,000 sqm of lettable accommodation across 25 upper floors. Its central location places occupiers close to financial institutions, professional services companies and established transport infrastructure, supporting its position within Frankfurt’s commercial property market.

Union Investment acquired the property in 2018 while it was still under development, incorporating the investment into its UniImmo: Deutschland open-ended real estate fund. Developer Groß & Partner completed the building and transferred ownership of the finished property in November 2023. The latest leasing agreement leaves only a small proportion of the accommodation unoccupied, providing the fund with a largely income-producing asset.

The transaction comes at a time when Frankfurt’s office market continues adapting to changes in corporate space requirements and workplace strategies. Hybrid working, operational efficiency and the quality of the working environment are influencing occupier decisions, while landlords face increasing pressure to differentiate their buildings. Modern properties in established business locations may be better positioned to attract tenants, particularly where they offer flexible layouts and services that support changing business activities.

For institutional investors, securing a twelve-year commitment provides greater visibility over future rental income and reduces the immediate risk associated with vacant accommodation. The agreement also illustrates the role of active asset management in maintaining occupancy and attracting businesses with different operational requirements. However, the performance of an individual building does not necessarily reflect conditions across Frankfurt’s wider office market, where demand and vacancy can vary considerably between locations and property types.

The near-complete occupancy of Aqua Tower demonstrates how location, building quality and adaptable commercial space can contribute to leasing performance. As companies continue reassessing their workplace requirements, developments that accommodate both traditional office users and businesses providing complementary corporate services may strengthen their competitive position. For Union Investment, the latest agreement represents another step in consolidating the building’s long-term income profile within its German property portfolio.

Digital Realty Raises €1 Billion to Strengthen Global Expansion

Global data-centre operator Digital Realty has strengthened its financial position through two major European bond transactions, securing access to long-term institutional capital as demand for digital infrastructure continues to grow. On 6 October 2026, the company announced the pricing of €1 billion in euro-denominated bonds alongside the completion of a CHF510 million Swiss bond offering. The transactions highlight the importance of diversified financing as operators expand their facilities to accommodate increasing requirements for cloud computing, artificial intelligence and corporate digital services.

The €1 billion bond offering, arranged through Digital Realty’s financing subsidiary Digital Euro Finco, carries an annual interest rate of 5.125% and matures in October 2036. Issued at 99.289% of nominal value, the securities create annual coupon obligations of approximately €51.25 million. The ten-year maturity provides greater certainty over repayment schedules, an important consideration for infrastructure businesses investing substantial amounts in facilities that may take several years to reach their intended operating capacity.

Digital Realty also completed a CHF510 million financing transaction in Switzerland, structured across three separate maturities. The offering includes CHF225 million at an annual interest rate of 1.6803%, repayable in 2029, CHF185 million at 2.06%, maturing in 2032, and CHF100 million at 2.415%, due in 2036. Net proceeds amounted to approximately CHF508.4 million. Although the Swiss bonds carry lower nominal interest rates than the euro securities, currency differences and potential hedging requirements influence the overall financing costs.

The financing arrangements form part of Digital Realty’s wider capital management strategy, with amounts equivalent to the proceeds intended for investments qualifying under its environmental financing framework. Eligible activities include the development and improvement of energy-efficient facilities, renewable energy projects and refinancing of existing investments. The company retains flexibility to use funds for other permitted corporate requirements before allocating equivalent amounts to qualifying projects, meaning the transactions should not be interpreted as financing specific developments.

The announcements follow Digital Realty’s continued international expansion, including its entry into Türkiye through a joint venture announced in September. The company is extending its presence in markets where businesses require greater computing capacity and reliable digital connectivity. While the latest financing provides additional financial flexibility, Digital Realty has not identified the Turkish venture as a direct beneficiary of the bond proceeds.

The transactions also demonstrate contrasting conditions within the international data-centre investment market. While Digital Realty has accessed European debt markets, Blackstone-backed AirTrunk has reportedly postponed a proposed Singapore property investment trust listing expected to raise approximately US$1.5 billion. The developments involve different financial structures, but illustrate how established operators with recurring income may continue attracting debt investors even when market uncertainty complicates public equity offerings.

For European real estate markets, access to long-term financing is becoming increasingly important as data-centre development grows more expensive and technically demanding. Germany remains an established investment destination, while Poland, the Czech Republic and Romania offer opportunities for additional facilities. However, electricity availability, grid connections, construction costs and customer commitments remain essential considerations. Operators with diversified portfolios and established financing relationships may be better positioned to manage these challenges than developers relying on individual projects or short-term funding.

Digital Realty’s financing activity demonstrates that substantial institutional capital remains available for established data-centre businesses, although investors continue assessing borrowing costs, financial performance and development risks. As demand for computing infrastructure expands, the ability to secure sustainable financing, reliable electricity and predictable construction schedules will play an increasingly important role in determining where new facilities are developed.

Data Centre Expansion Faces Financing Test as AirTrunk Delays Singapore Listing

The global data-centre industry is facing growing financial scrutiny despite strong demand for digital infrastructure. AirTrunk, the Asia-Pacific operator backed by Blackstone and CPP Investments, has reportedly postponed a planned Singapore stock market listing expected to raise approximately US$1.5 billion. According to financial reporting published on 13 October 2026, the company has delayed plans to establish a publicly traded real estate investment trust (REIT), citing uncertainty surrounding financial markets and borrowing costs. A listing during the first half of 2027 remains possible, although no revised timetable has been officially confirmed.

The proposed investment vehicle was expected to contain data-centre assets valued at approximately S$5 billion, potentially including facilities in Singapore, Australia, Japan and Hong Kong. Transferring operational properties into a listed structure could have allowed AirTrunk to release capital for further development. Earlier reports also indicated that the company was negotiating approximately S$2 billion in associated bank financing to support property acquisitions and reorganise existing financial commitments. The scale of these arrangements demonstrates the substantial capital requirements involved in expanding and managing international data-centre portfolios.

AirTrunk has become a major participant in Asia-Pacific’s digital infrastructure market. In 2024, Blackstone and CPP Investments acquired the business at an enterprise valuation exceeding A$24 billion, equivalent to approximately US$17 billion at the time. Despite the reported listing postponement, the company continues investing in expansion. On 7 October, AirTrunk announced plans to invest approximately US$1 billion in its data-centre campus in Inzai, Japan, supporting growing demand for computing capacity. The announcement demonstrates that delaying a public offering does not necessarily indicate reduced development activity or an inability to secure financing through alternative channels.

The wider challenge concerns the considerable capital required to construct and operate modern data centres. Developers must finance buildings, electrical infrastructure, cooling systems and network connections, often years before facilities reach their intended operating capacity. Higher borrowing costs, uncertain construction schedules and changing investor expectations can influence project returns. Financial institutions are also becoming more selective as their exposure to digital infrastructure increases, placing greater emphasis on customer commitments, electricity availability, development costs and the financial strength of borrowers.

Recent developments involving other infrastructure businesses suggest similar caution among public-market investors. Australian AI infrastructure developer Firmus has reportedly withdrawn its planned public offering, while other companies continue exploring international listings. These contrasting developments indicate that investor interest in digital infrastructure remains substantial, but valuations, operating performance and the reliability of projected income are receiving closer attention. Established operators with institutional backing may continue attracting significant funding, while smaller developers or projects without confirmed customers could encounter more demanding financing conditions.

For European real estate markets, the developments provide an indication of the financial considerations accompanying data-centre expansion. Germany remains an established investment destination, while Poland, the Czech Republic and Romania are attracting interest from operators seeking additional capacity. However, electricity availability, grid connection schedules, construction costs and regulatory requirements increasingly influence project feasibility. Central and Eastern Europe offers opportunities for new facilities, but relatively affordable land does not automatically guarantee a competitive investment. Locations without sufficient electricity capacity or predictable infrastructure delivery can create financial risks that outweigh initial development savings.

AirTrunk’s reported postponement should not be interpreted as evidence of a general decline in data-centre investment. Demand for computing infrastructure remains substantial, and major operators continue committing capital to expansion. Nevertheless, the development illustrates an important distinction between technological growth and financial sustainability. The next phase of international data-centre investment will depend not only on demand for computing capacity but also on developers’ ability to secure electricity, control construction costs and obtain competitive financing. Operators combining established customers, reliable infrastructure and strong financial backing may be better positioned as investors become increasingly selective.

The Growing Divide Between Home Prices and Household Budgets in CEE Capitals

The cost of purchasing residential property in Central and Eastern Europe’s major cities is becoming an increasingly important consideration for households, developers and investors. Although residential prices continue to increase across much of the region, the ability of local buyers to enter the property market depends on considerably more than the price of an apartment. Household earnings, mortgage interest rates, available savings and the supply of suitable housing are creating different purchasing conditions in Warsaw, Prague, Bratislava, Bucharest and Budapest.

Eurostat’s latest residential property figures, published on 1 October 2026, show that house prices across the European Union increased by 4.7% during the second quarter compared with the corresponding period of 2025. The euro area recorded growth of 4.0%. All five Central and Eastern European countries examined exceeded the European average, although the differences between their national markets were substantial. Slovakia recorded annual growth of 13.6%, Romania 12.1%, Hungary 10.2%, Czechia 8.6% and Poland 6.3%.

These figures provide an indication of residential market conditions but do not establish how affordable homes have become for individual households. National property-price movements include transactions across different cities, property types and market segments. In countries where economic activity is concentrated in major metropolitan areas, the cost of purchasing an apartment in the capital may differ considerably from the national average. Consequently, the financial challenges facing buyers in Warsaw or Prague cannot be assessed solely through national residential price statistics.

One of the most important measures of affordability is the relationship between apartment prices and household earnings. A property market can experience substantial price growth without becoming less affordable if wages increase at a similar or faster rate. Conversely, relatively modest property-price increases can create additional difficulties where household incomes stagnate. The distinction is particularly important in Central and Eastern Europe, where wage growth, inflation and borrowing conditions have followed different paths since 2021.

Research published by Austria’s central bank, the Oesterreichische Nationalbank, found that the relationship between residential prices and household incomes deteriorated in Czechia, Hungary and Slovakia between the first quarters of 2024 and 2025. Poland and Romania experienced a more favourable development during the same period, as earnings growth helped offset increases in property values. However, these findings describe an earlier period and cannot establish whether the same affordability trends continued throughout 2026.

Prague remains one of the clearest examples of the difficulties associated with purchasing property in a major Central European employment centre. Research published by the International Monetary Fund in 2026 indicated that acquiring a standardised apartment measuring approximately 70 square metres could require the equivalent of 13 to 15 years of gross annual earnings, depending on the measure applied. The calculation illustrates the considerable financial commitment involved in purchasing residential property, even before mortgage interest, transaction expenses and household living costs are considered.

The Czech capital’s affordability challenges are also connected with the delivery of new housing. Residential construction depends on the availability of suitable development land, infrastructure capacity and the ability to secure planning approvals. Where these processes take considerable time, developers may struggle to respond quickly to stronger purchasing demand. The resulting imbalance can maintain pressure on property prices, particularly in established residential districts and locations with convenient access to employment and public transport.

Warsaw presents a different combination of market conditions. Poland’s residential prices increased by 6.3% annually during the second quarter of 2026, the lowest rate among the five countries examined. Earlier research from Austria’s central bank also indicated that residential prices had become more favourable relative to household earnings during the year ending in March 2025. Nevertheless, these national findings do not necessarily describe the position of households seeking accommodation in Warsaw, where property values, salaries and housing demand differ from those in smaller cities.

Poland’s substantial residential construction sector provides an important counterbalance to demand. Statistics Poland recorded 234,718 completed dwellings in 2021, while Eurostat reported that construction permits covering approximately 287,000 dwellings were issued in 2024. Although the figures concern different stages of development and cannot be directly compared, they demonstrate the scale of residential activity within the country. The more important question for Warsaw is whether newly completed apartments are available in the locations and price ranges required by households seeking their first home.

Bratislava faces particularly strong national price momentum. Slovakia recorded the highest annual residential price increase among the five countries during the second quarter of 2026, at 13.6%. The country also experienced a deterioration in residential prices relative to earnings during the earlier period examined by Austria’s central bank. These developments raise questions about the ability of households to accumulate sufficient savings for a deposit while meeting the ongoing costs of financing a property purchase.

The Slovak capital’s concentration of employment and economic activity creates a distinct residential market within the wider country. Demand for apartments is influenced by household formation, employment opportunities and access to transport infrastructure. At the same time, residential development requires substantial upfront investment and can be affected by construction expenses and planning requirements. For buyers, the resulting challenge is not simply finding an available apartment, but securing accommodation that can be financed without placing excessive pressure on household budgets.

Bucharest illustrates why rising property prices and affordability should not automatically be treated as identical developments. Romania recorded annual residential price growth of 12.1% during the second quarter of 2026, including a quarterly increase of 4.4%. However, earlier research indicated that Romanian household earnings had improved relative to residential prices during the year ending in March 2025. The sharp acceleration in property prices during 2026 makes it important to establish whether wage growth has continued to compensate for the increased cost of housing.

The Romanian capital also has a diverse residential market, ranging from older apartment buildings to newly constructed developments in expanding districts. The availability of existing housing does not necessarily correspond with the requirements of contemporary buyers, particularly those seeking energy-efficient buildings, reliable transport connections and access to employment. As a result, households may face significant competition for suitable apartments even where the wider city contains a substantial number of residential properties.

Budapest’s residential market has been influenced by changing mortgage conditions and government measures supporting homeownership. Hungary recorded annual house-price growth of 10.2% during the second quarter of 2026, although prices declined by 1.4% compared with the preceding quarter. The contrast between annual and quarterly movements indicates that the market has not followed a consistent upward trajectory throughout the year.

Government-supported borrowing programmes can improve access to mortgage financing for eligible households, particularly when subsidised interest rates reduce monthly repayments. However, the effect on overall affordability depends partly on how residential supply responds. Where additional purchasing power increases competition for a limited number of suitable properties, some of the financial benefit may be reflected in higher selling prices. Establishing the extent of this effect in Budapest requires detailed evidence on mortgage lending, transactions and newly completed housing.

Across all five capitals, the cost of borrowing remains a critical consideration. Two households purchasing apartments at identical prices can face substantially different monthly repayments depending on mortgage interest rates, loan duration and the deposit available. A reduction in interest rates can improve access to homeownership without any decline in property prices, while an increase in borrowing costs can make purchasing more difficult even when residential values remain unchanged.

The initial deposit also represents a considerable obstacle for prospective buyers. Households must accumulate sufficient savings while continuing to pay rent and meet everyday expenses. Where residential prices increase faster than savings, the amount required to secure a mortgage can become progressively more difficult to obtain. This is particularly relevant for younger households and first-time buyers who do not already own residential property or have access to substantial family financial support.

For developers, the relationship between construction costs and household purchasing power creates another challenge. Land acquisition, building materials, labour expenses, infrastructure contributions and financing costs influence the minimum selling prices required to make residential projects commercially viable. Even where demand for more affordable apartments is substantial, developers may find it difficult to deliver housing at prices compatible with average local earnings without changes to project costs, land availability or development conditions.

The location of new housing is equally important. Residential development on the outskirts of major cities may provide opportunities to deliver apartments at lower prices than in established central districts. However, buyers must also consider commuting expenses, transport availability and access to schools, healthcare and employment. A cheaper apartment can become less financially attractive when the additional costs of living in a poorly connected location are taken into account.

Rental housing provides an alternative for households unable or unwilling to purchase property, but it introduces its own affordability considerations. Professionally managed rental developments and institutional residential investment may expand the range of accommodation available in major cities. Nevertheless, their contribution to housing accessibility depends on the relationship between rental payments and household earnings. Increasing the number of professionally operated apartments does not necessarily make accommodation affordable to households with average incomes.

The wider European development environment adds another dimension. Eurostat figures show that construction permits covering approximately two million dwellings were issued across the European Union in 2021, declining to around 1.5 million annually in 2023 and 2024. Although individual national markets followed different patterns, the reduction indicates a smaller pipeline of authorised residential construction across Europe. Where fewer projects proceed to completion, housing availability may become more constrained in subsequent years.

For residential investors, the differences between Warsaw, Prague, Bratislava, Bucharest and Budapest are becoming increasingly important. Strong property-price growth can indicate sustained demand, but it does not automatically demonstrate that local households can support further increases. Markets where earnings are improving relative to property values may offer different opportunities from those where affordability has deteriorated. Equally, locations with restricted construction activity may experience persistent competition for suitable housing, although future performance will also depend on economic and financing conditions.

A meaningful comparison of the five capitals requires a consistent methodology. Measuring the purchase price of a standardised apartment against local earnings would provide an indication of the financial commitment facing buyers. Adding mortgage interest rates, typical deposit requirements and estimated monthly repayments would offer a clearer assessment of financing affordability. Residential completions, planning approvals and development pipelines would then help establish whether construction activity is responding to local demand.

The available evidence demonstrates that Central and Eastern Europe’s residential markets face different combinations of price growth, borrowing conditions and development constraints. Prague continues to experience substantial affordability difficulties, while Slovakia’s strong price increases raise concerns about purchasing power in Bratislava. Romania’s recent acceleration requires renewed examination of household earnings, and Hungary’s changing mortgage environment adds uncertainty to Budapest’s residential outlook. Poland’s more moderate price growth provides a different perspective, although Warsaw’s local market cannot be assessed through national statistics alone.

For policymakers, developers and investors, the central issue is increasingly whether residential development can provide homes that households can realistically finance. Increasing construction volumes may help address supply pressures, but the location, cost and suitability of new accommodation are equally important. As Central and Eastern Europe’s major cities continue to attract employment and investment, the relationship between residential prices and local purchasing power will remain a defining challenge for their housing markets.

Source: CIJ.World Research & Analysis Team

CEE Warehouse Demand Remains Active as Economic Slowdown Tests Property Investment

Central and Eastern Europe’s industrial and logistics property sector is showing signs of an increasingly uneven market, with businesses continuing to lease modern facilities while property investment transactions have declined substantially. Slower economic growth, rising energy expenditure and uncertainty surrounding international trade are influencing decisions across the region, but recent market figures suggest that demand for warehouses and production facilities remains stronger than the wider economic outlook might indicate.

The World Bank’s latest assessment of Europe and Central Asia, published on 6 October 2026, forecasts economic growth of 2.2% this year, compared with 2.6% in 2025. Excluding Russia, growth is expected to moderate from 3.7% to 3.0%. The institution identifies expensive energy, weaker demand from important export markets and increasing competition in manufacturing as factors affecting economic performance. Its forecasts cover developing economies across Europe and Central Asia rather than the European Union alone, making the geographical distinction important when assessing their relevance to individual property markets.

The slowdown comes as Central European manufacturers face changing conditions in international trade. Industrial companies operating within automotive, engineering and other export-oriented industries remain exposed to economic developments in Western Europe, particularly Germany. At the same time, competition from Asian manufacturers and the growing importance of automation are encouraging businesses to reconsider production costs and the efficiency of their existing facilities. These developments could influence future demand for manufacturing premises, although their impact will differ between industries and locations.

Despite these challenges, industrial and logistics leasing across six Central and Eastern European markets remained active during the first half of 2026. Research by Cushman & Wakefield indicates that the region’s modern industrial property stock reached approximately 73.7 million square metres by the end of June, representing annual growth of 6.2%. Vacancy stood at 6.9%, while around 4 million square metres of additional accommodation remained under construction.

Leasing activity reached approximately 3.08 million square metres during the second quarter, contributing to a 16.5% annual increase in transactions during the first six months of 2026. The figures suggest that occupiers have continued securing industrial and distribution facilities despite uncertainty surrounding future economic growth. Manufacturing companies, logistics providers and businesses adapting their supply chains remain important sources of demand, although individual sectors are responding differently to changes in operating conditions.

Investment activity has followed a considerably weaker trajectory. Industrial property transactions across the six markets totalled approximately €451 million during the second quarter of 2026, compared with €825 million during the equivalent period in 2025. The decline of approximately 45% highlights a difference between the requirements of businesses occupying industrial buildings and the decisions of investors purchasing them. While companies continue to need operational accommodation, investment transactions are influenced by financing expenses, asset availability, pricing expectations and assessments of future returns.

The reduction in transaction volumes does not necessarily indicate that investors have lost confidence in the industrial property sector. Large acquisitions can significantly influence quarterly investment figures, and periods of disagreement between buyers and sellers may delay transactions. Nevertheless, the latest figures suggest that investors are exercising greater caution when committing capital, particularly where uncertainty surrounding economic growth and operating costs complicates longer-term financial projections.

Developers are also responding to changing market conditions. Approximately 37.5% of industrial space under construction across the region was being developed without secured tenants during the second quarter, down from 41.8% three months earlier. This suggests a shift towards projects supported by identified occupiers, allowing developers to reduce the financial exposure associated with constructing buildings before rental commitments have been obtained. The trend could favour customised manufacturing facilities and distribution centres designed around specific operational requirements.

Poland remains the largest industrial and logistics market within the regional comparison, representing approximately 52% of the modern stock covered by Cushman & Wakefield. The country also accounts for nearly one-third of the space under construction. Its economic outlook remains comparatively favourable, with the World Bank forecasting GDP growth of 3.6% in 2026. Poland’s large domestic market, established transport infrastructure and position within European distribution networks continue to support demand for modern industrial accommodation.

However, Poland’s industrial property market is exposed to different economic influences. Warehousing associated with domestic consumption and retail distribution may benefit from household spending, while manufacturers supplying international markets remain sensitive to changes in European industrial production. The strength of national economic growth therefore does not guarantee uniform performance across industrial locations, with occupier requirements varying according to transport connections, labour availability and proximity to customers.

Czechia continues to demonstrate substantial demand from manufacturing occupiers. Its modern industrial stock reached approximately 13.73 million square metres during the second quarter of 2026, while leasing activity totalled around 451,600 square metres. Approximately 248,400 square metres represented net leasing activity, and vacancy stood at 5.5%. The country also had approximately 1.15 million square metres of industrial accommodation under construction.

Manufacturing companies accounted for approximately 42% of Czech leasing activity during the quarter, underlining the importance of production-related demand. Nevertheless, the country’s dependence on European industrial supply chains creates exposure to changing export conditions, particularly in automotive manufacturing and engineering. Companies assessing future expansion may place greater emphasis on energy efficiency, automation and the ability of buildings to accommodate changing production requirements.

Romania’s industrial property sector has continued expanding, with modern stock reaching approximately 8.14 million square metres by the end of the second quarter. According to Cushman & Wakefield Echinox, around 86,000 square metres of new accommodation was completed during the period, while the development pipeline approached 500,000 square metres. Bucharest accounted for approximately 4 million square metres of the country’s modern industrial and logistics facilities, reflecting its importance as a national distribution centre.

Beyond Bucharest, Romania’s regional industrial markets remain relevant for companies seeking manufacturing locations and access to international transport routes. The development of transport infrastructure, the availability of labour and proximity to European supply chains are important considerations for occupiers. However, the continued expansion of industrial stock does not automatically demonstrate stronger demand in every location, making vacancy, leasing activity and the absorption of newly completed buildings important indicators for future market assessments.

Energy costs are becoming an increasingly significant element of industrial property decisions. Manufacturers with substantial electricity or gas requirements must consider how energy expenditure affects production costs, while temperature-controlled logistics operators depend on reliable power supplies to maintain their facilities. Changes in electricity pricing can therefore influence the financial attractiveness of individual locations, particularly where industrial operations require continuous energy consumption.

The issue is especially relevant for data centres, where electricity availability, grid connections and operating reliability are fundamental to project feasibility. Developers planning new digital infrastructure must assess whether suitable sites can provide sufficient power capacity alongside telecommunications connectivity and other technical requirements. Although energy costs are an important consideration, there is currently insufficient evidence to conclude that they have caused widespread cancellation or relocation of data-centre investments across Central and Eastern Europe.

Concerns about European energy supply have also increased following uncertainty surrounding gas storage levels and international supply conditions. Competition for liquefied natural gas and changes in wholesale energy markets could affect industrial operating expenses, although the impact on individual businesses will depend on their purchasing arrangements and exposure to market prices. For property developers, these considerations may strengthen demand for buildings incorporating energy-saving technologies and more efficient operating systems.

Longer-term economic changes could also influence the type of industrial accommodation required across the region. The International Monetary Fund has highlighted demographic pressures, weaker productivity growth and increasing international competition as challenges affecting Central Europe’s economic prospects. As businesses seek to improve efficiency, industrial facilities capable of supporting automation, advanced manufacturing and more sophisticated logistics operations may become increasingly important.

These changes could create opportunities for modern industrial buildings while presenting challenges for older properties that require substantial investment to meet contemporary operational standards. Higher technical specifications, stronger electricity connections and improved environmental performance may enhance the attractiveness of certain facilities, but they can also increase development costs. Investors and developers will therefore need to assess whether occupiers are willing to support the additional expenditure through rental commitments.

The difference between leasing and investment activity remains one of the most important developments in the current market. A 16.5% increase in first-half leasing activity demonstrates continued occupier requirements, while the approximately 45% decline in second-quarter investment transactions indicates a more cautious capital market. These movements should not be interpreted as directly comparable measures, since they cover different periods and reflect different types of activity, but together they illustrate the increasingly selective nature of the industrial property sector.

The outlook for Central and Eastern European industrial property will depend on how economic growth, manufacturing demand and operating costs develop over the coming quarters. Poland’s comparatively stronger economic forecast, Czechia’s manufacturing requirements and Romania’s continuing construction activity demonstrate that the region retains significant industrial property demand. However, individual markets will respond differently to international trade conditions, financing expenses and changes in occupier requirements.

For developers and investors, the coming period may place greater emphasis on projects supported by clear tenant demand, reliable infrastructure and sustainable operating costs. Industrial properties offering efficient transport connections, suitable technical specifications and dependable energy supplies are likely to remain important to businesses seeking to improve their operations. Rather than signalling a broad retreat from industrial and logistics property, the latest figures suggest a market in which investment decisions are becoming more closely tied to the practical requirements and financial resilience of occupiers.

Source: CIJ.World Research & Analysis Team

Britain Rethinks Who Pays When Artificial Intelligence and Smart Technology Fail

The growing use of artificial intelligence, connected devices and automated systems is prompting a major reconsideration of corporate responsibility in England and Wales. A consultation launched by the Law Commission on 8 October 2026 proposes significant changes to legislation governing compensation for harm caused by unsafe products. The reforms could extend legal exposure beyond traditional manufacturers to software developers, technology providers and digital marketplaces, potentially affecting industries ranging from consumer electronics to construction and property management.

The review examines legislation dating from 1987, when consumer products were predominantly physical goods and digital technology played a much smaller role in everyday life. Modern products increasingly depend on software, remote connectivity and automated decision-making, creating uncertainty over responsibility when technology malfunctions. The proposed changes would allow software and artificial intelligence systems to be considered products for liability purposes, whether installed within equipment, downloaded separately or accessed through online services. The proposals would also cover certain digital products supplied without direct payment from users.

Online platforms could face additional legal responsibilities under the proposed framework. Technologies influencing how users interact with social media, gaming environments and other digital services would potentially fall within the revised rules. These include automated recommendations, personalised notifications and features designed to influence user engagement. The proposals also consider circumstances in which online marketplaces and other intermediaries could become responsible for defective products, particularly where the original manufacturer or another directly accountable business cannot be identified.

Another significant area concerns the difficulties individuals encounter when attempting to establish why sophisticated technology has caused harm. Artificial intelligence systems and interconnected software can be difficult to examine, especially when essential technical information remains under the control of developers. The Law Commission is considering whether courts should be permitted to assume that a product was defective in exceptional cases where obtaining sufficient evidence is particularly difficult. Businesses would have an opportunity to challenge that assumption, while a proposed alternative mechanism could allow partial compensation where specified conditions are satisfied.

The consultation also examines the types of losses eligible for compensation and the period during which claims may be pursued. Proposed changes include broader recognition of certain psychological injuries, damage to personal digital information and reasonable expenditure incurred to prevent physical harm. Some claims involving injuries that become apparent only after many years could remain possible for up to 25 years. Significant alterations to products, including certain software changes, could also affect when liability periods begin. These measures may require manufacturers, technology companies and insurers to reconsider how long they retain technical records and maintain financial protection against potential claims.

For the real estate and construction industries, the proposals raise questions about responsibility for increasingly sophisticated building technologies. Commercial and residential properties now incorporate digital systems controlling heating, ventilation, security, access arrangements and energy consumption. Where defective software or connected equipment causes injury or qualifying property damage, the proposed framework could influence how responsibility is allocated among technology developers, equipment manufacturers and other businesses involved in supplying the systems. Property owners, developers and facilities managers may consequently need to examine procurement agreements, maintenance obligations and insurance arrangements more closely. The precise implications will depend on the final legislation and the circumstances of individual cases.

The proposals could also influence the commercial adoption of artificial intelligence within property operations. Automated building management, predictive maintenance and intelligent security technologies offer opportunities to improve efficiency, but their growing complexity creates additional questions about accountability. Companies introducing such systems may need clearer arrangements governing software updates, technical support, cybersecurity and responsibility for defects. The consultation does not propose a general regulatory regime for artificial intelligence, nor does it automatically make building owners responsible for failures involving third-party technology. Instead, it addresses the circumstances in which defective products could give rise to compensation claims.

The review comes as the European Union prepares to apply its revised product liability framework from December 2026. The European legislation also extends coverage to digital technologies, although the proposals being considered in England and Wales are not identical. Northern Ireland is expected to operate under arrangements linked to the updated European rules, potentially creating different compliance requirements within the United Kingdom. Businesses operating across European markets may therefore need to accommodate separate legal frameworks when developing, importing or distributing technology-based products.

The consultation remains open until 14 January 2027, with the Law Commission expecting to publish its recommendations towards the end of 2027. Any subsequent legislative changes would require government consideration and parliamentary approval. Although the proposals remain at an early stage, they highlight a growing challenge for businesses adopting digital technologies: determining who should bear the financial consequences when increasingly autonomous and interconnected products cause harm. For the property sector, where buildings are becoming more dependent on software and automated infrastructure, the outcome could have implications for future investment, procurement and operational risk management.

Source: CMS

MitziLinka: The Curious Case of the Invisible Taxi and the Passenger Who Failed to Disappear

There was a time when arriving at an airport meant finding a taxi, negotiating with a driver who had apparently studied economics under a Sicilian pirate, and hoping the meter wasn’t connected to the national debt. Fortunately, technology has rescued us from such primitive inconveniences. Today, we simply open an application, select our destination and watch a little car move across a screen. The future has arrived, complete with satellite navigation, artificial intelligence and the remarkable ability to make a vehicle disappear while insisting it is standing directly in front of you.

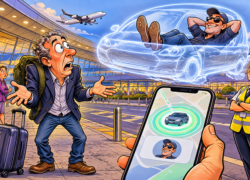
This particular adventure began at Bucharest’s Henri Coandă International Airport, where a traveller ordered a car through the wonderfully mysterious world of Abracadabra Mobility. The application cheerfully announced that the driver had arrived. Splendid news, except for one minor administrative detail: there was no car. The passenger searched the collection area, examined the surrounding roads and wandered around with the determination of an archaeologist looking for a lost Roman settlement. Nothing. Not a bumper, not a windscreen, not even a suspicious-looking exhaust pipe. Somewhere in the digital universe, however, the driver was apparently waiting with the patience of a Buddhist monk.

Eventually, the driver decided that enough was enough. Having successfully avoided the inconvenience of collecting his customer, he cancelled the booking and declared the passenger a no-show. This was a remarkable achievement. The passenger was physically present, the driver was nowhere to be found, yet technology concluded that the missing individual was the person standing at the airport. It was rather like a restaurant charging you for failing to eat a dinner that the chef had forgotten to cook. Whether the driver had genuinely reached the correct location remains unknown, but the application had already delivered its interpretation of reality.

A little investigation suggests that Bucharest is not alone in hosting this particular magic show. Passengers in Lisbon, London and other European cities have reported comparable adventures involving vehicles that exist confidently on mobile screens but prove considerably more elusive in the physical world. At Lisbon Airport, travellers have described searching designated collection points while drivers apparently waited somewhere in another dimension. In London, complaints have included disputed charges for cars that customers say never appeared. One begins to suspect that Europe’s ride-hailing industry has quietly developed a new transport category: the imaginary chauffeur service.

The economics are equally fascinating. Drivers can receive compensation when passengers fail to appear after a specified waiting period, which is perfectly reasonable when the driver actually turns up. But imagine the entrepreneurial possibilities if the system mistakenly rewards someone who never reaches the correct location. No passengers to collect, no luggage to load, no traffic to negotiate and no uncomfortable conversations about the weather. Just wait, cancel and potentially receive compensation. Of course, there is no evidence that every missing driver is operating such a scheme, but the theoretical business model would surely attract the attention of anyone who has ever dreamed of earning money by doing absolutely nothing.

Airports provide an especially convenient stage for these misunderstandings. A driver might be on the wrong level, behind a barrier, across a multi-storey car park or somewhere near a roundabout that only the airport architect understands. According to the application, the vehicle is practically close enough to shake hands with. In reality, reaching it might require a passport, climbing equipment and permission from air traffic control. Satellite navigation can identify geographical proximity, but it has yet to master the more complicated human concept of being somewhere that another person can actually find you.

Naturally, the transport platforms have rules. Drivers are supposed to reach the correct location, wait appropriately and make reasonable efforts to contact their customers. Passengers can challenge questionable charges, and the companies have access to location records that may establish what happened. The difficulty is that the passenger has a mobile telephone and a rapidly declining sense of humour, while the platform possesses the electronic evidence. One party remembers standing outside an airport looking for a car. The other has a computer suggesting that the car was there. In the modern world, the computer frequently gets the first opportunity to explain itself.

Perhaps the solution is to introduce a new technological breakthrough called looking out of the window. Before declaring a passenger missing, the driver could confirm that the vehicle is actually at the agreed collection point. The passenger might then be allowed to identify something revolutionary, such as a registration plate attached to a real automobile. For particularly advanced operators, an optional feature could require the driver and passenger to occupy approximately the same physical location before either is blamed for disappearing. It sounds ambitious, but humanity has already managed to put people on the Moon.

There is, of course, a serious issue beneath the comedy. Disputed airport collections waste time, create frustration and can leave travellers facing charges for journeys they never received. There is no verified evidence that an organised European network of invisible drivers exists, and many failed pickups are undoubtedly genuine misunderstandings. Nevertheless, repeated complaints suggest that the systems determining responsibility deserve closer attention. When a driver claims to have arrived and a passenger insists that no vehicle was present, the answer should come from examining the evidence rather than automatically assuming one party has vanished.

As for our traveller in Bucharest, he eventually discovered that the most impressive feature of modern transportation is not the electric motor, the smartphone or the satellite orbiting above Romania. It is the extraordinary ability to be standing exactly where you are supposed to be and still be officially declared missing. Somewhere out there, perhaps, an invisible car is waiting for its invisible passenger, while a very real cancellation fee considers making an appearance. Welcome to the future of airport travel, where the only thing guaranteed to arrive on time is the notification telling you that you weren’t there.

Author: Mitzilinka (Turning grim reality into comic relief-without losing the truth)

ZEITGEIST Secures Environmental Certification for 203-Apartment Rental Development in Gdańsk

ZEITGEIST Asset Management has received a BREEAM In-Use certification with a Very Good rating for its HOME by ZEITGEIST Górskiego residential development in Gdańsk, marking the first property in the company’s Polish private rented sector (PRS) portfolio to undergo this form of environmental assessment. The certification evaluates the sustainability characteristics of existing properties, providing an independent assessment of building performance and management practices after completion.

The development, located in Gdańsk’s Oliwa district, comprises 203 apartments distributed across four residential buildings at Górskiego Street 6, 8, 10 and 12. Completed in 2022, the scheme offers two- and three-room apartments ranging from 35 to 68 sqm, available with or without furniture. The property was designed to incorporate energy-efficient solutions and facilities supporting residents’ everyday needs, including electric vehicle charging stations within its outdoor parking area.

Unlike environmental assessments conducted during construction, BREEAM In-Use examines buildings already operating and considers factors such as energy and water management, maintenance standards and environmental policies. ZEITGEIST selected this certification process to evaluate the development several years after completion and establish whether its operational characteristics continued to meet recognised sustainability criteria. Property management company MVGM coordinated the assessment in cooperation with ZEITGEIST’s asset management team.

According to Tomasz Dąbrowski, Managing Director of ZEITGEIST Asset Management in Poland, assessing an occupied residential development provides an opportunity to examine how sustainability measures function under everyday operating conditions. The company considers independent certification an important instrument for monitoring property quality and supporting long-term asset management decisions, particularly as environmental performance becomes increasingly relevant to institutional residential investment.

The Gdańsk certification follows a separate environmental assessment completed for ZEITRAUM Racławicka in Kraków. That mixed-use development, combining accommodation for 289 students with 182 serviced apartments, received BREEAM International New Construction V6 certification following completion. The two projects demonstrate the company’s use of different assessment systems depending on whether a property is newly developed or already occupied.

ZEITGEIST has also pursued environmental certifications within its Czech portfolio. In Prague, the renovated Palác Dunaj office and retail property achieved LEED Gold and WELL Gold ratings, covering environmental characteristics and aspects of occupant wellbeing. Another residential investment, Rezidence Delta Hagibor, developed in cooperation with Invesco, has also received BREEAM certification. These projects form part of the company’s wider approach to evaluating property performance across its European operations.

Jakub Kaźmierczak, Managing Director of MVGM Poland, highlighted the growing role of property managers in coordinating sustainability assessments and maintaining building standards throughout the operational life of residential assets. For investors in Poland’s developing institutional rental market, certification of occupied properties provides an additional means of assessing environmental management and long-term building quality. The Gdańsk project illustrates how sustainability considerations are extending beyond new construction into the ongoing management of residential investment portfolios.

DP World Plans €100 Million Energy Transformation at Romania’s Largest Seaport

DP World is advancing a €100 million investment programme to modernise its container terminal at the Port of Constanța, introducing electric cargo-handling equipment and infrastructure that will allow vessels to receive electricity while docked. The initiative includes an initial €53.8 million project supported by European Union funding and financing from the European Bank for Reconstruction and Development (EBRD). The investment is intended to reduce dependence on conventional fuels and improve the environmental performance of one of the Black Sea region’s most important maritime logistics facilities.

The first investment package, scheduled for completion by 31 August 2028, will be implemented by Constanța South Container Terminal SRL, the company operating DP World’s facilities in the port. Financial support includes an EU contribution of up to €19.7 million through the Connecting Europe Facility, alongside an EBRD loan of up to €25 million. The remaining expenditure will be covered by the terminal operator. The European funding is administered through the European Climate, Infrastructure and Environment Executive Agency (CINEA), supporting improvements to transport infrastructure within the Trans-European Transport Network.

A substantial part of the programme will involve upgrading the terminal’s electricity distribution infrastructure to accommodate a new generation of cargo-handling machinery. The project covers 29 container storage sections, where approximately six kilometres of electrical distribution systems will be installed to support future electrically powered rubber-tyred gantry cranes. Three electrical substations, each equipped with three transformers rated at 2,000 kVA, will provide the additional capacity required for these operations.

The investment will also introduce electric vehicles for moving containers within the terminal. A dedicated charging facility with ten charging points will be developed, accompanied by the acquisition of ten electric terminal tractors. These vehicles will replace part of the equipment currently dependent on conventional fuels, while a separate electrical substation will support their operation. The transition is expected to reduce emissions associated with internal cargo movements and provide the infrastructure necessary for further fleet electrification.

Another component will enable ships to obtain electricity directly from the port’s infrastructure rather than relying on onboard generators during their stay. Two electrical supply installations, supported by transformers with a capacity of 5 MVA each, will be developed for this purpose. According to the project announcement, the electricity supplied through these systems will come entirely from renewable sources. The technology is intended to reduce emissions and local air pollution generated by vessels while they are berthed, although its practical benefits will depend on the compatibility and use of the facilities by visiting ships.

Beyond the initial €53.8 million investment, DP World is planning a further €46.2 million expenditure on electrically operated cargo-handling equipment. This additional programme includes remotely controlled electric gantry cranes, two electric mobile harbour cranes and further electric terminal tractors. Together, the two investment components will bring the planned expenditure on electrifying the Constanța terminal to €100 million, representing a substantial modernisation of the port’s operational infrastructure.

The programme reflects the growing importance of energy efficiency and environmental performance in European maritime logistics. Constanța occupies a strategic position in regional trade, connecting Black Sea shipping routes with European road, rail and inland waterway networks. By upgrading its electrical infrastructure and introducing cleaner cargo-handling technologies, DP World aims to strengthen the terminal’s long-term operational capabilities while supporting wider European transport decarbonisation objectives. The investment also demonstrates how port infrastructure is evolving as shipping operators, logistics companies and industrial customers face increasing expectations to reduce emissions throughout their supply chains.

Green House Development Begins Final Stage of Świnoujście Coastal Resort Project

Green House Development has launched pre-sales for the final stage of Wave Świnoujście Thermal & SPA, a coastal residential and hospitality development in northwestern Poland. The concluding phase, designated Building C, will introduce 192 fully finished apartments alongside additional wellness and conference facilities. Construction is scheduled for completion in the first quarter of 2030.

Located in Świnoujście’s spa district, near the Baltic Sea beach, promenade and Spa Park, the development comprises three buildings designed by Medusa Group and IDS Architekci. The final phase will offer apartments with views of either the resort’s outdoor swimming pools or surrounding landscaped areas, targeting purchasers interested in seaside accommodation for personal use or potential rental income.

The ownership structure allows buyers to determine how their apartments are used without mandatory participation in a rental management programme. Purchasers may retain their properties exclusively for private occupation or choose to make them available for short-term accommodation. An optional rental arrangement will operate under an 80/20 revenue-sharing model, although the developer’s announcement does not provide further details regarding operating expenses or additional management costs.

Building C will also introduce approximately 2,000 sqm of thermal and wellness facilities, including massage treatment rooms and a conference area. These additions will contribute to more than 4,000 sqm of planned wellness infrastructure across the completed resort. The combination of recreational amenities and business meeting facilities is intended to broaden the property’s appeal beyond conventional seasonal holiday accommodation.

According to Kamil Gaszyński, Sales Director at Green House Development, the final phase has been designed to provide apartment owners with greater flexibility while maintaining access to the resort’s shared amenities. The developer expects the combination of private residential accommodation, swimming pools and extensive wellness facilities to appeal to purchasers seeking both recreational opportunities and the possibility of generating rental income.

The project reflects a segment of Poland’s coastal property market in which residential ownership is combined with hospitality services and leisure infrastructure. Such developments aim to attract buyers seeking second homes or investment properties, while year-round wellness and conference facilities may help support visitor demand outside the peak summer months. Rental performance, however, remains dependent on occupancy levels, operating expenditure and local tourism conditions.

With Building C entering pre-sales, Green House Development is progressing towards completion of the three-building complex by early 2030. The final stage will expand the supply of privately owned holiday apartments in Świnoujście while adding leisure and business facilities to the resort’s overall offering.

front page info
LATEST NEWS