Energy Prices Push European Inflation Higher as Economic Pressures Persist

Consumer prices across the European Union accelerated in October 2026, with annual inflation reaching 4.0% as higher energy costs added to financial pressures on households and businesses. The increase, from 3.8% in September, brought inflation to its highest level in approximately three years and highlighted the continuing difficulties facing European economies in restoring price stability.

Figures published by Eurostat on 18 November show that inflation across the euro area also reached 4.0%, compared with 2.1% in October 2025. The renewed increase comes at a time when economic growth remains relatively modest and businesses continue to adjust to changing operating expenses, financing conditions and consumer spending patterns.

Energy accounted for much of the acceleration. Prices in this category increased by 21% over the preceding twelve months, compared with 19% in September. The increase contributed approximately 1.89 percentage points to annual euro area inflation, making energy the largest individual source of price pressure.

Services accounted for a further 1.55 percentage points, while manufactured consumer products and food-related categories made smaller contributions. Excluding energy, food, alcohol and tobacco, euro area inflation stood at 2.6%, considerably below the overall rate. The difference illustrates the extent to which energy costs influenced October’s figures.

The latest data reveal substantial differences between European economies. Romania recorded the highest annual inflation in the EU at 7.0%, followed by Lithuania at 6.1% and Bulgaria at 5.9%. These countries continued to experience significantly stronger price increases than the European average, creating additional challenges for household expenditure and business planning.

Elsewhere in Central and Eastern Europe, inflation was more moderate. Poland recorded an annual rate of 3.7%, declining from 4.0% in September, while Slovakia reported 2.9% and Hungary 2.4%. The Czech Republic registered 2.1%, among the lowest rates in the EU, following a slight decline from the previous month.

The differences are particularly relevant for companies operating across several European markets. Businesses with activities in Romania or Bulgaria face a different cost environment from those in Czechia or Hungary, potentially affecting expenditure, wage negotiations, procurement and investment planning.

Western European economies also experienced varying conditions. Italy recorded inflation of 5.6%, Belgium 5.2% and Spain 4.9%. France registered 3.7%, while Germany’s rate declined to 2.9% from 3.3% in September. Sweden recorded the lowest inflation in the EU at 0.6%.

Overall, annual inflation increased in 16 member states, declined in nine and remained unchanged in two. On a monthly basis, consumer prices rose by 0.4% across the EU and 0.5% in the euro area.

The October figures were published shortly after the European Commission released its autumn economic forecast, which anticipated continued growth alongside persistent price pressures. The Commission projected EU economic expansion of approximately 1.4% in 2026, with annual inflation averaging 3.3% for the year and 3.2% in 2027.

These projections suggest that the European economy could continue expanding without an immediate return to the lower inflation environment experienced in earlier periods. Although the forecast predates Eurostat’s final October release, it provides a broader indication of the economic conditions expected over the coming year.

For the real estate industry, energy prices are particularly important because they affect both the operation of existing buildings and the delivery of new developments. Offices, shopping centres, industrial properties and residential buildings all require energy for heating, cooling, lighting and other essential services.

Higher utility expenditure can increase costs for property owners and occupiers, although the financial consequences depend on lease structures, energy contracts and the efficiency of individual buildings. Properties with lower energy requirements may become comparatively more attractive to tenants seeking greater control over operating expenses.

Construction activity also remains exposed to changes in energy prices. The production and transportation of materials such as cement, steel and glass require substantial energy inputs, meaning sustained price increases could eventually affect construction budgets and project feasibility.

For developers, the challenge is particularly relevant to projects with lengthy construction schedules. Changes in material prices and contractor costs can alter financial assumptions between the planning and completion stages, potentially affecting development margins and investment decisions.

Inflation also influences the financial environment in which property transactions take place. Persistent increases in consumer prices can affect expectations for central bank interest rates, with consequences for borrowing costs, property valuations and the availability of investment finance.

However, the relationship is not automatic. Monetary policy decisions depend on a wider assessment of economic activity, underlying inflation and future price expectations. October’s figures therefore indicate continued inflationary pressure rather than establishing a particular direction for European interest rates.

Residential markets face additional considerations. Higher living expenses can reduce the income households have available for mortgage repayments, rental payments and savings towards a property purchase. This is especially important in cities where housing costs already represent a substantial proportion of earnings.

The effect may be uneven across Europe. In countries experiencing higher inflation, household purchasing power could face greater pressure unless wages rise sufficiently to compensate. Markets with lower inflation may provide a more stable environment for housing expenditure, although affordability also depends on property prices, income levels and financing conditions.

For commercial real estate investors, the divergence between national inflation rates reinforces the importance of evaluating individual markets rather than relying exclusively on European averages. Differences in operating costs, tenant finances and economic expectations can influence the performance of otherwise comparable properties.

The latest figures also underline the growing relevance of energy efficiency in property investment decisions. Buildings with lower energy consumption may offer greater protection against volatile utility costs, while older properties requiring extensive improvements could face additional expenditure.

Europe’s inflation outlook will remain closely connected to developments in energy markets and the wider economy. Although the October increase does not necessarily indicate that inflation will continue accelerating, it demonstrates that price stability remains vulnerable to changes in essential operating and household costs.

For Central and Eastern European property markets, the contrast between Romania’s 7.0% inflation and Czechia’s 2.1% illustrates the different economic conditions confronting developers, investors and occupiers. These differences are likely to remain important when assessing construction expenditure, financing requirements and the ability of households and businesses to absorb additional costs.

As European economies enter 2027, the interaction between energy prices, consumer spending and monetary policy will continue to influence the investment environment. For the real estate sector, managing operating expenses and maintaining financial flexibility may remain as important as identifying opportunities for development and acquisition.
Warsaw’s Signum Work Station Receives Highest Digital Infrastructure Rating

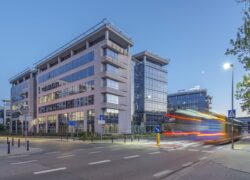
Signum Work Station, an office building in Warsaw’s Mokotów district, has received WiredScore Platinum certification, the highest rating awarded under the international assessment system for digital infrastructure. The certification comes 17 years after the property’s completion and highlights the growing importance of telecommunications reliability in established office buildings.

Located at 49 Domaniewska Street, the building was completed in 2009 and offers more than 32,400 sqm of office accommodation across seven above-ground floors. It is owned by Efekta Real Estate Fund, with TriGranit, part of the DRFG Investment Group, responsible for leasing and asset management. WiredScore evaluates telecommunications infrastructure, including network availability, connection resilience and the capacity to accommodate changing technological requirements.

Reliable connectivity has become increasingly important as businesses depend on cloud-based applications, digital communications and remote access to information. According to CBRE’s European Office Occupier Sentiment Survey 2026, 88% of respondents would reject buildings lacking facilities they consider essential, while 81% regard a productive working environment as an important reason for attending the office. These findings relate to workplace quality generally rather than telecommunications infrastructure specifically.

Marta Zawadzka, Head of Leasing and Asset Management at TriGranit, said the certification formed part of continuing improvements intended to maintain the property’s suitability for tenants. The announcement did not disclose the cost or scope of the telecommunications upgrades.

An important aspect of the assessment concerns the independence of network connections. Piotr Iwanowski, ESG Manager and certification coordinator at CBRE Poland, explained that separate internet services may remain vulnerable if their cables share the same access route. Providing alternative routes can reduce the risk of simultaneous outages and allow tenants to establish more effective backup arrangements.

The property also holds BREEAM Excellent and ActiveScore Platinum certifications, alongside the WELL Health-Safety Rating obtained in September 2026. Its tenants include Mondelez, Ringier Axel Springer Polska, enel-med Medical Centre, Columbia and PPD. The building provides office floors exceeding 4,600 sqm, approximately 870 parking spaces and additional commercial facilities. DRFG acquired the property in December 2024.

The certification reflects the importance of maintaining older office properties as they compete with newer developments across Warsaw. Improvements to telecommunications and other building systems can help landlords respond to changing occupier requirements, although certification does not necessarily translate into higher rents or stronger occupancy.

Signum Work Station’s latest assessment demonstrates that the technical capabilities of an established office building can be improved long after construction. Its commercial impact will ultimately depend on tenant demand, operating costs and leasing performance.

Higher Food Prices Put Pressure on Czech Workers and Restaurant Spending

Rising food costs are influencing how employees in the Czech Republic spend their lunch budgets, with younger workers reporting greater difficulty affording healthier meals. Research conducted through the FOOD Barometer 2026 found that 72% of surveyed employees aged 19 to 44 would choose better-quality and more varied food if the value of their employer-funded meal vouchers doubled.

The findings suggest that workplace food allowances have become an important factor in everyday spending decisions. Among younger respondents, 62% said a doubling of their allowance would enable them to purchase lunch throughout the working week without using additional personal funds. Across the Czech survey as a whole, 68% anticipated improvements in their food choices, compared with 73% of respondents internationally.

The financial pressures were more pronounced among younger participants. Approximately 44.5% of those aged 19 to 44 identified the price of healthier food as a barrier, compared with 31.6% of respondents aged 45 to 65. At the same time, 71% of younger employees considered workplace assistance with healthier eating important, indicating a difference between their dietary preferences and what they could regularly afford.

Aneta Martišková, Director of External Relations at Edenred, which coordinates the research, said the findings showed that employees were increasingly considering food quality alongside price. She argued that employers should assess whether their existing contributions remain sufficient to cover a reasonable proportion of daily lunch costs as prices change.

The research also identified a connection between employee benefits and restaurant visits. Among respondents aged 19 to 44, 54% considered the acceptance of meal vouchers when deciding where to eat. If the benefit were withdrawn, 46% said they would visit restaurants less frequently, while around three-quarters believed the allowance increased their available food budget.

For restaurants, these spending patterns may influence the stability of weekday trade, particularly in business districts where lunchtime customers include large numbers of office and service-sector employees. The international survey found that 60% of participating restaurant operators associated meal voucher acceptance with higher sales, while 55% believed it encouraged more frequent visits. These responses describe business owners’ assessments rather than independently verified revenue increases.

The findings also have implications for employers and commercial property occupiers. Food allowances form part of employment costs, while access to affordable lunchtime options can influence the experience of employees working in offices, industrial facilities and other workplaces. However, the research does not establish whether larger allowances would increase office attendance or produce measurable changes in workplace productivity.

The FOOD Barometer 2026 gathered responses from 55,468 employees in 21 countries and 1,035 restaurant operators across 18 countries. The Czech survey included 3,280 participants. The organisers caution that the findings reflect the views of those surveyed and should not be interpreted as representative of the entire Czech population.

The results point to a continuing relationship between food affordability, employee benefits and restaurant demand. While increased meal allowances could provide workers with greater flexibility, the financial consequences for businesses and hospitality operators would depend on employer decisions, restaurant pricing and actual changes in consumer spending.

Bulgaria’s FATF Grey List Exit Could Boost Property Investment

Bulgaria’s removal from the Financial Action Task Force (FATF) grey list marks an important improvement in the country’s regulatory standing, potentially reducing compliance requirements for international banks, investors and businesses. The decision, announced on 30 October 2026, ends three years of increased monitoring and could improve conditions for cross-border financing, corporate acquisitions and real estate investment.

The decision followed a FATF meeting in Paris, where Bulgaria was removed alongside Côte d’Ivoire, the Democratic Republic of the Congo and Monaco. According to an analysis published by international law firm CMS on 18 November, the move reflects progress in addressing weaknesses in anti-money laundering controls, corporate transparency and financial crime investigations.

Bulgaria had been under increased monitoring since October 2023 following an evaluation by the Council of Europe’s MONEYVAL committee. The assessment identified shortcomings in beneficial ownership records, financial intelligence and the investigation and confiscation of criminal proceeds. Bulgaria was the only European Union member state on the FATF grey list.

In response, Bulgarian authorities introduced legislative and regulatory reforms covering financial supervision, corporate ownership verification and controls on businesses including currency exchange providers, postal money operators and real estate agents. By June 2026, FATF concluded that the country had substantially completed its reform programme, with an on-site assessment subsequently supporting its removal.

For international businesses, the main benefit could be lower compliance costs and fewer administrative delays. Although grey listing does not impose economic sanctions, it often prompts financial institutions to apply additional scrutiny to transactions involving affected jurisdictions, potentially complicating banking relationships, payments and investment financing.

In the United Kingdom, Bulgaria’s inclusion in the high-risk third-country framework since December 2023 required regulated businesses to conduct enhanced due diligence on relevant transactions. Its removal from the FATF list should eliminate the automatic country-based trigger under the UK’s current framework, although institutions must continue assessing individual clients and transactions according to their risk profiles.

Within the European Union, Bulgaria’s FATF designation did not automatically place it on the EU’s separate high-risk third-country list. Nevertheless, banks and other regulated businesses could consider the classification when assessing financial risks. Its removal now allows institutions to reconsider internal risk ratings and potentially simplify procedures for Bulgarian counterparties.

For Bulgaria’s property market, the decision could make international investment transactions easier to complete. Real estate acquisitions frequently require detailed verification of funding sources, corporate ownership and financing arrangements. Reducing country-specific compliance concerns may help foreign investors and lenders process transactions more efficiently, particularly where several banking jurisdictions are involved.

The development also follows Bulgaria’s accession to the euro area in 2026, removing another potential obstacle to international financial activity. However, any impact on property investment volumes or financing costs will depend on broader economic conditions and individual lending policies.

Bulgaria remains subject to MONEYVAL monitoring and must continue strengthening its anti-money laundering framework. Further regulatory changes are approaching across the European Union, with Regulation (EU) 2024/1624 introducing harmonised requirements from July 2027.

The new framework will establish more consistent rules for customer identification, transaction monitoring and beneficial ownership verification. It will also introduce an EU-wide €10,000 ceiling on cash payments for goods and services, subject to applicable exceptions.

The EU Anti-Money Laundering Authority, established in Frankfurt, will progressively assume direct supervision of selected high-risk cross-border financial institutions. From 2028, it is expected to oversee up to 40 qualifying institutions and groups, while national regulators will continue supervising other businesses.

For Bulgarian financial institutions, property companies and investors, the regulatory changes will require continued attention to compliance procedures, particularly concerning ownership transparency and transaction monitoring.

The removal from the FATF grey list should therefore be viewed as a reduction in country-specific regulatory concerns rather than an elimination of financial crime risks. Enhanced checks will remain necessary where individual transactions or counterparties present higher risks.

For Bulgaria’s real estate sector, the decision removes a potential source of friction in international investment and financing. While its measurable impact remains uncertain, the change could improve the country’s attractiveness to foreign capital as it becomes more closely integrated into European financial markets.

Source: CMS

Higher Mortgage Costs Lead Prague Developer to Introduce New Buyer Incentives

Rising mortgage interest rates in the Czech Republic are prompting residential developers to reconsider how they attract purchasers, with Central Group introducing financial assistance for buyers of more than 250 completed apartments and houses across eight locations in Prague. The arrangement reduces the effective mortgage interest rate to 2.99% for the first two years, with the developer covering the difference between this level and the rate agreed with the lending bank.

The decision follows a period of increasing borrowing costs. According to Hypoindex figures cited by Central Group, average advertised mortgage rates have reached approximately 6%, compared with 4.9% in March 2026. The increase has made home purchases more expensive for households dependent on bank financing, adding to existing affordability pressures in Prague’s residential market.

Higher interest rates affect both monthly repayments and the amount households can borrow, potentially reducing the number of buyers able to complete a purchase. Dušan Kunovský, founder and Chief Executive Officer of Central Group, said financing conditions were influencing purchasing decisions, with some prospective buyers delaying transactions in anticipation of lower borrowing costs.

The developer’s new arrangement applies to completed residential properties and is scheduled to remain available until the end of January 2027. Buyers will obtain financing through a bank, while Central Group will provide financial support equivalent to the difference between the agreed mortgage rate and 2.99% for two years. The announcement does not identify participating lenders or provide detailed eligibility requirements.

An additional provision would allow qualifying purchasers to sell their property back to the developer for its original purchase price if mortgage rates fail to decline sufficiently within the two-year period. However, the company has not specified the conditions that would activate this arrangement, including the required movement in interest rates, possible transaction expenses or other contractual restrictions.

For buyers who do not use the mortgage arrangement, Central Group is offering contributions towards property furnishings. These range from CZK 300,000 for studio apartments to CZK 900,000 for five-room apartments and houses. The amounts for intermediate property sizes are CZK 450,000 for two-room homes, CZK 600,000 for three-room properties and CZK 750,000 for four-room accommodation.

The incentives apply to properties that have already been completed, allowing the developer to concentrate on selling existing residential stock. Rather than lowering published asking prices, the company is providing benefits linked to mortgage expenses or furnishing costs. The announcement does not disclose individual property prices, sales volumes or the financial cost of the programme.

Such arrangements may help developers maintain transaction activity when higher borrowing costs restrict purchasing power. However, temporary interest assistance does not reduce the outstanding mortgage principal, and borrowers could face increased repayments once the two-year period ends. The actual financial benefit will depend on the size of the loan, its repayment structure and future interest rates.

The initiative reflects the influence of mortgage conditions on Prague’s housing market, where affordability remains closely connected to household incomes and financing costs. Whether the incentives lead to additional sales will depend on buyer confidence, the terms of the financial arrangements and developments in the Czech mortgage market.

Eight Commercial Buildings Under Construction at Former Industrial Site Near Prague

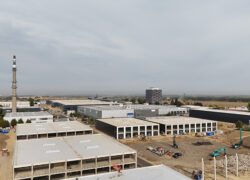
Developer CONTERA is expanding its CITYSITE business park in Říčany, southeast of Prague, with eight commercial buildings currently under construction. The project forms part of the redevelopment of a former industrial site, where regeneration began in 2010. HSF System, a construction company belonging to PURPOSIA Group, is responsible for the building works.

The development occupies a site of 53,246 sqm and is intended to accommodate smaller businesses requiring premises for several activities. Individual units range from approximately 500 to 4,000 sqm, allowing companies to combine offices, storage, sales facilities and light manufacturing. The developer has not disclosed the combined floorspace of the eight buildings, the investment value or their expected completion dates.

Unlike conventional large logistics facilities, the project focuses on businesses requiring smaller, adaptable premises. Potential occupiers include distributors, service providers, manufacturers and companies operating showrooms or research facilities. The arrangement allows different commercial activities to take place within individual units.

Construction is progressing simultaneously across eight buildings at different stages of completion. Jan Černý, Regional Director for Bohemia at HSF System, said the programme requires coordination between construction teams while ensuring that new buildings integrate with the infrastructure already operating on the site.

The development incorporates heat pumps, photovoltaic installations, planted roofs and rainwater management systems. Landscaping, electric vehicle infrastructure and cycling facilities are also included. However, no figures have been provided for expected energy savings or renewable electricity generation.

The location offers road connections to Prague and the surrounding metropolitan area, including access to the Prague ring road. An established retail area nearby may also support businesses requiring direct customer access. According to Martin Budina, Partner and Development Director at CONTERA, existing occupiers include companies involved in building products, optical equipment distribution and specialist materials manufacturing. Additional leisure and catering facilities are under consideration but have not been confirmed.

The project reflects demand for commercial accommodation that combines office, storage and operational functions without requiring large industrial premises. Such developments may appeal to smaller businesses seeking to consolidate activities near major urban markets, although demand will depend on rental costs, accessibility and the suitability of individual units.

The continued redevelopment of the Říčany property also illustrates the reuse of former industrial land around Prague. With eight buildings under construction, the latest phase will add further commercial accommodation to the existing site. Its eventual contribution to the local market will depend on completion schedules, leasing activity and occupancy levels.

Bucharest’s Calea Victoriei Records Europe’s Fastest Retail Rent Growth as Global Market Slows

Prime retail rents on Bucharest’s Calea Victoriei increased by 29% over the past year, the strongest annual rise among the European locations examined in Cushman & Wakefield’s Main Streets Across the World 2026 report. The increase lifted the Romanian capital three positions to 35th place in the global ranking of the most expensive retail destinations, although rents remain considerably below those recorded in Prague, Budapest and the leading Western European shopping streets.

According to the consultancy, the headline rent for the most sought-after retail premises on Calea Victoriei reached €90 per sqm per month in 2026, compared with €70 a year earlier. The increase was the second-largest among the 50 markets represented in the global ranking, behind New York’s Upper Fifth Avenue. Bucharest now shares 35th position with Belgrade and Mexico City, reflecting similar rental levels in the locations used for the comparison.

The figures represent prime headline rents for selected retail premises rather than average rents across Bucharest’s entire shopping market. They also describe the asking or benchmark rental level associated with the most sought-after locations and should not be interpreted as evidence that every retailer on Calea Victoriei experienced a 29% increase in its occupancy costs.

Cushman & Wakefield attributes the increase partly to improvements in the surrounding public spaces and a rise in visitor numbers, including international tourists. These changes have coincided with demand from retailers seeking premises in central Bucharest, where the supply of suitable ground-floor accommodation is limited. The report does not provide transaction-level leasing evidence or detailed vacancy figures for the street, making it difficult to determine how much of the increase reflects newly agreed rents rather than changes in market benchmarks.

Dana Radoveneanu, Head of Retail Agency at Cushman & Wakefield Echinox, said the street had attracted greater interest from international retailers and Romanian businesses seeking central locations. She pointed to the limited availability of suitable premises as an important factor influencing rental levels. The consultancy’s observations suggest that demand for established city-centre retail locations is becoming more selective, particularly where retailers place importance on pedestrian activity, tourism and proximity to other commercial uses.

Despite the substantial annual increase, Bucharest remains less expensive than several established Central European retail markets. Prime rents in Prague reached €235 per sqm per month, approximately 2.6 times the level recorded on Calea Victoriei. Budapest followed at €180, while Warsaw stood at €94, only slightly above Bucharest. Belgrade recorded the same €90 monthly level as the Romanian capital.

Elsewhere in the region, the report identified rents of €70 per sqm per month in Zagreb, €63 in Sofia and €60 in Ljubljana. Bratislava recorded €45, followed by Vilnius at €39, Riga and Tallinn at €35 each, and Skopje at €28. These differences illustrate the considerable variation in retail property costs across Central and Eastern Europe, although direct comparisons are influenced by the individual streets selected, local purchasing power and the characteristics of available premises.

At the global level, New York’s Upper Fifth Avenue returned to first place after a 35% annual increase in prime rents to €2,083 per sqm per month. The location moved ahead of London’s New Bond Street, where rents remained unchanged at €1,720, and Milan’s Via Montenapoleone, which recorded €1,667. Both European streets had experienced substantial increases in earlier reporting periods but showed no further growth in the latest assessment.

Hong Kong’s Tsim Sha Tsui ranked fourth globally at €1,085 per sqm per month, following a 6% decline, while the Avenue des Champs-Élysées in Paris completed the top five at €1,043, unchanged from the previous year. Tokyo’s Ginza ranked sixth at €917, followed by Zurich’s Bahnhofstrasse at €795, Sydney’s Pitt Street Mall at €697, Seoul’s Myeongdong at €571 and Vienna’s Kohlmarkt at €450.

The international comparison highlights the scale of the difference between Bucharest and the world’s most expensive retail locations. Prime rents on Upper Fifth Avenue were more than 23 times those recorded on Calea Victoriei, while New Bond Street commanded approximately 19 times the Bucharest level. These differences reflect variations in international retailer demand, visitor spending, property availability and the commercial position of individual shopping districts.

The 2026 report examined prime retail rents across 147 urban shopping locations worldwide, with its global ranking based on the most expensive destination in each of 50 markets. Across all monitored locations, rental growth averaged 3.0% year on year in local currency terms, compared with 4.3% in the previous edition. The figures indicate a moderation in overall rental growth despite substantial increases in selected cities.

Nearly half of the locations surveyed, approximately 49%, recorded higher rents, while 32% remained unchanged and 19% experienced declines. In Europe, average rental growth was 2.9%, with increases recorded in 42% of the 57 locations monitored. Bucharest’s 29% rise therefore stands considerably above the regional average and contrasts with the more limited changes observed across much of the European market.

The different growth rates also demonstrate why changes in global rankings require careful interpretation. A city may improve its position because rents have increased locally, because competing destinations have recorded slower growth or because of exchange-rate movements affecting euro-denominated comparisons. The report’s annual growth figures are calculated in local currencies, while the international rental table presents values in euros.

For Bucharest’s retail property market, the increase on Calea Victoriei points to stronger competition for a limited number of centrally located premises. However, the effect on retailers will depend on individual lease terms, sales performance and operating expenses. Higher rents can improve the income prospects of property owners, but they may also restrict the range of businesses able to afford accommodation in the most expensive sections of the street.

The findings also raise questions about how rental growth will develop if the availability of suitable premises remains constrained. Established buildings in central locations cannot necessarily accommodate the space requirements of larger international retailers, while alterations to historic properties and existing commercial premises may involve planning and construction limitations. The report does not establish whether the current pace of rental growth is sustainable.

Calea Victoriei’s movement to 35th place reflects a substantial change in its reported prime rental benchmark during 2026. Nevertheless, Bucharest remains a comparatively affordable market within the European high-street hierarchy, particularly when measured against Prague and Budapest. Its future position will depend on retailer demand, visitor spending, the supply of suitable premises and whether the sharp increase in rents is supported by continued leasing activity.

German Household Incomes Recover After Inflation Shock, but Inequality and Poverty Persist

German household incomes have begun recovering from the effects of high inflation, although purchasing power has yet to return fully to its previous level. New research published on 18 November 2026 by the German Institute for Economic Research (DIW Berlin) shows that real disposable household incomes have increased across all income groups in recent years, while longer-term differences between high- and low-income households remain substantial.

The findings, based on the Socio-Economic Panel (SOEP), indicate that average real household net income increased by approximately 30% between 1995 and 2024. However, the benefits of this growth have been unevenly distributed. Households in the middle of the income distribution experienced increases of slightly more than 25%, while those at the upper end recorded gains exceeding 50%. By comparison, incomes among the lowest-earning households have remained broadly unchanged over the longer period.

Although income inequality has increased considerably since the mid-1990s, DIW Berlin reports that the distribution of incomes has changed relatively little in recent years. The latest recovery follows the sharp increase in consumer prices during 2022 and 2023, which reduced the purchasing power of households across Germany.

Despite these pressures, satisfaction with household income has improved. The proportion of people reporting that they are very satisfied with their income doubled from 13% in 2005 to 26% in the latest findings. Improvements were also recorded among households in the lower half of the income distribution, suggesting that perceptions of financial wellbeing have strengthened even where longer-term income growth has been limited.

Household saving behaviour has also changed significantly. In 2005, approximately 57% of people reported being able to save money, compared with 72% in 2025. However, the ability to accumulate savings continues to depend heavily on income.

Among the lowest-income 10% of the population, approximately 30% reported saving at least some money, with an average savings rate of just 3% of household net income. Among middle-income households, 80% were able to save, with an average savings rate of 10%. At the highest end of the income distribution, 91% reported saving, with an average savings rate of 20%, equivalent to approximately €1,800 per month.

These differences illustrate the uneven financial capacity of German households. While higher-income groups can allocate substantial amounts towards savings and investment, lower-income households generally have less scope to build financial reserves or absorb unexpected expenditure.

The findings also have implications for Germany’s residential property market. Household disposable income and accumulated savings influence the ability to fund rental deposits, meet housing costs and build the equity required for home purchases. Although the DIW research does not directly measure housing affordability, the differences in savings capacity suggest that households are entering the housing market from markedly different financial positions.

The recovery in real incomes may gradually improve housing affordability for some households, particularly if income growth continues to outpace inflation. However, the limited financial reserves of lower-income groups remain a constraint, especially in markets where housing costs account for a substantial proportion of household expenditure.

Poverty remains another persistent concern. According to DIW Berlin, approximately 17% of Germany’s population lives below the relative poverty-risk threshold, a proportion that has remained broadly stable in recent years but is significantly higher than in the longer-term historical comparison.

Single-person households and single parents are particularly exposed to financial difficulties. The institute notes that limited income can restrict participation in social and economic activities, while some affected households have little or no employment income.

Markus Grabka, a researcher at DIW Berlin and author of the study, argues that Germany’s social support arrangements should provide stronger financial incentives for people on lower incomes to increase their working hours. Under existing arrangements, additional employment income can sometimes be largely offset by reductions in state benefits, leaving households with little financial improvement.

One proposal discussed in the research involves bringing together basic income support, social assistance, housing benefits and child-related supplements into a more coordinated system. Such an approach could reduce situations in which additional earnings produce only marginal improvements in disposable income.

For Germany’s economy, the findings present a mixed picture. Real incomes are recovering, household satisfaction has improved and a greater proportion of the population is saving. At the same time, the substantial differences in long-term income growth and savings capacity demonstrate that the recovery has not eliminated structural inequalities.

For the property sector, these trends reinforce the importance of examining household purchasing power alongside headline income growth. The ability to afford housing depends not only on earnings but also on accumulated savings, financing conditions and the proportion of income required to cover everyday living expenses.

The DIW findings suggest that while improving household finances may support housing demand, the divide between households with substantial financial reserves and those with limited savings will remain an important factor in Germany’s residential market.

EU Packaging Rules Prompt RON 15.3 Million Manufacturing Investment in Eastern Romania

Romanian cardboard packaging producer Printco is investing approximately RON 15.3 million in its manufacturing operations in Iași as European regulations place greater emphasis on recyclable materials and restrictions on potentially harmful chemicals. The programme, which receives partial financial support from European Union funds, is intended to reduce the consumption of raw materials and increase the proportion of recycled cardboard used in production. The company has not disclosed the value of the EU contribution or provided a detailed breakdown of the planned expenditure.

The investment follows the introduction of the European Union’s Packaging and Packaging Waste Regulation (PPWR), which began applying on 12 August 2026. The legislation establishes requirements for businesses involved in manufacturing, supplying and distributing packaged goods, with additional measures scheduled to take effect over the coming years. For packaging producers, the changes affect material selection, product testing, manufacturing methods and the information that must accompany products entering the European market.

Following publication of the regulation in January 2025, the manufacturer reviewed its production arrangements and material supplies in cooperation with customers and suppliers. The assessment examined how existing packaging products would be affected by the new requirements and what changes might be necessary. The investment announced in November 2026 forms part of that process, although the company has not specified whether it will involve additional production lines, replacement machinery or modifications to existing facilities.

One of the first areas affected by the legislation is packaging used for food products. New restrictions apply to per- and polyfluoroalkyl substances, commonly known as PFAS, a group of chemicals previously used in certain packaging materials to improve resistance to moisture and grease. Their persistence in the environment and concerns about possible health effects have resulted in tighter European controls. The regulation establishes several concentration thresholds, including 25 parts per billion for an individual PFAS identified through targeted testing, equivalent to 25 milligrams per tonne of packaging material.

The restrictions apply to food-contact packaging placed on the European market, including situations where chemical residues originate from the raw materials rather than being deliberately introduced during manufacturing. This creates additional responsibilities for producers using recovered fibres, as recycled paper and cardboard may contain substances associated with earlier printing, coatings or other industrial processes. Increasing the proportion of recycled material therefore requires manufacturers to assess chemical safety alongside environmental performance.

Printco reports that it has conducted annual laboratory examinations of its packaging materials since 2022, using two independent accredited testing facilities within the European Union. The analyses cover chemical migration, PFAS, heavy metals and mineral oil hydrocarbons, including MOSH and MOAH. According to the company, the results obtained to date have remained within the relevant regulatory limits. The underlying laboratory findings were not supplied with the announcement, meaning these statements have not been independently assessed.

The manufacturer has also been increasing its use of cardboard produced entirely from recycled fibres while examining ways to reduce the quantity of material required for individual packaging products. Lower material consumption may reduce purchasing costs and waste generation, although the extent of any savings will depend on the types of packaging produced, the availability of suitable recycled inputs and the technical requirements of customers.

Diana Mocanu, founder and Chief Executive Officer of the Printco-Gama group, said the regulatory changes had led the business to consider further adjustments to its production practices. She indicated that the company’s response was not limited to meeting the minimum requirements of the legislation, but also involved examining opportunities to reduce resource use. The announcement did not provide quantified targets for lower material consumption, recycled content or future production volumes.

The business holds ISO 14001 environmental management certification, together with FSC and PEFC certifications relating to material sourcing and BRCGS Packaging Materials certification. These standards address different aspects of manufacturing management, supply-chain controls and packaging quality. They do not, however, replace the need to demonstrate compliance with individual chemical and recyclability requirements established by European legislation.

Additional obligations are expected to affect packaging producers from 2028 onwards, including the introduction of more consistent labelling requirements across European markets. From 2030, further provisions concerning packaging design and recyclability are scheduled to apply. Manufacturers will consequently need to consider not only the composition of packaging materials but also how products can be identified, collected and processed after use.

For Romania’s manufacturing sector, these changes may require investment in equipment, laboratory testing, production controls and relationships with raw material suppliers. Smaller producers may face particular challenges where compliance involves additional technical expenditure or changes to established manufacturing processes. European funding can offset part of the financial burden, although the availability and scale of support vary between individual investment programmes.

The investment in Iași reflects the connection between European environmental policy and capital expenditure decisions in the manufacturing sector. Packaging producers supplying food manufacturers, retailers and other consumer-facing businesses must adapt to requirements that affect both the physical properties of their products and the documentation supporting their sale.

The financial implications of Printco’s programme remain difficult to assess without information on the equipment being purchased, implementation schedule or anticipated operating savings. The company has not announced an increase in manufacturing capacity or a property development component, and the available information does not establish whether additional industrial space will be required.

The longer-term significance of the investment will depend on measurable changes in material consumption, the proportion of recycled inputs and the ability of the manufacturer’s products to satisfy European market requirements. More broadly, the regulatory transition is likely to remain an important consideration for industrial investment across Romania as packaging producers prepare for further obligations later in the decade.

India’s Manufacturing Growth Brings Worker Housing into Focus Across Industrial Regions

India’s expanding manufacturing sector is creating new requirements for residential accommodation near industrial facilities, as investment in semiconductor production, electronics manufacturing and large industrial developments increases the need for workers to live within reasonable travelling distance of their workplaces. While government incentives and private investment are supporting the construction of factories, the availability of suitable housing is becoming an important consideration for manufacturers, property developers and regional authorities.

The relationship between industrial employment and residential development is particularly significant in locations where new manufacturing facilities are being established outside major urban centres. Large factories can attract workers from surrounding districts and other states, creating demand for accommodation that ranges from shared dormitories and rental housing to family apartments and homes for skilled professionals. However, the scale of residential development varies considerably between industrial locations, and announced manufacturing investments do not necessarily translate immediately into completed housing projects.

Research published by NITI Aayog in December 2024 identified inadequate accommodation near manufacturing centres as a constraint on industrial employment and productivity. The government policy institution estimated that India’s manufacturing workforce could reach approximately 120 million people by 2033. Under a scenario in which 20% of those workers require formal accommodation, the potential requirement would amount to approximately 25 million accommodation units.

The estimate illustrates the possible scale of demand but should not be interpreted as an existing shortage of 25 million homes or a forecast of residential construction. It relates primarily to affordable accommodation for industrial employees, including shared rental facilities, rather than conventional housing developments intended for private ownership.

For manufacturers, proximity between accommodation and production facilities can influence recruitment, employee retention and operational efficiency. Factories operating multiple shifts often require reliable transport arrangements, while workers relocating from other regions may face difficulties finding suitable rental properties. These challenges can become more pronounced in emerging industrial districts where employment grows faster than surrounding residential infrastructure.

India’s semiconductor industry provides an example of how manufacturing investment is creating additional infrastructure requirements. By September 2026, the government had approved 12 semiconductor projects involving proposed investment exceeding ₹1.64 lakh crore. These developments form part of a wider effort to increase domestic semiconductor production and strengthen electronics manufacturing.

The projects are concentrated in selected industrial locations, including Gujarat and Assam, with related electronics and manufacturing investment taking place across other states. Their workforce requirements differ according to the type of facility, the stage of construction and the level of automation. Semiconductor manufacturing plants require engineers and specialist technicians, alongside operational, maintenance and supporting personnel, while construction phases can generate temporary demand for accommodation on a different scale.

Gujarat’s Dholera industrial region is among the locations where the connection between manufacturing development and residential requirements is becoming more apparent. Tata Group’s semiconductor investment has encouraged planning for supporting infrastructure, including accommodation for employees and personnel associated with suppliers.

In March 2025, Business Standard reported that Tata was seeking approximately 80 additional acres in Dholera, with potential development including accommodation for around 3,000 to 3,500 employees and supplier personnel. Separate reporting has described proposals for approximately 1,500 apartments associated with the semiconductor project. These figures relate to development plans and should not be combined without confirmation that they represent separate housing schemes.

The proposed accommodation reflects the practical requirements of establishing a major manufacturing operation in a developing industrial district. Workers and specialist employees need access to housing, transport, healthcare, retail and other services, while manufacturers must consider whether local infrastructure can support their operations as employment increases.

The Indian government also approved a semiconductor-related special economic zone for Tata Semiconductor Manufacturing in Dholera in April 2026. The development covers approximately 66 hectares and carries an estimated employment potential of 21,000 people. This represents prospective employment associated with the project rather than an established workforce, and the eventual residential requirement will depend on recruitment, commuting patterns and the availability of existing housing.

Haryana provides another example of industrial and residential development taking place within the same broader economic area. Reliance’s Model Economic Township in Jhajjar, known as MET City, is being developed as a large industrial and commercial centre intended to accommodate manufacturing businesses and supporting activities.

The township has attracted hundreds of companies and generated substantial employment activity. The developer has reported more than 600 companies and over 40,000 jobs created within the wider development. These figures demonstrate the scale of industrial activity but do not establish how many employees live within the township or require newly constructed accommodation.

In February 2026, Reliance announced plans for a mixed-use development known as Metropolis, with an initial phase covering approximately 100 acres and including residential and industrial plots. The project illustrates how industrial developers are incorporating residential land into broader development strategies, although the announcement does not establish the number of completed homes or the eventual occupancy of the residential component.

Tamil Nadu offers a different example through its established electronics manufacturing industry. Production centres around Sriperumbudur and other industrial locations employ substantial numbers of workers, including people recruited from outside the immediate area. Employer-associated hostels, dormitories and transport arrangements have become part of the accommodation infrastructure supporting some electronics operations.

Recruitment information published through Tamil Nadu’s employment services has included hostel accommodation and transport for electronics manufacturing positions. Such arrangements demonstrate the importance of housing and mobility in attracting industrial labour, particularly for workers employed on production shifts. However, available information does not establish whether the existing supply is sufficient to meet demand across the state’s manufacturing centres.

The residential requirements associated with industrial expansion are not uniform. Temporary construction workers may need short-term shared accommodation, while permanent production employees often require affordable rental housing with dependable transport connections. Engineers, managers and specialist technical personnel may seek independent apartments or family homes with access to schools, healthcare and other urban services.

These differences create opportunities for several forms of property development. Purpose-built worker accommodation can provide relatively high residential capacity close to factories, while rental apartments and conventional housing may become viable as industrial locations develop more established employment bases. The commercial prospects of each model depend on local wages, occupancy levels, land costs and the willingness of employers to participate in accommodation provision.

The availability of land remains an important challenge. Industrial areas are frequently planned primarily around production facilities, roads, utilities and logistics infrastructure, with residential requirements receiving less attention during the early development stages. Where housing is subsequently introduced, developers may encounter restrictions on land use, limited public transport and insufficient supporting services.

Financing affordable worker accommodation can also be difficult. Rental levels must remain accessible to industrial employees while covering land acquisition, construction, maintenance and management costs. Projects may therefore require long-term agreements with manufacturers, suitable land arrangements or other measures that improve financial viability.

For residential developers, manufacturing investment can provide an indication of future demand, but employment announcements alone are not sufficient to justify large housing projects. The number of operational jobs, workforce composition, existing accommodation supply and expected commuting distances all influence the amount and type of housing required.

Institutional investors face similar considerations. Worker accommodation may offer opportunities for long-term rental income, particularly where established manufacturers support occupancy. However, concentration around a limited number of employers can expose properties to changes in production, recruitment and industrial investment. Buildings designed for shared accommodation may also require specialised management and may be less adaptable than conventional residential properties.

Public policy will influence how these markets develop. NITI Aayog’s research has drawn attention to the need for planning and regulatory arrangements that make formal worker accommodation easier to deliver. Better coordination between industrial investment, residential land allocation and local infrastructure could help reduce the gap between factory construction and the availability of suitable housing.

The expansion of semiconductor, electronics and other manufacturing industries is therefore creating a wider property development challenge that extends beyond industrial buildings. Projects in Gujarat and Haryana demonstrate how residential planning is becoming part of industrial development, while established manufacturing locations in Tamil Nadu show the importance of accommodation and transport arrangements for existing workforces.

Nevertheless, evidence of a nationwide residential construction boom around new factories remains limited. The current picture is better characterised by growing accommodation requirements, selected development proposals and differing local responses to industrial employment growth.

As India’s manufacturing investment continues, the ability to provide appropriate housing near production centres will become an increasingly important factor in the development of industrial regions. For the property sector, the opportunity lies not simply in constructing more homes, but in delivering accommodation that reflects the workforce, infrastructure and economic conditions of each manufacturing location.

Source: © CIJ.World India Research & Analysis Team

front page info
LATEST NEWS