OBERMEYER HELIKA Marks 35 Years in Czech and Slovak Markets

The design and consulting firm OBERMEYER HELIKA is marking 35 years since its founding. Established in 1990, the company has been involved in hundreds of projects in the Czech Republic and abroad, covering healthcare facilities, multifunctional arenas, residential and commercial complexes, bridges, highways, and industrial buildings.

The firm is part of the international OBERMEYER Group and operates from offices in Prague, Brno, and Bratislava. Its teams include architects, engineers and technical specialists, and it often works with experts from other disciplines such as medicine, history, and the arts.

One of its recent projects, the Family Care Pavilion at Pelhřimov Hospital, received the Building of the Year 2023 award, recognised for its construction quality and technical execution. In the industrial sector, OBERMEYER HELIKA is collaborating with Škoda Auto on conveyor bridges and a car body warehouse in Mladá Boleslav.

The firm has expanded its digital capabilities in recent years, using 3D models, point clouds, virtual and augmented reality, digital visualization, and programming tools. It is also beginning to apply artificial intelligence in project work.

From next year, OBERMEYER HELIKA plans to move its Prague headquarters to the E Factory building in the Pragovka Art District in Vysočany, a redevelopment of the historic Praga factory site.

Over its 35 years, the company has been involved in several high-profile projects, including the reconstruction of the former Grain Exchange at the Czech National Bank, the roof structure of Prague’s O2 Arena, and most recently the new multifunctional Brno Arena. Current projects include structural design for the expansion of Westfield Černý Most, general design for the Prospect Zlín high-rise, and documentation for Galerie Pernerka in Pardubice. In healthcare, key references include the Proton Therapy Center at Bulovka University Hospital and the Medicentrum in Prague’s Waltrovka district.

In Slovakia, OBERMEYER HELIKA has been active since 2004, starting with the Bory Mall shopping center in Bratislava. Ongoing work includes the reconstruction and expansion of the University Hospital in Banská Bystrica, as well as the refurbishment of the Dunaj department store and the development of the Metropolis residential towers in Bratislava.

Slovak Logistics Sector in 2025: Rising Investment, Higher Vacancies, and Competitive Rents

Slovakia’s industrial property market is in a transitional phase this year, marked by record capital inflows on one hand and signs of cooling demand on the other.

The volume of commercial real estate transactions in Slovakia in the first six months of 2025 exceeded half a billion euros, already surpassing the total figure for all of last year. Warehouses and production halls attracted the largest share of investor attention, while retail and office assets followed at a distance. Analysts expect that by the end of the year, total investment could approach one billion euros.

The surge in investment has come alongside a slowdown in leasing. Companies committed to just over 100,000 square metres of logistics space in the second quarter, with new leases and pre-leases making up most of the total. Despite steady activity, the vacancy rate climbed to just above six percent, the highest level in several years, as new projects came onto the market faster than they could be absorbed. Roughly a third of the space now under construction has not yet secured tenants, reflecting the risk that speculative developments launched earlier may take longer to fill.

Developers delivered nearly 80,000 square metres of new facilities in the second quarter, concentrated largely in western Slovakia. Another 300,000 square metres remains on the way, including notable schemes in eastern parts of the country, where manufacturers are expanding production.

Rental dynamics reflect the growing competition among landlords. Prime logistics rents have edged down slightly to around €5.50 per square metre per month, while in neighbouring Czech cities headline levels remain higher, and in Poland and Hungary owners are increasingly granting concessions to secure occupiers.

A clear shift is also visible in the quality of space being demanded. Warehouses equipped for automation, energy-efficient operations and certified under sustainability standards are quickly becoming the benchmark across Central Europe, and Slovakia is no exception. Tenants now expect smart systems and low operating costs as standard, while investors place increasing weight on environmental credentials.

Although the overall outlook remains positive, with new manufacturers such as Volvo moving into the market and nearshoring trends favouring Central Europe, geopolitical uncertainty and global trade tensions are tempering optimism. Analysts expect the remainder of 2025 to bring gradual stabilisation, with tenants benefiting from greater choice and landlords under pressure to deliver modern, flexible and sustainable facilities.

Source: comp.

Slovak Logistics Sector in 2025: Rising Investment, Higher Vacancies, and Competitive Rents

Slovakia’s industrial property market is in a transitional phase this year, marked by record capital inflows on one hand and signs of cooling demand on the other.

The volume of commercial real estate transactions in Slovakia in the first six months of 2025 exceeded half a billion euros, already surpassing the total figure for all of last year. Warehouses and production halls attracted the largest share of investor attention, while retail and office assets followed at a distance. Analysts expect that by the end of the year, total investment could approach one billion euros.

The surge in investment has come alongside a slowdown in leasing. Companies committed to just over 100,000 square metres of logistics space in the second quarter, with new leases and pre-leases making up most of the total. Despite steady activity, the vacancy rate climbed to just above six percent, the highest level in several years, as new projects came onto the market faster than they could be absorbed. Roughly a third of the space now under construction has not yet secured tenants, reflecting the risk that speculative developments launched earlier may take longer to fill.

Developers delivered nearly 80,000 square metres of new facilities in the second quarter, concentrated largely in western Slovakia. Another 300,000 square metres remains on the way, including notable schemes in eastern parts of the country, where manufacturers are expanding production.

Rental dynamics reflect the growing competition among landlords. Prime logistics rents have edged down slightly to around €5.50 per square metre per month, while in neighbouring Czech cities headline levels remain higher, and in Poland and Hungary owners are increasingly granting concessions to secure occupiers.

A clear shift is also visible in the quality of space being demanded. Warehouses equipped for automation, energy-efficient operations and certified under sustainability standards are quickly becoming the benchmark across Central Europe, and Slovakia is no exception. Tenants now expect smart systems and low operating costs as standard, while investors place increasing weight on environmental credentials.

Although the overall outlook remains positive, with new manufacturers such as Volvo moving into the market and nearshoring trends favouring Central Europe, geopolitical uncertainty and global trade tensions are tempering optimism. Analysts expect the remainder of 2025 to bring gradual stabilisation, with tenants benefiting from greater choice and landlords under pressure to deliver modern, flexible and sustainable facilities.

Source: comp.

BHM Group Acquires Six Renovated Apartment Buildings in Prague

Investment company BHM Group has purchased six fully refurbished apartment buildings in Prague from Zeitgeist Asset Management, in a deal arranged exclusively by consultancy Charles Irvine.

The portfolio comprises 94 residential units and five commercial spaces with a combined floor area of around 7,500 square metres. The properties are located in central districts 1, 2 and 5 and were fully occupied at the time of the transaction. All had been modernised in recent years under Zeitgeist’s management.

Zeitgeist described the sale as consistent with its long-term investment strategy and noted that it will continue to oversee the management of the properties on behalf of the new owner. BHM Group highlighted the appeal of the buildings’ technical condition and central locations, while Charles Irvine underlined that high-quality residential assets in prime Prague districts remain in strong demand from investors.

Historic Šumava Site Offered to Investors in Czechia

A large tract of land in the central Šumava Mountains is being offered to investors, opening the door to one of the most ambitious development opportunities in the region in recent years.

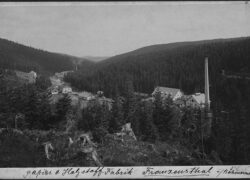
The property, known locally as Františkov, stretches across almost 38,000 square metres between Kvilda and Borová Lada. Once home to a 19th-century paper factory, the area also carries a more complex history: wartime accounts suggest that underground workshops may have been used to produce parts for German aircraft during the Second World War. The factory buildings were torn down in the 1950s, but remnants of cellars and waterways remain visible in the landscape today.

The current owner has put the land on the market and entrusted Prague-based auction house GAVLAS with managing the sale. A development concept prepared by ATELIER SAEM is included in the package. The plans envision a small residential quarter of 74 flats combined with cultural and community elements, including a museum recalling the paper mill’s heritage, a small brewery and dining space, as well as landscaped public areas. The proposals emphasize that any new construction should be discreetly integrated into the surroundings, with underground parking and careful attention to environmental standards.

Out of the nearly 38,000 square metres, about 12,000 are classified as buildable, situated within the cultural zone of Šumava National Park. Utility connections are already in place, including power lines and a wastewater treatment facility, and water can be sourced on site. The land is situated outside identified flood areas.

The seller has presented the site as one of the most significant parcels in the central Šumava available for new use, offering both natural beauty and a strong historical identity. For prospective buyers, it represents a rare chance to combine housing, culture and tourism in one of the Czech Republic’s most protected landscapes.

Is Poland’s Housing Market Slowing?

Poland’s residential sector is showing signs of strain, with fewer flats under construction, a sharp drop in building permits and the lowest number of completions since 2018. These trends suggest developers are rethinking investment plans and adapting strategies to a more cautious market environment.

Tomasz Kaleta, Managing Director of Sales and Marketing at Develia
Despite the record-high supply, we are not significantly changing our plans to launch new projects in the cities where we operate. This is particularly true given that in July this year we finalised the acquisition of Bouygues Immobilier Polska, which allowed us to increase both the number of flats under construction and the potential of our land bank – primarily in Warsaw, which is the largest and most stable market in Poland, as well as in Poznań and Wrocław. In line with our strategy, we assume a gradual increase in market share so that in 2028 we will achieve our sales target of 4,500 flats per year.

Well-designed investments in attractive locations, even in a challenging market environment, maintain a high level of demand, which is reflected in our sales results in recent months. The main area of our activity remains the sale of flats to individual customers. As part of our diversification, we are gradually acquiring new competences in the living sector. We are currently awaiting a building permit for a student residence in Wrocław in a joint venture formula. We have also acquired another plot of land in the centre of Wrocław, where we plan to build a facility for students comprising approximately 600 flats and commercial premises. In our opinion, the PBSA (Purpose Built Student Accommodation) segment has great growth potential in Poland.

Andrzej Gutowski, Sales Director, Ronson Development
It comes as no surprise that developers are adjusting their production to much lower demand. The housing market in Poland is currently slowing down, as signs of a slowdown have been visible for some time. There was a time when the market was deluded by the rapid introduction of housing programmes and faster interest rate cuts. This caused developers to increase supply beyond real demand. Currently, the situation has stabilised and the market has entered a phase of equilibrium at a lower level than in previous years.

Looking ahead to the next two years, we expect a return to the boom of 2021 or 2023. This naturally influences our strategy. We are making investments more cautiously, in a more selective manner and in line with real demand. We treat this period as a time of stabilisation, during which we can prepare for future growth impulses, such as potential interest rate cuts.

Our strategy is based primarily on stable growth, adjusting the pace of investment to the market situation and closely monitoring the decisions of the Monetary Policy Council, which will have a key impact on the further dynamics of the market. We see this period as a time of stabilisation with slight optimism rather than a sharp slowdown in the industry.

Mirosław Bednarek, Regional Business Director, President of the Management Board of Matexi Polska
We are seeing a gradual recovery in demand in the property development market. In the second quarter of this year, we observed a clear increase in customer activity. This was not only due to the first interest rate cut, but also to the fact that some buyers stopped postponing their purchasing decisions in anticipation of a new government programme. From April to June, we concluded a total of 99 development agreements, which represents an increase of nearly 40 per cent compared to both the first quarter of 2025 and the same period last year. According to preliminary sales data, we expect further improvement in results in the third quarter as well.
The consistent expansion of our offer with new projects also contributes to the increase in sales. We have recently launched two investments – Sady Żoliborz II at the intersection of Anny German and Zygmunta Krasińskiego Streets in Warsaw, where 66 flats are being built, and Bukowińska Mokotów in Warsaw’s Mokotów district, comprising 72 flats and two commercial premises. At the beginning of next year, we also plan to launch further investments, one in Krakow and two in Warsaw.

Thanks to growing customer interest and the planned launch of new projects, we are not limiting our investment activity and are constantly looking for attractive plots of land. However, it is worth noting that it often takes several years to obtain a building permit, and during this time, unforeseen circumstances may arise that could further prolong the process.

Joanna Chojecka, Sales and Marketing Director for Warsaw and Wrocław at the Robyg Group
Although statistics for the first months of 2025 indicate a certain slowdown in the number of investments started or building permits obtained, we do not see this as a permanent weakening of the housing market, but rather as a natural correction after a period of very dynamic growth. The market remains active, and demand for new flats, especially in large cities, remains high, due to strong housing needs, internal migration and the growing importance of renting, among other factors.

We are approaching this situation strategically, but we are not slowing down. We are maintaining high sales dynamics and actively introducing new projects to our offer, both in the largest agglomerations and in developing markets. Despite the more challenging economic environment, demand for flats remains stable, and our recognisable locations, competitive offer and quality of workmanship continue to attract customers.
We are seeing stable, high sales levels. Customers are active, and our wide range of products, flexible approach and attractive locations mean that we are enjoying considerable interest. Our strategy is to continue growing, both in the residential sales segment and in the PRS model, which allows us to respond flexibly to changing market needs.

We are optimistic about the second half of the year and the coming years. We expect demand to remain strong as interest rates continue to stabilise and mortgage lending becomes more accessible. We are well prepared to continue our operations – we have secured a land bank, ready-to-go projects and a highly experienced team. For us, the current situation is primarily an opportunity to further strengthen our market position and grow for the benefit of both customers and investors.

We do not plan to limit our activities – on the contrary, we are consistently implementing our development strategy and exploiting the market potential where there is still a real demand for housing. It is crucial for us to remain flexible and quickly adapt the structure of our offer to current customer expectations and market conditions. We monitor the situation on an ongoing basis, ensuring the appropriate pace of investment implementation and a safe level of capital commitment.

Damian Tomasik, President of the Management Board of Alter Investment
We are observing a slowdown in the housing market, especially in terms of the number of new building permits. Due to high interest rates, the supply of new investments is adjusting to demand. For Alter Investment, however, this does not mean a slowdown in activity, but a smarter selection of projects. We specialise in land preparation and refinement, which is why in the current environment we are focusing on investments with the highest potential and shorter time to obtain administrative decisions. At the same time, we are developing new locations and segments, both residential and single-family housing or PRS, which allows us to diversify our activities and flexibly adapt our strategy to changing market conditions.

Renata Mc Cabe-Kudla, Country Manager at Grupo Lar Polska
The housing market in Poland, particularly in Warsaw, is growing more slowly than in previous years due to a significant increase in the time taken to process applications by the authorities. We assume that the slowdown is temporary.

Piotr Ludwiński, Sales Director at Archicom
In my opinion, the residential market in Poland is not slowing down, but stabilising after a very intense period related, among other things, to the 2% Safe Credit programme. We continue to see stable demand and high customer activity, and our investments, carefully designed and diversified in terms of size, meet the needs of singles, families and those buying premises for investment purposes.

At the same time, we are not reducing our investment activity. On the contrary, we have an extensive land bank and are consistently developing our operations in the residential segment. The sale of the City2 office building has allowed us to focus 100% on this area. In this respect, we are diversifying our offer, from popular segment flats, through investment projects, to city-forming ‘destination’ projects such as Fuzja, Wita and Towarowa 22.
In the coming years, we plan to launch attractive projects in the largest Polish cities, while at the same time developing investments under the so-called lex deweloper (developer law) in Wrocław and Warsaw.

Source: dompress.pl
Image: WARYNSKI-STACJA LIGOCKA

Is Poland’s Housing Market Slowing?

Poland’s residential sector is showing signs of strain, with fewer flats under construction, a sharp drop in building permits and the lowest number of completions since 2018. These trends suggest developers are rethinking investment plans and adapting strategies to a more cautious market environment.

Tomasz Kaleta, Managing Director of Sales and Marketing at Develia
Despite the record-high supply, we are not significantly changing our plans to launch new projects in the cities where we operate. This is particularly true given that in July this year we finalised the acquisition of Bouygues Immobilier Polska, which allowed us to increase both the number of flats under construction and the potential of our land bank – primarily in Warsaw, which is the largest and most stable market in Poland, as well as in Poznań and Wrocław. In line with our strategy, we assume a gradual increase in market share so that in 2028 we will achieve our sales target of 4,500 flats per year.

Well-designed investments in attractive locations, even in a challenging market environment, maintain a high level of demand, which is reflected in our sales results in recent months. The main area of our activity remains the sale of flats to individual customers. As part of our diversification, we are gradually acquiring new competences in the living sector. We are currently awaiting a building permit for a student residence in Wrocław in a joint venture formula. We have also acquired another plot of land in the centre of Wrocław, where we plan to build a facility for students comprising approximately 600 flats and commercial premises. In our opinion, the PBSA (Purpose Built Student Accommodation) segment has great growth potential in Poland.

Andrzej Gutowski, Sales Director, Ronson Development
It comes as no surprise that developers are adjusting their production to much lower demand. The housing market in Poland is currently slowing down, as signs of a slowdown have been visible for some time. There was a time when the market was deluded by the rapid introduction of housing programmes and faster interest rate cuts. This caused developers to increase supply beyond real demand. Currently, the situation has stabilised and the market has entered a phase of equilibrium at a lower level than in previous years.

Looking ahead to the next two years, we expect a return to the boom of 2021 or 2023. This naturally influences our strategy. We are making investments more cautiously, in a more selective manner and in line with real demand. We treat this period as a time of stabilisation, during which we can prepare for future growth impulses, such as potential interest rate cuts.

Our strategy is based primarily on stable growth, adjusting the pace of investment to the market situation and closely monitoring the decisions of the Monetary Policy Council, which will have a key impact on the further dynamics of the market. We see this period as a time of stabilisation with slight optimism rather than a sharp slowdown in the industry.

Mirosław Bednarek, Regional Business Director, President of the Management Board of Matexi Polska
We are seeing a gradual recovery in demand in the property development market. In the second quarter of this year, we observed a clear increase in customer activity. This was not only due to the first interest rate cut, but also to the fact that some buyers stopped postponing their purchasing decisions in anticipation of a new government programme. From April to June, we concluded a total of 99 development agreements, which represents an increase of nearly 40 per cent compared to both the first quarter of 2025 and the same period last year. According to preliminary sales data, we expect further improvement in results in the third quarter as well.
The consistent expansion of our offer with new projects also contributes to the increase in sales. We have recently launched two investments – Sady Żoliborz II at the intersection of Anny German and Zygmunta Krasińskiego Streets in Warsaw, where 66 flats are being built, and Bukowińska Mokotów in Warsaw’s Mokotów district, comprising 72 flats and two commercial premises. At the beginning of next year, we also plan to launch further investments, one in Krakow and two in Warsaw.

Thanks to growing customer interest and the planned launch of new projects, we are not limiting our investment activity and are constantly looking for attractive plots of land. However, it is worth noting that it often takes several years to obtain a building permit, and during this time, unforeseen circumstances may arise that could further prolong the process.

Joanna Chojecka, Sales and Marketing Director for Warsaw and Wrocław at the Robyg Group
Although statistics for the first months of 2025 indicate a certain slowdown in the number of investments started or building permits obtained, we do not see this as a permanent weakening of the housing market, but rather as a natural correction after a period of very dynamic growth. The market remains active, and demand for new flats, especially in large cities, remains high, due to strong housing needs, internal migration and the growing importance of renting, among other factors.

We are approaching this situation strategically, but we are not slowing down. We are maintaining high sales dynamics and actively introducing new projects to our offer, both in the largest agglomerations and in developing markets. Despite the more challenging economic environment, demand for flats remains stable, and our recognisable locations, competitive offer and quality of workmanship continue to attract customers.
We are seeing stable, high sales levels. Customers are active, and our wide range of products, flexible approach and attractive locations mean that we are enjoying considerable interest. Our strategy is to continue growing, both in the residential sales segment and in the PRS model, which allows us to respond flexibly to changing market needs.

We are optimistic about the second half of the year and the coming years. We expect demand to remain strong as interest rates continue to stabilise and mortgage lending becomes more accessible. We are well prepared to continue our operations – we have secured a land bank, ready-to-go projects and a highly experienced team. For us, the current situation is primarily an opportunity to further strengthen our market position and grow for the benefit of both customers and investors.

We do not plan to limit our activities – on the contrary, we are consistently implementing our development strategy and exploiting the market potential where there is still a real demand for housing. It is crucial for us to remain flexible and quickly adapt the structure of our offer to current customer expectations and market conditions. We monitor the situation on an ongoing basis, ensuring the appropriate pace of investment implementation and a safe level of capital commitment.

Damian Tomasik, President of the Management Board of Alter Investment
We are observing a slowdown in the housing market, especially in terms of the number of new building permits. Due to high interest rates, the supply of new investments is adjusting to demand. For Alter Investment, however, this does not mean a slowdown in activity, but a smarter selection of projects. We specialise in land preparation and refinement, which is why in the current environment we are focusing on investments with the highest potential and shorter time to obtain administrative decisions. At the same time, we are developing new locations and segments, both residential and single-family housing or PRS, which allows us to diversify our activities and flexibly adapt our strategy to changing market conditions.

Renata Mc Cabe-Kudla, Country Manager at Grupo Lar Polska
The housing market in Poland, particularly in Warsaw, is growing more slowly than in previous years due to a significant increase in the time taken to process applications by the authorities. We assume that the slowdown is temporary.

Piotr Ludwiński, Sales Director at Archicom
In my opinion, the residential market in Poland is not slowing down, but stabilising after a very intense period related, among other things, to the 2% Safe Credit programme. We continue to see stable demand and high customer activity, and our investments, carefully designed and diversified in terms of size, meet the needs of singles, families and those buying premises for investment purposes.

At the same time, we are not reducing our investment activity. On the contrary, we have an extensive land bank and are consistently developing our operations in the residential segment. The sale of the City2 office building has allowed us to focus 100% on this area. In this respect, we are diversifying our offer, from popular segment flats, through investment projects, to city-forming ‘destination’ projects such as Fuzja, Wita and Towarowa 22.
In the coming years, we plan to launch attractive projects in the largest Polish cities, while at the same time developing investments under the so-called lex deweloper (developer law) in Wrocław and Warsaw.

Source: dompress.pl
Image: WARYNSKI-STACJA LIGOCKA

WDP Strengthens Romanian Portfolio as Strategic Hub for Central and Eastern Europe

With nearly 2 million square metres of logistics space in Romania, WDP has positioned its local operations as a cornerstone of its Central and Eastern European strategy. In an interview with CIJ EUROPE, Business Development Manager Gijs Klomp explained how Romania fits into WDP’s expansion plans, the role of nearshoring, and how sustainability is shaping tenant requirements – while new projects highlight the scale of the company’s ambitions.

At the start of 2026, WDP will launch construction of a 54,000 sqm distribution center at WDP Park Bucharest – Ștefănești, developed for international non-food discounter Action. The project, located on a 15-hectare site with future expansion potential, represents an investment of around €40 million and will be delivered by the end of 2026. The long-term lease, reportedly running for at least 15 years, underscores both Action’s confidence in the Romanian market and WDP’s ability to secure large-scale, sustainable pre-let projects.

“This is exactly the kind of deal that shows why Romania remains such a priority for us,” Klomp noted. “It combines a top-tier international tenant with a sustainable, tailor-made facility. It strengthens both our portfolio and Romania’s role as a regional logistics hub.”

Beyond Bucharest, WDP is also highlighting the strategic importance of the Constanța region, where WDP Park Constanța – Lazu offers direct rail access and possibilities for a multimodal terminal connecting to the Black Sea port. The platform, marketed as offering “almost endless logistics possibilities,” is seen as a gateway for occupiers dependent on import/export flows, especially those serving Southeastern Europe. “Constanța is unique,” Klomp explained. “It’s not only about serving Romania but also about being plugged into international supply chains via the port. That’s why the site has such potential.”

Romania has become WDP’s third-largest portfolio after the Netherlands, followed by Belgium, with strong growth in France and Germany. Klomp acknowledged that WDP has considered expansion into other Central European countries, but remains focused on Romania. “Unlike other CEE countries, Romania offers the ideal combination of scale, strategic location, and growth potential that makes it an attractive focus market for us. Over the long term, we see Romania not just as a national market, but increasingly as a logistics hub that connects Western Europe with Southeastern Europe. Strengthening our presence here is therefore a key part of WDP’s broader European growth strategy.” he said.

On the demand side, Klomp pointed to the reconfiguration of supply chains in the wake of COVID-19, trade tensions, and geopolitical risk. “There are several factors influencing demand: on one hand, Western companies want production closer to consumers and are still looking for cost savings through Central and Eastern Europe, which creates the ideal terrain for nearshoring. On the other hand, in the current macroeconomic context, Asian manufacturers want an EU base to hedge tariffs.. Romania, with its EU membership and competitive cost base, benefits from all three,” he explained. However, he cautioned that such transformations take time.

Sustainability remains central to WDP’s strategy. Rooftop photovoltaic panels, energy-efficient warehouses, and advanced systems are becoming standard, with the Action facility targeting BREEAM Outstanding certification. “That’s what we want to do because it’s the right thing, and also, that’s what clients and EU legislation require us to do,” Klomp said. While multinational tenants are generally ahead in setting ESG goals, he stressed WDP applies the same standards across all markets.

Asked about competition, Klomp pointed to North Africa as emerging rivals. “Morocco, for example, has become a competitor thanks to favourable EU trade agreements and established automotive clusters. For low value-added manufacturing, Romania is no longer as competitive as it once was,” he said.

Domestically, infrastructure and regulatory volatility remain the main risks. “Investors value predictability above all. Romania used to have a strong reputation for fiscal stability, but recent tax debates have created uncertainty,” Klomp observed. “Infrastructure has improved, but clients often discount official timelines, therefore thecontinuity of investment in infrastructure is critical.”

Agriculture highlights Romania’s paradox as a major crop producer but net importer of food. “We remain the largest landlord for food retailers in Romania, but agro-industrial infrastructure, such as silos, temperature-controlled warehouses, is missing. Building that would allow value to be added locally rather than exporting raw materials,” Klomp said, adding that WDP is open to such projects if strong partners are secured.

Reflecting on WDP’s evolution, Klomp pointed to its flexible mix of development and acquisition strategies. “We’ve gone from fewer than 100 tenants to more than 600 today. Sale-and-leasebacks, multi-tenant assets, and tailored build-to-suit facilities have diversified the portfolio and deepened client relationships.”

With Action’s new hub in Ștefănești and the ongoing development of Constanța–Lazu, WDP is reinforcing Romania as both a logistics base and a testing ground for innovation. “Romania remains one of our biggest opportunities,” Klomp concluded. “We are certainly committed to deepening our presence here before considering broader regional expansion.”

© 2025 www.cijeurope.com

Romania’s Housing Market Faces Segmentation, Supply Pressures, and Mortgage Constraints in H2 2025

Romania’s residential real estate market continues to show resilience despite affordability challenges and uneven supply. In a Q&A with CIJ EUROPE, Dan Voiculescu, Broker/Owner at RE/MAX Innovaton, shared his perspective on pricing trends, demand segmentation, and the forces shaping the outlook for the remainder of 2025.

Voiculescu expects moderate price growth in the country’s major urban centres, though not evenly distributed. Citing August 2025 data from Imobiliare.ro, he notes that average asking prices reached approximately €2,630 per square metre in Bucharest, €3,260 in Cluj, €1,640 in Timișoara and €1,550 in Iași. Year-on-year, that translates into increases of 6 percent in Bucharest, 3 percent in Cluj, 5 percent in Timișoara and 4 percent in Iași. “For the second half of the year, I see Bucharest and Timișoara continuing with three to five percent nominal growth, Cluj remaining flat to slightly positive, and Iași advancing by two to four percent,” he explains. Inflation, which still stands at 5.6 percent according to the national statistics office, remains a key driver, while the National Bank of Romania’s decision to hold its key policy rate at 6.75 percent means affordability will remain under pressure.

Demand patterns are shifting as well. “First-time buyers are clearly the most affected by financing conditions,” Voiculescu observes. “The high down payment requirements and elevated instalments limit access to mortgages.” He points to ANCPI’s August data showing around 4,500 transactions in Bucharest, up 15 percent from last year, but emphasises that growth is concentrated among mid- and upper-market buyers. In contrast, investors are making a cautious return, particularly in Iași and Timișoara, where gross rental yields of 6 to 6.5 percent are more attractive than the 4 to 4.5 percent available in Bucharest and Cluj. “Investors often come with liquidity, so they are less exposed to lending costs,” he adds. End-users, especially families upgrading their homes, remain the most stable group, supporting transactions in the €120,000 to €180,000 bracket in Bucharest and Cluj.

The mortgage market continues to exert a strong influence. According to Voiculescu, average annual interest rates on 30-year fixed loans remain between 7.5 and 8.2 percent, keeping borrowing costs high. “Banks are still very cautious, with strict eligibility criteria, and household incomes, even growing at about ten percent annually, are not keeping up with rising housing costs,” he says. He believes that a modest cut in the central bank’s policy rate later this year could improve affordability slightly, but cautions against expecting a strong rebound. “What we may see is a slow stabilization of mortgage-driven demand, not a spectacular recovery.”

Supply constraints remain an issue. ANCPI reported about 52,000 residential building permits nationwide in the first eight months of 2025, eight percent fewer than in the same period last year. “Permitting in Bucharest and Ilfov can still take up to two years, and developers are facing higher costs for materials such as steel and concrete, as well as labour shortages, particularly in Cluj and Bucharest,” Voiculescu explains. He estimates that actual deliveries in 2025 will be between 65,000 and 70,000 units nationwide, falling short of demand, which he puts closer to 80,000. “This gap will continue to sustain price pressure in the mid and upper-mid segments.”

Voiculescu also stresses the importance of looking beyond prices and volumes to understand the market’s underlying strength. “Days on market have risen to 45 to 60 days for centrally located properties in Bucharest, compared to 30 to 40 a year ago, while in peripheral projects sales can take more than 90 days. Absorption remains strong in premium projects in the north of Bucharest and in central Cluj, but weak in poorly connected areas.” Rental yields, he notes, are stabilising at 4.5 percent in Bucharest, 3.8 to 4.2 percent in Cluj, and higher at 6 to 6.5 percent in Timișoara and Iași. Vacancy rates remain under five percent in core urban areas but exceed 12 percent in peripheral or oversized developments.

“The Romanian residential market remains stable but segmented,” he concludes. “Strength lies in well-located and higher-quality projects, while vulnerabilities are concentrated in peripheral, delayed, or under-specified developments. Buyers and investors will need to be more selective, and developers must adapt to the realities of costs, financing, and consumer expectations.”

© 2025 www.cijeurope.com

Romania’s Housing Market Faces Segmentation, Supply Pressures, and Mortgage Constraints in H2 2025

Romania’s residential real estate market continues to show resilience despite affordability challenges and uneven supply. In a Q&A with CIJ EUROPE, Dan Voiculescu, Broker/Owner at RE/MAX Innovaton, shared his perspective on pricing trends, demand segmentation, and the forces shaping the outlook for the remainder of 2025.

Voiculescu expects moderate price growth in the country’s major urban centres, though not evenly distributed. Citing August 2025 data from Imobiliare.ro, he notes that average asking prices reached approximately €2,630 per square metre in Bucharest, €3,260 in Cluj, €1,640 in Timișoara and €1,550 in Iași. Year-on-year, that translates into increases of 6 percent in Bucharest, 3 percent in Cluj, 5 percent in Timișoara and 4 percent in Iași. “For the second half of the year, I see Bucharest and Timișoara continuing with three to five percent nominal growth, Cluj remaining flat to slightly positive, and Iași advancing by two to four percent,” he explains. Inflation, which still stands at 5.6 percent according to the national statistics office, remains a key driver, while the National Bank of Romania’s decision to hold its key policy rate at 6.75 percent means affordability will remain under pressure.

Demand patterns are shifting as well. “First-time buyers are clearly the most affected by financing conditions,” Voiculescu observes. “The high down payment requirements and elevated instalments limit access to mortgages.” He points to ANCPI’s August data showing around 4,500 transactions in Bucharest, up 15 percent from last year, but emphasises that growth is concentrated among mid- and upper-market buyers. In contrast, investors are making a cautious return, particularly in Iași and Timișoara, where gross rental yields of 6 to 6.5 percent are more attractive than the 4 to 4.5 percent available in Bucharest and Cluj. “Investors often come with liquidity, so they are less exposed to lending costs,” he adds. End-users, especially families upgrading their homes, remain the most stable group, supporting transactions in the €120,000 to €180,000 bracket in Bucharest and Cluj.

The mortgage market continues to exert a strong influence. According to Voiculescu, average annual interest rates on 30-year fixed loans remain between 7.5 and 8.2 percent, keeping borrowing costs high. “Banks are still very cautious, with strict eligibility criteria, and household incomes, even growing at about ten percent annually, are not keeping up with rising housing costs,” he says. He believes that a modest cut in the central bank’s policy rate later this year could improve affordability slightly, but cautions against expecting a strong rebound. “What we may see is a slow stabilization of mortgage-driven demand, not a spectacular recovery.”

Supply constraints remain an issue. ANCPI reported about 52,000 residential building permits nationwide in the first eight months of 2025, eight percent fewer than in the same period last year. “Permitting in Bucharest and Ilfov can still take up to two years, and developers are facing higher costs for materials such as steel and concrete, as well as labour shortages, particularly in Cluj and Bucharest,” Voiculescu explains. He estimates that actual deliveries in 2025 will be between 65,000 and 70,000 units nationwide, falling short of demand, which he puts closer to 80,000. “This gap will continue to sustain price pressure in the mid and upper-mid segments.”

Voiculescu also stresses the importance of looking beyond prices and volumes to understand the market’s underlying strength. “Days on market have risen to 45 to 60 days for centrally located properties in Bucharest, compared to 30 to 40 a year ago, while in peripheral projects sales can take more than 90 days. Absorption remains strong in premium projects in the north of Bucharest and in central Cluj, but weak in poorly connected areas.” Rental yields, he notes, are stabilising at 4.5 percent in Bucharest, 3.8 to 4.2 percent in Cluj, and higher at 6 to 6.5 percent in Timișoara and Iași. Vacancy rates remain under five percent in core urban areas but exceed 12 percent in peripheral or oversized developments.

“The Romanian residential market remains stable but segmented,” he concludes. “Strength lies in well-located and higher-quality projects, while vulnerabilities are concentrated in peripheral, delayed, or under-specified developments. Buyers and investors will need to be more selective, and developers must adapt to the realities of costs, financing, and consumer expectations.”

© 2025 www.cijeurope.com

front page info
LATEST NEWS