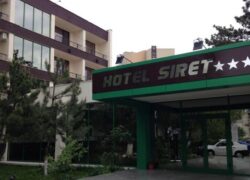
THR Marea Neagră sells Siret Hotel for EUR 3.5 million

THR Marea Neagră SA has finalized the sale of the Siret Hotel Complex in the Saturn resort for EUR 3.5 million plus VAT. The transaction  marks the conclusion of a public auction procedure launched at the beginning of this year and the consolidation of the company’s liquidity through the full collection of the price.


This represents the company’s second major asset sale in the recent period, after the Măgura Hotel Complex in Eforie Sud was sold in April 2026 for EUR 2.5 million.


THR Marea Neagră SA, headquartered in Eforie Nord, is 75.34% controlled by Transilvania Investments Alliance SA. According to the financial data for 2024, the company reported a turnover of approximately EUR 3.09 million and a net profit of EUR 1.87 million, while total liabilities amounted to EUR 7.16 million.


CPI Property Group secures EUR 100 mln Financing for Sun Plaza shopping center

CPI Property Group announces that its subsidiary, CPI Europe AG, has successfully closed a new EUR 100 million financing for Sun Plaza shopping center. The financing was in the form of a club-deal from OTP Bank and ING Bank Romania, with each bank participating with equal commitments. The transaction also marks the beginning of a new cooperative relationship between CPIPG and ING Bank.


Inaugurated in 2010, Sun Plaza brings together 170 retail, HoReCa and entertainment concepts with a gross leasable area of ​​approximately 81,000 sq m. The center benefits from direct access to the Piața Sudului metro station and is BREEAM Excellent certified.


“This transaction demonstrates the continued confidence of the financiers in the premium retail assets in the CEE region. We appreciate the professional and constructive cooperation of OTP Bank and ING throughout the entire process and are particularly pleased that ING becomes a new partner of the Group,” said  Marketa Vecerova, Group Head of Real Estate Financing at CPI Property Group


Dentons acted as legal advisor to the financiers in the transaction.

Analysis: Falling Mortgage Rates Push Monthly Repayments Below Average Rent in Bucharest

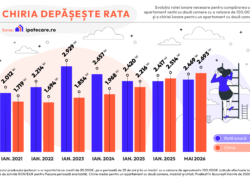
Falling mortgage rates in Romania have pushed the monthly repayment required to purchase a mass-market apartment in Bucharest below the average asking rent for a comparable property, according to an analysis by online mortgage broker  Ipotecare.ro based on banking and residential market data.

The analysis shows that the average monthly repayment for an EUR 85,000 mortgage over 25 years, calculated at a fixed interest rate of 4.55% per annum, stood at approximately RON 2,469 in May. The loan scenario reflects the purchase of a mass-market one-bedroom apartment in Bucharest valued at EUR 100,000, built before 2000, assuming a standard down payment and current exchange rate levels.

The monthly repayment is only RON 49 higher than at the beginning of last year, despite the National Bank of Romania maintaining its benchmark interest rate at 6.50%.

By comparison, the average asking rent for a furnished and fully equipped one-bedroom apartment of the same category reached RON 2,693 per month in May, equivalent to around EUR 517. According to the analysis, this places average asking rents approximately 9% above the monthly mortgage instalment required to purchase a comparable property through bank financing.

Rental prices have also continued to increase throughout the year. Average asking rents were approximately 7% higher than at the start of 2026 and around 21.5% above the levels recorded at the beginning of 2025, with exchange rate movements also contributing to the increase.

“The most competitive mortgage offers currently available are almost 2.5 percentage points below the peak recorded three years ago. Financial institutions are working to keep borrowing attractive, and the current 4.55% rate on the best offers is significantly below the 6.50% monetary policy rate,” said Laurentiu Bogdan, Managing Partner of Ipotecare.ro.

Even so, mortgage financing costs remain above the lows recorded during the pandemic period. The best mortgage rates currently available are still around 1.2 percentage points higher than the market low seen at the beginning of 2021, when leading mortgage products were priced at approximately 3.23%.

The analysis also highlights the growing gap between income growth and housing costs in Bucharest. While the average monthly repayment required to purchase a mass-market one-bedroom apartment has increased by approximately 22% since 2021, average wages in the capital have risen considerably faster.

According to data from the  National Institute of Statistics Romania, the average net salary in Bucharest reached RON 7,173 in February 2026, compared with RON 4,313 in February 2021, representing an increase of roughly 66% over the period.

At the same time, the average asking rent for a furnished and fully equipped one-bedroom apartment in Bucharest completed before 2000 has increased by approximately 46% since 2021, reflecting continued pressure on the city’s rental market.

CEDER 2026 in review: The New Meaning of Luxury: A Shift To A Way of Living

The first Residential panel held at CEDER 2026 showed that the definition of luxury in Romania’s evolving residential market is undergoing an essential transformation. While premium real estate was once defined by prestigious addresses and expensive materials alone, the experts invited to take part in the panel suggest that the market has matured, shifting the focus toward personal well-being, time efficiency, and integrated communities.


Jan Demeyere, Architect and Co-founder of SPEEDWELL, emphasizes that luxury has moved beyond mere aesthetics, like marble or wood finishes. He argues that true luxury is now defined by the quality of one’s daily life, stating: “When we talk about luxury, that’s something very personal. How do you define luxury? What is luxury living? … For me, luxury really is being able to find a job very close to where you are, even change jobs, is to be able not to commute for 3, 4, 6 hours to your job, so you still have free time with your family, with your friends. That’s very important. And also, to have access to nature. That’s for me, luxury.”


This sentiment is echoed by marketing experts who see luxury as “an emotional purchase” rather than a simple acquisition of property. Andreea Dumitru, Chief Marketing Officer at Hagag Development Europe, explains that modern buyers are highly informed and travelled, seeking a an experience that validates their status: “People are not just buying square meters of an apartment… They are looking to buy something that elevates their lifestyle. So, they look for [a] curated experience, they look for floor to ceiling heights, they look for privacy, for wellness, and all these services that they didn’t have until now.”


A critical component of this redefinition is the concept of “buying time.” Irina Caraene of CORDIA notes that for clients with budgets exceeding €200,000, the priority is “complete urban living without compromises”. This often manifests in the “15-minute city” concept, where amenities like work hubs, gastro bars, and playgrounds are all within immediate reach.


Ultimately, the dividing line between upper-middle and genuine premium residential property is no longer just price or location, but the “depth of the product”. As Răzvan Brasla, CEO of Cloud9 Residence, puts it: “The upper mid products, they are selling good homes, and the premium developers are selling a way of living”.


In conclusion, the panelists agreed that nowadays, luxury is less about what a building looks like and more about the ecosystem it provides for a healthy, efficient, and connected life.

CEDER 2026 in review: Key Differentiators for Office Development in the Next 24 Months

Industry experts participanting in the second Office panel held at CEDER 2026 suggest that successful projects in the future 12- to 24-month timeframe will be defined by their ability to integrate technology, ensure deliverability, and prioritize the human experience over mere square footage.


According to Antoniu Panait, Managing Director of Vastint Romania, the rapid pace of technological evolution is now a fundamental divider. He argues that staying ahead of the curve on sustainability is no longer optional but a primary competitive advantage: “Evolution of technology in the last years, it’s exponential, it’s mind blowing how quickly it evolves everything and it starts to be applicable also in real estate. I think it’s all about getting as soon as possible carbon neutral, Paris-proof, and implementing as quick as possible new technologies. (…) I think this will be the differentiator between the old buildings and the new buildings”.


Practical execution is the second major differentiator. Bogdan Mărginean, Technical Subdivision Manager at Strabag, notes that the market is moving away from being impressed by “theoretical” beauty. Success will instead go to developers who can guarantee that a project is viable and sustainable in the long term: “I’m absolutely sure nobody or the market will (…) reward renderings, very attractive renderings. It will reward performance and performance from the predictive delivery of the project, first of all, of efficient leasing and sustainable operation”.


Dan Ungureanu of Renomia Gallagher emphasizes that mature risk management is what will attract cautious lenders. He suggests that the projects that move forward will be those led by teams that “have a very open mindset” and “a mature way of thinking”.


Finally, Florian Nițu, Managing Partner at Popovici, Nițu, Stoica & Asociații, points out that the most successful projects will treat office space as a service designed to foster employee happiness. He observes: “The most important element is that [of] office as a service, that delivers the so-called occupier wellbeing. And by occupier wellbeing you mean the happiness of the employees and partners of your tenant. If that’s in and if that wellbeing is combined with higher ethics, social responsibility undertakings (…) I’m absolutely convinced that this will be the successful project”.


Ultimately, the projects that succeed in the coming years will be those that transition from providing a commodity to delivering a high-performance, ethically grounded product.

CEDER 2026 in review: Navigating Legal and Practical Frictions

One of the conclusions of the second Office panel held at CEDER 2026 was that the office development landscape is undergoing a fundamental shift, moving away from simple space-leasing models towards complex, service-oriented environments. This transition introduces significant legal and practical frictions.


According to Florian Nițu, Managing Partner at Popovici, Nițu, Stoica & Asociații, the success of mixed-use projects has made legal iterations far more intricate. He notes that the traditional “triple net” lease is a concept of the past, replaced by complex partnerships. Nițu explains: “In legal terms, successful as mixed means complex from a legal standpoint, because the benefits of a mixed-use project translate into complex obligations and complex legal iterations in the contracts that are signed. Office space means a lease agreement that is doubled by a service agreement”. Furthermore, permitting remains a primary friction point, particularly in markets like Bucharest. Nițu advocates for a “strong, firm” stance toward authorities, including using judicial instruments when necessary to push developments forward.


On the practical side, the industry faces a “structural problem” regarding project delivery. Bogdan Mărginean, Technical Subdivision Manager at Strabag, argues that developers often focus too much on optimistic renderings and not enough on the viability of execution. He highlights the friction caused by treating construction as a “downstream activity” rather than an integrated part of the design process from the start: “The biggest risk is not if we are able to design attractive buildings, office buildings. The biggest risk is if this project is really deliverable, it is financially deliverable, technically, operationally and within the expected time… Too often projects are designed in isolation, are optimized only on paper, from theoretical point of view and only afterwards tested if the market is taking them on. On execution capacity, procurement constraints… this will create by default (…) loops in redesign, additional cost, additional time”.


Adding to these frictions is a lack of economic visibility. Antoniu Panait, Managing Director of Vastint Romania, emphasizes that developers must be prudent because they cannot “foresee what will happen in the next few weeks, not next few years” regarding interest rates or taxes.


As highlighted by Dan Ungureanu, Business Development Leader CEE & CIS at RENOMIA Gallagher, this uncertainty is mirrored in the insurance sector, where lenders now demand more rigorous due diligence to ensure projects remain bankable, and developers have become more open to insuring their projects: “It’s about the global environment we’re living in. So, on one hand you have the lenders which are being more careful in what they put their money in, and of course they’re forcing somehow the market to get to upper level. But on the other hand, you have also the developers, and we are living in a mature market in which you have very powerful developers in the market. And of course, they’re coming with a lot of know-how brought by their group level, by their past experience, by their key people within the companies, which saw a lot of aspects happening.”


Ultimately, the projects that overcome these frictions will be those that prioritize integrated delivery models and a partnership-driven approach to both legal and construction challenges.

CEDER & HOF Awards 2026: Measuring the Event’s Carbon Footprint

Carbon Tool and CIJ Europe continued their collaboration at the 2026 edition of the CEDER Conference & Exhibition and HOF Awards, reinforcing a shared commitment to transparency, measurable sustainability performance and more responsible event planning within the real estate industry.


Held at the Radisson Hotel in Bucharest, the 19th edition of CEDER once again brought together developers, investors, consultants, occupiers and service providers from across the market for a full day of discussions, networking and business opportunities, with sustainability remaining a central theme throughout the event.


As part of this partnership, CarbonTool calculated and analysed the carbon footprint generated by the event, helping transform sustainability objectives into measurable environmental data and actionable insights.


2026 Carbon Snapshot: Understanding the Impact


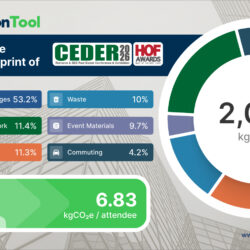
The total carbon emissions generated by the 2026 CEDER & HOF Awards reached 2,049 kgCO₂e, corresponding to an average of 6.83 kgCO₂e per attendee.

Here’s the breakdown of emissions by category:
• Food and Beverages: 1,090 kgCO₂e (53.2%)
• Commuting & CIJ Team Effort: 321 kgCO₂e (15.67%)
• Event Materials: 199 kgCO₂e (9.71%)
• Waste: 206 kgCO₂e (10.05%)
• Electricity: 233 kgCO₂e (11.37%)


As in previous editions, catering and transportation remained the largest contributors to the overall footprint, highlighting the importance of mobility choices and procurement strategies in the environmental performance of large-scale business events.


How Participants Traveled to the Event


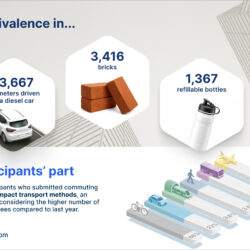
Attendees were invited to submit their commuting method through a dedicated QR-code-based system, helping create a more accurate picture of transport-related emissions and participant mobility patterns.


The results showed a strong preference for lower-impact commuting methods — around 28% of attendees submitted their commuting data, and of those participants, more than 76% chose lower-impact transport methods. This is particularly encouraging considering that, compared to last year, the event welcomed a higher number of international participants, which naturally increases the likelihood of higher transport-related emissions. The results reflect growing awareness around mobility choices and a stronger openness toward more sustainable ways of traveling to professional events.


A Continued Commitment to Sustainable Events


The ongoing collaboration between Carbon Tool and CIJ Europe demonstrates how carbon measurement and environmental accountability can become part of major industry events without compromising business value or participant experience.


While reducing the environmental impact of events remains a complex challenge, initiatives like these show that progress starts with data, awareness and the willingness to continuously improve.


For more information on how Carbon Tool supports organizations in measuring, managing and reducing carbon emissions, visit CarbonTool.

CEDER 2026 in review: ESG and Sustainability Define Modern Bankability

During the first panel held at CEDER 2026, dedicated to the bankability of Office developments, the panelists agreed that in the current real estate market, the concept of bankability has undergone a fundamental shift: while location and occupancy remain vital, financial institutions and tenants alike are increasingly prioritizing ESG (Environmental, Social, and Governance) elements and sustainability performance as non-negotiable pillars of a successful project.


Lenders are no longer just looking for a “green certificate” as a checkbox; they are diving deeper into the technical and operational reality of assets. Doron Klein, Group Deputy CEO of AFI and CEO of AFI Romania, notes a decisive trend in how banks approach financing: “It goes to more green elements that need to be incorporated in the project”, specifically highlighting the importance of the EU Taxonomy and comprehensive ESG reporting. For developers, these green credentials translate into direct financial benefits. Klein points out that in many regions, developers can “even get certain discounts in the spread, in the margin, financing assets with clear ESG component”. This “clear preference” from banks makes sustainability a core requirement for any project seeking competitive financing.


The push for ESG is equally driven by the tenant side of the market. Maria Jianu, Leasing Director at Speedwell, points out that, nowadays, the measurability of sustainability trends is key: “We’re all very fond of ESG. We’re all doing our best in this regard and we’re all striving to be the best in this domain. But what actually matters and what I’m seeing that tenants are looking after is results. What actually is going to impact my costs.”


Adinel Tudor, CEO of EVO Properties, also highlights the fact that it is no longer enough to have certifications: “simply having them, having a plaque on the wall that says LEED, BREEAM, whatever, it’s not enough anymore. (…) Which means that as a developer, you have to choose very carefully what amenities you implement in order to have your tenants happy and willing to remain for a longer period of time in your buildings.”


Andreea Cotigă of CPI Romania describes a “flight to quality or flight to experience over space,” where modern tenants are specifically inquiring about “ESG certification” and sustainable environments. Projects that fail to offer this integrated ecosystem—combining sustainability with high-quality services—struggle to convert inquiries into signed leases.

In a competitive landscape, ESG serves as a performance tool that enhances tenant retention and justifies premium positioning. Looking ahead, the failure to adopt a green philosophy represents a significant financial risk. Cotigă warns that building owners who “prioritize convenience and location over quality and sustainability performance” will inevitably “see their assets lose value”, while assets that manage to bring “ESG performances and superior experiences” will command the greatest market resilience.


Americans invest in real estate across European countries, but not yet in Romania

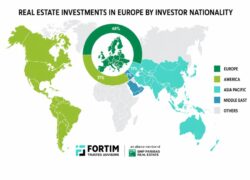
In Europe, most investors in commercial real estate still come from within Europe, accounting for 48%. They are followed by American investors, with 31%, while investors from Asia Pacific rank third, at a significant distance, with 7%, and those from the Middle East rank fourth, with 2%, in the first quarter of 2026, according to BNP Paribas Real Estate data.


According to BNP Paribas Real Estate, cross-border investment in Europe reached EUR 15.1 billion in the first quarter of 2026, while domestic investment, carried out by European investors in their own markets, totalled EUR 21.1 billion.


“Europe is strengthening its position as the main driver of real estate investment on the continent, in a context where European capital remains active and focused on markets with solid fundamentals. The volume of approximately EUR 7.3 billion directed toward cross-border transactions confirms investors’ confidence in European assets, while the significant growth recorded in markets such as the United Kingdom, Germany, and Italy shows that investment appetite is gradually returning, especially where there is liquidity, stability, and clear yield prospects,” said Nicolae Ciobanu, Managing Partner – Head of Advisory, Fortim Trusted Advisors, an alliance member of the BNP Paribas Real Estate.


By contrast, American investors, although representing almost one third of foreign capital, have adopted a more selective approach. Their activity was mainly driven by specific opportunities, particularly in Sweden, Spain, and Poland.


European capital dominates the analysed real estate transactions, accounting for more than two thirds of the investment volume and indicating significantly stronger interest compared with other buyer origin regions. At the same time, non-European capital continues to be present, but remains more attentive to financing costs, asset quality, and the predictability of local markets.


In Romania, investors from the region prevail


In Central and Eastern Europe, including Romania, investors are assessing opportunities more carefully than in previous years. While in mature markets the return of capital is supported by higher liquidity and a larger volume of available institutional products, Romania is in a different position: yields remain attractive, but the macroeconomic context requires greater caution.

Forecasts regarding the evolution of the local economy are being examined more carefully, while growth scenarios are assessed more conservatively.

Romania remains a relevant market in the region, but investment decisions will be more selective. Capital is available, but it is being directed primarily toward well-positioned assets, with stable income and low operational risk.

The origin of capital is changing, local and regional investors are becoming more visible

One of the most important trends for the coming period is the change in the structure of active capital in the market. While in previous years large transactions were dominated mainly by Western European institutional funds, there is now greater activity from local, regional, and entrepreneurial capital.


CEE investors, wealthy families diversifying their portfolios, private capital, and opportunistic funds are more actively analysing markets where they can achieve higher returns than in Western Europe. In Romania, this may lead to an increase in medium-sized transactions, especially in the industrial-logistics sector, retail parks, hotels, and assets with repositioning potential.

At the same time, institutional investors remain interested but are waiting for greater predictability regarding financing costs and yield evolution.


“Romania remains on investors’ radar, but we are no longer talking about broad-based investment appetite. Capital is present, but it is more disciplined, more risk-aware, and more focused on assets that can deliver stable long-term income. Over the next 12–24 months, we will likely see a market dominated by selective transactions, more active local and regional capital, and investors looking for well-founded opportunities, not just high yields,” said Ștefan Oană, Head of Capital Markets, Fortim Trusted Advisors, an alliance member of the BNP Paribas Real Estate.


Cometex Inaugurated the Aurora Retail Park shopping center

Cometex, owned by Dan Ostahie, the owner of Altex, inaugurated the network’s 17th retail park, Aurora Retail Park Bacău.


Aurora Retail Park Bacău is Coometex’s first investment in Bacău, and the investment is 16 million euros. The commercial area has 12,000 square meters, and among the main retailers opening stores here are: Action, Altex, DM, Sinsay, Stay Fit Gym, Tabac Xpress and Tedi.


In addition, Lidl is set to open a store in June, and Deichmann, Salofarm, Sportisimo and ZooCenter will become operational this summer.


“The retail park segment continues to expand in Romania, supported by the growing need for proximity and “The evolution of consumer behavior. Aurora Retail Park Bacău is a project that contributes to diversifying the commercial offer in the city and transforming a former industrial area into a modern retail and community services hub,” says Adrian Urdă, general manager of Cometex.


front page info
LATEST NEWS