India’s Ethanol Push Enters a More Difficult Second Phase

India has reached its 20% ethanol-blending objective years earlier than originally planned, marking a significant change in the country’s transport-fuel market. The achievement reduces the amount of conventional petrol required, creates a substantial domestic market for ethanol producers and farmers, and forms part of India’s wider attempt to reduce its exposure to imported energy.

The rapid transition, however, has created a new set of questions. Having demonstrated that E20 can be introduced on a national scale, policymakers now face the more complicated challenge of ensuring that motorists, vehicle manufacturers and the agricultural supply chain can adapt without undermining the economic and environmental benefits behind the programme.

India’s ethanol expansion has been remarkable. The share of ethanol blended into petrol was only around 1.5% in 2013-14. The country initially intended to reach 20% by 2030, but accelerated the programme as domestic production capacity expanded. By the current ethanol supply year, the average blend had reached the 20% level.

Reducing dependence on imported oil is one of the strongest arguments for the policy. India remains one of the world’s major crude-oil importers, leaving the economy exposed to international prices, currency movements and geopolitical disruption.

Replacing a proportion of petrol with domestically produced ethanol cannot eliminate that dependence, but the cumulative effect is becoming substantial. Official figures indicate that the blending programme has generated foreign-exchange savings exceeding ₹1.97 lakh crore and replaced the equivalent of almost 31.6 million tonnes of crude oil.

The agricultural impact is also considerable. Ethanol production has created another large market for crops and agricultural products that can be converted into transport fuel. Government figures put payments associated with ethanol feedstocks to farmers at more than ₹1.66 lakh crore.

This has helped turn ethanol policy into more than an energy programme. It has become part of India’s agricultural and rural industrial strategy, connecting fuel demand with sugar production, maize cultivation, distilleries, storage, transport and processing infrastructure.

There are nevertheless limits to how far this argument can be taken. E20 does not make India independent of international oil markets. Petrol represents only one part of national petroleum consumption, while the country’s wider demand for crude and refined products remains substantial.

The environmental calculation is similarly more complicated than replacing one litre of petrol with ethanol and assuming an equivalent reduction in emissions.

Government estimates attribute approximately 95 million tonnes of avoided carbon dioxide emissions to the ethanol programme. Ethanol can produce lower lifecycle greenhouse-gas emissions than conventional petrol, but the size of that advantage depends on how the feedstock is cultivated, transported and processed.

Water consumption is particularly important in India. Sugarcane, historically one of the principal sources of domestic ethanol, requires considerable quantities of water. Expanding ethanol production indefinitely through water-intensive crops could therefore create environmental pressures of its own.

Future growth is likely to require a more diversified supply base involving maize, agricultural waste and advanced biofuels alongside conventional sugar-derived ethanol. Developing these alternatives will become increasingly important if India wants to expand biofuel production without creating excessive competition for agricultural land, food production or water.

For motorists, however, the debate is less about national energy strategy and more about what happens inside their vehicles.

The transition towards E20-compatible vehicles has taken place progressively. Manufacturers were expected to introduce vehicles using materials capable of handling E20 from 2023, followed by engines specifically designed to operate efficiently with the blend from 2025.

That does not mean every petrol vehicle manufactured before 2023 is unsuitable for E20.

Testing undertaken by Indian automotive authorities and manufacturers has not identified evidence of widespread engine failures caused by the transition. Older vehicles have already been operating through successive increases in ethanol content without a corresponding pattern of systemic mechanical problems.

There is nevertheless an important distinction between a vehicle being able to operate on E20 and being specifically designed to obtain its best performance from it.

Older vehicles may contain fuel-system components originally specified for lower ethanol concentrations, while engine calibration may have been developed around conventional petrol or E10. Owners of older cars and motorcycles therefore have legitimate reasons to seek clear manufacturer guidance concerning compatibility and servicing.

Fuel economy is the most obvious consequence for consumers.

Ethanol contains less energy per litre than petrol. Unless an engine has been designed to exploit other characteristics of the fuel, increasing the ethanol proportion can therefore result in slightly higher consumption.

Indian testing indicates that the reduction in fuel efficiency can generally fall within a range of approximately 2% to 6%, depending on vehicle design and calibration. For some vehicles developed around E10, government assessments have indicated a difference of roughly 3% to 5%.

For an individual driver, even a relatively small reduction can be noticeable. A vehicle travelling fewer kilometres on the same quantity of fuel creates a direct cost that motorists can measure every time they fill the tank.

This helps explain why public perceptions of E20 can differ from the government’s assessment of its national benefits.

Foreign-exchange savings, lower oil imports and agricultural income are distributed across the economy. Reduced mileage, by contrast, is experienced immediately by the person driving the vehicle.

Consumer communication will therefore be critical to the next phase of the programme. Motorists need clear information about whether individual models were designed for E10, are compatible with E20 or were specifically optimised for the higher blend.

Fuel choice presents another issue.

India is moving towards E20 becoming the normal petrol specification rather than maintaining widespread parallel availability of conventional petrol, E10 and E20. This simplifies fuel distribution but leaves owners of older vehicles with fewer alternatives.

International comparisons show that there is no single approach to ethanol.

The United States sells several ethanol blends, although E10 overwhelmingly dominates petrol consumption and alternatives are not available at every filling station. Brazil has taken a much more aggressive approach, combining a high mandatory ethanol content in petrol with a mature market for vehicles capable of operating on high-ethanol fuel.

India is gradually developing flex-fuel vehicles of its own, but this part of the market remains relatively small. Wider adoption could eventually give motorists more flexibility while allowing the country to use higher ethanol concentrations where economically and technically appropriate.

The most important question surrounding E20 has therefore changed.

A few years ago, the challenge was whether India could produce enough ethanol, modify its fuel-distribution network and coordinate the automotive industry sufficiently to achieve 20% blending.

That target has now effectively been reached.

The harder task is ensuring that the system remains sustainable once the headline target disappears from the policy agenda.

India will need sufficient ethanol without placing unreasonable pressure on food production or water resources. Vehicle manufacturers will need to provide greater clarity for owners of older models. New vehicles will need to become increasingly efficient when operating on ethanol blends, while consumers will expect the economics at the filling station to make sense.

E20 should therefore neither be presented as an unquestionable solution to India’s energy challenges nor dismissed as a policy introduced before the country was ready.

Its rapid implementation demonstrates that India can transform a major part of its fuel market when government policy, agriculture, energy companies and manufacturers move in the same direction.

The next stage will be more demanding because success will no longer be measured simply by the percentage of ethanol blended into petrol. It will depend on whether India can make that achievement economically acceptable to motorists, environmentally sustainable for agriculture and sufficiently scalable to deliver meaningful long-term energy security.

Source: © CIJ.World India Research & Analysis Team
Southern India Emerges as a New Powerhouse for Institutional Real Estate Capital

India’s institutional property market is becoming increasingly diverse as investors expand beyond the country’s traditional financial centres and direct larger amounts of capital towards Bengaluru and Chennai. Strong office demand, expanding corporate operations, improving infrastructure and a deeper pool of domestic investment are strengthening the position of both southern cities.

Institutional investment across Indian real estate reached approximately USD 2.9 billion during the second quarter of 2026, around 70% higher than a year earlier. This lifted investment during the first six months of the year to approximately USD 4.5 billion, making it one of the strongest first-half performances of recent years.

Bengaluru and Chennai were among the major beneficiaries. Each attracted approximately USD 600 million during the first half of the year, giving the two cities a combined investment volume of around USD 1.2 billion. Together, they represented approximately 27% of institutional property investment recorded across India during the period.

Commercial property was responsible for most of this activity. Office assets accounted for approximately 85% to 95% of investment flowing into the two cities, demonstrating how strongly their institutional appeal remains connected to the performance of their corporate occupier markets.

The expansion is part of a broader change in India’s property investment landscape. International institutions remain important, but domestic investors have become considerably more influential. Indian capital represented more than half of institutional property investment during the first six months of 2026, giving the market a broader financing base and reducing its dependence on overseas investors.

This growing domestic investment pool is allowing larger transactions to take place across a wider range of cities. Markets with strong leasing fundamentals, modern properties and established corporate occupiers are increasingly capable of attracting institutional capital without relying exclusively on their status as traditional financial centres.

Bengaluru provides perhaps the clearest example. The city remains India’s largest technology and corporate office hub and recorded approximately 10.5 million sq ft of Grade A leasing during the first half of 2026 under one major market measurement.

Its position is being reinforced by continued expansion among multinational companies and global capability centres. These operations have evolved beyond traditional support functions and increasingly accommodate engineering, research, analytics, technology development and other strategic activities.

Across India, GCCs accounted for more than 40% of office demand during the first half of 2026. Bengaluru’s large technology workforce and established multinational business environment make it one of the primary destinations for this expansion.

For property investors, sustained occupier demand helps support rental income, occupancy and long-term asset values. It also provides confidence that large office developments can attract tenants even as companies become more selective about workplace quality.

Chennai offers a somewhat different investment proposition. While it has a substantial technology and business-services sector, its economy also includes automotive manufacturing, engineering, financial services and other industries.

This diversity reduces dependence on a single occupier category and is helping the city establish a larger institutional office market. Chennai recorded several million square feet of leasing during the first half of 2026, while relatively constrained additions to supply contributed to tighter availability in parts of the market.

The combination of occupier demand and controlled development can be particularly attractive to long-term investors. Lower vacancy creates greater competition for high-quality buildings and can improve prospects for rental growth, particularly in well-connected business districts.

Infrastructure development is further strengthening the investment case for both cities. Metro expansion, road improvements and better connections between residential districts and employment centres are gradually changing the accessibility of established and emerging office locations.

These projects have implications extending beyond commuting. Improved transport can increase the development potential of surrounding land, enlarge the workforce catchment available to employers and support the creation of new commercial districts.

The availability of skilled workers remains another major advantage. Bengaluru’s technology ecosystem gives companies access to one of India’s deepest pools of software, engineering and digital talent, while Chennai combines technology expertise with a large engineering and industrial workforce.

This is increasingly important as multinational corporations assess Indian locations according to their ability to recruit specialised employees rather than simply comparing property costs.

Building quality is also becoming more influential in investment decisions. Large corporate tenants increasingly seek energy-efficient, environmentally certified and professionally managed offices capable of meeting international workplace and sustainability requirements.

As a result, modern properties occupied by multinational companies can command greater attention from institutional investors than older buildings requiring substantial upgrades.

The rise of Bengaluru and Chennai should not, however, be interpreted as the decline of Mumbai. India’s financial capital continues to attract significant property investment and remains one of the country’s most important destinations for institutional capital.

Instead, the change reflects the growing depth of India’s overall real estate market. Investors now have more cities offering the scale of occupier demand, property quality and transaction opportunities required for substantial institutional allocations.

Bengaluru has already established itself as a commercial property market of international significance. Chennai is increasingly following the same trajectory as its office stock, infrastructure and corporate occupier base expand.

The result is a broader investment geography in which Mumbai is no longer the only obvious destination for large-scale property capital.

As domestic investment increases and multinational occupiers continue expanding across southern India, Bengaluru and Chennai are likely to capture a growing share of institutional allocations. Their rise represents less a transfer of capital away from Mumbai than the emergence of a deeper Indian property market capable of supporting several major investment centres at the same time.

Source: © CIJ.World India Research & Analysis Team
Ageing Cold-Chain Infrastructure Creates a New Logistics Opportunity in Japan

Japan’s logistics property market is opening to a more specialised form of investment as demand for modern refrigerated warehousing begins to outpace the capabilities of much of the country’s existing stock. Changing food consumption, an ageing logistics network, higher technical standards and growing demand for temperature-controlled distribution are creating opportunities for a new generation of cold-chain facilities.

For many years, refrigerated warehouses in Japan largely operated outside the mainstream institutional property market. Facilities were commonly developed or controlled by food producers, wholesalers and specialist logistics businesses for their own operational requirements. That structure is gradually changing as developers introduce modern facilities designed for several occupiers, potentially bringing cold storage closer to the investment model already established in Japan’s conventional logistics sector.

The age of Japan’s warehouse stock is one reason this transition is gaining momentum. More than half of the country’s logistics buildings are over 30 years old, while a relatively small proportion has been delivered during the past decade. This matters particularly for refrigerated facilities, where older cooling equipment, weaker insulation and outdated building systems can translate into higher electricity consumption, greater maintenance requirements and lower operational efficiency.

At the same time, Japan’s food distribution system is changing. Frozen and prepared foods have become an increasingly important part of household consumption, supported by demand for convenience, changing household structures and the popularity of products that can be stored for longer periods. Supermarkets, convenience stores, restaurants and food manufacturers consequently require increasingly reliable networks capable of maintaining different temperatures throughout storage and transportation.

Japan’s demographic structure reinforces some of these trends. A large elderly population, significant numbers of people living alone and the prevalence of households where adults have limited time available for cooking all contribute to demand for convenient and prepared meals. This supports not only food production but also the logistics infrastructure required to move chilled and frozen products efficiently through major metropolitan markets.

Digital retail is adding another dimension. Although Japan’s online grocery sector remains less developed than some areas of conventional e-commerce, home delivery of food and direct-to-consumer distribution require more sophisticated handling than standard parcel logistics. Maintaining product temperatures through distribution centres and the final stages of delivery increases the importance of well-located refrigerated facilities around major population centres.

Cold-chain requirements are also extending beyond food. Pharmaceutical products, vaccines, biologics and other temperature-sensitive healthcare products require carefully controlled storage and transportation. As Japan develops its pharmaceutical, biotechnology and life sciences industries, specialist logistics infrastructure will increasingly form part of the supporting real estate required by those sectors.

Environmental performance is becoming equally important. Refrigerated warehouses have substantial energy requirements, meaning inefficient cooling systems can materially affect operating costs. Changes affecting older refrigerants, together with pressure to improve energy efficiency, strengthen the case for replacing or extensively modernising older properties rather than continually maintaining obsolete equipment.

Labour pressures are accelerating the need for modernisation as well. Japan’s logistics industry continues to face shortages of drivers and warehouse employees, while changes to truck-driver working conditions have forced operators to reconsider distribution efficiency. New facilities incorporating automation, improved loading systems and more efficient internal layouts can allow occupiers to process greater volumes with fewer manual operations.

For the property industry, however, perhaps the most important development is the emergence of purpose-built leased cold storage.

A growing pipeline of multi-occupier projects indicates that developers are beginning to see refrigerated logistics as a property product in its own right. Industry research indicates that approximately 141,000 tsubo of new multi-tenant cold-storage space could be delivered during 2027, demonstrating how rapidly the sector is beginning to develop from its comparatively small institutional base.

New projects are also appearing in established logistics locations. Osaka’s Nanko district, for example, is seeing development of a fully refrigerated and frozen multi-tenant facility of around 21,000 sqm scheduled for completion in late 2026. The project demonstrates the type of modern building entering the market, combining different temperature environments with specifications capable of accommodating several logistics and food-sector occupiers.

The multi-tenant model could significantly alter the economics of the sector. Smaller food companies, retailers and third-party logistics providers can access modern refrigerated infrastructure without committing large amounts of capital to constructing their own facilities. Developers, meanwhile, can spread occupational exposure across several tenants rather than depending upon a single specialist user.

Cold storage nevertheless presents substantially greater development challenges than conventional warehousing. Refrigeration equipment, insulation, power infrastructure and specialist building systems increase construction costs, while occupier requirements can differ considerably. A facility designed around one temperature range or product category may require substantial modification for another user.

Power availability and energy costs are also critical considerations. A conventional logistics building may primarily compete on location, accessibility, specification and rent, whereas the viability of a refrigerated facility can depend much more heavily on electricity capacity and long-term operating efficiency. These characteristics make development expertise and careful assessment of occupier demand particularly important.

Yet the same complexity creates barriers to new supply. Modern cold-storage buildings are expensive and technically difficult to reproduce, while a substantial portion of Japan’s existing logistics infrastructure is approaching an age where redevelopment or replacement becomes increasingly necessary.

This combination is creating an unusual property opportunity. Demand is supported by essential consumer industries rather than discretionary warehouse expansion, while the existing supply base contains large numbers of older facilities requiring modernisation. At the same time, developers are introducing a leasing model capable of making the sector more accessible to institutional capital.

Japan’s next major logistics story may therefore be less about adding another generation of enormous dry warehouses and more about upgrading the infrastructure hidden behind the country’s food and healthcare supply chains. As ageing facilities meet increasingly sophisticated distribution requirements, cold storage is moving from a specialist operational necessity towards a potentially significant new segment of Japan’s institutional real estate market.

Source: © CIJ.World Japan Research & Analysis Team

From Algorithms to Infrastructure: AI Opens a New Chapter for Indian Real Estate

Artificial intelligence is beginning to leave a physical as well as technological footprint on India’s property market. While much of the discussion around AI has focused on software and productivity, its influence on real estate is developing along two parallel paths: investors are adopting increasingly sophisticated tools to evaluate property opportunities, while the infrastructure required to support AI is generating substantial demand for data centres, land and electricity.

This distinction is important because India’s wider property acquisition market cannot yet be described as an AI-driven phenomenon. Developers have been accumulating significant land holdings, but residential construction and conventional development remain responsible for much of this activity. Technology is instead becoming one of several factors changing how those acquisition decisions are researched and evaluated.

The Indian real estate industry represents approximately 7.3% of the country’s economy, making improvements in investment and development efficiency potentially significant. Property companies are increasingly incorporating digital platforms into activities ranging from planning and construction to transactions and asset management.

The speed at which companies are experimenting with AI illustrates the direction of travel. Around 91% of Indian companies surveyed in 2025 were either testing or preparing AI applications for their corporate property operations, compared with fewer than 5% two years earlier. However, relatively few had achieved most of the results they originally expected, demonstrating that adoption remains considerably ahead of proven commercial returns.

Investment analysis is one area where the technology could have a particularly meaningful impact. Property transactions involve large quantities of information concerning location, comparable transactions, demographics, occupier demand, infrastructure, development potential and future supply. AI-assisted systems can process these datasets quickly, allowing investment teams to screen a much larger number of potential opportunities before committing resources to detailed due diligence.

India’s fragmented land market makes these capabilities especially relevant. Establishing ownership, development restrictions and infrastructure availability can be complicated, particularly when assembling larger sites. Digitised land records, mapping systems and spatial analysis can help developers understand potential locations more efficiently.

These technologies do not eliminate India’s longstanding land-related risks. Legal verification of ownership, planning approvals, physical inspections and local expertise remain essential before acquisitions can proceed. Their value lies instead in helping investors identify potential problems earlier and concentrate professional resources on the most promising opportunities.

Property valuation is undergoing a similar evolution. Analytical systems can compare large numbers of transactions and market indicators, allowing investors to test pricing assumptions more rapidly. Rather than replacing professional valuers and investment committees, such tools can provide another layer of information for underwriting decisions.

The relationship between AI and Indian real estate becomes much more tangible when attention turns to data centres.

India had already exceeded 1.5 GW of operational data-centre capacity by the third quarter of 2025, with further expansion being supported by cloud services, digital consumption and rapidly increasing computing requirements. The development of artificial intelligence is adding another powerful source of demand because training and operating advanced models requires substantial computing capacity.

For property investors, this creates a fundamentally different type of real estate opportunity. Large data-centre developments require suitable land but also exceptional access to electricity, fibre networks and cooling infrastructure. In some locations, securing sufficient power may ultimately determine the viability of a development more than conventional property considerations.

The resulting investment opportunity extends beyond the data-centre buildings themselves. Large computing campuses require substations, electricity transmission infrastructure, renewable generation, battery storage and telecommunications networks. Equipment suppliers and maintenance providers can also generate additional requirements for nearby industrial and logistics space.

Global technology companies are beginning to demonstrate the scale of this opportunity. Google’s planned AI and data-centre infrastructure investment in Visakhapatnam forms part of a programme valued at approximately USD 15 billion, while Meta has secured capacity connected with Reliance Industries’ large AI-ready data-centre development in Jamnagar.

Projects of this scale could influence the geography of India’s technology property market. Mumbai, Chennai and other established centres remain important because of their connectivity and existing infrastructure, but the enormous electricity and land requirements associated with future facilities could encourage development in additional regions.

This creates opportunities for state governments able to combine reliable electricity, renewable energy, fibre connectivity, suitable development sites and predictable approval procedures. As computing requirements increase, competition to attract data-centre investment could increasingly resemble competition for major industrial projects.

For conventional property investment, AI’s influence will be more evolutionary. Technology can help identify opportunities, analyse markets and support valuation, but it cannot remove the fundamentals that determine whether a development succeeds. Land price, financing, planning, occupier demand, infrastructure and execution will remain central to investment performance.

The greater transformation may come from AI becoming both a tool used by the property industry and a customer of the property industry.

On one side, developers and investors gain increasingly powerful systems for processing information and evaluating opportunities. On the other, the rapid expansion of computing creates demand for some of the most capital-intensive property and infrastructure projects currently being developed in India.

This combination gives AI a potentially significant role in the next phase of India’s real estate market. Its importance will not be determined simply by how many property companies adopt artificial intelligence, but by whether those technologies improve investment decisions and how successfully India converts growing demand for computing capacity into a new generation of digital infrastructure assets.

Source: © CIJ.World India Research & Analysis Team
South Korea’s Rental Market Tightens as Housing Shortage Pushes Deposits Higher

South Korea’s residential rental market is coming under increasing pressure as a shortage of available apartments pushes lease deposits higher in Seoul and begins to affect other major cities across the country.

At the centre of the issue is jeonse, South Korea’s distinctive housing arrangement under which tenants provide landlords with a substantial refundable deposit instead of making conventional monthly rental payments. The system has traditionally provided households with an alternative to both home ownership and standard renting, but rapidly increasing deposit requirements are making this option considerably more expensive.

Seoul has experienced the strongest pressure. Apartment jeonse prices in the capital had increased by approximately 6.27% from the beginning of 2026 through the fourth week of July. The increase was more than five times the growth recorded over the comparable period of 2025, illustrating the extent to which rental conditions have changed within a year.

The acceleration became particularly visible during the second quarter. Seoul apartment jeonse values increased by 0.32% in the second week of June, marking the strongest weekly movement in more than a decade. Across June as a whole, prices rose approximately 1.37%, the largest monthly increase recorded in almost 13 years.

July brought some moderation, but rental costs continued to rise. Seoul apartment jeonse prices increased by approximately 1.03% during the month, maintaining considerable pressure on households looking to renew existing contracts or find alternative accommodation.

A lack of available apartments is one of the principal factors behind the increase. Tenants are competing for fewer suitable properties as new housing availability remains constrained in parts of the capital. Redevelopment and reconstruction projects can temporarily remove apartments from the market, while occupancy requirements and other regulatory changes can also influence how many properties are available to tenants.

The imbalance is increasingly affecting areas outside Seoul’s traditionally expensive neighbourhoods. Households priced out of preferred districts are searching farther afield, transferring demand into comparatively affordable locations and putting upward pressure on deposits across a wider part of the metropolitan market.

Higher jeonse deposits are also contributing to changes in the way South Koreans rent their homes. Monthly rental agreements have become increasingly important as some households find it difficult to finance the large deposits required for traditional leases.

In June, contracts involving monthly rental payments accounted for approximately 54% of Seoul apartment leases. The balance shifted again during July, when jeonse agreements returned to slightly more than half of transactions, demonstrating that the transition is not occurring in a straight line. Nevertheless, the growing use of monthly payments indicates a gradual change in a housing system historically dominated by large deposits.

The financial calculation has also changed for landlords and tenants. Financing a substantial jeonse deposit can be expensive for households dependent on bank lending, while landlords may increasingly prefer regular rental income rather than relying exclusively on large refundable deposits.

What began as an acute Seoul problem is also becoming more visible elsewhere in South Korea. By late July, apartment jeonse prices had increased by approximately 4.09% since the beginning of the year in Ulsan, while Sejong recorded growth of around 3.64% and Busan approximately 2.62%.

Across the country, apartment jeonse prices were approximately 2.91% higher than at the beginning of 2026. The increase was considerably stronger than during the corresponding period of the previous year, suggesting that rental-market pressure is becoming more geographically widespread.

The consequences extend beyond tenants renewing their leases. Households unable to afford higher deposits may have to accept monthly rental payments, move to less expensive locations or reconsider whether purchasing a property offers a more attractive long-term alternative.

This interaction between rental deposits, monthly rents and home purchases makes South Korea’s housing market particularly sensitive to shortages. Pressure in one part of the system can quickly influence another as households adjust their housing decisions.

The situation also highlights the importance of future apartment supply. If new completions remain insufficient in areas experiencing strong household demand, competition for existing homes is likely to continue. Redevelopment may eventually increase the housing stock, but during construction it can temporarily intensify shortages by displacing residents and removing existing properties.

For investors and developers, sustained rental inflation provides evidence of underlying housing demand but also increases the political and regulatory sensitivity surrounding residential development. Affordability, financing conditions and the delivery of new housing will remain central issues as authorities seek to prevent temporary shortages from becoming structural problems.

Seoul remains at the centre of the current rental squeeze, but developments in Ulsan, Sejong, Busan and other markets suggest that the pressure can no longer be viewed solely as a capital-city phenomenon.

If housing availability remains constrained, 2026 could become an important turning point for South Korea’s rental sector, accelerating a gradual movement towards monthly payments while further challenging the affordability of the traditional deposit-based system.

Source: © CIJ.World India Research & Analysis Team
Domestic Investors Reshape India’s Real Estate Capital Market in Record First Half

India’s property investment market is undergoing a significant change in the way projects and acquisitions are being financed, with local investors taking an increasingly prominent role alongside global institutions. The shift coincided with a record first half of 2026, when equity capital flowing into the country’s real estate sector reached approximately USD 8.5 billion.

Investment during the first six months was around 32% higher than the USD 6.4 billion recorded during the same period of 2025. Approximately USD 3.4 billion was deployed during the second quarter alone, demonstrating that investor appetite remained relatively strong despite uncertainty surrounding international trade, geopolitics and financial markets.

More important than the headline volume is where the money came from. Indian capital represented approximately 92% of real estate equity investment during the second quarter, marking a notable change for a property market that has historically depended heavily on overseas private equity, sovereign funds and international institutional investors for major transactions.

Developers were particularly active, accounting for roughly one-third of investment during the quarter, while Indian institutional investors contributed a similar proportion. This suggests that the country’s property market is developing a deeper pool of domestic capital capable of financing development and acquisitions without relying as heavily on international investors.

The assets attracting this money also provide an indication of investor priorities. Land and development opportunities, together with completed office properties, accounted for approximately 94% of second-quarter equity deployment. Investors are therefore pursuing opportunities at both ends of the property cycle: securing sites for future development while acquiring established commercial assets capable of producing immediate income.

Separate institutional investment figures also point towards strengthening domestic participation. Around USD 4.5 billion was invested by institutional players during the first half of 2026 under a narrower measurement of the investment market, approximately 50% more than a year earlier. Indian investors accounted for around USD 2.6 billion of this amount, with their deployment increasing by roughly 80% year-on-year.

Offices remained one of the strongest destinations for institutional money, attracting approximately USD 1.9 billion during the first six months. The sector continues to benefit from healthy occupier demand, particularly from Global Capability Centres and flexible workspace providers. Office leasing reached approximately 45.5 million sq ft during the period, accompanied by around 32 million sq ft of new completions.

Capital is nevertheless beginning to spread into a wider selection of property types. Mixed-use developments, hotels, data centres and other emerging sectors are becoming increasingly relevant as investors seek exposure to structural changes in India’s economy rather than relying solely on traditional office and residential strategies.

Mixed-use properties attracted around USD 800 million of institutional investment during the first half, while a similar amount was directed towards alternative assets. Hospitality investment reached approximately USD 300 million, more than three times the level recorded during the corresponding period of 2025, although the increase came from a comparatively low starting point.

Geographically, India’s three largest investment centres continue to dominate. Bengaluru, Delhi-NCR and Mumbai collectively accounted for approximately 60% of equity capital entering the property market during the second quarter. Their combination of corporate demand, development opportunities, established infrastructure and mature transaction markets continues to make them the preferred locations for large-scale investment.

However, the investment landscape is gradually widening. Capital is increasingly considering opportunities outside the largest metropolitan markets, particularly where expanding manufacturing, logistics, tourism and residential demand are creating new institutional-grade property opportunities.

The significance of India’s record first half therefore extends beyond the USD 8.5 billion invested. The composition of that capital indicates that the country’s real estate market is developing a stronger domestic financial ecosystem capable of supporting increasingly large transactions.

International capital will remain an important part of India’s property market, particularly for major platforms, portfolio transactions and specialised sectors. But its role is becoming part of a broader funding environment that now includes stronger domestic institutions, developers, listed REITs and alternative investment structures.

That evolution could make India’s investment market more resilient during periods when international capital becomes cautious. A deeper domestic investor base provides another source of liquidity and reduces the market’s dependence on global fundraising cycles.

If investment maintains its momentum during the remainder of the year, 2026 could become a landmark period for Indian real estate. The more important development, however, may be structural rather than numerical: India is increasingly generating the capital required to finance the next stage of its own property market growth.

Source: © CIJ.World India Research & Analysis Team
Cybersecurity Anxiety Deepens in Poland as Personal Data Exposure Grows

Concern over the security of personal information is becoming increasingly widespread in Poland, with new research showing that almost four in five people fear that compromised data could eventually lead to financial losses.

A 2026 study commissioned by the Credit Information Bureau, BIK, found that 79% of respondents were worried about the financial consequences that could follow a personal-data breach. More than one third, 37%, indicated a particularly high level of concern.

The findings point to a gradual change in how Polish consumers perceive cybercrime. Online fraud and identity theft are increasingly being regarded as risks that can affect ordinary households rather than isolated problems experienced by companies or particularly vulnerable internet users.

Personal experience of data-security incidents is also increasing. Around 33% of respondents said that either they or somebody close to them had encountered a situation involving compromised personal information. In 2022, the corresponding figure stood at 24%.

Direct exposure has also become significant, with 15% of people questioned in the latest study saying their own information had been involved in such an incident.

The results arrive against the backdrop of a major cybersecurity case affecting Poland’s healthcare sector. An incident involving technology provider MyDr has raised concerns over information relating to a very large number of patients and medical organisations.

Authorities have indicated that historical information associated with as many as approximately 18.8 million people could potentially have been exposed, together with data connected with more than 12,000 healthcare organisations. The precise number of individuals ultimately affected remains subject to investigation.

The scale of the case demonstrates how rapidly the consequences of a security failure can spread through an increasingly interconnected economy. A breach involving a technology supplier can potentially affect thousands of organisations using the same platform, even when those organisations’ own internal systems have not been directly attacked.

This creates an increasingly complicated risk environment for businesses. Companies routinely rely on external providers for cloud storage, customer management, payments, communications and specialist software. As these relationships multiply, protecting information increasingly depends not only on an organisation’s own cybersecurity standards but also on those maintained throughout its network of suppliers.

The same challenge is becoming relevant to the commercial property industry. Modern buildings increasingly depend on interconnected technology for access management, security, parking, visitor registration, energy monitoring, tenant services and building operations.

Office owners, shopping-centre operators, logistics developers, hotel groups and residential platforms can consequently hold or process substantial amounts of information about employees, tenants, customers, contractors and visitors. The expansion of digital building services therefore creates operational efficiencies while simultaneously increasing the number of systems that require protection.

The consequences of compromised information can also extend considerably beyond the original incident. Unlike a physical asset, personal information cannot simply be recovered and made unusable once an unauthorised party has obtained a copy.

Names, telephone numbers, addresses and other identifying information can subsequently be combined with information obtained from other sources. This can make fraudulent telephone calls, messages and emails appear considerably more credible because the person attempting the fraud already possesses genuine details about the intended victim.

That makes social manipulation an increasingly important component of cybercrime. Rather than attempting to obtain everything through a single technical attack, criminals can use previously compromised information to persuade individuals to reveal additional details or authorise transactions themselves.

For consumers, this means greater caution is required when receiving unexpected communications requesting information or financial action. Monitoring activity connected with an individual’s identity and credit history can also provide an indication that personal information is being used without permission.

For companies, however, the challenge is considerably broader. A serious security incident can generate regulatory investigations, legal costs, operational disruption and reputational damage while undermining confidence among customers and business partners.

The economic consequences can therefore continue long after the technical vulnerability responsible for the original incident has been repaired.

Poland’s growing public concern suggests that cybersecurity performance may increasingly influence consumer trust in businesses. Organisations collecting personal information are likely to face greater expectations to demonstrate not only that their own systems are appropriately protected, but that external technology providers handling the same information meet comparable standards.

The issue is particularly important as digitalisation spreads into industries that historically regarded cybersecurity primarily as a technology-sector concern. Healthcare, banking and telecommunications already manage large volumes of sensitive information, but property, retail, hospitality and logistics businesses are also becoming increasingly data dependent.

Buildings themselves are evolving into digital platforms. Access systems recognise employees and visitors, parking applications record movements, residential platforms manage tenant information and smart-building technology continuously exchanges operational data.

That evolution makes cybersecurity part of the wider discussion surrounding the resilience and management of real estate assets.

The latest Polish survey indicates that public awareness is moving in the same direction. With 79% of respondents now concerned about the possible financial consequences of compromised information and one third already having some direct or indirect experience of a data breach, confidence in the protection of personal information can no longer be taken for granted.

As businesses accumulate more information and become increasingly dependent on external technology providers, cybersecurity is moving beyond the boundaries of IT departments. It is becoming an issue of corporate governance, operational resilience and customer confidence, and one that companies across Poland’s increasingly digital economy will find progressively harder to ignore.

Eurocash Reshapes Its Property Footprint as Polish Grocery Competition Intensifies

Eurocash is moving into a new stage of its transformation after spending much of 2026 reducing the physical footprint of its retail, wholesale and logistics operations. With most of the planned closures now completed, the Polish food distribution group is preparing to turn its attention back towards sales growth and maintaining its position in an increasingly competitive grocery market.

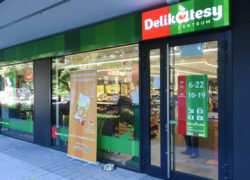
The changes underway across the business have significant implications for commercial property. Eurocash has been closing underperforming Delikatesy Centrum stores, reducing the number of Cash & Carry facilities, consolidating distribution operations and transferring directly managed shops to independent franchise operators. Together, these measures are changing the group’s requirements for retail, warehouse and administrative space across Poland.

By the end of the first half of 2026, Eurocash had closed 105 of the 144 Delikatesy Centrum locations selected for closure. The company has also been reducing the number of stores it operates directly. By the end of July, 73 locations had moved to franchise operators as part of a programme covering 188 stores, with further transfers expected through the beginning of 2027.

The wholesale property portfolio has been undergoing a similar adjustment. Fourteen of the 16 Cash & Carry locations scheduled to cease operations had already been closed, while the group’s distribution infrastructure has been consolidated from 15 centres to 10. Changes have also taken place within the corporate structure, where previously separate administrative and operational functions are being brought together.

For the property market, the consequences extend beyond the number of businesses being closed. Former grocery stores and wholesale facilities can return to landlords or become available for alternative occupiers, while locations converted to franchise operation may continue trading with relatively little visible change from a consumer perspective.

This distinction could become increasingly important for retail landlords. Moving a shop from direct Eurocash management to an independent entrepreneur does not necessarily remove the Delikatesy Centrum brand from the property. Instead, responsibility for operating the business shifts towards the franchise partner, potentially changing the contractual relationship surrounding the premises.

Eurocash has not published the combined floor area affected by the restructuring or detailed how many of the properties involved are owned rather than leased. It has also not provided a comprehensive breakdown of leases that have been cancelled, transferred or renegotiated. Consequently, the amount of space ultimately returning to the Polish commercial property market remains unclear.

Nevertheless, the geographical reach of the programme means its impact is likely to be dispersed across numerous local markets rather than concentrated in a handful of major cities. Grocery properties are often positioned within established residential districts and smaller regional centres, where suitable food-retail locations can remain attractive even when an individual operator decides that a store no longer fits its business model.

Some former Eurocash locations could therefore find new occupiers relatively quickly. Existing grocery infrastructure, established customer catchments and convenient neighbourhood locations may make them suitable for competing supermarket, discount or convenience operators. Other properties, particularly larger wholesale facilities, could require more extensive repositioning depending on their location, configuration and ownership structure.

The transformation is being driven by Eurocash’s attempt to reduce operating costs while preserving the scale of the commercial network supplied by the group. Increasing the proportion of franchise-operated stores allows the company to maintain relationships with retailers and continue supplying merchandise without carrying the full operating burden associated with running each individual shop.

Property expenses have been one element of that equation. A considerable part of the directly operated Delikatesy Centrum estate originated from earlier acquisitions, including the EKO and Mila businesses. Since those transactions, higher operating expenses, changing consumer behaviour and increasingly aggressive competition have altered the economics of many individual locations.

Eurocash is assessing stores according to their ability to operate sustainably under current market conditions. Locations considered viable under independent management can move into the franchise system, while weaker stores are being removed from the network.

The financial objective behind the programme is substantial. Eurocash had secured PLN 279 million of its targeted PLN 400 million in recurring annual savings by the middle of 2026. Changes to the directly operated Delikatesy Centrum portfolio are expected to make an important contribution to the improvement visible in the group’s 2027 performance.

The restructuring has also weighed on turnover. Eurocash generated approximately PLN 7.2 billion of sales during the second quarter, representing a decline of close to 9% compared with the corresponding period of 2025. Part of the reduction resulted from difficult conditions within Poland’s traditional grocery sector, while deliberate store closures and other restructuring measures also reduced revenue.

Management is now signalling that the emphasis is beginning to change. Rather than continuing to focus primarily on reducing expenditure, the second half of 2026 is expected to place greater importance on strengthening sales. Eurocash wants to preserve its share of the Polish FMCG market during 2027, meaning future performance will increasingly depend on growing with the wider market.

The franchise network will be central to that strategy. While Poland’s traditional grocery channel has been contracting, stores operating within networks supplied by Eurocash have performed comparatively better. Hundreds of additional stores joined networks cooperating with the group during the first half of the year, strengthening the company’s reach even as it reduced the number of locations under direct management.

This creates an unusual property dynamic. Eurocash can shrink its own directly controlled real estate requirements while maintaining or potentially expanding the number of shops connected to its distribution system. In effect, part of the property risk moves towards independent retailers while Eurocash concentrates on wholesale supply, purchasing power, logistics, technology and franchise support.

The strategy is unfolding at a particularly important moment for Poland’s grocery sector. Canadian convenience group Alimentation Couche-Tard is pursuing the acquisition of Żabka Group in a transaction valuing the Polish convenience-store operator at approximately PLN 32.6 billion. The tender process formally opened on 26 August 2026.

Żabka has developed one of Europe’s densest convenience networks, with approximately 13,000 stores across Poland and Romania. The proposed transaction would place that platform under the control of a major international convenience retailer and could provide additional financial and operational resources for further development.

For Poland’s commercial property market, this adds another dimension to the competition for neighbourhood locations. Convenience stores, supermarkets, discount operators and independent grocery businesses frequently compete for similar residential catchments, particularly in rapidly developing urban districts and commuter markets.

The contrast between the two strategies is notable. Eurocash is reducing direct responsibility for individual stores and relying more heavily on independent entrepreneurs, while Żabka could become part of a much larger international retail organisation. Both models nevertheless depend on securing extensive networks of well-positioned physical locations.

The next stage of Eurocash’s transformation will therefore be important for landlords as well as investors in the company. Properties released through closures could provide opportunities for competing retailers, while successful franchise conversions may allow Delikatesy Centrum stores to remain in existing premises under a different operating structure.

The larger question is whether Eurocash can reduce its direct property exposure without weakening the scale of the retail ecosystem it supplies. If the company succeeds, its restructuring could demonstrate how a large grocery group can retain market reach while shifting a greater share of store-level costs and property responsibilities towards franchise operators.

As the closure programme approaches completion, Eurocash is moving from contraction towards consolidation and renewed growth. At the same time, international capital is preparing to play a larger role in Poland’s convenience sector. Together, these developments suggest that the country’s next phase of grocery competition will not simply be about opening more stores, but about who controls the locations, who carries the property risk and which operating model can generate the strongest returns from Poland’s extensive neighbourhood retail network.

Source: CIJ.World Research & Analysis Team
Photo: Delikatesy Centrum – Eurocash

EU Goods Trade Moves into Deficit as Import Growth Accelerates

The European Union’s trade in goods with the rest of the world expanded during the second quarter of 2026, but imports grew considerably faster than exports, resulting in a quarterly trade deficit and highlighting the continued importance of China and the United States to European supply chains.

EU countries imported €701.8 billion of goods from outside the bloc during Q2 2026, while exports reached €680.0 billion. Compared with the first quarter, imports increased by 9.9% and exports by 5.4%. The difference was also pronounced on an annual basis, with imports rising 11.7% compared with Q2 2025 while exports increased by 4.5%.

Based on the reported values, the EU recorded a goods trade deficit of approximately €21.8 billion with non-EU countries during the quarter. The figures indicate that the expansion in international merchandise flows was increasingly weighted towards products entering the European market.

China remained by far the EU’s largest external source of goods. European imports from China reached €153.6 billion, equivalent to 21.9% of all goods purchased from outside the EU. Imports from China increased by 7.9% compared with the corresponding quarter of 2025.

The United States was the EU’s second-largest supplier, accounting for €98.7 billion, or 14.1% of imports. Purchases from the US increased by 11.5% year-on-year. The United Kingdom supplied €43.4 billion, Switzerland €36.9 billion and Türkiye €25.5 billion.

The geographical pattern looked substantially different on the export side. The United States remained the largest individual destination for EU goods, receiving €127.7 billion, equivalent to 18.8% of extra-EU exports. The UK followed with €92.7 billion, ahead of Switzerland at €60.5 billion, China at €50.3 billion and Türkiye at €27.3 billion.

The direction of EU-US trade changed noticeably compared with a year earlier. While imports from the United States increased by 11.5%, European exports to the US declined by 5.6%. Based on the quarterly values, the EU nevertheless retained a goods surplus of around €29 billion with the United States.

China presents a very different trading relationship. EU imports from China were more than three times the value of exports moving in the opposite direction. Based on the figures for the quarter, this produced an implied EU goods deficit with China of approximately €103.3 billion. European exports to China increased by 2.8% year-on-year but remained far below the value of incoming goods.

Switzerland recorded some of the strongest growth among the EU’s major export markets. European exports to the country increased by 16.1% compared with Q2 2025, reaching €60.5 billion. Exports to the UK rose by 5.6%, while shipments to Türkiye declined by 4.9%.

For Europe’s industrial and logistics property markets, the acceleration in imports is significant because international merchandise ultimately feeds into a network of ports, airports, rail terminals, warehouses and distribution centres. Higher trade values do not automatically translate into equivalent increases in physical freight volumes, but the figures nevertheless point to substantial activity moving through European supply chains.

The concentration of trade among a relatively small number of major partners also reinforces the strategic importance of Europe’s principal logistics gateways. Goods arriving from Asia and North America are distributed through major maritime ports and inland transport corridors before reaching manufacturing facilities, fulfilment centres, retailers and consumers across the continent.

At the same time, the growing difference between import and export performance raises a broader question for European industry. Strong imports can reflect resilient domestic consumption and demand for components and capital goods, but a sustained pattern in which imports expand significantly faster than exports could also increase concerns about the competitiveness of European manufacturing.

The US figures deserve particular attention in this respect. The country remains Europe’s most important external market for goods, but the combination of falling EU exports and sharply higher imports means the trade relationship became less favourable to the EU during the second quarter.

For commercial real estate, the immediate picture is more mixed. Expanding international trade should continue to support Europe’s logistics infrastructure, particularly around ports and major distribution corridors. However, the longer-term implications will depend on whether stronger imports are accompanied by investment and industrial growth within Europe or increasingly substitute domestically produced goods.

The Q2 figures therefore show an EU trading economy that remains deeply integrated with global markets but is becoming more import-heavy. With €701.8 billion of goods entering the bloc in just three months, the resulting flows continue to underpin demand for logistics infrastructure, while the €21.8 billion overall trade deficit raises a wider question about Europe’s ability to translate international demand into stronger export and manufacturing growth.

BIG Expands Warsaw-Area Retail Footprint with Grodzisk Mazowiecki Rebranding

BIG Poland has completed the rebranding of a recently acquired retail park in Grodzisk Mazowiecki, extending its presence in the Warsaw metropolitan area as the investor continues to expand its Polish portfolio.

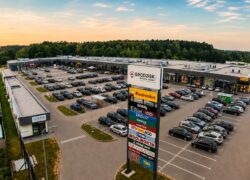
The former Grodzisk Sfera Park is now operating as BIG Grodzisk Mazowiecki following its acquisition by BIG Poland only weeks ago. The property becomes the company’s second retail park in the Mazowieckie voivodeship after BIG Łubna and gives the group a presence in the western part of the Warsaw metropolitan area.

The retail park provides approximately 11,000 sqm of gross lettable area and contains 19 shops and service units. The scheme is fully occupied, with tenants including Biedronka, Sinsay, New Yorker, JYSK, RTV Euro AGD, Rossmann, Pepco, Dealz, KiK, TEDi, Martes Sport, Maxi Zoo, Woolworth, Świat Książki and Kodano Optyk, alongside food and beverage operators.

Rather than representing additional retail development, the Grodzisk transaction illustrates BIG’s use of acquisitions to increase its Polish presence and bring established properties into its operating platform. The rebranding gives the existing scheme a new identity while allowing the investor to apply its own asset-management strategy to an already trading and fully leased property.

“Opening BIG Grodzisk Mazowiecki is another important step in strengthening our presence in the Mazowieckie voivodeship and the wider Warsaw metropolitan area,” said Eran Levy, CEO of BIG Poland. He described Grodzisk Mazowiecki as a growing market with long-term potential and said the company intends to develop further activities aimed at connecting the property with its local catchment.

BIG will formally introduce the rebranded property to customers on 29 August with a public event running between 14:00 and 20:00. The programme includes family entertainment, children’s activities, live performances and food, with admission to the attractions free of charge.

The location provides a strategic element to the acquisition. Grodzisk Mazowiecki is approximately 30 km from central Warsaw, while the retail park is positioned close to the town centre and has connections to the city ring road, A2 motorway and DK50 national road. The property provides 350 parking spaces.

According to BIG, the scheme serves more than 100,000 residents across Grodzisk Mazowiecki, the surrounding county and neighbouring municipalities. This combination of a growing suburban market, road accessibility and an established tenant base gives the property characteristics increasingly sought in Poland’s retail-park investment market.

The acquisition also fits into a much broader expansion of BIG’s Polish platform. The company has been operating in Poland since 2022 and now owns 13 retail parks with combined GLA approaching 258,000 sqm. Its portfolio extends across markets including Gorzów Wielkopolski, Olsztyn, Koszalin, Kielce, Włocławek, Lubin, Suwałki and Ostróda, as well as its two properties in Mazowieckie.

Further growth is planned through developments in Piła, Olkusz, Konstantynów Łódzki and Bolesławiec, giving BIG a combination of acquired operating properties and new projects through which to increase its exposure to the Polish retail market.

The Grodzisk Mazowiecki rebranding therefore represents more than a change of name. It shows how retail-park investors can expand through the acquisition of established, income-producing properties and subsequently integrate them into larger operating platforms.

For Poland’s retail property market, this approach is becoming an important complement to new development. Fully occupied schemes serving growing regional and metropolitan catchments can provide investors with immediate income while still offering opportunities for active management, repositioning and longer-term value creation.

front page info
LATEST NEWS