Sky Deutschland Extends Headquarters Lease in Unterföhring

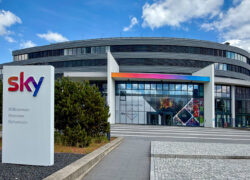
Sky Deutschland has extended the lease for its headquarters at Medienallee 26 in Unterföhring, near Munich, for a further ten years.

The office property, completed in 2010, provides approximately 30,000 square metres of leasable space and is fully occupied by the media company. The building is located within Unterföhring’s established media and office district, one of the main business clusters in the Munich metropolitan area.

The lease extension follows a review process that included an assessment of alternative locations. After evaluating available options, Sky Deutschland decided to remain at its current headquarters.

The Silverton Group managed the asset and supported the restructuring process on behalf of creditors. The company worked alongside insolvency administrator Béla Knof of  White & Case LLP⁠ on a long-term strategy for the property.

Savills⁠ advised Sky Deutschland during the lease renewal negotiations and assisted in the evaluation of alternative office options.

The agreement provides long-term occupancy certainty for the tenant and secures continued use of the building as Sky Deutschland’s headquarters in the Munich region.

Foundever Doubles Office Space in Bucharest to 3,500 sqm

Foundever, a provider of customer experience (CX) services, has expanded its office space in Bucharest to 3,500 sqm, doubling its footprint in the Campus 6.3 office building.

The company’s enlarged premises will accommodate around 300 employees and support the continued growth of its operations in Romania. The expansion was advised by  Cushman & Wakefield Echinox⁠, which also assisted Foundever with its initial lease in the building.

Campus 6.3, owned by  CPI Property Group Romania⁠, is located in Bucharest’s Centre-West office district near the National University of Science and Technology Politehnica Bucharest and public transport connections.

Completed as part of the Campus 6 office complex, the building holds LEED Platinum, WELL Gold and Access4You certifications. The project includes office space, outdoor collaboration areas and employee amenities.

Foundever operates in more than 45 countries and employs over 130,000 people globally, providing customer experience, digital operations and support services to companies across multiple sectors. In Romania, the company has operations in both Bucharest and Cluj-Napoca, delivering multilingual customer support and business services for international clients.

The transaction reflects ongoing demand from occupiers seeking to expand within existing locations while maintaining access to modern office space and workforce talent pools. Financial terms of the lease expansion were not disclosed.

Logfret Leases Approx. 4,900 sqm at SEGRO Logistics Park Warsaw, Nadarzyn

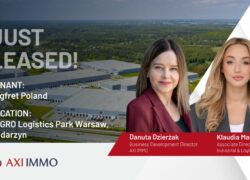
International logistics operator  Logfret⁠ has leased approximately 4,900 sqm of warehouse and office space at  SEGRO Logistics Park Warsaw, Nadarzyn⁠, expanding its logistics operations in Poland.

The transaction was advised by  AXI IMMO⁠, which represented the tenant throughout the leasing process.

Under the agreement, Logfret has taken around 4,600 sqm of warehouse space and approximately 290 sqm of office and staff facilities. The new location will support the company’s plans to develop its contract logistics activities alongside its existing freight forwarding operations in Poland.

Logfret is an international logistics provider with more than 50 years of experience in transport, warehousing and supply chain management. The company operates through a network of over 70 offices and more than 120 partner locations worldwide. In Poland, it is present in Warsaw, Kraków, Katowice and Gdynia.

The leased premises are located within SEGRO Logistics Park Warsaw, Nadarzyn, a logistics and industrial complex situated south-west of Warsaw. The park comprises more than 150,000 sqm of warehouse and production space and is located near the S8 expressway and the Paszków interchange, providing access to the A2 motorway and other key transport routes.

The facility also offers access to Warsaw’s freight airport and includes BREEAM-certified warehouse buildings.

Financial terms of the lease were not disclosed.

EOS Partners Acquires Majority Stake in Drooms

Private equity firm  EOS Partners⁠ has acquired a majority stake in  Drooms⁠, the Frankfurt-based provider of virtual data rooms and due diligence software, as part of a transaction aimed at supporting the company’s next phase of growth and international expansion.

Following the deal, co-founder and former co-CEO Jan Hoffmeister will leave the company after 25 years, while existing shareholder  J.F. Müller & Sohn AG⁠ will exit its investment. Co-founder Alexandre Grellier will remain chief executive officer.

Founded in Germany, Drooms provides digital platforms used for due diligence, asset transactions and document management, particularly within the real estate sector. The company said it plans to use the investment to strengthen its market position, expand internationally and continue developing automation and artificial intelligence tools for transaction processes.

According to Drooms, the company recorded its highest revenues and profits in 2024 and 2025 despite challenging transaction market conditions. It also reported overall growth of approximately 20 percent in 2025.

EOS Partners focuses on investments in software, technology-enabled services, industrial technology and healthcare companies across Europe. The firm stated that it intends to support Drooms’ further development and expansion.

Legal and financial advisers involved in the transaction included  Simmons & Simmons⁠ and  Stifel Financial Corp.⁠ on behalf of Drooms, while EOS Partners was advised by several firms including  KPMG⁠ and  EY⁠.

Financial terms of the transaction were not disclosed.

Central Point Office Tower in Warsaw Acquired by New Owner

The Central Point office building in central Warsaw has been acquired by a new owner, with Savills providing advisory services during the transaction process.

Located at the intersection of Marszałkowska and Świętokrzyska streets, the property was completed in 2021 and rises 93 metres above one of the capital’s key public transport hubs, where Warsaw’s two metro lines intersect. The building provides modern office accommodation in the city’s central business district.

During the acquisition process, assessments were carried out covering technical, environmental and sustainability-related aspects of the property. The review also included an examination of the building’s structural solutions, reflecting its location above active metro infrastructure.

“In today’s market environment, the scope of Due Diligence has evolved. For our clients, the key consideration is no longer only technical safety, but increasingly also compliance with growing sustainability requirements. In the case of Central Point, we carried out detailed ESG Due Diligence (ESGDD) and Environmental Due Diligence (EDD), providing the investor with a substantive basis for assessing the building’s risks and attributes from an environmental and ESG perspective,” said Ilona Otoka, Director of ESG and Sustainability at Savills Poland.

According to Bartłomiej Polnik, Senior Project & Development Manager in Savills Poland’s Building & Project Consultancy team, the building’s construction required specialised engineering solutions because of its location above the Świętokrzyska metro station and the infrastructure of both metro lines.

“Central Point is a unique engineering project on the Polish market. The 93-metre-high building was constructed directly above the infrastructure of two metro lines, which required the application of non-standard engineering solutions. The building has foundations only in selected locations, where the structure extends to a depth of 39 metres. Loads from the section suspended above the station are transferred through specialised tension elements,” he said.

The seller in the transaction was CP Development. Neither the buyer nor the financial terms of the acquisition were disclosed.

OECD Cuts Global Growth Forecast as Energy Shock and Geopolitical Tensions Weigh on Outlook

The OECD has lowered its forecast for global economic growth, warning that rising energy costs, geopolitical tensions and persistent inflationary pressures are creating a more challenging environment for economies worldwide.

In its latest OECD Economic Outlook, Volume 2026 Issue 1, the organisation projects global GDP growth of 2.8% in 2026, down from 3.4% in 2025, before recovering to 3.1% in 2027. The downgrade reflects the economic impact of ongoing disruptions linked to the conflict in the Middle East, which have pushed up oil, energy and commodity prices.

The report identifies the evolving situation in the Middle East as the principal factor shaping the global outlook. Higher energy prices are feeding through to inflation, reducing household purchasing power and increasing costs for businesses across multiple sectors. The OECD notes that the economic consequences extend beyond energy markets, affecting agricultural inputs, food prices and global supply chains. (OECD⁠)

Under its baseline scenario, which assumes that disruptions remain temporary, the OECD expects inflation across G20 economies to rise from 3.4% in 2025 to 4.0% in 2026 before easing to 3.1% in 2027.

The outlook varies significantly across major economies. Growth in the United States is projected at 2.0% in 2026 and 1.8% in 2027, while the euro area is expected to expand by just 0.8% next year before improving to 1.2% in 2027. China’s economy is forecast to grow by 4.5% in 2026 and 4.3% in 2027, reflecting slower but still comparatively strong expansion.

The OECD also outlines a more adverse scenario in which energy and commodity supply disruptions persist for a prolonged period. Under this scenario, global growth would slow to 2.1% in 2026 and 1.8% in 2027, while OECD economies collectively would grow by less than 1% in 2026 and just 0.5% in 2027. Countries highly dependent on imported energy and food would be particularly vulnerable. (OECD⁠)

The organisation calls on governments to maintain fiscal discipline while supporting investment in energy security, productivity and supply chain resilience. It also stresses the importance of structural reforms aimed at improving labour market participation, accelerating digitalisation and encouraging private investment.

For Europe, the report highlights continued exposure to energy market volatility and weaker industrial activity. At the same time, increased public spending on defence, infrastructure and energy transition projects is expected to provide some support for growth over the medium term.

The OECD concludes that while the global economy remains resilient, the balance of risks remains tilted to the downside. Future growth prospects will depend heavily on developments in energy markets, geopolitical stability and the ability of governments and businesses to adapt to a more uncertain economic environment.

OECD Calls for More Investment and Stronger Public Finances to Sustain Slovenia’s Growth

Slovenia should strengthen public finances, encourage greater private investment and improve resilience to global trade disruptions in order to maintain long-term economic growth, according to the latest Economic Survey of Slovenia published by the OECD.

The OECD expects Slovenia’s economic growth to accelerate from 1.1% in 2025 to 1.9% in 2026 and 2.2% in 2027. Inflation is forecast to rise from 2.5% in 2025 to 3.3% in 2026 before easing to 2.6% in 2027.

The report notes that Slovenia’s economy has remained resilient despite a series of external shocks, including geopolitical tensions in the Middle East and Russia’s ongoing war in Ukraine. Since 2022, the country has recorded stronger economic growth than the OECD and euro area averages, while unemployment has remained close to historic lows.

According to the OECD, maintaining this momentum will require continued efforts to reduce public deficits and ensure long-term fiscal sustainability. While recent fiscal reforms have improved the country’s short-term outlook, the organisation suggests that additional pension system reforms may be necessary to address longer-term demographic pressures.

The OECD also recommends shifting part of the tax burden away from labour and towards consumption and property taxation to support economic growth and improve revenue efficiency.

As a highly open economy, Slovenia remains dependent on international trade. The report highlights the need to diversify import sources and strengthen trade resilience amid increasing geopolitical uncertainty and global trade tensions. Enhanced cooperation between state trade agencies could also help facilitate international trade and reduce exposure to external shocks.

The survey identifies artificial intelligence as a potential source of future productivity gains. While AI adoption in Slovenia is already relatively advanced compared with some peers, it remains concentrated among larger and more digitally mature companies. The OECD recommends expanding workforce training and reskilling programmes, as well as attracting more skilled foreign workers, to support broader adoption of AI technologies across the economy.

Access to finance remains another challenge. The OECD notes that Slovenia’s capital markets are relatively shallow, limiting funding opportunities for innovative companies and start-ups. Household savings remain concentrated in bank deposits and real estate, while private pension funds and other institutional investors play a relatively small role in capital markets.

To encourage more productive investment, the report recommends increasing competition in financial markets, reducing tax incentives that favour property investment and expanding privately funded pension schemes. The OECD also argues that reducing public ownership in the insurance sector and lowering regulatory barriers in service professions could support investment and improve long-term economic performance.

The organisation concludes that a combination of fiscal discipline, investment-friendly reforms, greater trade diversification and broader adoption of new technologies will be key to sustaining Slovenia’s economic growth over the coming years.

Student Numbers Continue to Rise at Polish Universities in 2025/26 Academic Year

The number of students enrolled at higher education institutions in Poland increased for the fifth consecutive year, reaching 1.32 million in the 2025/26 academic year, according to new data published by Statistics Poland. The total represented an increase of 42,700 students, or 3.3%, compared with the previous academic year.

As of December 31, 2025, Poland had 345 higher education institutions, of which 328 submitted statistical reports used in the analysis. The latest figures confirm a continuation of the recovery trend that began in 2020/21 after student numbers declined from 1.4 million in 2015/16 to 1.2 million in 2019/20.

Women accounted for 58.2% of all students, while full-time programmes attracted 818,200 students, representing 61.9% of total enrolment. First-cycle programmes remained the most popular, accounting for nearly 59% of all students.

Mazowieckie Voivodship remained the country’s largest academic centre, hosting 287,800 students, equivalent to 21.8% of total enrolment. At the opposite end of the scale, Lubuskie recorded the lowest number of students, with just over 12,000 enrolled.

Business, administration and law continued to be the most popular field of study, attracting 22.1% of all students. Health and welfare ranked second with 14.7%, followed by social sciences, journalism and information at 14.4%, and engineering, manufacturing and construction at 12.3%.

The number of international students declined by 6.5% year-on-year to 101,600. Foreign students accounted for approximately 7.7% of total enrolment, with the largest groups coming from Ukraine (46.7 thousand students), Belarus (10.9 thousand) and Türkiye (4.8 thousand). Nearly 88% of foreign students were enrolled in full-time programmes.

Mazowieckie was also the leading destination for international students, hosting around 33,000 foreign students, nearly one-third of the national total.

While student numbers continued to increase, graduate numbers remained below levels seen a decade ago. In the 2024/25 academic year, 306,600 people graduated from higher education institutions, including 189,100 women, representing 61.7% of all graduates. However, the number of graduates was still 15.9% lower than in the 2015/16 academic year.

The largest share of graduates completed programmes in business, administration and law, accounting for 24.9% of all diplomas awarded. Health and welfare represented 13.2% of graduates, followed by social sciences, journalism and information at 12.9%, and engineering, manufacturing and construction at 12.3%.

Among the 22,600 foreign graduates, Ukrainians represented the largest group, accounting for 39.6%, followed by Belarusians with 12.2%. More than half of all international graduates were women.

The figures suggest that Poland’s higher education sector continues to attract growing numbers of domestic students despite demographic pressures, while international enrolment has moderated after several years of rapid growth. Business-related disciplines remain the dominant area of study, both among current students and recent graduates.


Czech Agricultural Producer Prices Fall Further in May as Industrial and Construction Costs Rise

Agricultural producer prices in the Czech Republic continued to decline in May, while industrial producer prices, construction costs and business service prices remained higher than a year earlier, according to data released by the Czech Statistical Office (CZSO).

Agricultural producer prices fell by 4.3% month-on-month and were 13.2% lower than a year earlier, deepening the annual decline from 10.6% recorded in April.

The sharpest monthly decreases were seen in fruit prices, which dropped by 9.7%, followed by eggs (-7.5%), milk (-2.8%), poultry (-2.2%), cattle for slaughter (-1.7%) and pigs for slaughter (-1.3%). Cereals and oilseeds recorded modest monthly increases.

On an annual basis, crop production prices fell by 13.6%, driven by lower prices for fruit (-43.3%), potatoes (-21.6%), cereals (-15.8%) and oilseeds (-10.9%). In animal production, prices declined by 13%, largely due to lower milk and pig prices. However, cattle, poultry and egg prices remained above year-earlier levels.

Industrial producer prices declined by 0.1% compared with April but increased by 1.5% year-on-year, accelerating from the 1.0% annual increase recorded in April.

The monthly decline was mainly driven by lower prices for electricity, gas, steam and air conditioning, which fell by 2.3%. Food product prices also edged lower, particularly dairy products and processed meat products.

Year-on-year growth in industrial producer prices was supported by significant increases in chemicals and chemical products (+14.7%), wood products (+9.8%) and non-metallic mineral products (+3.8%). Energy prices within the producer basket increased by 2.5% annually, while prices of non-durable consumer goods fell by 1.9%.

Construction work prices remained unchanged on a monthly basis but rose by 3.5% year-on-year, compared with 3.2% growth in April. Prices of construction materials and products increased by 1.3% month-on-month and by 6.1% annually, indicating continued cost pressures across the construction sector.

Prices of business services increased by 0.1% month-on-month and were 3.0% higher than a year earlier. The strongest annual increases were recorded in advertising and market research services (+15.4%), employment services (+8.7%), programming and broadcasting services (+6.5%) and information services (+6.2%).

According to preliminary Eurostat data, industrial producer prices across the EU rose by 0.7% month-on-month and 4.9% year-on-year in April. Among neighbouring markets, annual producer price growth reached 3.1% in Poland, 2.6% in Slovakia, 1.9% in Germany, 1.3% in Austria and 1.0% in the Czech Republic.

The latest figures suggest that while agricultural producers continue to face declining prices, cost pressures remain present across industrial production, construction and service sectors, particularly in materials, energy-related inputs and selected business services.

Slovak Inflation Eases to 3.8% in May as Food Prices Decline Year-on-Year

Consumer price growth in Slovakia slowed slightly in May, with annual inflation easing to 3.8% from April, according to data published by the Statistical Office of the Slovak Republic. On a monthly basis, consumer prices increased by 0.4%.

The moderation in inflation was supported by lower food prices compared with a year earlier, while transport and housing-related costs remained among the main drivers of overall price growth.

Food and non-alcoholic beverages, which account for around 21% of household spending, rose by 0.6% month-on-month in May after three consecutive months of declines. Higher prices for meat and fruit contributed to the increase, although food prices were still 0.3% lower than a year earlier. This marked the first period of annual food price deflation since late 2025 and the weakest annual growth rate for the category in more than two years.

Housing and energy costs continued to exert significant upward pressure on inflation. Prices in the housing, water, electricity, gas and other fuels category increased by 0.5% month-on-month and were 6.7% higher than a year earlier. The increase reflected higher costs for owner-occupied housing, rents, water supply and sewerage services. Heat energy prices were up 28% year-on-year, largely due to regulatory changes introduced at the start of the year.

Transport prices rose by 1% compared with April, although the pace of growth slowed significantly from the 4.6% increase recorded a month earlier. On an annual basis, transport prices were 9.4% higher, representing the fastest increase in the category since late 2022. Fuel prices rose by 19.7% year-on-year, while postal and courier services also became more expensive.

Other categories contributing to inflation included recreation, sport and culture, where prices increased by 4.8% year-on-year, and restaurants and accommodation services, where prices rose by 5.2%.

The Statistical Office noted that inflationary pressures also eased in furnishings and household equipment, as well as clothing and footwear. Growth in prices for alcoholic beverages and tobacco moderated, although tobacco prices continued to reflect the gradual impact of higher excise duties.

During the first five months of 2026, consumer prices increased by an average of 3.8% compared with the same period last year.

Core inflation, which excludes regulated prices and administrative measures, stood at 2.3% year-on-year in May, while net inflation, which additionally excludes food prices, reached 3.3%. Both measures increased by 0.4% on a monthly basis.

The Statistical Office also highlighted methodological changes introduced in January 2026, including the adoption of the revised COICOP 2018 classification and an updated consumer basket based on household spending patterns in 2024. Under the revised basket, housing and energy account for 21.8% of household expenditure, while food and non-alcoholic beverages represent 20.9%.

front page info
LATEST NEWS