Closer EU-Canada ties could reshape demand for European industrial property

A proposed closer economic relationship between the European Union and Canada could eventually create new sources of demand for industrial property, logistics facilities, energy infrastructure and technology real estate across Europe as the two economies deepen cooperation in manufacturing, raw materials, defence and advanced technology. European Commission President Ursula von der Leyen has opened discussions over a new form of association with Canada, potentially creating a relationship extending beyond the existing trade framework between the two markets.

Although the structure has yet to be defined, the areas identified for greater cooperation are closely connected with some of the fastest-changing parts of Europe’s property market. Manufacturing could be among the most important. European governments are attempting to increase production capacity in strategic industries while reducing dependence on concentrated international supply chains. Greater cooperation with Canada could support investment in factories, component manufacturing and supplier networks, generating requirements for industrial land and production facilities.

This would reinforce a change already visible across parts of Europe, where industrial property is increasingly being influenced by manufacturing rather than traditional warehouse development alone. Defence production, automotive supply chains, battery manufacturing, electronics and advanced engineering place different demands on sites, particularly in relation to electricity availability, transport connections and skilled labour.

Critical raw materials could create another property dimension. Canada has substantial mineral resources, while Europe is seeking more diversified sources of materials needed for batteries, renewable energy equipment, electronics, defence systems and other industries. The property opportunity would not necessarily be limited to importing Canadian materials. Greater cooperation could encourage additional processing, refining, recycling and component manufacturing within Europe. These activities require specialised industrial locations with substantial energy capacity, infrastructure and access to transport networks.

Defence is another area where the relationship has already moved beyond political discussions. Canada became the first non-European country to participate in the EU’s SAFE defence procurement framework in 2026, allowing Canadian companies and products to participate in projects supported through the programme. Further integration between Canadian and European defence industries could increase requirements for manufacturing plants, secure warehouses, research facilities and supplier locations.

Central and Eastern Europe could be particularly relevant because defence manufacturing and related industrial investment are already expanding across countries including Poland, the Czech Republic, Slovakia, Hungary, Romania and the Baltic states. New production and supplier networks associated with European defence expenditure could therefore add another source of demand for industrial sites in these markets.

Logistics property could also benefit if trade between Canada and Europe increases. Additional flows of industrial components, minerals, machinery and finished goods would strengthen the importance of European ports and the distribution corridors connecting them with manufacturing centres. The effect, however, should not be overstated. Canada and the EU already operate under a comprehensive trade agreement that has removed many conventional barriers, meaning the next stage of integration is more likely to influence investment decisions and industrial supply chains than produce an immediate surge in conventional warehouse demand.

Ports in northern and western Europe could nevertheless become strategically more important if transatlantic flows of energy, minerals and industrial goods increase. This could support demand for port-related logistics, storage and processing facilities as well as rail-connected industrial locations further inland.

Energy infrastructure represents another potential property theme. Europe continues to diversify its energy supplies while simultaneously increasing electricity demand from manufacturing, data centres, transport electrification and other industries. Canada has significant energy resources, and both sides have already discussed cooperation covering energy security, clean technologies and liquefied natural gas.

Technology investment could create a different type of real estate requirement. Plans for closer cooperation in artificial intelligence, quantum computing, cybersecurity and advanced research could contribute to demand for data centres, research campuses and specialised technology facilities. Electricity availability would again be critical. Across several European markets, access to grid capacity has already become one of the principal constraints on data-centre and energy-intensive industrial development. Any additional investment resulting from closer EU-Canada cooperation would therefore compete for sites capable of providing sufficient power rather than simply available land.

The impact would probably be uneven across Europe. Germany and France could attract advanced manufacturing and technology investment, while the Netherlands and Belgium could benefit from their ports and logistics infrastructure. Nordic markets could gain from energy-intensive technology and industrial projects, while Central and Eastern Europe could attract manufacturing, defence and supplier investment because of its existing industrial base.

Poland could be particularly relevant because of its expanding defence sector, manufacturing economy and position within European logistics networks. The Baltic states, Czech Republic, Slovakia, Hungary and Romania could also participate where projects align with existing industrial clusters and infrastructure.

Closer relations could influence investment capital as well as occupier demand. Canadian pension funds and institutional investors already have significant international property and infrastructure exposure. Greater economic integration could encourage further investment in European infrastructure and real assets, although the proposed relationship does not currently provide new property investment rights or guarantees of additional capital flows.

Europe is simultaneously strengthening scrutiny of foreign investment in strategically important sectors. Energy, transport, digital infrastructure, defence, artificial intelligence and critical materials are among the areas receiving greater attention. Closer relations with Canada would therefore develop alongside, rather than replace, Europe’s increasing focus on economic security.

For commercial property, the significance of the EU-Canada initiative will ultimately depend on whether political cooperation produces physical investment. Agreements themselves do not create demand for warehouses, factories or data centres. New manufacturing plants, processing facilities, defence production, energy projects and technology infrastructure do.

If that investment follows, the property effects could become significant. The European real estate markets most exposed to the relationship would probably not be conventional offices or residential property but industrial land, manufacturing facilities, specialised logistics, ports, data centres and energy-related infrastructure.

The proposed EU-Canada relationship should therefore be viewed as an emerging industrial and investment theme rather than an immediate property-market event. Its importance for European real estate will become clearer as governments and companies begin translating closer political cooperation into individual projects, supply chains and capital commitments.

Brazil’s Property Capital Is Returning, but Only the Right Assets Are Finding Buyers

Brazil’s commercial property investment market is showing convincing signs of renewed activity, but the headline numbers tell only part of the story. Transaction volumes increased strongly during the first half of 2026 compared with the same period a year earlier, giving the appearance of a broad recovery after a difficult period for real estate. Look beneath the aggregate figures, however, and a much more selective market emerges. Capital is returning, but it is not returning everywhere. Modern logistics facilities, established shopping centres and selected high-quality offices can attract buyers, while ageing buildings, secondary locations and assets requiring substantial investment remain considerably more difficult to trade. The distinction raises an important question for Brazil’s next property cycle: is the market genuinely recovering, or has liquidity simply returned to a relatively small group of assets that investors are comfortable owning?

The composition of transactions during the second quarter illustrates the divide. Logistics property accounted for the majority of commercial real-estate investment during the period, substantially ahead of retail and offices. That concentration is understandable. Brazil’s warehouse market has experienced strong occupier demand, historically low availability and continued expansion from e-commerce, retailers, manufacturers and distribution businesses. For investors attempting to justify property acquisitions while Brazilian interest rates remain high, buildings with strong occupancy and visible rental demand provide one of the clearest investment cases.

The buyers themselves are equally important. Brazil’s listed property funds remain among the most natural sources of capital for income-producing commercial real estate. These vehicles already operate within the domestic financial system, understand local leases and taxation, and can assemble portfolios without taking the currency exposure faced by international investors. Their activity can therefore provide an important source of liquidity even when global capital remains cautious. But property funds are not buying indiscriminately. Their willingness to deploy capital depends on whether real estate can generate sufficiently attractive returns relative to other domestic investments. When fixed-income products provide high yields, an office building, warehouse or shopping centre must offer a compelling combination of income, rental growth and potential appreciation to justify the additional risks associated with ownership.

This helps explain the attraction of modern logistics. Warehouses occupied by established tenants, positioned in major distribution corridors and benefiting from limited competing supply can offer relatively predictable cash flows. Large facilities around São Paulo are particularly attractive because the region combines Brazil’s biggest consumer market with manufacturing, transport infrastructure and deep occupier demand. The result is a market where logistics assets can attract several categories of buyers simultaneously. Listed funds, specialist property companies, institutional investors and private capital may all compete for the same well-located properties. That competition creates liquidity and provides owners with greater confidence that an asset can eventually be sold.

Retail property presents a different picture. Brazil’s strongest shopping centres continue to attract investment because they combine valuable locations with established consumer demand and operating businesses capable of generating rental growth. Experienced mall owners can also create additional value through refurbishment, tenant changes, restaurants, entertainment, healthcare and other uses that increase visits. Secondary retail is much harder to underwrite. A weaker shopping centre may require substantial capital before it can compete effectively, and investors must determine whether the surrounding consumer market is strong enough to justify that expenditure. The difference between a dominant mall and a struggling centre can therefore be much greater than the fact that both properties belong to the same real-estate sector would suggest.

Offices demonstrate the same selectivity even more clearly. São Paulo’s best buildings are benefiting from improving demand, reduced availability and rising rents in preferred business districts. Companies seeking modern workplaces are increasingly concentrating on buildings that provide efficient layouts, good transport access, technology, amenities and high-quality working environments. For investors, those buildings can once again provide a credible acquisition story. Rising rents create potential income growth, while tightening availability reduces leasing risk. Yet this recovery does not automatically extend to older offices. Buildings requiring major expenditure on mechanical systems, façades, lifts, common areas or energy performance can remain difficult to sell even when the wider office market is improving.

This means investors are increasingly buying specific buildings rather than simply allocating money to the office sector. Location, age, tenant quality, lease structure and future capital expenditure can determine whether two apparently similar properties attract completely different levels of interest. Rio de Janeiro reinforces the point. Improving demand in parts of the city’s premium office market demonstrates that recovery is possible, but it remains concentrated in particular buildings and districts. An investor buying Brazilian offices therefore cannot rely solely on a national or even citywide recovery. Each asset must demonstrate why occupiers will continue choosing it.

Private investors add another layer to the buyer pool. Family capital and wealthy individuals can sometimes move more quickly than institutional organisations and may be prepared to consider smaller transactions that are irrelevant to large funds. They can also take longer investment horizons or pursue redevelopment opportunities that require greater patience. However, private capital faces the same fundamental comparison with Brazilian fixed income. Property must provide enough potential reward to compensate for illiquidity, tenant risk and management responsibilities. High interest rates therefore do not simply constrain institutional buyers; they raise the hurdle for almost every domestic investor considering real estate.

Developers and specialist property companies approach the market differently. They can acquire buildings because they believe they can change the property rather than simply collect its existing income. Refurbishment, redevelopment, tenant restructuring or integration into a larger portfolio can create value unavailable to a passive investor. This gives developers a potential role in absorbing assets that conventional institutions avoid. An ageing office, poorly managed shopping centre or underdeveloped industrial site may be unattractive as an income investment but compelling if the buyer sees an opportunity to transform it. The price remains critical. Value-add investors need enough difference between acquisition cost and potential future value to compensate for construction, financing, planning and leasing risk. Owners unwilling to recognise that difference can leave properties stranded between the price sellers want and the return buyers require.

Corporations form another distinct group. Companies purchasing buildings for their own occupation do not necessarily assess property using the same criteria as investment funds. A manufacturer may acquire industrial land because controlling its production site has strategic value. A technology company may secure a data-centre location because access to electricity is more important than conventional property yield. A large business may purchase offices because long-term occupation makes ownership financially or operationally attractive. Corporate demand can therefore create transactions even when investment-market pricing remains difficult. It can be particularly important for specialised properties where the building has greater value to an occupier than to a conventional landlord.

International capital faces a different calculation again. Brazil offers enormous economic scale, large consumer markets and several property sectors with compelling fundamentals. But foreign investors must consider exchange-rate movements, financing, taxation and eventual exit liquidity alongside conventional property risks. This can make international buyers particularly selective. The additional complexity of investing across borders is easier to justify for large portfolios, exceptional buildings or opportunities capable of generating returns unavailable in more mature markets. Smaller secondary properties may simply not provide sufficient reward.

The result is a hierarchy of investibility across Brazilian commercial property. At the top are assets capable of attracting several buyer groups simultaneously. Modern logistics facilities with strong tenants, dominant shopping centres and prime offices in tightening submarkets can potentially appeal to domestic funds, private capital, property companies and international investors. Below them sits a much larger group of properties with a narrower buyer universe. These may be fundamentally sound buildings but have weaker locations, shorter leases, higher future expenditure or other characteristics that reduce institutional demand. At the bottom are assets for which conventional investment logic is increasingly difficult to justify. Obsolete offices, struggling secondary shopping centres and properties requiring substantial capital without sufficient rental upside may technically be available for sale but remain effectively illiquid unless their prices fall enough to attract redevelopment or opportunistic capital.

This distinction explains why transaction volume alone can give a misleading picture of Brazil’s recovery. A handful of large portfolio acquisitions or major logistics transactions can increase national investment figures substantially without restoring liquidity across the wider property stock. The same applies to falling interest rates. A gradual easing of monetary policy can improve property pricing by reducing the attractiveness of competing fixed-income investments and lowering financing costs. But cheaper money will not automatically make every building investible. Assets with structural problems will still require refurbishment, repositioning or lower prices.

The next stage of Brazil’s recovery will therefore depend on whether the buyer universe begins expanding. A genuinely broad market would see institutional investors moving beyond the safest logistics assets, more capital returning to offices, secondary properties finding buyers and international investors becoming increasingly active across several sectors. Until that happens, Brazil is better understood as a property market experiencing selective liquidity rather than universal recovery. That does not diminish the significance of the improvement. Stronger leasing markets, rising rents in selected sectors and increasing transaction activity provide the foundations for a wider recovery, but they also give investors greater ability to distinguish between properties worth owning and those requiring fundamental change.

The most important question is therefore not simply how much Brazilian commercial property is being bought. It is who is buying, what they are willing to own and where different categories of capital reach the same conclusion. When domestic funds, private investors, specialist operators and international capital all want the same type of property, liquidity can return quickly. When only a developer prepared to undertake major redevelopment can justify an acquisition, the market is sending a very different signal.

Brazil’s property recovery is consequently creating winners before it creates a universally liquid market. The buildings attracting capital today are those capable of competing successfully for both tenants and investors. The rest of the market still has to demonstrate why it deserves to be part of the recovery. The real measure of Brazil’s next investment cycle will not be whether transaction volumes continue rising. It will be whether the range of assets capable of finding buyers begins to widen.

Source: CIJ.World Research & Analysis Team

Katowice Business Point seeks new occupiers as office demand begins to recover

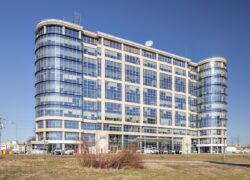
Adventum is stepping up leasing activity at Katowice Business Point as the city’s office market combines improving occupier demand with one of the highest vacancy rates among Poland’s regional business centres. Colliers has been appointed to handle leasing at the property, which offers close to 16,900 sqm of office space beside Silesia City Center. The building is being positioned for both private companies and public-sector organisations, an occupier group that has become increasingly visible in Poland’s commercial office market.

The leasing campaign comes during a period of gradual improvement in Katowice. Office transactions reached approximately 35,400 sqm during the first half of 2026, representing an increase of 51% compared with the same period last year. The second quarter produced the city’s strongest quarterly leasing result for three years. Available space nevertheless remains substantial, with around 22.2% of Katowice’s modern office stock vacant at the end of June. This continues to give tenants considerable choice and places pressure on landlords to compete through building quality, location, fit-out options and commercial terms.

Katowice Business Point is an established office property on Chorzowska Street, close to public transport and major road connections. The building also provides approximately 230 parking spaces and has access to the retail, restaurant and service facilities surrounding Silesia City Center. Its internal layout includes a substantial amount of subdivided office accommodation, potentially making the property suitable for organisations requiring separate departments, meeting areas, customer-facing facilities or restricted-access rooms rather than predominantly open-plan workplaces.

That characteristic is particularly relevant to public institutions. Government bodies and state-related organisations have become more active in Poland’s commercial leasing market as some seek to consolidate operations or move from older administrative properties into modern office buildings. Recent transactions demonstrate the scale such occupiers can achieve, with public organisations taking significant office areas in Warsaw, Łódź, Kraków and Katowice for administrative departments and other government functions.

This provides landlords with another potential source of demand at a time when corporate occupiers have become more selective about the amount and type of space they require. Hybrid working has reduced requirements for some businesses, while others are relocating to buildings offering better transport connections, energy performance and working environments.

Katowice Business Point also holds BREEAM certification and has two independent electricity supplies. Such characteristics can be relevant for occupiers with formal requirements covering energy performance, operational resilience or continuity of services.

The wider Katowice market is increasingly divided between buildings capable of meeting current occupier expectations and properties requiring investment or repositioning. High headline vacancy therefore does not necessarily mean that all available offices compete equally for demand. With relatively little new development changing the supply picture, competition is increasingly taking place within the city’s existing stock.

For owners, attracting tenants depends on how successfully established buildings can be adapted to current requirements rather than simply offering available floor area. The renewed leasing of Katowice Business Point reflects that challenge. Adventum will be competing in a market where occupiers have considerable negotiating choice, but where improving leasing activity and larger public-sector requirements could provide additional routes for absorbing existing office space.

PHOENIX Pharma increases Fót logistics footprint to 11,200 sqm

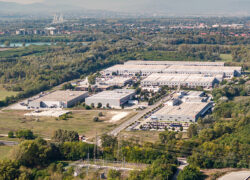
PHOENIX Pharma has added 3,200 sqm to its distribution operation at East Gate Business Park in Fót, increasing its total warehouse footprint at the WING Industrial property to 11,200 sqm. The pharmaceutical wholesaler previously occupied around 8,000 sqm at the location and, following the expansion, its storage capacity has increased to approximately 17,000 pallet positions.

The operation requires more specialised warehouse conditions than conventional distribution activities. Pharmaceutical products require controlled storage environments together with systems capable of monitoring stock and recording movements throughout the distribution process. The additional space therefore increases both physical capacity and the scale at which PHOENIX Pharma can operate from the Fót location.

East Gate Business Park is situated north of Budapest, close to the M0, M2 and M3 motorway connections. Its position provides access to the capital as well as routes towards other parts of Hungary and international transport corridors.

PHOENIX Pharma’s expansion comes as Hungary’s industrial and logistics property market adjusts to higher levels of available space than during the exceptionally tight conditions recorded earlier in the decade. Greater choice for occupiers has increased competition between properties, particularly within the standard warehouse segment.

Against that background, buildings capable of supporting businesses with more complex technical and operational requirements can occupy a different position in the leasing market. Pharmaceutical distribution is one example, alongside food logistics, manufacturing and other activities requiring more specialised building infrastructure.

The ability to expand at an existing location can also be important for these occupiers. Moving a pharmaceutical distribution operation involves more than transferring stock between warehouses, making additional capacity within an established site potentially more practical than relocating the entire operation.

The transaction forms part of wider leasing activity across WING Industrial’s portfolio. The company recorded close to 70,000 sqm of industrial and logistics leasing during the first half of 2026, with new leases accounting for approximately 60% of that area.

The PHOENIX Pharma expansion demonstrates that occupier activity continues within the Budapest logistics market despite the increase in overall warehouse availability. Demand is becoming more differentiated, with location, technical specification and the ability to accommodate future expansion playing a greater role in tenant decisions.

Following completion of the additional space, PHOENIX Pharma’s Fót operation is 40% larger than previously, strengthening the company’s distribution capacity while retaining its existing position within one of the established industrial locations surrounding Budapest.

Środa Wielkopolska retail development secures Lidl ahead of 2027 construction start

Refield and RGL have secured Lidl, Pepco and Sinsay for their planned retail development in Środa Wielkopolska, adding 3,500 sqm of committed space as the investors prepare to begin construction in early 2027. The project will provide approximately 18,000 sqm of retail space on a site of almost six hectares alongside national road DK11. More than 30 businesses are ultimately expected to operate within the complex, which is scheduled to open during the first half of 2028.

Lidl will operate from a standalone building positioned close to the entrance to the property, while Pepco and Sinsay will occupy space within the wider development. Further leasing discussions are underway, with the investors expecting agreements to cover around 80% of the project’s available space by the end of 2026. This would leave most of the development committed before physical construction begins.

The scheme is being developed for a market extending beyond Środa Wielkopolska itself. Refield and RGL estimate that more than 40,000 people live within approximately 15 minutes’ driving time of the property. Its position alongside DK11 is intended to provide access for both local customers and residents of surrounding municipalities.

Access improvements will accompany the development. A new roundabout is planned as part of the road infrastructure serving the property, while cycling connections are also expected to be extended towards the site. Around 460 parking spaces are planned for customers, together with charging facilities for electric vehicles. The developers also intend to pursue BREEAM environmental certification for the completed property.

The development is part of a wider partnership between Refield and RGL targeting retail projects in Poland’s regional cities and towns. Środa Wielkopolska illustrates the continuing expansion of the retail park model into markets outside the country’s largest urban areas, where developers are looking for locations capable of serving both town populations and wider regional catchments.

Grocery stores have become particularly important within these developments because regular food shopping can generate repeat visits throughout the week. Combining a supermarket with value-oriented fashion, household goods and services can also allow regional retail schemes to capture a larger share of everyday consumer spending without relying on the scale of a traditional shopping centre.

The 18,000 sqm planned in Środa Wielkopolska represents a sizeable addition to the town’s commercial property market. The level of leasing achieved before construction will therefore provide an early indication of retailer appetite for additional space in the local market.

Construction is currently scheduled to start at the beginning of 2027, followed by completion and opening during the first half of 2028.

AI Agents Are Starting to Spend Money – and a New Payments Layer Is Emerging

Artificial intelligence is moving rapidly from systems that answer questions towards software capable of taking actions. One of the most consequential next steps is financial: giving AI agents the ability to pay for information, services and digital tools without requiring a person to intervene in every transaction. That emerging market was the focus of a discussion at AI4 2026 in Las Vegas between Erik Reppel, creator of the x402 payment protocol and former Head of Engineering at Coinbase Developer Platform, and Aaron Stanley of Promenade Advisory. Their conversation highlighted how the convergence of AI, digital payments and blockchain infrastructure could create a new machine-to-machine economy in which software buys what it needs in order to complete a task.

The concept is different from the conversational shopping experiences increasingly appearing in consumer e-commerce. In that model, a person might ask an AI assistant to recommend running shoes, compare several options and then manually approve a purchase. Autonomous commerce goes further. While completing the research, the agent itself could pay for access to specialist data, premium reviews, computing capacity or another digital service without returning to the user for approval each time. This distinction could become economically important because AI agents increasingly depend on external information and tools. A general-purpose model may be able to answer many questions from its existing knowledge, but specialised tasks often require current data, proprietary databases, premium search, software interfaces or additional computing resources. Today, connecting those services usually requires a developer to create accounts, manage subscriptions, provide API keys and establish billing relationships in advance.

Reppel argues that a payment system designed for machine-to-machine transactions can remove much of that friction. Rather than an AI agent being limited to the tools configured by its developer, it can potentially discover a service, receive a price, pay for access and continue working automatically. The x402 protocol was developed to address that problem. Its name derives from HTTP status code 402, which was reserved decades ago for “Payment Required” but never became a widely used part of the web. Coinbase revived the concept by developing an open protocol that allows payments to be incorporated directly into normal internet interactions.

Coinbase formally introduced x402 in May 2025 as an internet-native payment standard allowing applications, APIs and AI agents to make payments directly through HTTP. The initial implementation focused heavily on stablecoins, but the broader ambition is not to make one payment method mandatory. Instead, x402 is intended to separate the payment request from the particular financial rail used to settle it. That could eventually allow agents to choose between stablecoins, payment cards and other methods according to the transaction. A large consumer purchase might still be more suitable for a credit card because of consumer protections, insurance or rewards. A payment of only a few cents for a single database query may make more economic sense on another rail.

This becomes particularly important for micropayments. The commercial internet has largely developed around advertising, subscriptions and relatively large individual purchases partly because conventional payment economics make extremely small transactions unattractive. Card transactions normally include fixed processing costs as well as percentage-based fees. As the purchase amount becomes very small, those costs can represent an impractical share of the transaction. AI agents could create demand for an entirely different type of payment behaviour. An agent researching a problem may value a particular piece of information at only a few cents. It may want to pay for one search result, one article, one API call or several seconds of specialised computing rather than purchasing an entire monthly subscription.

If payment infrastructure can handle those transactions economically, previously difficult business models become possible. This could have particularly important consequences for publishers and information providers. Generative AI can summarise information without sending users directly to the websites that produced it. That weakens advertising and affiliate models that depend on human visitors clicking through to the original publisher. A machine-payment model offers a different possibility. Rather than relying entirely on human traffic, publishers could potentially charge AI agents directly for access to premium articles, datasets, analysis or archives. A consumer might continue receiving an AI-generated answer, while the agent pays several information providers in the background to assemble that answer.

The economics could resemble wholesale information markets more than conventional media subscriptions. Instead of asking every consumer to maintain dozens of separate subscriptions, an AI assistant could purchase individual units of information only when they are useful. Whether publishers ultimately embrace that model remains uncertain, but the infrastructure is already beginning to appear. Coinbase has demonstrated x402 integrations allowing agents to purchase API access and other digital services on a pay-per-use basis without conventional API keys or account creation.

The x402 ecosystem is also expanding beyond its original Coinbase environment. In 2026, the protocol moved towards a foundation model intended to provide broader and more neutral governance. Participation from major payments, technology and infrastructure companies suggests that agentic payments are increasingly being treated as a wider payments-infrastructure issue rather than simply another cryptocurrency application.

Open standards may prove particularly important if autonomous commerce grows. No retailer, bank, technology provider or AI developer is likely to want a future in which one company controls the only infrastructure through which agents can make payments. Internet protocols historically became powerful precisely because competing businesses could build on common standards while retaining control over their own services. A neutral payment protocol could perform a similar role for autonomous software. Merchants could specify which methods they accept, while agents select whichever compatible payment option best suits the transaction.

That flexibility could become important because machine commerce will not consist of a single type of purchase. An AI agent arranging a business trip might pay for search access, buy specialised travel data, reserve a hotel and purchase an airline ticket. Each transaction carries different economics, regulatory requirements and consumer protections. Some may justify stablecoin settlement because of speed and transaction costs. Others may remain firmly within conventional banking and card networks. The infrastructure therefore needs to accommodate several payment rails rather than assume that one system will replace all others.

Reppel described another potentially significant consequence: AI agents could become more dynamic. Most agents today have a relatively fixed collection of capabilities. Developers decide which services they can access, configure the APIs and establish the required subscriptions. If the agent encounters a problem requiring a service that has not been configured, it may simply be unable to continue. A machine-payment layer could allow the agent to acquire capabilities as required. If it needs specialist weather information, advanced search, translation or another analysis tool, it could discover an available service and pay for one-time access. The set of functions available to the agent would therefore expand as new services entered the market without requiring the user to configure each one manually.

That begins to resemble an application marketplace operated primarily by software rather than people. Discovery infrastructure is already developing around this idea, allowing agents to identify services that can be purchased programmatically across areas including data, search, infrastructure, inference and other digital functions. If these marketplaces expand, software agents could eventually assemble their own combinations of tools according to the task they have been asked to complete.

This could also alter software pricing. The software-as-a-service economy has largely been built around subscriptions. Companies pay monthly or annual fees because establishing a billing relationship for every individual software interaction would be cumbersome. AI agents may favour consumption-based purchasing instead. An agent might pay for 20 searches today, use nothing tomorrow and purchase a different service the following week. For occasional users, this removes the need to maintain subscriptions to products they rarely use.

Reppel suggested that providers may even be able to charge slightly more per individual interaction because customers are paying for convenience and avoiding long-term commitments. Frequent users could then move naturally towards conventional subscriptions once recurring usage makes them more economical. That creates a possible two-stage commercial model: low-friction pay-per-use access for discovery followed by subscriptions for high-volume customers.

For software providers, this could reduce one of the largest barriers to acquiring new customers. A potential user would no longer necessarily need to create an account, enter payment details and agree to a monthly plan before testing a product. An AI agent could make a small payment, evaluate the service and continue using it if the result justified the price. Machine customers could therefore become a new route to market.

This also changes what it means to design a digital product. Companies have historically built websites and applications for human users. Increasingly they may also need to make products readable, discoverable and purchasable by software agents. That means publishing machine-readable pricing, clearly describing capabilities, exposing inventory or service availability and making it possible for automated systems to authenticate and transact securely.

The transformation could eventually reach beyond purely digital products. Consumer shopping, travel, logistics, financial services and procurement could all become partially agent-driven, but the timetable is likely to differ significantly by category. Low-value digital services are an obvious early market because transactions can be completed entirely online and the financial risk is limited. Autonomous purchasing of physical goods creates additional questions involving delivery, returns, fraud, liability and consumer authorisation.

Business-to-business commerce may also move relatively quickly. Corporate procurement frequently involves repetitive transactions governed by established budgets and approved suppliers. An agent operating within defined limits could potentially obtain prices, compare suppliers and execute routine purchases automatically. As these systems develop, financial controls will become as important as payment capability. Businesses will need to determine how much an AI agent can spend, which suppliers it may use, what categories are permitted and when a human must approve a transaction.

The challenge therefore is not simply giving AI access to a wallet. It is creating programmable authority. An organisation might allow an agent to spend several cents on information without approval, several hundred euros on routine procurement within an approved supplier network, but require human authorisation for larger commitments. Financial governance will need to become embedded in the agent itself.

This is likely to create new opportunities for banks, card networks, payment processors and financial technology companies. The financial industry has decades of experience with fraud detection, authorisation, identity and transaction monitoring. Agentic commerce introduces a new participant into those systems: software acting on behalf of a person or organisation. Payment companies therefore need to establish not only whether sufficient funds are available, but whether the AI agent itself has permission to make the transaction.

That helps explain why traditional payment groups are becoming involved so early. The future market is not necessarily a competition between blockchain and credit cards. It may be a competition over who provides the identity, authorisation, settlement and risk infrastructure connecting autonomous agents to the financial system.

The scale of that future market remains impossible to determine. Forecasts describing agentic commerce as a multi-trillion-dollar opportunity depend on assumptions about how quickly autonomous agents become reliable enough for consumers and companies to delegate meaningful spending authority. Adoption remains early. Even at an AI-focused conference, only a small number of attendees indicated that they had personally allowed an agent to transact for them.

Yet the underlying direction is significant. Search became a standard capability for AI assistants because an agent without access to current information quickly became less useful. Payments could follow a similar trajectory. Once agents can routinely pay for information and services, financial capability may become another expected component of an intelligent digital assistant.

For businesses, the strategic question is therefore broader than whether they should accept cryptocurrency or implement one particular payment protocol. It is whether their products and services will be accessible to customers that are increasingly represented by software. The internet was designed around people browsing websites, reading advertisements, clicking buttons and entering payment information. An agent-driven internet works differently. Software does not need graphical interfaces, may not respond to advertising and can compare large numbers of providers before completing a transaction.

That could undermine some of the assumptions behind today’s digital economy while creating entirely new markets. Publishers may sell individual pieces of information rather than advertising impressions. Software companies may sell individual API calls alongside subscriptions. Data providers may receive revenue from agents that discover their services moments before purchasing them. AI systems may automatically assemble combinations of paid services that no developer explicitly configured in advance.

None of this means conventional commerce disappears. Humans will continue to make purchasing decisions, payment cards will remain important and subscriptions will continue where they offer better economics. What changes is the customer base. For the first time, businesses may increasingly be selling not only to people and other companies but directly to autonomous software operating with its own purchasing authority.

If that develops at scale, agentic commerce will not simply become another feature within artificial intelligence. It could become a new economic layer of the internet, where information, computing resources and eventually physical goods are discovered, priced and purchased by machines in real time. The important development is therefore not that an AI agent can now hold a wallet. It is that the infrastructure is beginning to emerge through which millions of software agents could eventually participate in commerce without being individually configured for every transaction.

That possibility turns AI from a consumer of information into an economic participant and may force companies to rethink who, or what, their next customer actually is.

Source: CIJ.World Research & Analysis Team

Japan’s Ageing Buildings Drive a New Wave of Digital Investment

Japan’s commercial property market is entering a new phase of digitalisation as building owners look for ways to reduce energy consumption, manage labour shortages and extend the competitive life of existing assets. Rather than being driven by a single wave of futuristic smart buildings, the transformation is developing through practical investments in sensors, automated building controls, artificial intelligence, robotics and increasingly sophisticated property-management systems. The economic argument for these technologies is becoming stronger. Japan has a large stock of ageing commercial buildings, rising construction and operating costs and a shrinking workforce. At the same time, tighter energy-performance requirements are placing greater pressure on owners to understand how their buildings consume energy and where improvements can be made.

This makes digitalisation increasingly relevant to asset management rather than simply building design. New office towers can incorporate sophisticated systems from the beginning, but the larger long-term opportunity could be upgrading the enormous volume of property that is already standing. Japan’s regulatory environment is helping accelerate that process. From 2025, energy-efficiency requirements were extended across new buildings, including categories that had previously been outside mandatory compliance. The country is also progressively raising performance expectations toward 2030.

The direction of policy is important for property owners because a significant proportion of Japan’s existing non-residential building stock remains below current energy-efficiency standards. This creates a substantial requirement for refurbishment over the coming years. Improving insulation and replacing inefficient mechanical equipment will form part of that process, but technology can provide another layer of improvement. Sensors can monitor how individual parts of a property are being used, while automated controls can adjust heating, cooling, lighting and ventilation according to actual demand.

For landlords, the potential advantage is straightforward. An office floor that is lightly occupied does not necessarily need to be heated, cooled and illuminated in exactly the same way as a crowded one. Better information allows building systems to respond more closely to how the property is actually operating. This also changes the role of building management. Traditional facilities management depends heavily on scheduled inspections and staff carrying out repetitive tasks. Digital systems can increasingly identify unusual energy consumption, equipment problems or changes in building usage before employees physically inspect every area.

Japan’s labour shortage makes this particularly relevant. Cleaning, security, maintenance and property management all require workers, and the country’s demographic trajectory means that recruiting sufficient staff is likely to become increasingly difficult. Some Japanese landlords are consequently experimenting with systems that use sensors and artificial intelligence to determine when services are actually required.

At properties operated by Tokyu Land and its partners, technology is being tested to analyse occupancy and building conditions so that cleaning, security and energy management can be organised more efficiently. Instead of carrying out every task according to a fixed timetable, building operators can potentially direct employees toward areas where work is genuinely needed. This does not mean buildings are becoming autonomous. Human operators remain essential, and many artificial-intelligence applications in commercial real estate are still being tested rather than deployed throughout entire portfolios. Nevertheless, the direction is becoming clearer.

Mitsui Fudosan has been experimenting with a digital representation of parts of Tokyo Midtown Yaesu. The project connects information from the physical property with a virtual environment that can assist applications including robot management and navigation. The significance for real estate lies less in the visual representation of the building than in the possibility of combining previously separate streams of information. Building systems, robots, equipment and eventually tenant activity can potentially be understood through a common digital environment.

At the urban scale, Japan is pursuing a similar approach through the government’s programme for creating detailed three-dimensional models of cities. By the end of fiscal 2025, hundreds of municipalities had developed such models. These virtual city environments have potential applications ranging from disaster preparation and infrastructure planning to energy analysis and property development. They can also be combined with information generated by individual buildings.

For developers, this could eventually improve the earliest stages of investment decisions. Digital models can help examine what might be constructed on a particular site, how a building relates to neighbouring properties and how infrastructure or planning constraints affect development potential. Technology is therefore influencing much more than building operations. Japan’s property sector is gradually adopting digital tools throughout the real-estate lifecycle, including development planning, construction, leasing, workplace management, maintenance, energy control and investment analysis.

This broader transformation is particularly important when considering the role of artificial intelligence. AI is already being tested for highly practical applications rather than simply consumer-facing services. Mitsui Fudosan and Hitachi, for example, have been developing an artificial-intelligence system intended to assist personnel responsible for emergency management across a large office portfolio. The system is designed to help operators identify appropriate procedures during emergencies, including situations where normal communications infrastructure may be disrupted.

For a country exposed to earthquakes, typhoons and other natural hazards, the ability to manage buildings and large property portfolios during emergencies has direct financial implications. Faster access to information can potentially reduce disruption and improve the ability of property managers to respond when multiple buildings are affected simultaneously.

Energy infrastructure is another area where AI is moving closer to actual operation. In Tokyo’s Marunouchi district, companies associated with Mitsubishi Estate have been testing artificial intelligence in the operation of district heating and cooling infrastructure. The objective is to use data and machine learning to assist decisions that traditionally depend heavily on experienced human operators.

This is particularly relevant because large commercial districts consume substantial amounts of energy through heating, cooling and ventilation. Even relatively small improvements in the operation of these systems can become meaningful when applied across large portfolios. Building automation also has implications for tenant experience. Access systems, indoor navigation, environmental controls and workplace applications can make offices easier to use while giving landlords more information about occupancy patterns. That information can subsequently influence decisions about space configuration and building services.

However, greater digitalisation creates new challenges. Many existing commercial buildings were designed long before today’s connected systems became available. Introducing new technology into older properties can require extensive upgrades to electrical infrastructure, communications networks and mechanical systems. Different generations of equipment may also use incompatible software, making it difficult to combine information within one management platform.

This means the business case for digital refurbishment will vary considerably from property to property. A modern office building with relatively recent mechanical systems may be comparatively straightforward to upgrade. An older property requiring substantial replacement of its core infrastructure may need much greater capital expenditure. The result could contribute to a wider division within Japan’s commercial property market.

Buildings capable of being modernised efficiently may remain competitive for longer, particularly if owners can reduce operating costs and improve energy performance. Properties that are expensive to upgrade could face increasing pressure as tenants and investors place greater importance on building efficiency. This adds technology to the existing question of property obsolescence.

Traditionally, an ageing office might become less competitive because of its location, floorplate, appearance or mechanical condition. Increasingly, the ability to collect data, manage energy and integrate modern building systems may also influence whether the property remains attractive. The transition will not happen uniformly.

Some technologies are already widely understood and increasingly common, including building-management systems, energy monitoring, sensors and automated environmental controls. More advanced applications involving predictive maintenance, artificial intelligence and highly integrated virtual building models remain much less consistent.

Japanese construction companies are also developing digital systems, although these should be distinguished from technologies used in completed buildings. Automation, robotics and virtual modelling are increasingly being applied during construction and infrastructure inspection. These technologies can improve safety, identify defects and reduce dependence on labour, but they do not necessarily mean the completed property will operate as an advanced digital building.

The distinction matters for investors because technology is often presented as more mature than it actually is. The immediate commercial opportunity is unlikely to come from buildings operating independently through artificial intelligence. It is more likely to come from incremental improvements that reduce energy consumption, automate repetitive tasks, improve maintenance and allow owners to understand their properties more accurately.

Over time, these separate technologies are likely to become more closely connected. Energy systems could communicate with occupancy sensors. Maintenance platforms could identify equipment problems before failures occur. Robots could perform routine building tasks, while digital property models provide managers with a continuously updated view of the asset. The resulting building would not simply contain more technology. It could potentially require fewer resources to operate.

That is what makes Japan particularly interesting as a testing ground. The country combines sophisticated engineering and technology industries with some of the developed world’s most challenging demographic conditions. Labour availability is declining at the same time that a large amount of existing real estate requires continued maintenance and modernisation.

Digital investment therefore offers a potential response to two problems simultaneously: how to improve the performance of buildings and how to operate them with a more constrained workforce. For commercial property investors, this shifts the discussion away from technology for its own sake.

The more important question is whether digital systems can increase the useful life and financial performance of an asset. If technology reduces energy consumption, limits maintenance costs, improves resilience or makes a property more attractive to occupiers, it becomes part of the investment case rather than an optional feature.

Japan’s newest towers will continue to provide highly visible examples of advanced building technology. But the more significant transformation may eventually occur in less prominent properties across the country. Thousands of existing offices and other commercial buildings will need to become more efficient over the coming years. Some will require major physical renovation, while others may achieve meaningful improvements through better controls, data and building management.

As energy requirements rise and labour becomes harder to secure, the ability to operate buildings intelligently could increasingly influence their competitiveness and value. Japan’s next property technology cycle may therefore be defined not by how technologically impressive a building appears, but by how effectively technology helps an existing asset remain useful, efficient and economically viable for longer.

Source: © CIJ.World Japan Research & Analysis Team

AI Is Beginning to Rewrite the Economics of Online Retail

Artificial intelligence is beginning to alter one of the foundations on which online retail has been built for more than two decades: the assumption that consumers will search for a product, click through to a retailer and make their purchasing decision inside the retailer’s digital environment. Increasingly, the first part of that journey can take place somewhere else. Consumers can describe what they need to an AI assistant, compare products and prices, refine their requirements conversationally and arrive at a retailer already carrying a much clearer purchasing intention. For retailers, that represents a potentially significant shift in who controls product discovery, customer acquisition and ultimately the economics of e-commerce.

At AI4 2026 in Las Vegas, representatives from Nordstrom, Staples, Mirakl and technology consultancy CI&T discussed how artificial intelligence is changing the journey from product discovery through conversion and post-purchase service. The discussion suggested that the immediate transformation is less about autonomous AI agents purchasing everything on behalf of consumers and more about a gradual restructuring of how shoppers find, evaluate and select products. One of the clearest changes is appearing in search behaviour. Retail search was historically dominated by relatively short queries: a customer might enter a product category, brand or basic description and then navigate filters to narrow the results. AI assistants are encouraging consumers to express requirements much more naturally and in considerably greater detail.

Nordstrom described searches evolving from short product requests towards longer, more contextual questions. Instead of looking simply for a dress or pair of shoes, customers can describe an entire occasion and ask for an outfit. They can subsequently reject one recommendation while retaining the rest, creating a conversation around the purchase rather than restarting a conventional search. The distinction matters because it changes what retailers need to know about their own products. Traditional e-commerce could rely heavily on categories, keywords and structured filters. Conversational shopping requires much deeper information about how a product will actually be used.

A customer may not search for a technical product attribute at all. They may ask for running shoes suitable for long distances and a particular type of foot, an outfit appropriate for a specific wedding, or office equipment capable of meeting a certain workload. An AI assistant must translate that intention into products whose characteristics satisfy those requirements. That makes product information one of the most strategically important assets in the emerging retail AI market.

Retailers have spent years improving titles, descriptions, images and structured attributes, primarily to support website search, merchandising and search-engine visibility. AI-driven discovery raises the standard considerably. Models need sufficient information to understand why one product is appropriate for a customer’s particular circumstances and why another is not. Staples provided an example involving printer cartridges. A model number may contain information indicating whether a cartridge is a high-yield version capable of substantially greater printing capacity. If that meaning is not captured correctly within the retailer’s product information, an AI system can struggle to answer a customer’s underlying requirement even though the correct product exists in the catalogue.

Reviews and customer questions can become important as well. A shopper asking for a highly rated product, or one that performs well under a particular set of conditions, is requesting information that may sit within thousands of customer reviews rather than conventional catalogue fields. Retailers therefore need ways of making that unstructured information accessible to recommendation and discovery systems. The potential consequence is a shift from traditional search-engine optimisation towards a broader effort to make products understandable to AI systems. The objective is no longer simply achieving a prominent position in search results. Retailers increasingly need their products to be selected when an external AI assistant reduces hundreds or thousands of possibilities to a handful of recommendations.

That reduction in choice makes assortment strategically important. In conventional online retail, consumers can browse pages of results. An AI assistant may present only several products. If the retailer does not have an item closely matching the consumer’s increasingly precise requirements, it may disappear from consideration before the customer ever reaches its website. Mirakl argued that large catalogues can therefore become more valuable rather than less valuable in an AI-led discovery environment, provided the underlying product information is sufficiently strong. A broad assortment gives the system a greater chance of finding an exact match for increasingly detailed customer requirements.

This also has implications for online marketplaces. Marketplaces historically benefited from aggregating supply and allowing consumers to compare products within one destination. AI assistants can perform part of that aggregation externally, potentially comparing products across several marketplaces, retailers and brands simultaneously. The retailer’s challenge consequently becomes twofold: it needs to be selected by external agents while also developing a sufficiently useful internal experience that customers have a reason to begin future searches directly with the retailer. That tension may become one of the defining competitive battles in e-commerce.

Retailers including Nordstrom are already seeing referral traffic originating from generative AI services, although conventional search and digital advertising remain much larger sources of traffic. The significance lies less in today’s absolute volume than in what happens if consumers become comfortable beginning commercial searches through AI. The economics of customer acquisition could change substantially. Search engines, social networks and marketplaces have built enormous advertising businesses around controlling the point where consumers discover products. If AI assistants capture a meaningful share of that activity, retail marketing budgets may eventually follow them.

For the moment, some AI-generated referrals can reach retailers without the same established advertising economics associated with traditional search marketing. It would be risky, however, for retailers to assume that this will remain permanently free. As AI platforms become more important to commercial discovery, new advertising, referral, commission or transaction models are likely to develop. This makes direct customer relationships increasingly valuable. A retailer that receives a customer from an external AI platform has an opportunity to persuade that shopper to use its own search, recommendation or shopping assistant in the future rather than repeatedly relying on an intermediary.

Once consumers arrive on the retailer’s website, AI is also changing how products are recommended. Traditional recommendation engines frequently relied on historical behaviour processed through scheduled batch systems. More advanced models can interpret sequences of behaviour including products viewed, items placed into baskets, previous purchases and the timing of those actions. That can provide a better indication of purchasing intent. A consumer who has researched one category repeatedly over several weeks may require a different recommendation strategy from someone making an impulse purchase. AI can potentially distinguish between those contexts and adjust recommendations accordingly.

Conversational commerce is also returning in a more capable form. Retailers experimented with chatbots and virtual shopping assistants long before the current generative AI cycle, but the systems were often constrained by predetermined questions and limited product knowledge. Generative AI allows customers to communicate in much more natural language. The opportunity is particularly significant for retailers with large assortments. Instead of navigating extensive menus and filters, consumers can describe what they need. For the retailer, those conversations provide another valuable source of information because they reveal how customers naturally think about products.

A conventional filter might tell a retailer that a customer selected a colour, price range and size. A conversational request can reveal that the customer is attending a birthday party, starting a new job, renovating a kitchen or buying a gift. That context can improve merchandising and product development as well as recommendations. Yet the panel repeatedly returned to a less glamorous requirement underlying these experiences: data.

Retailers have accumulated information across decades of store systems, e-commerce platforms, loyalty programmes, supply chains, merchandising tools and point-of-sale systems. Much of it remains fragmented, duplicated or difficult to reconcile. Generative AI cannot automatically transform inconsistent information into reliable commercial decisions. According to CI&T, data modernisation is consequently becoming one of the most important areas of AI-related investment among large retailers and brands. Companies are consolidating information, improving context and connecting previously isolated datasets before attempting more sophisticated customer-facing applications.

The reason becomes obvious when AI begins making recommendations. A conversational shopping system may appear impressive while still failing basic retail tests. Mirakl described testing a retailer’s AI shopping experience and finding that products presented by the system frequently did not correspond with the retailer’s established best sellers. In another test, a customer request specifying a maximum budget produced recommendations whose average price was substantially above the stated limit. These failures demonstrate that sophisticated language capability does not replace retail fundamentals. The right product still needs to be offered at the right price, with accurate availability and realistic delivery information.

This becomes even more important when the AI system rather than the consumer is evaluating the alternatives. If an external assistant receives an incorrect price, outdated stock position or incomplete product specification, it can remove the retailer from consideration before the customer sees the offer. Inventory accuracy and substitution therefore become part of AI readiness. If a recommended product is unavailable, the retailer needs sufficiently rich product information to provide an appropriate alternative. Sizing, compatibility, delivery dates and location-specific availability all need to remain synchronised across channels.

Trust consequently moves earlier in the purchasing journey. Historically, retailers earned much of their trust after the customer had chosen a product: the item arrived as described, delivery occurred on time and problems were resolved effectively. AI-assisted commerce requires some of that trust before the purchase because consumers increasingly rely on automated recommendations to decide what they should buy. The panel argued that transparency will be important. Consumers should know when they are communicating with an AI system rather than discovering this after believing they were speaking with a person. Accuracy is equally important. A retailer cannot easily blame an external AI assistant when the price displayed to a customer differs from the price available at checkout. The customer ultimately associates the failed experience with the brand selling the product.

Post-purchase service represents another major application. AI agents can increasingly handle routine questions involving delivery status, returns, product information and compatibility without requiring customers to navigate telephone menus or wait for an employee. The potential extends beyond simple order tracking. If the retailer has a sufficiently detailed knowledge structure around its products, an AI service agent can potentially answer technical questions about whether a purchased component works with another product or explain how something should be used.

The next stage is agentic commerce, where AI moves from advising consumers towards taking actions for them. Predictions about how quickly fully autonomous shopping will develop varied considerably across the panel. Some participants expect agent-to-agent transactions to emerge relatively quickly in repetitive categories, while others believe consumer commerce could remain primarily focused on AI-assisted discovery for years. The distinction between categories is important. Consumers may readily allow an AI agent to reorder milk, household supplies or other frequently purchased goods within predetermined spending limits. Allowing the same system to autonomously select a wedding outfit, luxury product or other emotionally significant purchase requires a very different level of trust.

This suggests that agentic commerce will not arrive uniformly across retail. Business-to-business commerce may provide an earlier proving ground. AI agents can already assist with demand forecasting and routine ordering between companies where purchasing rules, product specifications and approved suppliers are clearly defined. Subscription-style consumer purchases could follow a similar model. Even in a world of autonomous agents, loyalty is unlikely to disappear. An AI assistant acting for a consumer can incorporate that consumer’s existing memberships, rewards, preferences and retailer relationships into its decisions. A customer who repeatedly shops with one retailer may instruct an agent to favour that company even when another seller offers a marginally lower price.

That means brands and retailers still need differentiation beyond price. If autonomous systems can compare thousands of offers almost instantly, competing purely on product availability could become increasingly difficult. Loyalty programmes, service quality, trust and exclusive assortment may become more important rather than less. Payments and fraud prevention will also need to evolve. Retailers must be able to determine whether an automated agent has legitimate authority to make a purchase on behalf of a customer, while payment networks need mechanisms for authenticating those transactions. Work on agent-authorised payments is already developing across the financial and technology industries, but mainstream adoption will require confidence that automated transactions can be controlled, disputed and audited.

Retailers simultaneously face the operational problem of scaling AI. A demonstration involving several products can work convincingly while an enterprise deployment covering millions of customers, locations and product combinations fails because of latency, cost or inconsistent data. The panel cautioned against assuming that the largest or most sophisticated model will necessarily produce the best commercial result. Search and recommendation systems operate in an environment where response speed directly affects conversion. A highly accurate model that takes too long to produce results may generate worse commercial performance than a simpler model capable of responding almost immediately.

The strategic question is therefore moving away from who has the most advanced AI model. Foundation models are becoming increasingly accessible. Competitive advantage is more likely to emerge from proprietary product information, customer understanding, operational data and the infrastructure connecting those assets. For large retailers, that changes the investment priority. The visible AI shopping assistant may attract customer attention, but the more valuable work can be happening underneath it: rebuilding product information, connecting inventory, modernising data infrastructure, establishing governance and creating systems that can deliver consistent information to websites, stores, external AI assistants and future autonomous agents.

The transition also has implications for physical retail. AI-led commerce does not necessarily mean the disappearance of stores. In categories where customers want to touch, try or experience products, physical locations can remain central to the relationship even if AI performs much of the initial research. Instead, AI could make the boundaries between digital and physical retail less important. A customer might begin with an AI conversation, visit a store to evaluate a product, complete the purchase digitally and subsequently use another automated agent for service.

The larger transformation is therefore not the replacement of the e-commerce funnel but its fragmentation across more interfaces. For the past two decades, retailers invested heavily in attracting consumers to websites and applications where they controlled search, merchandising, recommendations and checkout. AI assistants threaten to move some of those functions outside the retailer’s own environment. That creates a new competitive question. Retailers must decide whether they primarily want to supply products to other companies’ AI agents or become trusted AI destinations themselves.

The companies best positioned for either outcome may not be those with the most impressive chatbot. They are likely to be those with the cleanest product information, most accurate inventory, strongest customer relationships and infrastructure capable of exposing that information consistently wherever the purchasing decision takes place. AI may eventually allow software agents to negotiate and purchase products without consumers visiting a conventional online store at all. But the more immediate transformation is already simpler and commercially significant: customers are becoming accustomed to describing what they want rather than searching for it.

That changes the route to conversion. And as control over product discovery begins to move away from search engines and retailer websites, the battle over who owns the customer relationship is entering a new phase.

Source: CIJ.World Research & Analysis Team

International hotel brands expand in Bucharest as development pipeline builds

Bucharest is heading into a significant period of hotel development, with a series of internationally branded properties scheduled to open over the next several years as investors respond to stronger accommodation revenues and continued growth in visitor demand. The latest market assessment from Cushman & Wakefield Echinox puts the development pipeline through 2028 at more than 1,500 rooms. Earlier estimates during 2026 had placed the potential expansion above 2,000 rooms, indicating that delivery schedules and individual projects continue to evolve as developments move through planning, construction and financing.

Despite differences between current pipeline estimates, the direction of the market is clear. Bucharest is attracting new investment across several hotel categories, with much of the planned development concentrated in the higher-quality branded segment. Among the projects expected to reshape the market are Hyatt Place and Hyatt House at Nusco City, Mondrian Bucharest, Swissôtel Bucharest, The Julius Bucharest, Wyndham Garden and additional hotel developments associated with established mixed-use and commercial property projects.

The Hyatt development at Nusco City is planned with 270 rooms across two hotel concepts, while Mondrian Bucharest is expected to contain just over 100 rooms. Several other projects are undergoing development or repositioning, although room numbers and expected opening dates vary between current industry sources as individual schemes progress. New accommodation is already entering the market, with Hilton Garden Inn Militari among the properties scheduled to open during 2026, while Mercure Bucharest Cantemir has recently added further internationally branded capacity close to central Bucharest.

The expansion follows several years of improving hotel performance. During the first half of 2026, revenue generated per available room increased by 5% compared with the corresponding period of 2025 and remained around a quarter above its level during the first half of 2019. Higher room prices have been an important part of that improvement. Average daily rates during H1 2026 increased from the previous year and remained considerably above their pre-pandemic level. Occupancy has also continued to recover, although it has yet to move materially beyond the levels recorded before the pandemic.

The pattern suggests that Bucharest’s hotel recovery has increasingly been supported by operators’ ability to achieve higher room prices rather than simply filling substantially more rooms. That will become an important consideration as new capacity enters the city. The hotel development cycle is also broadening Bucharest’s institutional property market, as international brands and larger professionally operated properties can create assets more suited to hotel investors seeking scale, established operators and recognisable operating formats.

Transaction activity has already begun to recover. Hotel deals in Bucharest reached approximately EUR 46.3 million during 2025 according to Cushman & Wakefield Echinox, considerably above the previous year’s level. Transactions included the two-property Duke hotel portfolio and Hilton Garden Inn Bucharest Airport.

The wider Central and Eastern European hotel investment market has also become more active, supported by improving operating performance and better financing conditions. Regional investors continue to account for an important part of transaction activity, while international capital remains focused primarily on properties with established income and locations capable of supporting long-term demand.

Bucharest’s development pipeline is increasingly linked to larger real estate projects rather than solely traditional standalone hotels. Nusco City is bringing hospitality into a mixed-use development, while other planned hotels are connected with retail, residential or urban regeneration projects. This creates another route for developers to diversify large schemes while introducing international operators into new areas of the capital.

The next phase will depend on whether accommodation demand expands sufficiently to absorb the additional rooms. More supply will provide visitors with greater choice and increase the number of internationally operated properties available in the city, but it will also require hotel operators to protect occupancy and room rates as competing projects open.

Bucharest nevertheless enters this development cycle from a stronger operating position than before the pandemic. Room revenues remain substantially above 2019 levels, tourism demand has recovered and a growing group of international operators and property investors is committing capital to the city.

Rather than a simple increase in hotel capacity, the development pipeline therefore represents a broader change in Bucharest’s hospitality property market. The city is gaining more branded and investment-oriented hotel stock, potentially increasing its relevance to institutional and cross-border property investors as the new projects reach completion.

Poland introduces new board composition rules for large listed companies

New corporate governance requirements affecting some of Poland’s largest publicly traded companies have entered into force, introducing targets for gender representation on management and supervisory boards as well as changes to board recruitment, reporting and internal policies. The Polish legislation implementing the EU’s Women on Boards Directive has applied since 18 August 2026 and covers large companies whose shares are traded on an EU regulated market and which meet specified employment and financial thresholds.

Companies within the scope of the legislation must employ at least 250 people and have annual turnover exceeding EUR 50 million or a balance sheet total above EUR 43 million. Smaller companies are excluded from the requirements. The changes could affect a range of publicly listed businesses connected with Poland’s real estate and construction sectors, depending on whether individual companies meet the size and listing criteria.

One of the central requirements concerns representation within company governing bodies. Businesses covered by the legislation are expected to work towards having the less represented gender occupy the number of positions closest to 33% of all management and supervisory board seats. Representation is also required across both types of governing body rather than being concentrated entirely within one.

The legislation also changes the procedures companies use when appointing directors and supervisory board members. Businesses covered by the rules will need to establish selection criteria before recruitment begins, with candidates assessed according to clearly defined and non-discriminatory requirements. Where two candidates have equivalent qualifications, preference is generally to be given to the candidate belonging to the gender that is less represented within the company’s governing bodies.

This places greater importance on documenting how board candidates are assessed and how final appointment decisions are reached. Companies may therefore need to review existing nomination procedures and establish clearer records demonstrating that appointments have been conducted according to the new requirements.

Affected companies will also have to introduce a formal policy addressing gender representation. This is expected to cover areas including career development, the process for identifying potential board candidates and relevant aspects of human resources planning. The policy must also be made publicly available through the company’s website.

The requirements consequently extend beyond the final composition of management and supervisory boards. Companies may need to review succession planning, nomination procedures, internal governance documents and the records used to demonstrate how board appointments were made.

Regular disclosure will form another part of the new framework. Companies will have to provide information about the representation of women and men within their governing bodies and describe measures being taken to achieve the required balance.

Poland’s Financial Supervision Authority, KNF, will oversee certain elements of compliance. Financial penalties of up to PLN 500,000 may be imposed for specified breaches of the requirements. Candidates participating in board selection procedures will also receive additional protections and, depending on the circumstances, may be able to pursue claims where appointment procedures did not comply with the new selection rules.

For large listed companies, the immediate impact is therefore likely to be felt as much in corporate governance procedures as in the eventual composition of their boards. Businesses will need to establish whether they fall within the legislation, assess their existing management and supervisory structures and determine whether nomination and succession procedures meet the new standards.

For Poland’s publicly traded real estate and construction companies that meet the thresholds, the changes add another layer of governance requirements at a time when investors are placing increasing attention on the composition, independence and oversight of corporate boards.

Source: CMS

front page info
LATEST NEWS