Fabryka Mebli AKORD relocates main warehouse to MLP Teresin logistics center

Fabryka Mebli AKORD has signed a lease agreement for approximately 21,800 square meters of modern warehouse space at the MLP Teresin logistics center. The move marks a significant expansion for the Polish furniture manufacturer, which will use the facility as its main warehouse alongside its existing distribution centers in Germany and France. The decision to relocate was influenced by the availability of high-storage capacity, which is expected to improve logistics efficiency and support the company’s continued growth in European markets.

Under the lease terms, Fabryka Mebli AKORD will receive early access to the warehouse in April 2025, with full handover scheduled for September. Of the total leased space, around 21,200 square meters will be dedicated to storage, while the remainder will be used for office and social facilities. The transaction was facilitated by AXI IMMO.

Founded in 1995, Fabryka Mebli AKORD specializes in modern, e-commerce-ready furniture, offering a range of products for living rooms, offices, bedrooms, and kitchens. The company emphasizes fast order fulfillment, maintaining a 99% product availability rate and ensuring rapid delivery times, often within 24 hours. The relocation to MLP Teresin is expected to enhance its logistics operations and improve service efficiency for its growing customer base.

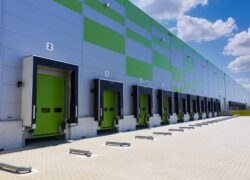
The MLP Teresin logistics center spans approximately 38,000 square meters on a 10-hectare site in Gnatowice Stare, 45 kilometers west of Warsaw. It offers direct access to Route 92, which connects Warsaw and Poznań, and is near the A2 motorway and the Wiskitki junction, ensuring strong transport links. The facility is designed to meet high technical standards, featuring reinforced flooring, multiple loading docks, and a spacious maneuvering area.

MLP Group, which owns and manages the logistics center, has been developing and retaining logistics parks under a build-and-hold strategy. The company focuses on providing flexible, tenant-oriented solutions, ensuring that facilities meet the evolving needs of their clients. The relocation of Fabryka Mebli AKORD to MLP Teresin aligns with this approach, offering modern infrastructure tailored to the requirements of a growing manufacturer in the furniture sector.

Executives from both companies have highlighted the advantages of the partnership. Agnieszka Góźdź, Member of the Management Board and Chief Development Officer at MLP Group S.A., emphasized that the agreement reflects the strong alignment between MLP Teresin’s capabilities and Fabryka Mebli AKORD’s expansion plans. Władysław Zając, owner of Fabryka Mebli AKORD, noted that the facility’s high-storage capacity and modern infrastructure will optimize logistics processes and enhance service efficiency.

The transaction also received support from AXI IMMO, whose Senior Advisor, Rafał Jełowicki, pointed to the facility’s proximity to Fabryka Mebli AKORD’s existing factory, allowing for smooth logistics integration and workforce retention. He also highlighted the flexibility of the space and the developer’s ability to accommodate the company’s technical requirements.

The relocation represents a strategic move for Fabryka Mebli AKORD, reinforcing its position in the European furniture market and enhancing its operational efficiency as it continues to expand.
King Cross Zagreb reopens first renovated section amid major modernization effort

King Cross Zagreb has reached a significant milestone in its ongoing redevelopment, with the reopening of the first fully renovated section of the shopping center on February 27. The refurbishment is part of a broader modernization plan led by SES, the owner and operator of the mall, which is investing more than EUR 40 million to upgrade the entire complex. The transformation is set to be completed by fall next year, with improvements being carried out in phases to allow the center to remain open throughout the process.

The renovation project includes a comprehensive upgrade of technical infrastructure, enhanced parking facilities, and modernized retail spaces. SES aims to position King Cross Zagreb as one of the most advanced shopping destinations in Croatia, offering an improved customer experience with contemporary design and upgraded amenities. The work is being carried out while ensuring that day-to-day operations continue, minimizing disruption for visitors and retailers.

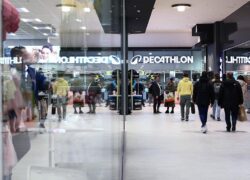
The first phase of the reopening introduces several new anchor tenants. Müller Drogerie, a well-known retailer, has opened a new location, and fashion brand Sinsay has also joined the center’s retail mix. One of the key highlights of this phase is the launch of Croatia’s largest and most modern Decathlon store, which serves as a flagship for the sporting goods brand. The redesigned store offers an updated layout, expanded product range, and an improved shopping experience tailored to the needs of sports and outdoor enthusiasts.

Further phases of the refurbishment will see additional enhancements across the shopping center, including upgraded common areas, improved energy efficiency, and new retail offerings. SES is focused on elevating King Cross Zagreb’s status as a leading retail destination in the region, ensuring that the shopping center meets the evolving expectations of both consumers and retailers.

The modernization of King Cross Zagreb reflects a broader trend in the retail sector, where shopping centers are adapting to changing consumer habits by investing in upgraded facilities, improved accessibility, and a more engaging retail environment. With the completion of the project next year, King Cross Zagreb is expected to solidify its position as a premier shopping and leisure destination in Croatia.

PohlCon GmbH expands in Northern Germany with new logistics property in Lüneburg

Logivest has brokered the lease of a 2,700-square-metre logistics property in Lüneburg to PohlCon GmbH. The property, located at Elso-Klöver-Straße 9 – 9a, is owned by the local Porth Group.

PohlCon GmbH, an international construction industry company, sought a location in northern Germany with modern office facilities and an efficient delivery area. The property includes a 2,300-square-metre warehouse and 400 square metres of office space. Features such as a ground-level roller shutter door over four metres wide, a floor load capacity exceeding five tonnes, and ample exterior space align with the company’s operational needs.

The site offers direct access to the B209 and B216 federal highways, as well as proximity to the A39 motorway, ensuring convenient connections to Hamburg and Bremen. “Lüneburg is becoming increasingly relevant for the logistics real estate market in northern Germany,” said Marvin Hesse, Head of Industrial & Logistics Letting at Logivest. He highlighted the area’s multimodal connectivity, including the Lüneburg port, the Hamburg-Hanover railway line, and regional motorway links.

PohlCon GmbH is expected to take occupancy of the property in May 2025.

INTREAL reports moderate growth in fourth quarter of 2024

IntReal International Real Estate Kapitalverwaltungsgesellschaft mbH (INTREAL) recorded steady growth in the final quarter of 2024 despite a challenging market environment. The company’s assets under administration (AuA) reached approximately €66.6 billion by 31 December 2024, reflecting a year-over-year increase of €909 million (1.4%). Compared to the nine-month figures of 2024, AuA grew by €171 million (0.3%).

At the end of the year, INTREAL managed 321 funds, up from 305 in 2023. The number of properties under administration increased by 76 over the year, reaching a total of 2,737, with 20 added in the fourth quarter. The company’s workforce expanded slightly, with 528 employees across its offices in Hamburg, Frankfurt, and Luxembourg (2023: 520 employees).

Camille Dufieux, Managing Director of INTREAL, described the company’s 2024 performance as stable despite market challenges. He noted that while recovery in the real estate market has been gradual, activity is expected to increase in 2025. Institutional investors remain focused on indirect real asset investments, with growing transaction volumes suggesting a narrowing gap between buyer and seller price expectations. Dufieux also pointed to recent interest rate developments as a potential positive factor for real estate fund investments.

The Partner Funds division remained INTREAL’s largest business unit, managing 156 funds with AuA of approximately €36.2 billion, accounting for 54% of the company’s total AuA. The division’s AuA increased by €118 million in the fourth quarter and €848 million over the full year. This unit provides fund administration services to asset managers and property developers without their own AIFM licenses.

The AIFM Services division managed 165 funds with AuA of approximately €30.4 billion at the end of 2024, adding 14 new funds over the year. This division provides administrative support to licensed AIF management companies, including reporting, fund accounting, and risk management.

INTREAL expects stable demand for its services in 2025, with continued investor interest in real estate fund structures and administrative solutions.

KINGSTONE Real Estate appoints new leadership for advisory board

KINGSTONE Real Estate (KRE) has announced changes to the leadership of its advisory board. Benedikt Gabor, head of the real estate department at Nordrheinische Ärzteversorgung, has been appointed as chairman, succeeding Dr. Eckart John von Freyend, whose term has ended. Martin Führlein, CEO of Pegasus Capital Partners, has joined the advisory board and will serve as deputy chairman.

The advisory board, established in 2019, provides strategic guidance to KRE. Gabor, who had been deputy chairman since 2023, will continue to oversee the German institutional investors segment. His previous roles include positions at Deutsche Rückversicherung AG, VöV Association of German Public Insurers, Catella Real Estate AG, and Deutsche Immobilien Leasing GmbH.

Führlein, taking on the deputy chairman role, brings extensive capital markets experience. In addition to leading Pegasus Capital Partners, he serves on the Supervisory Board of PSD Bank Nürnberg eG and has previously held board positions at GRR AG and GRR Real Estate Management.

KRE’s Managing Partner, Dr. Tim Schomberg, acknowledged the contributions of the outgoing chairman: “We appreciate Dr. Eckart John von Freyend’s leadership and support over the years. We look forward to continuing our collaboration with Benedikt Gabor in his new role and welcome Martin Führlein to the board.”

Other members of the KRE advisory board include Andreas von Buttlar, CEO and founder of Spinone Equity; Prof. Dr. Kerstin Hennig, head of the FS Real Estate Institute at the Frankfurt School of Finance & Management; and Philipp Wehle, former CFO of Global Wealth Management at Credit Suisse.

Major developments and investments reshape London’s office market

The London office market in 2025 is undergoing significant transformations, characterized by strategic shifts among major property owners, evolving tenant preferences, and a dynamic investment landscape.

Landsec, one of the UK’s leading commercial landlords, has announced a strategic pivot from traditional office investments to residential properties. The company plans to divest £2 billion worth of office assets, reducing its office holdings from 65% to approximately one-third of its £10 billion portfolio by 2030. This move aligns with broader industry trends favoring sectors like housing, which offer steady, inflation-linked income streams. Despite maintaining a 98% occupancy rate in its office spaces, Landsec aims to prioritize income growth and mitigate exposure to market cycles by focusing on major residential projects in areas such as Lewisham, Manchester, and North London.

Tenant demand is increasingly polarized, with a pronounced shift towards high-quality, sustainable office spaces. Over 60% of current space under offer comprises newly built or refurbished properties, reflecting tenants’ preferences for modern amenities and flexible layouts. Conversely, lower-quality office spaces face elevated vacancy rates, prompting landlords to consider refurbishments or conversions to alternative uses. This trend underscores the critical role of quality and sustainability in leasing decisions, ensuring continued activity in the Grade A segment.

The investment market is showing signs of recovery, with Central London office investment volumes increasing in January, bringing the 12-month total 16% above the same period last year. Notably, Axa IM Alts has submitted plans for a new 46-storey skyscraper at 63 St Mary Axe, estimated at over £750 million, marking its third skyscraper project in London since the pandemic. This development aims to meet the demand for high-quality office spaces, featuring advanced facilities and eco-friendly features, with completion projected for the 2030s.

Additionally, Aware Super, one of Australia’s largest pension funds, plans to invest up to £1 billion in London’s office sector in partnership with property group Delancey. This move is seen as a significant vote of confidence in the sector amidst high interest rates and uncertainties around post-pandemic demand.

Looking ahead, the London office market is expected to maintain its momentum in 2025, driven by a flight to quality as occupiers seek more space rather than less. Modern occupiers desire ESG-aligned office spaces with terraces and high-quality amenities, leading to intense competition for the best assets, with tenants prepared to pay premium rents. However, challenges persist, including elevated vacancy rates for lower-quality stock and stricter EPC regulations requiring minimum ratings of C by 2027 and B by 2030, which will pressure landlords to refurbish or retrofit their properties. This regulatory landscape, combined with hybrid working patterns, is expected to widen the gap between Grade A and Grade B spaces, further reinforcing the two-tier market.

In summary, the London office market in 2025 is characterized by strategic repositioning among major landlords, a clear tenant preference for high-quality, sustainable spaces, and a cautiously optimistic investment environment, all of which are reshaping the future of the city’s commercial real estate landscape.

Sources: FT and The Times

London office market rebounds with strong leasing activity amid supply constraints

The London office market experienced a notable resurgence in the latest quarter, with leasing activity reaching 2.87 million sq ft, marking a 30.45% increase quarter-on-quarter. This significant growth reflects a rebound in occupier demand, particularly for high-quality Grade A spaces. However, despite the uptick in activity, the figure remains 4.33% below the 10-year quarterly average of 3.0 million sq ft, underscoring the lingering impact of macroeconomic uncertainty and hybrid working patterns.

A key factor behind this leasing revival is the sustained flight to quality, as businesses continue to prioritize modern, sustainable, and well-located office spaces. Both the City and West End submarkets remain at the forefront of this trend, with occupiers seeking premium office environments that align with ESG commitments and evolving workplace expectations.

While challenges such as hybrid work models and stricter EPC (Energy Performance Certificate) regulations persist, a tightening supply of newly built and refurbished spaces has supported rental growth. This supply-demand imbalance, coupled with growing investor confidence, is fostering a cautiously optimistic outlook for 2025.

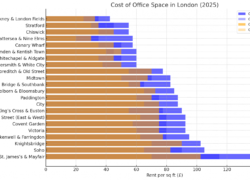
The limited availability of best-in-class office spaces has driven further increases in London’s prime office rents, with the West End core reaching £150 per sq ft—a new benchmark for the area. Other key submarkets also recorded growth, with the City at £85 per sq ft, while Shoreditch and Victoria saw their rental rates rise in response to demand.

By the end of 2024, prime rents across London continued their upward trajectory, supported by sustained occupier demand and a lack of premium stock. In the City core, prime rents edged up to £87.50 per sq ft, while Farringdon and Midtown recorded £95 per sq ft and £80 per sq ft, respectively.

These trends illustrate the emergence of a two-tier market, where demand for sustainable, high-quality spaces continues to drive rental appreciation, while lower-grade stock faces increasing pressure to modernize and align with evolving occupier preferences. As businesses place greater emphasis on ESG credentials and premium amenities, landlords of secondary office spaces must consider significant refurbishments or risk prolonged vacancies.

The financial sector emerged as the dominant force in London’s office market, accounting for 31% of total take-up in the most recent quarter. This was bolstered by major transactions such as Legal & General’s pre-let of 186,648 sq ft at Woolgate, EC2, demonstrating the industry’s ongoing commitment to securing prime, sustainable office locations.

The professional services sector followed closely, contributing 29% of total take-up. A standout transaction in this segment was BDO LLP’s 218,496 sq ft lease at The M Building, which marked the largest-ever letting in Marylebone and reinforced the sector’s preference for high-quality, centrally located developments.

The Technology, Media, and Telecommunications (TMT) sector remained a key driver of demand, accounting for 15% of overall leasing activity. Meanwhile, the public sector maintained its steady presence in the market, representing 8% of total take-up.

As London’s office market enters 2025, the flight to quality will continue to shape demand, with occupiers favoring buildings that offer top-tier sustainability credentials, premium amenities, and strategic locations. While challenges such as rising operating costs, regulatory pressures, and evolving workplace dynamics remain, the market is expected to maintain strong momentum, particularly in the prime and newly developed office segments.

With a tightening supply of premium office stock and increasing rental growth in core submarkets, landlords and investors who adapt to shifting occupier preferences will be best positioned to capitalize on London’s evolving commercial real estate landscape.

Source: oktra

Commercial Real Estate in 2025: Navigating Market Shifts and Financial Pressures

The commercial real estate (CRE) market is entering 2025 under significant pressure, facing a landscape shaped by rising interest rates, shifting work dynamics, and financial uncertainty. While the sector has already endured a period of turbulence, experts predict that the full impact of CRE loan losses will materialize gradually over the coming years rather than in a sudden crash. This slow unfolding of challenges will be influenced by economic factors, refinancing hurdles, and evolving investor sentiment.

Mounting Refinancing Challenges

One of the biggest concerns looming over the CRE market in 2025 is the wave of loan maturities set to come due. Many borrowers will be forced to refinance under financial conditions that are much less favorable than when their original loans were secured. Interest rates have risen significantly, making it unlikely that new financing will match the low-cost debt that fueled the sector’s expansion in previous years.

This situation presents a double challenge for property owners. Higher borrowing costs mean increased debt service, which could squeeze already tight cash flows. Additionally, lenders have become more selective, with many tightening credit standards or reducing exposure to certain CRE asset classes, particularly office properties. For some borrowers, access to refinancing may be limited or unavailable, increasing the risk of loan defaults and distressed asset sales.

Office Real Estate Faces Uncertain Future

Among the most vulnerable segments of the CRE market is the office sector. Despite some stabilization in demand for high-quality, well-located office spaces, the industry continues to grapple with the long-term effects of remote and hybrid work models. Many employees have yet to return to traditional office environments, leaving a significant portion of older office buildings underutilized or even obsolete.

The bifurcation in the office market is becoming more pronounced. Premium, modern office spaces with amenities that cater to evolving workforce preferences continue to attract tenants. However, older and less adaptable buildings face declining occupancy rates and falling valuations. With investors and lenders becoming more cautious about underwriting office loans, property owners of these struggling assets could face increasing financial distress.

The Impact of High Interest Rates and Valuation Adjustments

The sustained period of elevated interest rates has fundamentally altered the investment landscape for commercial real estate. Higher borrowing costs not only make refinancing difficult but also put downward pressure on property valuations. This is particularly evident in sectors that were already struggling with weaker fundamentals, such as office and certain retail assets.

As valuations adjust to the new interest rate environment, property owners and investors must navigate a changing market where deals that once made financial sense may no longer be viable. Cap rates have been rising across several asset classes, forcing sellers to either accept lower prices or hold onto properties in hopes of a future market rebound. Meanwhile, investors are taking a more cautious approach, focusing on assets with strong income potential and resilient demand drivers.

Where Are the Bright Spots?

Despite the challenges facing the broader CRE market, certain sectors are showing signs of resilience and even growth. Industrial real estate continues to benefit from strong demand driven by e-commerce, logistics, and supply chain expansion. Data centers, fueled by the increasing need for cloud computing and AI-driven infrastructure, are also attracting significant investor interest.

The multifamily sector, while facing its own set of affordability and regulatory challenges, remains a favored asset class for many institutional investors due to the persistent demand for rental housing. Similarly, niche property types such as life sciences facilities and medical office buildings are proving to be more insulated from the broader market downturn.

Outlook for 2025 and Beyond

Looking ahead, commercial real estate in 2025 will be shaped by a combination of economic forces, policy decisions, and evolving market dynamics. The ability of the sector to “weather the storm” will depend on how borrowers, investors, and lenders adapt to the new financial realities. While some distress is inevitable, it is also likely to create opportunities for well-capitalized players to acquire assets at attractive valuations.

The key themes for 2025 will revolve around refinancing risk, shifting property values, and the continued evolution of the office sector. Investors and market participants who can navigate these complexities strategically will be best positioned to capitalize on the opportunities that emerge in the next phase of the CRE cycle.

Source: comp.

Women in Master’s and PhD Studies in the EU: A Closer Look at Gender Representation

In 2022, women accounted for a significant majority of students pursuing master’s degrees across the European Union, while their representation at the doctoral level remained slightly below parity. According to recent data, out of 1.5 million master’s students in the EU, 905,678 were women, making up 58.6% of the total. At the doctoral level, however, female students represented 48.5% of the 99,204 enrolled candidates.

Women Dominate Master’s Studies in Most EU Countries

Women formed the majority of master’s students in nearly all EU countries, with one exception—Luxembourg—where gender parity was observed, with women making up 49.8% of students. The highest proportions of female students at this level were recorded in Cyprus (74.2%), Poland (67.3%), and Lithuania (66.1%).

At the doctoral level, gender representation varied significantly across member states. The lowest shares of women in PhD programs were recorded in Luxembourg (42.3%), Austria (43.3%), and Czechia (44.1%). In contrast, the highest proportions were found in Latvia (59.6%), Cyprus (58.0%), and Lithuania (57.4%).

Trends Over the Past Decade

Between 2013 and 2022, the proportion of women in master’s studies across the EU saw a slight decline of 0.4 percentage points. This drop was driven by decreases in 12 EU countries, with Latvia (-3.4 pp) and Hungary (-3.6 pp) registering the most significant reductions.

Conversely, the representation of women in doctoral programs rose by 1.0 percentage point over the same period, with 19 EU countries experiencing an increase in female PhD students. Cyprus recorded the most notable growth, with an 8.0 percentage point rise between 2013 and 2022.

Education: A Leading Field for Women

In terms of academic disciplines, women were overwhelmingly represented in education studies, comprising 75.6% of master’s students and 66.9% of doctoral students in 2022.

At the master’s level, other fields with a high proportion of female students included generic programs and qualifications (73.7%), arts and humanities (69.5%), and social sciences, journalism, and information (68.7%).

For doctoral studies, the most popular fields among women after education were health and welfare (60.9%), agriculture, forestry, fisheries, and veterinary sciences (57.5%), social sciences, journalism, and information (57.3%), and arts and humanities (53.3%).

Persistent Gender Gaps in STEM Fields

Despite their strong presence in education and social sciences, women remained underrepresented in STEM fields. In information and communication technologies (ICT), women accounted for just 26.2% of master’s students and 22.6% of PhD candidates. Similarly, in engineering, manufacturing, and construction, female representation stood at 33.4% at the master’s level and 32.7% at the doctoral level.

As efforts to bridge the gender gap in higher education continue, these figures highlight both the progress and the persistent disparities in academic fields across Europe.

Source: Eurostat

Czech employment rate rises to 75.6% in January 2025 while unemployment drops to 2.7%

The employment rate in the Czech Republic reached 75.6% in January 2025, reflecting a 0.1 percentage point increase compared to the same period in 2024, according to data from the Czech Statistical Office. The male employment rate stood at 81.1%, while the female employment rate was 69.8%.

The general unemployment rate, measuring the proportion of unemployed individuals within the economically active population, was 2.7% in January 2025. This marks a year-on-year decrease of 0.3 percentage points. The unemployment rate for both men and women remained equal at 2.7%.

Dalibor Holý, Director of the Labour Market and Equal Opportunities Statistics Department at the Czech Statistical Office, noted that the labour market remains stable, with the employment rate benefiting from increased female workforce participation.

The economic activity rate, which measures the proportion of economically active individuals aged 15–64, stood at 77.5% in January 2025, representing a 0.3 percentage point decrease compared to the previous year. The male economic activity rate was 83.0%, exceeding the female rate of 71.7% by 11.3 percentage points.

The data presented in the report are seasonally adjusted and derived from the Labour Force Sample Survey (LFSS), which is conducted by a network of interviewers in households. The LFSS methodology differs from administrative data collected by the Labour Office of the Czech Republic on registered job applicants. The survey follows internationally recognized definitions set by the International Labour Organization (ILO), ensuring comparability with data across EU member states.

The Czech Statistical Office regularly submits LFSS data to Eurostat, which publishes monthly unemployment reports for EU countries. In the broader 15–74 age group, the unemployment rate in the Czech Republic was 2.6% in January 2025.

The survey is conducted exclusively in private households, excluding collective accommodation facilities and temporary shelters. Historical data on employment and unemployment trends, starting from 1993, are available in the accompanying tables.

Source: Czech Statistical Office

front page info
LATEST NEWS