Fitch Ratings Cuts Global Credit Outlook as Growth Slows

Fitch Ratings has lowered its global credit outlook in its mid-year update for 2025, citing a deteriorating growth environment driven by higher tariffs, policy uncertainty in the United States, and heightened geopolitical risks.

The agency now forecasts global real GDP growth at 2.2 percent in 2025, a sharp slowdown from 2.9 percent in 2024. Fitch said weaker trade flows and reduced investment confidence are weighing on global activity, with advanced economies particularly exposed to the impact of U.S. tariff measures.

“Global growth momentum is fading, and the risks are increasingly tilted to the downside,” the agency noted in the update released on July 2. Fitch highlighted that while some emerging markets continue to post stronger growth, the overall slowdown is broad-based and likely to pressure credit markets in the coming months.

The revised outlook comes amid concerns over U.S. fiscal and trade policy direction, coupled with geopolitical tensions that are adding to financial market volatility. Fitch warned that the weaker economic backdrop could translate into tighter financing conditions for both sovereign and corporate borrowers.

Despite these challenges, Fitch emphasized that most banking systems remain resilient, with capital buffers stronger than in previous downturns. However, the agency cautioned that prolonged uncertainty and sluggish growth could erode credit quality if the current trends persist.
Survey reveals persistent inequalities in European working conditions

A new pan-European survey has found that while job quality across Europe has generally improved over the past decade, sharp inequalities remain between men and women and among workers in different regions.

The European Working Conditions Survey 2024, conducted by Eurofound, draws on interviews with more than 36,000 workers in 35 countries and assesses seven dimensions of job quality. The results show progress in areas such as working time, skills development, and physical working environments, but highlight widening gender disparities in social relations at work, job intensity, and exposure to risks.

One of the clearest improvements has been a decline in excessively long working hours. The proportion of employees working more than 48 hours per week has fallen from 19 percent in 2005 to 11 percent in 2024. This has narrowed gender gaps in working time quality, with men now scoring at similar levels to women for the first time.

Workers also reported greater opportunities to apply and expand their skills, with the “skills and discretion” index showing the strongest gains. Men in particular have seen improvements in their physical work environment.

However, the survey found that women’s working conditions are worsening in other respects. The social environment at work has deteriorated for women since 2010, largely due to higher exposure to verbal abuse and other negative behaviours. Women are also more likely to work in high-intensity sectors such as healthcare and education, where frequent interruptions and emotional strain are common.

Other challenges include the rise of sedentary work, with 40 percent of Europeans reporting prolonged sitting during working hours. This figure is higher among women (42 percent) than men (39 percent).

Job security and financial predictability remain uneven across Europe. Although overall fear of job loss has declined, men continue to report better career prospects than women. Meanwhile, 15 percent of workers across Europe are unable to predict their income over the next three months, with uncertainty particularly acute in Romania and Greece, compared to more stable conditions in Austria and Germany.

Eurofound’s findings underline that while average job quality has improved, these gains are unevenly distributed. The agency concluded that policymakers must look beyond broad trends to address the vulnerabilities and inequalities that continue to shape working lives across Europe.

EU market production falls slightly in June

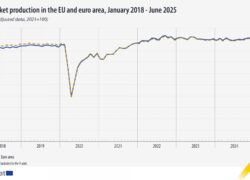
Market production in the European Union edged down in June 2025, according to Eurostat data released today. The Total Market Production Index (TMPI), which tracks industry, construction, trade, and services, declined by 0.2 percent in the EU compared with May, while the euro area recorded a sharper fall of 0.4 percent.

The decrease in the EU was largely driven by lower industrial production, which fell by 1.0 percent, alongside declines in construction (–0.5 percent) and services (–0.1 percent). Trade activity was the only component to grow, rising by 0.6 percent.

On an annual basis, however, market production remained in positive territory. Compared with June 2024, the TMPI increased by 2.2 percent in the EU and by 1.9 percent in the euro area.

The TMPI is a composite indicator under the European Business Statistics Regulation, combining data from short-term statistics across most of the market economy. It covers industry (mining, manufacturing, and energy), construction, trade (including motor vehicles, wholesale, and retail), and a broad range of services such as transport, accommodation, ICT, real estate, and professional and business support services.

While the index generally moves in line with GDP trends, Eurostat notes that differences in coverage and methodology can lead to divergences, particularly over longer periods.

Source: Eurostat – Total Market Production Index, June 2025.

Slovak Economy Grows 0.6% in Second Quarter, Slowest Pace in Over Two Years

Slovak Economy Grows 0.6% in Second Quarter, Slowest Pace in Over Two Years

Bratislava – Slovakia’s economy grew by 0.6 percent year-on-year in the second quarter of 2025, marking its slowest expansion in two and a half years, according to preliminary data. The modest increase was driven primarily by household and public sector consumption, while investment activity revived after a year of decline. However, weaker results in key economic sectors, notably real estate and construction, offset much of the positive momentum.

Gross domestic product (GDP) at constant prices reached €34.5 billion in the quarter, with growth remaining below one percent for the second consecutive quarter. After seasonal adjustment, GDP rose by 0.2 percent compared with the first quarter of 2025. Gross value added totaled €23.5 billion, essentially unchanged from the previous year.

Industry, the largest sector of the Slovak economy with a 17 percent share of total value added, grew by 2 percent year-on-year. Gains came from metal production, electrical equipment manufacturing, and transport equipment, while declines in machinery, equipment, and chemicals weighed on results. Trade, transport, accommodation, and food services posted a 0.9 percent increase, while financial and insurance activities grew by 1.5 percent. Public administration also registered a modest gain. In contrast, real estate activity fell by 4.5 percent, construction declined by 1.8 percent, and information and communication slipped by 1.1 percent.

From the expenditure side, GDP growth was supported by domestic demand. Household consumption rose by 2 percent, up from 0.5 percent in the previous quarter, while public sector spending increased by 2.2 percent. Gross fixed capital formation grew for the first time in three quarters, though overall gross capital formation fell by 4.2 percent due to lower inventories.

Exports rose by 3 percent and imports by 2.9 percent, producing a slightly positive trade balance – the first surplus in a year. For the first half of 2025, GDP increased by 0.7 percent, with nominal output reaching €65.6 billion. Domestic demand expanded by 1.8 percent over the same period, but foreign trade developments exerted a drag, as import growth outpaced exports, resulting in a trade deficit of €47 million.

Poland: Regional Business Sentiment Improves in August, but Labour Costs Remain a Key Barrier

Business sentiment across Poland’s regions improved in August 2025 compared with the same month a year earlier, according to the latest Business Tendency Voivodship Report published by the Statistical Office in Zielona Góra. The Regional Business Climate Indicator (R-BCI) rose in most sectors, particularly in accommodation and catering, transportation and storage, and information and communication.

On a year-to-year basis, 10 voivodships reported stronger conditions in accommodation and catering, while nine noted improvements in transport, storage, and ICT. Manufacturing sentiment improved in seven voivodships, and six reported gains in construction and both wholesale and retail trade. Month-to-month, sentiment was strongest in manufacturing, trade, and ICT, though in most other sectors it weakened.

Despite the more positive outlook, many firms continued to cite barriers to activity. High labour costs were the most frequently mentioned constraint, especially in construction and accommodation. Economic uncertainty was also widely reported, particularly by companies in transport, storage, and wholesale trade. High fiscal burdens remained a challenge in several sectors.

Investment expectations showed moderate optimism. Most entrepreneurs forecast stable investment levels compared to last year, especially in ICT. Where changes were expected, reductions in spending were more common than increases. Investment plans for 2025 are focused mainly on machinery and technical equipment in manufacturing and construction, transport assets in logistics, and IT equipment and staff training in the information and communication sector.

While sentiment varied by region, accommodation and catering stood out with positive forecasts in nine voivodships, contrasting with the more cautious outlooks elsewhere. Overall, the report suggests that while Poland’s business climate is improving, structural challenges and cost pressures continue to weigh on enterprises.

Czech retail sales growth slows in July

Retail trade in the Czech Republic recorded slower growth in July 2025, according to data from the Czech Statistical Office (CZSO). Sales adjusted for price effects rose by 2.5 percent year-on-year, but momentum weakened compared to previous months. On a month-to-month basis, overall sales fell by 0.3 percent.

Sales excluding motor vehicles dropped by 0.3 percent compared with June. Within this category, sales of non-food goods declined by 0.4 percent and food sales slipped by 0.2 percent, while sales of automotive fuel remained flat.

Year-on-year, non-food sales grew by 3.5 percent and automotive fuel sales rose sharply by 8.3 percent. Food sales, however, decreased by 0.9 percent.

“Sales in retail trade adjusted for price effects continued to grow, year-on-year, in July; however, the growth rate decelerated compared to the previous months,” said Jana Gotvaldová, Head of the Trade, Transport, and Services Statistics Unit at the CZSO. She noted that while fuel and non-food sales supported growth, declines were recorded in several categories, including clothing, footwear, and information and communication equipment.

Sales in cosmetic and toilet articles stores rose by 7.9 percent, dispensing chemists and medical goods stores gained 5.9 percent, and cultural and recreation goods rose 4.5 percent. Household equipment sales grew slightly by 0.9 percent. By contrast, information and communication equipment sales fell by 5.3 percent, while clothing, footwear, and leather goods sales declined by 1.5 percent. Food sales were down both in specialised stores (–1.4 percent) and in non-specialised food stores (–0.9 percent). Online and mail-order sales increased by 6.7 percent.

Motor vehicle sales and repairs provided a further boost. Sales in this segment rose by 1.5 percent compared to June and by 4.8 percent year-on-year, with vehicle sales up 5.2 percent and repair services up 3.0 percent.

IREMIS appoints Lisa Neubueser to lead hotel & leisure growth

IREMIS, the Luxembourg-based real estate investment manager, has appointed Lisa Neubueser as Director Hotel & Leisure, effective 1 September 2025. Neubueser, who brings more than 15 years of pan-European experience in hospitality and residential real estate investment, will support the firm’s expanding hotel platform.

Her appointment comes as IREMIS builds on recent milestones, including the closing of its first hotel-focused fund and the acquisition of its inaugural property. She will work alongside Peter Lenhardt, Head of the Hotel & Leisure division, and Chris Curtis, the company’s CFO, with whom she previously collaborated during her time at Invesco Real Estate.

Neubueser’s career includes senior roles in portfolio and investment management at Vertiq Capital, Greystar, and Redevco Living. She also held development positions with operators Zoku and Cycas Hospitality. Earlier, she worked at Invesco Real Estate on hotel fund management and acquisitions across Europe.

Commenting on the appointment, Lenhardt said Neubueser’s expertise will support the division’s continued growth and broaden investor access to the hospitality sector. Neubueser described the move as “an exciting opportunity” to help shape and expand IREMIS’ hospitality platform.

Jochen Schaefer-Suren, Founder and Co-Chairman of IREMIS, added that her background and network align with the firm’s strategy to provide specialist investment solutions and expand its European footprint.

Europe’s largest Lee Cooper store opens in Warsaw

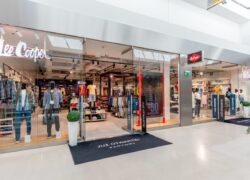
Lee Cooper has opened its largest European store at FACTORY Annopol in Warsaw, doubling its retail space from 170 to 340 square meters. The outlet, part of NEINVER’s portfolio of FACTORY centers in Poland, now hosts the most extensive Lee Cooper collection on the continent.

Founded in London, Lee Cooper is Europe’s oldest denim brand and has long been present in Polish outlet centers. The new store at FACTORY Annopol carries the brand’s full product range, including jeans in various styles and finishes, as well as shirts, sweaters, jackets, outerwear, and accessories. Many items are produced using recycled fabrics or through eco-friendly processes. The interior has been designed in line with the brand’s latest concept, incorporating references to British heritage alongside modern, industrial elements.

FACTORY Annopol is one of Warsaw’s key retail destinations, drawing millions of visitors annually. Together with FACTORY Ursus, also managed by NEINVER, it represents the capital’s largest outlet offering. The center’s occupancy rate stands at 98 percent, and in recent months several international brands, including Skechers and New Balance, have expanded their presence there.

According to NEINVER, Lee Cooper’s decision to expand at Annopol underscores both the center’s strong performance and the brand’s established position in the Polish market.

Leadership change at Art-Invest Real Estate Frankfurt branch

Art-Invest Real Estate is making a leadership change at its Frankfurt office. Roland Stöcklin will join the management board of Art-Invest Real Estate Management on September 15, 2025, taking over responsibility for the branch from Stephen von der Brüggen, who is stepping down after 15 years with the company.

Stöcklin will oversee the Frankfurt operations, which currently manage projects totaling around 200,000 square meters with a combined volume of approximately €1 billion. He brings extensive experience from more than a decade as managing director of SEG – Stadtentwicklungsgesellschaft Wiesbaden and EGM – Entwicklungsgesellschaft der Metropolregion Rhein-Main. In addition, he serves as spokesperson for the ZIA-Region Mitte, sits on the Hessian State Government’s Commission for Innovation in Construction, and is a member of the Regional Assembly of South Hesse. He holds a civil engineering degree from the University of Applied Sciences in Darmstadt.

“I am looking forward to the upcoming change of perspective,” Stöcklin said. “Art-Invest offers me the right professional challenge, with pioneering projects and an exceptional team. I am pleased to take responsibility for long-term investments in the Rhine-Main region, where Art-Invest’s quality standards align closely with my own approach to architecture and client satisfaction.”

Von der Brüggen, who joined Art-Invest in 2010, was instrumental in establishing the Frankfurt office in 2015. His work included projects such as the KölnTurm repositioning, the Morrow office building revitalization, the development of the maincubes data center, and the construction of Samsung Electronics’ German headquarters in Eschborn Gate. Although leaving the management board, he will continue to advise the company.

“I look back with gratitude on a successful and intense time at Art-Invest Real Estate,” von der Brüggen said. “It has been a privilege to realize groundbreaking projects with an excellent team. I look forward to new perspectives while remaining connected to the company and its people.”

Art-Invest Real Estate’s leadership expressed appreciation for von der Brüggen’s contributions and welcomed Stöcklin to his new role. “We would like to thank Stephen von der Brüggen for his many years of cooperation and wish him all the best,” said Markus Wiedenmann, CEO, and Ferdinand Spies, COO. “At the same time, we are very pleased to welcome Roland Stöcklin, a highly experienced colleague, to the Frankfurt branch.”

Maciej Müldner appointed to Management Board of MLP Group

MLP Group has expanded its Management Board with the appointment of Maciej Müldner, who takes responsibility for the company’s finance division. The move increases the number of board members to four and reflects the Group’s continued growth across European markets.

Müldner, who joined MLP Group in July as Chief Financial Officer, brings more than three decades of experience in financial management at international corporations and banks. He has worked extensively across Poland, Germany, Austria, and the wider Central and Eastern European region.

“The decision to expand the Management Board is a natural consequence of the Group’s dynamic growth across Europe,” said Radosław T. Krochta, President of the Management Board of MLP Group S.A. “Maciej brings significant corporate experience in managing finance at the European level. His expertise will be crucial for further scaling up our operations and will accelerate strategic decision-making to support the long-term and sustainable development of MLP Group.”

Before joining MLP, Müldner held senior financial roles at the Dentsu Group in Poland and CEE. He previously spent nearly two decades with Skanska, including managing treasury operations in Poland and Germany between 2002 and 2011, and later oversaw finance for Skanska Property’s commercial development arm. His career also includes roles at Echo Investment and Archicom, where he supported expansion and introduced modern approaches to corporate finance.

Müldner began his professional career in the banking sector, working at Deutsche Bank and Bank Austria. He holds a degree in Management from the University of Warsaw and is an active member of the Polish Association of Corporate Treasurers.

front page info
LATEST NEWS