Brno Plans Transformation of Špitálka–Radlas into New Urban Avenue

The city of Brno is preparing a major redevelopment of the area between Cejl and Radlas, aiming to turn what is currently a fragmented and hard-to-access district into a modern, livable urban zone with improved transport links, public spaces, and greenery. The plans are outlined in a study commissioned by the Office of the Architect of the City of Brno.

The Špitálka–Radlas area, located east of the historic city core, is marked today by brownfields, sparse streets, and limited green areas. Formerly home to a gas plant, incinerator, and heating plant, the district still contains remnants of industrial heritage. The study proposes transforming these underused spaces into a connected urban quarter, anchored by a new avenue linking Cejl and Masná streets and a tram line leading to the planned main railway station.

According to the study, the redevelopment would strengthen the city’s urban structure, making Špitálka–Radlas a counterpart to established neighborhoods such as Veveří and Černá Pole, while improving connections with Židenice. The plan emphasizes a balanced transport system, with trams playing a central role, complemented by denser pedestrian routes to enhance accessibility.

Green infrastructure is another key element. The proposal highlights the potential of the Svitavy riverbank and the old Židenice railway corridor to serve as green axes, improving the environmental quality of the area. At the same time, the study recommends preserving and adapting industrial-era architecture to give the district a distinctive identity.

The redevelopment framework will guide future zoning changes, detailed planning, and investment preparation. The transformation of brownfield sites is expected to be the cornerstone of the project, supporting Brno’s broader strategy of sustainable urban renewal.

Source: CTK
Images: images are illustrative visualisations of similar new urban avenue projects and do not depict the actual planned development
Analysis: Czech Public Trust in Government Erodes Amid Economic Strains and Corruption Concerns

Public confidence in the Czech government remains at low levels, with recent surveys and analyses pointing to economic pressures, unfulfilled policy commitments, and ongoing concerns over corruption as key factors.

According to data from the Organisation for Economic Co-operation and Development (OECD), only 19 percent of Czechs express trust in their government. A separate April 2025 survey by STEM found that just 3 percent of respondents said they “definitely trust” the cabinet, while 20 percent said they “rather trust” it. Political scientist Lukáš Valeš of the University of West Bohemia told the Czech News Agency that trust has been steadily declining since 2011 and that the current cabinet of Prime Minister Petr Fiala is faring worse than its predecessors from 2014 to 2020. He argued that unmet promises on fiscal consolidation, tax stability, and spending cuts have contributed to the erosion of confidence.

Analysts note that trust levels are closely tied to perceptions of political influence and everyday public services. Alexandra Cholevová, an analyst with the Europe project, explained that citizens who feel their voice does not matter trust government institutions on average 36 percentage points less than those who feel politically represented. Trust is also stronger among people with higher education, those not under financial strain, and voters who supported the governing parties.

Valeš emphasized that citizens’ evaluations often hinge on tangible services. “If safety is guaranteed, kindergartens and schools have enough capacity, people can access doctors without long waits, and surgeries are not delayed for months, then trust in the state increases. When these services fail, trust declines,” he said.

Corruption concerns further undermine confidence, though direct experience with bribery remains limited. In Transparency International’s 2024 Corruption Perceptions Index, the Czech Republic ranked 46th globally, alongside Spain, Cyprus, and Grenada. Ondřej Kopečný of Transparency International Czech Republic noted that perceptions are shaped more by public debate and media coverage than by first-hand experience.

The government introduced a new Lobbying Act in July 2025 aimed at increasing transparency in political influence. Analysts suggest that effective implementation of such measures could help narrow the gap between citizens and political elites.

Source: CTK

Vodafone Czech Republic Reports Strong Profit Growth and Expands 5G Coverage

Vodafone Czech Republic more than doubled its net profit in the fiscal year ending March 2025, reporting CZK 1.79 billion compared with CZK 839 million in the previous year. According to the company’s annual report, revenue increased by 2.2 percent to CZK 21.78 billion, driven by a growing customer base, higher demand for services beyond traditional connectivity, and lower financing costs.

Most of Vodafone’s revenue came from telecommunications services, supplemented by sales of phones and accessories. The company highlighted continued investment in both mobile and fixed networks. Its 5G network now covers an estimated 97 percent of the Czech population, an increase of about 12 percentage points compared with last year. Over the past three years, more than half of the fixed network has been modernised, and in early 2025 Vodafone launched 2 Gbps internet connections, which are now available to 1.3 million households.

The operator also benefited from a decision by the Czech Telecommunication Office in March to restore frequency allocations in the 900 and 1800 MHz bands. As part of its commitments linked to this spectrum, Vodafone has pledged to eliminate 200 “white spots” in mobile coverage by 2030. The company said that its largest investments targeted faster network speeds, durable IT systems, and improved customer support.

The workforce grew slightly to 2,172 employees, an increase of 56 compared with the previous year. Vodafone Czech Republic remains part of the global Vodafone Group, which operates in multiple markets across Europe, Africa, and Asia.

While the company did not disclose detailed audited financial statements beyond the annual report, the results underscore Vodafone’s focus on strengthening its market position through infrastructure investment and expanding digital services in a competitive Czech telecoms market.

EU mobility in 2023: cars still dominate, air travel’s share rises as rail sets a new record

Cars remained the primary mode of passenger transport in the EU in 2023, accounting for 70.6% of total passenger-kilometres, down 1.8 percentage points from 2022. Air transport’s share increased to 14.7% (+1.6 pp), followed by buses/coaches/trolleybuses at 7.2% (−0.2 pp), rail at 7.1% (+0.3 pp) and sea at 0.4% (unchanged), according to Eurostat’s latest “EU people on the move” update. Country patterns varied widely: car use was highest in Lithuania (85.7%), the Netherlands (77.1%) and Finland (76.4); the air share peaked in Croatia (43.5%), Bulgaria (29.0%) and Cyprus (27.4%); buses were most prominent in Malta (15.8%), Ireland (15.4%) and Estonia (12.0%); rail’s role was largest in the Netherlands (10.9%), Austria (10.5%) and France (9.1%); and sea transport led in Croatia (2.4%), Estonia (2.3%) and Finland (2.1%). 

Eurostat’s modal-split figures reflect shares of total passenger-kilometres rather than absolute volumes, meaning a rising share for one mode can coincide with growth in others. Complementary datasets indicate strong rebounds in the modes most affected by the pandemic: EU air passengers rose to 973 million in 2023, up 19.3% year on year, while rail passenger-kilometres reached a series high of 429 billion in 2023, up 11.2% from 2022. Both trends help explain the modest decline in the car share despite cars remaining dominant. 

Longer-term indicators suggest Europe’s modal mix changes slowly. The European Environment Agency notes that total passenger activity returned to around pre-COVID levels by 2022, while the car share has shifted only marginally over the past few decades outside the pandemic shock. With 2024 and 2025 releases continuing to show robust air traffic and resilient rail demand, policymakers marking European Mobility Week are likely to focus on managing growth in higher-emission modes while sustaining momentum in rail and public transport.

EU mobility in 2023: cars still dominate, air travel’s share rises as rail sets a new record

Cars remained the primary mode of passenger transport in the EU in 2023, accounting for 70.6% of total passenger-kilometres, down 1.8 percentage points from 2022. Air transport’s share increased to 14.7% (+1.6 pp), followed by buses/coaches/trolleybuses at 7.2% (−0.2 pp), rail at 7.1% (+0.3 pp) and sea at 0.4% (unchanged), according to Eurostat’s latest “EU people on the move” update. Country patterns varied widely: car use was highest in Lithuania (85.7%), the Netherlands (77.1%) and Finland (76.4); the air share peaked in Croatia (43.5%), Bulgaria (29.0%) and Cyprus (27.4%); buses were most prominent in Malta (15.8%), Ireland (15.4%) and Estonia (12.0%); rail’s role was largest in the Netherlands (10.9%), Austria (10.5%) and France (9.1%); and sea transport led in Croatia (2.4%), Estonia (2.3%) and Finland (2.1%). 

Eurostat’s modal-split figures reflect shares of total passenger-kilometres rather than absolute volumes, meaning a rising share for one mode can coincide with growth in others. Complementary datasets indicate strong rebounds in the modes most affected by the pandemic: EU air passengers rose to 973 million in 2023, up 19.3% year on year, while rail passenger-kilometres reached a series high of 429 billion in 2023, up 11.2% from 2022. Both trends help explain the modest decline in the car share despite cars remaining dominant. 

Longer-term indicators suggest Europe’s modal mix changes slowly. The European Environment Agency notes that total passenger activity returned to around pre-COVID levels by 2022, while the car share has shifted only marginally over the past few decades outside the pandemic shock. With 2024 and 2025 releases continuing to show robust air traffic and resilient rail demand, policymakers marking European Mobility Week are likely to focus on managing growth in higher-emission modes while sustaining momentum in rail and public transport.

Poland’s State Budget Deficit Reaches PLN 172 Billion by August 2025

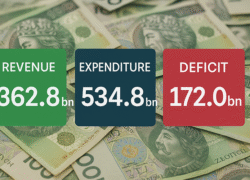
The Polish Ministry of Finance reported that by the end of August 2025, the state budget recorded revenues of PLN 362.8 billion and expenditures of PLN 534.8 billion, resulting in a deficit of PLN 172 billion. This represented 57.3% of planned revenues, 58.0% of planned expenditures, and 59.6% of the deficit limit set in the 2025 budget law.

The fall in revenues compared with last year was primarily due to reforms in the financing of local government units (JST), which redistributed shares of personal income tax (PIT) and corporate income tax (CIT). Without this reform, state budget revenues would have amounted to PLN 484.9 billion, nearly PLN 40 billion higher than in the same period of 2024.

Tax revenues totaled PLN 311.2 billion, down 12.2% year-on-year. VAT receipts grew by 10.5% to PLN 214.6 billion, and excise duty revenues rose 1.9% to PLN 59.1 billion. PIT revenues fell sharply to PLN 11.3 billion due to the transfer of a larger share to local governments, while CIT revenues increased 5.8% to PLN 44.1 billion. Non-tax revenues amounted to PLN 40.7 billion, 5.1% lower than in the same period last year.

Expenditures of PLN 534.8 billion were up 7.4% compared with January–August 2024. Significant outlays included PLN 112 billion for the Social Insurance Institution, PLN 63.2 billion for national defence, PLN 41.6 billion for servicing state debt, PLN 36.6 billion in general subsidies for local governments, and PLN 32.5 billion for health. Transfers included PLN 19 billion in March for repayment of Polish Development Fund bond obligations from the 2020 financial support programme, and PLN 16 billion in July to the COVID-19 Countermeasure Fund for liabilities issued between 2020 and 2023.

Higher year-on-year expenditure was reported in healthcare, social insurance, national defence, debt servicing, transport, EU contributions, internal affairs, and higher education. The health budget alone grew by PLN 19.2 billion, partly due to increased transfers to the National Health Fund and new programmes such as support benefits for people with disabilities and the “widower’s pension.” Defence spending rose by PLN 4.8 billion, reflecting purchases of equipment and armaments.

General subsidies to local governments decreased by PLN 50.3 billion compared with 2024, reflecting structural changes in public finances. Since January 2025, the subsidy has had a complementary role, as JSTs now receive a larger share of PIT and CIT revenues directly.

The Ministry highlighted that despite the deficit increase, revenue shortfalls were largely statistical, caused by the redistribution of PIT and CIT shares, while underlying tax bases, particularly VAT and CIT, continued to grow.

Slovakia’s Inflation Slows in August but Remains at a 20-Month High

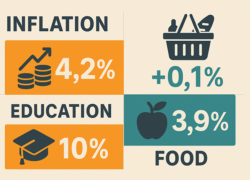
Consumer prices in Slovakia rose 4.2% year-on-year in August 2025, slowing slightly from the previous two months but still marking the highest inflation rate in 20 months, according to the Statistical Office of the Slovak Republic. Month-on-month, prices increased by just 0.1%, the lowest growth so far this year, matching April’s figure.

Transport costs had the strongest impact on monthly inflation, with prices in this category rising 1.9%, driven by higher air and combined passenger transport fares. Food and housing costs, which carry the greatest weight in household spending, remained unchanged after several months of steady increases. Within food, price developments were mixed: vegetables, oils and fats, and dairy products fell, while meat, sugar, and cereals registered modest increases. Restaurant and hotel services rose 0.2%, while telecommunications prices also climbed, reflecting higher charges for phone services.

Five of the 12 main expenditure divisions recorded month-on-month declines. Furniture and furnishings fell the most, down 0.5%, followed by recreation and culture (-0.2%). Alcoholic beverages and tobacco decreased 0.3%, largely due to lower beer and spirits prices. Apparel, footwear, and healthcare also edged lower.

On a year-on-year basis, all 12 expenditure categories posted higher prices. Education recorded the sharpest increase at 10%, followed by restaurants and hotels, alcoholic beverages and tobacco, and miscellaneous goods and services such as insurance, hairdressing, and personal care. Food and non-alcoholic beverages rose 3.9% compared with August 2024, with notable increases in oils and fats, dairy, and fruit, offset by lower prices for meat and vegetables. Non-alcoholic beverages jumped more than 19% year-on-year.

Housing and energy, healthcare, and transport recorded the slowest price growth, each remaining below 3%. Across the first eight months of 2025, consumer prices have increased by an average of 4.1% year-on-year.

Core inflation, which excludes regulated prices and tax-driven changes, stood at 3.5% in August, while net inflation, which further strips out food prices, was 3.2%. Both measures rose 0.1% month-on-month.

The Statistical Office noted that new scanner data sources, covering food, non-alcoholic beverages, alcoholic drinks, and tobacco, have been integrated into inflation calculations since 2024–2025, enhancing coverage and accuracy of price data.

Polish Households Used More Electricity and Gas in 2024 While Heat Energy Sales Declined

Household energy consumption in Poland rose in 2024, according to new data from Statistics Poland. Electricity use in homes increased by 2.1% year-on-year to 30.4 TWh, while consumption of gas from the network rose by 0.9% to 54.6 TWh. At the same time, sales of heat energy to residential buildings fell by 2.7%.

Electricity consumption per household reached 1,832 kWh, up 0.7% from 2023. Urban households used an average of 1,612 kWh compared with 2,269 kWh in rural areas. Per capita use stood at 809 kWh, with rural residents consuming more than their urban counterparts. The number of electricity consumers rose 1.4% to nearly 16.6 million.

The country’s heat supply network grew modestly to almost 25,910 km, with more than 96% located in urban areas. Regional density was highest in Śląskie, followed by Małopolskie and Pomorskie. Total heat energy sales reached 180.5 petajoules, of which 78.5% was delivered to residential buildings. Solid fuels remained the main source of heat production, though gaseous fuels also played a significant role.

The gas supply network expanded by 1.3% to 176,600 km, with connections to buildings rising 2.3% to 3.56 million. Rural areas accounted for 59% of the network length. Household gas consumption increased to an average of 6,162 kWh per consumer, though the number of gas customers declined slightly overall by 0.5%. Rural households used an average of 10,364 kWh compared with 5,254 kWh in urban areas.

The findings highlight shifting patterns in Poland’s municipal energy infrastructure. While demand for electricity and gas grew, heat energy sales contracted, reflecting changing consumption behaviour and the ongoing modernization of energy networks.

Polish Households Used More Electricity and Gas in 2024 While Heat Energy Sales Declined

Household energy consumption in Poland rose in 2024, according to new data from Statistics Poland. Electricity use in homes increased by 2.1% year-on-year to 30.4 TWh, while consumption of gas from the network rose by 0.9% to 54.6 TWh. At the same time, sales of heat energy to residential buildings fell by 2.7%.

Electricity consumption per household reached 1,832 kWh, up 0.7% from 2023. Urban households used an average of 1,612 kWh compared with 2,269 kWh in rural areas. Per capita use stood at 809 kWh, with rural residents consuming more than their urban counterparts. The number of electricity consumers rose 1.4% to nearly 16.6 million.

The country’s heat supply network grew modestly to almost 25,910 km, with more than 96% located in urban areas. Regional density was highest in Śląskie, followed by Małopolskie and Pomorskie. Total heat energy sales reached 180.5 petajoules, of which 78.5% was delivered to residential buildings. Solid fuels remained the main source of heat production, though gaseous fuels also played a significant role.

The gas supply network expanded by 1.3% to 176,600 km, with connections to buildings rising 2.3% to 3.56 million. Rural areas accounted for 59% of the network length. Household gas consumption increased to an average of 6,162 kWh per consumer, though the number of gas customers declined slightly overall by 0.5%. Rural households used an average of 10,364 kWh compared with 5,254 kWh in urban areas.

The findings highlight shifting patterns in Poland’s municipal energy infrastructure. While demand for electricity and gas grew, heat energy sales contracted, reflecting changing consumption behaviour and the ongoing modernization of energy networks.

Poland’s Housing Stock Reached Nearly 16 Million Dwellings in 2024

At the end of 2024, Poland’s housing stock reached almost 16 million dwellings, an increase of 1.2% compared with the previous year, according to Statistics Poland. The total useful floor area expanded by 1.4% to just over 1.2 billion square metres, while the number of rooms rose by 1.1% to 61.2 million.

Urban areas accounted for 10.8 million dwellings with 704 million square metres of floor area, while rural areas had 5.1 million dwellings with 503 million square metres. Growth in new dwellings was more pronounced in urban locations, which saw an increase of 138,900 units (1.3%), compared with 47,600 in rural areas (0.9%).

Housing conditions showed modest improvements. The average dwelling size rose to 75.6 m², and the average space per person increased from 31.6 m² in 2023 to 32.2 m² in 2024. Rural dwellings remained larger, averaging 98.1 m² compared with 64.9 m² in urban areas. There were 426 dwellings per 1,000 residents nationwide, up from 419 a year earlier.

The share of dwellings fitted with modern installations remained high: 97.8% with water supply, 95.3% with lavatories, 93.9% with bathrooms and 59.1% with gas installations. However, disparities persisted, with urban homes better equipped than rural ones.

Ownership patterns continued to be dominated by private individuals, who held nearly 13.1 million dwellings—about 88% of the total floor area. Housing cooperatives accounted for almost 1.9 million dwellings, while municipal stocks declined to around 756,000. State Treasury holdings remained minimal at 29,000 units.

In 2024, close to 91,000 dwellings were sold to private owners, mostly from housing cooperatives and municipal stocks. At the same time, municipalities managed nearly 596,000 rental dwellings, down 1.2% year-on-year, and around 119,000 households remained on waiting lists for municipal housing, a 3.6% decrease compared to 2023.

Housing allowances continued to support households. More than 2.7 million payments were made in 2024, slightly fewer than in 2023, but the total value rose to PLN 898.4 million. The average allowance increased to PLN 329 per month.

Land availability for housing also remained stable. Municipalities held just over 24,000 hectares for housing construction, with almost 63% located in urban areas. More than 80% of plots handed to investors in 2024 were designated for single-family housing.

front page info
LATEST NEWS