Slovakia’s Housing Market Enters 2026 in a Phase of Adjustment and Slower Growth

Slovakia’s housing market is moving into a new phase in 2026, shaped by the after-effects of several years of higher interest rates, rising construction costs and limited new supply. While the pace of change has slowed compared with the sharp swings seen earlier in the decade, both buyers and tenants continue to feel pressure on household budgets, particularly in larger cities.

Market observers describe the current period less as a recovery and more as an adjustment to new conditions. Mortgage rates have eased from their recent peaks but remain above the levels many households were used to before 2020. This has reduced purchasing power and kept part of the potential buyer base on the sidelines. At the same time, developers face higher financing and construction expenses, which limits the number of new projects and keeps the supply of newly built apartments relatively tight.

As a result, ownership remains difficult for many first-time buyers, especially younger households. Renting, which was once often seen as a temporary solution, is increasingly becoming a longer-term choice. Demand for rental housing has been supported by labour mobility, lifestyle changes and the growing number of smaller households.

During 2025, rental prices rose more slowly than in previous years, and in some periods increases were only marginal. After adjusting for inflation, real rental income for landlords in major cities showed limited growth or even slight declines. This has influenced investor expectations, particularly for properties purchased with mortgage financing, where borrowing costs continue to play a significant role in profitability.

In Bratislava, rental activity has remained concentrated in several districts, with central neighbourhoods continuing to command the highest prices. However, part of the demand has gradually shifted toward outer districts where rents are lower. Newly completed apartments generally achieve higher rental levels than older housing stock, reflecting differences in energy efficiency, layout and amenities.

Investment interest in residential property has not disappeared, but it has become more selective. Smaller apartments tend to attract the most attention due to their easier lettability and more predictable income streams. Older properties are also of interest to investors seeking lower entry prices, although expected returns depend heavily on purchase costs, rental levels and financing terms. Inflation continues to influence decision-making, as it can both reduce the real burden of debt and erode the long-term value of returns.

Looking ahead, moderate price growth is expected rather than rapid increases. Well-located and higher-quality projects are likely to maintain stronger pricing, while older or less attractive properties may see little change. Differences between market segments are therefore expected to widen. Rental prices are also projected to rise gradually, particularly for smaller units, although the pace will vary by city and neighbourhood.

Overall, the Slovak housing market in 2026 is characterised less by dramatic shifts and more by gradual adaptation. Housing remains expensive relative to incomes, supply growth is limited, and both buyers and tenants are adjusting expectations. For many households, flexibility in location, size and property type is becoming increasingly important as the market settles into a new equilibrium rather than returning to earlier, lower-cost conditions.
CTP completes first phase of CTPark Warsaw Janki, second building under construction

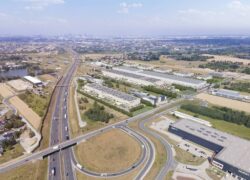
CTP has completed the first phase of its industrial and logistics park in Puchały near Warsaw and obtained the occupancy permit for a warehouse building with an area of approximately 9,100 square metres. The facility was developed in the CTFlex format, which is designed for smaller units primarily aimed at small and medium-sized enterprises. At the same time, construction is continuing on a second building of around 22,000 square metres.

CTPark Warsaw Janki is one of several CTP warehouse projects in the Warsaw metropolitan area. The site is located close to the S8 expressway, providing direct access to Warsaw and key national transport routes. The newly completed hall was planned to allow division into modules of roughly 1,500 square metres, enabling flexible arrangements for different tenants.

According to CTP Polska, the second building is already at an advanced stage of construction and is expected to be delivered later this year. The full project is planned to include five buildings, increasing the volume of immediately available warehouse space in the southern Warsaw region, near Chopin Airport.

The general contractor for the first building was Depenbrock. The complex is being developed on a plot of just over 13 hectares. In addition to standard technical parameters, the design includes features intended to improve working conditions, such as increased natural lighting throughout the warehouse and translucent façade panels in selected areas.

Romania’s modern retail stock exceeds 5 million sqm as new deliveries continue

Romania’s modern retail market passed the 5 million square metre mark in 2025 after the completion of around 190,000 square metres of new space, according to Colliers’ annual market report. The volume delivered last year was roughly one-fifth higher than the average recorded over the previous five years. While economic conditions have become more moderate, the consultancy expects development activity to remain solid in 2026, with new completions estimated at about 240,000 square metres, potentially making it the most active year for retail deliveries since 2011. Despite recent growth, Romania still has less modern retail area per inhabitant than several neighbouring countries, suggesting room for further expansion, particularly in regional cities.

The largest addition to the market in 2025 was in Iași, where the Mall Moldova scheme was extended following the refurbishment of the former Era Shopping Center, adding close to 60,000 square metres of leasable space. In Arad, the Agora Mall project re-entered the market after renovation works, contributing around 35,000 square metres. A reassessment of national stock, which included older centres upgraded and reopened, also contributed to the overall total surpassing the 5 million square metre threshold.

Although numerous smaller retail parks continue to appear across the country, these are generally excluded from official statistics, which typically track only projects above approximately 4,000–5,000 square metres. Nevertheless, their presence indicates ongoing investor interest in secondary cities and towns where consumer demand remains active.

On the demand side, 2025 was less dynamic than the previous decade. Purchasing power weakened toward the end of the year and consumer spending slowed. Real wages declined compared with the previous year, and non-food retail sales showed a modest contraction in late autumn. Analysts note, however, that this represents a short-term adjustment following several years of strong growth, with Romania still ranking among the larger retail markets in the European Union by overall sales volume.

Labour market trends also pointed to relative stability. Employment growth slowed but overall workforce levels remained broadly unchanged, limiting the impact on household consumption. Several international retailers entered or expanded their presence in the country during 2025, while additional brands are expected to open their first stores in 2026. Traditional brick-and-mortar retail slightly outperformed online channels, reflecting cautious consumer behaviour and increased sensitivity to price amid inflationary pressures.

Occupancy rates in established shopping centres remained high, and newly completed schemes were generally absorbed without significant delays, including in smaller urban areas. Dominant malls in major cities reported limited availability, allowing owners to adjust tenant mixes and maintain rental levels. Discounters and essential goods retailers are expected to remain among the most active occupiers in the coming year.

For 2026, Colliers anticipates a more measured pace of decision-making from both developers and retailers, even as construction volumes remain elevated. Planned projects vary widely in size and are being advanced by both domestic and international investors. While building costs continue to weigh on budgets, the medium-term outlook for Romania’s retail property sector is viewed as stable, supported by ongoing urban development and consumer demand outside the capital.

New BMW logistics hub under construction at Mošnov as industrial park continues expansion

Construction is progressing on a large distribution facility for the BMW Group within the industrial zone near Leoš Janáček Ostrava Airport, part of the wider Ostrava Airport Multimodal Park development. The complex, which is being built by Czech developer Gridarch, is expected to be completed in 2026 and will serve as an international distribution point for the automotive manufacturer.

The Mošnov site has been developed in stages over several years and combines warehouse buildings with rail, road and air transport access. Since the first buildings were delivered at the beginning of the decade, the area has attracted a range of logistics operators and manufacturing companies that use the location for regional and cross-border distribution.

The newest phase of the park includes several large halls intended primarily for automotive logistics. Company representatives involved in the project have indicated that the construction schedule is on track and that preparations for operational activity are already underway, including the recruitment of warehouse and logistics staff in the Ostrava region.

Earlier phases of the industrial park were partly sold to an international real estate investment manager, while later stages have continued under Gridarch’s ownership. When all planned stages are completed, the total leasable area of the Mošnov complex is expected to exceed half a million square metres, making it one of the largest logistics and light-industrial concentrations in the northeastern part of the Czech Republic.

Electric mobility in Germany shows gradual recovery, but growth remains moderate

After a noticeable decline in 2024, registrations of electric cars in Germany increased again in 2025, although overall growth in electric mobility remains gradual over the longer term. According to an analysis by the German Institute for Economic Research (DIW Berlin) based on data from the Open Energy Tracker platform, the expansion of charging infrastructure has outpaced the growth of the electric vehicle fleet, while policy uncertainty continues to affect the pace of adoption.

There are currently around two million fully electric passenger cars on German roads, representing roughly four percent of the total vehicle fleet. In 2025, nearly one in five newly registered cars was battery electric. This marks an improvement compared to the previous year, when demand declined following the end of purchase subsidies, but the share is only slightly higher than levels recorded in 2022 and 2023. Plug-in hybrid vehicles also increased their share of new registrations to just over ten percent, although studies indicate that these vehicles are often driven on combustion engines for much of their mileage.

Newly registered electric cars are increasingly concentrated in larger vehicle categories. Sport utility vehicles and off-road models account for around half of all new electric registrations, while more than ten percent are in upper or upper-middle market segments. European manufacturers dominate the market, producing about four out of five newly registered electric cars, with German brands accounting for more than half. The market share of North American suppliers has declined, while Chinese brands have expanded from a relatively low base.

Electrification is also advancing in parts of the commercial vehicle sector. The share of battery-electric articulated lorries in new registrations reached around three percent in 2025, with higher monthly figures toward the end of the year. Electric buses represent approximately one quarter of new bus registrations, the highest proportion among vehicle categories, and about five percent of the total bus fleet is now fully electric.

Public charging infrastructure has expanded significantly in recent years. Germany now has close to 190,000 public charging points, around one quarter of which are fast chargers. The ratio of electric cars to fast-charging points has improved compared with previous years, and average installed charging capacity per vehicle has increased. According to the DIW analysis, charging availability is unlikely to be the main constraint on further adoption in most regions.

The study notes that policy direction remains a key factor influencing market development. DIW researcher Wolf-Peter Schill stated that clearer long-term priorities and consistent regulatory signals could support investment and purchasing decisions. While financial incentives such as subsidies or tax advantages may provide short-term effects, the report suggests that long-term growth depends largely on stable policy frameworks and clearer guidance regarding future drive technologies.

Source: DIW Berlin

Makita expands leased space at MLP Pruszków II logistics park

Makita has increased the amount of warehouse and office space it leases at the MLP Pruszków II logistics park near Warsaw. The company will occupy around 18,000 square metres in total after the expansion, almost twice the size of its previous lease. The additional area is scheduled to be handed over in mid-2026. Cushman & Wakefield advised the tenant during the transaction.

Makita has operated at the site since 2017, when it initially leased approximately 9,800 square metres of warehouse space. Under the new agreement, the company will use about 16,800 square metres for storage and logistics functions and around 1,200 square metres for offices and staff facilities.

Representatives of both the landlord and the tenant said the expansion reflects the company’s growing logistics requirements and the availability of additional space within the same complex. Cushman & Wakefield noted that concentrating operations in a single location can simplify distribution and inventory management processes.

Makita is a Japanese manufacturer of power tools and garden equipment and operates two logistics centres in Poland, one of which is located at MLP Pruszków II together with a training and presentation area.

MLP Pruszków II is a large logistics park in the Brwinów municipality west of Warsaw, close to the A2 motorway and several rail connections. The complex is being developed in stages and is planned to reach more than 400,000 square metres of leasable space. Some buildings have environmental certifications, and rooftop solar installations are being introduced as part of the developer’s sustainability programme.

Quantum reports strong acquisition activity and portfolio growth despite cautious market climate

The Hamburg-based real estate developer and investment manager Quantum has reported continued expansion of its property portfolio despite more demanding conditions across European markets. According to company information, the group added assets with a combined value of more than €650 million during the past year, while also completing several disposals and project handovers.

The newly acquired properties are primarily residential buildings located in major urban areas in Germany as well as selected cities in Austria and Denmark, complemented by a purchase in the light industrial segment. At the same time, the company finalised the sale of two investment properties and concluded the redevelopment and transfer of a large mixed-use scheme in Cologne.

By the end of the year, the total value of properties managed on behalf of investors reached approximately €12.5 billion. Housing continues to represent the largest share of the portfolio, followed by office space and retail premises. Leasing activity remained steady, with tens of thousands of square metres of commercial area newly occupied and several thousand apartments rented in both existing and recently completed residential projects.

In addition to investment transactions, the company secured new development management assignments in Hamburg and Munich. Three major projects were delivered during the year, including two large residential quarters in Hamburg and the final phase of an inner-city regeneration project in Cologne. Developments currently under construction or in preparation represent an estimated pipeline of more than €2 billion.

Company representatives indicated that residential real estate will remain a strategic focus moving forward, particularly in large European metropolitan regions. Following the completion of several flagship schemes, the group expects to continue launching further large-scale projects in the coming year, positioning itself for gradual growth as market conditions stabilise.

Euro area price growth eases at the start of 2026

Price growth across the countries using the euro slowed at the beginning of 2026, according to newly released preliminary data from the European Union’s statistical office. The early estimate for January indicates that consumer prices rose at a slower annual pace than in the final month of 2025, suggesting a continued cooling of inflationary pressures across the monetary union.

The main driver of price increases remained the services sector, although the rate of growth there also showed a slight moderation compared with the previous month. Food and beverage prices continued to rise year-on-year, but at a more measured speed than seen during much of the previous year. By contrast, energy costs continued to decline, helping to offset price increases in other categories and contributing significantly to the overall slowdown in inflation.

Goods excluding energy and food registered only limited annual price changes, reflecting relatively stable conditions in retail markets. The combination of softer energy prices and a gradual easing in service-related costs played a key role in bringing the overall rate lower at the start of the year.

The figures are based on an initial calculation and will be revised later in the month when more complete national data becomes available. Such early releases are closely monitored by financial markets and policymakers, as they provide one of the first signals of economic trends within the euro area each month.

Source: Eurostat

BBI Development receives final approval for 170-metre Roma Tower project in central Warsaw

BBI Development has obtained final administrative approval allowing the construction of the long-planned Roma Tower high-rise in central Warsaw, removing the last formal obstacle before work on the project can begin. The decision confirms that the building design and construction plans have been fully accepted by authorities, enabling the developer to move forward with both the start of works and the marketing of the scheme.

The tower is planned for a site near the junction of Nowogrodzka and Emilii Plater streets, one of the capital’s most prominent central locations. According to project information, the structure is expected to reach around 170 metres in height and comprise close to fifty above-ground levels. The building is intended primarily for residential use, with additional commercial and service areas at lower floors and parking space below ground.

Roma Tower is being developed through a partnership between BBI Development, the Liebrecht & WooD Group and the Pro Bonum Foundation. The project has been discussed in the Warsaw market for several years and has undergone a lengthy planning and permitting process, including design adjustments and changes in functional concept before reaching its current form.

Developers indicate that the final approval allows preparations for construction to accelerate during the year, while also opening the way for commercial activity related to the apartments and other premises planned within the building. Market observers note that the project is set to become one of the tallest predominantly residential buildings in the Polish capital once completed, further reshaping the skyline of Warsaw’s city centre.

Indotek divests Warsaw office property to Łazarski University for educational redevelopment

A Warsaw office building previously owned by the Hungarian investment group Indotek has been sold to Łazarski University, which plans to transform the property into new academic facilities focused on medical and dental education. The transaction marks another step in the ongoing conversion of older office assets in the Polish capital toward alternative uses.

The property, known as Taifun, is situated in the Włochy district of Warsaw and comprises approximately 7,000 square metres of space spread across several floors, along with both underground and surface parking areas. Its proximity to rail connections and relatively short travel time to Chopin Airport are considered key advantages of the location. Following the acquisition, the university intends to adapt the building to house teaching rooms and a modern medical simulation centre designed to support practical training for students.

University representatives described the purchase as part of a broader expansion strategy aimed at strengthening healthcare-related study programmes. The institution is preparing to introduce a new dentistry course alongside its existing medical studies, and the additional premises are expected to accommodate specialised laboratories and smaller class groups.

For Indotek, the disposal aligns with a pattern of repositioning its Polish portfolio by selling selected office assets that offer potential for functional change. Market observers note that interest in such properties has grown as educational institutions and other non-traditional occupiers seek well-located buildings that can be reconfigured rather than constructing new facilities from scratch.

Indotek Group, headquartered in Budapest, manages a large real estate portfolio across multiple European countries, covering retail, office, logistics, hotel and mixed-use properties. The sale of the Taifun building reflects a continuing shift in the Warsaw market, where older office stock is increasingly being repurposed to meet evolving demand from sectors outside the traditional corporate tenant base.

front page info
LATEST NEWS