Luxiona leases headquarters and showroom space at Greenwings in Warsaw

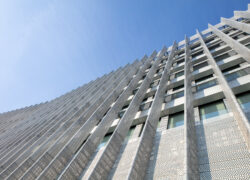
Luxiona has signed a lease for 430 sqm of office space at the Greenwings Offices complex in Warsaw. The premises will serve as the company’s Polish headquarters and include a showroom for its lighting solutions. AXI IMMO advised the tenant in the transaction.

Luxiona is a European lighting manufacturer and supplier headquartered in Barcelona, with operations across multiple markets including Poland, Germany, France and Italy. The group has been active for more than 90 years, delivering lighting systems for commercial, industrial and architectural applications. In Poland, the company operates a commercial office in Ożarów Mazowiecki and a production facility in Jacentów near Ostrowiec Świętokrzyski.

According to Luxiona, the speed of launching operations was a key factor in selecting the new location. The company noted the landlord’s flexibility and the ability to adapt the office space quickly to accommodate showroom requirements.

Anna Piłka-Sutkowska, Advisor in the Office Agency at AXI IMMO, said the search focused on office buildings in Warsaw’s Włochy district due to proximity to Chopin Airport, transport accessibility and convenient access to major exit routes. She added that the client prioritised Class A space offering strong technical standards and functionality.

Luxiona ultimately chose space in the Greenwings building, part of the Greenwings Offices scheme at 48 Komitetu Obrony Robotników Street in Warsaw. Annick Van Hool of Greenwings Offices said the tenant’s clearly defined requirements supported a smooth leasing process and highlighted the importance of providing sufficient parking for showroom visitors.

Greenwings Offices is a seven-storey Class A office building located near Warsaw Chopin Airport. The property offers more than 10,850 sqm of leasable space and 270 parking spaces across three underground levels, along with conference facilities, cyclist amenities and environmental features. The project was designed by JEMS Architekci and built by CFE Polska. The developer was OKRE Development.

Logistics take-up in North Rhine-Westphalia exceeded 1 million sqm in 2025

Logistics and industrial take-up in North Rhine-Westphalia reached 1,147,000 sqm in 2025, surpassing the 1 million sqm threshold for the first time in two years, according to REALOGIS. The analysis covers the submarkets of Düsseldorf, Cologne and the Ruhr area.

The result represents an increase of 203,900 sqm, or 22 percent, compared with 2024, when take-up totalled 943,100 sqm. The 2025 figure also exceeded the five-year average by 7 percent. The largest individual transactions were signed by Amazon (86,000 sqm), FIEGE (55,000 sqm), Goodcang (43,200 sqm), Blitz Distribution (37,000 sqm) and Winnet (36,000 sqm).

Rental levels remained stable across the three analysed markets. Düsseldorf continued to record the highest rents, with prime rents at €8.25 per sqm and average rents at €7.00 per sqm. Cologne reported €8.00 per sqm and €6.85 per sqm respectively, while the Ruhr area remained the most affordable at €7.75 per sqm prime and €6.50 per sqm on average. All figures were unchanged compared with both full-year 2024 and the first half of 2025.

The Ruhr area remained the largest submarket, with take-up of 603,200 sqm. Düsseldorf followed with 299,000 sqm and Cologne with 244,800 sqm. Year-on-year, activity in the Ruhr area increased by 75 percent, while Düsseldorf recorded a 6 percent decline and Cologne fell by 12 percent.

In terms of space type, existing properties accounted for the largest share of activity, totalling 587,800 sqm, or 51 percent of the market. Brownfield developments represented 350,200 sqm, or 31 percent, while greenfield projects accounted for 209,000 sqm, or 18 percent.

By occupier sector, logistics and distribution companies remained the main drivers of demand, leasing 686,200 sqm and representing 60 percent of total take-up. Retail and wholesale occupiers followed with 261,200 sqm, including 191,200 sqm attributed to e-commerce operators. Manufacturing companies leased 145,700 sqm, while other sectors accounted for 53,900 sqm.

Large transactions continued to dominate the market structure. Units of 10,001 sqm and above accounted for 893,000 sqm, or 78 percent of total take-up. Mid-sized categories between 5,001 sqm and 10,000 sqm totalled 104,300 sqm, while space between 3,001 sqm and 5,000 sqm reached 72,000 sqm. Units between 1,000 sqm and 3,000 sqm accounted for 64,500 sqm, and spaces below 1,000 sqm represented the smallest share at 13,200 sqm.

Industrial real estate under construction in the Czech Republic reaches record levels

Demand for industrial real estate in the Czech Republic remained strong in 2025, while the development pipeline continued to expand to record levels, according to Colliers.

Annual gross take-up reached nearly 2.1 million sqm, the third-highest result on record and 6.9 percent above the five-year average. At the same time, investor interest in the sector exceeded €800 million, surpassing the combined total of the previous three years.

“The Czech industrial market experienced a dramatic recovery in the second half of 2025. Since 2015, modern industrial warehouse space has grown by 133%,” said Josef Stanko, Director of Market Research at Colliers. He noted that nearshoring trends and increased demand from Asia-Pacific occupiers have supported market growth.

New supply totalled 229,000 sqm in the fourth quarter, bringing full-year completions to 813,500 sqm. The country’s total modern industrial stock approached 13.3 million sqm, representing year-on-year growth of 7.7 percent. However, the development pipeline remains substantial, with more than 1.6 million sqm currently under construction.

The largest share of development activity is located in the Karlovy Vary Region (21.3 percent), followed by Prague and the Central Bohemian Region (19.2 percent) and the Ústí Region (18.6 percent). The elevated share in Karlovy Vary is largely driven by the construction of a major automated warehouse project in Cheb exceeding 200,000 sqm.

Beyond projects under construction, approximately 2.8 million sqm has secured permitting and is ready to start, while a further 2.5 million sqm is in earlier planning stages awaiting zoning or building approvals.

The vacancy rate increased to 4.9 percent in the fourth quarter of 2025, equivalent to around 655,400 sqm and up 118 basis points year-on-year. In addition, more than 679,000 sqm of speculative space is currently under development without secured tenants, much of it in Prague and the Central Bohemian Region. According to Colliers, much of this space is near completion and could be delivered quickly once pre-leased.

Leasing activity strengthened notably in the second half of the year. Fourth-quarter gross demand rose 47 percent year-on-year to nearly 642,000 sqm, with net take-up accounting for 58 percent of the volume. While the first half of 2025 was driven largely by renegotiations among logistics and transport occupiers, the second half saw manufacturing companies — particularly from the automotive and FMCG sectors — account for 46 percent of demand. Logistics and transport represented 29 percent.

Prime industrial rents remained stable for the sixth consecutive quarter at €7.00–7.50 per sqm per month. Mezzanine office rents typically range between €9.50 and €12.50 per sqm per month, while service charges are generally €0.75–1.00 per sqm per month.

Stanko noted that tenants are increasingly in a stronger negotiating position, which is reflected in more incentive packages from landlords. In some markets with higher recent development activity, including the Moravian-Silesian Region, a modest oversupply is contributing to gradual rent adjustments.

Urban Regeneration, Technology and the Changing Role of Property Management

Property management in Romania is moving beyond traditional building oversight toward a broader role in shaping mixed-use destinations and long-term asset value. For operators such as Nhood Romania, the focus increasingly includes urban regeneration, community integration and performance optimization across multiple asset classes. In this context, Mihaela Petruescu, Country Director for Property Services at Nhood Romania, discusses how the company is adapting its operating model, deploying technology and navigating current market pressures.

Under Petruescu’s leadership, Nhood positions itself as an integrated real estate services provider working across retail, office, residential and mixed-use projects. She emphasises that the company’s work now extends well beyond conventional property oversight, with urban regeneration embedded into how assets are designed, operated and enhanced for clients. According to her, the objective is long-term value creation through the transformation of spaces into sustainable, community-oriented destinations.


A key example is the Coresi District in Brașov, which Nhood manages exclusively for its client. Developed on a former industrial platform, the project has evolved into a multifunctional district combining retail, offices, residential, hotel components and green areas while preserving the site’s historical identity. Petruescu notes that although the retail component is widely recognized, the office element has also become a significant success indicator. Coresi Business Campus currently provides around 75,000 sqm of modern office space and hosts more than 30 national and international companies employing over 6,000 people. The campus also includes approximately 3,000 sqm of coworking and flexible workspace designed for agile teams. Looking ahead, the U1 office building, scheduled for completion in Q3-Q4 of 2026, will add roughly 11,000 sqm of leasable space, with the first 2,000 sqm already reserved.


To monitor performance across its portfolio, Nhood relies on a broad set of indicators covering commercial activity, operational efficiency and user experience. Petruescu explains that visitors’ number, tenant sales, effort rates and occupancy levels remain central measures of asset vitality, while utility consumption has become increasingly important in the context of cost control and sustainability. Through an energy optimization programme that included building management systems and smart metering, the company reports a 31 percent reduction in energy consumption across the assets it manages over the past three years. These metrics, she says, are intended to provide a holistic understanding of performance from commercial, social and environmental perspectives.


Petruescu’s responsibilities span both Romania and Poland, requiring alignment with Nhood’s global strategy while adapting to local market realities. She describes the role as balancing a unified group framework with country-specific execution. While service lines such as property management, rental management, leasing, specialty leasing and operational marketing follow common standards, the Romanian market has developed a distinct profile, particularly in large-scale mixed-use regeneration. Projects such as Coresi have positioned Romania as an internal reference point for integrated redevelopment, with lessons increasingly transferable to other markets depending on their maturity.


Technology has also become a growing focus. Over the past year, Nhood Romania has expanded the use of digital tools within property and asset management, including the deployment of digital twin solutions in commercial centres. Petruescu says these platforms support building diagnostics, predictive maintenance and performance monitoring, helping improve operational efficiency and tenant comfort while supporting longer-term regeneration objectives.


Community activation remains another core pillar of the company’s approach. Rather than treating events and experiential retail as purely promotional tools, Nhood evaluates their impact through a combination of financial and behavioral indicators. Petruescu points to increases in footfall, dwell time and tenant sales following major activations, noting that the company’s managed assets recorded more than 71 million visitors in 2025, with double-digit growth at some locations. Alongside commercial metrics, the company also tracks tenant satisfaction, community participation and broader social impact indicators, reflecting what she describes as a shift toward experience-driven retail environments.


Against the backdrop of persistent inflation and tighter fiscal conditions across Central and Eastern Europe, cost allocation between landlords and tenants has become more sensitive, particularly in retail portfolios. Petruescu notes that the region’s lease structures have generally provided a relatively transparent framework for risk sharing. Most retail leases in Romania apply annual CPI or HICP indexation to base rents, helping preserve income levels, while operating costs and utilities are typically passed through to tenants on an open-book basis. Property managers, she adds, play an important role in mitigating volatility through procurement strategies, competitive tendering and energy-efficiency measures.


Looking ahead, Petruescu suggests that the role of property services providers will continue to expand as assets become more complex and user expectations evolve. The companies that succeed, she argues, will be those able to combine operational discipline with community insight and technological capability. For Nhood Romania, the direction is clear: property management is no longer only about maintaining buildings, but about shaping resilient urban places that can adapt to changing economic and social conditions.

© 2026 cij.world

From device-level controls to portfolio-wide optimization: why Samsung is advancing SmartThings Pro and doubling down on training, comfort and integration.

Samsung is positioning SmartThings Pro as a practical bridge between consumer-level connected ecosystems and the operational requirements of professional building owners.

In a conversation with CIJ Europe, Vlad Croitoru, Business Development Manager at Samsung Climate Solutions Romania, described how the company is approaching multi-building monitoring, interoperability across brands and the role of artificial intelligence in improving energy efficiency and comfort standards. He also discussed the strategic importance of training installers and designers, the integration opportunities following Samsung’s acquisition of FläktGroup, and the growing demand for draft-free climate solutions.

Croitoru explained that SmartThings Pro was designed to simplify what has traditionally been a technically complex environment dominated by heavily programmed building management systems.

“SmartThings Pro, it’s a new solution, it’s a new app that Samsung developed,” he said. “When you’re talking about a BMS, you’re talking about a significant amount of programming.” Samsung’s alternative, he noted, is to approach this from the end-user’s interaction with connected devices and extend that logic into professional property management. “We believe that it’s way better to come from the end-user perspective.”

A central component of SmartThings Pro is interoperability. Croitoru emphasized that SmartThings Pro is built around the Matter protocol, allowing devices from different manufacturers to communicate through a common digital language. “We aim to control every device that can be linked to a Wi-Fi, regardless of the brand, as long as it can be linked to a Wi-Fi and if it’s controlled with the Matter protocol,” he said. He described the advantage for portfolio owners managing multiple locations as immediate visibility and remote control from a single interface.

“If you have a chain with 20 stores, now you can see remotely, from your head office, how the smart equipment is running in each location.”

Automation and scheduling form another layer of the solution’s value proposition. Croitoru pointed to everyday inefficiencies such as lighting or air conditioning left running overnight or cooling systems operating while windows are open. “Maybe you have the air conditioning on and it’s left running during the night. It should not be and with SmartThings Pro you can close it,” he said, adding that these functions are not new in concept but are often difficult to configure. “We don’t invent things now. We only make it way easier for the owner to set and to use.”

Artificial intelligence plays a growing role in refining these processes. Croitoru described AI-driven algorithms that learn occupancy patterns and adapt start-up times for heating and cooling systems to reach comfort targets more efficiently. “We are using AI algorithms that growing the buildings’ energy efficiency level, higher and higher,” he said. Unlike fixed schedules, which may waste energy during mild nights or fall short during hotter periods, AI systems can dynamically adjust. “This kind of efficiency can be achieved only with a learning AI.” He stressed that this capability depends heavily on sensor data. “Everything is sensor-based. Everything is sensor-based.”

While technology is advancing rapidly, Croitoru acknowledged that European privacy regulations limit how deeply behavioral data can be integrated into automation systems. “In Europe it’s a bit tricky because we have the GDPR” he said, noting that the technical potential for more personalized control already exists. “Technology-wise, we are already there. It’s simply a matter of personal choice — how much are we willing to accept?”

Beyond technology, Croitoru highlighted cultural differences in comfort expectations as a key factor influencing energy consumption. He compared heating norms in Germany with those common in Romanian households to illustrate how behavioral patterns can override equipment efficiency. “In Germany, the room temperature during winter is typically 18–19°C. If you go to a Romanian household with a similar climate, they will say that the heating system is not working,” he explained. He added that historical context also shapes present behavior. “I think there is some trauma involved in the former Communist Bloc, because we had very harsh winters without any heating given by the government.”

Even the most efficient systems, he noted, can become inefficient if users consistently select extreme temperature settings. “Everybody is just switching on the air conditioning and putting on 18 degrees. In such cases, even the most efficient equipment becomes inefficient.”

Samsung’s acquisition of FläktGroup represents a significant expansion of Samsung’s indoor climate capabilities. Previously strong in VRF systems and heat pumps, we did not manufacture air handling units or close-control solutions. “FläktGroup is a premium manufacturer of air handling units — something we previously did not have in our portfolio,” he said. “Being in the same group will lead to seamless integration.” He noted that the acquisition also opens new opportunities in data-center and IT-focused projects. “The acquisition also opens access to new segments, particularly data centers and IT-focused projects.”

Training and technical education form another pillar of Samsung’s regional strategy. Croitoru confirmed plans for a dedicated training and experience center in Bucharest aimed at improving standards across design, installation, commissioning and maintenance. “We will cover the design phase, the installation phase, the commissioning phase, the maintenance phase, and of course the service.” He views the initiative as both a market-development effort and a quality assurance mechanism. “It is our responsibility to contribute to raising the level of expertise in the market.”

Replacement projects are also becoming increasingly relevant as older systems reach the end of their economic life. Croitoru noted that equipment installed in the late 2000s is now significantly less efficient than current alternatives. “The efficiency level of the 2008 equipment is significantly different from today’s standards,” he said. “So, if you want to be efficient, upgrading to modern systems becomes essential.”

On the product side, Samsung continues to emphasize comfort-focused technologies such as WindFree™, which successfully eliminates cold drafts while maintaining stable temperatures. “WindFree™, it’s all about comfort. It’s a technology that was invented by Samsung,” Croitoru said, adding that its replication by competitors, reflects market validation. Samsung’s WindFree™ technology provides high-capacity cooling when needed and transitions to a micro-hole airflow pattern during lower load periods, especially at night. “With the micro-holes, users are able to feel the cold air, but without feeling the drafts,” he explained. For markets sensitive to airflow discomfort, he added, the appeal is clear. “For the Romanian market, it’s perfect. We hate the draft; we don’t want to feel any cold drafts.”

While Croitoru declined to reveal specific upcoming product releases, he signaled continued development in digital integration and climate innovation. “We are preparing some nice surprises. Keep an eye on us because you’ll be impressed. There are developments ahead that will further strengthen our position.”

© 2026 cij.world

Tudor Popp (BEYOND-SPACE): Hybrid Hospitality Is Not About Buildings – It’s About Building Communities

As developers across Central and Eastern Europe explore new living and hospitality formats, the idea of “hybrid hospitality” is gaining traction. Tudor Popp, Managing Partner at BEYOND-SPACE, has been closely analysing this shift and recently shared deeper reflections in his article When Everything Became Hospitality. In this interview, he discusses the operational realities, investment questions and organisational changes that will determine whether the model succeeds in the region.

CIJ EUROPE: From concept to execution, what are the biggest operational risks developers underestimate when trying to implement a hybrid hospitality model in Central and Eastern Europe?

Tudor Popp: The biggest risk is the one nobody puts in a business plan: the assumption that a building with interesting functions will spontaneously become a community. It will not. I have seen many beautifully designed mixed-use projects that look great on the website and feel completely lifeless when you walk in. People show up, do what they came to do, and leave. Nothing connects. Nothing stays.

What creates community is not only architecture. It is people whose job is to build it every day, without a clear metric for success and without an obvious place in the traditional developer org chart. In CEE, developers are very good at construction but still uncomfortable with the idea that the most important hire in a new building may be a community manager whose impact cannot be easily measured on a spreadsheet.

The second underestimated risk is technical and regulatory complexity. When you try to design a building for multiple simultaneous functions that were never originally meant to coexist, the gap between concept and code compliance becomes very real. A hotel room, a student unit and a coworking floor have fundamentally different requirements for plumbing, fire safety, access control, ventilation and operational flows. Across much of CEE, the regulatory framework was built for single-use assets, so hybrid projects inevitably require deeper, earlier conversations with planning and permitting authorities.

CIJ EUROPE: How should investors realistically underwrite hybrid hospitality assets when traditional valuation benchmarks and comparables are still limited?

Tudor Popp: I want to be honest here, I am not a financier. But the truthful answer is that nobody has a fully established framework yet. Many of the confident models you see today are essentially old valuation tools applied to a new type of asset.

From an operational perspective, the core question is actually quite simple: does this building become more valuable over time because the community inside it grows, or does it age like a conventional asset when the market turns? That is a fundamentally different way of thinking about value. It is closer to investing in a brand than buying a static property.

The pandemic provided a useful real-world stress test. The Social Hub, because it could flex its rooms between students and hotel guests, remained operationally positive through 2020 and 2021 while many traditional hotels struggled. That resilience came directly from having multiple user groups and revenue streams.

At the same time, there is an important warning in the Soho House story. The brand built a genuinely strong community and still lost money for decades before being taken private in early 2025. The lesson is not that the model cannot work financially, it is that growth speed and experience quality are tightly linked, and that connection is very easy to underestimate when the concept is exciting and capital is available.

CIJ EUROPE: In markets like Romania and Slovakia, which component typically anchors the business case first, and why?

Tudor Popp: My instinct today is that student accommodation is the most credible entry point, and the reason is very straightforward demand.

In Bucharest, Cluj-Napoca, Iași, Timișoara, in almost every Romanian university city, there is a visible shortage of quality, purpose-built student housing. Not dormitories and not informal shared flats, but professionally managed living environments with real amenities and social programming. Western Europe has been building this product for years, while in our region the category is still largely undeveloped.

What makes PBSA such a strong anchor is that it creates immediate baseline energy inside the building. Once students live there year-round, the hotel, coworking, food and beverage and events components become more natural and more financially viable. The building is alive before the tourist even arrives.

The hotel component helps smooth seasonality, while coworking, at least for now in our markets, should be viewed less as a primary revenue driver and more as an activation layer that connects the building to the surrounding neighbourhood.

CIJ EUROPE: What organisational changes must developers make internally, and where do most groups currently fall short?

Tudor Popp: The most important, and uncomfortable, shift for traditional property companies is accepting that the key person in the building is not the asset manager or the property manager. It is whoever is responsible for the experience.

That role barely exists in most CEE developer organisations today. And when companies attempt to fill it, they often hire either a hotel operations profile or a marketing coordinator and expect the concept to work. Hybrid hospitality requires something different: someone whose primary job is to make people feel they belong.

Developers also sometimes assume the concept can simply be handed off after delivery. They design the building, appoint an operator and expect the vision to survive intact. But the concept is not embedded in the floor plan. It lives in daily programming decisions, who is welcomed, how spaces are used, how commercial efficiency is balanced against experience quality.

Based on many years observing office fit-outs, I would add that organisations consistently underestimate how long it takes for a place to develop real character. You cannot accelerate it with a launch party. It is slow, continuous work, and the developers who succeed will be the ones patient enough to let the ecosystem mature.

CIJ EUROPE: Looking ahead five to seven years, which current assumptions about hybrid hospitality do you believe the market may be overestimating or getting wrong?

Tudor Popp: The first assumption I would question is automatic transferability. There is a tendency to look at concepts developed in Amsterdam or Barcelona and assume they will scale at the same speed and price point in Bucharest or Bratislava. I am not convinced. The willingness to pay a premium for community varies significantly between markets, and CEE is still earlier in that behavioural cycle.

The second is the belief that good design substitutes for real programming. We are already seeing projects that look hybrid, attractive communal areas, mixed uses, well-designed interiors, but are delivered by organisations without a genuine commitment to experience management. The risk is a wave of buildings that are architecturally interesting but socially empty. Romania’s first coworking wave provided a clear precedent.

The third, and perhaps most important, is the assumption that you can scale quickly without diluting what made the concept special. The Soho House trajectory illustrates the tension clearly. The brand’s value came from selectivity and curation. Rapid expansion put pressure on that culture. The key question for hybrid hospitality is not how large the platform can become, but how well the experience can be preserved as it grows.

CIJ EUROPE: Your recent article frames hybrid hospitality as a structural shift rather than a passing trend. What is the deeper change developers and investors should understand?

Tudor Popp: What we are seeing is not simply another mixed-use cycle. It is a response to a more fundamental behavioural shift. As I wrote in my recent piece, “The way we work, live, travel and socialise has blurred into something for which we do not yet have a clean vocabulary.”

Traditional mixed-use stacked functions side by side. Hybrid hospitality blends them under a single operating philosophy derived from the best hotels, one focused on making people feel welcomed, comfortable and connected.

From an investor perspective, the appeal is structural adaptability. A building designed under hybrid logic is not a bet on one use remaining dominant. It is a bet on the enduring human need for community and experience, needs that are far more resilient across cycles.

Ultimately, the developers and investors who will succeed are the ones who stop thinking of buildings as containers for functions and start treating them as environments for human experience. The distinction may sound philosophical today, but over the next decade it will become very practical and very visible in performance.

© 2026 cij.world

Coral Construct looks to Moldova expansion and community-driven services as next stage of growth

Coral Construct is extending its footprint beyond Romania’s borders with a new presence in the Republic of Moldova, a move the company describes as both strategic and personal. Speaking to CIJ EUROPE, Cătălin Duma, Managing Partner of Coral Construct, said the decision was influenced by cultural and historical ties as much as by business considerations.


“The expansion in the Republic of Moldova was for us also an emotional step,” Duma explained, noting the long-standing relationship between the two countries. “We feel like there is still a connection between our countries.” He described the move as a natural continuation of the company’s regional development, supported by the shared language and similar cultural habits. The current political direction of Moldova, which is increasingly aligned with Romania and the European Union, was also cited as an encouraging factor.


Coral Construct entered the Moldovan market through a partnership with one of the country’s leading banks, focusing on asset and property management standards modelled on Western European practices. According to Duma, the objective is not rapid short-term expansion but establishing a stable local base and growing in parallel with the country’s economic development. “We didn’t target to develop very fast there, just to be present, to find some serious landlords which need our services and to wait, to be there, waiting for their potential to be achieved.”


Transferring Romanian operational standards to Moldova has, so far, presented fewer obstacles than expected. Language and cultural similarities have eased recruitment and communication. The larger challenge, Duma noted, is educating the market about the value of higher-level facility management services. “The biggest challenge for now is to teach the market that facility management done at another level… it’s the future and that they will need it.”


Despite this, he sees significant long-term potential, particularly in industrial, office and retail segments, drawing comparisons with Romania’s own development cycle two decades ago. The company has already formed a local team and implemented its internal procedures and digital platforms, while also facilitating internships in Romania to accelerate knowledge transfer.


Alongside its geographical expansion, Coral Construct is investing in two internal initiatives designed to broaden its service offering and address structural challenges in the property and construction sectors: Coral Community and Coral Academy.


Coral Community is envisioned as a digital ecosystem linking landlords, tenants and building occupants through a concierge-style platform that goes beyond traditional technical and maintenance services. The system is designed to provide both business-related support and lifestyle benefits for employees working in the buildings managed by Coral. Duma described it as “a living ecosystem that brings together and brings added value to both landlords and tenants,” offering services ranging from operational support to reservations, travel arrangements and access to discounts across restaurants, healthcare, fitness and other everyday needs. The platform is currently in development, with an application phase planned after initial market testing.


In parallel, Coral Academy aims to tackle the shortage of skilled technical labour affecting the construction and facility management industries. The initiative will function as a practical training centre combining classroom theory with hands-on technical instruction using real building systems. Duma pointed to the absence of vocational pathways as a major issue, explaining that many young people lack structured routes into technical professions. The academy is intended to fill this gap by providing accredited training and direct employment pathways. “It’s not just a course for taking you a diploma… it’s a practical school which gives you also the practical knowledge about the skill you want to learn,” he said.


Initially focused on training Coral’s own staff, the academy is expected to open to external participants and partner companies once the model is tested and refined. The approach resembles apprenticeship systems used in Western Europe, combining formal certification with on-site technical experience.


Through its expansion into Moldova and the parallel development of community and education platforms, Coral Construct is positioning itself not only as a property and facility management provider but also as a long-term ecosystem builder within the built environment sector.

© 2026 cij.world

Bulgaria updates Consumer Protection Act to align with EU product safety rules

Bulgaria has introduced amendments to its Consumer Protection Act (CPA), which took effect on 3 February 2026. The changes bring national legislation into line with EU rules on general product safety and collective consumer protection. The updated framework strengthens obligations across the supply chain and clarifies consumer rights in cases involving unsafe products.

Under the revised law, products may be placed on the Bulgarian market only if they comply with EU Regulation 2023/988 on general product safety, which has applied across the EU since December 2024. The rules cover a wide range of consumer goods regardless of the sales channel, including distance sales and online marketplaces. Certain categories remain excluded, such as medicines, food and feed, products of plant or animal origin and antiques.

The scope of the safety requirements has been extended to include second-hand goods as well as products that have been repaired, refurbished or recycled and reintroduced commercially. An exception applies where consumers cannot reasonably expect compliance with the latest standards, for example items clearly marketed as requiring repair or sold as works of art or collectors’ pieces.

The amendments also introduce more detailed responsibilities for producers, importers, distributors, service providers and online marketplace operators. Companies are now required to carry out internal risk assessments and prepare technical documentation before placing products on the market, provide safety information in Bulgarian and maintain registers covering complaints, incidents involving dangerous products, recalls and corrective actions. Online marketplace operators must additionally register with the EU Safety Gate system and appoint a single contact point for communication with consumers and market surveillance authorities.

Consumer remedies have been clarified in cases where dangerous products are recalled. Affected customers are entitled to repair, replacement or a refund. The law also sets out how inspection costs are allocated: authorities bear the costs if a product is ultimately deemed safe, while economic operators must cover them if the product is found to be dangerous.

The revised legislation increases fines for sole traders and companies that place non-compliant products on the market or fail to follow mandatory instructions from the Consumer Protection Commission.

Separate clarifications address price reduction announcements. Traders must indicate the previous price, defined as the lowest price applied during the 30 days preceding the discount. For products marketed for less than 30 days, the reference price must reflect the lowest level applied for at least seven days before the reduction. Perishable goods with short shelf lives are exempt. These pricing clarifications will apply from 5 February 2027.

Finally, the amendments introduce a formal framework for representative actions aimed at protecting the collective interests of consumers. The Consumer Protection Commission and other organisations approved by the Minister of Economy and Industry may be designated as qualified entities empowered to bring such actions under defined conditions.

Source: CMS

Polish Consumer Confidence Edges Up in February but Outlook Weakens, Survey Shows

Consumer sentiment improved slightly in February compared with the previous month, although expectations for the coming months became more cautious, according to the latest consumer tendency survey published by Statistics Poland. The overall indicator measuring current confidence rose modestly, while the forward-looking measure slipped marginally.

The index reflecting households’ assessment of their present situation moved to minus 9.1 points, an increase of 0.5 points from January. Despite the improvement, the value remains in negative territory, indicating that pessimistic views still outweigh optimistic ones. Compared with February last year, however, the indicator shows a noticeable improvement.

Among the elements shaping the current reading, the most significant positive shift was recorded in assessments of the country’s economic prospects. Households also expressed slightly better opinions about their own expected financial position and about recent economic conditions. At the same time, perceptions of the ability to make major purchases and evaluations of current household finances weakened compared with January.

The survey’s forward-looking indicator, which captures expectations for consumption trends in the coming months, declined by 0.3 points to minus 7.0. The drop was mainly linked to reduced optimism about future savings and concerns related to employment prospects. Offsetting these declines were more favourable expectations regarding the broader economy and household financial conditions. Year on year, the forward indicator still shows an improvement.

The study was conducted in early February through more than 1,300 interviews. Both consumer confidence indicators are measured on a scale from minus 100 to plus 100, with negative values signalling a predominance of pessimistic responses.

Additional questions in the survey addressed the perceived impact of the situation in Ukraine on consumer attitudes. Just over half of respondents said current events have a moderate or significant influence on their answers, while nearly 46 percent reported no effect. Among working respondents, roughly half indicated they did not fear losing their job or closing a business due to the situation.

When asked about broader economic implications, around one quarter of respondents described the situation as a major risk to Poland’s economy, while the largest share viewed it as an average threat. Perceived risks to personal finances were lower, with most respondents classifying the impact as small or moderate. Concerns about national sovereignty and independence were more pronounced, with nearly a third identifying a high level of threat, although this share declined slightly from the previous month.

Slovak Inflation Reaches 4% in January 2026 as Housing, Energy and Food Prices Rise

Consumer prices in Slovakia increased in January both compared with the previous month and the same period last year, with inflation reaching 4 percent on an annual basis. The rise was driven mainly by higher costs for housing, utilities and food, while fuel prices declined and seasonal retail discounts slightly reduced clothing and footwear prices.

According to data released by the Statistical Office of the Slovak Republic, prices of goods and services rose by 1.8 percent month-on-month, representing the steepest monthly increase in roughly three years. January typically records stronger price movements due to the introduction of new tax rules and adjustments to regulated tariffs at the start of the year.

The most significant monthly increase was recorded in housing-related expenses, where regulated energy price changes pushed overall costs sharply higher. Heating, gas and electricity all became more expensive, alongside water and sewage charges. Food and non-alcoholic beverages also posted noticeable growth, with fruit, vegetables and confectionery among the categories showing the largest jumps. Soft drinks and other beverages rose markedly following higher taxation on sugar content. Alcohol prices also increased during the month.

Smaller but still visible price growth was seen in leisure services and dining, while transportation costs eased due to lower fuel and airfare prices. Retail promotions at the beginning of the year contributed to a modest drop in clothing and footwear prices.

On a year-on-year basis, prices were higher across nearly all spending categories, with restaurants and hotels among the fastest-growing segments. Housing and food remained the two largest contributors to overall inflation due to their substantial share in household budgets. Energy-related costs recorded some of the strongest annual increases, particularly for district heating, while rents and maintenance expenses also moved upward. Non-alcoholic beverages rose significantly compared with a year earlier, partly reflecting higher coffee prices.

Transportation was the only major category to show an annual decline, supported by cheaper fuels and air travel.

The statistical office also introduced an updated consumer basket structure at the start of the year, expanding the number of expenditure categories and adjusting their weightings based on recent household spending patterns. Housing and energy now account for just under 22 percent of total expenditure, while food and non-alcoholic beverages represent about 21 percent.

Core inflation, which excludes regulated prices and administrative changes, stood below the headline rate, while net inflation, which also omits food, remained slightly higher than core levels. Additional detailed datasets are scheduled for publication later in the month.

front page info
LATEST NEWS