Greece’s Student Rental Squeeze Is Opening the Door to Institutional Housing

Greece has spent years with a mismatch between the number of students needing accommodation and the amount of housing specifically designed for them. Most students continue to depend on conventional privately owned apartments, while university residences accommodate only a fraction of demand. Rising rents are now making that imbalance increasingly important to property investors.

The commercial student-housing sector is no longer negligible. Private investors are developing and operating dedicated residences, while universities are advancing substantial accommodation projects through partnerships with private capital. Nevertheless, Greece remains at an early stage compared with European markets where purpose-built student accommodation has developed into a large and regularly traded institutional asset class.

The pressure is most visible in rents. During the second quarter of 2026, average asking rents for student accommodation across Greece increased approximately 5.3% from a year earlier. Students searching in Athens were working with an average monthly housing budget of around €543, while the corresponding figure in Thessaloniki was approximately €496. At prevailing asking levels, those budgets were sufficient for relatively small apartments of roughly 40 sq m in Athens and 38 sq m in Thessaloniki. Students compete for smaller apartments with young professionals, couples and other tenants, particularly in neighbourhoods with good public transport and access to universities. In cities where tourism and short-term accommodation are also significant, the number of homes available for longer-term occupation can face additional pressure.

Dedicated university accommodation provides only part of the answer. Aristotle University of Thessaloniki, for example, operates four student residences providing approximately 1,500 places, a relatively limited number compared with the scale of its overall student community. The shortage is increasingly being addressed through investment. Greece is progressing a substantial programme of new university accommodation involving private-sector participation. Projects announced during 2026 envisage more than 8,600 additional beds through public-private partnership structures, representing investment of more than €700 million.

One of the clearest examples is the University of West Attica, where plans involve approximately 1,100 new student beds. Under the proposed long-term arrangement, a private-sector partner is expected to finance, design and construct the accommodation and subsequently operate and maintain it. Such projects demonstrate that student accommodation can attract substantial private capital, but they should be distinguished from conventional commercial student housing.

A university-backed project operating under a long concession has different economics from an investor purchasing land or an existing building, developing student rooms and depending directly on rents paid by occupants. The former combines property with infrastructure-style investment characteristics. The latter more closely resembles the commercial student-housing model that has become established across several European markets. Greece is beginning to develop both.

Private property investors are already assembling dedicated student accommodation portfolios. PREMIA Properties, for example, has expanded into the sector through several residences and is developing additional projects. Its acquisition of a building in Kaisariani illustrates one route through which the market can grow: converting existing urban property rather than relying exclusively on new construction. The building, acquired for approximately €6.15 million, is being transformed into a student residence with around 150 rooms. Its significance lies not simply in the number of beds but in the investment model it represents.

Conversions could become an important part of the Greek student-housing market. Athens, Thessaloniki and other university cities contain older commercial buildings that may no longer be competitive in their existing use. Some can potentially be repositioned as student accommodation, particularly where they offer access to universities and public transport. The economics, however, are more complicated than acquiring an inexpensive obsolete building and dividing it into rooms.

Conversions can require structural alterations, completely new mechanical and electrical installations, energy improvements, fire-protection systems, lifts, accessibility work and extensive internal reconstruction. Buildings designed as offices or other commercial premises may also have layouts that make efficient residential conversion difficult. The acquisition price therefore represents only one component of the investment.

Developers must compare the complete cost of creating each bed with the rent students can realistically afford. This is one of the central constraints on the expansion of commercial student housing in Greece. Strong rental demand does not automatically translate into unlimited pricing power. Students and their families generally operate within relatively fixed monthly budgets. A new residence may provide better facilities and professional management than an ordinary apartment, but the rent still has to compete with alternative accommodation in the surrounding neighbourhood.

This creates a difficult balance for developers. Higher construction and financing costs require stronger income, while affordability places a natural ceiling on rents. Projects are consequently most viable where acquisition costs, building efficiency, location and achievable occupancy work together. Scale can improve that calculation. Operating a single small student residence is very different from managing hundreds of rooms across several properties. Larger portfolios can spread management, maintenance, marketing and technology costs across more beds. They can also become sufficiently substantial to attract specialist operators and eventually other institutional investors.

There are signs that this process is beginning. PREMIA already has several student residences and has been expanding its portfolio towards a significantly larger room count. Combined with the university PPP programme and other private projects, this suggests Greece is moving beyond isolated experiments. It does not yet mean the country has a mature institutional student-housing market.

For that to happen, investors need a continuing pipeline of suitable projects, experienced operators, reliable occupancy performance, financing and a secondary market in which completed residences can be sold between professional owners. That final element is particularly important. An institutional property sector becomes substantially deeper when investors know that assets have an identifiable exit market. Building student accommodation can be attractive, but large funds also need confidence that another investor will eventually be prepared to acquire an operating residence or portfolio. Greece has not yet developed that transaction depth at significant scale.

This is what makes the current phase of the market particularly interesting. The underlying housing shortage has existed for years. What is changing is the amount of organised capital attempting to address it. The opportunity also extends beyond Athens and Thessaloniki. Greece has universities in numerous regional cities where students create significant rental demand. The investment case in those locations will depend less on absolute rents than on the relationship between student numbers, existing accommodation, property acquisition costs and achievable monthly income. Some smaller university cities could potentially offer better development economics than the country’s most expensive residential markets.

Student accommodation may also have a wider effect on housing availability. Every substantial purpose-built residence creates housing specifically for a population that would otherwise compete in the conventional rental market. Large-scale student-housing development will not solve Greece’s broader affordability problem, but additional student beds could reduce some pressure on small apartments in university neighbourhoods.

For investors, however, the central issue remains whether demand can be converted into a scalable property product. Greece clearly has students requiring accommodation. It has rising rents, limited university housing and a growing pipeline of publicly backed and privately developed residences. It is also beginning to produce professional owners capable of building portfolios rather than treating student accommodation as a single-project opportunity.

What remains to be demonstrated is whether those ingredients can create a sufficiently large and liquid investment market. If the next generation of projects achieves sustainable occupancy and rents while additional institutional investors and specialist operators enter the country, student accommodation could develop into a meaningful component of Greece’s living-sector investment market. The shortage itself is already evident. The investment story now depends on whether Greece can build enough professionally operated accommodation to turn that shortage into a durable institutional property sector.

Source: CIJ.World Research & Analysis Team
Skanska Commits €66m to First Stage of Kraków’s Nowy Format Office Campus

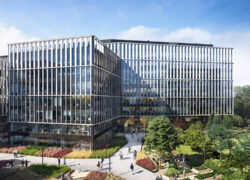
Skanska is investing approximately €66 million in the first phase of its Nowy Format office development in Kraków, with construction of the initial building scheduled to begin in the fourth quarter of 2026.

The first property, Nowy Format A1, will comprise nine storeys and provide 21,400 sqm of leasable space. The construction contract is valued at approximately PLN 140 million and will be recorded in Skanska’s European order intake for the third quarter of 2026. Completion of the building is planned for the third quarter of 2028.

Nowy Format is being developed on the site of a former printing facility in central Kraków. Once all phases are completed, the complex is expected to consist of three buildings providing approximately 48,000 sqm of leasable space.

The first building will include a 1,800 sqm garden, more than 300 sqm of private terraces for occupiers and an urban fruit orchard. The landscaping forms part of a wider design intended to provide substantial outdoor space within the office development.

Skanska is also planning the building without a connection to Kraków’s municipal heating system. Heat pumps and other technologies will provide heating and thermal management, while the wider complex is intended to operate entirely on electricity sourced from renewable generation and backed by guarantees of origin.

Nowy Format A1 is being developed with LEED Core & Shell, WELL Core & Shell and Building without Barriers certifications in mind. Skanska also intends the development to meet the requirements of the EU Taxonomy.

The location provides access to one of Kraków’s main tram interchanges, while Kraków Airport can be reached in approximately 30 minutes by car. The combination of public transport access and the redevelopment of an existing urban site positions Nowy Format as another significant addition to Kraków’s next generation of office stock.

Outdoor Concept and Raben Take Space at P3 Plzeň Myslinka

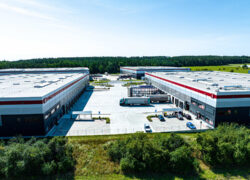
P3 Logistic Parks has added two tenants to its P3 Plzeň Myslinka industrial park in western Czechia, with Outdoor Concept and logistics operator Raben beginning operations at the site in September. Outdoor Concept has leased 3,500 sqm of warehouse space together with 40 sqm of offices. The company develops outdoor clothing and equipment through brands including Hannah and Rafiki, distributes international outdoor brands across Czechia and Central and Eastern Europe, and operates the Rock Point retail network. The Myslinka facility will primarily be used for clothing storage and regional distribution.

Raben has taken 3,350 sqm of warehouse space and 315 sqm of administrative facilities, while P3 is preparing an additional second-floor office area for the logistics company. The new operation will strengthen Raben’s presence in western Czechia, complementing its existing network of ten locations across the country supporting domestic and international road transport, contract logistics and warehousing.

The two leases demonstrate the mix of occupier demand being attracted to modern industrial properties in the Plzeň region. While Raben represents conventional logistics demand, Outdoor Concept will use its premises to support a retail and distribution business serving markets across Central and Eastern Europe.

P3 Plzeň Myslinka is located approximately 21 km from Plzeň and provides access to the D5 motorway towards Germany. The park is also close to a railway station and freight terminal and is situated near P3’s other industrial park in Nýřany. Existing occupiers at Myslinka include RSF Elektronik, WM Logistic Nýřany and HP Pelzer.

The park currently comprises four buildings providing a combined 34,406 sqm. P3 also has capacity for another build-to-suit facility of almost 30,000 sqm, potentially increasing the overall size of the location to more than 64,000 sqm if the additional development proceeds.

All four completed buildings hold BREEAM Excellent certification. Features incorporated across the park include LED lighting, rainwater reuse systems, enhanced insulation and roofs prepared for photovoltaic installations. Solar panels have already been installed on Hall C, while landscaped areas, a retention pond and outdoor exercise facilities form part of the wider site.

The arrival of Outdoor Concept and Raben expands the tenant base at P3 Plzeň Myslinka while P3 retains substantial capacity for further development at the location.

Helsinki’s Office Recovery Is Leaving Hundreds of Buildings Behind

Helsinki’s office market is producing an increasingly unusual contradiction. Companies are competing for good workspace and investors remain interested in high-quality office property, yet a substantial amount of existing space across the metropolitan area remains vacant. The explanation is becoming clearer. Helsinki does not simply have too much office space. It has a growing mismatch between the buildings available and the buildings that today’s occupiers actually want.

Vacancy across the Helsinki Metropolitan Area has reached approximately 15.3%, according to Newsec, but the picture changes dramatically at the top of the market. Among the highest-quality offices in Helsinki’s central business district, vacancy has been measured at only around 5.8%. The difference suggests that the metropolitan vacancy figure increasingly combines two very different markets. Modern, efficient and well-located offices can attract tenants, while substantial quantities of older or less competitive space struggle to participate in that demand.

Companies have changed the way they use their workplaces. Hybrid working has allowed many businesses to reduce their overall space requirements, but it has not eliminated the office. Instead, employers are becoming more selective about the space they retain. That puts greater emphasis on accessibility, public transport, energy performance, services, meeting facilities and the overall working environment. A company occupying fewer square metres can potentially afford to concentrate its employees in a better building.

For owners of secondary offices, this creates a difficult problem. Cutting rents may attract some tenants, but price alone cannot correct poor accessibility, inefficient layouts, outdated technical systems or high operating costs.

The investment market shows a similar pattern. Approximately €122 million was invested in Finnish office property during the second quarter of 2026. Over the preceding 12 months, office transaction volume reached approximately €357 million, representing a decline of around 24% compared with the previous year. Pricing continues to distinguish sharply between Helsinki’s strongest locations and other established office districts. Prime CBD yields were around 5.50% during the second quarter, compared with approximately 6.25% in Pasila, Ruoholahti and Keilaniemi.

But yields tell only part of the story. An investor considering a modern building with strong tenants can make relatively conventional assumptions about rent, occupancy and future income. Buying a partially empty secondary office requiring extensive refurbishment is an entirely different investment.

The acquisition price may look attractive after the correction in Finnish property values, but the purchase is only the beginning. Older buildings can require significant expenditure on heating, cooling, ventilation, façades, energy efficiency, lifts, common areas and tenant facilities before they can compete with newer stock. There may then be additional costs associated with leasing incentives and periods without rental income while the property is repositioned.

That means Helsinki’s secondary office market ultimately has to answer a financial question: how far must the purchase price fall before the cost of modernising an older building becomes economically worthwhile?

For some properties, that calculation will eventually work. A building in a good location with a flexible structure may offer an attractive opportunity once its acquisition price reflects the required capital expenditure and leasing risk. Investors willing to undertake substantial refurbishment could then return the property to the competitive office market.

For other buildings, the numbers may never work as offices. This is where Helsinki’s growing experience with conversions becomes increasingly relevant.

The city has already enabled significant quantities of former commercial property to move into residential use. Planning changes since 2015 have facilitated roughly 200,000 sqm of new residential space, with former offices forming part of that transformation. The process is changing entire districts rather than only individual properties.

Ilmala, for example, is gradually moving away from its traditional character as a predominantly employment-focused area. Former commercial plots are being considered for housing and mixed development as Helsinki seeks to introduce more residents and services into areas previously dominated by offices. Lauttasaari has also demonstrated how obsolete commercial property can be redirected towards housing and other uses when continued office operation no longer makes sense.

The opportunity is significant because conversion can solve two urban problems simultaneously. Helsinki needs additional housing, while parts of its existing office stock are experiencing persistent vacancy. Yet converting offices into apartments is far from straightforward.

Buildings designed for large workplaces can have deep floorplates that make residential layouts difficult. Apartments need appropriate daylight, ventilation, entrances, bathrooms and services. Structural columns and existing cores can restrict layouts, while façades may require substantial alteration. A property that appears suitable for housing when viewed from the street can therefore prove prohibitively expensive once its structure is examined.

Other uses could provide alternatives. Student accommodation, hotels, healthcare facilities and serviced apartments may work in some locations. But these options also depend on local demand, building configuration and planning.

Helsinki is consequently developing a category of property for which there is no simple solution. These are buildings that struggle to attract office tenants, require too much investment to compete with modern stock and are difficult to convert economically into another use.

For some, the long-term answer may be redevelopment. Once the income value of an existing office falls sufficiently, the value of the underlying land and its redevelopment potential can become more important than preserving the building itself. Demolition followed by residential or mixed-use construction may then become the most rational outcome, particularly where municipalities are prepared to alter planning regulations.

This could gradually transform parts of Helsinki, Espoo and Vantaa. Business districts created during previous development cycles were often designed around large concentrations of office employment. If companies permanently require less space, some of these areas may eventually need more housing, services and other activities to remain economically active throughout the day.

Transport connections will play an important role in determining which districts adapt successfully. Properties close to metro and railway stations may have greater potential because they remain attractive to both occupiers and alternative uses. Buildings in isolated business parks with weaker public transport could face a more difficult adjustment.

The same distinction applies at building level. Helsinki’s office stock can increasingly be divided into several categories. There are competitive buildings capable of attracting tenants without major intervention. There are properties that can remain offices after significant modernisation. There are buildings where conversion offers a more convincing future. And there are properties where the existing structure may eventually be worth less than the redevelopment opportunity underneath it.

These categories are not permanent. A property that is currently too expensive to refurbish can become viable if its purchase price falls. A conversion that does not work under existing planning rules can become possible following a change of use. A poorly performing site can gain value if surrounding infrastructure or transport connections improve.

This helps explain why high vacancy has not automatically produced a rush of investment into discounted Helsinki offices. Cheap property is not necessarily attractive property. An investor buying secondary office space must effectively purchase both the existing building and the problem attached to it. The discount therefore needs to be large enough to finance the solution.

The Helsinki office market is consequently moving beyond a conventional cycle of falling occupancy followed by eventual recovery. Demand is returning selectively rather than evenly. Better buildings are capturing tenants while weaker properties risk remaining vacant even as leasing conditions improve elsewhere.

The next stage will therefore be less about predicting when metropolitan vacancy starts falling and more about determining how much of today’s vacant stock should continue functioning as offices. Helsinki still has a healthy market for buildings that companies genuinely want to occupy and investors are prepared to own. Its much bigger challenge is deciding what to do with the buildings that no longer fit either requirement.

Source: CIJ.World Research & Analysis Team
Crestyl and WOOD & Company Launch CZK 4bn Residential Project in Prague 6

Crestyl and investment partner WOOD & Company are moving ahead with the Šárka residential development in Prague’s Vokovice district, with investment in the project expected to exceed CZK 4 billion. The scheme will replace a former industrial and logistics complex close to the Divoká Šárka nature reserve with a new residential neighbourhood containing 224 apartments, four detached houses and supporting public amenities.

The development has a valid building permit, while demolition of the former commercial premises on the site has now been completed. Construction of the first phase is scheduled to begin around the end of 2026, delivering 98 apartments. Completion and occupancy approval for this stage are planned for 2029, with public sales expected to start this autumn.

The overall development will comprise 18 residential buildings containing 224 apartments, together with four houses positioned close to the adjoining woodland. Apartments in the first phase will range from two-room to five-room layouts, with floor areas between 62 sqm and 165 sqm. Penthouses will also form part of the residential mix, while parking will primarily be located underground.

WOOD & Company is participating as the project’s strategic investment partner. Šárka represents the third acquisition for its residential sub-fund, which invests in development projects alongside established residential developers. As of the end of June 2026, the fund reported net assets exceeding €81 million.

The revised architectural concept has been prepared by Chmelař Architekti, led by David Chmelař. The buildings have been designed with varying heights and setbacks intended to respond to the landscape around Divoká Šárka, while stone and timber will feature prominently across the development. Terraces, balconies and private gardens are planned throughout the residential scheme.

The project will also provide infrastructure intended for the wider Vokovice neighbourhood. Plans include a kindergarten for 50 children, which Crestyl intends to transfer to Prague 6 following completion without charge. A separate building close to the public transport stop is planned for publicly accessible commercial and service uses, potentially including retail, healthcare and food and beverage operators.

Landscaped areas will run between the residential buildings, while a new woodland playground and exercise facilities are planned close to the forest. Crestyl has also said it will participate in transport improvements within the wider Vokovice area.

Šárka adds another sizeable residential scheme to Prague 6 at a time when the availability of new housing remains an important issue for the capital. The redevelopment will also remove an obsolete industrial and logistics site and replace it with predominantly residential uses, public landscaping and local services immediately beside one of Prague’s largest protected natural areas.

Riga’s New Housing Market Faces a Fivefold Price Divide

Riga is adding new apartments, residential construction is strengthening and developers continue to prepare projects for the market. Yet most apartment buyers are still purchasing homes constructed decades ago. The difference is not marginal. It reveals a substantial divide between the price of the housing being produced today and the part of the market where most transactions are actually taking place.

During the second quarter of 2026, building construction output across Latvia increased by 12.6% compared with the same period a year earlier. Residential construction was among the areas contributing to the increase, while developers continued adding apartments to their pipelines. The transaction market, however, remains heavily dependent on Riga’s existing housing stock.

In June, approximately 66.6% of registered Riga apartment transactions involved homes in buildings dating from the Soviet period between 1946 and 1993. Apartments in properties constructed from 1994 onwards represented only around 17.6% of transactions. July reinforced the pattern. Soviet-era housing accounted for approximately 69.1% of apartment transactions, while properties completed since 1994 represented around 15.4%.

The reason becomes clearer when transaction values are examined. During June, the average transaction involving a Soviet-era apartment was approximately €37,000. For apartments in buildings completed from 2015 onwards, the average was close to €187,000. That means the average amount paid for a relatively new apartment was roughly five times the average transaction value for a Soviet-era property.

The comparison is not perfect. Newer apartments can be larger, better located or have parking and other features that increase the total transaction value. Nevertheless, the difference illustrates the enormous financial distance separating different sections of Riga’s housing market. Prices per square metre tell a similar story. Soviet-era apartments traded at an average of around €775 per sqm in June, compared with approximately €2,815 per sqm for apartments in buildings completed from 2015 onwards.

For households deciding where they can afford to live, that difference can determine the entire housing search. An older apartment may require renovation and could be located in a building facing future expenditure on insulation, heating systems, lifts, roofs or common areas. A newer home should generally provide better energy performance, modern building systems and fewer immediate capital requirements.

Those advantages matter, particularly as energy costs become an increasingly important part of household expenditure. But they do not eliminate the initial purchase-price problem. A household capable of financing a €40,000 or €60,000 apartment cannot automatically move into a €170,000 or €190,000 property simply because the newer home costs less to heat.

Mortgage affordability becomes the dividing line. Higher purchase prices require larger deposits, greater household income and substantially higher monthly repayments. Even households that would prefer a modern apartment can therefore find themselves directed towards older properties by the amount banks are prepared to lend.

This helps explain why Riga’s Soviet-era housing stock continues to dominate transactions. The buildings are ageing, and many will require increasing investment, but they perform an essential economic function. They provide an ownership market at price levels that modern development cannot easily reproduce. The city’s affordable ownership market therefore depends heavily on homes constructed under an economic system that disappeared more than three decades ago.

Contemporary developers operate under completely different conditions. Land must be purchased, construction financed, contractors paid and increasingly demanding building and energy standards satisfied. These costs establish a level below which new apartments become difficult to deliver profitably.

There are already indications that asking prices and actual purchasing power are not always aligned. Recent analysis of Riga’s new-build market has identified a meaningful difference between advertised prices and the values at which transactions are eventually completed. Buyers are also considering relatively recent second-hand apartments and renovated older buildings as alternatives to purchasing directly from developers.

This creates another layer of competition. A newly completed apartment does not compete only with other new developments. It competes with almost every acceptable home available to a household within its mortgage limit. For developers, the critical question is therefore whether the number of households capable of buying new housing is expanding quickly enough to absorb the development pipeline.

That does not mean Riga lacks buyers for new apartments. Higher-income households, existing homeowners trading up, returning Latvians and investors can all provide demand. New developments also offer advantages that older buildings cannot easily match, particularly energy efficiency and modern technical standards. The challenge is broadening that buyer pool.

One possible response is smaller apartments. Developers can reduce the total purchase price by delivering more compact units even when construction costs prevent significant reductions in the price per square metre. This strategy has limits. Families require adequate living space, while hybrid working has increased the importance of having enough room to work at home.

Development location could provide another solution. Land outside Riga’s most expensive areas may allow developers to produce homes at lower total prices. Improved transport connections could consequently increase the attractiveness of suburban development, particularly for households prepared to exchange a central location for more space.

Developers could also reconsider specifications. The market may increasingly distinguish between features buyers consider essential and those they are unwilling or unable to finance. Energy efficiency and building quality are difficult to compromise, but parking arrangements, interior finishes and communal amenities can have significant effects on total development costs.

Rental housing offers another possible direction. Households unable to finance the purchase of a modern apartment may still be capable of renting one. A larger professionally managed rental sector could therefore provide another route for new residential development, although Latvia’s institutional rental market remains relatively small.

Financing will also influence the outcome. Mortgage conditions and programmes helping households with deposits can expand access to homeownership. However, financial support cannot permanently compensate for a large structural difference between household incomes and property prices.

The ageing housing stock presents the other side of the problem. Soviet-era apartments remain affordable partly because of their age. As buildings require more substantial renovation, owners may face increasing contributions towards improvements. Successful renovation could extend the useful life of these properties and reduce energy consumption, but it could also increase the cost of occupying them.

Riga therefore faces two connected housing challenges. It needs to maintain and improve the older buildings that provide much of today’s affordable ownership market while simultaneously finding ways to make newly constructed housing accessible to a larger section of the population.

Transaction data show how large that challenge has become. When roughly two-thirds of apartment purchases take place in Soviet-era buildings and the average transaction value of a relatively new apartment can be around five times higher, the market is sending a clear signal about where purchasing power is concentrated.

Riga is not short of households wanting better housing. The more difficult question is how many can finance the housing currently being built. Until that gap narrows, the city’s older apartment blocks will continue carrying a disproportionate share of Riga’s ownership market, while developers search for ways to bring the economics of new construction closer to the budgets of ordinary buyers.

Source: CIJ.World Research & Analysis Team
Unibep Builds Larger Pipeline as Profitability Takes Priority Over Turnover

Unibep could see its order book approach PLN 6 billion as several large contracts move towards finalisation, while the Polish construction group maintains a more selective approach to new business and prepares for the possibility of lower general construction revenue in 2026.

The company currently estimates its backlog at around PLN 4.5–4.6 billion. That figure could move close to PLN 6 billion if major projects in the pipeline proceed to signed contracts. Among them are works connected with the E75 Białystok–Ełk railway section and a planned sports and entertainment arena in Białystok. At the end of June, the combined construction and modular backlog stood at approximately PLN 3.66 billion.

The larger pipeline follows a first half in which Unibep deliberately limited the amount of new work it accepted. New contracting across the construction business was substantially lower than a year earlier, reflecting management’s decision to focus more heavily on the expected profitability of projects rather than expanding turnover through less attractive contracts.

This approach is visible in the group’s first-half financial performance. Consolidated revenue declined 17.3% year-on-year to PLN 856.6 million, but gross profit from sales remained close to the previous year’s level at PLN 80.9 million. As a result, the gross margin increased to 9.4% from 7.9%. Construction revenue fell 28.4% to PLN 648.4 million, while the segment’s gross margin improved to 10.2% from 6.9%.

Management has indicated that general construction revenue may remain below the 2025 level for the full year because the first-half shortfall is unlikely to be completely recovered. Part of the difference could be offset by stronger activity at Unihouse, where modular construction revenue increased sharply during the first six months of the year.

Residential development is also showing stronger sales activity. Unidevelopment sold 164 homes during the first half of 2026, compared with 110 a year earlier, representing an increase of 49%. Unibep is aiming for approximately 300 residential sales over the full year, although management has acknowledged that reaching this level will depend on market conditions.

The developer is also looking to replenish its land portfolio, with Warsaw remaining the immediate priority and the Tricity market expected to receive greater attention in subsequent periods. Management does not currently intend to expand Unidevelopment into additional regional markets.

The combination of a potentially much larger construction pipeline, improving margins, expanding modular activity and stronger residential sales suggests that Unibep is entering the second half of 2026 from a stronger position than its headline revenue decline might indicate. The key issue will be how much of the prospective workload converts into signed contracts while the group maintains the improved profitability that has become central to its contracting strategy.

Dutch Retail Investment Is Returning to the Places People Use Most

Dutch retail property has returned to investors’ attention in 2026, but the capital flowing into the sector is revealing a very different market from the one that existed before online shopping transformed the industry. Investors are buying retail again, yet they are concentrating increasingly on properties where customer demand is frequent, locations are difficult to replace and the buildings have a clear role within their communities. Around €1.2 billion was invested in Dutch retail property during the first half of 2026, almost 30% more than during the corresponding period last year. Retail represented approximately 17% of total Dutch real estate investment, its largest share since 2017. Leasing activity also accelerated, with approximately 278,600 square metres taken up during the second quarter, more than twice the level recorded a year earlier.

Those numbers could suggest a broad revival in shopping property, but the composition of investment tells a more revealing story. Around 60% of first-half retail investment was directed towards convenience-focused shopping centres, neighbourhood centres and supermarkets. Rather than making a general bet on physical retail, investors appear to be concentrating on formats connected to regular household spending and locations that people repeatedly use. Supermarkets sit at the centre of this strategy. Grocery shopping remains embedded in everyday consumption, giving well-located supermarket properties characteristics that differ substantially from more discretionary forms of retail. For investors, the attraction can include recurring customer demand, established catchment areas and leases with major operators. The quality of each property still depends on the tenant, lease structure, accessibility, competition and surrounding population, but supermarkets have increasingly become one of the clearest routes for capital seeking exposure to Dutch retail.

Neighbourhood and convenience centres extend the same investment logic. A successful local centre can combine a supermarket with pharmacies, food outlets, personal services and other businesses serving frequent household needs. Its purpose is not to persuade consumers to spend an entire day shopping. It is to become part of their normal weekly routines. That characteristic can make these properties attractive to investors seeking relatively predictable income. Their prospects can also benefit from residential growth. As Dutch cities add housing and increase density within existing urban areas, some neighbourhood centres gain additional customers without requiring a corresponding expansion in their physical footprint. Recent transactions demonstrate that this is no longer simply a theoretical investment argument. Large portfolios of Dutch neighbourhood shopping centres have attracted institutional and private capital, providing evidence that investors are prepared to commit substantial amounts to properties supported by convenience-oriented spending.

Retail parks are developing into another increasingly important category. Vacancy across Dutch retail parks stood at approximately 4.4% in June 2026, below the wider national retail-property level. Many locations have little or no immediately available space, suggesting that the strongest parks are operating within relatively tight occupier markets. More importantly, the range of businesses considering these locations is widening. Retail parks were traditionally associated heavily with furniture, home improvement and other businesses requiring large stores. They are increasingly attracting concepts connected with sport, fitness, leisure and convenience alongside their established occupiers.

This broadening tenant base could materially change the investment characteristics of the format. A retail park dependent on a narrow group of large-format retailers presents a different leasing risk from one capable of accommodating several types of businesses. More potential uses can provide owners with greater flexibility when units become available. The physical characteristics of retail parks also help explain their appeal. They commonly provide large units, straightforward road access and substantial parking. Occupancy costs can be more manageable than in prime city centres, while customers are accustomed to travelling directly to these locations for particular purchases or activities. Investor interest has followed. More than €220 million has been invested in Dutch retail parks between 2024 and 2026, while specialised investment strategies targeting the format have begun to emerge. The amounts remain modest compared with the country’s largest property sectors, but they indicate that retail parks are increasingly being considered as a distinct investment proposition rather than simply a secondary part of the retail market.

Prime high streets are following a different trajectory. The best city-centre locations remain valuable to brands seeking visibility and direct access to large concentrations of consumers, workers and visitors. Prime Dutch high-street rents increased by approximately 6.5% during the first half of 2026. The important detail is that this growth is becoming concentrated within relatively small sections of the strongest streets. That creates significant differences even within individual city centres. A property on the dominant pedestrian route can experience strong retailer demand while another only a short distance away faces a much more difficult leasing environment.

Amsterdam remains particularly important because of its international visitor base and concentration of major retailers, but the principle applies more widely. Investors cannot assess high-street property simply by looking at citywide averages. Individual streets, pedestrian patterns, surrounding occupiers and the flexibility of the building increasingly determine performance. This creates both risk and opportunity. Strong high-street properties can continue attracting international and domestic brands, while weaker streets may require lower rents, different tenants or alternative uses. Upper floors can also become important. Where planning and building configuration allow, space above shops may support housing, offices or other activities, allowing investors to extract value from more than the retail frontage.

Shopping centres require an equally selective approach. Dominant centres serving large catchment areas can remain attractive because their scale allows owners to manage tenant mix, introduce new concepts and respond to changing consumer behaviour. Successful centres increasingly combine shopping with food, leisure, services and other activities capable of generating reasons to visit beyond purchasing goods. The challenge lies with secondary centres that lack the same dominance. A shopping centre can continue producing rental income while gradually losing customers and retailer demand. If the surrounding population, competing destinations or changing consumer behaviour reduce the amount of retail space required, maintaining the entire property as shops may eventually become difficult.

Some of these properties could offer opportunities for investors prepared to undertake more complicated repositioning. Parts of a centre might eventually accommodate housing, healthcare, leisure, community services or other functions where planning and local demand support them. Such projects should not be considered a universal solution, but they provide an alternative where conventional retail no longer justifies the amount of space available. The contrast between these different formats explains why the approximately €1.2 billion invested during the first half of 2026 should not be interpreted as investors deciding that all Dutch retail has become attractive again.

Capital is differentiating sharply. A supermarket-anchored neighbourhood centre serving everyday needs has little in common with a secondary shopping centre struggling to maintain its tenant base. A successful retail park with low vacancy and an expanding range of potential occupiers represents a different proposition from a weak high-street property outside the strongest pedestrian routes. All are classified as retail, but investors are increasingly pricing them according to very different sources of demand and risk.

This separation is changing investment strategies. Buyers seeking stable income can concentrate on supermarkets, convenience centres and dominant retail locations. Investors prepared to undertake more active management can target properties where improving the tenant mix or repositioning space can increase income. Development-oriented capital can consider secondary centres and larger retail sites where alternative uses may ultimately produce greater value. The distinction also changes how investors need to think about retail risk. Lease length and tenant strength remain important, but they cannot explain whether a property will remain relevant over the next decade. Investors increasingly need to understand why consumers visit the location, how frequently they return and how easily the property can accommodate different businesses if shopping patterns continue changing.

The strongest retail assets have a clear purpose. They provide food, services, convenience, leisure, brand exposure or experiences that remain valuable despite the growth of online commerce. The weakest properties face a more difficult question about why customers and retailers need them at all. This is why the return of investment capital to Dutch retail could prove more significant than a conventional cyclical recovery. Investors are not simply returning because pricing has changed or transaction markets have improved. They are increasingly identifying particular formats that appear capable of generating sustainable demand.

The evidence is clearest in the concentration of investment. With convenience-focused centres, neighbourhood schemes and supermarkets accounting for around 60% of first-half retail transactions, capital is already indicating where it sees the strongest defensive characteristics. Retail parks are developing another institutional proposition, supported by relatively low vacancy and a broader occupier base. Prime high streets remain valuable but increasingly concentrated around the strongest locations. Dominant shopping centres can continue functioning as managed destinations, while weaker centres may require substantial repositioning.

Dutch retail is therefore not returning as a single institutional property category. It is becoming a collection of distinct investment markets, each driven by different forms of consumer demand, occupier behaviour and property economics. The most important development in 2026 may not be that €1.2 billion has returned to the sector. It is where that money is going. Investors appear increasingly willing to own Dutch retail again, but only when they can clearly understand why people will continue using the property.

Source: CIJ.World Research & Analysis Team
New Investors Join Prague’s Savarin Redevelopment After Competition Approval

The ownership structure behind Prague’s Savarin development is changing following regulatory approval for the entry of J&T and a company associated with Czech investor Richard Morávek into the major city-centre project. The Czech Office for the Protection of Competition has cleared the transaction involving J&T RFI VIII and PERRARUS HOLDING. Following completion of the deal, Savarin JV will be jointly controlled by Savarin HoldCo and JPTR, with J&T RFI VIII and PERRARUS HOLDING participating through JPTR alongside Crestyl’s existing involvement in the development.

The competition authority concluded that the transaction would not create significant competition concerns. Financial terms and the size of the interests being acquired by the incoming investors have not been disclosed. The arrival of additional investors represents another step in the development of Savarin, one of the largest regeneration schemes planned in Prague’s historic centre.

Located immediately beside Wenceslas Square, Savarin is intended to open up a substantial part of an existing city block that has historically had limited public access. The development will establish pedestrian connections between Wenceslas Square and Na Příkopě, Panská and Jindřišská streets, combining new commercial uses and public areas with the restoration and reuse of historic buildings.

A restored former riding hall will form one of the principal elements of the development. The surrounding area is planned to include a new public square and garden, together with restaurants, cafés and other commercial premises. Cultural and exhibition spaces are also included in the wider concept, alongside an additional entrance to Prague’s metro network.

The masterplan has been developed by Heatherwick Studio, the London-based architecture and design practice founded by Thomas Heatherwick. The concept combines the preservation of important historic structures with new buildings, pedestrian routes and publicly accessible spaces within the existing urban block.

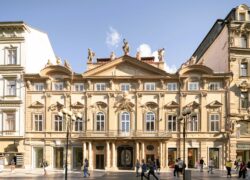
Crestyl has already completed the restoration of the Baroque Savarin Palace as an initial stage of the wider development. Future phases will extend the transformation deeper into the surrounding courtyards and connect areas that are currently separated from the main pedestrian routes through this part of central Prague.

Savarin is currently scheduled for completion in 2029. The entry of J&T and PERRARUS HOLDING into the investment structure brings additional capital partners into one of the most prominent redevelopment projects around Wenceslas Square as it moves towards its next stages.

Civil-Law Contract Workforce in Poland Expands by 82,000 in a Year

The number of people in Poland working exclusively through civil-law arrangements increased noticeably over the year to March 2026, highlighting the continuing importance of work outside conventional employment contracts. At the end of March, 1.477 million people were working exclusively under contracts of mandate and comparable arrangements, according to Statistics Poland. This was 82,000 more than in March 2025, representing annual growth of 5.9%. Compared with the end of December 2025, however, the number declined by 20,900, or 1.4%.

A further 20,300 people worked exclusively under contracts covering the completion of a specified task during March. Unlike the mandate-contract figures, which represent the number of people working under such arrangements at the end of the month, this figure measures people who entered into a specified-task contract during March. Men represented a slight majority of people working exclusively under mandate and related contracts, accounting for 51.5% at the end of March. Their number increased 6.1% year-on-year, compared with growth of 5.6% among women.

Administrative and support services accounted for the largest concentration of these workers. The sector, which includes employment placement agencies among its activities, had 312,600 people working exclusively under mandate and related arrangements at the end of March. This represented 21.2% of the national total, meaning that more than one in five people covered by the statistics worked in this broad area. Health and social work represented the second-largest category, with 154,600 people, equivalent to 10.5% of the total.

The sector distribution also covers areas closely connected with the property economy, including construction, manufacturing, transportation and storage, real estate, professional services and accommodation. The figures provide a broader picture of a segment of Poland’s workforce that can be difficult to identify through conventional employment statistics.

The population measured by Statistics Poland does not include people already classified as employed in the national economy, students under the age of 26 or people carrying out comparable work without remuneration. The data are based on administrative information held by Poland’s Social Insurance Institution, ZUS.

Statistics Poland refined its methodology for identifying people working exclusively through these contractual arrangements, and from 2026 the figures have been classified as official statistics rather than the experimental data published for periods up to the end of 2025.

The 5.9% annual increase therefore provides an additional perspective on changes taking place in Poland’s labour market. While conventional employment indicators remain important for assessing economic conditions, almost 1.5 million people were earning exclusively through mandate and related civil-law arrangements at the end of March.

For businesses and sectors dependent on flexible labour, the figures underline the scale of this part of Poland’s workforce. They also demonstrate why assessments of labour availability increasingly need to look beyond conventional employment relationships when considering the country’s workforce and the industries supporting its property and wider economy.

Source: Statistics Poland

front page info
LATEST NEWS