German Economy Returns to Growth in H1 2026 as Exports Strengthen

Germany’s economy showed clearer signs of improvement during the first half of 2026, expanding in both quarters as stronger exports helped lift overall activity. The recovery remained uneven, however, with industrial production showing limited progress, household spending barely increasing and construction continuing to face difficult conditions.

Real GDP increased by 0.4% during the first quarter compared with the final three months of 2025 and expanded by a further 0.3% in Q2. Compared with a year earlier, economic output was 0.8% higher during the first quarter and 1.0% higher in the second. The improvement follows several years of weak economic performance, with Germany contracting in 2023, recording little change in 2024 and achieving only modest growth during 2025.

International trade was an important contributor to the stronger first-half performance. Exports of goods and services increased by 3.7% year-on-year in real terms during Q2, while imports rose by 2.5%. Goods exports increased by 5.0%, supported by stronger activity across areas including chemicals, electronics, electrical equipment and other transport equipment.

Across the first six months of 2026, Germany exported goods worth approximately €816.6 billion, an increase of 3.7% compared with H1 2025. Imports grew by 4.4% to €711.6 billion, leaving a trade surplus of around €105 billion. June was particularly strong, with seasonally and calendar-adjusted goods exports reaching approximately €139.3 billion, 0.9% above May and 6.6% higher than a year earlier.

The improvement in international demand is particularly important for Germany because manufacturing remains a major component of the economy. German industry has spent several years adjusting to higher energy costs, changing global supply chains, weak demand in important markets and substantial restructuring within the automotive sector.

Industrial production nevertheless remained subdued at the end of H1. Output increased by only 0.2% between May and June and remained 0.1% below its level in June 2025. Across April to June, production was 0.7% higher than during the preceding three-month period, indicating some improvement without signalling a broad industrial rebound.

Manufacturing orders provided a somewhat stronger indication of potential future activity. New orders increased by 3.1% between May and June and were 6.5% higher than a year earlier. Large individual contracts contributed significantly to the headline result, however, and when these were excluded, orders declined by 0.5% from May.

The difference between stronger orders and relatively flat production highlights the incomplete nature of Germany’s manufacturing recovery. Demand has strengthened in parts of industry, but this has not yet translated into sustained growth across the wider manufacturing base.

Domestic consumption also remained restrained. Private household spending increased by just 0.1% during the second quarter compared with Q1 and was only 0.1% higher than a year earlier. Consumer demand therefore contributed relatively little to the improvement in the overall economy during the first half.

Construction continued to face difficult conditions. Investment in construction was lower than a year earlier during Q2, extending the challenging environment for residential and commercial development. Building costs, financing conditions and uncertainty surrounding project economics have continued to restrict new development activity.

Inflation increased during the spring before moderating towards the end of H1. Consumer prices were 2.9% higher year-on-year in April and 2.6% higher in May before annual inflation eased to 2.3% in June.

Energy prices increased by 3.4% year-on-year in June, considerably below the 10.1% rise recorded in April and the 6.6% increase in May. Motor fuels nevertheless remained 11.3% more expensive than in June 2025. Food prices increased by only 0.4%, while services were 3.1% more expensive. Inflation excluding food and energy stood at 2.5%.

German companies were also dealing with higher costs for imported products. Import prices increased by 6.1% year-on-year in June, while export prices rose by 3.5%. Higher energy and intermediate-product costs were important contributors to the increase in import prices, maintaining pressure on businesses dependent on international supply chains.

Germany’s public finances are simultaneously undergoing a significant shift as the government increases expenditure. The general government deficit reached approximately €71.3 billion during the first six months of 2026, around €36.6 billion more than during the corresponding period of 2025. The H1 deficit was equivalent to 3.1% of GDP.

Government revenue increased during the first half, but expenditure rose considerably faster. Higher public expenditure is expected to provide increasing support to the economy as Germany directs additional resources towards infrastructure, defence and other investment programmes.

This change in fiscal policy could become increasingly important for economic activity during the coming years. Greater spending on transport networks, energy infrastructure, defence capacity and modernisation has the potential to generate additional demand at a time when private-sector investment remains cautious.

The European Commission expects the German economy to expand by approximately 0.6% across 2026 following growth of only 0.2% during 2025. Growth is forecast to strengthen to around 0.9% in 2027 as higher public expenditure and gradually improving domestic conditions provide additional support.

Greater government spending will also affect Germany’s fiscal position. The Commission expects the budget deficit to reach approximately 3.7% of GDP during 2026, while public debt is projected to increase from around 63.5% of GDP in 2025 to approximately 65.8% this year.

For Germany’s commercial property sector, the economic environment has improved compared with the prolonged period of stagnation, although the first-half figures do not yet indicate a strong cyclical recovery. Higher exports and improving manufacturing orders provide a better backdrop for industrial and logistics property, while additional infrastructure and defence expenditure could support property demand in regions benefiting directly from new investment.

The weakness in construction is also becoming increasingly relevant to the property market. Reduced development activity could restrict future additions to modern building stock in some locations, particularly where financing costs and development economics have already resulted in projects being delayed or cancelled.

Germany entered the second half of 2026 with economic conditions stronger than a year earlier. GDP expanded during both quarters, exports increased and manufacturing orders improved. At the same time, industrial output remained broadly flat, household consumption barely grew and construction continued to struggle.

The next stage of the recovery will depend on whether the improvement spreads more widely through the domestic economy. Stronger consumer demand, private investment and industrial production would provide clearer evidence that Germany is moving beyond several years of weak performance. For now, H1 2026 represents progress, but the recovery remains uneven and increasingly dependent on the combination of international demand and higher public expenditure.

Source: CIJ.World Research & Analysis Team
Primark Moves Beyond Store-Only Model with Sheffield Fulfilment Deal

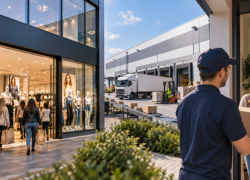
Primark is preparing to introduce home delivery across Great Britain, marking a significant shift for a retailer that has built its business around physical stores and for years resisted the economics of delivering low-priced fashion directly to customers.

The move is being supported by a £90 million transaction involving a highly automated distribution facility in Sheffield. Debenhams Group has agreed to transfer the site’s automation equipment and assign its lease to Primark Stores Limited. The consideration comprises £76.5 million payable on completion and a further £13.5 million when vacant possession is provided.

The Sheffield facility extends to approximately 615,000 sq ft and will provide Primark with substantial infrastructure for processing online orders. The investment represents an important change in the retailer’s property requirements, adding dedicated fulfilment capacity alongside its extensive network of high-street and shopping-centre stores.

Primark has been building its digital operations gradually, including the expansion of Click & Collect across Great Britain. The retailer now believes developments in its own digital capabilities and changes in the economics of online shopping provide an opportunity to generate additional profitable sales through delivery. A date for the introduction of the service has not yet been announced.

The company is not moving away from physical retail. Stores will remain at the centre of Primark’s strategy, with delivery providing customers with another way of accessing its products. The result will be a more integrated model in which shops and distribution infrastructure increasingly work together rather than operating as separate channels.

The strategic change comes during a softer trading period. Primark expects comparable sales to decline by around 3% in its fourth quarter. Performance differs considerably between markets, with the UK and Ireland expected to record a 0.4% increase while continental European comparable sales are forecast to fall by 4.3%. Total Primark sales are nevertheless expected to increase by approximately 2% for the full financial year, supported partly by expansion of the store network and franchise operations.

Online fashion businesses have also changed consumer expectations around convenience, delivery and returns. Primark’s decision indicates that maintaining very low product prices no longer necessarily requires remaining outside home delivery, particularly as fulfilment technology and customer charging structures evolve.

For the property sector, the Sheffield transaction illustrates the increasingly close relationship between retail and logistics real estate. Primark will continue investing in stores while simultaneously requiring sophisticated distribution infrastructure capable of serving customers directly.

The change is particularly notable because Primark was one of Europe’s largest retailers to remain committed to a predominantly store-based purchasing model. Its move into home delivery suggests that even value retailers with large physical estates are having to reconsider how stores, warehouses, automation and digital sales fit together as shopping behaviour continues to evolve.

Lisbon Office Demand Weakens as Prime Rents Hold Firm

Lisbon’s office market is becoming increasingly divided between buildings capable of meeting modern corporate requirements and older properties competing for a weaker pool of demand. Leasing slowed during the first half of 2026 while new supply increased, yet rents for the strongest locations remained firm. The combination suggests that the amount of vacant space across Lisbon is becoming less important than the quality and location of the offices actually available.

Companies leased approximately 38,050 sqm during the second quarter, taking first-half activity to around 66,900 sqm. Although Q2 improved by roughly one-third compared with the opening quarter, activity remained about 44% below the same period of 2025. Across the first six months, leasing was approximately 20% lower year-on-year, pointing to a more cautious occupier market despite the improvement between Q1 and Q2.

Measuring how much office space is actually vacant is less straightforward. CBRE calculated a vacancy rate of 8.39% at the end of Q2, while Cushman & Wakefield arrived at approximately 6.6%. The difference reflects variations in the geographical boundaries, building samples and methodologies used to monitor Lisbon. More important for the market is the type of accommodation sitting behind those figures. Companies seeking recently developed or comprehensively modernised offices have very different requirements from occupiers prepared to consider older space. Energy efficiency, technical standards, workplace amenities, transport connections and flexible floorplates are increasingly influencing relocation decisions alongside traditional considerations such as rent and location.

Rental evidence illustrates this divide. Prime CBD rents remained at approximately €32 per sqm per month during Q2, while CBRE recorded rents in Lisbon’s Expansion Area increasing to around €23 per sqm per month. Most other locations remained broadly stable. Over a longer period, Lisbon’s prime rents have also recorded substantial annual growth despite the decline in overall leasing during the first half, suggesting that weaker aggregate demand has not translated into widespread pressure on the best buildings.

The location and size of Q2 transactions provide further evidence that companies remain willing to make significant commitments when suitable offices become available. The CBD generated around 36% of quarterly take-up, while newer office districts also attracted a meaningful share of demand. Investment technology company iCapital committed to approximately 9,000 sqm at Fidelidade’s headquarters on Avenida Álvaro Pais, making it one of the largest transactions of the quarter. Other notable leases included approximately 3,470 sqm at República 24 and Boston Consulting Group taking around 3,230 sqm at Campo Novo.

The question facing Lisbon is therefore not simply whether the city has enough offices, but whether enough of its existing stock matches what major occupiers now require. An older vacant building with weaker environmental performance or outdated technical specifications does not necessarily compete directly with a newly constructed office, even when both properties appear within the same city-wide availability statistics.

That distinction will become more important as Lisbon’s development pipeline reaches the market. Approximately 47,900 sqm of new office accommodation was completed during Q2 alone, while around 204,000 sqm is already being built. Total expected deliveries over the next three years approach 273,000 sqm. Only around one-fifth of the space currently under construction has already been secured by occupiers, meaning developers will be delivering a substantial amount of new accommodation into a market where first-half leasing has declined.

This does not necessarily mean Lisbon is heading towards general oversupply. New buildings will compete most directly for companies seeking high-quality offices, while older properties could face a different challenge. As modern developments increase the choices available to occupiers, landlords of ageing buildings may come under greater pressure to refurbish and reposition their assets if they want to compete successfully for larger corporate tenants.

The result could be a widening performance gap within Lisbon’s office stock. Well-located, efficient buildings offering modern specifications may continue supporting stronger rents even if overall vacancy increases, while properties requiring substantial capital expenditure could find it progressively more difficult to attract occupiers without investment. For developers, this places greater importance on delivering the right specification rather than simply adding floor space. Investors must similarly distinguish between buildings where refurbishment can restore competitiveness and assets where the cost of modernisation may become difficult to justify.

Lisbon consequently presents an unusual office-market picture in 2026. Leasing volumes have declined, new construction is increasing and estimates show meaningful vacant space across the city, yet prime rents remain resilient and companies continue committing to substantial leases when appropriate buildings become available. As more projects are completed, the difference between desirable and secondary offices is likely to become increasingly visible. Lisbon’s next office challenge may therefore be less about how much vacant space the city has and more about how much of that space companies still consider worth occupying.

Source: CIJ.World Research & Analysis Team
ATAL Adds 72 Homes to Gdańsk Pipeline with Second Jasieny Phase

ATAL has launched sales of the second stage of its Jasieny residential development in Gdańsk, adding 72 homes to its pipeline in the city’s Jasień district. The new phase will be developed on Stężycka Street, with completion planned for mid-2028. The scheme will comprise 22 terraced and detached two-unit buildings, with homes ranging from approximately 26 sqm to 101 sqm.

The residential mix is focused primarily on three- and four-room properties, alongside two five-room homes and 14 studios. Some apartments will extend across two or three levels, providing layouts that allow living and private areas to be separated. Each property will have an individual entrance, while upper-floor homes will include balconies and ground-floor units will have gardens and terraces.

The development will provide 100 parking spaces together with landscaped areas, rain gardens, a children’s playground and a dedicated dog park. The arrangement of the buildings is intended to create a lower-density environment more closely associated with individual housing than a conventional apartment development.

ATAL Jasieny is located around eight kilometres from central Gdańsk and within a short drive of the Tricity ring road. Public transport is available immediately beside the development, while nearby amenities include grocery shopping, childcare facilities and Morski Park Handlowy. The location also provides access to green and recreational areas around Jasień and Otomin lakes.

Homes in the second phase are being offered at prices between PLN 10,500 and PLN 13,000 per sqm in developer standard. Buyers can also select from ATAL’s interior finishing packages. The first phase of the Jasieny development has already been completed and received its occupancy permit.

The project forms part of ATAL’s continuing expansion across the Tricity residential market, where the company is marking ten years of activity in 2026. During that period, ATAL says it has completed nine projects in the region, while another ten are underway, with more than 2,000 homes sold.

ATAL also strengthened its position in the Tricity market during summer 2026 through the acquisition of local developer Budner and its assets. Jasieny II further expands the company’s regional pipeline with a residential format combining proximity to Gdańsk with lower-density development and access to surrounding green areas.

Spanish Investors Move to the Front of a €12 Billion Property Market

Spain’s commercial property market entered 2026 with investment accelerating at a pace few European markets have matched. More than €12 billion changed hands during the first six months of the year, an increase of approximately 59% compared with the same period of 2025 and the strongest first-half performance recorded in the available market series. The scale of the increase is striking, but the composition of the capital behind it may prove more significant for the next stage of the cycle.

Spanish investors accounted for close to half of investment during the period, giving domestic capital a central role in a market that continues to attract substantial international interest. Investment was also distributed across several property sectors rather than depending on a single category. Residential and other living assets attracted more than €4.5 billion during the first half, making them the largest destination for capital. Hotels exceeded €2 billion, while offices and retail each attracted approximately €1.6 billion.

The figures indicate a market in which investors are prepared to consider a much broader range of property than during the most defensive stages of the recent cycle. Housing, hospitality, offices and retail are all attracting significant capital, although the buyers pursuing them can have very different objectives.

The growing presence of Spanish money is particularly interesting because domestic investors operate across several distinct categories. Institutions, listed property companies, private investors, family offices and locally managed investment vehicles do not necessarily pursue the same assets or accept the same levels of risk. Large domestic institutions can favour investments capable of producing predictable income over extended periods, while private investors and family offices may have greater flexibility over transaction size and holding periods. Listed property vehicles and specialist asset managers can pursue sector-specific strategies or buildings requiring more active management.

This diversity makes the simple distinction between Spanish and foreign capital increasingly inadequate. Some investment structures managed in Spain include money originating internationally, while internationally backed platforms may employ Spanish management teams and pursue highly local strategies. Understanding who is buying therefore requires looking beyond the registered nationality of the purchaser to the source of capital, investment horizon and intended business plan.

Nevertheless, the scale of domestic participation during the first half of 2026 demonstrates that Spanish capital has become an important source of market liquidity. That matters particularly when transaction markets are recovering from a period of higher financing costs and uncertainty over property values.

International institutions typically compare opportunities in Spain with assets available across multiple countries. An office building in Madrid may be assessed against investments in Milan, Paris, Frankfurt, Amsterdam or London. Changes in yields, borrowing costs and investment conditions elsewhere can therefore influence whether global capital decides to invest in Spain.

Domestic investors can approach the same opportunity from a different perspective. Their existing relationships, familiarity with local occupiers and knowledge of individual cities may allow them to evaluate risks differently. This does not necessarily mean Spanish buyers will pay more, but it does mean they can remain active for reasons that are not entirely dependent on Spain’s relative position within a global property allocation.

The development of a deeper domestic buyer pool could be particularly important for assets outside the largest institutional transactions. Spain contains substantial quantities of property requiring refurbishment, repositioning or changes in management strategy. Older offices need investment to meet modern occupier expectations and environmental requirements. Retail properties may require changes to tenant mix or format. Hotels can depend heavily on operational improvements, while residential buildings may offer redevelopment or conversion opportunities.

These projects require capital prepared to accept execution risk rather than simply collect income from completed prime assets. Local knowledge can be valuable in such circumstances. Understanding municipal planning, leasing conditions, construction costs and potential occupiers becomes more important when the investment case depends on changing the property rather than maintaining it in its existing condition.

The office sector provides a useful example of the changing market. Investment has recovered significantly, but investors remain highly selective about building quality, location and future capital expenditure. Prime offices capable of meeting modern environmental and workplace standards can attract a different buyer group from older buildings requiring extensive refurbishment. This creates opportunities for investors willing to take redevelopment risk while also widening the gap between the strongest buildings and properties that require substantial additional capital.

Living assets present another dynamic. More than €4.5 billion invested during the first half demonstrates the scale of interest in housing-related property. Population growth, household formation and shortages of accommodation in several major Spanish markets continue to support investment across rental housing, student accommodation and other residential formats.

Hotels have also remained a major destination for capital. Spain’s position as one of the world’s largest tourism markets gives hospitality property a diverse buyer base, ranging from hotel operators and domestic investors to international funds. Retail’s approximately €1.6 billion of investment provides further evidence that investors are reconsidering sectors that were treated cautiously during earlier phases of the market. Properties with strong trading locations, resilient tenants and opportunities for active management can once again compete for capital.

International investors remain fundamental to all of these markets. Spain continues to attract global institutions, private equity and other international buyers, particularly for transactions requiring substantial amounts of capital. Foreign investment also remains important for price discovery, portfolio transactions and the development of new property sectors. The difference in 2026 is that international capital is operating alongside a substantial domestic buyer base.

This distinguishes the current environment from parts of the recovery following Spain’s previous property downturn, when international opportunity funds and private equity played a particularly visible role in acquiring distressed property, loan portfolios and development platforms. Today’s market is operating under very different circumstances. Spanish banks, developers, investors and property companies have had more than a decade to restructure, accumulate experience and develop new investment platforms. Domestic capital is therefore entering the current cycle from a different position.

For property owners considering disposals, that potentially increases the number and variety of credible buyers. A transaction does not necessarily need to depend on a large international institution. Spanish investment companies, institutions, private investors and family offices can compete for assets depending on their size, sector and risk profile.

For foreign investors, a stronger domestic market can also increase competition. Waiting for substantially better pricing may become more difficult if local buyers are prepared to transact at current levels.

The first six months of 2026 therefore tell a broader story than Spain simply experiencing another property investment rebound. More than €12 billion of transactions demonstrates the scale of activity, while the close-to-half share attributed to domestic buyers reveals something potentially more structural: Spain now has a sizeable local investment base participating across several sectors at the same time.

Whether that balance continues through the remainder of the year will be important to watch. If domestic capital maintains a substantial share while international investment also increases, Spain could enter the next stage of its property cycle with a considerably broader buyer base than during previous recoveries.

For investors, developers and owners, the defining feature of Spain’s 2026 property market may therefore be not simply how much money is being invested, but how much more diverse the competition for assets has become.

Source: CIJ.World Research & Analysis Team
Local Buyers Gain Ground as Estonia’s Property Market Waits for Foreign Capital

Estonia’s commercial property market remained relatively quiet during the first half of 2026, but the limited number of transactions disguises an important change in the investment landscape. While many large international investors continue to approach smaller European markets cautiously, Estonian capital is playing an important role in keeping transactions moving. Around €120 million of commercial property changed hands in Estonia during the first six months of the year. Industrial assets accounted for approximately 60% of the total, while retail represented about 30%. The figures leave offices and other property sectors with only a relatively small share of overall investment activity.

The size of the market becomes particularly apparent when Estonia is compared with larger Central and Eastern European countries. Investment across the six principal CEE markets reached approximately €5.8 billion during the first half of 2026. Poland accounted for more than €3 billion, while Czechia attracted more than €1.4 billion. For international institutions allocating hundreds of millions of euros across Europe, this difference in scale matters. Estonia can offer attractive individual properties, but it cannot regularly provide the volume of large transactions available in Warsaw, Prague or other major regional markets. A transaction capable of making a meaningful contribution to a local or Baltic portfolio may simply be too small for a large international fund.

This creates an opportunity for investors operating closer to the market. Estonian buyers have remained an important source of capital during the current period of subdued investment activity. Local property funds, private investors, developers and other domestic buyers can consider transactions that may fall below the size requirements of larger international institutions. Baltic investment managers occupy another important position. They can combine knowledge of Estonia with the ability to allocate capital across Latvia and Lithuania, potentially giving them greater flexibility than investors assessing Tallinn as an isolated market.

Pricing is also beginning to change the investment calculation. At the end of the second quarter, yields for Tallinn’s leading office properties were around 7%. The equivalent level for prime industrial assets was approximately 7.5%, while shopping centres stood at around 8%. Office and industrial yields moved further outward during the quarter, indicating that buyers were demanding greater returns before committing capital. These levels represent very different pricing conditions from the exceptionally low-yield environment experienced during the previous property cycle. Whether they are attractive enough to bring international institutional investors back to Estonia in greater numbers remains uncertain.

Headline yield alone will not determine that decision. International investors must consider the depth of the buyer market when they eventually want to sell, financing conditions, Estonia’s economic outlook, the availability of suitable investment-grade properties and the size of individual transactions. Broader geopolitical considerations surrounding the Baltic region can also influence investment committees assessing allocations to Estonia. Domestic investors face many of the same risks, but their investment decisions can operate differently. Familiarity with local tenants, municipalities, development conditions and financing relationships can potentially make smaller or more complicated transactions easier to assess. Local investors may also be able to hold properties that would not meet the scale requirements of international funds.

That difference could become particularly important during the current stage of the market cycle. When international competition is limited, domestic and Baltic investors potentially have more time to negotiate acquisitions. If foreign capital eventually returns as financing conditions and economic confidence improve, assets acquired during the quieter period could become more strongly contested.

Industrial property is currently providing the clearest evidence of where capital is comfortable investing. Its approximately 60% share of H1 transaction volume puts warehouses, production facilities and other industrial properties firmly at the centre of Estonia’s investment market. There are practical reasons why the sector can appeal to regional investors. Industrial properties can often be traded individually rather than as enormous portfolios, creating transaction sizes accessible to a wider range of buyers. Demand is also spread across logistics, manufacturing, distribution and smaller businesses rather than depending upon a single occupier category.

Retail’s approximately 30% share of investment provides another indication that investors have not abandoned established commercial property. Shopping centres and other retail assets offering sustainable income can still attract capital when pricing adequately reflects perceived risk. Offices present a more complicated investment proposition. Tallinn is simultaneously experiencing substantial new development and relatively cautious occupier demand. Investors therefore have to distinguish carefully between modern buildings capable of attracting tenants and older properties that could require additional investment to remain competitive.

The broader question is whether today’s buyer composition represents a temporary phase or the beginning of a longer change in Estonia’s commercial property ownership. If international institutions return strongly, domestic investors will once again face greater competition for the best assets. Increased competition could support transaction volumes and eventually place upward pressure on property values. If international capital remains selective, however, Estonian and Baltic investors could continue accumulating assets while the market operates at relatively modest transaction volumes.

Neither outcome can yet be assumed. What can already be seen is that Estonia does not need a large investment market for ownership patterns to begin changing. In a country where approximately €120 million of transactions constituted the entire first-half market, a relatively small number of acquisitions can materially alter who owns significant commercial properties. That makes the identity of today’s buyers more important than the headline transaction figure might suggest.

Estonia’s property market may still be waiting for a broad return of international capital, but local investors are not necessarily waiting with it. They are already participating in the market, and the assets acquired during this quieter period could determine their position when the next investment cycle gathers momentum.

Source: CIJ.World Research & Analysis Team
Brazil’s Logistics Growth Is Moving Inland From Its Ports

Brazil’s expanding ports are beginning to influence a much larger property market than the terminals located along the country’s coastline. As investment increases capacity at major gateways and cargo volumes place greater demands on transport networks, the effects are spreading into warehouses, container facilities, industrial sites and logistics parks positioned along the routes connecting ports with Brazil’s production and consumer centres. For property investors, this creates a different logistics proposition from the distribution centres surrounding São Paulo and other large metropolitan areas. Conventional urban logistics is primarily driven by access to consumers and the need to deliver goods quickly, while port-related logistics depends more heavily on international trade, industrial production, agricultural exports and the infrastructure required to move cargo efficiently between ships and inland markets.

The distinction matters because Brazil’s institutional warehouse market remains heavily concentrated around São Paulo. The country’s largest metropolitan economy combines an enormous consumer population with manufacturing and transport infrastructure, producing the deepest and most liquid logistics property market in Brazil. Yet the expansion of ports and their inland connections could gradually create additional investment locations where demand is supported by trade rather than population alone.

Santos provides the clearest example. Brazil’s largest port handles enormous volumes of containers, agricultural products and industrial cargo while serving São Paulo state and much of the country’s wider economy. Its importance extends far beyond the waterfront because every additional shipment moving through the port eventually requires road, rail, storage or distribution infrastructure somewhere within the wider logistics system. Land close to the port is constrained, and congestion can make immediate proximity less attractive than it initially appears. This encourages some logistics activities to move inland towards locations where larger sites can be developed while maintaining efficient connections to Santos.

Warehouses, container yards, distribution centres and industrial facilities positioned along the routes between the port and Greater São Paulo can therefore benefit from both international trade and domestic distribution. That combination gives the Santos corridor an important advantage. A warehouse does not necessarily have to depend entirely on port-related demand. The same property may serve importers, manufacturers, retailers and consumer distribution networks, creating a broader potential tenant base than facilities built around more specialised gateways.

Paranaguá presents a different but increasingly significant opportunity. The port is central to the movement of agricultural commodities and other cargo from southern and central Brazil, and substantial investment is being directed towards improving maritime and rail access. Deeper navigation capacity can accommodate larger vessels, while improvements to railway infrastructure can increase the amount of cargo arriving from inland production regions. The property implications extend beyond greater throughput at the port itself. Increasing maritime capacity without expanding storage, transport and distribution infrastructure simply transfers congestion from the waterfront to surrounding areas.

As cargo volumes grow, businesses need locations where containers can be stored and serviced, agricultural products consolidated, imported goods distributed and trucks managed before entering congested port areas. The emergence of new container facilities around Paranaguá illustrates how port investment can generate secondary property demand. These facilities may not resemble conventional institutional warehouses, but they form part of a larger logistics ecosystem that can eventually support distribution parks and industrial development farther inland.

The Curitiba-Paranaguá relationship is particularly interesting from an investment perspective. Curitiba and its surrounding industrial economy provide manufacturing and consumption demand, while Paranaguá supplies access to international markets. Locations capable of connecting the two can potentially serve both industrial occupiers and trade-related logistics companies, giving properties along the corridor a broader demand base than facilities dependent solely on port activity.

Santa Catarina offers another variation on this model. The Itajaí and Navegantes area combines important container gateways with one of southern Brazil’s strongest manufacturing and distribution economies. Industrial production across the state creates substantial import and export demand, while growing urban markets generate domestic distribution requirements. This makes the surrounding logistics market potentially attractive because its demand is diversified. Warehouses can serve port users while also supporting manufacturers, retailers and distributors operating within Santa Catarina and neighbouring states.

Improving port infrastructure could reinforce that advantage. As maritime access, terminal capacity and transport connections expand, more cargo can move through the region. But the property opportunity will depend on whether roads and inland logistics infrastructure develop quickly enough to accommodate that growth. The same pattern can be found elsewhere in Brazil. Rio Grande serves agricultural and industrial activity across the country’s south, while ports in the Northeast are becoming increasingly important to energy, industrial and agricultural supply chains. Ceará’s Pecém complex, for example, combines port infrastructure with industrial development and major energy projects, creating a property proposition that is very different from a conventional consumer warehouse market.

These locations demonstrate why the most interesting port-related property opportunities may not sit directly beside the sea. In many cases, the real investment potential lies farther inland, where land is more readily available and cargo can be consolidated before entering the port or distributed after arrival. An inland logistics park connected effectively to a major port can perform several functions. Importers can use it as a distribution base, exporters can consolidate products before shipment, logistics operators can transfer cargo between transport modes and manufacturers can store components arriving from overseas. Cold-storage facilities can serve agricultural and food exports, while container depots can reduce pressure on terminal areas.

Rail infrastructure could expand this geography significantly. Brazil’s ports handle exports originating hundreds or even thousands of kilometres inland. As rail connections improve, logistics locations positioned at intersections between railway lines, highways and port corridors can become increasingly strategic. The port effectively begins to extend inland through a network of logistics nodes. This creates an important property investment question: should a warehouse located along a major port corridor be valued in the same way as a conventional metropolitan distribution centre, or does its connection to trade infrastructure create a different risk and return profile?

The answer will depend heavily on the individual location. Simply being close to a port does not guarantee strong property performance. Some facilities depend on a narrow group of customers or particular cargo flows, creating greater exposure to changes in trade patterns. Others can serve several industries and combine port-related activity with regional distribution, providing a more resilient demand base. Infrastructure is particularly important. A modern warehouse can still perform poorly if trucks spend hours navigating congested roads or if rail connections are unreliable. Investors therefore need to assess the entire transport system rather than the property in isolation. Port capacity, highway access, railway connections and customs infrastructure can all influence the competitiveness of an industrial site.

Environmental and planning considerations add another layer. Coastal and river locations can face flooding and other climate-related risks, while land around ports may have complicated environmental restrictions. Suitable industrial sites with appropriate licences, resilient infrastructure and good transport access can consequently become difficult to reproduce. That scarcity can create value. If cargo volumes continue growing while the supply of well-connected development land remains constrained, established logistics locations could gain pricing power. Developers able to secure land before infrastructure improvements are completed may also benefit as transport corridors become more important.

However, Brazil’s port-related logistics market should not yet be treated as equivalent to its established metropolitan warehouse sector. Institutional investment remains considerably deeper around São Paulo, where investors can analyse extensive leasing evidence, rents, vacancy and transactions. Many port markets remain smaller, more specialised and less liquid. This makes them more appropriate for investors prepared to understand infrastructure and trade flows in addition to conventional property fundamentals. The opportunity may initially appeal to developers and specialist logistics investors capable of identifying locations before they become mainstream institutional markets.

The strongest opportunities are likely to emerge where several forms of demand overlap. A logistics park serving only one export commodity may carry substantial concentration risk. A location connected to a port, industrial cluster, major highway and large consumer market has a much broader economic foundation. Santos already demonstrates many of these characteristics because of its relationship with São Paulo. The Curitiba-Paranaguá corridor offers another combination of port access and industrial demand, while Itajaí and Navegantes benefit from Santa Catarina’s manufacturing and distribution economy. Other gateways could follow as infrastructure investment improves their connections with inland production centres.

The long-term property story is therefore not simply about expanding Brazilian ports. It is about what must be built behind them. Larger terminals and deeper channels can increase the amount of cargo entering and leaving the country, but that cargo still requires land, buildings and transport infrastructure before reaching its final destination. Warehouses, industrial parks, cold-storage facilities, container depots and inland logistics hubs could become increasingly valuable parts of that system.

As these networks develop, institutional investors may begin viewing port-connected property as a more distinct investment strategy rather than simply another part of the warehouse market. Brazil’s next generation of logistics locations may consequently emerge along corridors that connect maritime gateways with factories, farms and cities. The ports will remain the entry and exit points, but much of the investible real estate could be created kilometres inland. For investors looking beyond Brazil’s established metropolitan warehouse markets, that shift could provide the next stage of logistics expansion. The most valuable sites may ultimately be those that turn growing ports into efficient inland supply chains.

Source: CIJ.World Research & Analysis Team
AI Is Turning Garbage Trucks Into Mobile Urban Infrastructure Platforms

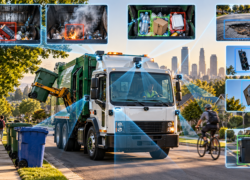
Garbage trucks may appear an unlikely testing ground for artificial intelligence, but their combination of heavy vehicles, repetitive routes, complex urban environments and almost daily contact with city streets is creating an increasingly valuable platform for AI-powered safety and municipal data. At AI4 2026 in Las Vegas, Paul Marsolan, Chief Software Officer at Battle Motors, outlined how the US vocational truck manufacturer is integrating computer vision, onboard computing, fleet software and advanced driver-assistance technology directly into refuse vehicles. The objective extends well beyond making collection routes more efficient. Battle Motors is using the technology to identify fires, dangerous materials, pedestrians, recycling contamination and service problems, while exploring how the same vehicles could eventually gather information about wider urban infrastructure.

The approach illustrates an important development in industrial AI. Rather than relying entirely on large cloud-based models, Battle Motors is placing computing power directly inside the vehicle. Cameras surrounding the truck feed images into onboard processors capable of analysing the environment without waiting for a cellular connection. That is particularly important for refuse fleets because vehicles frequently operate in rural locations or other areas where network coverage cannot be guaranteed. Marsolan said the company’s models can respond locally in less than 200 milliseconds. For safety-critical applications, that difference matters. A system intended to identify smoke developing inside a refuse body cannot depend on the truck remaining connected to a mobile network before warning the driver.

Battle Motors is a US vocational truck manufacturer producing vehicles for heavy-duty and severe-service applications, including refuse. The company operates from New Philadelphia, Ohio, and its product strategy combines commercial vehicles with connected fleet-management technology. Its Fortris platform is designed to integrate safety, vehicle information and fleet operations rather than leaving operators to work across multiple aftermarket systems. That integration addresses a longstanding characteristic of the refuse industry. A commercial chassis may leave one manufacturer before being fitted with a specialised refuse body and subsequently receiving cameras, routing software, telematics and other equipment from several additional suppliers. The result can leave drivers surrounded by separate screens and systems that were never designed to operate together.

Battle Motors is attempting to bring more of that technology into the vehicle before it leaves the factory. Marsolan described an architecture incorporating multiple cameras, centralised driver displays and onboard AI. The company says its Fortris platform can also be fitted to existing fleets, creating a subscription-based software and hardware business alongside vehicle manufacturing. The most immediate use cases involve safety. Refuse trucks operate in unusually complicated environments. They move repeatedly between traffic lanes and kerbs, reverse frequently, interact with pedestrians and cyclists and operate large mechanical collection systems in residential neighbourhoods. Their blind spots and vehicle mass make even relatively low-speed accidents potentially serious.

Vision systems can provide the driver with a wider view around the truck while AI models identify objects that may require immediate attention. Marsolan described systems designed to recognise people and other hazards around the vehicle and combine that information with advanced driver-assistance capabilities. The technology is also being used inside the refuse collection process itself. Cameras can analyse what enters the hopper when a bin is lifted, allowing the system to identify objects such as batteries, propane cylinders, electronic devices and other potentially hazardous materials.

Lithium-ion batteries and pressurised containers represent a particular problem for waste operators because they can ignite or explode after entering compaction equipment. A fire inside a refuse truck can escalate rapidly from a manageable incident into the loss of the entire vehicle and potentially create danger for surrounding properties. Battle Motors is therefore developing computer-vision models capable of identifying smoke and fire inside the collection body. The system is designed to alert the operator early enough to take action according to the fleet’s own emergency procedure.

Marsolan explained that Battle Motors deliberately accepts a greater risk of false alarms for fire detection because the consequence of missing a genuine fire is considerably more serious. However, the system also uses repeated image frames to distinguish sustained smoke or flame from temporary visual conditions such as dust or brightly coloured waste. Drivers remain part of the feedback loop. When the software identifies a potential fire, the operator can confirm whether the warning was correct. That information can subsequently become training data for improving the model. This human feedback is particularly important because refuse environments are visually difficult. Dust, steam, unusual lighting, plastic bags and hundreds of different waste materials can resemble hazards under particular conditions. An AI system that repeatedly generates unnecessary alarms could rapidly lose the confidence of drivers.

The same cameras can be used for another growing challenge in municipal waste management: contamination of recycling and organic waste streams. When inappropriate materials are placed in recycling or compost containers, the cost of processing increases and the value of the recovered material can fall. California provides one example of how regulation is increasing attention on contamination. Under the state’s organic-waste regime, local jurisdictions must conduct monitoring and provide education when contamination is detected. Jurisdictions can also introduce stricter local enforcement measures, including penalties in certain circumstances.

Computer vision potentially gives waste operators a much more detailed picture of where contamination originates. Rather than discovering problems only after an entire load reaches a processing facility, cameras on the collection vehicle can associate inappropriate material with individual stops. That creates opportunities for targeted education. A municipality or private operator could notify customers that a particular recycling container repeatedly contains unsuitable material rather than sending general information to an entire neighbourhood. However, this is also where the technology begins to intersect with public policy and privacy. Marsolan acknowledged that some municipalities are still considering whether and how information gathered by truck-mounted cameras should be used to contact residents or impose local charges.

Battle Motors says its system applies privacy measures such as obscuring identifiable information in captured images and retaining certain imagery for limited periods. The larger issue nevertheless extends beyond the technical platform. Municipalities need to determine what constitutes legitimate operational evidence, how residents should be informed and how automated observations can be challenged. Another application is proof of service. Disputes regularly arise when a resident reports that waste was not collected while the driver maintains that no container was placed outside.

A camera-equipped truck can potentially provide evidence showing whether the vehicle passed the address, whether a container was present and whether it was lifted. That could reduce customer-service disputes and allow operators to communicate proactively with customers rather than investigating complaints after they occur. Similar technology could identify overfilled containers, particularly in commercial waste collection where customers may be charged according to volume or service conditions. Instead of relying entirely on driver observations, vision models can gradually create a photographic and operational record associated with each collection point.

The resulting dataset becomes considerably more interesting when combined with routing information. A refuse truck already knows where it is, which address it is servicing and where it is travelling next. Adding computer vision means the vehicle can also begin to understand what it is seeing at each location. That creates a potential second role for the fleet beyond waste collection.

Garbage trucks travel through residential streets with a frequency few other municipal vehicles can match. Most neighbourhoods are visited at least weekly, while multiple waste streams can increase that frequency further. The vehicles therefore represent a recurring mobile observation network covering large parts of a city. Marsolan said Battle Motors has been discussing whether cameras already fitted to refuse trucks could identify problems including potholes, damaged traffic signals and missing road signs. Instead of sending a dedicated inspection vehicle around a municipality, information could be gathered passively during routes the city is already paying to operate.

The concept has significant implications for smart-city infrastructure. Municipal governments have invested for years in fixed sensors, connected street furniture and specialised inspection systems. A fleet of vehicles already travelling throughout the city could provide another source of continuously refreshed infrastructure information without requiring an entirely separate physical network. Pothole detection is an obvious example. Computer vision could identify deteriorating road surfaces and associate the observation with location data. Repeated observations from multiple vehicles could potentially help authorities distinguish isolated defects from rapidly worsening sections of road.

Traffic infrastructure could be monitored in a similar manner. Cameras could flag a damaged stop sign, malfunctioning light or obstructed road marking. Changes could then be sent to the relevant municipal department for inspection. The difficult part is no longer necessarily identifying the problem. As Marsolan observed, the harder question becomes what happens once the truck has found it. Municipal departments need workflows capable of receiving, verifying, prioritising and acting on the information.

That distinction is important for the wider smart-city market. AI can dramatically increase the volume of defects and anomalies a city can detect, but the economic value depends on whether municipal organisations can convert those observations into maintenance decisions. The Battle Motors architecture also demonstrates why edge computing is gaining importance in connected infrastructure. Sending continuous video from multiple cameras on thousands of vehicles to the cloud would create substantial bandwidth and computing costs. Much of the footage is also irrelevant.

Instead, the onboard system can determine when something significant is happening. During refuse collection, for example, the model can concentrate on the period when the mechanical arm is lifting and emptying a container rather than analysing every second of an entire route with the same intensity. Relevant events can then be transmitted to central systems for fleet analysis, model training and management reporting. The architecture distributes computing between the vehicle and the cloud rather than attempting to perform everything remotely.

Cost was one reason Battle Motors rejected a cloud-only approach. Connectivity was another. If an application is intended to protect a vehicle from fire or alert a driver to an immediate hazard, local processing offers a degree of resilience that a remote model cannot guarantee. The company is also creating a feedback loop between vehicles operating in the field and future versions of its models. Images collected during real-world operations can be processed centrally, labelled and used to improve object-recognition models before updated versions are validated and returned to vehicles.

A refuse truck can make hundreds of stops during a working day, potentially generating a substantial amount of relevant training material. Across a large fleet, that creates a continually expanding dataset of waste types, road environments, containers and operating conditions. The advantage for an original equipment manufacturer is that the digital system can be designed alongside the vehicle rather than added afterwards. Marsolan contrasted the traditional refuse cab, where separate displays may handle routing, cameras and operational instructions, with Battle Motors’ attempt to consolidate information onto two central screens.

Reducing the number of interfaces matters because drivers already perform a demanding job. Additional safety technology becomes counterproductive if it creates more distraction. The objective is therefore to provide contextual information only when it is relevant rather than forcing the driver to continuously monitor multiple systems. Battle Motors’ approach also points towards the changing economics of commercial vehicle manufacturing. Revenue historically centred overwhelmingly on selling the physical truck and aftermarket parts. Connected fleets create the possibility of recurring software revenue throughout the operating life of the vehicle.

Marsolan said Fortris is offered through a subscription model, with customers able to purchase the hardware or incorporate it into a recurring service arrangement. Battle Motors has separately promoted Fortris as a fleet-management platform with functions including route management, vehicle health, safety integration and fire detection. This turns the vehicle into an ongoing software platform rather than a product whose commercial relationship with the manufacturer largely ends after delivery.

For municipalities and private haulers, that creates both opportunities and new procurement questions. Connected trucks can provide operational intelligence that previously required several independent systems, but fleets must evaluate long-term software costs, data ownership, cybersecurity and whether information can be moved between platforms. Privacy will become particularly important as vehicles gather increasing amounts of street-level imagery. Refuse trucks operate directly outside homes and businesses, meaning cameras may encounter people, vehicles, licence plates and private property almost continuously.

Any attempt to extend the data beyond immediate fleet operations into municipal monitoring will therefore require clear rules around retention, access and permissible use. The technical ability to collect information does not automatically establish the public authority to use it for every possible purpose. The broader significance of Battle Motors’ strategy lies in how ordinary municipal equipment is becoming part of the digital infrastructure of cities.

A garbage truck was historically a specialised machine performing one physical task. Once cameras, connectivity, edge computing and AI are integrated into the vehicle, it can simultaneously become a safety system, waste-monitoring tool, customer-service record, fleet-management platform and potentially an infrastructure inspection vehicle. The same principle could eventually extend to buses, delivery vehicles, street sweepers, maintenance vans and other fleets that continuously travel through cities.

That may create a different model for smart-city investment. Instead of installing dedicated infrastructure for every new source of urban information, cities could increasingly extract intelligence from assets already circulating through the built environment. For Battle Motors, refuse trucks provide an unusually practical starting point because their routes are repetitive, geographically comprehensive and operationally predictable. For municipalities, the appeal is equally straightforward: an asset that already has to travel down almost every street could potentially perform additional digital work while it is there.

AI may therefore make the garbage truck considerably more important to the future of urban infrastructure than its traditional role suggests. The vehicle will still collect waste, but increasingly it may also help cities understand what is happening around it.

Source: CIJ.World Research & Analysis Team
Moldova Wants More European Factories, But Its Property Market Is Not Ready Yet

Moldova is moving steadily closer to the European economy, creating an opportunity to attract manufacturers and logistics companies looking for locations close to the EU without paying the operating costs associated with more established Central and Eastern European markets. But there is a problem that could become increasingly important as investment interest grows: Moldova still has a relatively shallow supply of modern factories, warehouses and development-ready industrial property.

The country’s economic relationship with the European Union is already substantial. The EU accounted for more than half of Moldova’s goods trade in 2025, generating turnover exceeding €7 billion. European capital has also become increasingly important to the country’s investment base, with accumulated EU investment reaching approximately €3.14 billion by the end of 2025.

Political integration is progressing alongside trade. Moldova formally opened negotiations on the first cluster of its EU accession process on 15 June 2026. A second cluster, covering external relations, followed in July. Membership remains a longer-term process, but regulatory alignment, investment programmes and closer economic integration are progressively reducing some of the barriers separating Moldova from the European single market.

For commercial real estate, this creates an important question. If more European companies decide to manufacture, assemble, process or distribute products from Moldova, where will they operate?

The answer is currently dominated by Chișinău. Moldova had approximately 1.09 million sqm of commercial logistics warehouse space at the end of 2025, with around 70% concentrated in the capital and its immediate surroundings. Demand for warehouse space has been stronger than for conventional production property, while companies unable to find suitable facilities have increasingly looked for land on which to develop their own buildings.

This reveals one of the structural weaknesses of the market. Moldova has industrial property, but relatively little of it resembles the large institutional logistics parks that have become common across Poland, the Czech Republic, Hungary and Romania.

The country’s largest recent warehouse and logistics development cited in Invest Moldova’s market research was a 21,000 sqm project developed near Chișinău by Moldretail Group. Estimated warehouse rental activity across Moldova during 2025 was approximately 65,000 sqm, while another roughly 60,000 sqm of activity involved newly constructed or purchased facilities, much of it associated with companies developing buildings for their own occupation.

That is a very different market from neighbouring Romania, where international developers can offer occupiers extensive portfolios of immediately available or build-to-suit industrial space. The difference matters when companies choose manufacturing locations.

A manufacturer considering Iași, for example, is not comparing labour costs alone with those in Moldova. It is comparing the entire operating environment: building availability, motorway access, electricity capacity, customs procedures, workforce, construction times, financing and the ability to expand. Moldova can be cheaper and still lose the investment if the required factory cannot be delivered quickly enough.

This is why Ungheni could become one of the country’s most important industrial property locations. The city sits directly beside Romania and is increasingly positioned along an improving cross-border transport corridor. New road and bridge infrastructure will connect the area more closely with Romania’s developing A8 motorway, improving access towards Iași and the wider European road network.

Nearby Berești could strengthen that position further. Plans for a multimodal logistics complex envisage an approximately 18-hectare site combining road and railway freight infrastructure with warehousing and container handling. Ungheni also already possesses an industrial base through its free economic zone.

Taken together, those ingredients create the possibility of something Moldova has not previously had at scale: an industrial location capable of functioning increasingly as part of a Romanian-Moldovan manufacturing corridor.

For some occupiers, the geography could become compelling. Production could take place in Moldova while suppliers, customers and logistics networks remain closely connected with Romania. Components could cross the border during different stages of manufacturing, while finished goods could move west towards EU markets.

But infrastructure alone will not create that market. International occupiers need serviced development sites. Electricity connections must provide sufficient capacity. Roads need to accommodate freight vehicles. Planning and construction procedures need to be predictable, and suitable buildings must either exist or be capable of rapid delivery.

Bălți starts from a different position. The northern city already has an established manufacturing economy, including automotive-component and industrial production supported by the Bălți Free Economic Zone. Manufacturing accounted for almost 18% of Moldova’s accumulated foreign direct investment at the end of 2025, demonstrating that the country already has a meaningful industrial investment base.

The opportunity in Bălți is therefore not to invent a manufacturing market but to deepen one. Existing producers can attract suppliers. Suppliers create demand for warehouses, packaging operations, component storage and specialist services. As the cluster grows, additional manufacturers gain another reason to locate nearby.

That process could eventually create a more investible industrial property market. For the moment, however, Moldova’s regional warehouse markets remain thin. Transactions outside Chișinău are irregular enough that consistent rental benchmarks can be difficult to establish. Some older regional warehouse properties can be rented extremely cheaply, but low rents frequently reflect building quality rather than an exceptional investment opportunity.

This distinction will matter increasingly as Moldova attempts to attract international occupiers. A manufacturer does not necessarily want the cheapest building. It wants a facility capable of supporting its production process reliably.

Giurgiulești represents another type of opportunity altogether. Moldova’s principal international port has become more closely connected with Romania following the acquisition of Danube Logistics, operator of Giurgiulești International Free Port, by Romania’s state-owned Port of Constanța.

The transaction gives Moldova’s main maritime gateway a strategic owner with direct interests in Black Sea trade. Giurgiulești already handles more than 70% of Moldova’s waterborne imports and exports, and the new owner’s plans include further infrastructure development, additional capacity, new berths and development of available land.

The property implications could be significant. Rather than competing with Chișinău for conventional distribution warehouses, Giurgiulești could develop a specialised cluster involving agricultural storage, food processing, bulk commodities, manufacturing, freight handling and industrial operations requiring access to port infrastructure.

Its Romanian comparison is therefore not Bucharest or Iași but the wider Galați-Constanța logistics system.

Cahul remains a more speculative proposition. Its southern location and proximity to Romania give it potential, particularly for food processing, agricultural industries and smaller manufacturing operations. But the modern industrial property market remains considerably less developed than in Chișinău, and the case for large-scale speculative logistics development has yet to be demonstrated.

That illustrates a wider challenge for Moldova. Industrial land can be inexpensive because there is little demand. Warehouses can offer very low rents because they are obsolete. Neither necessarily makes a location competitive for international investment.

The real comparison with Romania therefore needs to go beyond headline costs. Romanian industrial rents are higher, but occupiers gain access to an established development industry, institutional landlords, larger labour markets, EU infrastructure and a mature logistics ecosystem. Moldova must compensate for those disadvantages with some combination of lower operating costs, investment incentives, improving infrastructure and access to suitable property.

Government policy is increasingly designed to encourage that investment. Moldova introduced a regional state-aid programme for industrial projects in 2025, offering substantial support for qualifying investments. The programme forms part of the country’s wider industrialisation strategy and is intended to encourage manufacturing investment outside the traditional economic centres.

Property availability could determine how effective those incentives become. There is little benefit in attracting a manufacturer with financial support if the company then spends years securing land, obtaining infrastructure connections and constructing a factory.

That creates an opportunity for industrial developers. Instead of waiting for manufacturers to acquire sites and construct their own premises, developers could begin offering serviced industrial plots, smaller speculative production buildings and build-to-suit facilities around locations where occupier demand is most credible.

Chișinău would remain the safest market because it already has the greatest concentration of logistics demand. Ungheni could become the strongest cross-border development opportunity because of its connection with Romania and emerging transport infrastructure. Bălți offers the strongest existing manufacturing cluster outside the capital. Giurgiulești provides a specialised port-led proposition. Cahul remains a longer-term location where investment will probably need to follow proven occupier demand rather than precede it.

The types of companies Moldova can realistically attract also matter. Automotive components already provide a foundation. Electrical equipment and electronics assembly could build on similar advantages. Food processing is a natural opportunity given Moldova’s agricultural economy, while packaging, light manufacturing and selected pharmaceutical production could also benefit from competitive operating costs and increasing access to European markets.

Large regional e-commerce distribution centres are less obvious because Moldova’s domestic consumer market is relatively small. But warehouses serving cross-border trade with Romania and Ukraine could become increasingly relevant as transport connections improve.

Electricity may ultimately prove just as important as roads. Modern manufacturing can require substantial and reliable power capacity, while warehouses increasingly consume more electricity through automation, refrigeration, digital systems and vehicle charging. Moldova’s continuing investment in energy security and stronger connections with European electricity networks therefore has direct consequences for industrial land.

A cheap development plot without sufficient electricity is not necessarily cheap at all.

Labour presents a similar complication. Moldova retains a cost advantage over many EU locations, but years of outward migration mean investors must examine actual labour availability rather than assume an unlimited workforce. Locations with existing industrial skills and reasonable commuting populations may therefore have a considerable advantage over isolated sites offering cheaper land.

This is why Moldova’s industrial proposition should not be built simply around being less expensive than Romania. The more interesting opportunity is integration.

As Romania’s motorway, logistics and manufacturing geography extends towards its eastern border, Moldova could gradually become connected to the same production networks. Ungheni could interact increasingly with Iași, Giurgiulești with Galați and Constanța, while Moldovan manufacturers could become deeper suppliers to factories operating throughout Romania and the rest of the European Union.

That would change the country’s industrial property market. More international manufacturers would create demand for better buildings. More modern buildings would make Moldova easier for additional manufacturers to enter. Eventually, that cycle could attract institutional developers and investors willing to own industrial property rather than leaving companies to construct almost everything themselves.

Moldova is not at that stage yet. Its warehouse market remains heavily concentrated around Chișinău, regional property markets lack depth and much industrial development still depends on companies creating facilities for their own use.

But the country’s economic geography is changing. EU accession negotiations, closer trade integration, Romanian transport infrastructure, new border connections, industrial incentives and investment in Moldova’s energy network are gradually improving the conditions for manufacturing and logistics investment.

The next constraint may therefore be real estate itself. If Moldova wants to become part of the industrial geography developing across eastern Romania, attracting companies will only be half the challenge. It will also need somewhere modern for them to manufacture, store and distribute what they produce.

Source: CIJ.World Research & Analysis Team
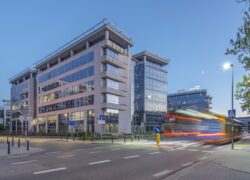
Signum Work Station Secures WELL Health-Safety Rating in Warsaw

Signum Work Station in Warsaw’s Mokotów business district has received the WELL Health-Safety Rating from the International WELL Building Institute, adding another certification focused on the operational standards of the 32,400 sqm office property.

The assessment covers how a building is managed in areas affecting the health and safety of its occupants. At Signum Work Station, the process included cleaning and hygiene procedures, measures intended to reduce contact with frequently touched surfaces, monitoring of air and water quality, emergency preparedness and business continuity procedures. Communication with building users and access to health-related resources were also included in the assessment.

CBRE Poland coordinated the certification process. According to Piotr Iwanowski, ESG Manager and BREEAM-In-Use Assessor at CBRE Poland, the work involved reviewing day-to-day procedures across property management, technical services, security and external contractors, as well as defining responsibilities and improving the way operational measures are monitored.

The rating remains valid for one year and requires annual renewal. Signum Work Station’s management team will therefore need to continue reviewing the relevant procedures to retain the designation.

The certification comes as competition within Warsaw’s office market increasingly centres on the quality and performance of existing buildings. According to figures included with the announcement, take-up of modern office space in Warsaw reached 282,800 sqm during the second quarter of 2026, while vacancy declined to 8.5%. With relatively limited new supply, landlords are placing greater emphasis on building management, occupier amenities and environmental and wellbeing standards.

Located on Domaniewska Street, Signum Work Station comprises seven above-ground and three underground levels. The property provides more than 32,400 sqm of leasable space and 870 parking spaces, while a typical floor extends to approximately 4,650 sqm. The building also contains retail, service and storage areas.

Signum Work Station already holds BREEAM Excellent and ActiveScore Platinum certifications. Occupiers include Mondelez, Ringier Axel Springer Polska, enel-med, Columbia and PPD.

The property was acquired by DRFG in December 2024 and is currently owned by Efekta Real Estate Fund. TriGranit, part of DRFG Investment Group, is responsible for leasing and asset management of the building.

front page info
LATEST NEWS