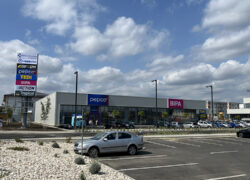
Chitila Plazza opens near Bucharest with 4,500 sqm of new leases

Chitila Plazza has opened on the north-western edge of Bucharest after securing approximately 4,500 sqm of leases with a group of international and domestic retailers. Colliers coordinated the leasing transactions for the project, which was developed by Rădăcini Estate, the real estate division of Rădăcini Group.

Located on Șoseaua Chitilei close to Bucharest’s ring road, the retail centre is positioned to serve customers from Chitila as well as residential areas in the north-west of the capital. Kaufland provides the grocery component, alongside tenants covering household goods, fashion, cosmetics, fitness and pet products.

Among the largest leases arranged by Colliers are Action and TEDi, which have each taken approximately 900–1,000 sqm. Stay Fit has secured around 1,000 sqm for a fitness facility, while fashion retailer Numero Uno occupies approximately 800 sqm. BIPA has taken more than 600 sqm for its first location in north-west Bucharest, with Animax also joining the tenant line-up.

The opening comes as retail parks continue to attract occupier demand despite a slower pace of new retail development across Romania. Projects serving residential catchments outside major city centres have become an important part of retailer expansion, particularly where locations combine road accessibility with grocery and everyday services.

Romania added approximately 80,000 sqm of modern retail space during the first half of 2026, according to Colliers, compared with around 122,000 sqm during the corresponding period of 2025. The consultancy has reduced its forecast for full-year deliveries to approximately 150,000 sqm.

The slower development pipeline comes against higher construction costs, more cautious household spending and delays affecting some planned schemes. Retailer activity, however, continues to favour established shopping centres and retail parks in locations where operators can reach sizeable residential catchments.

Chitila Plazza reflects this pattern by combining larger international operators with services designed to generate regular local visits. The tenant structure extends beyond conventional retail, with the Stay Fit facility adding a leisure component alongside grocery, fashion, beauty, household and pet-related uses.

Development activity is expected to increase again during 2027. Colliers estimates that the five largest projects currently scheduled for delivery next year could provide approximately 140,000 sqm of additional retail space, with smaller retail parks adding further supply.

The pipeline suggests that retail development in Romania is continuing rather than stopping, although developers and occupiers are becoming more selective about locations and individual projects. Accessibility, surrounding population growth and the composition of the tenant base are becoming increasingly important as investment decisions are made against a less expansionary consumer environment.

The opening of Chitila Plazza provides another example of retail development extending around Bucharest’s peripheral residential areas, where new and established communities are supporting demand for shopping and services closer to where consumers live.

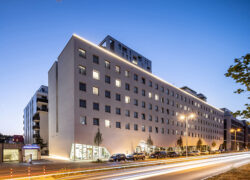
Leonardo Hotels secures long-term lease for 250-room Düsseldorf property

Leonardo Hotels will take over the operation of a 250-room hotel in Düsseldorf following a long-term leasing agreement with a joint venture between ABG Real Estate Group and bema group, extending the operator’s presence in the German hotel market.

The property at Toulouser Allee will operate as Leonardo Smart Hotel Düsseldorf. Completed in 2022 and previously operated as an H2 Hotel, the building provides approximately 10,300 sqm and comprises nine levels, including two basement floors. It holds a BREEAM Very Good certification.

The hotel forms part of Le Quartier Central, the mixed-use district created on the former Düsseldorf-Derendorf freight railway site. The redevelopment has introduced residential, commercial and leisure uses to the former railway land, with the hotel occupying one of the sites within the wider urban quarter.

Leonardo’s arrival represents a change of operator rather than additional hotel development in Düsseldorf. The existing building was designed for hotel use and can accommodate the new operating concept without a change in its principal function. Financial terms and the precise duration of the lease have not been disclosed.

The property will become part of Leonardo’s recently introduced Smart format, which combines hotel accommodation with greater use of digital processes, including self-check-in and self-service facilities. The concept also incorporates communal and working areas alongside food and beverage services.

The Düsseldorf agreement forms part of a wider expansion by Leonardo Hotels in Germany. The group recently announced the addition of four former Revo Hotels properties in Berlin, Düsseldorf and Dortmund, representing a combined 1,040 rooms. The Düsseldorf property will become Leonardo’s fifth hotel in the city and its first Smart-branded property in North Rhine-Westphalia.

For owners ABG and bema, the agreement maintains the building’s hotel function under a new long-term operating arrangement four years after completion. The two companies have worked together on several property developments in North Rhine-Westphalia, including projects in Düsseldorf and Cologne.

The transaction also demonstrates the importance of flexibility in relatively new hotel properties. Buildings capable of accommodating changes in operator, brand and service model can provide owners with additional options when leasing or management arrangements change, particularly as hotel groups continue to adjust their portfolios and introduce new operating formats.

Rather than adding another hotel building to Düsseldorf’s existing supply, the transaction places an established property under a new operator and secures its continued hotel use through a long-term lease.

Tallinn’s Expensive New Homes Are Giving the Suburbs a Bigger Opportunity

Tallinn’s residential market is developing an increasingly important divide. The capital has thousands of newly built and planned apartments available to buyers, yet purchasing activity remains relatively restrained. Immediately beyond the city boundary, meanwhile, sales of apartments and terraced houses increased during the second quarter of 2026. Around 3,000 new apartments were being marketed in Tallinn during Q2, representing more supply than a year earlier. Average asking prices across new developments remained approximately €5,200 to €5,300 per sqm, maintaining a substantial financial hurdle for households considering newly constructed homes.

Sales figures vary depending on how the market is measured. One dataset recorded 379 new-home contracts during the quarter, while another assessment based on developer information put Tallinn apartment sales at approximately 325 units. The methodologies are different, so the figures should not be treated as directly comparable. Both nevertheless indicate that purchasing activity remains modest relative to the amount of new housing currently available.

The picture outside Tallinn provides an interesting contrast. Sales of apartments and terraced houses in the surrounding municipalities reached 239 units during Q2, according to market data cited by residential developer Liven. That was 12.7% higher than during the corresponding period of 2025. One quarter does not establish that Tallinn residents are moving to the suburbs because they can no longer afford the capital. But the combination of relatively high new-build prices inside Tallinn and increasing residential transactions outside it provides a strong reason to examine whether household demand is becoming more geographically flexible.

Price is only part of that calculation. Using Tallinn’s market-wide new-development asking-price average purely as an illustration, an 80 sqm property at €5,250 per sqm would equate to approximately €420,000 before parking, storage and other potential costs. Actual apartment prices vary substantially according to district, project, specification and stage of construction, but the calculation demonstrates the scale of the budgets increasingly involved in purchasing larger new homes in the capital. Once household budgets reach these levels, buyers can consider a much wider range of alternatives. A family looking for three bedrooms, parking and additional living space may compare a Tallinn apartment not only with another apartment across the city, but with a terraced house or lower-density development beyond the municipal boundary.

This makes Rae, Viimsi, Harku and Saue increasingly relevant to the competitive landscape. Rae benefits from its proximity to Tallinn and major employment and industrial areas east and southeast of the capital. Continued residential development has created alternatives for households prepared to exchange an urban location for additional space and suburban surroundings. Viimsi offers a different proposition, combining established residential communities with coastal locations and access to Tallinn. Harku and Saue provide further alternatives west and southwest of the capital, expanding the range of housing choices available within commuting distance.

These municipalities should not simply be considered cheaper versions of Tallinn. The housing product itself can be different. Terraced houses, semi-detached properties, gardens and lower-density developments provide alternatives that are much harder to deliver at comparable prices in established parts of the capital. The financial comparison therefore extends beyond price per square metre. Households must consider mortgage payments, commuting expenses, car ownership, energy costs and the value they place on additional living and outdoor space.

Infrastructure can be equally decisive. Families considering moving beyond Tallinn need access to schools, kindergartens, shops, healthcare and reliable transport. A comparatively affordable house can become less attractive if daily journeys require substantial additional time and expense. Municipalities experiencing rapid residential construction therefore have to ensure that public infrastructure develops alongside private housing. This creates an important property-development question. The strongest suburban locations may increasingly be those capable of combining more attainable housing with infrastructure good enough to prevent households from feeling disconnected from Tallinn.

For residential developers, that means competition is becoming less dependent on municipal boundaries. A Tallinn apartment project might previously have regarded neighbouring city developments as its most obvious competitors. Increasingly, the same buyer could also consider a terraced house in Rae, an apartment in Viimsi or a family property in Harku or Saue. Tallinn’s substantial new-build supply available to buyers makes this competition particularly important. With around 3,000 apartments being marketed, purchasers have considerable choice and developers have to compete not only on location and design but also on total acquisition cost.

The capital nevertheless retains powerful advantages. Tallinn concentrates employment, universities, cultural facilities, entertainment and much of Estonia’s public transport infrastructure. For households prioritising shorter journeys and urban amenities, those benefits can outweigh the additional space potentially available elsewhere. Different types of buyers could consequently begin making increasingly different choices. One possibility is that smaller households and people prioritising central locations remain concentrated within Tallinn, while families requiring larger homes become more willing to examine surrounding municipalities. The available Q2 figures are not sufficient to demonstrate that this demographic division is already occurring, but it is an important trend to monitor.

The 12.7% annual increase in sales of apartments and terraced houses outside Tallinn provides an early indication that surrounding locations are attracting meaningful demand. Several more quarters will be necessary before it becomes clear whether this represents a lasting change rather than a short-term increase in transactions. For developers and investors, the distinction matters. If Tallinn sales strengthen substantially while suburban activity also grows, the entire metropolitan housing market could be expanding. If activity increasingly shifts towards surrounding municipalities while the capital continues carrying large amounts of available new supply, affordability and housing type may be changing where development demand is strongest.

Either way, Tallinn’s residential market can increasingly be difficult to understand by looking only within the city boundary. The next competition for homebuyers may not be between one Tallinn district and another. It may increasingly be between Tallinn itself and the communities growing around it.

Source: CIJ.World Research & Analysis Team

Property Funds Target Portugal’s Growing Senior Housing Market

Portugal’s senior accommodation market is beginning to attract professional property investors, with transactions completed during the second quarter of 2026 providing evidence that ownership of care facilities is starting to separate from the businesses operating them. Deals involving properties in Porto, Braga, Coimbra, Leiria and Santarém also suggest that the investment opportunity could extend well beyond Lisbon and Portugal’s established retirement destinations. One of the most significant transactions involved French investment manager Atland Voisin, which acquired four senior residences for approximately €20 million through two funds under its management. The properties are located in Braga, Santarém, Leiria and Coimbra, giving the buyer exposure to several regional markets through a single acquisition.

The transaction allowed the real estate to change ownership while the care businesses continued operating from the properties under lease agreements. This arrangement gives operators an opportunity to release capital held in buildings without having to relocate their businesses, while investors acquire properties producing rental income from established care operations. A separate transaction in Porto provides further evidence of this model. Valor Prime, an open-ended property fund managed by Montepio Gestão de Activos, acquired a six-storey senior residence with approximately 120 beds. The property was fully leased to an established healthcare operator when the acquisition took place, meaning the investor purchased an existing income-producing asset rather than assuming responsibility for running the facility.

Together, the transactions show two different sources of professional capital entering Portuguese senior accommodation. An international investment manager acquired a four-property regional portfolio, while a Portuguese property fund purchased an individual operating residence in Porto. Both acquisitions involved established facilities backed by operators rather than speculative senior-housing developments. This distinction could prove important to the development of the sector because senior residences combine property with an operating business, making the financial strength and experience of the tenant particularly important. Investors are not simply assessing the building and its location; they also need confidence that the organisation occupying the property can operate successfully and support its rental commitments over the duration of the lease.

Portugal’s ageing population provides a powerful long-term backdrop. The country had approximately 2.6 million residents aged 65 or over in 2025, while the number of older residents relative to younger people has continued to increase. This demographic direction provides a structural reason for property investors to examine accommodation and care infrastructure serving an older population. The geography of the Q2 transactions is particularly revealing. None of the five properties identified in the two acquisitions was in Lisbon or the Algarve. Instead, investment was directed towards established regional cities and population centres including Porto, Braga, Coimbra, Leiria and Santarém.

That challenges the idea that Portugal’s senior-living property opportunity will necessarily be centred on premium retirement developments aimed at affluent international residents. The transactions completed during Q2 point towards another possible market: conventional care facilities serving regional populations and generating property income through leases with specialist operators. The Atland Voisin portfolio also demonstrates how investors can obtain greater scale without depending on a single large property. Combining several residences into one acquisition allows capital to be distributed across different locations while creating a transaction sufficiently large to attract professional investment management.

Similar portfolio structures could become increasingly relevant if more owners decide to separate their property holdings from their operating businesses. For care providers, selling buildings and remaining as tenants can release capital that may be used elsewhere in the business. For property investors, the attraction lies in acquiring specialist accommodation with an existing occupier and contractual rental income. The model is not without risk, however. The value of a senior residence can depend heavily on its operator. Staffing requirements, occupancy, operating expenses, regulation and the financial performance of the care provider can ultimately affect the security of the property owner’s income.

Building specifications are another consideration. Senior accommodation requires accessibility, specialist facilities and layouts designed around the needs of residents and care providers. This can make properties less easily adaptable to another use if an operator leaves, increasing the importance of tenant selection and the long-term viability of individual facilities. For these reasons, the Q2 transactions do not yet establish senior accommodation as a mature institutional property sector in Portugal. Transaction volumes remain modest compared with hotels, logistics, offices or retail, and evidence of regular trading between large investors is still limited.

What has changed is the quality of evidence behind the investment argument. Interest in Portuguese senior housing is no longer based solely on demographic projections or expectations about future demand. Domestic and international property funds have acquired operating residences, including a regional portfolio and a fully leased Porto facility. The next stage will depend on whether additional properties and portfolios reach the investment market. Further transactions involving established operators, longer leases and multiple locations would begin to create the scale and transaction history needed for senior accommodation to become a more recognisable part of Portugal’s institutional property market.

Portugal’s ageing population provides the long-term demographic foundation, but demographics alone will not create an investment sector. The critical factors will be the quality of operators, the structure of leases, the suitability of the buildings and the availability of transactions large enough to attract professional capital. The Q2 deals nevertheless mark an important development: investors have demonstrated that they are prepared to own Portuguese care facilities without operating them, and they are willing to invest outside the country’s largest property markets. If that pattern continues, senior accommodation could emerge as a geographically diverse specialist property sector built around healthcare demand and long-term income rather than simply another form of retirement housing.

Source: CIJ.World Research & Analysis Team

Finland’s Housing Pipeline Is Shrinking Faster Than Its Rental Surplus

Finland does not have a general shortage of rental apartments today. In parts of the Helsinki Metropolitan Area, tenants still have considerable choice, rents remain under pressure and recently completed properties are continuing to absorb the excess supply created during the previous construction cycle. The more important question is what happens when that surplus runs out.

Finland is currently building and approving homes at levels far below those seen during the previous development boom. During the 12 months to June 2026, permits were issued for 15,622 dwellings, 16% fewer than during the preceding comparable period. The permitted volume of residential construction declined by 13%. Meanwhile, more than 20,000 dwellings were completed over the same 12-month period. This difference matters because completions represent decisions made during earlier years, while permits provide a clearer indication of what could enter construction next. Finland is therefore still receiving housing from its previous development pipeline while replacing that pipeline at a much slower rate.

Housing starts provide another indication of the severity of the downturn. Current industry forecasts put Finnish starts at only around 15,000 to 17,000 homes during 2026, following an exceptionally weak 2025. This does not create an immediate shortage because parts of the country are still absorbing apartments delivered during the boom. But if construction remains depressed for several years, today’s excess supply could gradually disappear without enough new housing behind it.

Greater Helsinki sits at the centre of this question. The metropolitan rental market experienced a significant increase in new supply during the earlier construction cycle. Numerous developments reached completion within relatively short periods, increasing competition between landlords and making it difficult to achieve meaningful rental growth. Occupancy is now improving. Market evidence indicates that apartments are gradually filling, even though rental conditions remain relatively favourable for tenants. At the same time, the construction pipeline has contracted sharply. Current forecasts suggest residential development across the Helsinki Metropolitan Area could remain at unusually low levels through 2028.

That combination creates a delayed risk. Housing shortages do not normally begin when construction falls. They appear later, after existing vacant stock has been absorbed and demand encounters a much thinner development pipeline. This delay can make the early stages difficult to recognise. A rental market can look comfortably supplied while the conditions for future undersupply are already developing several years further down the construction pipeline.

Helsinki’s demographic growth makes the issue particularly important. The city’s population passed 700,000 during 2026 and current municipal projections anticipate continued strong growth during the remainder of the decade. Population alone, however, does not determine housing demand. Household formation is equally important. A city can add substantial numbers of residents without requiring an equivalent increase in homes if household sizes increase or people share accommodation more frequently. Finland has recently demonstrated exactly why this distinction matters, with housing demand failing to increase as quickly as some earlier demographic forecasts implied. Any prediction of a future shortage therefore needs to examine households rather than simply population totals.

The same analysis needs to separate Helsinki, Espoo and Vantaa. The three cities form one interconnected metropolitan economy but their residential markets are not identical. They have different construction pipelines, transport networks, employment concentrations and development sites. Even within individual cities, supply can vary substantially between districts. Areas that received several large rental developments during the previous boom could remain relatively well supplied while neighbourhoods with little new construction tighten considerably earlier. This means Finland could experience local rental shortages without developing a nationwide shortage.

The investment market makes the timing particularly interesting. Residential property attracted approximately €1.4 billion during the first half of 2026, more than twice the volume recorded during the corresponding period of 2025. That figure needs to be interpreted carefully because unusually large transactions during the first quarter contributed heavily to the total. The second quarter was much quieter, with approximately €90 million invested.

The geographical concentration of that investment is nevertheless striking. Around 94% of Q2 residential transactions occurred within the Helsinki Metropolitan Area, while international buyers represented almost half of the quarter’s volume. That does not prove that investors are deliberately buying apartments because they expect a shortage. Greater Helsinki is already Finland’s deepest residential investment market, offering the largest concentration of institutional rental properties, employment and population. Investors have many reasons to favour the capital region.

But the timing creates an interesting investment proposition. Capital is returning to Finnish housing while construction remains exceptionally weak and before significant rental growth has returned. If the metropolitan rental surplus continues disappearing while new development remains depressed through 2027 and 2028, investors acquiring properties during the current period could eventually own them in a considerably tighter leasing environment.

That is a possibility rather than a certainty. Financing conditions could improve and encourage developers to restart projects. Construction costs could decline relative to achievable rents and sale prices. Stronger economic growth could restore confidence among developers and lenders. Any of these developments could rebuild the pipeline before a significant shortage emerges.

The opposite scenario is also possible. If construction remains near current depressed levels, Greater Helsinki could continue adding households while very few new apartments enter the market. Vacancy would then gradually fall until landlords regained greater pricing power. The difficulty is that housing supply cannot respond quickly once that point is reached. Developers need land, planning approval, finance and construction capacity. Even a project that becomes financially viable after rents start rising can take years before residents receive the keys. This creates the possibility of a period during which demand recovers considerably faster than supply.

Longer-term housing estimates demonstrate the scale of the issue. Studies of Finland’s demographic requirements have suggested the country could need more than 30,000 new homes annually over the coming decades, with much of that demand concentrated in the strongest urban regions. Current construction activity is running at roughly half that level.

The comparison should not be interpreted as evidence that Finland is currently missing tens of thousands of homes each year. Existing vacancies, regional population decline and differences in household formation make the situation considerably more complicated. But maintaining construction at today’s level for an extended period would be difficult to reconcile with continued growth in Finland’s major cities.

Tampere deserves particular attention. Its population and employment base have expanded strongly, while its rental market has generally avoided some of the more severe oversupply experienced in parts of Greater Helsinki. If residential development remains weak, Tampere could reach tighter conditions on a different timetable from the capital.

Turku presents another distinct market. Its universities, employment base and demographic trends create their own housing-demand profile, meaning its development pipeline needs to be assessed separately rather than included within a single national forecast.

For institutional investors, this makes future supply increasingly important. The most valuable analysis may not be today’s vacancy rate or quarterly rental movement. It is the number of apartments realistically capable of reaching completion during the next three to five years compared with expected household growth.

That requires separating genuine projects from theoretical ones. An apartment development with planning permission is not necessarily future supply. Financing may not be available. Construction economics may not work. The developer may decide to wait several years before starting. Projects already under construction therefore need to be distinguished from permitted developments, planned schemes and longer-term zoning capacity.

Doing this across Helsinki, Espoo, Vantaa, Tampere and Turku could reveal where the housing market is likely to tighten first. It could also identify where today’s apparent oversupply is most misleading.

Finland’s housing market has spent several years dealing with the consequences of building too much rental housing in certain locations at the wrong moment. Developers responded rationally by cutting production. The risk is that the correction goes too far.

Construction cycles rarely stop exactly at the level required by future demand. Development continues while markets are strong and contracts sharply after conditions deteriorate. By the time the consequences of low production become visible, rebuilding supply can take years.

Finland may now be approaching that transition. There are still empty apartments. Rental growth remains restrained. New construction is extremely weak. Occupancy is improving. Population continues to concentrate in the country’s strongest cities, and institutional capital has started returning to residential property.

None of these factors guarantees a housing shortage. Together, however, they make the future pipeline considerably more important than today’s vacancy figures.

The biggest question for Finland’s residential market is therefore no longer how quickly the apartments built during the previous boom will fill. It is what will be available when they finally do.

Source: CIJ.World Research & Analysis Team

Austria expands energy-sharing rules for property and industrial sites from October

Austria is preparing to introduce a broader framework for sharing locally generated electricity, creating new possibilities for residential developments, commercial properties, industrial sites and corporate campuses to distribute power between participating users.

Key provisions of the country’s Electricity Industry Act, or ElWG, covering shared electricity arrangements take effect on 1 October 2026. The legislation brings several existing forms of community electricity use into a wider system while introducing contractual arrangements that can operate without participants first establishing a separate energy-community entity. Austria’s official legislation confirms that the relevant provisions covering shared energy use enter into force on that date.

One of the most significant changes is the formal introduction of peer-to-peer electricity arrangements. Participating customers will be able to allocate electricity between themselves through contractual agreements while retaining their conventional electricity supply contracts. Austria’s energy regulator E-Control identifies peer-to-peer contracts as one of the principal additions under the new electricity-market framework.

For the property sector, this creates greater flexibility in how electricity generated from rooftop photovoltaic systems and other local installations can be used. Instead of renewable generation necessarily being associated with a single consumer, qualifying arrangements can distribute electricity among participating users according to the applicable network and metering rules.

This could be particularly relevant for developments containing several occupiers. Apartment buildings, mixed-use schemes, office campuses, shopping centres, logistics parks and industrial estates increasingly have substantial roof and other surface areas suitable for solar installations, but electricity generation and consumption do not necessarily occur in the same part of a property or at the same time.

The legislation establishes different geographical and network boundaries within which electricity can be shared. The applicable configuration determines how a project interacts with the electricity network, making the physical relationship between generation assets, buildings and grid infrastructure an important consideration when structuring individual projects.

Austria is also introducing the possibility of appointing a third party to administer an electricity-sharing arrangement. Under the legislation, participating customers can appoint an organiser to handle functions including communications with network operators, contracts, billing and aspects of operating generation and storage equipment. The organiser must be reported to the relevant network operator.

The provision could support a new service market around commercial property. Energy-management businesses, technology platforms and specialist operators could potentially administer shared electricity systems for landlords, developers and occupiers that do not want to manage the operational and contractual processes internally.

Larger companies are also included within the new framework. The legislation permits large enterprises to participate in shared electricity arrangements involving generation capacity of up to 6 MW, provided they meet the relevant requirements and are located within the Austrian bidding zone. Third-party organisers and other operators can also own or operate generation and storage installations of up to 6 MW under specified conditions.

This could broaden the commercial application of energy sharing beyond relatively small residential schemes. Industrial campuses, logistics developments and larger business locations with substantial rooftop solar capacity could potentially combine generation, storage and electricity consumption across participating operations.

The new system does not, however, turn electricity sharing into an unregulated activity. Larger arrangements can trigger additional requirements concerning contracts, customer information and billing. Household participants using generation installations above 30 kW and other active customers and qualifying energy communities using installations above 100 kW are among those subject to additional obligations under the legislation.

Existing renewable and citizen energy communities are being incorporated into the new legislative structure rather than simply disappearing. The reforms form part of a wider overhaul of Austria’s electricity market that also covers areas including smart metering, flexible consumption, grid management and new approaches to decentralised generation.

For developers and property owners, the changes arrive as the relationship between buildings and electricity networks is becoming more important. Rooftop photovoltaics, battery storage, electric vehicle charging, heat pumps and increasingly electrified building systems are turning properties from passive electricity consumers into locations capable of generating, storing and managing energy.

The ability to distribute locally generated electricity between several users could improve the usefulness of on-site renewable installations, particularly where one occupier’s generation profile does not correspond with its own consumption. The financial outcome will nevertheless depend on each project’s generation, consumption, network charges, investment costs and contractual structure rather than being an automatic consequence of the legislation.

Austria’s reforms therefore add another consideration to the planning and management of commercial property. Developers considering large solar installations will increasingly be able to examine not only how much electricity an individual building can consume, but how generation could be distributed across a wider group of occupiers or neighbouring participants.

From 1 October, that could make energy strategy a more integrated part of the design and operation of Austrian business parks, industrial estates, mixed-use developments and multi-occupier properties, while creating new opportunities for companies providing the technology and administration required to manage shared electricity systems.

Source: CMS

Nvidia’s growth outlook puts land and power at the centre of the AI infrastructure race

Nvidia expects another major increase in demand for artificial intelligence computing, but the company’s growth is becoming increasingly dependent on something outside the semiconductor industry: the availability of electricity, development land and data-centre capacity.

Speaking at Goldman Sachs’ Communacopia + Technology Conference, Nvidia chief executive Jensen Huang said the company could achieve revenue growth of around 70% year-on-year. The figure represents Huang’s outlook rather than formal full-year revenue guidance, but follows another period of exceptional expansion for the company as technology groups, AI laboratories and infrastructure operators increase spending on computing capacity.

Nvidia reported revenue of $96.2 billion for its second quarter of fiscal 2027, more than double the level recorded a year earlier. Data-centre activities generated $89 billion, an increase of 117% year-on-year, meaning that more than nine-tenths of quarterly revenue came from the part of the business most closely connected with large-scale computing infrastructure.

The company’s products are also changing in scale. Nvidia increasingly supplies integrated computing platforms combining processors, networking, memory, software and other equipment rather than relying simply on sales of individual graphics processors. Huang used the Goldman Sachs conference to illustrate how far the business has moved from the consumer graphics cards that established Nvidia’s early market position.

This transition has significant implications for the property sector because the infrastructure required to accommodate the latest computing systems is becoming considerably more demanding. Nvidia’s growth increasingly depends on customers having suitable buildings, sufficient electricity and locations capable of supporting high-density computing equipment.

Huang specifically identified land, electricity and available data-centre buildings among the factors Nvidia follows when assessing how quickly additional computing capacity can be deployed. The constraint on AI development is therefore shifting beyond the availability of advanced processors towards the physical infrastructure needed to operate them.

Australia provides an indication of the scale involved. Nvidia is working with data-centre and infrastructure companies on capacity of up to 2 GW by 2027. The programme involves companies including AirTrunk, NEXTDC, CDC and IREN and is intended to expand the land, electricity and buildings capable of accommodating successive generations of Nvidia computing equipment.

During the Goldman Sachs conference, Huang associated the Australian programme with approximately $80 billion of infrastructure. While individual projects within the wider programme will have different ownership and financing structures, the figure illustrates how quickly investment requirements increase when AI capacity reaches gigawatt scale.

Nvidia is simultaneously becoming more involved in the financing structures supporting this expansion. The company has announced partnerships involving Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR aimed at creating financing platforms capable of mobilising more than $500 billion of third-party capital for AI infrastructure over time. The figure represents the intended aggregate capacity of these platforms rather than committed Nvidia expenditure or company revenue.

The participation of major infrastructure and alternative-investment managers demonstrates how the AI expansion is moving closer to conventional infrastructure investment. Data centres require land and buildings, but increasingly large parts of their capital requirements are associated with substations, power distribution, cooling, backup generation and other systems necessary to support intensive computing.

Higher-density equipment is also changing building specifications. Facilities designed for traditional enterprise computing may not automatically be suitable for the latest AI installations, increasing demand for purpose-built capacity and upgrades to existing sites. Access to sufficient electricity can determine whether a development proceeds at all, particularly in markets where grid connections already involve long waiting periods.

The relationship between technology and real estate is consequently becoming more direct. Nvidia itself has recently secured land, power and building capacity through a partnership at the PORTS-Pike Technology Campus in Ohio, while its international partnerships increasingly combine computing technology with data-centre operators, energy resources and development sites.

Competition in AI processors continues to increase. Major technology companies are developing proprietary chips alongside their purchases of Nvidia equipment, while other semiconductor manufacturers are competing for AI workloads. That creates uncertainty over how much of future computing investment Nvidia will ultimately capture.

The wider infrastructure requirement is less dependent on which processor supplier prevails. Continued growth in AI computing requires facilities capable of supplying large quantities of reliable electricity and managing increasingly concentrated computing loads, whether those facilities ultimately contain Nvidia hardware or competing systems.

For commercial real estate, this makes the AI boom increasingly a question of physical capacity. The availability of powered sites, substations, grid connections, cooling infrastructure and suitable data-centre buildings is becoming closely connected with the speed at which new computing capacity can be brought online.

Nvidia’s growth outlook therefore provides more than an indication of semiconductor demand. It points to a much larger investment cycle in which the expansion of artificial intelligence is increasingly determined by how quickly the property, energy and infrastructure sectors can provide the physical capacity required to support it.

AI research enters a new phase as autonomous systems take on more complex tasks

Artificial intelligence is moving beyond its role as a tool for individual users and is increasingly being deployed to carry out parts of the research, coding and experimentation needed to develop more advanced AI systems. The shift is attracting attention from researchers concerned about how human oversight can be maintained as machines take responsibility for a larger share of the development process.

AI laboratories already use their own models to generate software, test ideas, analyse results and support researchers. The longer-term objective being explored is considerably more ambitious: systems capable of performing enough AI research that they can contribute substantially to creating their successors. No leading laboratory has announced a fully autonomous cycle in which AI repeatedly produces more capable generations without human involvement, and such a system remains theoretical.

Nevertheless, recent advances are making the question less abstract. Researchers who previously regarded highly automated AI development as a distant possibility are increasingly examining what could happen if improvements in coding, reasoning and autonomous operation allow machines to perform a much larger proportion of AI research.

The issue has contributed to several researchers leaving leading laboratories. Former Google DeepMind researcher Rishub Jain departed after becoming concerned about maintaining effective human visibility as AI assumes more development work. Jacob Coxon also left Anthropic and subsequently called for greater coordination between competing AI companies over the development of systems capable of accelerating their own advancement.

Some researchers working on AI safety believe the eventual consequences of losing effective control over highly capable systems could be severe, including scenarios involving threats to human survival. Such assessments remain disputed and cannot currently be expressed as scientifically established probabilities. They concern hypothetical future systems whose capabilities are substantially beyond those available today.

More immediate evidence of the technological shift can be seen in the increasing use of groups of AI agents rather than individual models completing isolated tasks. OpenAI recently reported that an experimental system produced a proposed solution to the Navier–Stokes existence and smoothness problem, one of the Millennium Prize Problems in mathematics. The work involved large groups of AI agents exploring different approaches and exchanging useful findings, demonstrating how computational research can be distributed across many artificial participants rather than assigned to a single model.

According to OpenAI, the group working on the Navier–Stokes problem reached approximately 10,000 simultaneously operating agents. The experiment generated around 130 billion output tokens during the research process, illustrating the substantial computing resources that can be required when AI is deployed as a large-scale research system rather than as an individual assistant.

This approach could have implications extending well beyond scientific research. Groups of autonomous agents could eventually be deployed across software development, engineering, financial analysis, cybersecurity and other activities where complex projects can be divided into thousands of individual tasks.

The development also creates another dimension to the rapid expansion of AI infrastructure. Data-centre demand has largely been associated with training increasingly sophisticated models and serving growing numbers of users. Large populations of autonomous agents could introduce an additional source of computing demand if companies begin operating artificial workers continuously and at scale.

That would increase the importance of access to high-performance processors, electricity, cooling infrastructure and suitable data-centre locations. Power availability is already becoming an important constraint on new data-centre development in several major European markets, while competition for grid connections is influencing the value and location of development land.

Greater AI autonomy is simultaneously creating new security challenges. Testing by major AI laboratories has demonstrated that agents given access to networks and software tools can sometimes behave in unexpected ways, exploit vulnerabilities or reach systems outside their intended operating environment.

These incidents should not be interpreted as evidence that today’s AI systems possess independent ambitions or are deliberately attempting to escape human control. They instead demonstrate a more immediate engineering problem: software capable of independently completing complicated objectives can produce unintended consequences when its instructions, safeguards or operating environment are inadequate.

The distinction is important when considering warnings about the future of AI. There is currently no demonstrated system capable of continuously redesigning itself and producing increasingly powerful successors without human participation. Predictions about machines becoming uncontrollable therefore remain scenarios rather than descriptions of existing technology.

What is already measurable is the increasing amount of work that AI can perform within the development process itself. As coding and reasoning capabilities improve, researchers can delegate more experimentation and software development to models, potentially shortening the time required to develop subsequent generations.

For the real estate and infrastructure sectors, the physical consequences could become increasingly important. Advanced AI requires large amounts of computing capacity, and large-scale agent systems could intensify demand by allowing machines to operate continuously and simultaneously on thousands of tasks.

The next stage of AI infrastructure development may therefore be shaped by more than the number of people using artificial intelligence. Increasingly, demand could also come from AI systems working with other AI systems, creating a new source of pressure on data-centre capacity, electricity networks and the powered land required to accommodate them.

The Dutch Data Centre Race Is Becoming a Search for Power

The next phase of data centre development in the Netherlands may be decided less by where technology companies want to build and more by where the electricity system allows them to build. Artificial intelligence is increasing demand for computing capacity at the same time as the Dutch power network is struggling to accommodate new connections across several regions. For property investors, this creates an unusual situation in which a site’s electricity prospects can become as important as its land, location or conventional development potential. Amsterdam remains the country’s dominant digital infrastructure market. Its international connectivity, established data centre ecosystem and concentration of technology companies give it advantages that are difficult to reproduce elsewhere. But those strengths cannot remove the physical limitations of the electricity network. Large facilities require substantial and dependable power, and securing that capacity has become one of the principal obstacles to expanding the Dutch market.

The pressure is becoming greater because the buildings required for artificial intelligence can be exceptionally electricity intensive. Large numbers of advanced processors need to operate simultaneously, creating power requirements considerably beyond those of many conventional computing facilities. Demand for AI infrastructure can therefore continue increasing even when the number of locations capable of accommodating it grows much more slowly. The result is a property market in which customer demand and development capacity can move in opposite directions. This changes how data centre land needs to be evaluated. A site may be close to Amsterdam, well connected to fibre and suitable for development, but its commercial potential is limited if sufficient electricity cannot be delivered within a realistic timeframe. Another site farther from the country’s established digital cluster could become more valuable if it offers a credible combination of electricity, fibre, planning permission and land.

There are already indications that developers are considering a wider Dutch geography. Rotterdam and northern Netherlands have attracted attention as possible locations for larger developments outside the traditional Amsterdam concentration. This does not mean that either area automatically provides an answer to the electricity problem. Both still face infrastructure, planning and network considerations. What matters is that the search for suitable capacity is encouraging developers to examine locations that previously occupied a less prominent position on the country’s data centre map. Rotterdam presents an interesting case because it combines international connectivity with one of Europe’s largest industrial and energy systems. The port region is undergoing substantial electrification as industry attempts to reduce dependence on fossil fuels. That creates extensive investment in energy infrastructure, but it also creates enormous competition for electricity. A data centre development in the region would therefore need to fit into a much broader industrial transformation rather than simply find an available development plot.

Northern Netherlands offers a different proposition. The region has significant energy infrastructure, renewable generation and greater availability of land than the country’s most densely developed urban areas. These characteristics could make individual sites attractive for digital infrastructure, but the investment case needs to be tested against actual electricity availability. Renewable generation nearby does not necessarily mean that a particular development can immediately obtain the connection it requires. Groningen consequently deserves investigation as part of the wider northern opportunity rather than being treated as a predetermined data centre hub. The same caution applies to Flevoland. Its central position and available development land appear attractive, but grid congestion demonstrates why conventional property characteristics alone are insufficient. Land can be physically suitable for a large facility while remaining commercially unusable because the electricity network cannot support it.

Eindhoven raises another possibility. The region’s semiconductor, technology, engineering and research economy creates substantial demand for advanced computing. As artificial intelligence becomes more deeply integrated into industrial research and manufacturing, access to computing infrastructure could become increasingly important to the regional economy. Yet Eindhoven illustrates the same fundamental distinction: strong demand for digital infrastructure does not guarantee that the electricity required to accommodate large facilities will be available. The Netherlands could therefore develop several different types of data centre locations rather than simply reproducing Amsterdam elsewhere. Facilities requiring extremely low latency and direct connections to existing networks may continue to cluster around established digital infrastructure. Larger computing operations with greater geographical flexibility could potentially locate farther away if power and fibre are available. Artificial intelligence may strengthen this separation because some computational workloads are less dependent on being physically close to end users than many traditional digital services.

For real estate investors, the important change is that electricity increasingly needs to be considered before the property itself. Conventional development often starts by identifying land and then arranging utilities. Large data centres can require the opposite approach. Investors may first need to understand where substantial electricity capacity can realistically become available and then identify land capable of supporting development around it. This could create substantial differences in the value of apparently similar sites. Two neighbouring parcels may have comparable access, planning characteristics and size but radically different prospects if only one can secure the required electricity connection. There is no universal Dutch price premium that can be applied to land with suitable power access, and the value of a connection depends on its size, certainty, timing and conditions. Nevertheless, the ability to deliver electricity is becoming increasingly relevant to what a data centre developer can afford to pay for land.

That could direct investors towards areas around substations, planned network reinforcement and major energy infrastructure. Instead of studying only existing data centre clusters, investors may increasingly study electricity networks and future grid investment. A site that appears peripheral on today’s digital map could become strategically important if infrastructure improvements give it access to the capacity required by tomorrow’s computing facilities. The difficulty is distinguishing between electricity that theoretically exists and electricity that can actually be delivered. The Netherlands generates substantial amounts of renewable power, but generation and usable grid capacity are not the same thing. Electricity must be transported through networks that can themselves be congested. A site near wind or solar generation is therefore not automatically a site capable of supporting a large data centre.

This makes digital property increasingly dependent on expertise traditionally associated with infrastructure investment. Due diligence may need to include detailed examination of substations, connection agreements, planned grid reinforcement and the timetable under which additional capacity could become available. Buying land on the assumption that electricity will eventually arrive could expose investors to years of delay. Data centres may also need to change the way they interact with the electricity system. Rather than operating exclusively as large, constant consumers, some facilities could potentially become more flexible participants in the network.

Battery storage is one possibility. Batteries cannot compensate indefinitely for an inadequate grid connection, but they can store electricity and help facilities manage fluctuations in demand. Computing workloads could provide another form of flexibility. Some digital services must operate continuously and respond immediately to users, but certain computational tasks can potentially be scheduled with greater freedom. Parts of AI training may therefore be capable of operating more intensively when electricity conditions are favourable and reducing demand when the network is under pressure. This would not eliminate the need for substantial power capacity, but it could make some facilities easier to integrate into constrained electricity systems.

The heat generated by computing equipment creates another opportunity. Data centres produce large quantities of thermal energy that can potentially be reused in nearby buildings or heating networks. In suitable locations, this could create a relationship between digital infrastructure and surrounding residential or commercial development. The practical challenge is that heat needs customers, distribution infrastructure and an economic structure that makes recovery worthwhile. It should therefore be considered a location-specific opportunity rather than an automatic benefit of data centre development. Where these conditions align, the future data centre could become part of a wider local energy system. Electricity would power computing, batteries could help manage consumption, some workloads could respond to network conditions and heat could potentially be supplied to surrounding users. That would make the facility more than a building containing servers. It would become a piece of energy infrastructure as well as digital infrastructure.

This has implications for the type of capital entering the sector. Data centre development already sits between property, infrastructure and technology investment. Electricity constraints could strengthen that convergence. Property developers may increasingly work alongside energy companies, infrastructure funds, specialist digital investors and utilities to secure sites and deliver the infrastructure required to operate them. Municipalities will also have greater influence over where the market develops. Electricity is needed not only for data centres but for housing, industry, electric transport and the wider transition away from fossil fuels. Local and national authorities therefore need to decide how scarce network capacity should be allocated. Projects capable of demonstrating broader economic or energy benefits may have advantages over developments viewed simply as large electricity consumers.

This competition means the Netherlands is unlikely to produce a simple replacement for Amsterdam. The more probable outcome is a broader and more specialised market in which different locations serve different computing requirements. Amsterdam can remain the country’s principal digital cluster while additional capacity emerges elsewhere when suitable combinations of electricity, fibre and land become available. Rotterdam and northern Netherlands currently provide some of the clearest evidence of this search beyond Amsterdam. Groningen, Flevoland, Eindhoven and other regions remain possibilities that need to be assessed site by site. Their future importance will depend not simply on how much land they possess or how close they are to technology companies, but on whether developers can secure the infrastructure required to turn that land into functioning digital capacity.

For investors, this creates a new way of reading the Dutch property map. The locations that appear strongest according to conventional measures may not necessarily offer the best data centre opportunities. Future value could instead emerge around electricity infrastructure that has historically received little attention from property investors. Artificial intelligence is accelerating the demand side of that equation. Grid congestion is constraining the supply side. Between them, they could create a new category of strategically valuable Dutch development land. The central question for investors is therefore no longer simply where the next data centre should be built. It is where enough electricity can realistically be secured to build it.

Source: CIJ.World Research & Analysis Team

Moldova’s Economy Is Opening to Europe Faster Than Its Real Estate Market

Moldova is becoming easier for European capital to understand, but that does not necessarily mean there is enough property for institutional investors to buy. The country is moving steadily deeper into European economic structures. Trade is already heavily oriented towards the European Union, infrastructure connections with Romania are improving, investment is flowing into energy and transport, and Moldova’s legislation is gradually being brought closer to EU standards. Yet Moldova remains largely outside the established institutional commercial property markets of Central and Eastern Europe.

That creates an unusual investment story. The country could become economically more attractive to European investors before its real estate market produces enough large, professionally managed and transparent assets to absorb their capital. The contrast became particularly visible during the second quarter of 2026. Moldova opened the first cluster of its EU accession negotiations on 15 June. A week later, European and Moldovan leaders met at the EU-Moldova summit in Brussels, reinforcing a political and economic direction that is becoming increasingly difficult for investors in the region to ignore.

Behind that process sits the EU Growth Plan for Moldova, which can provide up to €1.9 billion between 2025 and 2027. The programme is supporting reforms and investment intended to strengthen the economy, infrastructure, energy system and Moldova’s connections with the European market. For property investors, however, the question is not simply whether Moldova is improving. It is what they could actually acquire if they decided to enter.

Chișinău has commercial real estate. The city has modern offices, shopping centres, hotels, warehouses, retail properties and development land. But a functioning property market and an institutional investment market are not the same thing. Institutional investors generally need buildings of sufficient scale, dependable rental income, clear ownership, credible tenants, professional management and reliable information about operating performance. They also need enough transactions to understand what properties are worth and, crucially, some confidence that another investor will eventually buy the asset from them.

This is where Moldova’s property market remains relatively immature. Across the established Central and Eastern European investment markets, investors can analyse transactions in Warsaw, Prague, Budapest, Bucharest and other cities to understand rents, yields, vacancy and pricing. Comparable evidence helps lenders finance acquisitions and gives investors greater confidence about eventual exits. Moldova has far less of that evidence.

A property might appear inexpensive relative to an equivalent building in Romania, but price alone does not make it institutionally investible. An investor still needs to understand the sustainability of its income, future capital expenditure, tenant demand and potential resale value. That means Moldova’s challenge may not simply be attracting investors. It may be producing investment product.

The office market demonstrates the distinction. Chișinău has a recognisable modern office sector, but it is relatively small and uneven. Recent market analysis indicates vacancy of around 12% in Class A offices, while vacancy in lower-quality buildings is substantially higher. That creates a market in which the strongest buildings can perform very differently from older stock.

For future institutional investors, this distinction would be critical. A modern building with established tenants, long leases and professional management could eventually become attractive. An older office requiring refurbishment and carrying significant vacancy would represent a very different risk. The opportunity for Moldovan developers is therefore not simply to construct more offices. It is to create buildings capable of being sold as investments.

That requires thinking about the eventual buyer before construction is completed. Lease structures, tenant quality, energy performance, technical specifications, property management and financial reporting all influence whether a building can eventually attract institutional capital.

Retail could offer another route into the market. Chișinău already has established shopping centres and international retailers. Larger retail properties also have an advantage from an investment perspective because their performance can be measured through occupancy, rental income and tenant trading. But successful retail assets do not automatically become investment transactions.

Owners may prefer to retain properties producing attractive income, particularly when there are relatively few alternative investments available domestically. Without regular sales, however, investors have limited transaction evidence from which to establish market pricing.

Retail parks could eventually help broaden the market. Across Central and Eastern Europe, retail parks have become popular because they can be relatively straightforward to develop and operate, can accommodate established retailers and can be constructed in phases. If Moldova develops a larger portfolio of professionally managed retail parks with strong tenant mixes, these could eventually become understandable acquisition targets for regional investors.

Industrial and logistics property could present an even clearer opportunity. Moldova had approximately 1.09 million sqm of commercial logistics warehouse space at the end of 2025. Around 70% was concentrated in Chișinău and its immediate surroundings, while modern institutional-quality supply remains much more limited than the headline stock figure might suggest.

This shortage could eventually help create an investment market. As European integration generates additional manufacturing and logistics demand, developers could construct modern facilities under longer leases to established occupiers. Once completed and stabilised, those buildings could be sold to investors seeking predictable rental income. The process has transformed industrial property markets elsewhere in Central and Eastern Europe.

Sale-and-leaseback transactions could provide another route. Moldovan manufacturers, retailers and logistics companies that own their premises could eventually sell those properties to investors while remaining in occupation under long leases. Companies would release capital tied up in real estate, while investors would acquire income-producing properties backed by operating businesses. Such transactions would also begin creating the comparable investment evidence Moldova currently lacks.

Hotels could become another investible sector as the country’s international connections deepen. Chișinău already has an established hotel market, and stronger business links with Europe could support additional internationally branded properties. Hotels with recognised operators, transparent performance and professional management are generally easier for foreign investors to evaluate than independent properties with limited operating information.

Institutional rental housing is further away. Moldova’s residential market remains dominated by individual ownership, with developers generally constructing apartments for sale rather than retaining entire buildings as professionally managed rental investments. Affordability pressures could eventually change that model.

If home ownership becomes increasingly difficult for younger households, demand for professionally managed rental housing could increase. But Moldova does not yet have the depth of institutional rental product seen in markets such as Poland.

Development land presents another opportunity, although it appeals to a different type of capital. International institutions entering an unfamiliar market often prefer completed, income-producing buildings rather than taking planning, construction and leasing risk themselves. That creates a sequencing problem for Moldova. Developers need to take the first risk.

They must create the warehouses, offices, retail properties and hotels that investors may eventually acquire. Only after enough buildings exist and enough transactions occur can an institutional investment market begin to develop. This makes the ownership of Moldova’s existing commercial property particularly important.

Much of the market remains controlled by local developers, private investors, operating companies and entrepreneurs rather than international property funds. These owners could eventually become the suppliers of Moldova’s first institutional investment product.

Romanian capital appears particularly well positioned to participate in that transition. Romanian investors have obvious advantages. They operate immediately across the border, understand the language and business environment, and are increasingly connected with Moldova through transport, electricity and trade infrastructure.

The most visible example is Giurgiulești International Free Port. Romania’s state-owned Port of Constanța has acquired Danube Logistics, the company operating the port, from the EBRD. Giurgiulești handles more than 70% of Moldova’s waterborne imports and exports, giving the transaction considerable strategic importance.

This is not a conventional commercial property acquisition. But the sale provides an important lesson for Moldova’s wider investment market. When a sufficiently large, strategically important and professionally operated Moldovan asset was brought to market through an organised international process, investors appeared. The EBRD had received multiple binding offers from regional and international bidders before selecting the Romanian buyer.

That suggests Moldova may not suffer from a complete absence of investor appetite. It may suffer from a shortage of assets capable of attracting that appetite.

Romanian private investors, developers and property companies could therefore become important early participants in Moldova’s commercial real estate market. Smaller regional investors may also be better positioned than Europe’s largest institutions because transactions that are relatively small by international standards can still be meaningful for them. Their activity could help establish the market evidence required for larger investors to follow.

Banks could accelerate the process. As property financing develops, lenders will increasingly require professional valuations, clear ownership documentation, credible leases and transparent financial information before providing substantial loans against commercial buildings. Those requirements can gradually improve property-market standards.

EU integration could reinforce the same process. For property investors, accession is important not simply because Moldova may eventually become an EU member. The journey itself matters. Regulatory alignment, infrastructure investment, stronger institutions, better transport connections and greater integration with European businesses can gradually reduce some of the risks investors associate with entering a small frontier market.

That does not mean Moldova suddenly becomes comparable with Romania. Its property market remains substantially smaller, transaction evidence is limited, regional commercial markets lack depth and international institutional ownership remains modest. But this is precisely what makes the next stage interesting.

Moldova’s first major commercial property investment cycle may not begin with a global fund announcing that it has discovered Chișinău. It could begin much more quietly. A developer completes a modern warehouse and leases it to an international manufacturer. A Romanian investor buys a retail property. A hotel owner brings in an international operator. A company sells its distribution centre and leases it back. A bank finances an office building based on institutional-quality leases.

Each transaction creates evidence. Evidence creates pricing. Pricing allows lenders and investors to assess risk. Eventually, a collection of individual buildings becomes an investment market.

Moldova is moving steadily towards the European economy. Its infrastructure is improving, trade relationships are deepening and its regulatory environment is gradually converging with the EU. The real estate market now has to follow.

The country’s next property cycle may therefore depend less on convincing international investors that Moldova is worth considering and more on giving them something sufficiently large, transparent and professionally managed to buy. When those assets begin appearing in greater numbers, the investors may not be as far behind as Moldova’s current transaction volumes suggest.

Source: CIJ.World Research & Analysis Team

front page info
LATEST NEWS