Five Years After Brexit: The Economic Reality

Brexit ushered in a new era of ‘global Britain’ or an extended period of national decline, depending on your viewpoint. Five years on, we sift the evidence.

In January 2020, the United Kingdom officially left the European Union, a move that supporters hailed as a historic step towards economic freedom while opponents feared it would trigger long-term decline. Five years on, the reality is more complex. The economic impact of Brexit has been compounded by global challenges, including the COVID-19 pandemic and Russia’s invasion of Ukraine. However, Brexit itself has left a deep mark on the UK economy, with some analyses estimating a £140 billion loss directly linked to the country’s departure from the EU.

The Trade and Cooperation Agreement (TCA), which took effect on January 1, 2021, introduced new regulatory barriers, customs checks, and rules of origin requirements. As a result, UK trade with the EU declined sharply, with goods exports dropping by £27 billion in 2022 alone. Even now, the UK’s total trade in goods remains 12 percent below pre-Brexit levels, with goods exports at just 82 percent of their 2020 volume. In contrast, EU trade has rebounded, matching pre-Brexit levels. Economist Dana Bodnar of Atradius describes the situation as grim, noting that UK exports have struggled even more than imports, leaving the country’s overall trade performance weaker than anticipated.

Beyond Europe, the UK has pursued new trade agreements, though results have been underwhelming. While the country has secured 70 trade deals, most simply replicate previous EU agreements. New deals with Australia and New Zealand have been widely publicized but are limited in scope, and negotiations with the United States have stalled. The UK’s accession to the Comprehensive and Progressive Agreement for Trans-Pacific Partnership (CPTPP) may offer future benefits, though in the short term, its impact remains modest. Given that the UK already had agreements with nine of the eleven CPTPP members, any significant gains will depend on the bloc’s expansion.

Brexit’s impact has been uneven across different industries. Agriculture has been particularly hard-hit, with Brexit-related labor shortages exacerbated by the war in Ukraine. UK farmers, once reliant on seasonal migrant workers, have struggled to find replacements, leading to crop losses reported by 40 percent of farmers surveyed by the National Farmers’ Union. In response to concerns about rising costs, the UK government has delayed post-Brexit checks on EU agricultural imports for a third time, pushing them back to July 2025.

The automotive industry faces a major Brexit-related challenge in the form of a planned 10 percent tariff on electric vehicles traded between the UK and the EU, set to apply if they fail to meet strict rules of origin requirements. Originally scheduled for 2024, these rules have been deferred for three years to avoid disruptions at a time when the European auto industry is already grappling with rising competition from Chinese manufacturers.

For the chemicals sector, Brexit has introduced both tariffs and regulatory complications. With two-thirds of UK chemical production destined for export—mostly to the EU—new trade barriers mean that 70 percent of these exports now face tariffs, while raw material imports from the EU are also subject to new costs. The lack of a cost-effective UK regulatory framework to replace the EU’s chemicals registration system has created further uncertainty, affecting investment in the petrochemicals sector.

Despite these challenges, some industries remain resilient. Aerospace, paper and packaging, and renewable energy are expected to perform well in 2025, and the UK media industry is poised for significant growth. However, sectors with greater exposure to Brexit-related challenges—such as steel, logistics, and construction—face a more uncertain future.

While Brexit was driven by political as well as economic motivations, its economic benefits have yet to materialize. Trade remains sluggish with both the EU and the rest of the world, while key industries are struggling with increased costs, bureaucracy, and labor shortages. Supporters of Brexit argue that these are temporary adjustments and that opportunities such as CPTPP and a potential US trade deal could deliver future gains. Recent IMF data also suggests that the UK is on track to be the fastest-growing major European economy in 2025.

Even so, the UK’s growth remains below its historical average, and trade prospects remain highly uncertain. Five years after leaving the EU, Brexit has yet to deliver the economic advantages its proponents promised, and for many sectors, its challenges remain an ongoing reality.

Author: Silvia Ungaro, Senior Advisor, Atradius N.V.
Private equity industry contracts for the first time in decades

The private equity industry experienced a rare decline in 2024, marking the first contraction in decades. Assets under management (AUM) fell by 2% as investors scaled back commitments amid economic uncertainty and tighter financial conditions.

The pullback reflects a broader trend of cautious investment behavior, driven by rising interest rates, concerns over global economic stability, and reduced liquidity in capital markets. For years, private equity has seen continuous expansion, fueled by strong fundraising and high levels of deal activity. However, the slowdown suggests a shift in investor sentiment, with some limited partners choosing to rebalance their portfolios away from alternative assets.

Industry analysts point to multiple factors influencing the contraction. Higher borrowing costs have made leveraged buyouts less attractive, while valuation adjustments across portfolios have also weighed on overall AUM. Additionally, institutional investors, such as pension funds and endowments, have faced liquidity constraints, leading to reduced capital allocations for private equity funds.

Despite the decline, private equity firms continue to seek investment opportunities, with some focusing on distressed assets or alternative deal structures. Market participants anticipate a potential rebound if macroeconomic conditions stabilize and fundraising efforts regain momentum. However, in the short term, the industry may face continued headwinds as investors adopt a more cautious approach to capital deployment.

The contraction signals a potential inflection point for private equity, challenging firms to adapt to a changing financial landscape while maintaining long-term value creation strategies.

Source: comp.

Bolero Office Point 1 achieves BREEAM excellent certification

Bolero Office Point 1, an office building in Warsaw with 11,300 m² of leasable space, has been awarded the BREEAM In-Use certification at the Excellent level under the latest International Commercial V6 evaluation standard. The building is part of the Real Management S.A. portfolio.

BREEAM In-Use is an assessment system for existing buildings that evaluates their environmental impact, resource management, and user comfort. The most recent Version 6 focuses on climate adaptability, sustainability, and occupant well-being. The certification confirms that Bolero Office Point 1 meets high standards in these areas.

The building received top scores in the Resilience category, reflecting its ability to withstand environmental factors. It also performed well in the Resources and Health & Wellbeing categories. Auditors noted features such as high levels of natural daylight (≥ 95% of interior spaces), designated relaxation areas, and comprehensive recycling and waste management infrastructure, including three dedicated storage areas for reusable materials.

Bolero Office Point 1 also achieved the highest possible score for access to public transportation. A public transport stop is located 500 meters from the building, with frequent service during peak hours. Additional assessments confirmed the building’s ability to adapt to future operational needs and evaluated risks related to flooding and natural hazards, with findings indicating minimal risk.

“Ensuring user comfort, safety, and sustainable building management is a key aspect of our asset strategy. Upgrading from Very Good to Excellent in the BREEAM In-Use certification process highlights our commitment to high-quality building standards,” said Eliza Wielgus, Senior Asset Manager at Real Management S.A.

Colliers served as the assessor for the certification process. “Achieving BREEAM In-Use certification demonstrates the owner’s commitment to maintaining sustainability in an existing building. We are pleased to have contributed to this achievement,” said Edyta Chromiec, Associate Director, ESG Strategic Advisory, Colliers Poland.

Bolero Office Point 1 is a seven-storey Class B+ office building located at 4 Równoległa Street in Warsaw. The fully leased building includes 187 parking spaces and a ground-floor restaurant. Its proximity to the Warsaw Commuter Railway (WKD) station ensures convenient access to the city center, while its location near the airport and major transport routes benefits businesses with frequent travel needs.

Germany: Gender pay gap widens with age, particularly for academics

The gender pay gap in Germany, currently at 16% based on gross hourly wages, varies significantly depending on age and education level, according to a new study by the German Institute for Economic Research (DIW Berlin). The gap increases notably with age and is particularly pronounced among those starting a family. This trend is seen across all educational backgrounds but is most evident among university graduates, where the pay gap reaches up to 28% for those aged 45 and older. Among individuals with A levels and/or vocational training, as well as those without these qualifications, the gap is around 20%.

One factor contributing to this disparity is the correlation between higher education and increasing hourly wages with longer working hours. However, women, particularly in western Germany, are more likely to work part-time than men. The smallest gender pay gap occurs between the ages of 25 and 29, at approximately 10% across all educational groups.

Katharina Wrohlich and Fiona Herrmann analyzed data from the Socio-Economic Panel (SOEP) from 2013 to 2022 for this study. Wrohlich, head of the Gender Economics research group at DIW Berlin, emphasized that reducing the gender pay gap requires policies that promote a more equal distribution of paid work and caregiving responsibilities. She highlighted the need for tax reforms, particularly concerning the income tax splitting system for married couples and mini-job regulations, which have historically encouraged women to take on part-time or marginal employment, limiting career progression and earnings potential.

A second study examined the role of gender-specific differences in basic skills, such as reading and arithmetic, in relation to the gender pay gap. Using data from the Programme for the International Assessment of Adult Competencies (PIAAC), researchers found that while women in Germany generally have stronger reading skills, men consistently outperform them in numeracy across all age groups. However, these skill differences account for only a small portion of the wage gap.

Lavinia Kinne from DIW Berlin’s Gender Economics research group, who conducted the study alongside Jonas Jessen from the Wissenschaftszentrum Berlin für Sozialforschung (WZB) and Frauke Witthöft from the ifo Institute in Munich, emphasized the importance of addressing gender stereotypes early in education. Encouraging girls to pursue STEM subjects and boys to engage more in language studies could help create a more balanced distribution of skills and career opportunities in the long term

Source: DIW Berlin

Decline in Slovak completed and started dwellings in 2024 marks multi-year low

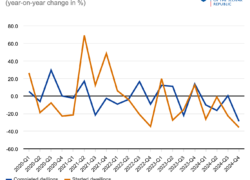
The number of completed dwellings in Slovakia in 2024 fell to its lowest level in six years, while the number of housing starts reached an 11-year low. Three out of eight regions recorded completion figures below the pre-pandemic average, and seven regions saw a significant decline in construction starts.

Both completions and new construction slowed notably in the fourth quarter, contributing to the overall low annual figures. The total number of completed dwellings dropped below 18,000, while new housing starts fell to approximately 15,000. The most significant decline was observed in Bratislavský kraj, where dwelling completions decreased by 24%, and new construction started declined by 56% compared to the five-year pre-pandemic average.

In the last quarter of 2024, 4,900 dwellings were completed in Slovakia, marking a 29% year-on-year decrease and a 19% drop compared to the pre-pandemic five-year average. This was the lowest fourth-quarter figure in 13 years. Family houses continued to dominate approvals, accounting for 67% of all completed dwellings.

Regional trends varied significantly. Košický kraj recorded a 50% increase in completed dwellings year-on-year, while Trenčiansky kraj saw a modest 3% rise. However, six regions experienced declines, with five seeing double-digit drops, including Bratislavský kraj, historically the leader in new dwelling construction.

Over the longer term, compared to pre-pandemic averages, Košický kraj recorded higher completion levels, with Prešovský and Žilinský kraj also showing double-digit growth. In contrast, all four regions in western Slovakia, along with Banskobystrický kraj, recorded lower completion levels.

Housing Starts in Q4 2024

In the final quarter of 2024, nearly 3,600 new dwellings were started, representing a one-third decrease year-on-year and a level well below the pre-pandemic average. Family houses accounted for 57% of all new construction.

Housing starts declined year-on-year in seven of Slovakia’s eight regions, with the steepest drops—over 50%—recorded in Bratislavský and Prešovský kraj. Compared to pre-pandemic averages, only Žilinský kraj saw an increase, with a rise of more than 17%. All other regions recorded significant declines, with Bratislavský kraj experiencing the most substantial decrease at 70%.

Source: Statistical Office of the SR

Polish industrial and logistics market 2024: Stability with signs of growth

Poland’s industrial and logistics real estate sector maintained stability in 2024, remaining a key segment of the commercial property market both nationally and across Europe. Investment transactions in warehouse assets totaled EUR 1.26 billion, while take-up reached 5.8 million sqm, marking a 4% year-on-year increase. Although developer activity declined by 30%, new supply returned to pre-pandemic levels at 2.6 million sqm, with 1.8 million sqm still under construction. Vacancy rates remained stable at 7.5%, and rental levels showed little change from the previous year.

Investment Market Sees Recovery and Stabilization

The warehouse segment accounted for EUR 1.26 billion of total investment in 2024, a 27% increase year-on-year, representing 25% of all transactions. While retail and office assets saw exceptional growth, the industrial and logistics sector continued to attract stable capital inflows. Portfolio transactions played a significant role, comprising 58% of the total transaction volume. Notable deals included the acquisition of five 7R parks by Czech fund Investika and the purchase of three Diamond Business Parks by US investor Greykite.

Grzegorz Chmielak, Head of Capital Markets & Valuations at AXI IMMO, noted that investors remained focused on key warehouse hubs such as Warsaw, Upper Silesia, and Poznań, where market fundamentals remain strong. He highlighted that portfolio transactions are often more cost-effective than new developments due to high construction and financing costs. By the end of 2024, prime big-box yields had stabilized at 6.5%, enhancing investment appeal.

Leasing Activity Driven by Renewals

Total leasing activity in 2024 reached 5.8 million sqm, up 4% year-on-year, with lease renewals comprising 48% of all transactions. This trend reflects businesses’ focus on operational stability and cost management. The most active regions were Mazowieckie (1.37 million sqm), Łódzkie (1 million sqm), and Dolnośląskie (891,000 sqm). Net take-up, which includes new leases and expansions, stood at 3.4 million sqm, maintaining last year’s level.

Retail tenants surpassed logistics firms as the largest demand driver, with major leases including a 103,800 sqm contract in Bydgoszcz Białe Błota LC, a 98,700 sqm renewal and expansion for a logistics operator at Prime Logistics Wrocław Pietrzykowice, and a new 91,000 sqm lease at Panattoni Wrocław Logistics South Hub.

Anna Głowacz, Head of Industrial at AXI IMMO, emphasized that companies are choosing to remain in existing locations to avoid relocation costs and maintain stability. She also highlighted a growing interest in environmentally certified buildings, reflecting the increasing implementation of ESG strategies.

Supply Returns to Pre-Pandemic Levels

New warehouse supply in 2024 totaled 2.6 million sqm, a 30% decline year-on-year but in line with pre-pandemic averages, signaling a shift towards more sustainable growth. The highest volume of new space was delivered in Dolnośląskie (675,000 sqm), followed by Mazowieckie (468,000 sqm) and Łódzkie (343,000 sqm). Major completions included P3 Wrocław (172,800 sqm) and two CTP projects: CTPark Gdańsk Port (119,400 sqm) and CTPark Warsaw West (110,400 sqm).

At year-end, 1.8 million sqm remained under construction, a 38% drop from the previous year, with the highest concentration in Śląskie, Dolnośląskie, and Łódzkie. Speculative developments accounted for 47% of all space under construction, slightly lower than in past years.

Vacancy Rates Remain Stable

The overall vacancy rate stood at 7.5% by the end of 2024, reflecting a marginal 0.1 percentage point increase year-on-year but a 0.5 percentage point drop quarter-on-quarter. The highest vacancy rates were recorded in Lubuskie (19%) and Świętokrzyskie (16.9%), while emerging markets like Podlaskie and Warmińsko-Mazurskie remained nearly fully occupied. Among major markets, Łódzkie (9.7%), Dolnośląskie (9.6%), and Wielkopolskie (7%) had the highest availability.

Rental Rates See Minor Changes

Base rents in 2024 remained stable, with slight increases of up to 5% in some regions. Average rents for big-box facilities ranged from EUR 3.6 to 4.3/sqm/month in older buildings and from EUR 4.0 to 5.5/sqm/month in new developments. The lowest rents were in Łódzkie, Śląskie, and Wielkopolskie (EUR 3.6–3.8/sqm/month), while Warsaw commanded the highest rates, reaching up to EUR 7.25/sqm/month for new projects.

2025 Outlook: Cautious Optimism

Looking ahead, Poland’s industrial and logistics sector is expected to remain one of Europe’s strongest, supported by projected economic growth. Businesses will prioritize process optimization and ESG strategy implementation. Rising costs and labor shortages are likely to encourage increased lease renegotiations. Developers will focus on markets with limited availability, prioritizing projects with a high level of pre-leasing. Stabilization of yields in the investment market is also expected to stimulate further investor activity, including acquisitions of ready-built assets.

Source: AXI IMMO

BF.Quartalsbarometer Q1 2025: Real Estate Lending Sees a Slight Decline

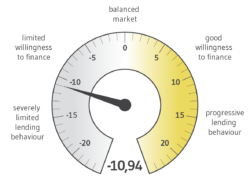
The sentiment among commercial real estate lenders declined slightly at the beginning of the year. The BF.Quartalsbarometer fell from -9.89 points to -10.94 points in Q1 2025, marking a drop of 1.05 points and breaking a five-quarter upward trend. Previously, the index had reached its lowest point in Q3 2023 at -20.22, while its highest score of +8.11 was recorded in Q1 2015.

Fabio Carrozza, Managing Director of BF.real estate finance GmbH, noted that the decline should not be overstated. While lenders remain cautious, there is continued openness toward financing volumes of up to 20 million euros, with a preference for inventory financing over property development financing. He pointed out that the moderately positive trend observed since the ExpoReal trade fair has continued into early 2025, despite the index still being in negative territory at -10.94 points.

Professor Dr. Steffen Sebastian of the International Real Estate Business School (IREBS) at the University of Regensburg attributed the decline in sentiment to economic uncertainty in Germany, the challenges of forming a new government, and geopolitical risks stemming from U.S. foreign policy. Additionally, concerns over inflation and potential interest rate hikes continue to affect lender confidence.

A key factor influencing the index score is the assessment of financing terms. The proportion of respondents expecting tighter financing conditions increased to 45%, a rise of 6.1 percentage points. At the same time, sentiment regarding new lending became more cautious, with only 32.5% of respondents anticipating stable or growing lending volumes, a decline of 6.4 percentage points. Meanwhile, 55% of respondents reported stagnation in new lending, an increase of 13.3 percentage points.

The composition of lending volumes has also shifted toward smaller transactions. More than half (51.3%) of survey participants reported average lending volumes below 10 million euros, up by 11.3 percentage points. In contrast, the share of respondents reporting average lending volumes between 10 and 50 million euros fell to 28.2%, a decline of 14.7 percentage points.

Margins have softened slightly from the borrower’s perspective. In inventory financing, margins decreased from 239.5 basis points in Q4 2024 to 223.7 basis points, a decline of 15.8 basis points. Development financing margins also saw a slight reduction, dropping by 6 basis points from 337 to 331 basis points. Carrozza highlighted that borrowers who have remained active despite the prolonged real estate downturn tend to be financially stable and are benefiting from improved loan conditions.

HIH Invest and Ampega Partner on fund of funds and master fund solutions

HIH Invest Real Estate and Ampega Investment have formed a strategic partnership to provide institutional investors with fund of funds and master fund solutions. The collaboration aims to streamline investment management by enabling investors to pool liquid and illiquid assets, including bonds, equities, real estate, and private equity, into a single vehicle. This approach is intended to enhance portfolio efficiency, reduce administrative costs, and improve reporting quality.

Under the partnership, Ampega will manage liquid assets and fixed-income products, while HIH Invest will oversee direct and indirect real estate investments as well as infrastructure assets. Both companies bring extensive experience in institutional investment management and offer a digitised reporting system that provides investors with a transparent view of their portfolios. The services are modular, allowing investors to tailor solutions to their specific needs.

Alexander Eggert, Managing Director of HIH Invest, stated that the collaboration strengthens their multi-asset strategy offering and allows them to provide tailored investment solutions. The partnership reflects a commitment to flexible investment strategies designed to align with evolving market conditions and investor requirements.

Italy: Employment and unemployment trends in January 2025

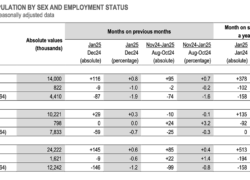
The employment market in January 2025 experienced positive growth, with the number of employed individuals increasing while unemployment and inactivity rates declined. The employment rate rose to 62.8%, reflecting a 0.4 percentage point increase compared to the previous month.

Employment gains were observed across both men and women, as well as all age groups, except for individuals aged 35-49, where a decline was recorded. Meanwhile, the number of unemployed persons dropped by 0.6%, equivalent to a reduction of 9,000 individuals. This decline was particularly evident among men and across most age groups, although there was an increase in unemployment for those aged 25-34. The unemployment rate fell to 6.3%, marking a 0.1 percentage point decrease, while the youth unemployment rate also declined to 18.7%, down by 0.3 percentage points. The number of unemployed women remained stable during this period.

Inactivity levels also saw a notable decline, with the number of inactive individuals falling by 1.2%, amounting to a reduction of 146,000 people. This decline was observed across men, women, and individuals aged 15-34 and 50 and over, whereas those aged 35-49 saw an increase in inactivity. Consequently, the inactivity rate dropped to 32.9%, a decrease of 0.4 percentage points.

Looking at the broader quarterly trends from November 2024 to January 2025, employment rose by 0.4%, adding 85,000 new jobs compared to the previous quarter of August to October 2024. However, the number of unemployed persons increased by 1.4%, equating to 22,000 additional unemployed individuals. At the same time, inactivity among people aged 15-64 declined by 0.8%, reflecting a reduction of 99,000 individuals.

On an annual basis, employment showed strong growth, with the number of employed individuals rising by 2.2%, amounting to an increase of 513,000 people. This increase was recorded across both sexes and among individuals aged 25-34 and 50 and over, while employment decreased for other age groups. The employment rate improved by 1.0 percentage point over the year.

The yearly increase in employment was accompanied by a significant reduction in the number of unemployed individuals, which fell by 10.7%, equivalent to 194,000 fewer unemployed persons. Additionally, the number of inactive individuals aged 15-64 dropped by 1.3%, representing a decrease of 158,000 people. These figures indicate a continued strengthening of the labor market, with positive trends in employment and reduced inactivity levels contributing to overall economic stability.

Source: Istat

Munich’s office market sees strong growth in 2024

Munich has once again solidified its position as Germany’s leading office market, recording a substantial increase in take-up in 2024. The city’s office market outperformed Berlin and Hamburg, reaching a total take-up of 606,000 square meters. This marks a significant 30% increase compared to 2023, despite still falling 17% short of the long-term average. The resurgence in demand was primarily fueled by large-scale lettings exceeding 10,000 square meters, which saw a remarkable tenfold rise from the previous year.

Throughout 2024, the Munich office market exhibited consistent growth across all four quarters, with the final quarter leading as the strongest. The last three months of the year contributed 162,000 square meters to the total take-up, reinforcing a positive year-end momentum. Key transactions in this period included two of the four largest lettings of the year. The Technical University of Munich (TUM) secured 19,300 square meters for an innovation campus at the airport site, while Capgemini committed to 13,600 square meters on Prinzregentenstrasse. Additionally, the Bavarian State Parliament took up 19,200 square meters, further boosting the market’s overall performance.

The robust demand for premium office space has been reflected in rising rental prices. Prime rents increased by 9% over the past year, reaching €53.50 per square meter, while the average rent now stands at €25.00 per square meter. This trend underscores the growing appeal of high-quality office locations and premium developments in Munich’s competitive real estate market.

Despite the strong take-up performance, vacancy rates have also seen an uptick. The overall vacancy rate rose by 1.1 percentage points compared to 2023, bringing the total to 7.4% or 1.69 million square meters. Notably, nearly half of this vacancy volume is accounted for by modern office spaces, totaling 830,000 square meters. However, the city center remains an exception, with an exceptionally low vacancy rate of just 2.9%. In this prime location, only 98,000 square meters of office space is currently unoccupied, of which merely 5,500 square meters belong to newly constructed properties.

Looking at sector-specific activity, the administration offices of industrial companies emerged as the leading driver of take-up, accounting for 21% of the total volume. ICT firms followed closely behind with a 17% share, while public administration and consultancies each contributed around 15%. This distribution highlights the continued demand for office spaces from key economic sectors, reinforcing Munich’s status as a diverse and resilient office market.

Among the most notable leasing deals of 2024, the Bayerische Versorgungskammer secured the largest contract, leasing 25,200 square meters in the second quarter. Other significant agreements included TUM’s airport campus deal and the Bavarian State Parliament’s lease, both mentioned earlier. Meanwhile, Isar Aerospace and BA die Bayerische Allgemeine Versicherung each signed contracts exceeding 11,000 square meters.

While the demand side has demonstrated strength, supply dynamics suggest further shifts in the market. The vacancy rate is expected to continue rising in 2025, particularly in subcenters and peripheral locations, where supply has outpaced demand. Conversely, in central locations, the availability of premium office space is expected to dwindle, further tightening conditions for occupiers seeking prime properties.

The macroeconomic outlook for 2025 remains a crucial factor in determining the trajectory of the Munich office market. While economic recovery may gain momentum, external factors such as political developments in the U.S. and Germany could introduce volatility. Nevertheless, if the newly elected German government provides stability and economic support, this could lead to increased office take-up in the second half of the year.

Going forward, the Munich office market is poised for further rental growth, particularly in prime locations. With demand for large-scale office spaces rising—especially from international firms—prime rents are expected to see further increases in 2025. Additionally, as the availability of newly constructed office space declines, competition for premium properties is likely to intensify.

The evolving landscape presents both challenges and opportunities for investors, landlords, and occupiers. Those with high-quality, centrally located office spaces stand to benefit from sustained demand, while areas with oversupply may need to adapt through repositioning strategies. With Munich remaining a top choice for businesses seeking a dynamic and stable office market, the city’s commercial real estate sector is set to remain a focal point of investment and development in the coming year.

Source: BNP Paribas Real Estate GmbH

front page info
LATEST NEWS