Decarbonizing existing buildings: Challenges and progress in the real estate industry

The real estate industry faces increasing pressure to make existing buildings emission-free by 2050, requiring annual renovations of up to 1.2 million properties. Currently, only about 280,000 buildings are renovated each year, raising concerns about meeting climate targets.

At an online press conference organized by Rueckerconsult, industry experts discussed the challenges of aligning ambitious decarbonization goals with economic realities. A survey by aedifion and Rueckerconsult, involving project developers, portfolio holders, and financiers, provided insight into current industry trends. More than half of respondents do not have a decarbonization strategy for their real estate portfolios, and 60 percent lack a budget for such initiatives. Among those with a strategy, a quarter are unaware of their properties’ carbon emissions.

Despite these challenges, regulatory pressure and market shifts are prompting companies to act. According to the survey, 73 percent of respondents worry that failing to implement decarbonization measures could reduce property values. Concerns also include the risk of stranded assets (29 percent) and lower rental income (17 percent), while 23 percent believe inaction will have no impact.

Alexander Roth, ESG & Operations Director at Savills Investment Management, noted that buildings with high carbon footprints are becoming harder to sell. Some companies set decarbonization targets aligned with the Paris climate agreement, but economic conditions complicate large-scale investments.

One key challenge in improving energy efficiency is understanding consumption data. Experts agree that measuring energy use is the first step in assessing necessary improvements. Iris Hagdorn, Head of Sustainability at HIH Invest, emphasized the need for long-term sustainability strategies rather than short-term ESG initiatives. She stressed that detailed energy data collection is essential for identifying areas where improvements are possible.

Energy sources and building systems play a more significant role in reducing carbon emissions than insulation upgrades. While better insulation can offer some efficiency gains, Roth explained that measures such as switching energy sources or optimizing heating and cooling systems have a greater impact.

Among the most common measures implemented or planned for reducing CO2 emissions are heating system upgrades, operational efficiency improvements, and switching to green electricity. Heat pumps, although less frequently mentioned, are gaining attention as a transitional technology. Johannes Fütterer, Managing Director of aedifion, highlighted their potential to integrate with flexible energy pricing, allowing buildings to optimize energy costs by adjusting consumption patterns.

Artificial intelligence (AI) is another emerging tool, though its application in real estate remains limited. Survey results show that 47 percent of respondents are open to using AI for decarbonization, while a third remain skeptical. Fütterer explained that AI can help analyze building operation data to optimize energy use. However, industry-wide adoption is slow due to the lack of interconnected systems capable of exchanging data.

Roth pointed out that digitalization is crucial for AI implementation. Many buildings lack smart control systems that allow for room-specific heating and cooling, requiring retrofits before AI-driven solutions can be effective.

The discussion concluded that while the real estate industry recognizes the importance of decarbonization, economic challenges and technical limitations slow progress. Improving data collection, optimizing energy sources, and integrating smart technologies will be key to meeting long-term climate goals.

Photos: Iris Hagdorn-HIH Invest, Dr.-Ing. Johannes Fütterer, Alexander Roth-Savills IM and Prof. Dr. Henric Hahr-Real Blue
Andrej Zverzhanovski Appointed CFO of Crestyl in the Czech Republic

Crestyl, a property development and investment group, has appointed Andrej Zverzhanovski as its Chief Financial Officer for the Czech Republic. In this role, he will oversee the financial management of the company’s Czech operations. The position was previously handled by Jozef Ďurík, CFO of the Crestyl Group, who will now focus on the company’s international financial strategy.

Zverzhanovski has over 18 years of experience in investments, transactions, and corporate development across Europe and Asia. His responsibilities at Crestyl will include financial planning, capital allocation, risk management, and compliance.

Before joining Crestyl, he served as Chief Investment Officer at SOLEK, leading M&A activities across seven European countries. He was also CFO and COO at foodtech startup Manifesto Market, where he contributed to its expansion into new markets. His experience includes senior roles at Axes Capital and Swisslake Capital AG, focusing on investor relations and transactions in real estate, energy, and healthcare.

A graduate of the University of Strasbourg with a degree in economics, Zverzhanovski speaks five languages, including Czech, English, French, and German, in addition to his native Serbian. Outside of work, he is an active sports enthusiast, with interests in tennis, squash, and skiing. He also enjoys cultural events, frequently visiting Prague’s theatres.

Sarantis Polska expands warehouse and office space at MLP Pruszków II

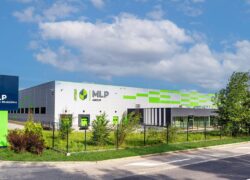
Sarantis Polska, a manufacturer and distributor of cosmetics and household goods, is expanding its operations within the MLP Pruszków II logistics complex near Warsaw. The company will move to a newly built facility, increasing its leased space by 35% to over 24,000 square meters. This expansion continues a 25-year collaboration with MLP Group, during which Sarantis Polska’s leased space has grown fivefold.

Under the new lease agreement, Sarantis Polska will transition to a built-to-suit (BTS) facility while vacating two smaller sites totaling 17,600 square meters. The relocation process, managed by consulting firm Graphene Partners, aims to optimize logistics and accommodate the company’s future growth. The new facility will be available in November 2025, with full operations expected by July 2026.

The warehouse will cover approximately 22,700 square meters, including a 5,200-square-meter Very Narrow Aisle (VNA) zone for high-density storage. Another 2,000 square meters will be dedicated to packaging operations, and 1,400 square meters will serve as office space. Designed for efficiency, the facility will feature a 12-meter clear height and will meet high environmental standards, undergoing BREEAM certification at the Excellent level.

Tomasz Pietrzak, Leasing Director Poland at MLP Group, emphasized the long-term collaboration with Sarantis Polska and its commitment to sustainable, modern warehouse solutions. He noted that the new facility aligns with the company’s strategy of providing flexible, environmentally friendly logistics spaces that support tenant growth.

Graphene Partners played a key role in the transition, working with Sarantis Polska to analyze its distribution network and identify future logistics needs. Karol Gułaś, Director at Graphene Partners, highlighted the strategic planning involved in selecting the new location, negotiating lease terms, and ensuring the facility meets operational requirements.

Sarantis Polska, part of the Sarantis Group founded in 1964 in Athens, has expanded significantly in Central and Eastern Europe. With operations in 13 countries and exports to over 50 markets, the company owns well-known brands in Poland such as Jan Niezbędny, Kolastyna, Luksja, and STR8.

Romania’s hotel market reaches record growth with highest tourist numbers in 30 years

Romania’s hotel market has reached a new peak, recording over 25 million overnight stays in 2024, the highest level in more than three decades, according to Colliers’ annual report. This growth has been driven by an increase in foreign tourists and strong demand for modern hotels. The country’s international visibility is improving, and its expected accession to the Schengen area in 2025 could further boost tourism. Investments in new hotels and growing interest from international brands continue to strengthen Romania’s position as a market with long-term potential.

Tourism in Romania has outpaced pre-pandemic levels, with overnight stays increasing by 4% compared to 2019, surpassing the EU average growth of less than 2%. While domestic tourism and the leisure sector have been the primary drivers, the number of foreign visitors, despite notable growth in 2024, remains below pre-pandemic peaks.

According to Raluca Buciuc, Director and Partner at Colliers, Romania is gradually closing the gap with more developed tourism markets. The country recorded a 6% increase in overnight stays compared to the previous year, with foreign tourism growing by 13% and domestic tourism by 5%. However, business travel has yet to fully recover, with overnight stays by foreign business travelers still nearly 3% below 2018-2019 levels. Air traffic increased by 5%, and outbound travel spending reached a record high, showing that more Romanians are opting to travel abroad.

Romania has experienced a notable rise in tourism spending over the last decade. Eurostat data indicates that in 2023, business travelers in Romania spent an average of €333 per trip, one of the lowest figures in the EU. This remains well below Hungary (€562) and Poland (€488), yet Romania has recorded the third fastest growth rate in the EU for business travel spending, increasing by 134% between 2013 and 2023, compared to the EU average of 31%.

Colliers’ analysis of 4- and 5-star hotels in Bucharest affiliated with international brands shows that the average daily rate (ADR) surpassed 2019 levels, exceeding €140 per night—a 21% increase in foreign currency and 27% in local currency. Compared to the previous year, ADR grew by 8%, placing Bucharest ahead of capitals such as Warsaw, Budapest, and Vienna in terms of growth dynamics. Revenue per available room (RevPAR) increased by 10% compared to pre-pandemic levels, further indicating the market’s expansion. However, business tourism has not fully recovered, with an average occupancy rate below 70% in the first 10 months of 2024, still short of the 78% recorded in 2018-2019.

According to Buciuc, Romania’s tourism growth, supported by leisure travel and a gradual recovery in business travel, combined with a limited supply of hotels, is making the country increasingly attractive to investors. In 2024, over 400 new rooms were added to the market in international hotels, including Romania’s first 5-star Swissotel in Poiana Brașov. By 2026, approximately 15 new hotels are expected to open, adding more than 2,000 rooms, with brands such as Marriott, Hilton, and Accor expanding their presence. New entrants, including Ascott Hotels (The Crest Collection) and Corinthia, are also set to enter the Bucharest market.

While Romania’s hotel market is still developing compared to other regional markets, its potential for growth continues to attract investors and international operators. The long-term trajectory of the sector will depend on economic stability and continued investment. Across Europe, tourism growth has varied, with southern countries like Italy, Spain, and Greece seeing the highest increases in hotel occupancy and ADR, while Central and Eastern Europe maintains steady expansion. According to Colliers, the luxury and premium hotel segment continues to grow, while mass-market accommodations remain stable.

CA Immo finalises sale of Bitwy Warszawskiej office building in Warsaw

CA Immo has completed the sale of the Bitwy Warszawskiej office building in Warsaw, marking another strategic move in its portfolio management. The transaction aligns with the company’s ongoing efforts to streamline its real estate holdings and optimize asset value in key European markets.

Located in the Ochota district of Warsaw, the Bitwy Warszawskiej office building has been a notable part of the city’s commercial real estate landscape. The property has attracted tenants from various industries, benefiting from its well-connected location and modern office space offerings. The sale reflects continued investor interest in Warsaw’s office market, despite evolving dynamics in the sector.

CA Immo has been actively adjusting its investment strategy, focusing on prime office properties in core markets. The divestment of Bitwy Warszawskiej aligns with this approach, allowing the company to reallocate capital towards high-value assets and new development opportunities. The buyer has not yet been disclosed, but the transaction underscores the resilience of Warsaw’s office sector and its appeal to institutional investors.

With this sale, CA Immo continues to refine its European office portfolio, reinforcing its focus on high-quality, sustainable, and strategically located assets. The company remains committed to strengthening its presence in key markets while adapting to changing market conditions.

Slovakia’s housing market faces decline as apartment completions hit six-year low

Slovakia’s real estate sector experienced a significant downturn in 2024, with the number of completed apartments reaching its lowest level in six years. The decline reflects broader challenges in the construction industry, as economic conditions and regulatory hurdles continued to slow development. According to the latest data from the Statistical Office, construction activity fell to an 11-year low, raising concerns about the future of the country’s housing market.

The slowdown was particularly evident in the final quarter of 2024. Between October and December, only 4,900 apartments were completed, marking a year-on-year decrease of nearly 29 percent. This drop represents the weakest quarterly performance in the past 13 years. Within this total, single-family houses accounted for 67 percent of all newly approved residential units, highlighting a shift in housing demand toward private homes rather than large-scale apartment developments.

Regional disparities have also widened, with the capital region performing significantly better than other parts of the country. Bratislava continued to see steady construction activity, reflecting strong demand and the ongoing appeal of urban housing. In contrast, many regional areas struggled with declining investment and fewer completed projects. The Košice region was an exception, recording a 50 percent increase in apartment completions in the last quarter of the year compared to the same period in 2023. This localized growth stands out as a rare positive trend in an otherwise subdued market.

The overall decline in residential construction is attributed to several factors. Rising material costs, high interest rates, and labor shortages have all contributed to delays and cancellations of planned projects. Additionally, economic uncertainty and regulatory changes have made it more difficult for developers to secure financing and navigate approval processes. These challenges have resulted in fewer new housing projects breaking ground, further tightening the supply of available homes.

Market analysts warn that unless there is a shift in policy or economic conditions, Slovakia could face a prolonged period of stagnation in the residential sector. With demand for housing still present, particularly in urban centers, the lack of new supply may lead to affordability issues and increased pressure on rental markets. Policymakers and industry stakeholders will need to address these barriers to encourage new investment and prevent further declines in construction activity.

As Slovakia enters 2025, the outlook for the real estate sector remains uncertain. While the Košice region’s performance offers some optimism, the broader market continues to grapple with economic and structural challenges. The coming months will be crucial in determining whether the sector can stabilize or if further contraction is on the horizon.

Photo: Zwirn, Bratislava – YIT

Romania’s office market sees over 1 million sqm leased in five years

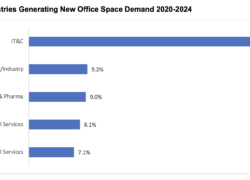
Over the past five years, IT companies, manufacturing and industrial firms, and the medical and pharmaceutical sectors have been the most active in Romania’s office leasing market. According to Cushman & Wakefield Echinox, these industries accounted for more than half of the new office space demand across major cities.

Between 2020 and 2024, net take-up in Bucharest, Cluj-Napoca, Timișoara, Iași, and Brașov totaled approximately 1.06 million square meters. This figure is equivalent to the total office stock in the four regional cities combined or about 30% of Bucharest’s total office supply. Given an average office space allocation of 8-10 square meters per employee, the newly leased spaces could accommodate at least 100,000 employees.

The IT sector remained the main driver of demand, accounting for over 35% of new leases, or approximately 375,730 square meters. With a nearly 7% contribution to Romania’s GDP in 2024, the sector has remained a key force in the office market. Manufacturing and industrial companies followed, leasing about 98,000 square meters, representing 9.2% of total volume. The pharmaceutical and medical sectors secured 95,200 square meters, making up 9% of total demand. Professional services firms leased nearly 86,000 square meters, while the financial sector, including banks and insurance companies, contracted over 75,000 square meters.

Total office space transactions, including renegotiations, exceeded 2 million square meters over the period, with IT firms accounting for more than 40% of the total volume.

The current stock of modern office space in Bucharest and the major regional university cities stands at approximately 4.51 million square meters. Another 390,000 square meters are under development and scheduled for completion in the next five years. The overall vacancy rate across these five cities is 13.8%, with Cluj-Napoca recording the lowest at 6.6% and Iași the highest at 19.4%. In Bucharest, the vacancy rate declined to 14.2% by the end of 2024.

Prime office rents in Bucharest reached €21 per square meter per month by the end of last year, marking a 10.5% increase since 2020. In regional cities, rental growth reached up to 13%, with maximum rates of €17 per square meter per month.

Mădălina Cojocaru, Partner in the Office Agency at Cushman & Wakefield Echinox, noted that IT companies continue to shape the office leasing market, despite some adjustments in space requirements. She highlighted the sector’s steady expansion and its role in driving real estate demand. The limited availability of office spaces in central Bucharest, coupled with sustained demand, points to the need for new developments in well-connected areas. She cited Calea Buzești as an emerging business hub, benefiting from ongoing urban redevelopment.

Source: Cushman & Wakefield Echinox Research

MOMENI and Art-Invest Real Estate are investing in innovation together

MOMENI Ventures, a subsidiary of the MOMENI Group, and BitStone Capital, affiliated with Art-Invest Real Estate, have partnered to establish REALYZE Ventures, a European investment platform focused on sustainable innovations in real estate, construction, and skilled trades. The initiative aims to support start-ups that contribute to the transformation of these industries through technological advancements and sustainability-driven solutions.

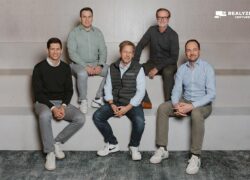
The REALYZE partner group, including Kai Panitzki, David Nadge, Stefan Läufer, Manfred Heid, and Tim Fischer, brings together a range of expertise to identify and develop high-potential investment opportunities. The fund seeks to facilitate a net-zero transition in the built environment while generating attractive returns for investors.

REALYZE Ventures is designed to leverage sector-specific knowledge and existing networks within the construction and real estate industries. Investors benefit from access to a broad network of national and international market leaders, as well as insights into emerging innovations that align with sustainability goals. By integrating venture capital with industry expertise, the fund supports both start-ups and investors in achieving long-term growth and transformation.

According to Kai Panitzki and David Nadge, the collaboration builds on a history of successful investments and aims to create synergies that strengthen market impact. The REALYZE Ventures Fund I is positioned to expand its investor network and establish one of the leading European ecosystems for innovation in real estate and construction.

With a structure designed to go beyond traditional investment approaches, REALYZE Ventures not only identifies promising start-ups but also provides strategic support for market entry and product development. The team applies a comprehensive evaluation process to assess the viability of start-ups, ensuring benefits for both the portfolio companies and investors.

Tim Fischer highlighted the fund’s operational approach, emphasizing the value of close cooperation with innovation departments from leading industry players. By leveraging these insights, REALYZE aims to enhance investment effectiveness and market influence.

The management team has extensive experience, having invested in more than 40 start-ups with a total of over €100 million in assets under management. REALYZE Ventures is set to play a key role in shaping the future of sustainable construction and real estate through targeted investment and industry collaboration.

Sonar Development launches nationwide modular timber housing programme in Germany

Sonar Development has announced the launch of a nationwide residential development programme in Germany using modular timber construction. The initiative is backed by a long-term institutional mandate through Institutional Investment Partners and focuses on metropolitan regions across the country.

The programme will begin with a housing project in Hamburg-Barmbek, where a 2,900-square-meter site has been acquired by a well-known local developer. The plan includes a five-storey courtyard building and a six-storey block along the street, both built to KfW Standard 40 for energy efficiency. The development will offer approximately 80 residential units, with sizes ranging from 40 to 100 square meters, and will include a mix of privately financed and subsidised apartments.

Currently in the planning phase, construction on the Hamburg project is expected to start by the end of 2025, with completion scheduled for early 2027. Sonar Development is working with project planner DIEfabrik and timber module manufacturer Timpla to implement the project. As part of the programme’s broader expansion, the company is actively seeking additional sites for modular timber housing in urban areas. Managing Director Steffen Wittwer highlighted the increasing demand for sustainable housing, particularly in cities, and emphasized Sonar’s commitment to addressing this need. Matthias Gerloff, Managing Partner for Fund Management & Investment Solutions, added that the investment strategy is tailored for a German institutional investor.

Modular timber construction relies on prefabricated modules that are assembled on-site, reducing construction time, waste, and energy consumption. As a renewable material, wood captures CO₂ and helps lower emissions, making it a more sustainable alternative to conventional construction methods. The flexibility and scalability of modular timber housing also allow for efficient residential and commercial development.

In addition to new housing projects, Sonar is focused on densifying existing urban structures and converting office buildings into residential use. A project in Berlin’s Blissestrasse and another in Eschborn demonstrate this approach by repurposing existing buildings to conserve resources and minimize land use.

Sonar currently manages a portfolio of 46 residential properties totaling approximately 60,000 square meters. The company plans to expand its holdings and introduce new institutional investment solutions as part of its long-term residential development strategy.

China’s JMEV to begin construction of EV plant in Serbia

China’s electric vehicle manufacturer JMEV is set to begin construction of a new EV production plant in Serbia this summer. The project marks a significant investment in the country’s automotive sector and aligns with Serbia’s efforts to attract foreign investment in green technology and sustainable transportation.

JMEV, a subsidiary of Jiangling Motors Corporation (JMC), specializes in electric vehicles and is expanding its footprint beyond China as demand for EVs continues to grow globally. The new plant in Serbia will serve as a strategic hub for the company’s European operations, facilitating production and distribution across the region.

The decision to build the facility in Serbia follows a trend of Chinese automakers investing in European markets to strengthen supply chains and meet regulatory requirements for electric mobility. The Serbian government has actively supported foreign investments in the automotive industry, offering incentives and infrastructure support to attract manufacturers.

Once operational, the plant is expected to contribute to Serbia’s economic growth by creating jobs and integrating local suppliers into the EV production process. The project also aligns with broader European initiatives to promote cleaner transportation and reduce carbon emissions.

JMEV’s expansion into Serbia reflects the growing role of Chinese automakers in the global EV market. With construction set to begin in the coming months, the new facility is positioned to enhance the company’s presence in Europe and support the region’s transition to electric mobility.

front page info
LATEST NEWS