Singapore’s GIC Backs £700 Million UK Hospital Portfolio in Partnership with PHP

Singaporean institutional investor GIC has agreed to partner with Primary Health Properties (PHP) in a £700 million transaction involving 27 private hospitals in the United Kingdom. The agreement will enable the British healthcare property investor to release approximately £500 million from its existing assets, helping reduce debt following its acquisition of Assura in 2025.

The proposed partnership will be equally owned by GIC and PHP, with the hospitals transferred from PHP’s existing portfolio into a newly established investment vehicle. The properties will be valued at approximately 5% below their December 2025 book value. Completion is expected in November 2026, subject to the finalisation of financing arrangements.

The transaction represents an important step in PHP’s efforts to strengthen its financial position following the Assura acquisition. Proceeds will be used to repay outstanding acquisition financing, including a £266 million term loan. Once completed, the arrangement is expected to reduce the company’s net debt from approximately £3.4 billion to £2.9 billion, while bringing its loan-to-value ratio below 55%.

The hospitals included in the agreement have an average remaining lease duration of 22 years, with rental payments linked to inflation. These characteristics provide investors with visibility over future income and exposure to healthcare facilities that serve an established medical market. However, the performance of the portfolio will continue to depend on the financial stability of hospital operators and the demand for private healthcare services.

PHP will retain half of the investment vehicle and continue overseeing the properties, generating management fees alongside income from its ownership interest. The arrangement also provides scope for additional earnings linked to investment performance. For GIC, the partnership offers an established portfolio of specialist healthcare properties without requiring the investor to establish its own management operations in the UK.

The agreement follows a period of expansion for PHP, particularly its acquisition of Assura, which increased the scale of its healthcare property holdings and associated borrowing. Introducing an institutional partner allows the company to recover capital from existing investments while maintaining exposure to their future performance. The transaction also reduces the amount of debt carried directly by the group.

Following completion, PHP expects its average borrowing cost to be approximately 3.6%, with net debt relative to annual operating earnings falling below ten times. The company also anticipates that more than 80% of its rental income will once again come from government-supported sources, reflecting the change in the composition of its directly held portfolio.

The partnership highlights the continued role of institutional capital in specialist property sectors where long leases and established tenants can support investment strategies extending over several decades. Healthcare real estate offers these characteristics, although property valuations, operating costs and tenant financial performance remain important considerations.

Both partners have indicated that the investment platform could accommodate additional hospital properties in the future. However, no further acquisitions or construction projects have been confirmed, and the immediate priority remains completing the initial transaction.

The agreement is conditional on finalising a secured lending arrangement, with the principal commercial terms already settled and property due diligence completed. If concluded as anticipated in November, the transaction will provide PHP with additional financial flexibility while giving GIC a substantial position in the UK’s private hospital property market.
Tower Investments Seeks New Revenue Sources as Construction Projects Face Delays

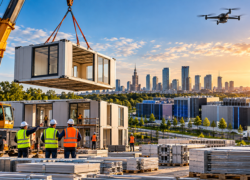
Polish property developer Tower Investments is exploring new business opportunities in modular construction, building materials and technology services as it works to overcome project delays and financial pressures. The company is also holding preliminary discussions with international businesses involved in data centre technology and unmanned aircraft monitoring.

In an update published on 19 October 2026, Tower Investments outlined progress across several initiatives intended to diversify its operations and generate additional revenue. A central element is Broad Tower, a joint venture in which the company holds a 44% interest, established to introduce modular building technology developed by Chinese partner Broad Box to the Polish market.

The initiative has encountered delays in obtaining technical approvals from Poland’s Building Research Institute. Rather than waiting for the broader certification process to conclude, the partners are preparing individual pilot projects using components manufactured for specific buildings, subject to applicable regulatory requirements. Potential locations and technical specifications are being assessed, although construction dates have not been announced.

Tower Investments is also considering whether successful pilot projects could support the establishment of modular building component production in Poland. Such an investment could create opportunities for domestic manufacturing, although any decision will depend on the results of the initial projects and their commercial viability.

Separately, the company is evaluating opportunities involving international technology businesses, including those operating in the data centre sector. Discussions remain preliminary, with no confirmed development projects, acquisitions or binding agreements. The initiative forms part of a broader effort to identify additional sources of income beyond traditional property development.

Another area of activity involves cooperation with Chinese manufacturer SDS Tengzhou Star Smith Metal Products. More than one tonne of sample construction materials has arrived in Poland for testing in concrete mixtures. The results will determine whether the partners proceed with commercial distribution arrangements.

These expansion plans are progressing alongside financial difficulties within the group. Tower Investments acknowledged that certain subsidiaries continue to experience delays in meeting payment obligations. Management is negotiating with creditors over revised repayment schedules and the possible conversion of some liabilities into shares, subject to the necessary approvals.

The Broad Box partnership, first announced in 2025, remains an important part of the company’s diversification strategy. Its pilot programme could provide an opportunity to demonstrate alternative construction methods in Poland, although their commercial effectiveness has yet to be established through completed projects.

For Tower Investments, the immediate challenge is to convert these initiatives into sustainable business activities while resolving outstanding financial obligations. Progress with construction approvals, pilot developments and creditor negotiations will determine how quickly the company can advance its plans and whether its diversification strategy delivers additional revenue.

Czech Republic Gains Ground in Global Tax Rankings, Outperforming Central European Neighbours

The Czech Republic has emerged as the strongest-performing economy in Central Europe’s Visegrád Group in the latest international comparison of national tax systems. The country climbed to seventh place worldwide in 2026, benefiting from changes to investment taxation, although substantial employment costs and less favourable deductions for business expenditure continue to affect its economic competitiveness.

The annual assessment by the US-based Tax Foundation examined tax arrangements across 38 OECD countries, awarding the Czech Republic 79.4 points. This represented an increase of 2.4 points and an improvement from eighth to seventh position compared with 2025. According to an analysis released by Czech economic research organisation CETA on 19 October, the country recorded the largest improvement in its score among all participating economies.

The principal reason for the improvement was the removal of a restriction affecting long-term investors. Since January 2026, individuals selling qualifying shares or ownership interests in companies have no longer been subject to the previous CZK 40 million ceiling on exempt proceeds, provided they meet the applicable ownership-period requirements. The change contributed to the Czech Republic moving from tenth to fourth position in the assessment of personal taxation.

Property-related taxation also contributed positively to the country’s international standing. The Czech Republic ranked fifth in this area, supported by the absence of general wealth taxation and taxes on property acquisitions. While property owners and investors remain responsible for annual property taxes and other applicable obligations, the overall structure compares favourably with several competing European jurisdictions.

However, the international results present only part of the picture for companies operating in the Czech economy. OECD figures for 2025 show that taxes and compulsory contributions accounted for 41.2% of total employment costs for a single employee earning the average wage, compared with an OECD average of 35.1%. Much of the Czech burden arises from mandatory employer and employee contributions rather than personal income tax itself.

This distinction is particularly important for businesses in manufacturing, construction, logistics and other sectors requiring substantial workforces. Employers must consider these additional costs when evaluating recruitment, operational expenditure and potential expansion. Consequently, a favourable position in international tax comparisons does not necessarily translate into lower overall business costs.

The Czech Republic placed ninth in the corporate taxation category, although its treatment of investment expenditure remains a relative weakness. It ranked 24th for depreciation arrangements, reflecting the consequences of earlier changes that reduced opportunities for accelerated deductions on machinery and equipment. Companies making significant capital investments may therefore face longer periods before recovering qualifying expenditure through tax deductions. The general restriction limiting the use of carried-forward tax losses to five years adds another consideration.

For industrial developers and occupiers, these conditions are relevant when assessing investments in production facilities, technology and automated operations. Tax treatment is only one element of such decisions, alongside labour availability, infrastructure, energy prices and access to markets. Nevertheless, differences in the timing of deductions can affect projected returns and influence comparisons between competing investment locations.

The country’s lowest ranking was recorded in consumption taxation, where it finished 32nd. One factor was the relatively high threshold requiring businesses to register for VAT, calculated at more than USD 153,000 in the international comparison. Although the arrangement reduces administrative responsibilities for smaller enterprises, it also means a narrower range of business activity falls within the VAT system.

Among neighbouring economies, Hungary secured tenth place, followed by Slovakia in twelfth and Poland in 32nd. Slovakia experienced a particularly noticeable decline, losing three positions as changes to personal taxation affected its assessment. Earlier increases in corporate taxation and the introduction of a financial transaction tax also contributed to a less favourable overall position.

The Czech Republic’s performance was nevertheless surpassed by three Baltic economies. Estonia retained the highest international ranking, Latvia followed in second place and Lithuania finished fifth. Austria occupied eighteenth position, while Germany ranked nineteenth. The results suggest that countries maintaining relatively straightforward and predictable tax arrangements continue to perform strongly under the methodology used by the Tax Foundation.

For international businesses and property investors, the Czech Republic’s seventh-place position reinforces its standing as an established Central European investment destination. Its treatment of qualifying long-term capital gains and certain property-related transactions offers advantages, but employment expenses and restrictions on capital allowances remain important considerations when evaluating investment opportunities.

The latest findings demonstrate that international tax rankings cannot be interpreted as a direct measure of the total financial burden facing businesses. While the Czech Republic has improved its relative position, its ability to attract further investment will also depend on the wider economic environment and the costs companies encounter when establishing or expanding operations.

As competition for industrial, commercial and residential investment continues across Central Europe, maintaining a stable and predictable tax framework will remain important. The Czech Republic currently holds a stronger position than its Visegrád neighbours in the international assessment, but sustaining that advantage will require policies that encourage long-term investment while supporting business growth and employment.

Strong Early Sales Prompt Central Group to Expand Prague Tower Launch

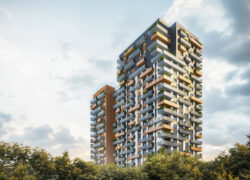
Central Group has accelerated the release of apartments at its Metropolis Tower development in Prague 10 following strong buyer interest during the project’s initial sales period. More than half of the homes offered in the first stage were sold within seven days, prompting the Czech residential developer to introduce additional units. The 23-storey building will contain 256 apartments and is scheduled for completion in December 2028.

Reaching approximately 70 metres, Metropolis Tower is expected to become the third-tallest residential building in Prague. The development will offer homes ranging from one-room apartments to larger four-room properties, with modern ventilation systems, external window shading and selected units equipped with air conditioning. Most apartments will also include balconies, storage space and underground parking.

Prices start at CZK 6.9 million for two-room apartments and CZK 9.9 million for three-room homes, including VAT. Central Group states that its pricing is approximately 20% below the average for newly constructed apartments in Prague. According to founder and chief executive Dušan Kunovský, the combination of pricing and apartment specifications has contributed to the strong initial response from buyers.

The project is being developed in an established residential district near Depo Hostivař metro station, with tram and bus connections providing access to other parts of the capital. Residents will also benefit from existing educational, healthcare and shopping facilities. Further improvements planned for the surrounding neighbourhood include a public park, children’s play areas and additional retail and dining amenities.

Metropolis Tower will join a relatively small number of residential high-rise buildings in Prague, where development heights are carefully controlled to preserve the city’s architectural character. According to Central Group, the city’s tallest completed residential properties are currently the 104-metre V Tower in Pankrác and the 94-metre Rezidence Eliška in Vysočany. The new development will add another prominent residential building to Prague’s skyline.

Central Group currently has around 3,200 apartments under construction in Prague, representing investments valued at approximately CZK 25 billion. The company is preparing to launch more than 2,000 additional homes across nine projects in seven districts, with an estimated development value of CZK 17 billion. Its longer-term pipeline includes land identified for more than 40,000 apartments across approximately 60 locations throughout the Czech capital.

ShockPrice Adds 2,000 Sqm of Retail Space at Sosnowiec Plaza

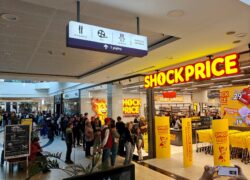
ShockPrice has opened a new store covering approximately 2,000 square metres at Sosnowiec Plaza in southern Poland. The shopping centre, owned by Focus Estate Fund, is expanding its retail selection as part of an ongoing strategy to attract customers and strengthen the property’s commercial performance.

The retailer, developed by MODIVO PLATFORM, builds on the experience of the HalfPrice concept, offering branded products across a frequently changing range of merchandise at discounted prices. Its arrival introduces a substantial new retail format to the shopping centre, broadening the selection available to customers in central Sosnowiec.

For Focus Estate Fund, the opening forms part of a wider programme to improve the performance of its retail properties through changes to tenant composition and the introduction of recognised brands. The investment manager aims to increase visitor interest and reinforce the role of its shopping centres as convenient destinations for everyday purchases and services.

Maxim Shkolnick, General Partner at Focus Estate Fund, highlighted the importance of securing established retailers capable of attracting customers and supporting the long-term development of shopping centres. He noted that the fund concluded leasing agreements covering approximately 28,300 square metres across its portfolio during 2025, while maintaining occupancy above 95%.

The addition of ShockPrice also reflects the continuing importance of discount-oriented retail concepts in Poland’s shopping centre market, where operators are seeking formats that encourage repeat visits and appeal to price-conscious consumers. For Sosnowiec Plaza, the new store is expected to contribute to a more diversified retail environment and strengthen the centre’s competitive position.

White Star Real Estate oversees leasing and property management at Sosnowiec Plaza, working with Focus Estate Fund on the centre’s commercial strategy and daily operations. The latest opening represents another stage in the repositioning of the property and its efforts to maintain relevance within the local retail market.

PORR Wins €100 Million Contract for US Military Aviation Hub in Poland

Austrian construction group PORR has secured a contract worth approximately €100 million (PLN 438 million) to develop the first stage of a new military aviation logistics facility at Wrocław-Strachowice Airport in southwestern Poland. The project, commissioned by the Regional Infrastructure Authority in Wrocław, will provide additional infrastructure for United States military operations, with completion scheduled for 2029.

The development forms part of Poland’s wider programme to establish four logistics facilities supporting American forces stationed in the country. Known as the Aerial Port of Debarkation (APOD), the Wrocław installation will accommodate the arrival and departure of military personnel, equipment and supplies. The investment is being implemented under the Enhanced Defense Cooperation Agreement between Poland and the United States, which provides the framework for expanding American military infrastructure in Poland.

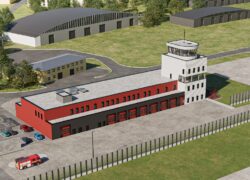
PORR will undertake the construction of two aircraft parking areas designed to accommodate different categories of military transport aircraft. One will provide four positions for C-5 Galaxy aircraft, while the second will accommodate three C-130 Hercules aircraft. The contract also includes connecting taxiways, a dedicated military airport fire station and a technical operations building.

Construction is expected to take approximately 33 months, with the completed facilities scheduled to undergo certification before entering service in 2029. The new infrastructure will operate within the existing international airport, improving its capacity to handle military transport operations while supporting the logistical requirements of allied forces.

PORR CEO Karl-Heinz Strauss highlighted the company’s experience in delivering technically demanding aviation and security-related infrastructure. He described the investment as an important contribution to Poland’s defence capabilities and economic development, emphasising the contractor’s role in delivering strategically significant infrastructure projects.

The contract represents another major infrastructure investment in Poland, reflecting the country’s expanding defence commitments and cooperation with the United States. Beyond its military purpose, the development will generate construction activity and demand for specialised engineering services, while strengthening Wrocław’s position as an important aviation and logistics location in southwestern Poland.

Radisson Blu Manchester Airport Hotel Secures Lease Extension Through 2035

Union Investment has agreed to extend its lease with Radisson Hotel Group for the Radisson Blu Hotel at Manchester Airport until the end of 2035. The agreement also provides an option for both parties to extend the arrangement by another ten years, potentially continuing their partnership until 2045.

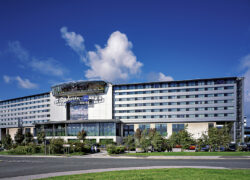
The property has been owned by Union Investment since 2004 through its UniInstitutional European Real Estate fund, which manages property investments for institutional clients. Completed in 1998, the hotel covers approximately 24,712 square metres and offers 352 guest rooms and eight suites. Its direct connection to the airport terminals provides convenient access for international passengers and business travellers.

In addition to accommodation, the hotel offers 27 meeting and conference facilities capable of hosting events for up to 400 participants. The property also includes 170 outdoor parking spaces and a restaurant overlooking the airport, supporting demand from corporate visitors and travellers using Manchester’s international flight connections.

Manchester Airport handled more than 32 million passengers in 2025, ranking as the United Kingdom’s third-busiest airport. Annual passenger traffic is projected to approach 40 million by 2030, supported by additional international routes, including services connecting Manchester with destinations in South and East Asia. The airport is also nearing completion of a £1.3 billion redevelopment programme aimed at improving passenger facilities and expanding operational capacity.

Thorsten Purkus, Head of Asset Management Hospitality at Union Investment, highlighted the hotel’s direct terminal access and the airport’s ongoing expansion as important factors supporting the property’s long-term prospects. Jens Brandin, Cluster General Manager of Radisson Blu Hotel Manchester Airport, also welcomed the extension, emphasising the established relationship between the hotel operator and property owner.

For Union Investment, the renewed agreement provides greater certainty over the property’s future occupancy while maintaining its investment in a major international transport location. The anticipated increase in passenger numbers and continued improvements to airport infrastructure are expected to support demand for accommodation, meetings and business travel services in the years ahead.

Bratislava’s Housing Market Offers More Choice but Ownership Remains Expensive

Bratislava’s residential market is entering the final months of 2026 with more newly built apartments available and slower price growth. However, greater supply has not necessarily improved affordability for working households. High property prices, substantial mortgage deposits and monthly repayments remain significant barriers, particularly for first-time buyers and younger families without considerable savings.

According to research published by Bencont Investments in July, Bratislava had 4,231 new apartments available across 105 residential developments at the end of the second quarter, compared with 3,922 three months earlier. The increase of almost 8% provided buyers with more options, although it remains unclear whether additional supply is placing meaningful downward pressure on prices.

Average advertised prices reached €5,341 per square metre in the second quarter, slightly below the €5,384 recorded in the preceding three months. Nevertheless, prices remained approximately 2.3% higher year-on-year. The modest quarterly decline suggests greater price stability, although changes in the types and locations of apartments being marketed can influence average values without developers necessarily reducing individual asking prices.

Sales activity remained relatively consistent with previous periods. Developers sold 652 apartments during the second quarter, compared with 742 in the first quarter and 638 during the third quarter of 2025. The quarterly decline followed unusually strong sales at an individual development earlier in the year, making it difficult to establish whether underlying demand has weakened.

The financial commitment required to purchase a new apartment remains considerable. Bencont placed the average advertised price at approximately €380,000 during the second quarter. With an 80% mortgage, buyers would need €76,000 in personal funds before additional expenses. Even a €250,000 property would require a €50,000 deposit, presenting a substantial challenge for households without existing property wealth or family financial support.

Monthly repayments add further pressure. A €240,000 mortgage over 30 years at an illustrative interest rate of 3.5% would cost approximately €1,078 per month, increasing to around €1,146 at 4%. Actual borrowing capacity depends on household earnings, existing debts and bank lending requirements. Although Bratislava generally offers higher salaries than other Slovak regions, average earnings do not necessarily reflect the circumstances of younger professionals or first-time purchasers.

Apartment configurations also influence affordability. Bencont’s earlier research indicated that two-room properties accounted for approximately 45% of available new-build apartments at the end of the first quarter, averaging around 51.6 square metres. Smaller homes generally require lower total expenditure than larger properties, but the figures do not establish whether developers have recently reduced apartment sizes specifically to accommodate financially constrained buyers.

For families requiring additional bedrooms, purchasing a suitable property can be considerably more expensive. Some households may therefore consider surrounding municipalities, where alternative housing options could offer better value. However, commuting costs, transport connections and access to schools and healthcare must also be considered. There is insufficient evidence to establish whether affordability pressures have caused a measurable increase in relocation from Bratislava during 2026.

Slovakia’s state-supported rental housing programme could provide an alternative for households unable or unwilling to purchase property. Its effectiveness will depend on the number of apartments delivered, rental costs and eligibility requirements. Without verified figures on operational capacity, its potential influence on Bratislava’s wider housing market remains uncertain.

Housing affordability also has broader economic implications. Expensive accommodation can affect labour mobility and recruitment, particularly for companies attracting employees from other regions or abroad. For Bratislava, maintaining access to suitable housing is therefore relevant not only to residential development but also to its competitiveness as a business and employment centre.

The latest comprehensive new-build market figures independently identified for this analysis cover the second quarter, with complete third-quarter results not yet verified as of 19 October. While increased supply and slower price growth suggest a more balanced residential market, they do not automatically make ownership accessible. Bratislava’s longer-term challenge remains bringing housing costs, mortgage requirements and household purchasing power into closer alignment.

Source: CIJ.World Research & Analysis Team

Slovakia’s Manufacturing Sector Faces Growing Investment Uncertainty

Slovakia’s manufacturing industry is entering the final quarter of 2026 with increasingly different prospects for established producers and companies investing in new technologies. While major international manufacturers continue developing factories and upgrading production facilities, others face weaker orders, rising costs and stronger international competition. These developments are raising questions about future investment and industrial property demand, particularly in regions dependent on automotive manufacturing.

The automotive industry accounts for more than half of Slovakia’s industrial production and approximately 43% of exports. Around 1.07 million vehicles were manufactured in 2025, maintaining the country’s position among the world’s leading automotive producers relative to population. However, this dependence also exposes Slovakia to changing European vehicle demand, international investment decisions and the transition towards electric mobility.

Recent figures indicate growing pressure on established manufacturers. Germany Trade & Invest reported that inflation-adjusted automotive turnover declined by approximately 4% during the first half of 2026, while new orders fell by more than 5%. The organisation also identified relatively few new automotive investment projects and indications that some suppliers were reducing their activities. Slovakia’s industrial production declined by 0.2% year-on-year in August, although temporary factory schedules influenced the figures. These developments suggest increasing caution without establishing a nationwide decline in manufacturing investment.

The planned closure of Mata Automotive Slovakia’s factory in Nová Ves near Veľký Krtíš illustrates the difficulties facing some component manufacturers. Production is scheduled to end in November 2026, affecting approximately 120 employees. The decision reflects weaker automotive demand and changes within the company’s international operations. Although individual closures do not establish a wider national trend, they demonstrate the vulnerability of manufacturing locations dependent on a limited number of employers.

Despite these pressures, significant investments continue. Volvo Cars is developing its approximately €1.2 billion electric vehicle factory near Košice, with production scheduled to begin in 2027. Designed to manufacture up to 250,000 vehicles annually, the project could attract additional suppliers and logistics businesses to eastern Slovakia. However, the eventual impact will depend on confirmed investment commitments and the number of companies establishing operations locally.

Battery manufacturing represents another potential growth area. Volkswagen’s battery subsidiary PowerCo and Gotion announced an agreement in September involving projects in Slovakia and Morocco, although the financial commitment specifically allocated to Slovakia remains unclear. The planned battery manufacturing facility at Šurany also forms part of the country’s industrial investment pipeline. Meanwhile, government agreements announced in September aim to support modernisation and lower-emission steel production in Košice, although the implementation timetable and final investment commitments require confirmation.

Established manufacturers are also improving existing operations. Volkswagen Slovakia and Kia have undertaken projects involving automation and production technology, demonstrating continued investment despite challenging market conditions. However, there is insufficient evidence to conclude that manufacturers are generally replacing factory expansion with modernisation. Both investment approaches remain important, depending on individual companies’ production requirements and future strategies.

The changing manufacturing environment could influence industrial property demand across Slovakia. Established automotive centres around Bratislava, Trnava, Nitra and Žilina remain important locations for suppliers and logistics operators, but weaker orders may discourage some companies from expanding. Eastern Slovakia could benefit from Volvo’s investment and related manufacturing activity, although new factories do not automatically generate equivalent demand for commercially leased warehouses.

Slovakia’s industrial property market is already experiencing greater competition for occupiers. CBRE reported that vacancy approached 8% during the second quarter of 2026, despite leasing activity increasing by 23% year-on-year to approximately 131,000 sqm. Net take-up reached around 67,000 sqm, while average rents declined by 3%. These figures indicate continued demand alongside increasing available space, although rising vacancy cannot be directly attributed to automotive restructuring.

For industrial property investors, the principal concerns involve tenant stability, building adaptability and future leasing demand. Suppliers dependent on a limited number of automotive contracts may face greater exposure to production changes, while manufacturers introducing battery technologies and automated systems could require more specialised facilities. Buildings capable of accommodating different industrial activities may therefore offer greater flexibility if occupier requirements change.

The amount of manufacturing investment cancelled or postponed during the fourth quarter remains unknown. Industry research and company announcements indicate weaker conditions among some established producers, but major projects continue progressing. Without comprehensive information on individual investments, it would be misleading to estimate the proportion of capital expenditure being withdrawn or delayed.

Slovakia’s manufacturing sector is therefore undergoing adjustment rather than a general contraction. New investment in electric vehicles, batteries and industrial technology offers opportunities, while traditional automotive suppliers face increasing competitive pressure. For the industrial property market, the central question is whether emerging manufacturing activities will generate sufficient demand to offset potential consolidation elsewhere, influencing future vacancy, rental performance and development across the country.

Source: CIJ.World Research & Analysis Team

China’s Economic Growth Strengthens Despite Continued Property Market Weakness

China’s economy recorded stronger growth during the third quarter of 2026, although the improvement continues to contrast with difficulties affecting the country’s real estate sector. According to figures released by the National Bureau of Statistics on 19 October, gross domestic product increased by 4.5% compared with the same period last year, accelerating from 4.3% in the second quarter. Economic growth reached 4.6% during the first nine months of 2026, placing the country within reach of its official annual target of between 4.5% and 5.0%.

The latest figures illustrate how China’s economy is becoming less dependent on property development and more reliant on manufacturing, technology and international trade. Industrial production increased by 5.5% in September, supported by continued activity across manufacturing industries. Investment in advanced production facilities, automation and technology-related businesses is helping sustain economic output. These developments could create opportunities for industrial property owners, logistics operators and developers serving expanding manufacturing sectors.

Domestic consumption, however, remains relatively subdued. Retail sales increased by just 1.1% in September, suggesting that households remain cautious about spending. Concerns surrounding employment, household finances and residential property values continue to influence consumer confidence. For shopping centres, retail landlords and businesses dependent on discretionary expenditure, the modest improvement indicates that operating conditions may remain challenging despite stronger national economic growth.

The property sector continues to represent one of China’s most significant economic weaknesses. Real estate development investment declined by 20.6% during the first nine months of 2026, reflecting persistent financial pressure on developers, weak residential demand and the consequences of earlier excessive borrowing. Overall fixed-asset investment also decreased by 7.2% during the same period, indicating continued caution among businesses and investors when committing capital to new projects. The figures demonstrate that stronger economic activity has yet to translate into a meaningful recovery in property development.

China’s prolonged property downturn is also changing the structure of its commercial real estate investment market. Developers seeking to reduce financial obligations and improve liquidity have increasingly considered selling income-producing properties, including office buildings, shopping centres, hotels and logistics facilities. These disposals may create acquisition opportunities for institutional investors and investment funds, although weaker rental demand, financing conditions and uncertainty surrounding asset valuations remain important considerations.

The outlook varies considerably between property sectors and locations. Industrial facilities connected to advanced manufacturing, technology production and international supply chains may benefit from continued economic expansion. In contrast, residential developments in markets with substantial unsold housing inventories face a more difficult recovery. Office and retail properties are also exposed to changes in corporate expansion plans, household consumption and tenant demand, making asset selection increasingly important for investors seeking stable long-term income.

Government efforts to strengthen domestic spending, stabilise residential markets and encourage private investment will remain important during the final months of 2026. However, restoring confidence in property markets may require more than an improvement in national economic indicators. Developers must address existing financial obligations, while potential homebuyers and commercial investors need greater certainty regarding property values, financing availability and future demand. International investors will also be assessing whether China’s changing economic priorities can generate sustainable opportunities across industrial, logistics and other commercial property sectors.

China’s third-quarter performance demonstrates that the economy can continue expanding even as real estate investment contracts sharply. Nevertheless, the difference between industrial growth and property market conditions raises questions about how widely the benefits of economic expansion are being distributed. With China approaching its annual growth objective, attention is increasingly shifting towards whether stronger economic performance can eventually restore confidence in residential and commercial property markets. For developers, property owners and institutional investors, the pace and direction of that recovery will remain central considerations heading into 2027.

Source: CIJ.World Research & Analysis Team

front page info
LATEST NEWS