Romania’s Industrial Property Market Enters Slower Phase as Regional Logistics Hubs Gain Ground

Romania’s industrial and logistics property market is experiencing a reduction in leasing activity following an exceptionally strong 2025, although demand remains considerably higher than before the pandemic. New research from Colliers shows that approximately 450,000 sqm of industrial and warehouse accommodation was leased during the first nine months of 2026, around 30% less than in the corresponding period last year. The figures suggest that businesses are becoming more selective about expansion commitments, while improvements to transport infrastructure are creating opportunities in locations beyond the country’s established logistics centres.

The slowdown has been particularly noticeable around Bucharest. The capital and surrounding Ilfov County generated approximately 265,000 sqm of transactions between January and September, compared with 448,000 sqm a year earlier. This represents a reduction of approximately 41%. Elsewhere in Romania, leasing volumes declined by less than 10%, reaching approximately 186,000 sqm. Although Bucharest continues to dominate national activity, the smaller contraction in regional markets indicates that demand is becoming less concentrated in the capital.

The development of new motorway connections is contributing to this geographical change. Industrial locations south and east of Bucharest are attracting greater interest as improvements to the A0 ring road provide more convenient access to major transport routes. Among the largest transactions recorded this year were agreements at VGP Park Bucharest A2 and CTPark Bucharest South. These areas are increasingly competing with the western and northern parts of the capital, where much of the previous decade’s logistics development was concentrated.

Infrastructure investment could also improve the prospects of industrial markets further from Bucharest. Moldova, in northeastern Romania, is identified by Colliers as an area that could benefit from major road construction programmes. Better connections to manufacturing centres, labour markets and national distribution networks may encourage developers and occupiers to consider locations that previously faced disadvantages because of longer transport times and limited motorway access.

Meanwhile, Romania’s supply of modern industrial and logistics accommodation continues to expand. More than 300,000 sqm of new space was completed during the first nine months of 2026, including approximately 80,000 sqm in the third quarter. The country’s total modern stock has consequently exceeded 8.3 million sqm. Recent developments include a 56,000 sqm facility built for retailer LPP in western Bucharest and a warehouse project of approximately 46,000 sqm north of the capital. Additional large facilities are expected to enter the market before the middle of 2027.

Despite weaker leasing volumes, headline rental levels have remained relatively stable. Modern logistics buildings in established locations generally achieve monthly rents of approximately €4.50–€5.00 per sqm, although transactions are increasingly being negotiated towards the lower end of that range. Competition between property owners has intensified as some occupiers seek to sublease warehouse space they no longer require. This additional accommodation is providing tenants with more options, particularly where businesses can accept existing building specifications rather than commissioning new facilities.

Development economics nevertheless remain challenging. Construction costs have increased by more than 10% over the past year, limiting the ability of landlords to reduce rents without affecting project viability. Available space remains relatively restricted in most locations, with vacancy generally below 10%. Companies requiring facilities larger than approximately 10,000 sqm often need developers to construct buildings specifically for their operations, particularly when location and technical requirements are important.

Manufacturing investment is providing some support to the market as consumer-related logistics demand remains subdued. Production companies accounted for approximately 28% of industrial and logistics demand during the first half of 2026, while investment in machinery and equipment increased by more than 18% in volume terms. These developments indicate continued interest in expanding industrial capacity, although uncertainty in European manufacturing, particularly the automotive sector, is affecting the timing of some investment decisions.

Romania’s performance is consistent with a wider adjustment across European logistics markets. Colliers reports that industrial vacancy across the EMEA region stood at 5.8% during the second quarter, while construction activity was lower than a year earlier. Rental growth has also moderated, and most markets are expected to experience relatively limited changes in pricing over the coming year. These conditions suggest that the sector is moving away from the unusually rapid expansion experienced after the pandemic towards a more balanced relationship between occupier demand and available space.

For Romania, the outlook for 2027 will depend on whether improving consumer activity translates into renewed warehouse requirements and whether manufacturers proceed with planned investments. The expansion of motorway infrastructure could become an increasingly important influence on development decisions, particularly outside Bucharest. Although leasing volumes are unlikely to match the exceptional performance of 2025 in the immediate term, the combination of industrial investment, improving connectivity and comparatively limited vacancy continues to provide opportunities for logistics property development.
Garbe Industrial Leases 19,500 Sqm Logistics Facility in Germany

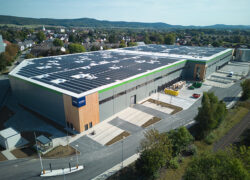
Garbe Industrial has leased its newly developed 19,500 sqm logistics property in Dissen, Lower Saxony, to the Oval Group, securing a single occupier for a facility originally intended to accommodate several tenants. The property will support temperature-controlled distribution operations, with the logistics company scheduled to begin using the building in February 2027.

Located in the Osnabrück district near the Teutoburg Forest, the development has been adapted to meet the operational requirements of the new tenant. Rather than dividing the building into separate units, the landlord will provide the entire facility to Oval Group, which is expanding its capacity for handling goods requiring controlled storage temperatures.

The building will accommodate two distinct storage environments. A refrigerated area operating between 0°C and 7°C will provide capacity for approximately 4,000 Euro-pallets, while a separate section maintained between 12°C and 18°C will accommodate around 23,000 Euro-pallets. Both areas include space for loading, unloading and handling goods, allowing different product categories to be managed within the same distribution centre.

The development occupies a site of approximately 32,000 sqm on Westring in Dissen, previously used for an older refrigerated warehouse. The former building was dismantled, with recovered materials processed for reuse in the new development. The completed property comprises approximately 17,200 sqm of warehouse accommodation, 1,700 sqm of mezzanine storage and 600 sqm of office and employee facilities.

The facility includes 17 loading docks and two ground-level access doors, together with external parking for six trucks and 40 cars. Its location provides access to the A33 motorway, with the Dissen/Bad Rothenfelde and Dissen-Süd junctions approximately two kilometres away. These connections support distribution movements between Osnabrück, Bielefeld and the wider German motorway network.

Energy efficiency has been incorporated into the building’s design. The property meets the German GEG-40 standard and uses air-source heat pumps for heating instead of fossil-fuel systems. Rooftop solar panels have also been installed, while the external areas include provisions for electric vehicle charging and landscaping intended to support local biodiversity.

Garbe Industrial is pursuing DGNB Gold certification for the development, although certification has not yet been confirmed. The project also incorporates architectural features including timber façade elements, alongside measures intended to reduce energy consumption and improve the building’s environmental performance.

For Oval Group, which is headquartered in Bad Oeynhausen and operates in freight forwarding, logistics and personnel services, the new facility provides additional capacity in an established distribution region. The agreement also demonstrates the continuing importance of specialised industrial properties capable of accommodating different storage temperatures, particularly for operators handling food and other temperature-sensitive products.

The transaction was supported by property consultancy Ruhr Real. For the landlord, securing a single tenant for the entire development removes the need to lease individual units while demonstrating how logistics properties can be adapted to meet specific occupier requirements.

HireRight Expands Katowice Headquarters as Globalworth Secures Lease Renewal

International employment screening company HireRight has renewed its lease at Silesia Star in Katowice, increasing its office accommodation to approximately 3,300 sqm. The agreement with Globalworth allows the company to remain in a building it has occupied since 2016 while adapting the premises to accommodate its growing operations.

The decision to extend the lease was influenced by the property’s accessibility, parking facilities and range of services, together with the flexibility to reorganise the office space. The planned refurbishment will provide a working environment better suited to the company’s current requirements. Financial details and the duration of the new agreement have not been disclosed.

JLL represented HireRight during negotiations and will also provide technical advice for the refurbishment. Piotr Gawlik Law Firm supported the legal aspects of the transaction. The agreement was concluded following approximately three months of negotiations.

Silesia Star offers more than 29,000 sqm of office accommodation in central Katowice, close to the city’s Culture Zone and major transport connections. The complex provides landscaped terraces, relaxation areas, childcare facilities and infrastructure for cyclists and electric vehicle users.

Environmental performance remains an important feature of the property. Silesia Star holds BREEAM In-Use v6 certification at Outstanding level, with a score of 87.2%. According to Globalworth, the building uses electricity sourced entirely from renewable energy and incorporates waste management measures. It has also received accessibility certification from Poland’s Integration Foundation.

The transaction reflects the importance of retaining established occupiers in Poland’s regional office markets. For businesses with existing operations, renewing a lease can offer an opportunity to modernise their workplace without the costs and disruption associated with relocation. For property owners, accommodating changing tenant requirements can help maintain occupancy and reduce potential vacancy.

Katowice remains an established location for international business services, supported by its workforce, transport infrastructure and modern commercial properties. As companies reassess their office requirements, the ability to provide adaptable accommodation and reliable building services continues to influence leasing decisions.

For Globalworth, the agreement secures the continued presence of a longstanding international tenant while increasing the space occupied within its Katowice portfolio. The renewal also illustrates how building quality, environmental performance and active property management can contribute to tenant retention in a competitive office market.

Romania Introduces New Merger Control Rules with Shorter Decision Deadlines

Romania has introduced updated regulations governing the review and approval of corporate mergers and acquisitions, bringing changes to administrative procedures that may affect transactions across the country’s investment and property markets. The revised framework entered into force on 1 October 2026, replacing rules established in 2017 and introducing clearer requirements for companies seeking regulatory approval.

The new regulation, adopted through Competition Council President’s Order No. 2,192/2026, retains the principal system for notifying and assessing transactions that fall within Romania’s merger control requirements. However, it introduces several procedural adjustments intended to clarify the responsibilities of businesses and regulators during the approval process. Some provisions also bring the secondary legislation into line with requirements already contained in Competition Law No. 21/1996.

One significant change concerns transactions that receive permission to proceed with certain implementation measures before final merger clearance. The Competition Council now has an expressly defined right to withdraw such permission if it was granted using inaccurate, incomplete or misleading information. Approval may also be withdrawn when companies fail to comply with conditions attached to the original decision. This makes the accuracy of transaction documentation particularly important when businesses request exceptions to the normal restrictions on completing a deal before authorisation.

The regulation also establishes a maximum response period of 15 days for information requests issued by competition inspectors during merger investigations. Such requests may be directed not only to the companies involved in a transaction but also to business associations, public institutions and individuals holding relevant information. The previous regulation did not specify an equivalent maximum period, leaving greater uncertainty over the time available to respond.

Additional provisions address transactions that require examination under both competition legislation and Romania’s national security investment screening system. Where the Foreign Direct Investment Review Commission, known as CEISD, rejects a transaction, the Competition Council must notify the parties within ten days of receiving that decision. Such a rejection results in the termination of the merger approval procedure.

Where the national security assessment concludes that a transaction does not present a relevant security risk, the Competition Council must inform the parties within seven days of receiving the commission’s communication that its merger review procedure will resume. These provisions provide greater clarity on the interaction between the two regulatory processes, particularly for transactions involving investors or activities subject to additional scrutiny.

Another important amendment concerns the period available for issuing the reasoning and communicating merger decisions. The new regulation establishes a maximum of 15 days following deliberation, replacing the 120-day period contained in the previous secondary legislation. The change aligns the regulation with provisions already established under Romania’s Competition Law and should provide greater clarity over the final administrative stages of merger proceedings.

For the commercial real estate sector, the amendments may be relevant to acquisitions involving property companies, development businesses, investment platforms and other corporate structures that meet the applicable merger notification thresholds. Transactions involving the direct purchase of individual properties do not automatically fall within merger control requirements, making the legal structure and economic substance of each acquisition important when determining whether regulatory clearance is necessary.

The changes do not remove the requirement for qualifying transactions to undergo competition assessment, nor do they eliminate the possibility of separate national security screening. Instead, they clarify certain procedural obligations and communication deadlines that can influence transaction planning. Investors and advisers will need to account for these requirements when preparing acquisition agreements, establishing completion conditions and assessing regulatory risks.

Romania’s revised merger framework therefore represents an administrative update rather than a fundamental change to the country’s competition approval system. Its practical significance lies in clearer communication requirements, defined response periods and the regulator’s ability to reconsider permissions granted before final approval. For companies planning acquisitions, careful preparation of regulatory submissions and coordination between competition and investment screening procedures will remain essential.

Source: Deloitte

Yareal Reshapes Its Warsaw Headquarters as LIXA Campus Maintains Leasing Momentum

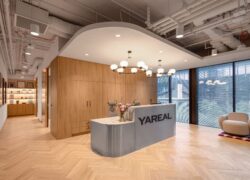
Yareal Polska has relocated its headquarters to a newly designed 750 sqm office within the LIXA business complex in Warsaw, demonstrating how established office developments can accommodate changing workplace requirements without companies having to move to different locations. The developer has transferred its operations to the second floor of LIXA C, while the premises it previously occupied in LIXA B have already attracted another tenant.

The relocation represents an internal move within the five-building campus near Rondo Daszyńskiego, one of Warsaw’s principal commercial districts. Rather than expanding into a separate property, the company has reorganised its accommodation around a new interior layout intended to provide greater flexibility for employees and improve the experience of visiting clients.

The Design Group was responsible for the architectural interiors, with Katarzyna Oleksińska managing the project on behalf of Yareal. The design combines traditional office facilities with features commonly found in residential properties, including natural materials, softer lighting and a less formal arrangement of working areas. The objective was to create an environment suited to different professional activities while maintaining the standards expected of a corporate headquarters.

The office is organised into separate areas for external meetings and internal operations. Reception and visitor spaces feature timber flooring, marble finishes and oak detailing, while the main employee areas combine shared workstations with enclosed rooms and smaller spaces for individual work. Planting, subdued colours and carefully arranged lighting are used throughout the premises to create a consistent interior environment.

Digital systems have been incorporated to support everyday operations, including mobile access to the office and electronic management of meeting room availability. The technology is intended to simplify how employees use the space rather than introduce unnecessary complexity. This reflects an approach to workplace planning in which building functionality and employee requirements take priority over highly visible technological installations.

The move also has implications for the management of the wider LIXA development. The previous office space in LIXA B was leased again shortly after becoming available, indicating continued interest in accommodation within the complex. For property owners, retaining an existing occupier within a development while securing a replacement tenant for vacated premises can help maintain rental income and reduce the disruption associated with tenant relocations.

LIXA was developed by Yareal in several stages and comprises five buildings with approximately 77,000 sqm of office space. The architectural design was prepared by HRA Architekci, with the campus incorporating commercial services, restaurants and landscaped public areas. Yareal currently owns the LIXA C and LIXA E buildings, maintaining a direct investment interest in part of the completed development.

More than 5,500 sqm of outdoor space is distributed across the campus, including landscaped courtyards and terraces. These areas provide connections between the buildings and contribute to the wider pedestrian environment. The new headquarters overlooks one of the courtyards, integrating the office with the surrounding outdoor facilities.

The development also incorporates recognised environmental and building performance standards. Properties within LIXA have obtained certifications including BREEAM Excellent, WiredScore Platinum, WELL Health-Safety, ActiveScore and AirRated. These assessments address different aspects of building performance, ranging from environmental efficiency and digital infrastructure to indoor conditions and facilities supporting active transport.

The relocation highlights the importance of adaptable office accommodation in Warsaw’s established business districts. Companies increasingly evaluate premises according to how effectively they support daily operations, employee preferences and long-term organisational requirements. For developers and landlords, the ability to offer different workplace configurations within the same complex can support tenant retention while creating opportunities to lease space released through internal relocations.

Prague’s Pankrác Office Market Attracts Major Tenant as BDO Consolidates Operations

Prague’s office market has secured a significant new leasing agreement, with BDO Czech Republic committing to more than 4,100 sqm at the Isola development in Pankrác. The audit, tax and advisory firm will relocate employees from two existing Prague offices into a single headquarters, providing accommodation for approximately 350 workstations. The move is planned for the third quarter of 2027, following the completion of the building’s redevelopment at the end of 2026.

The agreement covers almost the entire upper three floors of the five-storey property, including a terrace overlooking Prague. The new premises will be configured around the company’s operational requirements, with adaptable working areas and facilities for client meetings. Consolidating employees into one location is intended to improve coordination between teams while providing accommodation capable of supporting future business requirements.

Savills advised on the leasing transaction and has also been appointed to oversee the delivery of the office interiors. Its responsibilities extend from the selection of premises and negotiation of commercial terms to managing the preparation of the space for occupation. The arrangement reflects the importance of coordinating property decisions with workplace planning, particularly when companies are combining operations previously distributed across several buildings.

The transaction comes at a time when opportunities to secure newly developed office accommodation in Prague are relatively limited. Many businesses have chosen to remain in their existing premises, making substantial relocation agreements particularly relevant to the market. For BDO, the availability of modern space in an established business district provided an opportunity to address its longer-term accommodation requirements.

Pankrác remains an important location for corporate offices because of its existing public transport connections and proximity to other commercial developments. The planned Metro Line D could further improve accessibility, although its eventual contribution will depend on the progress of the transport project. The district’s established business environment also makes it a practical location for companies seeking to accommodate larger teams within a single property.

The Isola project is owned by Generali Real Estate and involves the reconstruction of a building originally developed for industrial use in 1989. The property previously housed ČKD Polovodiče before being adapted for office occupation by Česká pojišťovna in the late 1990s. Its current redevelopment will provide approximately 8,000 sqm of office accommodation, transforming an older commercial asset into a building designed for contemporary workplace requirements.

Environmental performance is a major component of the investment. The project is designed to operate without net carbon emissions from building operations and is pursuing BREEAM Outstanding and WELL Health-Safety certifications. Generali Real Estate also states that the redevelopment meets the applicable EU Taxonomy criteria for sustainable investment. The building’s architectural design was prepared by Chapman Taylor, with the project combining substantial modernisation and the continued use of an existing structure.

The agreement also demonstrates the commercial potential of upgrading older office properties rather than relying exclusively on new construction. Extensive refurbishment can enable landlords to improve energy performance, building services and interior flexibility while maintaining a presence in established business locations. For occupiers, such projects can provide access to modern facilities in districts where development opportunities are limited.

BDO’s commitment represents more than half of Isola’s planned office area, giving the project a substantial tenant ahead of completion. The transaction provides further evidence that demand remains for well-connected, modern offices in Prague, particularly among businesses seeking to bring employees together and improve the efficiency of their accommodation. It also highlights the continuing role of major refurbishment projects in maintaining the competitiveness of the city’s established office districts.

London Office Landlord Reports 30% Drop in New Lettings as Investment Market Remains Challenging

London’s flexible office sector is facing a more difficult leasing environment, with Workspace Group reporting a substantial reduction in new customer agreements during the quarter ending 30 September 2026. The company’s latest business update reveals weaker demand for office accommodation, modest pressure on occupancy and continued difficulties selling commercial properties at valuations acceptable to both buyers and sellers.

The company completed 227 new lettings during the quarter, compared with 326 in the corresponding period of 2025, representing a decline of approximately 30%. The amount of office space covered by new agreements fell from 179,000 sq ft to 121,000 sq ft. Customer enquiries also declined, averaging 516 per month against 666 a year earlier, while monthly property viewings decreased from 519 to 322. Activity was particularly subdued in August before improving in September.

Despite the reduction in transactions, rental levels remained relatively stable. Average rents across the portfolio increased marginally to £42.71 per sq ft, while rents within established properties rose by 0.4% during the quarter to £46.13 per sq ft. However, the total annualised rental income generated by the portfolio declined from £128 million at the end of June to £126.6 million at the end of September, reflecting a combination of property sales, refurbishment work and changes in occupancy.

Overall occupancy decreased by one percentage point to 79.2%, although the company attributed much of this movement to changes within its property portfolio rather than tenants vacating existing offices. The completion of 31,000 sq ft of additional accommodation at The Biscuit Factory introduced space that had not yet been fully leased, while other offices were temporarily unavailable because of refurbishment and conversion work. Excluding these factors, management reported a small improvement in occupancy.

Workspace is introducing changes to its leasing arrangements as it seeks to attract businesses looking for greater cost certainty and more flexible accommodation. A revised pricing structure introduced in September combines office rental and associated services into a single charge. The first 18 completed agreements under this arrangement achieved an average rent of £60.57 per sq ft, approximately 8% above the company’s estimated rental value for those spaces. Another 18 agreements under negotiation were priced at an average of £59.71 per sq ft, although these transactions had not yet been completed.

Investment in fully equipped offices is also being accelerated. Twenty-four units are being prepared across three properties in Clerkenwell, with the first accommodation scheduled to become available in November and the remainder expected in December. The company plans to invest approximately £1.5 million in these units and expects to introduce more than 100 additional furnished offices during 2027. Four other refurbishment projects are progressing, with completion anticipated in the second half of next year.

The investment market presents a separate challenge. Workspace has completed £138.3 million of property disposals since March 2025 and continues to target £200 million by March 2027. However, negotiations are taking longer as prospective purchasers respond to financing costs and economic uncertainty by seeking lower prices. Three sales agreed during the first quarter of the current financial year were priced at an average discount of 28% to their March 2026 valuations, highlighting the gap that can emerge between reported property values and achievable transaction prices.

Although more than £50 million of assets are currently under offer and further properties are being discussed with potential purchasers, management has indicated that an additional disposal programme exceeding £100 million is unlikely to be fully completed by March 2027. The company is therefore balancing its objective of reducing debt with the risk of accepting prices below its assessment of the properties’ longer-term value.

Net debt increased to £754 million at the end of September, compared with £740 million three months earlier. Available cash and unused credit facilities totalled £246 million, while the company’s indicative loan-to-value ratio stood at 36%, calculated using its March 2026 property valuations. Refinancing remains an important consideration as higher borrowing costs continue to influence commercial property investment decisions.

The quarterly figures illustrate the pressures facing London office landlords as they adapt to changing occupier requirements. Businesses are completing fewer leasing transactions, but rental rates have not experienced a comparable decline. At the same time, property owners are investing in ready-to-use offices and new leasing structures while managing the financial implications of a slower investment market. Workspace’s half-year results, scheduled for 18 November, will provide further information on the company’s financial performance and progress with its portfolio strategy.

Big Yellow’s Future Ownership Back in Focus as Investor Calls for Sale Review

The future ownership of British self-storage operator Big Yellow Group has returned to the spotlight following reports that one of its shareholders wants the company to consider a potential sale. The development comes less than a year after the business explored interest from prospective buyers but decided against pursuing a transaction because the valuation under discussion was considered insufficient.

In a statement issued in response to the reports, the company confirmed that representatives had recently met with the shareholder concerned. However, it did not identify the investor or disclose the nature of the discussions. There was also no indication that a formal acquisition proposal had been received or that negotiations with potential buyers had resumed.

The renewed attention follows an earlier review of the company’s strategic alternatives. In October 2025, the board acknowledged that it had engaged with a limited number of interested parties regarding possible changes to the business, including a complete sale. Two months later, an interested party communicated a preliminary valuation at which it might be prepared to proceed with an offer.

The board subsequently decided that the proposed valuation did not adequately recognise the company’s longer-term prospects, bringing those discussions to an end. No financial details of the preliminary approach were disclosed, leaving the difference between the potential buyer’s assessment and the board’s expectations unclear.

Big Yellow operates one of the United Kingdom’s established self-storage platforms, comprising 115 facilities with approximately 6.9 million sq ft of maximum lettable space. Its development programme includes ten additional facilities representing around 800,000 sq ft. If all planned projects are completed, the portfolio would increase to approximately 7.7 million sq ft.

The company’s concentration in London and its surrounding commuter towns is a significant characteristic of its business. Facilities in these locations account for approximately three-quarters of revenue, while the remaining income is generated from properties serving larger regional cities. The portfolio therefore provides substantial exposure to storage demand in and around the British capital.

Property ownership is another important consideration for prospective investors. Approximately 99% of the company’s stores and development sites, measured by value, are held through freehold or long-term leasehold arrangements. This gives the business a substantial real estate component alongside its storage operations, customer relationships and management infrastructure.

The latest developments also draw attention to the potential acquisition value of established self-storage businesses. Unlike conventional commercial properties, self-storage facilities combine ownership or control of physical assets with an operating business serving individual and corporate customers. Any prospective buyer would therefore need to assess both the property portfolio and the earnings potential of the wider business.

Despite the renewed speculation, there is currently no confirmation that a transaction is being prepared. Management remains focused on operating and expanding the existing portfolio, while the board has indicated that it will continue considering alternatives that could benefit shareholders. Whether investor pressure results in another formal review or renewed acquisition interest remains uncertain.

CTP Strengthens European Expansion with Major Logistics Investment in Northern Italy

A new logistics development covering almost 200,000 sqm is taking shape in northern Italy as European industrial property investor and developer CTP advances its expansion into the country. Located in Castel San Giovanni, near Piacenza, the project represents the company’s first Italian logistics park under its established European brand and forms part of a €1 billion investment programme planned over the next five years.

The development follows the company’s entry into the Italian market in 2025 through the €241 million acquisition of VLD S.r.l., a property development business holding land suitable for industrial and logistics construction. The transaction provided access to several established distribution locations and created a foundation for developing a wider portfolio across Italy.

The first building at CTPark Castel San Giovanni has been completed, providing approximately 52,000 sqm of logistics accommodation for an international operator. A second facility, covering around 113,000 sqm, is currently being developed for a company active in the luxury goods sector. Together, the two buildings account for approximately 165,000 sqm of the park’s planned capacity, with further development space available within the project.

Castel San Giovanni is situated southeast of Milan within the province of Piacenza, an established logistics location serving northern Italy. The area benefits from motorway connections linking Lombardy, Piedmont, Emilia-Romagna and Liguria, providing access to major manufacturing centres, consumer markets and freight corridors. Its position makes it suitable for businesses managing distribution activities across Italy and neighbouring European markets.

The scale of the second facility reflects the growing importance of specialised logistics infrastructure for companies operating in high-value consumer industries. Luxury goods businesses require distribution networks capable of supporting inventory management, product handling and international deliveries. Modern facilities designed around individual occupier requirements can help accommodate these activities while providing flexibility for future operational changes.

The investment follows a development strategy in which properties are constructed for identified occupiers and subsequently retained as income-generating assets. This approach combines new construction with long-term ownership and management, allowing the landlord to maintain relationships with tenants while expanding its rental portfolio. The same model has been used extensively across Central and Eastern Europe, where the group has established a substantial industrial property presence.

Italy represents an opportunity to extend this strategy into one of Europe’s largest manufacturing economies. Established industrial clusters, international trade activity and demand for modern distribution facilities provide a foundation for further development. The expansion also broadens the geographical distribution of the company’s European assets beyond its traditional markets in the Czech Republic, Romania, Poland, Slovakia and Hungary.

Further logistics projects are planned in Alessandria, Novara Sant’Agabio and Padova Vescovana, creating a development pipeline across northern Italy. The company has also opened an office in Rome and is considering opportunities in central and southern regions, indicating an intention to establish a nationwide industrial property platform rather than concentrate exclusively on the Milan logistics corridor.

The launch of the Castel San Giovanni park marks a transition from acquiring development land to delivering operational logistics facilities in Italy. With one building completed, another substantial project underway and additional locations identified, the investment programme is beginning to take shape. Its longer-term performance will depend on the successful delivery of new properties, continued occupier demand and the strength of Italy’s industrial and distribution markets.

Union Investment Expands Amsterdam Hospitality Offering with Staycity’s First Dutch Aparthotel

Union Investment has introduced a new hospitality operation at its YVIE development in Amsterdam following the opening of a 120-apartment property operated by Staycity Group. The accommodation, marketed under the Wilde brand, represents Staycity’s first entry into the Netherlands and is supported by a 25-year lease agreement, providing the German investment manager with a long-term hospitality tenant within its mixed-use property.

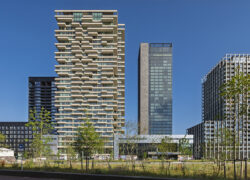
The aparthotel occupies approximately 7,000 sqm across eight floors of YVIE’s 31-storey residential tower in Amsterdam-Noord. Located in the Overhoeks neighbourhood overlooking the IJ River, the development forms part of an area that has experienced considerable residential and commercial investment. The new accommodation is designed for stays of at least seven nights, placing it between conventional hotel operations and longer-term residential rentals.

The property contains 120 furnished apartments intended for business travellers, professionals relocating to Amsterdam and visitors requiring accommodation for extended periods. Designed by Studio Barba Mendoza, the interiors combine private residential facilities with communal amenities. Guests have access to a café and bar, a food outlet, shared working and relaxation spaces, fitness facilities and an outdoor terrace.

The opening marks a further stage in the commercial relationship between Union Investment and Staycity Group. The companies have worked together in London since 2021, when Staycity began operating its Wilde Aldgate property on Commercial Road. The Amsterdam agreement extends that relationship into continental Europe, with the long lease providing contractual stability for the property owner while allowing Staycity to establish its presence in the Dutch hospitality market.

YVIE’s residential tower was completed during 2024 and 2025 and contains 176 conventional apartments in addition to the new hospitality accommodation. According to Union Investment, the residential units are approaching full occupancy. The combination of apartments and serviced accommodation allows the development to serve different residential and visitor requirements within the same building.

Union Investment acquired the development in 2019, before construction was completed, and holds the property through its UniImmo: Europa open-ended real estate investment fund. The addition of the aparthotel introduces a long-term hospitality income arrangement alongside the residential component. Neither the annual rent nor the wider financial terms of the Staycity agreement have been disclosed.

The transaction illustrates the increasing overlap between residential property and hospitality investment. Extended-stay accommodation can appeal to companies arranging temporary housing for employees, international professionals undertaking assignments and visitors who require facilities suitable for longer periods. Unlike conventional hotels, aparthotels generally provide greater independence through self-contained accommodation while retaining selected hospitality services.

For institutional property investors, long-term agreements with specialist operators offer a way to incorporate hospitality activities into mixed-use developments without directly managing daily guest operations. Nevertheless, the financial performance of such investments remains dependent on the operator’s business model, the strength of the local accommodation market and the contractual structure of the lease.

The opening strengthens the hospitality component of YVIE while expanding Staycity’s European network. With its residential apartments approaching full occupancy and a hospitality operator committed under a 25-year agreement, the Amsterdam development provides an example of how institutional investors are combining different accommodation formats within a single urban property.

front page info
LATEST NEWS