Empira Secures Technology Occupier for 3,192 sqm at Munich’s Kistlerhof Development

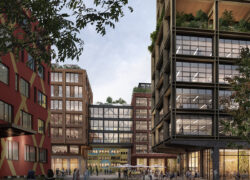
Empira Group has agreed a lease with Munich-based technology company Hologate for approximately 3,192 sqm of office and exhibition accommodation at Kistlerhof, a mixed-use commercial complex in the city’s Obersendling district. The transaction forms part of the property investment manager’s ongoing efforts to reposition the location as a destination for technology businesses and other commercial occupiers.

Hologate will occupy premises on the ground and sixth floors of Building 1 at Kistlerhofstraße 70. The company is expected to move into the accommodation on 1 November 2026, following the completion of refurbishment works. The new premises will allow Hologate to consolidate its workplace activities and technology presentation facilities within one building.

Established in Munich in 2013, Hologate develops technologies combining artificial intelligence, extended reality and integrated digital systems. Its products and services are used across several industries, including corporate applications, defence, public safety, education and entertainment. The company operates internationally and has expanded its activities beyond its original focus on immersive entertainment technology.

The relocation will bring Hologate’s employees together in a more consolidated working environment while providing dedicated areas for demonstrating its technologies to customers and business partners. According to founder and CEO Leif Petersen, the move reflects the company’s recent expansion and its intention to create a workplace that supports closer cooperation between teams and engagement with clients. Hologate is relocating within the existing Kistlerhof complex rather than moving to the location for the first time.

For Empira Group, which operates as part of Partners Group, the agreement contributes to its strategy of attracting businesses involved in technology, digital services and creative industries. The investment manager is seeking to establish a varied occupier base while adapting existing buildings to accommodate different workplace requirements.

Benjamin Meiereder, Asset Manager at Empira Group, said the agreement supports the company’s plans for Kistlerhof by adding to its concentration of internationally active technology businesses. The property’s combination of office accommodation and other commercial uses is intended to provide flexibility as occupier requirements evolve.

Kistlerhof comprises approximately 78,000 sqm of gross floor area, including existing properties and proposed new construction. The development concept incorporates offices alongside retail premises, restaurants, leisure facilities, hotel accommodation and laboratory space. This combination is intended to create a commercial environment accommodating businesses with different operational requirements.

Building 1, where Hologate will establish its new premises, contains approximately 18,000 sqm of gross floor area. The agreed lease therefore represents approximately 17.7% of the building’s total stated area, although this comparison is based on gross floor area rather than net lettable accommodation.

The complex is situated close to Aidenbachstraße underground station, providing access to Munich’s public transport network. Its location within Obersendling, an established commercial district, offers connections to other employment areas and business services across the city.

The transaction illustrates continuing demand from technology companies for premises combining conventional workplaces with specialist facilities. For landlords, accommodating these requirements can involve adapting existing commercial buildings to provide more flexible layouts and space capable of supporting activities beyond traditional office functions.

Empira has not disclosed the financial terms or duration of the lease. The announcement also does not specify the refurbishment investment associated with Hologate’s premises or the occupancy level of the wider Kistlerhof complex.

Moldova’s Economic Progress Faces Challenges from Rising Prices and Slower Construction

Moldova’s economy is showing signs of improvement during 2026, supported by higher investment, increasing household earnings and stronger industrial activity over the first eight months of the year. However, rising consumer prices and declining construction output are creating difficulties for businesses, households and property developers. According to the National Bureau of Statistics, economic output increased by 0.9% year on year during the second quarter, while inflation reached 8.6% in September. The contrasting figures suggest that the country’s recovery remains uneven as investors and businesses consider opportunities for 2027.

Economic activity increased by 0.9% during the second quarter compared with the same period in 2025, while growth across the first six months reached 0.6%. After seasonal adjustments, output expanded by 1.4% compared with the preceding quarter. Although the figures indicate that Moldova maintained a positive rate of economic growth, the relatively modest expansion suggests that improvements have not yet become widespread across the economy. Domestic spending, business investment and industrial performance will remain important influences on the country’s development during the remainder of the year.

Inflation has become a significant concern for households and businesses. Consumer prices increased by 8.6% in September compared with the corresponding month last year, accelerating from 7% in August. Prices also rose by 1.7% during September alone, while the cumulative increase since December 2025 reached 6.6%. The continued rise in living expenses is placing pressure on household budgets and increasing the cost of operating businesses, particularly those dependent on energy, transport and other essential services.

Energy expenditure contributed substantially to September’s inflation. Regulated natural gas tariffs increased by 40.8% compared with August, while electricity prices were 23.7% higher than a year earlier. Natural gas prices also recorded an annual increase of 21.3%, while petrol and diesel became more expensive. These developments have implications for manufacturers, logistics operators, retailers and commercial property owners, as higher utility and transport costs can influence profitability, rental affordability and decisions concerning future investment.

Household earnings continued to improve, although the benefits were partly offset by inflation. Average gross monthly wages reached MDL 16,895.7 during the second quarter, representing an increase of 9.2% compared with the same period last year. After allowing for changes in consumer prices, earnings increased by 2.3% in real terms. The number of employees covered by the wage survey also increased by 2.5%. The figures indicate that household income continued to rise, but the improvement in purchasing power was considerably smaller than the nominal wage increase suggests.

Differences in earnings between economic sectors remained substantial. Employees working in information technology and communications received average gross monthly wages of approximately MDL 41,010, while those in financial and insurance services earned around MDL 31,451. By comparison, average earnings in agriculture were approximately MDL 10,830, while accommodation and food services recorded around MDL 11,723. These differences influence household purchasing power and can contribute to variations in residential and commercial property demand between employment centres and regional markets.

Labour market conditions improved between the first and second quarters. Approximately 859,300 people were employed during the second quarter, an increase of 5.9% compared with the preceding three months. Unemployment declined from 10.4% to 7.3%, while the number of people without work fell to approximately 67,600. The employment rate reached 45% among people aged 15–89. However, changes in the statistical methodology used to measure unemployment mean that comparisons with earlier years require caution. The figures nevertheless indicate an improvement in labour market conditions during the first half of 2026.

The structure of employment also provides an indication of Moldova’s economic characteristics. Services accounted for approximately 61.2% of employed people, followed by agriculture at 14.4%, industry at 12.6% and construction at 11.8%. Around 19.5% of workers were estimated to be employed through informal arrangements, with construction recording particularly high levels. These characteristics are relevant to the availability of skilled labour, employment stability and the organisation of development projects, particularly where businesses require experienced workers and predictable construction schedules.

Industrial activity increased during the first eight months of the year, although the latest monthly figures showed a decline. Total production between January and August was 6.7% higher than during the corresponding period of 2025, supported by growth of 5.7% in manufacturing and 14.9% in energy production and supply. However, industrial output declined by 0.7% year on year in August, while manufacturing production fell by 2%. The difference between the cumulative and monthly figures indicates that earlier improvements were followed by weaker performance during the summer.

For Moldova’s industrial and logistics property markets, manufacturing activity remains an important indicator of potential occupier demand. Food processing companies, manufacturers, distributors and export-oriented businesses require suitable production premises, storage facilities and transport connections. Stronger industrial activity can support investment in these properties, although changes in production do not automatically translate into additional demand for warehouse or factory space. Energy costs, labour availability and access to international markets will remain important considerations for companies evaluating expansion.

Investment activity continued to increase during the first half of 2026. Approximately MDL 16.4 billion was invested in fixed assets between January and June, representing growth of 5.2% compared with the same period last year after accounting for price changes. Investment in physical assets increased by 7.4%, indicating that businesses and other investors continued allocating resources to equipment, infrastructure and long-term productive capacity. However, these figures cover a broad range of expenditure and should not be interpreted as investment in property development alone.

Construction activity presented a less encouraging picture. The volume of work completed during the second quarter declined by 6.3% compared with the corresponding period in 2025, while construction output across the first six months decreased by 8.2%. The figures indicate that higher overall investment has not been accompanied by a corresponding increase in building activity. Project financing, development preparation, construction expenditure and the timing of major contracts may all influence performance, although the available statistics do not establish which factors were primarily responsible for the decline.

Moldova’s residential market faces a combination of improving earnings and rising household expenditure. Higher wages may strengthen the purchasing capacity of some prospective buyers, particularly those employed in technology, financial services and other higher-paying industries. However, inflation and increasing utility costs reduce the income available for savings and mortgage repayments. Developers must also consider construction expenditure, financing conditions and the ability of households to afford newly built properties. These issues are particularly relevant in Chișinău, where residential development and demand for urban accommodation are concentrated.

Retail activity showed stronger performance during the summer. Official figures indicated that retail sales volumes increased by 15.9% year on year in July, while wholesale trade expanded by 10.9%. The figures suggest that commercial activity continued to grow despite inflationary pressures, although they do not establish whether all retail categories or locations benefited equally. For shopping centres, supermarkets and neighbourhood retail properties, household purchasing power and consumer spending patterns will remain important influences on tenant performance and future expansion decisions.

Moldova’s office property market is influenced by the performance of professional services, technology businesses and other employers requiring modern commercial accommodation. The relatively high earnings recorded in information technology, communications and financial services demonstrate the importance of these industries within the economy. Such businesses can generate demand for offices, particularly in Chișinău, although national employment and wage statistics do not directly establish changes in leasing activity. Companies considering additional premises will continue to evaluate workforce requirements, building quality, operating expenses and accessibility.

The wider investment environment remains closely connected to infrastructure development, energy security and Moldova’s international economic relationships. Rising utility costs create additional challenges for industrial facilities, retail premises and residential buildings, while improvements in transport infrastructure and essential services can influence the attractiveness of development locations. Investors must also consider financing conditions, regulatory requirements and the ability of individual projects to generate sustainable income. The latest economic indicators suggest that opportunities exist, but conditions remain highly dependent on location and sector.

Looking towards 2027, Moldova’s economic prospects will depend on whether industrial activity strengthens, inflation moderates and construction returns to growth. Higher earnings and increasing investment provide some encouragement, but rising energy expenditure and declining building activity demonstrate that the recovery remains fragile. For residential developers, industrial occupiers, retail operators and commercial property investors, Moldova presents opportunities within a developing economy, although the current conditions reinforce the importance of careful financial planning, realistic demand expectations and close attention to operating costs.

Hungary’s Economy Shows Signs of Recovery as Manufacturing and Consumer Spending Strengthen

Hungary’s economy is entering the final months of 2026 with improving industrial activity, higher household earnings and continued growth in consumer spending, although employment and construction figures reveal an uneven recovery. According to the Hungarian Central Statistical Office, economic output increased by 1.7% during the second quarter compared with the same period last year, while manufacturing production and retail sales recorded further increases during the summer. The figures suggest that economic conditions are improving in several important areas, but the outlook for businesses, developers and property investors remains influenced by differences between individual sectors.

The Hungarian economy expanded by 1.7% year on year between April and June 2026, with output increasing by 0.5% compared with the preceding quarter after seasonal adjustments. Growth across the first six months also reached 1.7%, indicating that the country maintained a positive economic trajectory during the first half of the year. Domestic consumption, manufacturing activity and investment decisions remain important influences on economic performance, particularly given Hungary’s close commercial connections with European industrial markets. The relatively moderate expansion suggests that the economy is recovering without experiencing a broad acceleration across all areas of activity.

Employment conditions remained relatively stable, although the number of people working declined slightly. Approximately 4.65 million people were employed in August, while unemployment stood at 4.7%, equivalent to around 229,000 individuals. During the June–August period, employment averaged 4.66 million, approximately 24,000 fewer than a year earlier, although the annual difference was within the statistical survey’s margin of error. The figures indicate that Hungary continues to maintain a comparatively high level of workforce participation, but businesses have not substantially increased recruitment despite improvements in economic activity.

Household earnings presented a more encouraging picture. Average gross monthly wages reached HUF 740,600 in August, an increase of 8.4% compared with the previous year, while average take-home earnings rose by 10% to HUF 519,900. After allowing for changes in consumer prices, net earnings increased by 8.6%, indicating a meaningful improvement in average purchasing power. The median gross wage stood at HUF 611,400, reflecting the difference between the national average and the earnings received by employees closer to the middle of the income distribution. Higher disposable income provides households with greater financial flexibility, although individual circumstances continue to vary according to employment, housing expenditure and family commitments.

Inflation remained relatively contained in September, with consumer prices increasing by 1.6% compared with the corresponding month of 2025. Prices were 0.2% higher than in August, while the measure excluding selected volatile items stood at 1.9% annually. The relatively modest increase in living costs, combined with stronger wage growth, has helped improve household purchasing power. However, changes in individual expenditure categories mean that the benefits are not experienced equally, particularly among households facing higher accommodation costs or other essential expenses.

Manufacturing activity strengthened considerably during August, with industrial production increasing by 8.7% compared with the same month last year. Output also rose by 1% from July after seasonal adjustments, while production across the first eight months of 2026 was 3.4% higher than during the corresponding period of 2025. Automotive manufacturing and the production of electronic and optical equipment contributed significantly to the improvement, although performance varied between industrial branches. The figures suggest that Hungary’s manufacturing economy is regaining momentum, but the concentration of growth in particular industries indicates that the improvement has not been evenly distributed.

The increase in industrial production is particularly relevant to Hungary’s logistics and manufacturing property markets. Automotive manufacturers, electronics companies and their suppliers require production facilities, storage capacity and distribution infrastructure to support their operations. Stronger output can improve the economic environment for industrial occupiers, although it does not automatically result in additional demand for commercial premises. Decisions concerning new factories, warehouses and logistics centres will continue to depend on international orders, energy expenditure, labour availability and the financial requirements of individual businesses.

Consumer spending also continued to expand during the summer. Retail sales volumes increased by 2.4% year on year in August, with non-food retailers recording growth of 5% and food retailers achieving a smaller increase of 0.5%. Online and mail-order purchases rose by 12%, while total retail sales during the first eight months of the year were 4.3% higher than in the corresponding period of 2025. Despite these annual improvements, monthly sales declined by 0.7% from July after seasonal adjustments, indicating that consumer demand continued to fluctuate.

For Hungary’s shopping centres and retail parks, stronger household earnings and rising consumer expenditure provide a potentially supportive environment. Improving purchasing power can encourage spending on clothing, household products and other non-essential goods, benefiting retailers and service providers. However, the continued expansion of online shopping also influences the way consumers purchase products and how retailers organise their operations. Property owners must therefore consider changing customer behaviour, tenant requirements and competition between physical stores and digital distribution channels when evaluating future investments.

Construction activity presented a more complicated picture. Total output increased by 21.9% year on year in August and by 14% compared with July after seasonal adjustments. However, the substantial annual increase was driven primarily by infrastructure projects, where activity more than doubled against a relatively weak comparison period. Construction involving buildings declined by 9.6%, while the volume of new contracts and the value of outstanding work also weakened. The figures demonstrate that the strong headline increase in construction output did not represent an improvement across every part of the industry.

Residential development nevertheless recorded increased activity during the first half of 2026. Hungary completed 6,278 new homes between January and June, representing growth of 22% compared with the corresponding period last year. Building permits and simplified construction notifications covered 16,588 homes, an increase of 29%. Budapest accounted for 2,224 completed properties, maintaining its importance within the national housing market. Although the increases partly reflected a relatively weak comparison period, they indicate that developers continued delivering homes and preparing additional residential projects.

The outlook for Hungary’s housing market will depend on whether improving household earnings translate into stronger purchasing demand. Higher real wages may support affordability for some buyers, but property prices, mortgage conditions and regional income differences remain important considerations. Developers must also evaluate construction costs, financing requirements and the availability of suitable development sites. The increase in residential permits suggests that additional projects are being prepared, although the number of approved homes does not necessarily indicate how many will ultimately be completed.

Office property demand remains closely connected to corporate investment, employment conditions and the performance of business services. Budapest continues to serve as Hungary’s principal office market, accommodating international companies, professional services and domestic businesses. Although economic growth provides a positive background, the slight reduction in employment suggests that companies may remain selective when considering additional accommodation. Demand for modern office premises will depend on building efficiency, location, operating costs and the requirements of individual occupiers.

The wider investment environment is influenced by the relationship between economic growth, inflation and financing conditions. Lower inflation can provide greater predictability for household expenditure and business costs, while stronger industrial production may improve confidence among manufacturers and their suppliers. However, the contrasting construction figures underline the importance of examining individual sectors rather than relying exclusively on national economic indicators. Commercial property investors will continue to assess rental income, tenant stability, development expenditure and financing costs when considering acquisitions or new projects.

Looking towards 2027, Hungary’s economic prospects will depend on whether industrial growth continues, household spending remains resilient and construction activity becomes more consistent. Rising real wages and stronger retail sales provide encouraging indications for domestic demand, while employment conditions remain broadly stable despite a slight reduction in the number of people working. The difference between expanding infrastructure construction and declining building activity illustrates the uneven nature of the country’s recovery. For commercial property developers, investors and occupiers, Hungary continues to present opportunities across industrial, residential, retail and office markets, but future investment decisions will require careful assessment of individual locations, financial conditions and underlying demand.

Poland’s Economic Growth Faces New Test as Consumer Confidence Weakens and Investment Conditions Evolve

Poland enters the final quarter of 2026 with its economic outlook shaped by domestic consumption, industrial performance, employment conditions and the cost of living. While the country’s manufacturing, construction and service industries remain important sources of economic activity, the latest consumer confidence figures indicate growing concerns among households about the direction of the economy. Data released by Statistics Poland on 21 October show that perceptions of current conditions and expectations for the coming months have deteriorated, creating additional uncertainty for businesses and property investors preparing their strategies for 2027.

Economic growth remains a central consideration for Poland’s investment environment, particularly given the country’s substantial domestic market and close trading relationships with other European economies. Household expenditure, industrial production, public infrastructure programmes and private investment all contribute to national economic performance. For commercial property developers and investors, changes in these activities influence demand for industrial facilities, offices, retail premises and residential accommodation. The extent to which economic expansion translates into additional property demand will depend on the performance of individual sectors and regional markets.

The labour market is another important factor in Poland’s economic outlook. Employment conditions influence household purchasing power and business expansion, while the availability of qualified workers affects manufacturing, logistics, construction and professional services. Although unemployment provides an indication of labour market conditions, employment trends and workforce participation are also relevant when evaluating the economy’s underlying strength. For property developers, labour availability can influence construction costs, project delivery schedules and the attractiveness of locations for new investment.

Household earnings remain particularly important in determining consumer spending and residential affordability. Average wages provide a measure of income across the economy, but their impact on living standards depends on how quickly earnings increase relative to consumer prices. Housing expenditure, food, utilities and transport costs all influence the amount households can allocate to discretionary purchases or long-term financial commitments. For residential developers, the relationship between income growth, mortgage costs and property prices remains an important consideration when assessing demand.

Consumer sentiment weakened noticeably in October. According to Statistics Poland, the indicator measuring households’ assessment of their present economic circumstances declined from minus 10.8 in September to minus 14.0, while the measure reflecting expectations for the coming months fell from minus 7.9 to minus 10.6. The deterioration was particularly pronounced in assessments of the national economy, with expectations for economic developments over the next year falling by 7.6 points. These results suggest that households are becoming more cautious about the broader economic outlook, even though their assessments of personal finances have changed comparatively little.

The weakening of consumer confidence has potential implications for Poland’s retail property market. Shopping centres, retail parks and other commercial destinations depend on household expenditure, making consumer expectations relevant to retailers’ expansion strategies and leasing decisions. Although the October survey does not establish that retail sales are declining, sustained caution could influence discretionary purchases and demand for certain goods and services. Property owners and investors will therefore be monitoring retail turnover, tenant performance and consumer spending patterns as they evaluate prospects for 2027.

Industrial production and logistics activity remain significant components of Poland’s economy and commercial property market. Manufacturing businesses, distribution operators and international companies require production facilities, warehouses and transport infrastructure to support their operations. Changes in export demand, energy expenditure, labour costs and supply-chain requirements can influence decisions about new facilities. Poland’s geographical position within European distribution networks continues to provide a basis for logistics activity, although future development will depend on occupier requirements and the financial viability of individual projects.

Construction activity provides another important indication of economic conditions. Residential development, commercial buildings, transport infrastructure and public investment programmes all contribute to demand for construction services and materials. Changes in construction output can affect employment, contractor capacity and development schedules, while financing costs and planning requirements influence the delivery of new projects. For property investors, the relationship between construction expenditure, expected rental income and market demand remains essential when evaluating development opportunities.

The residential property sector faces a combination of affordability and supply considerations. Household income, employment security, borrowing costs and the availability of suitable homes influence purchasing decisions, while developers must account for land prices, construction expenses and financing requirements. Economic uncertainty may encourage some prospective buyers to delay major commitments, although the consumer confidence survey does not directly measure housing demand. Regional differences in wages, employment and property prices will continue to influence residential market conditions across Poland.

Office property demand is closely connected to corporate investment, business services and employment trends. Warsaw remains the country’s largest office market, while Kraków, Wrocław, Gdańsk, Poznań and other regional centres accommodate significant business activity. Companies evaluating office requirements must consider workforce expectations, accommodation costs and operational efficiency. Demand for modern premises may remain supported by occupiers seeking higher-quality buildings, although national economic indicators alone cannot establish the direction of office leasing activity.

Inflation and financing conditions will also influence Poland’s economic prospects. Changes in consumer prices affect household purchasing power and business expenditure, while borrowing costs influence investment decisions and property affordability. For commercial real estate investors, financing expenses, rental income and expectations for future asset values are important considerations when assessing acquisitions and development projects. The interaction between inflation, interest rates and economic growth will therefore remain relevant as the market approaches 2027.

Looking ahead, Poland’s economic performance will depend on the resilience of domestic consumption, industrial demand, investment activity and employment conditions. The deterioration in consumer confidence during October introduces a note of caution, particularly for businesses exposed to household expenditure. However, sentiment indicators represent expectations rather than confirmed changes in economic output or spending. For the property industry, the coming months will provide a clearer indication of whether household concerns translate into changes in retail performance, residential demand or corporate investment. Poland’s commercial real estate market will continue to offer opportunities across several sectors, but investment decisions will require careful assessment of local economic conditions, financing costs and occupier demand.

Czech Economy Maintains Growth as Rising Wages Support Households Despite Renewed Inflation Pressures

The Czech Republic entered the final quarter of 2026 with continued economic growth, improving household earnings and relatively stable employment conditions, although renewed inflationary pressures and rising housing costs remain important challenges. Figures published by the Czech Statistical Office show that gross domestic product increased by 1.8% year on year during the second quarter, while average wages rose considerably faster than consumer prices. The combination suggests that domestic purchasing power has strengthened, providing support for consumer spending and business activity as companies and investors prepare for 2027.

Economic output expanded by 1.8% between April and June 2026 compared with the corresponding period of 2025. Although growth remained positive, the pace was below the 2.1% recorded in the first quarter and the 2.8% registered during the final quarter of 2025. Household consumption continued to contribute to economic activity, increasing by 2.7% year on year, while investment in fixed assets rose by 7.1%. The figures indicate that domestic expenditure and capital investment remained important sources of support for the economy, even as overall growth moderated.

Employment conditions remained comparatively favourable, with the number of people working increasing during the second quarter. National accounts figures indicate that employment rose by 1.5% year on year, while the number of employees measured on a full-time-equivalent basis increased by 0.7%. These developments suggest that businesses continued to maintain and expand their workforces despite the more moderate pace of economic growth. Labour availability remains an important consideration for employers, particularly in manufacturing, logistics, construction and professional services, where access to qualified personnel can influence investment and expansion decisions.

Average gross monthly earnings reached CZK 51,966 during the second quarter of 2026, representing an annual increase of 6.4%. After accounting for consumer price changes, wages rose by 4.3%, indicating an improvement in employees’ purchasing power. The average was CZK 3,105 higher than in the corresponding period of 2025. However, earnings continued to vary considerably between regions and industries, with Prague recording an average monthly wage of CZK 66,459, compared with CZK 44,476 in the Karlovy Vary Region. These differences remain relevant to residential affordability, regional consumer spending and the ability of businesses to attract employees outside the capital.

Consumer price developments presented a more mixed picture. Annual inflation increased to 2.5% in September, compared with 1.9% in August, although the overall price level remained unchanged from the previous month. The acceleration was influenced particularly by transport-related expenses, while housing and several service categories continued to record price increases. Residential rents were 6.1% higher than a year earlier, while accommodation services increased by 7.0% and restaurant services by 3.8%. Electricity and natural gas prices, by contrast, were lower than in September 2025.

The combination of rising wages and moderate inflation provides a potentially supportive environment for household consumption. With earnings increasing faster than prices during the second quarter, employees experienced an improvement in their average purchasing power. This development is relevant to retailers, shopping centre operators and retail park developers assessing consumer demand. However, the benefits are not distributed equally, and households facing higher housing costs or other financial commitments may experience different spending pressures. Retail property performance will therefore continue to depend on local income levels, employment conditions and the spending patterns of individual consumer groups.

The industrial and logistics property markets remain closely connected to the Czech Republic’s manufacturing economy and its relationships with European trading partners. Automotive production, engineering, electronics and other export-oriented industries influence demand for production facilities, warehouses and distribution infrastructure. Although economic growth has moderated, the increase in fixed investment suggests that businesses continued committing capital to equipment, facilities and other long-term assets during the second quarter. Nevertheless, national investment statistics do not establish how much expenditure was directed specifically towards commercial property development.

Residential property development faces a combination of improving household earnings and continued pressure from accommodation costs. The increase in real wages may strengthen the financial position of some prospective buyers, but affordability remains influenced by mortgage rates, property prices and the availability of suitable housing. The 6.1% annual increase in residential rents recorded in September also highlights the financial pressures facing tenants. For developers and investors, these conditions underline the importance of evaluating local purchasing power, construction expenditure and the relationship between rental costs and homeownership.

The construction sector is another important component of the economic outlook, particularly as investment activity influences demand for new commercial buildings, residential projects and infrastructure. Rising wages can support household demand, but they also contribute to labour expenses for contractors and developers. Construction companies must balance workforce availability, material prices, financing requirements and project schedules when evaluating new commitments. The broader increase in fixed investment provides an indication of continued capital expenditure, although the performance of construction activity itself must be assessed through separate industry statistics.

Office property demand will be influenced by developments in employment, corporate investment and the financial position of businesses. The increase in national employment provides a supportive economic background, particularly for companies considering additional staff or new premises. However, office leasing activity depends on factors extending beyond employment growth, including workplace strategies, operating costs, building efficiency and the availability of modern accommodation. Prague remains the country’s principal office market, while Brno and other regional centres continue to serve important business and technology activities.

Regional economic differences also remain significant. Average earnings in Prague were substantially above the national figure during the second quarter, while several regions recorded monthly wages below CZK 47,000. These variations influence residential purchasing power, retail expenditure and the attractiveness of different locations for employers. For property investors, understanding regional employment conditions and household income remains essential when evaluating development opportunities outside the largest urban centres.

Looking towards 2027, the Czech Republic’s economic prospects will depend on the continued recovery of household purchasing power, industrial demand, capital investment and conditions across European export markets. The combination of positive GDP growth, increasing employment and higher real wages provides a relatively supportive economic foundation. However, the acceleration of inflation in September and continued increases in housing-related expenses demonstrate that cost pressures have not disappeared. For commercial property developers, investors and occupiers, the latest figures suggest an environment in which opportunities remain available, but financial performance will depend on careful assessment of local demand, operating expenditure and the long-term competitiveness of individual assets.

The Health of a City: How Environmental Conditions Are Shaping Life in Five Central European Capitals

Environmental conditions are becoming an increasingly important factor in determining the attractiveness of Europe’s capital cities as places to live, work and invest. While economic opportunities, housing costs and infrastructure have traditionally dominated comparisons between urban centres, greater attention is now being paid to the quality of the air residents breathe, the water they consume, the availability of natural surroundings and the ability of cities to protect their populations from rising temperatures and pollution. An examination by CIJ.World of Prague, Bratislava, Budapest, Bucharest and Warsaw in 2026 reveals different approaches to environmental management, alongside challenges that continue to affect the health and everyday comfort of millions of residents.

Air pollution remains one of the most significant concerns across the five capitals. Although European cities have made progress in reducing emissions from transport, industry and domestic heating, concentrations of harmful particles and gases continue to present health risks. European environmental monitoring published in 2026 indicates that fine particulate pollution remains widespread, with many monitoring locations exceeding internationally recommended health thresholds. The consequences extend beyond respiratory illnesses, with prolonged exposure also associated with cardiovascular disease and other serious medical conditions. For residents considering where to live, the difference between a property beside a heavily trafficked road and one situated in a quieter, greener neighbourhood can therefore be substantial.

Prague has several environmental advantages, particularly its established public transport system and extensive network of parks, woodland and other vegetated areas. Trams, metro services and buses provide alternatives to private vehicles, while green corridors and recreational areas contribute to the city’s residential appeal. Municipal planning information identifies approximately 834 hectares of established parks and hundreds of kilometres of streets containing trees. Nevertheless, these environmental benefits are not distributed evenly. Densely developed central districts and locations experiencing substantial redevelopment face challenges involving traffic, limited vegetation and the accumulation of heat during summer. As former industrial and railway properties are transformed into residential and commercial districts, the integration of public greenery, shaded streets and environmentally responsible building design is becoming increasingly important.

Bratislava benefits from a distinctive geographical setting, with the Danube, surrounding forests and the Little Carpathians providing access to natural environments close to the urban area. These features offer recreational opportunities and contribute to the city’s environmental character. However, proximity to nature does not automatically guarantee favourable living conditions throughout the capital. Heavily developed neighbourhoods experience different levels of traffic exposure, summer temperatures and access to vegetation. Municipal assessments have identified parts of Staré Mesto, Ružinov and Petržalka as particularly vulnerable to excessive heat. During 2026, the city introduced a network of more than 30 publicly accessible locations where residents could find relief during hot weather, demonstrating the growing importance of practical measures designed to protect people from extreme temperatures.

Budapest faces a more complex combination of environmental pressures associated with its transport network, residential heating systems and densely developed urban districts. Pollution generated by vehicles and heating remains a concern, particularly where traffic is concentrated and buildings have limited energy efficiency. During October 2026, municipal authorities presented proposals for a revised programme intended to improve air conditions across Budapest and neighbouring settlements. The initiative recognises that environmental problems extend beyond administrative boundaries, with commuting patterns, heating emissions and regional activities influencing conditions throughout the metropolitan area. Budapest’s residential environment also varies considerably between its busy central streets, riverside districts and greener neighbourhoods extending towards the surrounding hills.

Bucharest continues to face challenges involving traffic emissions, summer heat and the condition of its urban vegetation. The Romanian capital’s dense road network and extensive built environment contribute to environmental pressures that can be particularly noticeable during periods of high temperatures. Authorities have sought to improve their understanding of local pollution through the introduction of additional monitoring equipment, including sensors positioned near schools and medical facilities. The expansion of environmental observation is important because pollution levels can differ considerably between neighbourhoods and even individual streets. Meanwhile, proposals to develop a wider network of protected and connected green areas around Bucharest could improve access to nature and strengthen the city’s ability to cope with climate-related pressures, although the eventual benefits will depend on implementation.

Warsaw has adopted a more direct approach to reducing pollution associated with older vehicles. The city’s designated low-emission traffic area, introduced in 2024, entered a further stage of implementation at the beginning of 2026, tightening access requirements for certain petrol and diesel vehicles. The programme is intended to reduce harmful emissions in areas experiencing substantial traffic activity. Official environmental assessments have also recorded improvements in some air quality measurements, including compliance with applicable annual limits for particulate pollution and nitrogen dioxide during 2024. However, meeting existing regulatory requirements does not necessarily mean that pollution has fallen to levels considered optimal for long-term human health. Continued monitoring will be necessary to determine whether transport restrictions produce lasting improvements.

Access to safe drinking water represents another essential consideration when comparing the environmental quality of these capitals. Modern treatment facilities, reliable distribution networks and regular testing are fundamental to protecting public health. Warsaw’s municipal water provider published monitoring results during 2026, while sanitary assessments confirmed compliance with relevant requirements for the samples and parameters examined. Across the wider region, however, comparisons must also consider the age and condition of residential plumbing. Water that meets official standards when entering a distribution system may encounter additional risks within older buildings, particularly where internal pipework has not been modernised. Consequently, the environmental quality of individual residential properties cannot always be determined from municipal infrastructure performance alone.

Urban greenery is another area where appearances can be misleading. A capital surrounded by forests may appear environmentally attractive, yet residents living in densely populated neighbourhoods might have limited access to parks within walking distance. Equally, a city with smaller natural areas distributed throughout residential districts may provide more frequent opportunities for outdoor activity and relief from urban temperatures. The quality, accessibility and maintenance of green spaces are therefore as important as their total area. Trees along streets, vegetation within residential developments and connections between parks can also improve the experience of moving through a city without relying on private transport.

Noise pollution deserves greater attention in assessments of urban living conditions. Road traffic, aircraft movements, railway operations and construction activity can create persistent disturbances, particularly in residential areas situated close to major transport infrastructure. Long-term exposure to excessive noise is associated with disrupted sleep, stress and increased risks to cardiovascular health. The five capitals contain neighbourhoods with substantially different acoustic environments, making it difficult to establish meaningful comparisons using general citywide descriptions. For prospective residents and property investors, understanding the immediate surroundings of a building may be more informative than relying on a city’s overall environmental reputation.

Climate conditions are also changing the requirements for healthy urban development. Extended periods of high temperatures can make densely constructed neighbourhoods uncomfortable, especially where buildings retain heat overnight and public spaces provide little shade. Older residents, young children and people with existing medical conditions may be particularly vulnerable. Across Central and Eastern Europe, local authorities are increasingly considering the role of vegetation, water management, building materials and public cooling facilities in reducing these risks. The issue is especially relevant to residential development, where decisions about insulation, ventilation, landscaping and building orientation can influence living conditions for decades.

The environmental performance of housing itself represents a further consideration. Poor ventilation, dampness, mould, inadequate insulation and excessive indoor temperatures can affect residents even in cities with relatively favourable outdoor conditions. Older apartment buildings may require substantial investment to improve energy performance and internal comfort, while newly constructed properties are increasingly expected to incorporate measures addressing overheating, energy consumption and water efficiency. For the property sector, this creates a closer relationship between environmental standards, building quality and long-term residential attractiveness.

Waste collection, energy infrastructure and the management of natural resources also contribute to the wider environmental picture. Reliable municipal services, effective recycling systems and cleaner energy production can reduce pollution and improve urban cleanliness. Nevertheless, these factors should be distinguished from conditions that directly affect residents in their immediate surroundings. A city may have ambitious environmental targets and extensive investment programmes while still experiencing substantial traffic emissions, inadequate greenery or uncomfortable residential environments. The effectiveness of environmental policy ultimately depends on measurable improvements rather than the scale of announced commitments.

The comparison of Prague, Bratislava, Budapest, Bucharest and Warsaw illustrates why identifying the healthiest capital requires more than examining individual environmental achievements. Prague benefits from an extensive public transport network and established green infrastructure. Bratislava offers access to substantial natural surroundings while developing measures to address heat exposure. Budapest is pursuing wider cooperation to reduce pollution across its metropolitan area. Bucharest is expanding environmental monitoring and considering additional green infrastructure, while Warsaw is implementing restrictions intended to reduce emissions from older vehicles. Each city has identifiable strengths, but none can be declared the healthiest on the basis of these measures alone.

For real estate investors, developers and occupiers, environmental quality is becoming an increasingly relevant component of location assessment. Residential demand may be influenced not only by access to employment, schools and transport, but also by pollution exposure, neighbourhood greenery, noise levels and the ability of buildings to remain comfortable during extreme weather. These characteristics can vary significantly within the same city, meaning that environmental assessments conducted at district or street level may provide greater practical value than broad comparisons between capitals.

The findings also demonstrate the importance of distinguishing environmental commitments from actual living conditions. New parks, cleaner transport systems and climate adaptation programmes can improve urban environments, but their effects must be measured over time. Similarly, a city’s proximity to forests or rivers does not necessarily compensate for pollution, traffic congestion or inadequate public space within its residential neighbourhoods. Reliable comparisons require consistent information on air quality, drinking water, vegetation, noise, temperature exposure and housing conditions.

As Central and Eastern European capitals continue to develop, the relationship between environmental quality and urban competitiveness is likely to strengthen. Cities that succeed in reducing pollution, improving access to nature and protecting residents from increasingly difficult climatic conditions may become more attractive places to live and invest. The central question is no longer simply which capital has the largest parks or the most ambitious environmental programme, but which can consistently provide the healthiest everyday environment for the people who call it home.

Source: CIJ.World Research & Analysis Team

Slovakia’s Tourism Economy Reaches New Financial High Despite Fewer Visitors

Slovakia’s tourism industry achieved its strongest nominal financial performance on record in 2024, generating €3.2 billion in direct economic output measured by GDP, according to figures published by the Statistical Office of the Slovak Republic on 21 October 2026. The results highlight the growing financial importance of hospitality, accommodation and visitor-related services, although the number of tourism trips remains considerably below levels recorded before the pandemic.

Tourism accounted for 2.5% of Slovakia’s total GDP in 2024, its highest proportion since 2020, while the sector generated €2.7 billion in direct gross value added. Despite reaching new financial highs, tourism’s contribution to the wider economy remained below the proportions recorded during the stronger years preceding 2020. The difference reflects broader economic growth, changes in tourism activity and adjustments to statistical calculations.

The combined production of industries associated with tourism reached approximately €13.4 billion, exceeding the €10 billion recorded in 2019 for the third consecutive year. Accommodation providers, restaurants and passenger transport businesses remained central to the industry’s economic contribution. Together, these activities represented approximately 60% of tourism’s direct gross value added, demonstrating the importance of hospitality facilities and transport infrastructure to the sector.

Visitor expenditure also increased substantially, reaching €8.8 billion in 2024, approximately €1.2 billion above the previous year and €2 billion higher than in 2019. Domestic travellers spent €3.5 billion within Slovakia, while international visitors contributed €2.3 billion. Spending by Slovak residents travelling abroad approached €2.9 billion, reflecting particularly strong growth in outbound tourism expenditure.

The increase in spending was not accompanied by a comparable recovery in visitor numbers. Slovakia recorded approximately 55 million domestic, inbound and outbound tourism trips in 2024, representing a 1.4% annual decline and remaining more than 22% below the 71 million trips registered in 2019. Domestic travel accounted for approximately 32 million trips, falling 6.4% compared with the previous year, while international arrivals and outbound journeys each increased by around 6%.

For Slovakia’s hotel and hospitality property market, the figures suggest that higher expenditure per journey has become an increasingly important feature of the tourism economy. Accommodation represented 24.2% of spending by visitors travelling within Slovakia, while restaurants and other food services accounted for 18.6%. These expenditure patterns are relevant to hotel operators, hospitality investors and developers assessing the potential for new accommodation projects and upgrades to existing properties.

Employment figures presented a more restrained picture. Approximately 172,000 people worked in tourism-related industries during 2024, a marginal annual decrease of 0.3%. Employees accounted for 85% of the workforce, with self-employed individuals representing the remainder. Food and beverage businesses employed approximately 68,000 people, while passenger transport accounted for another 20,000. Health resorts recorded employment growth of 7.1%, contrasting with reductions in accommodation, transport and several other tourism activities.

The latest statistics provide a useful indication of the financial scale of Slovakia’s hospitality economy as property owners and investors consider future opportunities. However, the combination of record nominal expenditure and lower travel volumes also underlines the importance of distinguishing higher prices and spending per trip from growth in visitor demand. For the hotel and tourism property sectors, future investment decisions will depend not only on expenditure trends but also on occupancy, operating costs, profitability and the ability to attract visitors throughout the year.

Polish Households Turn More Cautious as Economic Uncertainty Clouds Spending Outlook

Polish households became noticeably more pessimistic about the country’s economic prospects in October 2026, raising questions about the outlook for consumer spending and the potential consequences for the retail and property sectors. Figures published by Statistics Poland on 21 October show that confidence weakened across every category measured, with concerns about the wider economy increasing more sharply than worries about household finances.

The indicator measuring consumers’ assessment of their present circumstances declined from minus 10.8 in September to minus 14.0 in October, representing a monthly deterioration of 3.2 points. Compared with October 2025, the reading was 3.1 points lower. Expectations for the months ahead also weakened, with the forward-looking measure falling from minus 7.9 to minus 10.6, suggesting that households anticipate a more challenging economic environment as Poland approaches 2027.

The most significant change concerned perceptions of the national economy. Assessments of economic developments over the previous 12 months fell by 6.9 points to minus 29.6, while expectations for the coming year declined by 7.6 points to minus 25.3. These movements indicate that consumers are becoming increasingly concerned about the country’s overall direction, even though their assessments of their personal financial circumstances have changed comparatively little.

Household finances showed greater stability than the broader economic indicators. Expectations for personal finances over the next year declined by just 0.5 points to minus 5.2, while assessments of financial developments over the preceding year slipped marginally to minus 7.3. However, the measure reflecting consumers’ willingness to make substantial purchases weakened from minus 1.6 to minus 2.9, suggesting greater caution towards expenditure on higher-value goods and services.

For Poland’s commercial property market, the figures introduce an additional consideration for shopping centre operators, retail park developers and investors assessing future consumer demand. Although weaker confidence does not necessarily translate into an immediate reduction in retail sales, prolonged uncertainty could influence discretionary expenditure and the performance expectations of retailers. This may become particularly relevant when occupiers evaluate expansion plans, new store locations and leasing commitments for 2027.

The findings could also have implications for residential developers, particularly if concerns about economic conditions begin influencing decisions on major financial commitments. However, the survey does not directly examine housing purchases or mortgage demand, meaning that any effect on residential transactions remains uncertain. Employment conditions, financing costs, household income and housing affordability will continue to play important roles in determining purchasing activity.

The research also examined how developments in Ukraine are influencing Polish consumers. In October, 27.8% of respondents considered the situation a serious threat to Poland’s economy, compared with 27.2% in September, while another 41.6% assessed the economic risk as moderate. Overall, 54.9% indicated that developments in Ukraine had influenced their responses to the survey to a moderate or significant extent. These findings suggest that regional geopolitical uncertainty remains an important consideration in how households evaluate economic stability and their financial outlook.

The October results come at a time when Poland’s property industry is preparing investment, development and leasing strategies for the coming year. While the survey provides no direct evidence of declining property demand or retail turnover, the broad deterioration in sentiment highlights the importance of monitoring household expenditure and economic expectations. For developers, landlords and investors, the coming months will help establish whether October’s weaker confidence represents a temporary change in attitudes or the beginning of a more sustained period of consumer caution.

European Laboratory Properties Attract Institutional Attention as Investors Assess Specialist Real Estate Risks

Europe’s specialised laboratory and research property market is attracting greater attention from institutional investors seeking opportunities beyond conventional commercial real estate. However, differences in building specifications, tenant requirements and operating arrangements mean that investment risks can vary considerably between properties. A new study published by HELIX alpha examines these distinctions and identifies the factors investors should consider when evaluating facilities used by pharmaceutical, biotechnology and other research-intensive businesses.

The Hamburg-based investment and advisory platform released its research on 22 October 2026, examining how laboratory buildings and related scientific facilities can fit within institutional property portfolios. The analysis highlights the importance of understanding who finances specialist equipment, who manages the premises and how closely the financial performance of an investment depends on the activities of its occupiers. Unlike conventional office buildings, research properties frequently require substantial technical infrastructure and modifications tailored to particular scientific activities.

One approach involves property owners delivering buildings with the structural and essential technical systems needed to accommodate laboratory operations, while occupiers fund much of the specialised internal installation and scientific equipment. Such arrangements can provide investors with rental income supported by longer lease commitments, although the financial strength of the tenant and the adaptability of the property remain important considerations. At the other end of the market are facilities offering fully equipped laboratory accommodation together with operational services, allowing companies to access research infrastructure without making substantial initial investments in their own premises.

These different arrangements create distinct financial exposures. Properties occupied by established pharmaceutical or biotechnology companies under long-term agreements may offer relatively predictable rental income, depending on tenant creditworthiness and lease conditions. Facilities serving smaller research businesses can provide greater operational flexibility but may expose owners or specialist operators to higher management costs, changes in occupancy and the financial uncertainty associated with early-stage companies. Investors must therefore assess laboratory property according to its operating structure rather than treating the sector as a single investment category.

The technical characteristics of buildings are another important consideration. Research facilities can require advanced ventilation, specialist electrical systems, temperature controls, enhanced safety arrangements and infrastructure capable of supporting demanding scientific processes. These requirements can increase construction and refurbishment expenditure compared with conventional commercial premises. They may also create challenges when an existing tenant leaves, particularly if the building has been designed around highly specific activities that are difficult to accommodate for a replacement occupier.

Location is equally important, although successful research destinations do not necessarily correspond with Europe’s largest commercial property markets. Cities such as Heidelberg, Oxford and Leiden have developed recognised concentrations of universities, research institutions, pharmaceutical businesses and specialist service providers. These networks can generate demand for laboratory accommodation by bringing together scientific expertise, commercial funding and businesses engaged in research and development. For property investors, the strength of these local relationships can influence both occupancy prospects and the ability to secure replacement tenants.

The study also examines the potential stability associated with research occupiers that have invested heavily in adapting their premises. Relocating scientific operations can involve substantial expenditure, technical disruption and regulatory considerations, making certain businesses less inclined to move frequently. Nevertheless, such commitments do not eliminate investment risk. The financial position of the occupier, the remaining lease period and the property’s suitability for alternative users remain essential elements of assessing future income security.

HELIX alpha argues that Europe has opportunities to attract additional long-term investment into the buildings required to support scientific innovation. Although funding is available for research programmes and the development of biotechnology businesses, financing the specialised property infrastructure needed to accommodate these activities presents a separate challenge. Institutional investors could potentially contribute to meeting this requirement by providing capital for suitable laboratory and research facilities, provided the underlying property characteristics align with their investment objectives.

Martin Eberhardt FRICS, Founder and CEO of HELIX alpha, emphasises that investment decisions must distinguish between buildings leased to established businesses and facilities providing laboratory accommodation and services to emerging companies. The financial characteristics of these properties can differ substantially, particularly regarding operational responsibilities, tenant stability and the amount of capital required after acquisition.

Patrick Schlump, Managing Partner of HELIX alpha, similarly identifies the relationship between lease arrangements, occupier financial strength, technical expenditure and location quality as central to determining whether a property is appropriate for institutional investment. The research suggests that these considerations should be evaluated collectively, rather than relying on the broader growth prospects of the biotechnology and pharmaceutical industries.

For Europe’s commercial property sector, the findings highlight the potential for research-related facilities to develop into a more established specialist investment market. Demand for scientific accommodation is influenced by pharmaceutical research, biotechnology development and the expansion of innovation networks, but individual properties can have significantly different financial and operational characteristics. Investors entering the sector must therefore consider the technical requirements of laboratory buildings alongside the commercial fundamentals traditionally applied to income-producing real estate.

The study concludes that institutional participation could support the development and modernisation of Europe’s scientific property infrastructure. However, the investment case depends on selecting buildings with appropriate technical capabilities, financially sustainable occupiers and locations capable of maintaining demand over time. Rather than viewing laboratory accommodation as a uniform asset class, the research encourages investors to distinguish between different property and operating arrangements when assessing opportunities for long-term capital deployment.

Prague Housing Market Sees Fewer Transactions Despite Rising Prices and Expanding Supply

Prague’s residential property market is experiencing a shift in buyer activity, with sales of newly developed apartments declining during 2026 despite continued increases in prices and a growing selection of available properties. Developers sold 5,350 new apartments during the first nine months of the year, representing an 11% reduction compared with the same period in 2025. Nevertheless, purchasing activity remained more than 20% above the ten-year average, indicating that demand continues to be relatively strong by historical standards. The findings are based on research published on 21 October by Central Group, Skanska Residential and Trigema.

During the third quarter, approximately 1,600 new apartments were purchased in Prague, 6% fewer than in the corresponding period last year. The developers identified higher borrowing costs, stricter financing conditions for investment properties and uncertainty about future economic developments as factors influencing purchasing decisions. Despite the annual decline, quarterly sales have exceeded the long-term average of approximately 1,500 apartments for eleven consecutive quarters. The figures suggest that demand has moderated from recent levels without returning to the weaker conditions experienced during earlier market cycles.

Property prices continued to move upwards. The average advertised price of newly developed apartments reached CZK 193,814 per square metre during the third quarter, an increase of 3% compared with the previous quarter and 12% year on year. The average total asking price for an apartment reached CZK 11.8 million. Prices achieved in completed transactions were somewhat lower, averaging CZK 186,408 per square metre, although this represented an increase of 2% quarter on quarter and 10% compared with the previous year. The continued difference between asking and transaction prices illustrates the importance of distinguishing advertised property values from the amounts buyers ultimately pay.

Residential sales remained concentrated in a limited number of Prague districts. Approximately 75% of apartments purchased during the first nine months were located in Prague 5, 8, 9 and 10, reflecting the concentration of major development activity in these areas. Smaller apartments continued to attract the greatest interest, with studio-style 1+kk properties and two-room 2+kk units accounting for almost three-quarters of transactions. These layouts generally require a lower overall financial commitment than larger apartments and can also appeal to purchasers seeking rental investment opportunities. Prague 9 and Prague 10 recorded the lowest average prices for new apartments, while Prague 1 remained the most expensive location.

The distribution of sales among developers also highlighted the importance of established residential projects. According to market intelligence company BuiltMind, Central Group recorded the largest number of new apartment transactions during the third quarter, followed by Finep and UDI Group. Among individual developments, Tesla Hloubětín, Nové Chabry and British Quarter were identified as the strongest-performing projects. Their results indicate that large residential schemes continue to account for a substantial proportion of purchasing activity, particularly in districts where new housing construction is concentrated.

At the same time, the number of apartments available for purchase increased significantly. By the end of September, developers were marketing approximately 7,200 new homes across Prague, representing growth of 12% compared with the preceding quarter and 26% year on year. The increase was partly associated with additional residential schemes and subsequent development phases entering the market following planning approvals. Although the larger selection provides prospective buyers with more options, the simultaneous rise in prices suggests that the additional availability has not yet translated into a general reduction in property values.

The relationship between supply and affordability remains a central issue for Prague’s residential market. Developers continue to face expenditure associated with land acquisition, construction, financing and project preparation, all of which influence the prices required to make new developments financially viable. Central Group Chairman Dušan Kunovský has maintained that residential property remains attractive to purchasers seeking long-term financial security and protection against inflation. However, continued price increases also raise questions about the ability of households to purchase newly built accommodation, particularly when earnings do not increase at a comparable rate.

Other developers have expressed greater concern about the limits of buyer affordability. Ekospol Chairman Evžen Korec believes that prices are approaching levels beyond the financial reach of a substantial proportion of prospective purchasers. He expects greater pressure on developers to limit the total cost of individual homes, potentially resulting in smaller apartment layouts. Such a development could make some properties more accessible in terms of overall purchase price, although it would also influence the amount of living space available to residents.

The future availability of new housing remains dependent on the development pipeline and the ability of projects to progress through planning and construction. Skanska Residential Chairman Petr Michálek has identified limited access to suitable development land, administrative delays and rising construction expenses as continuing obstacles. These factors could restrict the number of homes entering the market in subsequent years, even though the current volume of advertised apartments has increased. The recent expansion in supply may therefore reflect the timing of individual project launches rather than a lasting improvement in Prague’s housing availability.

However, some market participants expect additional residential schemes to increase the selection of new apartments. BuiltMind Chief Operating Officer Tomáš Kajúch anticipates further growth in available properties as developers introduce additional phases of existing projects. Sekyra Group has commenced construction of the third stage of Smíchov City, which is planned to deliver approximately 800 apartments. UDI Group is also preparing Building A within its Side Smíchov Living development, with construction scheduled to begin in the second quarter of 2027. These projects represent part of the future residential pipeline, although their eventual contribution to completed housing supply will depend on construction progress and delivery schedules.

The latest market figures present a contrasting picture of Prague’s residential development sector. Apartment sales have declined compared with 2025, yet purchasing activity remains above historical averages, while both advertised and achieved prices continue to increase. The expansion in available properties provides greater choice, but affordability remains a significant consideration for households and developers alike. As the market approaches 2027, the relationship between new supply, construction expenditure and buyers’ financial capacity will be central to determining whether transaction volumes recover or purchasing activity becomes increasingly selective.

front page info
LATEST NEWS