Poland: What is the prevailing mood on the housing market at the beginning of 2026?

What is the prevailing sentiment in the housing market at the start of 2026? How is the new-build residential segment performing this year, and how do companies evaluate their sales results from last year? What expectations have developers set for 2026, and is the market likely to see any significant structural changes?

Tomasz Kaleta, Managing Director of Sales and Marketing at Develia

Last year, we again recorded record sales of 3,345 units, 5 per cent more than in 2024, exceeding our annual target. At the same time, we handed over 2,959 flats to customers, the highest number in the company’s history, 3 per cent more than in 2024.

In 2026, we expect further gradual growth in sales, which will be supported by lower financing costs, wage growth and a relatively stable economic outlook. With moderate growth in flat prices – on average 1-2 per cent above inflation – the market will gradually move towards a better balance between supply and demand. The demand side will be influenced by decisions on further interest rate cuts and increased availability of financing. On the supply side, however, low availability of attractive land and long and complex administrative procedures delaying the launch of new projects will remain a constraint.

The residential property market in Poland remains fragmented, so the sector will continue to undergo consolidation. Although our priority is organic growth, we do not rule out further strengthening it through acquisitions and joint ventures.

Grzegorz Smoliński, Member of the Management Board of Dom Development

The past year was very successful for the Dom Development Group, both in terms of sales and apartment deliveries. The fourth quarter brought record sales of 1,232 units in our history. It was also the sixth consecutive quarter in which we sold at least 1,000 units, confirming the stable demand for our offer and its high attractiveness. In total, in 2025, we found buyers for 4,448 units, which is our best annual result in 30 years of operation.

For 2026, we expect to further strengthen our leading position in the markets where we operate. To this end, we are consistently developing our residential offering and land bank. We systematically purchase land for new, promising projects and regularly secure further transactions, which gives us the comfort of medium- and long-term planning.

From the perspective of the entire industry, a further decline in interest rates is expected, which may translate into increased interest in purchasing flats. On the other hand, the growing complexity of the investment process as a result of new regulations will favour large entities with the appropriate competences. In addition, the relatively high level of supply, including a significant proportion of ready-to-move-in flats, may lead to new projects being launched in a more selective manner and translate into price pressure in some markets, such as Warsaw and the Tri-City.

Zbigniew Juroszek, President of the Management Board of Atal

The company ended the last quarter of 2025 with good sales results, with December being the best month of all. This is the result of the market recovery that we have been observing since the second half of last year.

In the coming months, the housing market will continue to be characterised by a large volume of supply, and as a result, the situation on the market will remain stable. Over time, however, supply will shrink as developers reduce the pace of new construction and fewer and fewer small and medium-sized developers remain active. This may also contribute to the consolidation of the highly fragmented property development market in Poland.

Demand will be stimulated by key macroeconomic factors, such as the generally good condition of the Polish economy and wage levels, low inflation and, as a result, increasingly attractive financing conditions for purchases following interest rate cuts. This cycle is unlikely to have ended, so we expect this parameter to improve further. Interest in purchasing new flats will continue to be supported by attractive promotions from developers, which have been stimulating the market for about a year now. However, as the range of discounts gradually runs out, there may be fewer and fewer of them, and customers will finalise transactions more quickly.

Demand, which was previously postponed due to high interest rates or in anticipation of decisions on buyer support programmes, will also have a positive impact on contracting. In general, we expect it to increase in 2026 and assume a result in the range of 2,500-3,000 flats sold. This should be facilitated by the current profile of our offer, in which flats ready for occupancy, which are more popular with customers, are beginning to predominate.

Newly launched projects will be offered at similar or increasingly higher prices, which will be influenced by their construction costs, lengthy permit procedures, persistently high land prices, as well as regulations and new technical and environmental requirements affecting developers’ activities.

Waldemar Olbryk, President of the Management Board of Archicom

Archicom is currently in a stable operational and financial condition, based on very good sales results achieved in 2025. The company sold nearly 2,850 flats, achieving its strategic goal. A particularly strong fourth quarter confirmed the effectiveness of the adopted business model and the accurate matching of the offer to the structure of demand, especially in the popular segment, which remains one of the drivers of the market. For 2026, the company has a prepared portfolio of projects and a flexible schedule for their launch, which allows it to adjust the scale and pace of development to current market conditions. Another important factor is the company’s 40th anniversary on the market. The experience gained in various phases of the economic cycle translates today into greater predictability of operations and the ability to plan for the long term.

From the perspective of the entire market, the availability of financing will remain a key factor in 2026. Expected further interest rate cuts should support credit demand and stabilise purchasing activity. At the same time, the market will continue to operate under the influence of structural supply constraints, including low availability of well-prepared land, quality locations and the risk of regulatory changes. In this context, a scenario of sudden breakthroughs, such as mass consolidation of the industry or a sharp slowdown in investment, is unlikely. More realistic seems to be moderate, controlled growth and further strengthening of the position of entities with the appropriate scale, financial and operational resources and the ability to act flexibly.

Mariusz Gajżewski, Head of Sales, Marketing and Communication, BPI Real Estate Poland

We are starting 2026 on a stable footing, with a plan for consistent development of the company’s presence on the Polish residential property market. 2025 was marked by strategic decisions, intensive work on preparations for investments and the finalisation of construction projects, such as Chmielna Duo in Warsaw and the first stage of Cavallia in Poznań. At the same time, we initiated new projects in the capital, such as PianoForte and the prestigious Moniuszki Tower office building, which we added to our portfolio with plans to transform it into a residential investment in the future.

Our assumptions for 2026 focus on further expansion in Warsaw, Poznań and Gdańsk, and the implementation of projects in the spirit of sustainable development. We expect that the development market may face consolidation, increased construction costs and changing demand. We estimate that demand for flats will remain stable or increase moderately. Whether the year will be a breakthrough for the industry depends primarily on the regulatory situation, credit costs and land supply in cities.

Andrzej Gutowski, Sales Director, Ronson Development

The year 2025 brought an improvement in the housing market. After a quieter start to the year, the following quarters saw a gradual recovery in demand, supported by further interest rate cuts, which significantly improved the availability of mortgages. For our company, it was an intense but successful year. We achieved our goals, and improving market conditions allowed us to consistently develop our offer and effectively respond to customer needs. We ended 2025 with solid sales results, selling a total of 542 units.

In 2026, we plan to start construction of approximately 1,000 units in six projects, both in new locations and in subsequent stages of ongoing investments. Warsaw will play a special role, where we have planned several important launches, but at the same time we are developing our portfolio in Wrocław, Szczecin and other large urban centres.

The consolidation process is largely complete, with some of the smaller, less well-prepared players having disappeared from the market. From the customers’ point of view, this is a positive development, as proven, reliable brands are playing a greater role. The market will not be supported by new government programmes, but at the same time there are no strong negative impulses in sight.

Andrzej Swoboda, Vice-President of the Management Board, CTE Group

We are entering 2026 with cautious optimism, but also with a great deal of realism. For the housing market, 2025 was a period of stabilisation after the very dynamic and uneven years that preceded it. From our company’s perspective, it was a challenging year, but a satisfactory one in terms of sales, especially in the segment of well-designed, energy-efficient flats located in proven parts of Wrocław. We are successfully completing the sale of rent-free flats on Bakaliowa Street in Wrocław.

We clearly saw that customers were making more careful decisions. The decision-making process became longer, price sensitivity increased, but at the same time, customers expected higher product quality and greater transparency of the offer. Projects well suited to the real needs of the market sold steadily.

For 2026, we have adopted assumptions for continued cautious development, and we plan to commence the first stage of our new investment located in the northern part of Wrocław. Could 2026 bring groundbreaking changes? Potentially yes, but not in one direction.

The key factors are interest rate policy, availability of financing, regulatory stability and investment implementation costs. We expect further consolidation of the industry, especially among smaller, less capitalised entities. We also do not rule out a temporary slowdown in new investments, which in the medium term may again affect supply and price pressure.

Zuzanna Należyta, Commercial Director at Eco Classic

We do not anticipate any drastic changes in the market. We have a fairly large oversupply, which must be reduced for prices to change, and this depends on sales growth. Despite the increased availability of credit, most of the loan agreements concluded after the interest rate cuts concerned refinancing or changes in the interest rate. For borrowers to return to the primary market, several more interest rate cuts are needed, as well as some time for customers to see that lower interest rates are here to stay.

Marcin Michalec, Managing Director, Okam Capital

We are starting 2026 with great optimism. First of all, in January 2026, the City Council voted in favour of the largest Lex in Poland for the first stage of our F.S.O. PARK investment on the site of the former Passenger Car Factory in Warsaw. This is the culmination of almost four years of work on this project, which will now allow us to proceed with the preparation of the project for a building permit.

In addition, we have many development plans, not only in Poland, but also on the Italian market. We will certainly face many new challenges.

In 2025, the housing market faced high supply and considerable interest from customers, but customers’ decision-making was prolonged. At the beginning of 2026, we are seeing signs of recovery. Our sales results in 2025 were at a satisfactory level for us; we can say that we have achieved our target.

Interest rate cuts by the Monetary Policy Council and the expected further easing of monetary policy in 2026 are gradually improving customers’ creditworthiness, which already translated into greater interest in flats in the last months of 2025. We anticipate that demand will grow in 2026, supported by improved financing conditions, rising wages and pent-up demand from previous periods. Our key assumption for 2026 is to continue our strategy of delivering high standards and building integrated communities. We focus on quality and tailoring our offer to the real needs of the market.

In terms of groundbreaking changes, 2026 is likely to bring a gradual consolidation of the development market. Smaller companies that have overestimated the market’s potential and built up excess supply may find it difficult to maintain financial liquidity. However, we do not expect dramatic price changes, but rather stabilisation with moderate growth at the level of inflation. The macroeconomic situation, further actions by the Monetary Policy Council and the final shape of the planning reform, which may significantly affect the availability of land for development, will be of key importance.

Witold Kikolski, member of the management board of MS Waryński Development S.A.

We are entering 2026 with moderate optimism, but at the same time with great investment caution, resulting from very demanding market conditions. The situation is particularly difficult in regional markets, such as Katowice, where high housing supply and strong competition significantly affect the rate of absorption of the offer and prolong the decision-making process on the part of customers. The market environment remains under pressure from financing costs and limited availability of mortgage loans, which further restricts demand.

In these conditions, our assumptions for 2026 are based on a selective approach to launching new investments, a focus on financial liquidity, and the quality and alignment of our offer with the real possibilities of the market. Any breakthrough changes in the development market, such as industry consolidation, a slowdown in new projects or significant price changes, will, in our opinion, depend primarily on the direction of interest rate policy, the availability of financing for customers and further regulatory decisions. These factors will largely determine the scale and pace of market improvement in the coming quarters.

Damian Tomasik, President of the Management Board of Alter Investment S.A.

We are entering 2026 in a mood of calm confidence, but without any illusions. Today, this market does not reward loud declarations – it rewards process, pace and risk control. I consider 2025 to be a good year, albeit a challenging one. Selection was key in terms of sales: what mattered was the quality of the transaction and the predictability of the project, not ‘volume at any cost’. With rising capital costs and regulatory changes, those who have projects ready to go are the biggest winners.

For 2026, we assume a continued focus on urban projects for multi-family housing and PRS, as well as consistent land refinement – from analysing absorption and risks, through organising the legal and planning status, to bringing projects to a stage where they can be implemented or sold.

Will 2026 bring a breakthrough? Yes, more in the form of polarisation than a single event. Good locations and well-prepared projects will become more expensive, while weaker projects will either stall or be sold at a discount. Industry consolidation is very real, as the cost of error is increasing. This depends mainly on the cost of financing, credit availability, land supply, and the predictability and efficiency of administrative procedures.

Photo: Wolne Miasto – Eco Classic
Source: dompress.pl
Logivest brokers lease of more than 5,000 sqm of logistics space in Hilden

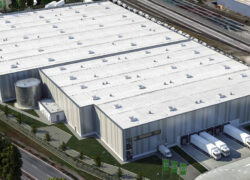
Logistics real estate consultancy Logivest has arranged a long-term lease for approximately 5,000 square metres of logistics and office space in Hilden, North Rhine-Westphalia. The property, located at Im Hock 14, is owned by the Schoppmann Group.

The tenant is a logistics service provider focused on e-commerce that was seeking its first logistics facility in the Düsseldorf region. According to Logivest, the Hilden location met the company’s requirements due to its proximity to the state capital and access to the nearby motorway junction.

Marlon Bäumler, Consultant Industrial and Logistics Letting at Logivest NRW GmbH, stated that Hilden has gained importance as a logistics location in recent years, citing its transport connections and relatively moderate rental levels compared with neighbouring cities.

The building includes several loading ramps and a covered external area of around 1,000 square metres designed for vehicle loading and unloading operations. The tenant is expected to take occupancy of the premises in February 2026.

Czech Housing Price Growth Slows, Quarterly Levels Largely Flat

Housing prices in the Czech Republic showed limited movement in the fourth quarter of 2025, with quarter-on-quarter values remaining broadly stable despite continued year-on-year growth. According to an analysis by the real estate platform Bezrealitky.cz provided to the Czech News Agency, prices of older apartments, single-family houses and rents increased by more than ten percent compared with the previous year, but changed little compared with the third quarter.

The report attributes the stabilisation partly to the composition of properties on the market. Higher-quality and more expensive units attracted strong demand and were sold more quickly, leaving a larger share of lower-priced or renovation-ready properties in listings. Analysts note that it remains uncertain whether this period of price stagnation will continue into the following quarters.

The average price of older apartments nationwide reached approximately CZK 118,500 per square metre in the fourth quarter. While this represented a double-digit increase compared with the same period a year earlier, the average price was unchanged from the previous quarter. Prague remained the most expensive market, with average prices exceeding CZK 155,000 per square metre and only marginal quarterly growth. Regional differences were more pronounced, with some areas recording moderate increases and others slight declines.

Hendrik Meyer, head of the EEC Group, which includes the Bezrealitky platform, stated that lower or declining asking prices in certain locations were influenced by limited supply and the mix of available properties. In some regions, specific apartment layouts were temporarily scarce, while in others sellers were more willing to negotiate on price.

The analysis also suggests that part of the price stabilisation in the apartment segment may be linked to shifting buyer preferences. Some households have increasingly considered purchasing family houses, where price growth has been slower in recent months. According to Meyer, the widening price gap between flats and older houses has made detached homes, even those requiring renovation, more financially attractive for certain buyers.

Average prices for single-family houses also remained broadly flat compared with the previous quarter, with a national average of roughly CZK 66,000 per square metre. Regional movements varied significantly, with notable declines recorded in the Karlovy Vary and Ústí regions, while selected areas such as Pilsen and Pardubice saw moderate increases.

Rental markets continued to show gradual upward pressure. Nationwide, average monthly rents rose slightly in the fourth quarter, reaching approximately CZK 374 per square metre. Prague recorded the highest rental levels, while regional cities displayed mixed trends, with some markets experiencing modest growth and others slight decreases.

Overall, the data indicate that while annual growth in housing and rental prices remained visible at the end of 2025, short-term momentum slowed, resulting in a period of relative stability rather than continued rapid increases.

Source: CTK

Czechia: Majority of young people doubt government will resolve housing crisis

Most young people in the Czech Republic do not believe the current government will significantly improve access to housing, despite expecting the state to play a role in addressing the issue. This follows a survey conducted by building materials producer Xella in cooperation with research agency Ipsos, involving 1,050 respondents aged between 18 and 30.

According to the findings, only 16 percent of respondents believe the government will succeed in improving housing affordability. A further 39 percent expect conditions to remain largely unchanged over the next four years, while 35 percent anticipate a deterioration. At the same time, 96 percent of those surveyed said they expect some form of state support to help them secure housing.

When asked about potential measures, roughly one third of participants supported the construction of affordable state-backed housing for young people. Nearly 30 percent favoured the introduction of interest-free housing loans, while around one fifth suggested government intervention to reduce apartment prices or mortgage costs.

High property prices were identified as the main barrier to home ownership by 69 percent of respondents. Expensive mortgages were cited by less than half, while 43 percent pointed to rising land prices and 39 percent mentioned insufficient income as key obstacles.

Housing affordability has worsened in the Czech Republic in recent years, according to international and domestic analyses. Rising property prices and rental costs have placed increasing pressure on household budgets, with young families and lower-income groups among those most affected. Prague continues to rank among the least affordable European capitals for housing, although some regional markets have also seen sharp price growth, partly due to increased investor interest.

The government coalition has announced plans to amend construction legislation with the aim of accelerating the approval process for large residential projects and recognising housing development as a public interest. It has also indicated that support schemes for young families, including preferential housing loans, are under consideration.

Source: CTK

Garbe Industrial extends lease with MBS Logistik at Port of Regensburg

Garbe Industrial has extended its lease agreement with logistics service provider MBS Logistik at a logistics property in the Port of Regensburg, Bavaria. MBS Logistik occupies approximately 7,000 square metres at the site, where it carries out storage, order picking and distribution services for industrial and commercial clients.

According to Garbe Industrial, the extension reflects continued tenant demand for modern logistics facilities. Company representatives noted that the agreement supports ongoing cooperation between the two parties.

The logistics building, completed in 2019, has a total area of nearly 19,000 square metres and is fully leased. Under the renewed contract, MBS Logistik uses around 5,900 square metres of warehouse space, 800 square metres of mezzanine storage and approximately 280 square metres of office space. The remaining areas are leased long term to another logistics operator.

The property is situated on a plot of about 34,400 square metres within the Port of Regensburg, close to the Danube and the port basin. The location provides road, rail and water transport connections. Access to the A3 and A93 motorways is available via the nearby Odessa-Ring and the B15 federal road, while freight railway tracks run directly alongside the logistics complex.

Cushman & Wakefield Echinox appointed to sell HempFlax agricultural portfolio in Romania

Cushman & Wakefield Echinox has been mandated on an exclusive basis to market and sell an agricultural portfolio in Romania owned by HempFlax Netherlands, a company active in hemp cultivation and processing. The assets are located in the Sebeș–Alba Iulia area.

The portfolio includes nearly 800 hectares of contiguous agricultural land situated close to an existing processing facility. The transaction also covers related agricultural equipment and machinery. According to the adviser, the scale and configuration of the land allow for various types of farming or agribusiness use.

The properties are positioned in a region known for industrial activity, with established automotive, wood-processing and food production operations nearby. Market participants note that agricultural land values in Romania remain below those in many Western European countries, which has supported investor interest in recent years.

HempFlax’s decision to divest its Romanian assets follows a shift in the company’s strategic priorities toward activities closer to its core Western European markets and a stronger focus on value-added processing rather than large-scale primary production.

Despite the company’s exit, the land and associated infrastructure remain available for potential agricultural or mixed agribusiness development. Cushman & Wakefield Echinox stated that both domestic and international investors are being targeted in the sales process.

HempFlax was founded in 1993 and operates hemp cultivation and processing facilities in several European countries, including the Netherlands, Germany and Romania, with production sites in Oude Pekela and Alba Iulia.

Scrap Export Restrictions from Ukraine Raise Concerns for Polish Steel Producers

At the start of 2026, companies in Poland’s steel sector are facing renewed uncertainty over the availability of key raw materials. For several years the industry has been under pressure from high energy prices, tighter environmental regulation and competition from producers outside the European Union. In this context, access to metal scrap — an important input for both steel mills and non-ferrous smelters — has become increasingly important for maintaining production levels and controlling costs. Ukraine has traditionally been one of the nearby sources of this material for Polish buyers.

The situation changed at the turn of the year when the Ukrainian government introduced export restrictions covering various categories of metal scrap for 2026. The decision effectively halted regular commercial shipments abroad unless specific exemptions are granted. For Polish manufacturers that had relied on Ukrainian supply, the immediate effect has been reduced availability and upward pressure on prices, alongside the need to identify alternative suppliers in other markets. Facilities that base their production largely on recycled inputs are particularly exposed to such disruptions.

Ukrainian authorities have explained the measure as a way to secure sufficient raw materials for domestic processing industries and to support local employment and tax revenues. Similar export controls on scrap have been used periodically by several countries in recent years, especially during times of economic strain or geopolitical tension. In this case, the timing has drawn attention because the European Union has simultaneously been encouraging shorter and more resilient regional supply chains for strategic materials.

The Polish government has indicated that it intends to address the issue at the European level, arguing that the sudden limitation on exports affects industrial planning and cross-border trade relationships. Officials have also signalled that the matter will be raised in bilateral discussions with Kyiv. From Warsaw’s perspective, the dispute is not only about the steel sector but also about the broader question of how trade preferences and market access should function when one side introduces unilateral restrictions.

Beyond the immediate industrial impact, the episode has added to an ongoing debate about the balance between national economic policy and international trade commitments. Ukraine benefits from preferential trade arrangements and extensive financial and political support from the European Union, yet it also retains the right to regulate the export of certain resources deemed strategically important. Supporters of the restrictions view them as a temporary protective step, while critics see them as a signal of growing economic nationalism.

For now, the practical outcome is a tighter regional scrap market and higher input costs for some European producers. Whether the restrictions will remain in place for the entire year or be adjusted under diplomatic or economic pressure remains uncertain. The development illustrates how decisions taken in one country’s domestic policy sphere can quickly ripple across neighbouring industries and supply networks.

Source: WEI-Warsaw Enterprise Institute

Jitka Steinmetz joins Manova Partners as Chief Operating Officer

Manova Partners has appointed Jitka Steinmetz as Chief Operating Officer, expanding its management structure in response to increasing operational and regulatory requirements in the real estate investment sector. In her new position, Steinmetz will be responsible for the company’s operational activities, with a focus on process development, organisational structures, governance and technological infrastructure.

Steinmetz brings more than 15 years of international management experience in senior operational roles. Prior to joining Manova Partners, she served as Chief Operating Officer at a digital strategy and software development company, where she also held the position of Managing Director. In that role, she oversaw operations across several European branches, managing approximately 1,500 employees and an annual sales volume of around €140 million. Earlier in her career, she worked as Director of Operations at McKinsey & Company, coordinating operational functions across multiple Central European markets.

Commenting on her appointment, Steinmetz said, “We are currently seeing significant changes around framework conditions for companies, particularly due to regulatory developments, technological advancements and intensifying organisational requirements. I look forward to bringing my experience to Manova Partners and working with the team to advance our operational structures.”

Florian Winkle, Co-CEO of Manova Partners, stated, “We are delighted to have gained such a high-calibre, experienced manager in Jitka Steinmetz. She will make a decisive contribution to the further expansion and success of Manova Partners. In her newly created role as COO, she will drive the strategic diversification of our business in a demanding market environment, master complex organisational challenges and ensure consistent improvement of our customer service offering.”

Deloitte study: majority of commercial real estate companies expect revenue growth in 2026

Most commercial real estate companies anticipate higher revenues in 2026, although expectations have moderated slightly compared with the previous year, according to the Deloitte 2026 Commercial Real Estate Outlook. The study indicates that 83 percent of respondents expect revenue growth in the coming year, down from 88 percent a year earlier, while 68 percent plan to increase operating expenses. In parallel, 65 percent foresee improvements in underlying market conditions such as access to capital, rental levels and vacancy trends, a marginal decline from last year’s figure of 68 percent.

Against this backdrop, nearly three-quarters of surveyed companies intend to raise their level of real estate investment during 2026. Inflation protection was cited as the primary motivation, followed by portfolio diversification and potential tax considerations. The findings suggest that companies continue to view property assets as a tool for balancing financial exposure in a volatile economic environment.

Regional sentiment varied. European respondents expressed the strongest confidence in market prospects, with around 70 percent expecting more favourable conditions in leasing, lending and capital market financing. Companies in the Asia-Pacific region were comparatively more cautious, with 63 percent anticipating improvements but close to one in five expecting conditions to worsen, particularly in relation to financing costs and capital availability. In North America, expectations were more neutral, with roughly a quarter of participants predicting stable trends in rents, vacancies and funding costs.

Overall industry sentiment, measured through Deloitte’s sector index, remained elevated at 65 points out of 100, significantly above levels recorded in 2023 and only slightly below last year’s peak. Respondents identified access to capital as the most influential macroeconomic factor for 2026, moving sharply up the ranking compared with the prior year. Other concerns included interest rates, financing costs, currency fluctuations and tax policy changes. Cybersecurity risks declined in perceived importance, while employee retention moved higher on the list of business challenges. International trade policy appeared as a newly identified risk, ranking particularly high among Asia-Pacific participants.

Developments in the real estate market are closely linked to the economic conditions in the respective market, so the optimism of the participants to the study indicates that they are adapting on the go to the volatility of the business environment they have faced over the recent years and are increasingly relying on the speed of reaction, while also quickly identifying long-term development opportunities. In Romania, real estate companies are counting on a gradual decrease in inflation and, implicitly, in financing costs this year, but also on the continuation of public investment, especially in infrastructure, which can generate increased demand in the real estate market (industrial, logistics, retail, offices, etc.),” said Irina Dimitriu, Partner at Reff & Associates | Deloitte Legal, and Real Estate Industry Leader at Deloitte Romania.

In terms of asset preferences, properties linked to the digital economy, including data centres and telecommunications infrastructure, ranked highest among investment targets. Logistics and warehousing moved into second position, while industrial and manufacturing assets slipped to third place. Office properties in both suburban and central locations improved their standing compared with the previous year, indicating a partial return of investor interest in the office segment.

The survey also noted a moderation in expectations surrounding artificial intelligence adoption within the sector. Around one fifth of respondents reported being at an early stage of implementation, while more than a quarter cited challenges such as technical limitations, limited expertise and organisational resistance.

The Deloitte 2026 Commercial Real Estate Outlook study was conducted among more than 850 commercial real estate companies worldwide, each managing assets exceeding USD 250 million, across Europe, North America and the Asia-Pacific region.

Source: Deloitte

WDP reports higher earnings and sets new growth targets through 2030

Warehouses De Pauw (WDP) reported increased earnings and continued leasing activity across its European logistics portfolio in its full-year 2025 results, while outlining a new five-year growth plan extending to 2030.

For 2025, the company achieved EPRA earnings per share of €1.53, representing a year-on-year improvement when adjusted for one-off items and regulatory changes affecting prior results. Dividend guidance for the year was confirmed at €1.23 per share. WDP stated that performance was supported by a combination of internal rental growth, development deliveries and acquisitions, alongside stable operating margins and controlled financing costs.

Leasing activity remained strong throughout the year, with more than 550,000 square metres of new lease agreements signed across both existing assets and development projects. Portfolio occupancy stood at 97.7 percent at the end of December 2025. The share of pre-let projects under development increased to above 80 percent, compared with 60 percent a year earlier, indicating continued demand for logistics space in the company’s core markets.

WDP’s total portfolio reached approximately 9 million square metres, with 750,000 square metres of fully pre-let developments and acquisitions delivered during the year. The active investment pipeline amounted to €708 million, providing visibility on future rental income growth. Portfolio valuation recorded a modest positive adjustment, while reported yields remained broadly stable.

On the financing side, the company highlighted an improvement in its credit profile, including an upgrade from Moody’s and the successful issuance of a €500 million public bond. Equity increased during the year, supported by retained earnings, an optional dividend and in-kind contributions. Reported leverage ratios remained within previously communicated targets.

Alongside its annual results, WDP introduced a new strategic plan covering the period 2026 to 2030. The company aims to grow into a logistics platform exceeding €10 billion in assets across Europe, with expansion supported by pre-let developments, selective acquisitions, internal portfolio growth and energy-related initiatives. Gradual market entry into Spain and Italy is also planned.

Under the new plan, WDP targets minimum EPRA earnings per share of €2.00 and a dividend of at least €1.60 by 2030, alongside a cumulative total shareholder return of at least 50 percent over the five-year period. Annual capital expenditure of around €500 million is expected to be largely financed internally, with debt levels maintained within established leverage parameters.

For 2026, the company forecasts EPRA earnings per share of approximately €1.60 and a corresponding dividend increase to €1.29, subject to market conditions and macroeconomic developments.

front page info
LATEST NEWS