Private Real Estate Debt Turns Towards Development as Lending Conditions Tighten

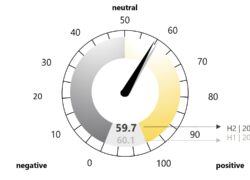
Private debt markets entered the second half of 2026 with investor confidence remaining positive, while real estate lenders are showing greater interest in financing development and repositioning projects. The BF.Private Debt Market Sentiment Index stood at 59.7 points, little changed from 60.1 in the first half and remaining comfortably above the neutral level of 50.

Within real estate debt, the purpose of financing is changing. The proportion of respondents reporting development financing doubled from 20% to 40%, while financing for refurbishment and repositioning remained at 40%. Acquisition financing declined from 80% to 60%, refinancing from 60% to 40%, and short-term bridge financing from 80% to 20%. None of the real estate debt respondents reported distressed or special-situation transactions.

The figures suggest private lenders are increasingly supporting projects where capital can be deployed into development or improvements rather than concentrating primarily on refinancing existing assets. Lending structures nevertheless remain disciplined. Among the real estate debt respondents, 80% of transactions were within a 56–65% loan-to-value range, with the remaining 20% between 66% and 75%. Average all-in spreads were estimated at approximately 430 basis points above the three-month base rate.

Negotiating conditions are also moving towards lenders. Across the broader private debt survey, the share of respondents reporting improved terms for lenders increased from 20.9% in H1 to 38.7% in H2, with expectations indicating that lender influence over pricing and transaction structures could remain stronger during the coming six months.

Property-sector risks remain uneven. Offices and high-street retail recorded the highest stress levels within real estate debt portfolios, both scoring 8.7 in the survey. Logistics and industrial property stood at 6.0, residential at 4.4 and hospitality at 3.6, highlighting significant differences in perceived risk between property sectors.

Fundraising remains active but is taking longer. Among real estate debt managers, the proportion reporting fundraising periods exceeding 18 months increased from 20% to 40%, while none reported completing a fundraising process within six to twelve months during H2. Across private debt more broadly, credit performance remained relatively stable, although the proportion expecting a significant increase in defaults or non-accruals over the next six months rose from 1.6% to 6.6%.

The results point to a private real estate lending market where capital remains available but underwriting discipline is increasing. Development and repositioning are attracting a greater share of financing activity, while lenders are gaining negotiating power and remaining cautious towards sectors facing greater pressure.

The real estate results should nevertheless be treated as directional rather than representative of the entire market. The survey contained 63 respondents overall, of which five were primarily real estate debt managers. Those five represented organisations with average assets under management of approximately €115 billion, but the small sample makes the findings more useful as an indication of changing lender sentiment than as a comprehensive measure of the private real estate debt market.

German Innovation Clusters Deliver Strongest Gains for Smaller Companies

Germany’s regional innovation programmes appear to generate their strongest economic impact among small and medium-sized companies, with new research showing significant increases in investment, employment spending and innovation among participating businesses.

A study involving the German Institute for Economic Research (DIW Berlin) examined Germany’s Spitzencluster programme, which supported 15 regional innovation networks with approximately €600 million of public funding. Contributions from participating organisations brought the combined project volume to around €1.2 billion.

The clusters connect businesses with universities, research organisations and other partners working in related industries. They cover areas including biotechnology, medical technology, mechanical and automotive engineering, electronics and renewable energy, creating regional ecosystems intended to accelerate research and commercial development.

Researchers compared participating companies with similar businesses that did not receive support, using corporate and patent information covering the period from 2000 to 2016. The strongest differences were identified among SMEs.

During the funding period, fixed assets among supported SMEs were approximately 50% higher on average than among comparable companies outside the programme. Spending associated with employment was almost 15% higher, while researchers also identified an increase in patent activity after taking the technological and economic significance of individual patents into account.

“Cluster funding is particularly effective for SMEs as an instrument for increasing investment, employment and innovation,” said Knarik Poghosyan from DIW Berlin’s Entrepreneurship research group. “SMEs should therefore be involved more strongly and more specifically in future cluster programmes.”

The results were less pronounced among larger corporations. While participating large companies increased expenditure on personnel, researchers did not find statistically robust evidence of comparable effects on fixed assets or patent activity.

For regional development, the findings suggest that innovation policy can have consequences beyond research expenditure alone. When smaller companies increase capital investment and employment, successful technology clusters can potentially support demand for laboratories, research facilities, advanced manufacturing premises and specialist business space. However, the DIW study itself examines company investment rather than directly measuring commercial property demand.

“The results suggest that future cluster programmes should be more closely aligned with the needs of small and medium-sized enterprises,” Poghosyan said. She noted that smaller businesses often have fewer financial and organisational resources and can therefore benefit particularly from improved access to knowledge, research partners and innovation networks.

The findings provide an important consideration for German regional economic policy. Rather than distributing innovation support uniformly across companies of different sizes, concentrating more resources on SMEs could generate stronger investment and innovation effects while reinforcing the regional business ecosystems surrounding Germany’s technology and manufacturing centres.

Bucharest Property Yields Stay High as Prime Rents Continue to Climb

Bucharest continued to record rental growth across its main commercial property sectors during the second quarter of 2026, while investment yields remained considerably above European averages, according to Cushman & Wakefield’s latest European market data.

Prime office rents in the Romanian capital reached €22 per sqm per month, an increase of 4.8% year-on-year. Prime office yields remained at 7.25%, compared with a European average of 5.39%. Across Europe, prime CBD office rents increased by 4.5% over the same period.

The strongest movement came from Bucharest’s high-street retail sector. Prime rents on Calea Victoriei increased to €90 per sqm per month, 28.6% above their level a year earlier, while prime retail yields stood at 7%. The rental increase significantly exceeded the 3% annual growth recorded across Europe’s prime high-street markets.

Industrial and logistics property also recorded further growth. Prime rents reached €4.80 per sqm per month, rising 2.1% year-on-year, with prime yields remaining at 7.5%. By comparison, European logistics rents increased by 2.4% annually, while the average European prime logistics yield stood at 5.23%.

“The European real estate market continues to be shaped by the occupiers’ focus on quality assets and the investors’ preference for markets offering an attractive balance between income return and long-term growth potential,” said Vlad Săftoiu, Head of Research at Cushman & Wakefield Echinox. He added that Bucharest’s combination of occupier demand and comparatively high yields continues to support its position within CEE.

Across the CEE region, office rents increased by an average of 5% year-on-year, retail rents by 7.4% and logistics rents by 0.8%. Bucharest therefore outperformed the regional average particularly strongly in high-street retail, while continuing to offer relatively high yields across offices, retail and logistics.

For investors, the yield premium does not automatically make Bucharest less risky or more attractive than Western European markets, as liquidity, financing conditions, asset quality and exit opportunities also influence investment decisions. Nevertheless, the Q2 figures show a market where prime rents are still moving higher while yields remain substantially above European benchmarks, maintaining Bucharest’s appeal to investors seeking higher income returns alongside rental growth.

HIH Invest Takes Control of Düsseldorf Landmark in Major Office Acquisition

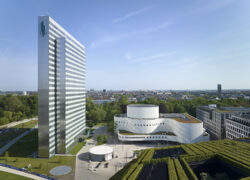
HIH Invest has acquired Düsseldorf’s Dreischeibenhaus together with institutional investors through a club investment structure, adding one of the city’s most recognisable office properties to its portfolio.

The property was sold by the Schwarz-Schütte family, which will retain an investment in the new ownership structure. The parties have not disclosed the transaction price, while HIH Invest intends to hold the building as a long-term investment.

Located in Düsseldorf’s central business district between Königsallee and the Hofgarten, Dreischeibenhaus provides 32,239 square metres of lettable space and has an occupancy rate of approximately 96%. Around 29,800 square metres is dedicated to offices, with the remainder comprising restaurant, storage and archive areas. The property also provides 276 parking spaces.

The listed high-rise was completed in 1960 and underwent an extensive refurbishment in 2014 under the ownership of the Schwarz-Schütte family. The building holds LEED Gold certification.

Its tenant base includes several international legal, consulting, financial and real estate businesses, including Hogan Lovells, Gleiss Lutz, DLA Piper, A&O Shearman, Kearney, Jones Lang LaSalle and LGT Bank.

“With the acquisition of the Dreischeibenhaus, we are investing in one of Germany’s most distinctive office properties. Its combination of a central location in Düsseldorf’s CBD, high building quality, long-term leases and a diversified tenant mix makes the property an attractive investment for institutional investors. In addition, the property benefits from tenants’ growing focus on prime locations and premium fit-outs, which is driving stable demand for high-quality space, particularly in the top office markets,” said Felix Meyen, Managing Director of HIH Invest.

The acquisition comes as investors in Germany’s office sector continue to differentiate increasingly between prime, well-occupied properties and buildings facing leasing, location or modernisation challenges. With occupancy close to full capacity and a tenant roster concentrated around established professional-services companies, Dreischeibenhaus represents the type of core office property capable of attracting institutional capital despite greater selectivity across the wider market.

The Schwarz-Schütte family’s decision to remain financially involved following the transaction also distinguishes the deal from a conventional disposal. Rather than exiting the property completely, the former owner will retain exposure alongside HIH Invest and the participating institutional investors.

“The Dreischeibenhaus has been a key part of our portfolio for many years. In HIH Invest, we have found a long-term partner that shares our appreciation of the property’s exceptional quality and significance. Through our investment, we will remain associated with the property going forward,” said Patrick Schwarz-Schütte of Black Horse Properties.

The building’s location within Düsseldorf’s CBD places it close to one of the city’s principal business, retail and leisure areas. Its position between Königsallee and Hofgarten also provides access to a concentration of corporate occupiers and city-centre amenities.

Ashurst LLP advised on legal and tax matters associated with the acquisition, while Drees & Sommer carried out the technical and ESG assessment. BNP represented the seller in the transaction.

For Germany’s office investment market, the deal provides another example of capital concentrating on highly occupied buildings in established central locations. While the undisclosed purchase price prevents an assessment of the transaction’s yield or valuation, the acquisition demonstrates continuing institutional appetite for selected prime office assets where location, occupancy and building quality can support a long-term investment strategy.

Higher-LTV Mortgages Gain Ground as UK Housing Finance Recovers

The UK mortgage market strengthened considerably during the second quarter of 2026, with lending volumes rising sharply and mortgages requiring smaller deposits accounting for their largest share of new lending in almost two decades.

Gross mortgage advances reached £77.4 billion in Q2, an increase of 11.1% from the previous quarter and 31.7% from the same period of 2025, according to the Financial Conduct Authority. Total outstanding residential mortgage balances increased to approximately £1.761 trillion, 3.1% higher than a year earlier.

The increase in completed lending was considerably stronger than the movement in new mortgage commitments. Commitments reached £79.2 billion, rising 1.4% quarter-on-quarter and 1.3% annually. The difference suggests that the surge in advances should not automatically be interpreted as an equivalent acceleration in future housing transactions.

One of the clearest changes was the increasing proportion of lending at higher loan-to-value ratios. Mortgages exceeding 90% of a property’s value accounted for 8.4% of gross advances, the highest share since the second quarter of 2008. Lending above 75% LTV represented 47.5% of advances, reaching its largest proportion since the fourth quarter of 2007.

Higher borrowing relative to household income also became more prevalent. The FCA’s measure of high loan-to-income lending increased to 46.0% of advances, rising 0.9 percentage points during the quarter and 4.6 percentage points compared with Q2 2025.

The figures are significant for the residential property market because deposit requirements remain one of the principal barriers facing households attempting to buy homes. A greater proportion of high-LTV lending potentially expands the financing options available to buyers with sufficient income to service a mortgage but limited capital for a large deposit. The FCA statistics, however, do not establish that lenders have generally relaxed their underwriting requirements.

Despite the increase in higher-leverage mortgages, first-time buyers did not take a larger share of overall lending. They accounted for 27.3% of gross advances, slightly below both the previous quarter and the equivalent period of 2025. Home movers represented 28.8%, while mortgages used for owner-occupied purchases accounted for 56.1% of advances.

Refinancing became a more important part of activity. Owner-occupier remortgages increased to 31.2% of gross advances, up 3.1 percentage points from Q1 and the highest proportion since early 2024. This indicates that a meaningful part of the increase in mortgage volumes came from existing homeowners arranging new financing rather than from property purchases alone.

Buy-to-let lending moved in the opposite direction. Its share of gross advances declined from 8.9% in the first quarter to 8.0% in Q2, the lowest level since the third quarter of 2024 and 1.2 percentage points below a year earlier.

The decline does not demonstrate on its own that landlords are withdrawing permanently from the UK housing market, but it does show owner-occupied and refinancing activity taking a greater proportion of mortgage flows. If sustained, the divergence will be important for the relationship between homeownership and the privately rented housing sector.

There was also encouraging evidence on existing mortgage performance. Balances in arrears declined 1.9% during the quarter to approximately £19.7 billion, leaving them 7.3% below their level a year earlier and at their lowest since the third quarter of 2023. Arrears represented around 1.1% of outstanding mortgage balances.

Repossession activity also decreased. There were 2,058 new possessions during Q2, 7.1% fewer than in the previous quarter and 15.6% below the corresponding period of 2025. The stock of properties in possession declined 4.5% to 8,825.

For developers and residential investors, the figures present a more nuanced market than the headline increase in lending might suggest. Mortgage finance is flowing at substantially higher volumes than a year ago and higher-LTV products are accounting for a growing proportion of activity, while arrears and possessions are moving lower. At the same time, first-time buyers have not increased their share of lending, buy-to-let activity has weakened and new mortgage commitments are growing much more slowly than completed advances.

The next test for the UK residential market will therefore be whether the growing use of higher-LTV mortgages translates into sustained purchasing demand. If it does, the financing environment could provide additional support for transactions and new-build sales. If much of the current increase reflects refinancing and previously agreed mortgages reaching completion, the underlying recovery in housing demand may prove more moderate than the headline lending figures initially indicate.

Source: FCA Q2 2026 Mortgage Lending Statistics

Żabka Reaches 13,000-Store Milestone with Warsaw City-Centre Opening

Żabka has expanded its Polish retail network to 13,000 locations with the opening of a new store at DT Wars Sawa Junior in central Warsaw, marking another step in the convenience retailer’s continued growth across the country.

The choice of Wars Sawa Junior for the milestone opening gives the expansion particular significance for the commercial property market. Rather than being located in a conventional neighbourhood retail setting, the store places Żabka within one of Warsaw’s established city-centre retail destinations, demonstrating the growing role of convenience formats in high-footfall urban properties.

Located in the centre of Warsaw, Wars Sawa Junior forms part of one of the capital’s best-known retail areas. Żabka’s presence adds a convenience-led offer designed to serve a broad customer base that includes office workers, residents, shoppers, commuters and visitors moving through the city centre.

The opening also illustrates how the boundaries between traditional convenience retail and larger commercial destinations are becoming less distinct. Shopping centres and established retail properties are increasingly combining fashion, food, services and everyday shopping, creating opportunities for operators that can generate frequent visits throughout the day rather than relying predominantly on discretionary spending.

For Żabka, reaching 13,000 stores underlines the scale achieved by a network built largely around relatively small retail units and franchise-operated locations. Its expansion has made convenience retail an increasingly important source of demand for street-level commercial space, mixed-use developments, transport-linked properties and retail schemes across Poland.

The Wars Sawa Junior opening also provides an example of how mature retail properties can broaden their tenant mix as consumer behaviour changes. Convenience stores can complement restaurants, fashion retailers and service operators by generating regular everyday visits and extending the range of reasons customers have for entering a property.

From a real estate perspective, Żabka’s continuing expansion creates demand for a type of space that differs from that required by conventional large-format retailers. Accessibility, pedestrian traffic, visibility and proximity to workplaces, residential areas and transport connections can be more important than the large floorplates traditionally associated with shopping centres.

Reaching 13,000 locations therefore represents more than another numerical milestone for the retailer. The decision to mark it at Wars Sawa Junior highlights the increasingly important relationship between convenience retail and prime urban commercial property, as landlords seek tenant combinations capable of attracting customers repeatedly throughout the working week and beyond.

Saudi Arabia’s Housing Expansion Is Running Into the Cost of Ownership

Saudi Arabia continues to expand its housing supply at extraordinary speed, but the residential market is beginning to expose a challenge that construction alone cannot resolve. The country needs additional homes as its cities grow and its economy attracts more activity, yet weaker sales during the second quarter of 2026 suggest that the ability of households to purchase those homes is becoming increasingly important. Residential transactions slowed markedly during the quarter. The total value of housing deals was approximately 26.9% lower than a year earlier, while the number of transactions declined by around 14.2%. At the same time, residential land values increased by approximately 6.3%. Apartment prices remained comparatively resilient, while villa prices recorded a much larger decline.

The combination creates an unusual development equation. The underlying land required to produce housing is becoming more expensive while buyers appear more cautious about committing to finished homes. If this pattern continues, developers will increasingly have to reconcile the price they pay for development sites with the amount households can borrow and comfortably repay. This is particularly significant because Saudi Arabia’s housing requirement remains substantial. Population growth, household formation, economic diversification and continued urban expansion all support the need for additional residential supply. The slowdown in transactions therefore does not necessarily indicate that people no longer want homes. It raises a different question: whether enough of the homes available are being offered at prices that match household purchasing capacity.

The contrasting performance of villas and apartments provides an indication of how that pressure could reshape the market. Villas have traditionally occupied an important position in Saudi housing, but their larger floor areas and greater land requirements generally produce higher total purchase prices. Apartments can accommodate more households on the same site and provide a lower entry price by reducing the amount of space each buyer purchases. The second-quarter figures do not prove that Saudi households are abandoning villas in favour of apartments. Differences in location, age, specification and the properties actually transacted can all influence market averages. Nevertheless, the substantial decline in villa pricing compared with the relative resilience of apartments suggests that the total amount buyers are being asked to spend deserves closer attention.

For developers, the issue begins with land. When site prices rise, there are only a limited number of ways to maintain acceptable development returns. Selling prices can increase, construction costs can fall, margins can narrow or more saleable space can be created from the same site. When buyers resist higher prices, increasing density becomes one of the most practical responses. That could gradually alter Saudi residential design. Instead of simply increasing the size and specification of homes, developers may need to pay greater attention to the final purchase price. Smaller apartments, more efficient layouts, compact family homes and villas on reduced plots could allow projects to reach a wider group of purchasers without necessarily reducing construction quality.

Riyadh is likely to be central to this adjustment. The capital is expanding rapidly as employment, corporate activity, entertainment, tourism and infrastructure investment increase. These trends create additional residential requirements, but they also intensify competition for land in established and well-connected areas. Moving housing development further from expensive locations provides one solution, although cheaper land does not automatically create affordable living. A household purchasing a less expensive home on the edge of a city may face longer journeys, greater transport costs and reduced access to schools, shops, healthcare and employment.

Infrastructure therefore becomes part of the housing affordability equation. Riyadh’s expanding transport network has the potential to make a wider range of residential locations practical for commuters. If peripheral districts can be connected efficiently to employment centres, developers gain access to a larger pool of land on which housing can potentially be delivered at lower prices. The same principle applies to new master-planned communities. Their success will depend on more than the number of homes constructed. Schools, retail, recreation, healthcare, roads and transport connections determine whether households view a new district as a realistic alternative to established neighbourhoods.

Jeddah faces similar pressures, although its urban structure is different. New residential districts can expand outward from an established metropolitan economy with existing employment, airport connections, commercial activity and public services. Developers still have to balance the lower cost of emerging locations against buyers’ preference for established neighbourhoods and shorter journeys.

Financing adds another layer to the affordability challenge. Most purchasers experience the housing market through the size of the deposit and the monthly mortgage payment rather than through abstract movements in property prices. A home can therefore become harder to purchase even when its nominal value changes relatively little if financing conditions increase the monthly burden. Saudi Arabia has developed extensive mechanisms intended to broaden access to home ownership. Public housing initiatives, financing programmes and partnerships between government-related organisations and private developers have accompanied a substantial increase in home ownership. Such measures remain important because they can help eligible households bridge the gap between savings, income and property prices.

However, buyer assistance cannot indefinitely compensate for housing whose production cost moves beyond household purchasing capacity. Sustainable affordability ultimately requires supply to be created at price points that households can support without increasingly large interventions. This is where the Q2 divergence between land and completed housing becomes especially relevant. If residential sites continue appreciating while buyers become increasingly price-sensitive, the pressure will eventually move back through the development chain. Developers will have to reconsider density, location, unit mix and land acquisition strategies.

Companies that already control land could consequently have an advantage. Sites acquired before substantial increases in value provide developers with greater flexibility when setting selling prices. Partnerships involving public-sector land can potentially create similar flexibility, while higher-density planning can spread land costs across a larger number of homes. For investors, this means residential opportunity should not be measured simply by population growth or the number of homes Saudi Arabia expects to require. The composition of that demand matters. A development aimed at households capable of purchasing SAR1 million homes faces a fundamentally different market from one requiring buyers to finance properties costing several times as much.

The most successful projects may therefore be those designed around household budgets from the beginning rather than adjusted after sales slow. That means considering the likely mortgage payment, required deposit and total purchase price before deciding unit sizes, density and specifications. There is also an opportunity for residential developers to rethink what affordability means. Smaller does not necessarily have to mean basic. Efficient apartments can still provide attractive communal spaces, landscaping, recreation and access to services. Compact villas can preserve private family space while using considerably less land than conventional detached housing.

This could produce a more diverse Saudi housing market. Apartments may become increasingly important for younger households and buyers seeking lower entry prices, while smaller villas and townhouses could provide alternatives for families wanting more space without paying for large plots. None of this means Saudi Arabia is facing an absence of residential demand. The country’s demographic and economic development continues to create a considerable long-term requirement for housing. The more important distinction is between needing a home and being able to purchase the particular homes available.

That difference helps explain why declining transactions can coexist with extensive construction and rising land values. Housing demand can remain structurally significant while the pool of buyers capable of completing purchases at prevailing prices becomes more selective. Saudi Arabia’s residential expansion is therefore entering a more demanding stage. Increasing supply remains necessary, but the market will increasingly judge developers by whether their homes match household finances as closely as they match demographic projections.

The next phase of Saudi housing may consequently be defined less by the sheer number of units announced and more by decisions about size, density, location and connectivity. With land becoming more expensive and buyers showing greater sensitivity to total purchase costs, affordability is moving from a social policy issue to a central development consideration. For Saudi Arabia’s residential market, building enough homes is only half of the challenge. The other half is ensuring that the people those homes are intended for can realistically afford to buy them.

Source: CIJ.World Research & Analysis Team

Vienna’s Missing Office Deals Leave Property Values Untested

Vienna’s office investment market reached an unusual point during the second quarter of 2026. According to CBRE, not a single office investment transaction was recorded during the period. Approximately €53 million of office properties changed hands during the first half of the year, with all of that activity taking place during the first quarter. Despite the absence of transactions, the quoted prime office yield remained around 4.75%. This creates one of the more interesting questions facing Vienna’s property market: whether investment values have genuinely stabilised or whether there have simply been too few transactions to demonstrate where buyers and sellers are currently prepared to agree.

The distinction is important. Property valuations can be supported by rental income, comparable assets and professional assessments, but completed transactions provide some of the clearest evidence of what investors are actually willing to pay. When an entire quarter passes without an office investment deal, that evidence becomes considerably more limited. The weakness was not restricted to Vienna offices. According to CBRE, approximately €298 million of Austrian commercial property changed hands during Q2 2026, bringing first-half investment volume to around €1 billion. That was approximately 31% below the corresponding period of 2025. Other property advisers calculate somewhat different market totals, reflecting differences in the transactions included in their research, but they reach a similar conclusion: Austrian investment activity remained subdued during the first half of 2026.

A limited supply of properties available for acquisition contributed to the low transaction volume. This means the weakness cannot necessarily be interpreted simply as investors losing interest in Austrian real estate. In some parts of the market, potential buyers have relatively few opportunities on which to deploy capital. Vienna’s underlying office market also presents a more complicated picture than the investment statistics alone suggest. Vacancy remains comparatively low, particularly when measured against a number of other major European office markets, while modern buildings in central locations continue to benefit from occupier demand.

Prime rents were around €28.50 per square metre per month during the second quarter. Limited availability of high-quality space continues to support the upper end of the rental market, giving owners of well-let modern buildings some protection against the wider slowdown. Leasing activity, however, weakened considerably. CBRE recorded approximately 20,500 square metres of office take-up during Q2, making it the weakest quarter for leasing activity in several years. Other market research produced a very similar result. Companies have become more cautious about major property decisions, with some occupiers extending existing leases rather than relocating, while businesses considering new offices increasingly focus on modern buildings that offer strong locations, efficient operating costs and high technical standards.

This is creating a growing division within Vienna’s office stock. The strongest properties can benefit from scarce supply, established tenants and relatively resilient rents. Older offices face a more difficult future, particularly where substantial investment is required to meet changing occupier expectations or improve energy performance. For an investor, these differences increasingly affect the amount of capital that can reasonably be paid for a building. Purchasing an older property may involve substantial expenditure after acquisition, potentially reducing the price a buyer is prepared to offer.

Owners may view the calculation differently. A building that continues producing reliable income does not necessarily need to be sold simply because investment markets have slowed. Where refinancing remains manageable, holding the property while market conditions improve may be preferable to accepting a price below the owner’s expectations. This can produce an investment market in which neither side has a strong reason to compromise. Buyers continue to assess property against financing costs, expected returns and opportunities elsewhere in Europe, while sellers consider existing rental income, replacement costs and the possibility that financing conditions could become more favourable. If those calculations produce significantly different values, transactions can remain scarce without either side necessarily being under immediate pressure.

The continued presence of international capital makes the situation more nuanced. Foreign investors have not disappeared from Austria. International buyers continued to account for a substantial share of overall Austrian investment during the first half of 2026. Vienna therefore still competes for global capital. The challenge is that international investors can compare an Austrian office acquisition with properties across Europe and with alternative real estate sectors. Vienna must consequently offer an attractive balance between price, income security and future growth.

That competition becomes particularly important when prime office yields remain around 4.75%. Investors must decide whether the security offered by Vienna’s strongest buildings adequately compensates them for financing costs and other investment alternatives. Domestic investors face many of the same calculations, although their familiarity with Vienna and potentially longer holding periods may allow them to assess individual opportunities differently.

The scarcity of transactions becomes more significant outside the prime segment. A modern, fully occupied building in a central location can be relatively straightforward to value. The position of an older office with upcoming lease expiries, refurbishment requirements or weaker environmental performance is much harder to establish when few comparable properties are trading. This is where the absence of deals could be concealing a larger adjustment. The quoted prime yield describes the strongest part of the market, but it does not necessarily show what would happen if a substantial number of secondary offices were simultaneously offered for sale.

Austria’s wider property financing environment adds another dimension. Banks have been dealing with increased levels of problematic commercial real estate lending following the sharp change in financing conditions since 2022. Although Austria’s banking system remains well capitalised, some individual property owners may face increasingly difficult refinancing decisions. If those pressures eventually cause more properties to be offered for sale, the resulting transactions could provide much clearer evidence of current values.

This does not mean that Vienna is heading towards widespread distressed selling. Falling interest rates, resilient rental income and low vacancy in stronger buildings could allow many owners to refinance or continue holding their properties. Instead, the adjustment is likely to vary substantially from asset to asset. Buildings with secure tenants, good locations and limited capital expenditure requirements may continue to justify relatively strong valuations, while offices requiring extensive modernisation or facing weaker leasing prospects could experience considerably greater pricing pressure.

That makes the next significant Vienna office transactions particularly important. After a quarter without recorded investment deals, new sales will provide more than additional transaction volume. They will help establish how investors are valuing Vienna offices after several years of higher financing costs and changing expectations about the future of the workplace.

Vienna’s office investment market therefore presents an unusual paradox. The strongest buildings continue to benefit from comparatively supportive leasing fundamentals, while headline prime pricing appears stable. Yet almost no investment activity has taken place to test those assumptions. The question for the remainder of 2026 is not simply when office investment returns, but what the first meaningful transactions reveal about where Vienna’s office values actually stand.

Source: CIJ.World Research & Analysis Team

CEVA Takes on 20,000 Refrigeration Units Annually in Expanded PepsiCo Turkey Contract

CEVA Logistics has signed a new agreement with PepsiCo Türkiye covering the maintenance, repair and refurbishment of refrigeration equipment across the country, extending the logistics provider’s role into technical services and equipment management. Under the contract, CEVA plans to service and refurbish approximately 20,000 refrigeration units each year across thousands of retail locations in Turkey.

Dedicated technical teams will carry out scheduled maintenance, repairs and on-site servicing, while equipment requiring more extensive work will be transferred to CEVA facilities for refurbishment. Units that cannot be restored at the point of use will undergo mechanical and technical repairs before being returned to operation where possible. CEVA says the process can extend the useful life of refrigeration equipment by up to ten years, reducing the requirement for replacement equipment and supporting more efficient use of materials.

The agreement combines field servicing with reverse logistics and refurbishment within a single operating structure. For CEVA, the contract illustrates how third-party logistics providers are increasingly expanding beyond transport and warehousing into technical services that support products and equipment throughout their operational life.

“The project we are carrying out together with PepsiCo is an important example of CEVA’s integrated service capabilities, which go significantly beyond traditional logistics operations,” said Serkan Etleç, Vice President of Contract Logistics Ground Operations, Türkiye at CEVA Logistics. He added that the company will combine its Turkish operating network with technical expertise and equipment lifecycle management to support PepsiCo’s refrigeration operations.

The model also introduces a circular-economy element to the logistics process. By repairing and returning existing equipment to service rather than automatically replacing it, CEVA expects to reduce the resources required for new refrigeration units and the associated environmental impact.

The PepsiCo agreement reflects a broader expansion of the role played by contract logistics companies. As manufacturers and consumer businesses seek to combine distribution, returns, repair and equipment management, logistics networks are increasingly being used for specialist technical activities alongside conventional storage and transport.

Power Access Is Rewriting the Investment Map for Dutch Real Estate

A development site in the Netherlands can have the right zoning, strong transport connections, an attractive location and willing occupiers and still face a fundamental obstacle: there may not be enough electricity available to support what is supposed to be built there. That problem is changing the way Dutch real estate needs to be assessed. Electricity infrastructure, once largely treated as a technical matter to be resolved during development, is increasingly becoming part of the investment decision itself.

Pressure on the national electricity network has intensified as the Netherlands simultaneously builds new housing, electrifies industry, installs heat pumps, expands renewable generation, introduces electric transport and develops increasingly power-intensive commercial buildings. In several regions, companies requesting new connections or additional capacity can face substantial delays. The consequences extend directly into property markets. Development can be legally possible without being immediately practical, while buildings designed for modern occupiers may require significantly more electricity than the properties they replace.

This introduces a new question into land acquisition: what is a site really worth if sufficient electricity cannot be obtained when the project needs it? There is no established national valuation formula answering that question. Dutch transaction evidence does not yet demonstrate a standard percentage premium for land with dependable electricity access. Nevertheless, the underlying conditions that could create such a premium are becoming increasingly visible.

The issue is already familiar to the data-centre industry. Electricity requirements are so large that access to suitable infrastructure can determine where facilities are developed. But concentrating exclusively on data centres understates how broadly the problem now reaches into real estate. Logistics provides one of the clearest examples.

The conventional warehouse was relatively straightforward from an electricity perspective. The next generation of distribution facilities can be very different. Automated storage, robotics, sorting systems, refrigeration, digital equipment and charging infrastructure can dramatically increase demand. As commercial transport becomes more electrified, the requirements could rise further. A distribution centre serving a fleet of electric delivery vehicles or trucks may need infrastructure that was never envisaged when the site was originally developed.

This matters particularly in logistics markets such as Tilburg and Venlo. Both locations benefit from their positions within European supply chains and strong road connections, but future competitiveness may depend increasingly on whether individual properties can accommodate more electricity-intensive operations. Two warehouses with comparable size, specification and motorway access may therefore offer very different possibilities to an occupier if one has sufficient power and the other does not.

Manufacturing creates an even larger challenge. The Netherlands is seeking to reduce the dependence of industrial processes on fossil fuels while companies are simultaneously investing in more automated production. Both trends can increase electricity consumption. Around Eindhoven, this has particular significance because the regional economy includes advanced manufacturing, technology companies, research operations and specialised suppliers. Laboratories and sophisticated production facilities require dependable infrastructure as well as suitable buildings.

For such businesses, electricity availability is not simply an environmental consideration. It can determine whether machinery, research equipment and production systems can operate at the required scale. Rotterdam presents the issue in another form. Its port and industrial complex faces an enormous energy transition involving manufacturing, transport, logistics and infrastructure. Electrification can create substantial new demand at the same time as surrounding areas continue to require capacity for conventional commercial and residential development. Real estate in these locations is therefore competing for infrastructure within a much larger economic transformation.

Amsterdam has its own combination of pressures. Housing construction, offices, technology businesses, transport electrification and digital infrastructure all contribute to electricity requirements. The development potential of individual sites increasingly needs to be considered alongside the capacity of the surrounding network.

Utrecht demonstrates how severe the constraint can become. Network limitations across Utrecht and neighbouring parts of the Netherlands have resulted in particularly restricted availability for new and enlarged connections. This is occurring in a region where housing demand remains strong and considerable development is still required. The contradiction is significant. A city can have exceptional demand for new property and still struggle to accommodate that demand because the infrastructure supporting additional buildings cannot expand at the same speed.

Housing is therefore part of the electricity problem as well. New residential districts increasingly rely on electric systems for heating, domestic consumption and mobility. Thousands of new homes also require supporting schools, shops, services and transport infrastructure, all adding to local demand. For developers, this means electricity capacity needs to be considered much earlier. Acquiring land, completing planning and arranging financing do not necessarily guarantee that a project can operate according to its intended timetable.

The Dutch authorities are responding by expanding infrastructure, changing how scarce capacity is distributed and seeking ways to use the existing network more efficiently. Housing and other socially important uses can receive priority under the revised system for allocating constrained capacity, while municipalities are being given a greater role in addressing electricity requirements earlier in development planning. But changing allocation rules cannot instantly create additional physical infrastructure.

New substations, cables and transmission capacity require major investment and lengthy construction programmes. Until that expansion catches up with demand, property markets must operate within the limitations of the existing system. That is where the investment implications become particularly interesting.

Consider two development sites with similar planning status, land area, transport access and potential rents. One has a credible route to obtaining the electricity required by the future occupier. The second faces substantial uncertainty over when sufficient capacity will become available. Their risk profiles are clearly different. The first site may move from construction into occupation and rental income according to schedule. The second could encounter delays, restrictions on use or a smaller pool of potential occupiers.

Those differences can eventually influence what a developer is prepared to pay. They can also affect financing. A lender assessing a logistics, industrial or technology development increasingly needs to understand whether the completed property can operate as intended. A technically finished building waiting for critical infrastructure presents a different risk from an asset capable of generating income immediately.

Existing buildings could gain an unexpected advantage from this shift. Some established industrial and logistics properties already have access to substantial electricity capacity because of their historic use. Where that infrastructure remains suitable and can legally and technically support redevelopment or a new occupier, it could add another dimension to the value of the site.

This has potentially important consequences for brownfield property. An ageing factory may appear obsolete when judged solely by its building quality. But the underlying site could possess valuable infrastructure, planning characteristics and established utility arrangements that are difficult to reproduce on undeveloped land. Investors may therefore need to look beyond the physical condition of a property when evaluating redevelopment opportunities.

Electricity also introduces a new dimension to obsolescence. Traditionally, an industrial or logistics property might become outdated because its ceiling height was insufficient, loading facilities were inadequate, energy performance was poor or the building could not accommodate modern automation. In future, inadequate electricity capacity could become another reason why otherwise functional buildings struggle to attract certain occupiers.

The reverse may also occur. A physically older property with strong infrastructure could remain commercially useful precisely because competing locations cannot easily obtain comparable capacity. This makes electricity increasingly relevant during due diligence.

Investors need to understand not only whether a property has a connection today but also the amount available, the contractual arrangements surrounding it, the future requirements of potential occupiers and the likelihood that additional capacity can be obtained. Importantly, an existing connection should not automatically be assumed to remain available under every redevelopment scenario. The position can depend on the site, network operator, intended use and specific arrangements governing the connection.

There is therefore no simple rule that a property with an existing supply automatically possesses a transferable development advantage. Nor is there sufficient evidence yet to declare that Dutch property markets have established a standard electricity premium. What can be said is that electricity availability increasingly affects development timing, occupier suitability and investment risk. Once a constraint influences those factors consistently, it has the potential to influence value as well.

That is the next stage investors should watch. The Netherlands already prices real estate according to accessibility, planning scarcity, environmental performance, location and the strength of local occupier markets. Electricity infrastructure could increasingly join that list.

The effect will not be identical everywhere. Amsterdam, Utrecht, Eindhoven, Rotterdam, Tilburg and Venlo have very different property markets and energy requirements. Nor will every building need large amounts of electricity. But for power-intensive uses, the traditional definition of a prime development site is changing.

A motorway junction cannot operate automated machinery. A railway station cannot charge a commercial vehicle fleet. Planning permission cannot run a laboratory, heat thousands of homes or power an advanced factory. Those activities ultimately depend on infrastructure capable of supplying them.

Dutch real estate therefore faces a new location test. Investors still need to know where a property is, what can be built and what rent it can achieve. Increasingly, they also need to know whether there will be enough electricity to make the investment work.

Source: CIJ.World Research & Analysis Team

front page info
LATEST NEWS