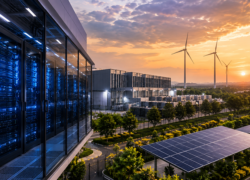
India’s AI Expansion Is Creating a New Geography for Data Centres

India’s rapid adoption of artificial intelligence is beginning to transform the country’s data-centre industry, creating demand for facilities that require considerably more electricity, advanced cooling and larger infrastructure commitments than earlier generations of digital infrastructure.

The change extends beyond simply building additional server capacity. AI applications depend on powerful computing systems capable of processing enormous quantities of information, meaning developers increasingly have to reconsider where facilities are located, how much power they can secure and how efficiently they can manage the heat generated by high-performance equipment.

India already has around 1.6 GW of operational data-centre capacity, with approximately another 3.1 GW either under construction or planned. Current projections indicate that national capacity could exceed 4.5 GW by 2030 as cloud computing, digital services and AI applications continue to expand.

AI is likely to accelerate this development because its computing requirements differ significantly from those of conventional corporate IT systems. Traditional data-centre racks have generally operated at relatively modest power densities, often averaging around 10–12 kW. Infrastructure designed for high-performance AI computing can require 40–100 kW per rack or more, with some of the latest configurations moving considerably beyond those levels.

The difference has substantial consequences for real estate. A building containing high-density computing equipment requires far more electrical infrastructure for the same amount of technical floor space. It also generates significantly greater heat, requiring more sophisticated cooling and mechanical systems.

Liquid cooling is therefore becoming increasingly important. Instead of relying entirely on conventional air-conditioning systems, new facilities can use technology that transfers heat directly from processors through liquid-based systems. This allows greater computing density but changes the design and cost of the property. Developers must allocate more space and capital to power distribution, cooling equipment and supporting infrastructure.

The result is that the value of a potential data-centre site is increasingly determined by what surrounds the land rather than simply the land itself. Reliable access to large quantities of electricity is becoming one of the most important considerations in site selection. Fibre connectivity, water availability, renewable-energy potential and proximity to major digital networks are also becoming increasingly influential.

This could gradually change the geography of India’s data-centre market. Mumbai remains the country’s largest hub, with operational capacity approaching 900 MW during the first half of 2026. Its established digital infrastructure, international connectivity, corporate demand and concentration of operators continue to give the city a significant advantage.

Chennai has also developed into one of India’s principal data-centre locations, supported by international cable connectivity and a large technology economy. Hyderabad and Delhi-NCR have established substantial positions of their own and should no longer be viewed as secondary data-centre locations.

Hyderabad in particular is attracting major investment. New projects announced by international and domestic operators are adding hundreds of megawatts of planned capacity, strengthening Telangana’s position within India’s digital infrastructure market.

The more significant development is the emergence of additional locations capable of hosting very large AI-oriented campuses. Visakhapatnam is becoming one of the clearest examples.

Google is developing a major AI and data-centre hub in the city as part of an investment programme valued at approximately USD 15 billion between 2026 and 2030. The development is expected to include large-scale computing infrastructure alongside new energy and telecommunications capacity. The scale of the project demonstrates how a single major technology investment can change the position of an emerging city within India’s digital economy.

Jamnagar provides another example of how AI could widen the country’s data-centre geography. Meta has committed to capacity within a large AI-oriented facility being developed by Reliance Industries, demonstrating that future hyperscale investment does not necessarily have to remain concentrated in established metropolitan markets.

These developments suggest that the next generation of Indian data centres could increasingly follow electricity and infrastructure availability rather than conventional commercial property patterns. Large AI campuses may require hundreds of megawatts of power. Future projects could eventually operate at gigawatt scale, making their energy requirements comparable with major industrial developments.

This creates an important challenge for India’s electricity system. Data centres already account for a measurable share of national power consumption, and demand is expected to increase substantially as new capacity becomes operational. AI could accelerate that growth because high-performance computing requires much more electricity than conventional digital workloads.

Developers are consequently placing greater emphasis on renewable power. Long-term agreements for solar and wind electricity are becoming more important, while battery storage could eventually help operators manage the difference between intermittent renewable generation and the continuous electricity requirements of data centres.

However, renewable generation alone does not solve the problem. Data centres require exceptionally reliable electricity at every hour of the day, meaning grid infrastructure, substations, storage and backup systems remain critical.

Water represents another challenge. Cooling large computing facilities can require substantial quantities of water, particularly in locations using evaporative cooling systems. India’s existing data-centre industry is already estimated to consume significant water resources, and consumption could rise sharply as capacity expands.

This makes cooling technology and local water availability increasingly important considerations when selecting future sites. New facilities may rely more heavily on closed-loop systems, recycled water, desalination or other technologies designed to reduce pressure on municipal supplies.

These requirements are beginning to make data centres resemble infrastructure projects as much as conventional real estate developments. A major campus may require extensive land not only for server buildings but also for substations, cooling facilities, backup power, energy storage and telecommunications infrastructure.

This creates opportunities beyond the data-centre property itself. Large developments require electrical equipment, cooling technology, construction materials, network infrastructure and specialist maintenance services. Suppliers serving these facilities can create additional requirements for industrial and logistics property nearby. Data-centre investment can therefore become a catalyst for wider industrial development.

For property investors, this changes the characteristics that make a site valuable. Cheap land alone is unlikely to attract major AI infrastructure. A successful location needs a combination of available land, sufficient grid capacity, dependable electricity, fibre connectivity and a regulatory environment capable of supporting very large projects.

States able to provide these conditions could attract investment that previously would have been concentrated in Mumbai, Chennai or other established markets. Mumbai is unlikely to lose its position as India’s leading data-centre centre in the immediate future. Its connectivity, existing infrastructure and large customer base remain difficult to replicate.

But the scale of future AI computing requirements means that India’s digital infrastructure market is likely to become more geographically diverse. Hyderabad is strengthening its position as a major established market, while developments in Visakhapatnam and Jamnagar demonstrate the potential for large projects to create entirely new digital infrastructure clusters.

India’s data-centre expansion is therefore entering a different phase. The first stage was largely driven by cloud adoption, digital services and rising internet consumption. The next will increasingly be influenced by the enormous computing requirements of artificial intelligence.

That transition will change the buildings themselves, but its greatest impact may be on where they can realistically be developed. For the next generation of India’s data centres, the decisive question may no longer be where technology companies want to locate their servers, but where developers can find enough land, electricity, connectivity and cooling capacity to operate them.

Source: © CIJ.World India Research & Analysis Team
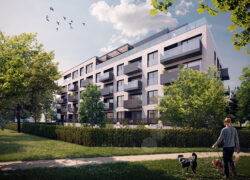
Ryšánka Shifts to Rental Housing as BTR Group Takes Over Leasing and Management

A residential development in Prague is moving from an original apartment-sales strategy to a professionally managed rental model, highlighting the growing role of institutional rental housing within the Czech capital’s residential market.

The Ryšánka project, being developed under the Realia Home brand, will provide 51 rental apartments ranging from one-bedroom-style studios to larger three-room units. BTR Group has now been selected to handle the exclusive leasing of the apartments and will assume responsibility for property management and resident services once the development becomes operational.

BTR Group has been involved in Ryšánka since the construction phase, although the property was initially designed as a conventional development in which individual apartments would be sold. Following the decision to retain the building for rental purposes, the company was brought in to help adapt the scheme to the requirements of a professionally operated residential property.

Its work included reviewing the apartment mix and layouts and developing interior specifications appropriate for the rental market. Following a subsequent tender, the relationship has been extended from development consultancy to the operational phase of the investment.

The change in strategy is particularly relevant as Prague’s rental market attracts increasing attention from investors and developers looking for alternatives to the traditional build-and-sell residential model. Retaining an entire building for rental operation requires a different approach to apartment configuration, interiors, operating costs and long-term asset management than selling individual units following completion.

Ryšánka is being positioned towards the higher end of Prague’s rental market. The development will be set within a landscaped garden and will combine residential accommodation with services intended for tenants. Sustainability measures and interior design are also being incorporated into the scheme.

The appointment gives BTR Group responsibility for bringing the apartments to market as well as managing the completed property. This creates continuity between decisions taken during development and the subsequent operation of the building, where occupancy, rental income, maintenance costs and resident retention will ultimately determine investment performance.

For Realia Home, the conversion also changes the financial profile of the project. Instead of generating proceeds primarily through individual apartment disposals, Ryšánka will become an income-producing residential asset, making leasing performance and long-term operating efficiency more important to its economics.

The project provides a relatively small example of a broader change taking place within Prague residential development. Professionally managed rental housing is creating another route for properties that might previously have been developed almost exclusively for individual ownership, particularly where investors are prepared to hold residential assets over longer periods.

Marketing of the apartments is scheduled to begin towards the end of 2026. The development is expected to become operational in the second quarter of 2027, when the first tenants are due to move into the property.

Ryšánka’s transition from apartments intended for sale to a single professionally managed rental property illustrates how operating strategy can increasingly influence residential projects before construction is completed. As Prague’s institutional rental sector develops, decisions over apartment design, management and leasing are likely to become progressively more integrated with development and investment strategy.

Tram Construction Accelerates Transformation of Prague’s Žižkov Brownfield

The redevelopment of Prague’s former Žižkov Freight Station is moving into a new phase as transport infrastructure begins to advance alongside the residential and commercial projects planned across one of the capital’s largest regeneration areas.

Construction of a new tram connection between Olšanská and Habrová began on 31 August, adding an important piece of infrastructure to the emerging district. The route will run close to several planned developments in the area, including Yards Žižkov, a residential-led project being prepared by Cresco Real Estate.

The new Malešická and Nad Kapličkou stops are expected to improve public transport access across the former railway site and provide connections towards central Prague. Passenger services on the new section are scheduled to begin in 2027.

The tram investment is significant for the wider transformation of the Žižkov Freight Station because development of the extensive brownfield depends not only on delivering new housing but also on creating sufficient transport capacity, public amenities and connections with established surrounding neighbourhoods.

Cresco’s Yards Žižkov forms part of this broader redevelopment. The scheme is planned as a mixed urban neighbourhood combining residential buildings with commercial premises, public spaces and community facilities.

A kindergarten is included in the plans, while ground-floor areas are intended for shops and services. The development will also incorporate a new square and a pedestrian promenade running alongside the future tram corridor.

The urban and architectural concept has been prepared by QARTA Architecture. The design seeks to connect the new development with the existing character and scale of Žižkov while drawing on the industrial history of the former freight station.

Rather than functioning as a predominantly residential enclave, the project is being planned around a mixture of housing and everyday services. This approach is also intended to encourage walking, cycling and public transport for shorter journeys within the district.

The arrival of the tram infrastructure could prove particularly important as the population of the former industrial area increases. Large brownfield projects can place considerable pressure on surrounding roads and existing public transport when residential construction advances faster than supporting infrastructure.

At Žižkov, the challenge is larger because several individual developments are contributing to the transformation of the former railway land. Their long-term success will depend partly on how effectively housing, transport, streets, public spaces, schools, services and green areas are connected across the wider district.

Cresco argues that reducing the distance between homes and everyday amenities can decrease the need for residents to travel across Prague for routine activities. While the eventual travel patterns of residents will depend on employment locations and the range of services that ultimately occupy the development, the combination of mixed uses and improved public transport should provide alternatives to car-dependent development.

For Prague’s property market, the transformation of the Žižkov Freight Station represents more than the addition of another residential pipeline. It is gradually converting a major former industrial and railway site into an extension of the existing city.

With tram construction now underway and private developments progressing across the area, the focus is increasingly shifting from individual projects to whether the different components can be delivered as a coherent district. The coordination of transport infrastructure with residential development will be one of the most important factors determining how successfully this substantial part of Žižkov is integrated into Prague.

Dubai’s Housing Boom Enters a New Phase as Supply Accelerates

Dubai’s residential property market is moving into a more demanding stage of its expansion as a growing volume of completed housing reaches the market at the same time as sales activity begins to moderate.

During the first half of 2026, 104 real estate projects with an investment value exceeding AED 111 billion were completed across Dubai, compared with 75 projects during the same period last year. The number of completed projects increased by almost 39%, while their combined investment value rose by 52%, according to Dubai Land Department data cited by Kamco Invest.

Residential delivery was an important part of that increase. Some 24,537 new homes were completed during the first six months of the year, up from 18,043 in H1 2025. The value of land associated with completed developments also increased sharply, reaching AED 19.5 billion compared with AED 8.3 billion a year earlier.

The figures demonstrate the scale of Dubai’s development pipeline moving from construction into completed property. However, Q2 market research suggests this new supply is arriving as conditions in the residential market become more balanced after several years of exceptional growth.

Savills recorded around 35,900 residential transactions during Q2, representing a 19% decline from the previous quarter. Off-plan properties continued to dominate activity, accounting for approximately three-quarters of transactions, but average apartment prices declined by around 4% quarter-on-quarter while villa and townhouse values showed a smaller adjustment.

Research from Cushman & Wakefield Core similarly identified a change in market direction during Q2. More than 13,000 residential units were completed during the quarter, while average citywide sales prices and rents came under downward pressure. A further substantial volume of housing was expected to reach completion during the second half of 2026.

The combination marks an important transition for Dubai. For much of the recent property cycle, attention centred on the strength of off-plan sales and rapidly rising residential values. Increasingly, the investment question is shifting towards how effectively the market can absorb properties as projects reach completion and investors take possession.

This does not necessarily point to a market-wide oversupply problem. Dubai continues to benefit from population growth, international capital inflows and its position as a regional business centre. Furthermore, the number of properties formally scheduled for delivery frequently exceeds the number ultimately completed within the original timetable.

There are nevertheless signs that supply exposure is becoming more important in determining individual asset performance. Communities receiving large numbers of competing apartments may experience greater pressure on rents and resale pricing than established districts where new construction remains more restricted.

Developers also appear to be responding. Cushman & Wakefield Core reported a significant reduction in residential launches during the first half of the year compared with 2025. This could eventually moderate the volume of future supply, although projects already under construction will continue to feed completed stock into the market.

The change is particularly significant for investors who purchased properties during the recent off-plan boom. As developments are handed over, units that previously existed primarily as investment contracts become homes competing for tenants and buyers in the secondary market. Rental performance, service charges, location and the amount of competing supply within individual communities consequently become more important to investment returns.

Prime residential property continues to show greater resilience. Knight Frank recorded 296 Dubai homes sold for more than $10 million during H1 2026, with a combined value of approximately $5.1 billion. Of these, 131 transactions occurred during Q2.  The figures underline how conditions at the top of the market can differ substantially from those affecting mainstream apartment developments.

The emerging picture is therefore less one of a broad correction than a market becoming increasingly differentiated. Prime locations, established communities and developments with constrained competing supply may continue to perform differently from districts experiencing intensive construction and large numbers of simultaneous handovers.

There are signs of similar caution in the listed market. Dubai’s stock-market real estate sector declined 2.2% during August even as the broader DFM General Index increased 0.7%. Emaar Properties nevertheless remained the exchange’s most actively traded company by value during the month, with AED 4.2 billion of shares changing hands.

Dubai’s next property test will therefore be less about its ability to launch and sell projects than its capacity to absorb the homes already moving through the construction pipeline. With more than 24,500 residential units delivered during the first half alone, the transition from off-plan growth to completed stock is becoming increasingly visible.

For developers, investors and lenders, that makes absorption rates, rental performance and secondary-market liquidity increasingly important indicators. Dubai’s property expansion remains substantial, but the market entering the second half of 2026 is becoming more selective — and the performance gap between individual locations and projects is likely to become more important than the direction of the citywide market as a whole.

Germany’s Recovery Leans on Public Investment as Private Economy Struggles to Keep Pace

Germany’s economic outlook has improved following a stronger-than-expected first half of 2026, but the recovery remains heavily dependent on government spending while private investment, household demand and parts of the industrial economy continue to underperform.

The German Institute for Economic Research (DIW Berlin) now expects GDP to expand by 1.2% in 2026, followed by growth of 1.0% in 2027 and 0.7% in 2028. The upgrade reflects stronger export performance earlier in the year and a less severe energy-price shock than initially feared.

Germany’s economy expanded by 0.3% quarter-on-quarter during the second quarter. Foreign trade provided much of the momentum, with exports increasing by 2.0%. Petroleum products and chemical intermediate goods contributed to the improvement, while manufacturers of computing and electronic equipment benefited from international investment associated with the expansion of artificial intelligence infrastructure and data centres.

Domestic activity presents a less convincing picture. Private consumption increased by only 0.1% during the quarter, with households remaining cautious amid labour-market uncertainty and limited income growth. Business investment has also remained subdued, leaving government expenditure as an unusually important component of the recovery.

DIW estimates that public consumption and investment account for around 70% of Germany’s economic growth this year. Infrastructure expenditure, defence investment and higher government spending in areas including healthcare and social services are consequently supporting an economy in which private-sector demand has yet to generate comparable momentum.

This composition of growth has important implications for Germany’s property and construction markets. An economy expanding primarily through public investment can create opportunities for contractors, infrastructure providers and property markets connected with defence, transport, energy and other government-backed projects without necessarily producing an equivalent recovery across conventional commercial real estate.

Germany’s substantial infrastructure programme could therefore become one of the most important sources of construction demand over the next several years. Increased expenditure on transport networks and other public assets provides greater visibility for infrastructure-related construction at a time when privately financed development continues to face relatively difficult conditions.

Defence expenditure could have a similar effect in selected locations. Increased investment can generate requirements extending beyond military equipment to manufacturing facilities, logistics infrastructure, warehouses, research facilities and supporting supply chains. The property consequences are likely to be concentrated geographically rather than spread evenly across the country.

Technology investment provides another potential source of demand. The global expansion of AI-related infrastructure is already benefiting parts of Germany’s electronics and computing manufacturing sector. Continued investment in digital infrastructure could support industrial and data-centre-related activity, although the strength of the international AI investment cycle itself represents an increasingly important economic risk.

For traditional commercial property, the picture remains less straightforward. Weak private consumption provides limited support for consumer-dependent sectors, while cautious corporate investment restricts the prospects for a rapid improvement in occupier demand. Germany may therefore record stronger headline economic growth without immediately experiencing an equally broad recovery in offices, retail or privately financed development.

Industrial property also faces competing forces. Export growth helped Germany during the first half, but energy-intensive industries continue to operate in a challenging environment. Elevated gas prices remain a particular concern, while low water levels on important shipping routes are creating additional difficulties for chemicals, metals and other industries dependent on reliable transport and energy supplies.

DIW expects economic activity to lose momentum during the third quarter, with GDP broadly stagnating. Some of the export strength recorded earlier in the year may also have resulted from companies bringing forward activity because of uncertainty surrounding energy markets, meaning the first-half performance should not automatically be extrapolated into the remainder of 2026.

The labour market remains another constraint. DIW expects employment to decline from approximately 45.88 million people in 2025 to 45.68 million this year, while the unemployment rate is forecast to increase from 6.3% to 6.4%. Consumer-price inflation is projected at 2.7% in 2026 before easing to 2.6% next year and 2.0% in 2028.

Germany’s fiscal position is simultaneously becoming more expansionary. DIW forecasts a government deficit equivalent to 4.1% of nominal GDP this year, increasing to 4.6% in 2027 before easing slightly to 4.3% in 2028. The widening deficit reflects, among other factors, the greater role being played by public investment and expenditure.

For real estate investors, the headline improvement in GDP therefore tells only part of the story. The sectors most closely exposed to infrastructure, defence, technology investment and government expenditure may encounter substantially different conditions from property dependent on household consumption or broad-based corporate expansion.

Germany appears to be moving away from the stagnation that characterised much of the previous period, but the foundations of the recovery remain uneven. The critical question for property markets is whether government-supported investment can eventually stimulate stronger private capital expenditure, business expansion and household confidence.

Until that transition occurs, Germany’s commercial real estate recovery is likely to remain similarly divided: stronger where public spending and structural investment are creating demand, but considerably more cautious in sectors still waiting for the private economy to regain momentum.

AI Emerges as Productivity Tool as German Construction Sector Seeks Recovery

Artificial intelligence is beginning to move from experimentation towards practical use in Germany’s construction industry, with some of the clearest opportunities emerging in estimating, design, tender preparation, project documentation and construction monitoring. The shift comes as contractors continue to face pressure from weak building activity, elevated costs, skilled-labour shortages and financial risk.

Atradius expects AI to have its most immediate impact on activities involving large quantities of documents and project data. Construction companies routinely process specifications, quotations, invoices, variations, schedules and technical records, creating opportunities to automate parts of administrative work and accelerate the assessment of complex information.

Design and pre-construction could be among the areas experiencing the earliest changes. AI applications can generate and compare different design options and assess proposals against parameters including building regulations, project size and energy performance. Estimating and tender teams could similarly use the technology to process documentation and identify relevant information more quickly.

The potential extends onto construction sites. Increasing use of cameras, sensors and drones is creating larger quantities of digital information about projects. Combined with AI, these data can be analysed to follow construction progress, identify potential quality problems and support safety management.

David Engelhardt, Manager Risk Services at Atradius, expects these applications to become increasingly relevant to contractors. In his assessment, the barriers to wider adoption are increasingly connected with the availability and quality of data, workforce capabilities and regulation rather than the technology itself.

Further development could connect AI more closely with digital twins, robotics and automated project-management systems. Digital models could be used to assess the possible consequences of weather disruption, delivery delays or cost increases, while software agents could coordinate elements of scheduling, procurement and communication with subcontractors. Robotics could eventually reduce the amount of repetitive physical work required on construction sites.

The technology is emerging against a challenging economic background. Atradius forecasts that German construction output will decline by 1.6% in 2026, although this would represent a smaller contraction than the 3.7% fall recorded in 2024 and the 3.4% decrease in 2025.

There are nevertheless indications that some parts of the market are beginning to stabilise. Germany approved 21,600 homes in June 2026, according to figures cited by Atradius, representing an increase of 13.8% compared with the same month a year earlier. During the first six months of the year, approvals reached 126,300 homes.

The improvement needs to be considered against the substantial decline in residential construction experienced during previous years. An increase in permits also does not necessarily result immediately in construction starts, particularly while financing costs, development economics and construction expenses continue to influence project viability.

Infrastructure is providing greater support to the industry. Investment connected with railways, energy and heating networks, utilities, bridges and data centres is generating opportunities for contractors even as some conventional building segments remain subdued. Road construction has been weaker, while the additional infrastructure funding provided by the federal government has yet to produce a broad increase in industry order books, according to Atradius.

Financial pressure also remains visible. Germany recorded 735 construction-sector insolvencies between January and May 2026, compared with 744 during the corresponding period of 2025. Although the number of cases declined slightly, Atradius reports that losses associated with individual failures have become larger. The credit insurer also recorded a 6.2% year-on-year increase in reports of non-payment.

These conditions could make the financial case for AI more important than its technological novelty. Faster tender analysis, more accurate cost control, automated invoice checking and earlier identification of construction problems could help contractors reduce administrative workloads and protect margins in a sector where relatively small project errors can have significant financial consequences.

Atradius expects the broader construction market to improve from 2027 as increased public investment begins to reach projects. Its current forecast anticipates approximately 5% annual growth in German construction output in both 2027 and 2028, although the strength and timing of that recovery will depend partly on how quickly planned investment translates into procurement and construction activity.

AI is unlikely to remove the industry’s fundamental constraints, including planning delays, expensive materials, energy costs and shortages of skilled workers. Its more immediate significance may instead lie in helping construction businesses operate more efficiently within those constraints.

As Germany prepares for a potentially stronger infrastructure and construction cycle from 2027, the competitive divide may increasingly be determined not simply by which contractors adopt AI, but by which companies can successfully integrate it into estimating, procurement, project control and site operations to produce measurable improvements in cost, risk and delivery.

CTP Poland Approaches One Million sqm Leased as Expansion Accelerates

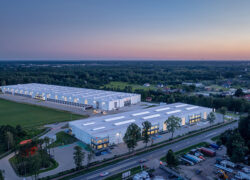
CTP is approaching a major scale milestone in Poland, with almost one million square metres of its industrial and logistics space now leased following several years of rapid portfolio expansion.

At the end of the first half of 2026, CTP had 996,840 sqm under lease in Poland. The company’s completed Polish portfolio has meanwhile reached approximately 1.092 million sqm, up from 218,000 sqm at the end of 2022. This represents more than a fivefold increase in completed space in around three and a half years.

Poland is also generating a disproportionately large share of the group’s current leasing activity. The country’s completed properties represent around 7.4% of CTP’s 14.8 million sqm European portfolio, while Polish transactions accounted for approximately 10.7% of the space leased by the group during the first six months of 2026.

CTP signed agreements covering approximately 168,000 sqm in Poland during H1, including space in existing properties, newly completed buildings and projects under construction. All of the Polish agreements signed during the period involved new customers, according to the company.

This differs from the wider European portfolio, where around 65% of leasing volume came from transactions with existing tenants. The comparison indicates that CTP’s Polish business is currently expanding its customer base alongside increasing its physical portfolio.

Demand in Poland came from several occupier groups. E-commerce and retail businesses represented almost 40% of H1 leased space, while logistics operators accounted for approximately 23%. Manufacturing companies, including businesses connected with renewable energy, generated around 17%.

One of the larger manufacturing transactions was a 29,000 sqm lease with Windar Renovables at CTPark Legnica. The renewable-energy equipment manufacturer provides an example of the type of industrial occupier CTP expects to become increasingly important as European companies adjust production and supply networks.

CTP Group CEO Remon Vos said demand remained strong across the company’s markets following record leasing during both quarters of the first half. He identified manufacturing localisation, rising consumer purchasing power and changes to European supply chains as important drivers, alongside emerging demand from industries including life sciences, defence, semiconductors, robotics, electric vehicles and batteries.

CTP has also been widening the geographical reach of its Polish platform. During the first half of the year, the developer announced projects in Suchy Las and Bydgoszcz, adding to a network that now comprises 20 parks. Sixteen of these are completed, with the company managing 35 operating buildings across 16 Polish locations.

Further development capacity is supported by approximately 2.6 million sqm of land held by CTP in Poland. The land portfolio gives the developer scope to add both speculative facilities and projects designed around the requirements of individual occupiers.

The pace of expansion in Poland forms part of continued growth across CTP’s wider European business. The group completed leases covering approximately 1.6 million sqm during H1 2026, an increase of 55% from the corresponding period of 2025.

Rental income also moved higher. Gross rental revenue reached €413.3 million, increasing 12.6% year-on-year, while net rental income rose 12.4% to €404.8 million.

Across its 11 European markets, CTP now owns approximately 14.8 million sqm of completed industrial and logistics property, with another 2 million sqm under construction. Its development land totals 33.7 million sqm, providing a substantial pipeline for future expansion.

The company continues to target €1 billion in annual rental income in 2027, making continued leasing and development across its larger Central and Eastern European markets important to achieving that objective.

Poland’s contribution is becoming increasingly significant. The combination of new customer acquisition, manufacturing requirements and continued demand from logistics, retail and e-commerce companies has enabled CTP to increase its Polish portfolio considerably faster than would be suggested by the country’s current share of the group’s completed European stock.

With leased space now less than 4,000 sqm short of the one-million-sqm threshold, the milestone itself is likely to be passed quickly. More significant for the industrial property market is the speed at which CTP has moved from a relatively small Polish presence at the end of 2022 to a portfolio exceeding one million sqm, backed by additional development land and expansion into new regional markets.

Ochnik Opens at Galeria Przymorze as Gdańsk Centre Refreshes Retail Mix

Galeria Przymorze in Gdańsk is continuing to reshape its retail offer with the addition of Polish fashion brand Ochnik, following several other recent changes to the shopping centre’s tenant line-up.

Ochnik opened its new store on 27 August, taking 386 sqm of space next to Pepco. The letting adds another established Polish retailer to the centre and forms part of a broader commercialisation strategy aimed at strengthening its mix of fashion, services and consumer brands.

Founded in 1989, Ochnik has developed from its original focus on leather clothing into a wider fashion and accessories business. Its current range covers women’s and men’s clothing, footwear, bags and accessories as well as luggage and travel products.

The arrival of Ochnik follows several other additions to Galeria Przymorze. The centre has recently expanded its tenant base with cosmetics retailer Douglas, optical chain Fielmann and travel agency ITAKA.

Agnieszka Wojtaszczyk, Director of Galeria Przymorze, said the centre is focusing on retailers that complement its existing offer and respond to customer demand. She added that the decision by another established brand to open at the property supports management’s assessment of the centre’s continuing attractiveness as a retail location.

The series of openings illustrates how established shopping centres are increasingly able to adjust their positioning through incremental leasing changes rather than relying exclusively on major redevelopment programmes. Introducing retailers across different categories can broaden the reasons for visiting a centre while replacing concepts that may no longer correspond with changing consumer habits.

For Galeria Przymorze, the recent changes span fashion, beauty, optical services and travel, creating a more diversified commercial offer. Ochnik’s 386 sqm store strengthens the fashion component while also adding product categories extending beyond conventional clothing.

The letting comes as Poland’s established shopping centres compete not only with newer schemes but also with the country’s expanding retail-park sector and online shopping. Maintaining an attractive tenant mix and adapting existing space to changing retailer requirements have consequently become increasingly important elements of asset management.

The latest opening represents another stage in that process at Galeria Przymorze, where a succession of new tenants is gradually refreshing the centre’s commercial offer and reinforcing its position within Gdańsk’s competitive retail market.

Fake Border Claims Attempt to Undermine Polish-Czech Relations

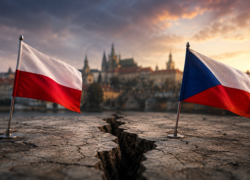
A coordinated online campaign has attempted to create friction between Poland and the Czech Republic by reviving an obscure historical border question and presenting it as evidence of a new territorial dispute between the two neighbouring countries.

The narrative suggested that Warsaw was preparing to seek Czech territory, despite there being no genuine political confrontation between the two governments over the issue. Instead, those behind the campaign appear to have combined fragments of historical fact with fabricated documents, impersonated officials and manipulated media content to make the story appear credible.

At the centre of the narrative was a border adjustment agreed between Poland and Czechoslovakia in 1958. Under the settlement, Poland transferred 1,205.9 hectares while receiving 837.46 hectares, creating a difference of 368.44 hectares. The discrepancy was never completely resolved, but for decades it has been handled as a technical matter between the countries rather than as an active territorial conflict.

The recent information campaign attempted to give this largely forgotten question a very different meaning.

One element involved the website of Polish regional broadcaster Radio PiK, where a fabricated story appeared following a cyberattack. A separate website designed to resemble Czech public radio was also reportedly used to give false information the appearance of legitimate journalism.

The campaign went further by creating social-media identities that appeared to belong to government representatives. One account impersonated the Czech ambassador to Poland and circulated a forged document supposedly showing that Poland wanted more than 600 hectares of Czech territory. Another profile presented itself as belonging to a Polish deputy foreign minister.

The difference between the historical 368-hectare imbalance and the considerably larger figure circulated through the false material is particularly important. The campaign was not simply drawing attention to an unresolved administrative question; it was constructing a new political narrative around it.

Those responsible also introduced Zaolzie into the story, bringing a considerably more sensitive historical issue into the campaign. The region became a source of Polish-Czechoslovak tension during the twentieth century and consequently provides considerably greater emotional potential than the technical border settlement of 1958.

False social-media material included claims about opposition to alleged Polish influence in the Czech city of Třinec. By connecting contemporary fabrications with historical disputes, the campaign attempted to make the suggestion of renewed Polish-Czech tensions appear more plausible.

The choice of Poland and Czechia is significant. Both countries are members of NATO and the European Union and have developed increasingly important political, economic and security cooperation. They have also been prominent supporters of Ukraine since Russia’s invasion.

At the same time, their shared history contains episodes that can be selectively presented to generate nationalist resentment. Modern influence campaigns do not necessarily need to invent an entirely new disagreement. An unresolved historical detail can instead provide the foundation upon which a much larger fictional confrontation is constructed.

Poland’s NASK disinformation specialists have indicated that techniques associated with the operation resemble methods previously identified in campaigns linked to Russian influence activity. Similar concerns have emerged on the Czech side.

That assessment, however, needs to be distinguished from definitive attribution. Publicly available evidence has not established conclusively that a particular Russian intelligence organisation or other specific group directed the operation. Similarity in methods can provide an indication of origin without constituting proof of who ordered or conducted a campaign.

Authorities and officials on both sides responded quickly to the false claims, rejecting suggestions that a territorial confrontation was developing and emphasising the strength of bilateral relations.

The attempt also appears to have struggled to move from manipulated websites and social media into established news coverage. Rather than reporting the supposed territorial dispute as genuine, mainstream reporting largely treated the material as an example of an effort to manufacture hostility between the two countries.

That outcome demonstrates one of the most effective defences against such operations: rapid verification before a fabricated narrative has time to establish itself.

The Polish-Czech case also illustrates how sophisticated disinformation does not have to be entirely fictional. In some circumstances, the most convincing false narratives begin with something that is demonstrably true.

The 1958 border adjustment happened. The resulting territorial imbalance exists as a historical issue. Zaolzie has a complicated Polish-Czech history. What changes the story is the artificial connection of those facts to invented contemporary demands, false government documents and impersonated officials.

This combination can be more persuasive than a completely fabricated story because readers encountering one verifiable element may assume that the surrounding claims are equally reliable.

The episode therefore has implications extending beyond relations between Warsaw and Prague. Central Europe contains numerous historical borders, minority questions and twentieth-century territorial changes that can be removed from their original context and repackaged for modern political purposes.

As Poland, Czechia and other countries in the region deepen cooperation on defence, energy, infrastructure and support for Ukraine, attempts to exploit historical sensitivities are likely to remain an information-security concern.

In this instance, the effort appears to have produced the opposite of its intended effect. Rather than triggering a serious diplomatic dispute, the fabricated territorial narrative resulted in Polish and Czech representatives publicly reinforcing the strength of their relationship.

The wider lesson is that disinformation can be most difficult to recognise when it contains enough genuine history to sound believable. The challenge for governments, media organisations and the public is therefore not simply identifying completely false stories, but recognising when authentic facts have been deliberately rearranged to manufacture a conflict that does not exist.

Source: WEI

De Haas Expands Logistics Capacity with 4,250 sqm Weiterstadt Lease

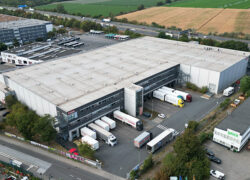
De Haas Road Cargo is relocating and expanding its German logistics operations with a new 4,250 sqm facility in Weiterstadt, strengthening its position on transport routes connecting the Frankfurt region with southern Germany and Austria.

The logistics company has agreed to occupy space at Gutenbergstrasse 19–21 in the Weiterstadt-Riedbahn industrial area, moving its existing operation from Hochheim am Main. The transaction was arranged by REALOGIS Immobilien Frankfurt, while the property is owned by  ⁠P3 Logistic Parks.

De Haas Road Cargo specialises in transporting flowers and plants, making efficient handling and reliable connections to regional and international road networks important elements of its operation. The relocation will provide the company with approximately 3,340 sqm of warehouse accommodation together with around 910 sqm of offices.

Immediate availability was among the factors influencing the choice of the property. The leased space also provides eight dock-level loading doors, allowing vehicles to be processed efficiently as goods move through the facility. De Haas intends to use the additional capacity to support further development of its transport activities, particularly towards southern Germany and Austria.

The building was completed in 2008 and provides approximately 11,350 sqm of warehouse accommodation and 2,650 sqm of offices in total. The lease demonstrates the continuing ability of established logistics properties to attract occupiers where location, loading infrastructure and operational functionality meet current requirements.

Weiterstadt-Riedbahn is located approximately six kilometres northwest of Darmstadt and benefits from connections to several of the region’s principal transport routes. The A5 motorway is readily accessible, while the B42 provides connections towards the A67. Frankfurt Airport is approximately 24 kilometres from the property.

For logistics operators, the location provides access to the wider Rhine-Main market while maintaining road connections towards southern Germany. This positioning was particularly relevant for De Haas as the company seeks to increase capacity and develop its transport network further south.

The transaction also illustrates the role of existing buildings in Germany’s logistics market. With occupiers increasingly focused on operational efficiency and the ability to commence operations without lengthy development periods, modern specifications are not the only factor determining competitiveness. Well-connected properties with sufficient loading capacity and suitable layouts can continue attracting specialist logistics companies even as buildings become older.

For P3, the agreement brings a specialist transport occupier into part of its Weiterstadt property, while for De Haas the move provides additional operational capacity without requiring a purpose-built development.

The lease adds another occupier transaction to the Frankfurt-Darmstadt logistics corridor, where access to major motorways, Frankfurt Airport and the wider Rhine-Main economic region continues to support demand. The De Haas relocation shows that immediately usable warehouse space in established transport locations can remain competitive when it provides the infrastructure required for increasingly specialised logistics operations.

front page info
LATEST NEWS