FCA Signals Shift Towards More Flexible AI Regulation in Financial Services

The UK’s financial regulator is reassessing its approach to oversight as artificial intelligence becomes increasingly embedded across financial services, according to a speech delivered by Nikhil Rathi at techUK’s Agents of Change conference.

Rathi, chief executive of the Financial Conduct Authority (FCA), said financial services will play a central role in the UK’s ambitions to become a leading AI economy by providing the capital, infrastructure and trust needed to support wider adoption of AI technologies.

According to the FCA, more than 80 percent of financial services firms are already using AI in some form. The focus is now shifting from experimentation to scaling deployment across retail and wholesale markets.

One area highlighted by the regulator is the emergence of so-called agentic AI systems, which are capable of carrying out actions and transactions rather than simply generating content or analysing data. Rathi said such systems could support functions ranging from personal financial management and investment strategies to liquidity management and trading operations.

He stressed, however, that accountability for regulated activities must remain clearly assigned and subject to appropriate human oversight.

The FCA also identified tokenisation as a significant development for financial markets. The regulator recently approved the launch of the UK’s first natively tokenised authorised investment fund by Baillie Gifford and Bank of New York Mellon. The FCA and the Bank of England are also consulting on the future development of tokenised wholesale markets.

Rathi argued that the pace of technological change is challenging traditional regulatory approaches and that legislation alone cannot keep pace with developments in AI. As a result, the FCA is placing greater emphasis on risk-based supervision, market stewardship and collaboration with industry participants.

The regulator is also exploring the use of agentic AI internally to enhance market surveillance and detect potential market abuse more quickly. The FCA currently processes around one billion rows of data daily as part of its supervisory activities.

The speech highlighted the growing importance of competition policy as AI lowers barriers to entry and accelerates market change. Rathi said the FCA expects to make more frequent use of its system-wide powers under UK competition legislation to address emerging risks and market developments.

At the same time, the regulator acknowledged that collaboration between firms may become increasingly necessary in areas such as open finance, data sharing and AI development.

The FCA also warned of growing resilience and cybersecurity risks linked to increasing dependence on cloud infrastructure, AI model providers and external technology suppliers. According to industry data cited by the regulator, the UK lost nearly £1.3 billion to payment fraud in the past year, with most authorised fraud cases originating through social media and messaging platforms.

Rathi noted that 98 percent of operational incidents reported to the FCA last year were related to technology or cyber issues. He said financial institutions should strengthen governance around third-party dependencies and ensure boards understand the risks associated with AI adoption.

To support innovation, the FCA continues to expand initiatives including its Supercharged Sandbox testing environment, AI Lab and AI Consortium, which it operates together with the Bank of England. The regulator plans to publish further guidance on AI practices later this year, alongside a review examining how AI could reshape retail financial services.

The FCA said its objective is to support the safe and responsible adoption of AI while maintaining competition, resilience and consumer confidence across the financial system.

Source: FCA

Hungary Expands Public Procurement Liability Rules for Economic Operators

Hungary has adopted Bill No. T/174, introducing amendments to the country’s Public Procurement Act (Act CXLIII of 2015), including changes that broaden the scope of liability for companies participating in public procurement procedures.

Under the new rules, the Public Procurement Disputes Board (PPDB) will be required to assess the conduct of economic operators when determining responsibility and imposing fines for public procurement infringements. The amendment also requires the PPDB to publish guidance on its fining principles and standard fine levels for specific violations.

The changes affect cases involving serious procurement breaches, such as the unlawful omission of a procurement procedure or violations of standstill requirements. Existing legislation allows fines of up to 15 percent of the estimated value of the procurement or the contract value.

According to the legislative justification accompanying the amendment, previous legislation did not explicitly address whether responsibility and sanctions could be imposed on economic operators for breaches of procurement rules, although such liability was not excluded. The amendment seeks to provide a clearer legal framework for assessing responsibility on both sides of a procurement relationship.

The justification refers to Case C-263/19 before the Court of Justice of the European Union, which confirmed that EU law does not prevent the imposition of sanctions on successful tenderers or contracting parties involved in unlawful contract modifications, provided that the principle of proportionality is respected.

Under the revised framework, the PPDB will be expected to examine factors including the nature of the operator’s obligations, whether its conduct contributed to the infringement, and what level of knowledge or diligence could reasonably be expected in the circumstances. The legislative reasoning suggests that companies entering into significant contracts with public-sector entities may be expected to recognise when a procurement procedure should have been conducted.

At the same time, the amendment indicates that sanctions may not be proportionate in cases where a contracting authority fails to carry out a procurement procedure but is not listed in the official register of contracting authorities, potentially limiting the ability of an economic operator to identify the issue.

The legislation distinguishes between contracting authorities and economic operators. While contracting authorities continue to bear broad objective responsibility for compliance, the conduct of economic operators will be assessed against standards of reasonable behaviour in the specific circumstances.

Legal practitioners note that several practical questions remain unresolved, particularly regarding what compliance measures companies will be expected to undertake before entering into contracts with public entities. Greater clarity is expected once the PPDB publishes its fining guidelines and develops a body of case law under the new provisions.

In addition to the changes concerning fines, the legislative package introduces amendments related to procurement transparency, public access and monitoring mechanisms, and an enhanced role for the Integrity Authority. The reforms also include new anti-corruption measures that allow contracting authorities to incorporate proportionate anti-corruption requirements into contract performance, extending compliance obligations beyond the tendering stage.

The amendments are intended to strengthen oversight and accountability within Hungary’s public procurement system, although their practical impact on market participants will depend on future regulatory guidance and enforcement practice.

Source: CMS

Skanska Awarded Contract for Cincinnati Convention Center Hotel Project

Skanska has signed a contract with an entity managed by Portman Holdings to construct a new Marriott hotel adjacent to the convention center in downtown Cincinnati.

The contract is valued at USD 325 million (approximately SEK 3.0 billion) and will be included in Skanska’s U.S. order bookings for the second quarter of 2026.

The project involves the development of a 61,400 sqm (approximately 660,500 sq ft), 21-storey hotel located opposite the First Financial Convention Center. The property will comprise 700 guest rooms and include conference facilities, meeting spaces, ballrooms, ground-floor retail areas, a rooftop terrace, and a skybridge linking the hotel to the convention center and nearby parking facilities.

According to the project partners, the development is intended to expand Cincinnati’s convention and hospitality infrastructure and support the city’s ability to host larger events.

Construction is scheduled to begin in June 2026, with completion expected by the end of 2028.

Tokyo’s Urban Transformation Enters a New Era of Mixed-Use Development

Tokyo is undergoing one of the most significant waves of urban renewal in its modern history. Across districts such as Yaesu, Toranomon, Shinagawa and Shibuya, large-scale projects are reshaping the capital’s skyline while redefining how people live, work and move through the city.

Unlike earlier redevelopment cycles that focused primarily on commercial expansion, the current generation of projects combines offices, housing, hospitality, retail, education, public amenities and transport infrastructure within integrated urban environments. The objective is not simply to add new buildings but to create highly connected districts capable of supporting Tokyo’s long-term economic competitiveness and quality of life.

Building Vertical Communities

A defining characteristic of Tokyo’s redevelopment strategy is the creation of large-scale mixed-use destinations. Rather than separating residential, commercial and civic functions, new projects are bringing these elements together within compact, high-density environments.

Around Tokyo Station, major redevelopment schemes are introducing new office space, residential units, retail facilities, educational institutions and public gathering areas within a single district. These developments are designed to maximise land efficiency while creating vibrant neighbourhoods that remain active throughout the day and evening.

A similar approach is evident in Toranomon, where multiple interconnected towers have transformed the area into a major business and lifestyle destination. The district now combines corporate headquarters, hospitality facilities, cultural attractions, residential accommodation and public spaces within a unified urban framework.

Shibuya is also continuing its transformation from a retail and entertainment centre into a multifunctional business district. Several major projects currently under construction will add substantial office, residential and commercial capacity over the remainder of the decade, reinforcing the area’s role as one of Tokyo’s most dynamic urban centres.

Meanwhile, Shinagawa is emerging as another strategic growth corridor. Large redevelopment sites are attracting major corporate occupiers alongside hotels, retail facilities and new public infrastructure, supporting the area’s evolution into a key gateway district for both domestic and international business activity.

Transport Connectivity at the Core

One of the most important aspects of Tokyo’s redevelopment model is the close integration between real estate projects and transportation infrastructure.

Rather than treating stations as separate transport facilities, developers are increasingly designing entire districts around rail hubs, pedestrian networks and public transit connections. This approach improves accessibility, reduces reliance on private vehicles and supports sustainable urban growth.

Shibuya Station provides one of the clearest examples of this strategy. Serving millions of passengers every day, the station area has undergone a long-term transformation aimed at improving passenger circulation, accessibility and connectivity between different transport modes. The redevelopment extends beyond the station itself, creating new public spaces, commercial facilities and pedestrian routes throughout the surrounding district.

Around Tokyo Station, redevelopment projects are similarly enhancing connections between rail services, metro networks and surrounding commercial districts. New underground walkways and public spaces are helping to improve pedestrian movement while linking previously disconnected parts of the city centre.

Expanding Public Realm and Green Space

While Tokyo remains one of the world’s most densely populated metropolitan areas, recent redevelopment projects place increasing emphasis on public space, landscaping and environmental quality.

Developers are incorporating plazas, parks, rooftop gardens and pedestrian-friendly environments into projects that would once have been dominated solely by commercial uses. These spaces are intended to improve the urban experience for residents, workers and visitors while contributing to broader sustainability objectives.

The integration of green infrastructure has become particularly important as Tokyo seeks to enhance resilience, reduce urban heat effects and create more attractive environments for global businesses and talent.

Supporting Future Growth

Urban renewal is also being supported by continued investment in transportation infrastructure beyond central Tokyo. Proposals for new rail connections and transit improvements aim to strengthen links between the city centre, waterfront districts and major international gateways, including Haneda Airport.

Improved connectivity is expected to support future commercial development while enhancing Tokyo’s position as a leading international business destination.

Outlook

Tokyo’s latest redevelopment cycle represents more than a construction boom. It reflects a broader shift toward integrated urban planning that combines real estate, mobility, public space and sustainability within a single development model.

As projects in Yaesu, Toranomon, Shibuya and Shinagawa continue to progress, they are creating a new generation of urban districts designed to meet the evolving needs of residents, businesses and international investors. Together, these developments are reinforcing Tokyo’s position as one of the world’s most innovative and resilient metropolitan centres while setting new benchmarks for large-scale mixed-use urban regeneration.

Source: © CIJ.World Japan Research & Analysis Team

Japan’s Semiconductor Revival Sparks a New Wave of Industrial Real Estate Development

Japan’s efforts to rebuild its semiconductor manufacturing capabilities are generating far-reaching effects well beyond the technology sector. Across Kyushu, particularly in Kumamoto Prefecture, a surge in investment is transforming industrial land markets, accelerating infrastructure projects and creating new demand for housing, logistics facilities and commercial development.

At the centre of this transformation is the rapid expansion of advanced chip manufacturing capacity, supported by a combination of government incentives, foreign direct investment and private-sector capital. What began as an industrial policy initiative aimed at strengthening supply chain resilience has evolved into one of the most significant regional development stories in Japan.

Kumamoto Emerges as a Strategic Manufacturing Hub

Kumamoto has become one of the focal points of Japan’s semiconductor strategy. Major investments in fabrication facilities have attracted a growing network of suppliers, equipment manufacturers, logistics operators and service providers, creating a rapidly expanding industrial ecosystem.

The region’s appeal stems from several factors, including available land, access to water resources, an established manufacturing base and proximity to other technology clusters across Kyushu. As production capacity expands, industrial demand is spreading beyond the manufacturing plants themselves and into supporting sectors that require warehousing, distribution facilities, research centres and specialised infrastructure.

The scale of investment is reshaping perceptions of Kumamoto from a regional city into one of Japan’s most important technology and manufacturing destinations.

Industrial Land and Logistics Demand Accelerate

The expansion of semiconductor manufacturing has triggered strong demand for industrial land across the region. Developers are actively seeking sites suitable for factories, supplier facilities and logistics operations, while municipalities are working to prepare additional industrial zones to accommodate future growth.

Demand for modern logistics facilities has also increased as semiconductor production requires highly sophisticated supply chains involving precision components, specialised materials and time-sensitive deliveries. As more suppliers establish operations near major production facilities, the need for distribution infrastructure continues to expand.

This has created new opportunities for industrial real estate investors, particularly those focused on build-to-suit developments and modern logistics assets capable of serving advanced manufacturing occupiers.

Infrastructure Investment Becomes a Priority

The rapid pace of industrial growth has placed increasing pressure on local infrastructure. Roads, utilities and public transport systems are facing greater demand as construction activity intensifies and employment expands throughout the region.

Traffic congestion has emerged as a growing concern around major industrial sites, prompting local and national authorities to accelerate infrastructure improvements. Investment in transport networks, utility upgrades and site preparation is becoming a critical component of the region’s long-term development strategy.

The experience highlights a broader lesson increasingly relevant across global manufacturing markets: industrial expansion requires supporting infrastructure to develop at a similar pace if growth is to remain sustainable.

Housing Market Feels the Impact

The arrival of new employers and thousands of workers has also begun to reshape local residential markets. Demand for housing has increased significantly as engineers, technicians, construction specialists and service-sector employees relocate to the area.

Developers are responding with new residential projects, but supply has struggled to keep pace with demand in some locations. Rising housing costs and limited availability of modern accommodation have become increasingly visible challenges for local authorities seeking to support economic growth while maintaining affordability.

The situation has created opportunities for residential developers, investors and operators of rental housing, particularly in communities located near major employment centres.

Beyond Manufacturing: The Return of “Silicon Island”

The current wave of investment is reviving Kyushu’s historical reputation as one of Japan’s most important technology production regions. While the area has long maintained a presence in electronics manufacturing, recent investments are attracting a new generation of companies focused on advanced semiconductors, materials science, research and development, and precision engineering.

This broader ecosystem is expected to generate long-term demand across multiple real estate sectors, including industrial, logistics, residential, hospitality and business parks. Universities, research institutions and training facilities are also likely to play an increasingly important role as companies compete for highly skilled talent.

Outlook

Japan’s semiconductor resurgence is becoming one of the strongest drivers of regional economic development and industrial real estate activity in the country. Supported by government policy, international investment and growing demand for advanced technologies, Kumamoto and the wider Kyushu region are emerging as strategic locations within the global semiconductor supply chain.

For the real estate sector, the implications extend well beyond factory construction. Industrial parks, logistics facilities, housing developments and infrastructure projects are all benefiting from the manufacturing expansion. As investment continues to flow into the sector, the semiconductor industry is likely to remain a key force shaping Japan’s property market and regional growth strategies throughout the coming decade.

Source: © CIJ.World Japan Research & Analysis Team

Resilience and Sustainability Drive a New Investment Strategy in Japan’s Real Estate Market

Environmental performance and earthquake resilience are increasingly shaping investment decisions across Japan’s real estate sector. What were once considered separate areas of risk management and sustainability have become closely linked, creating a new framework through which investors evaluate property assets.

As climate targets become more ambitious and concerns over natural disasters remain ever-present, developers, lenders and institutional investors are placing greater emphasis on energy performance, carbon reduction and structural resilience. This shift is influencing everything from asset valuations and financing conditions to redevelopment strategies and long-term portfolio planning.

The Growing Divide Between Old and New Buildings

One of the most important distinctions in the Japanese property market remains the seismic standard under which a building was constructed. Buildings completed before June 1981 were designed according to older earthquake regulations and are generally viewed as carrying higher structural risk than properties developed under subsequent standards.

As a result, older buildings often face additional scrutiny during acquisition and financing processes. Investors frequently commission structural assessments to determine whether seismic upgrades have been completed and whether a property can meet contemporary safety expectations. Financial institutions have also become increasingly cautious, with lending terms often reflecting the perceived resilience of an asset.

Properties built after the introduction of modern seismic regulations generally attract stronger investor interest, while more recent developments benefit from increasingly sophisticated engineering standards designed to improve performance during major earthquakes.

Retrofitting Gains Momentum

Rather than replacing ageing buildings through demolition and reconstruction, many owners are turning to renovation programmes that improve both structural safety and environmental performance.

Government policies are encouraging this transition through financial incentives aimed at reducing energy consumption and accelerating the modernisation of existing building stock. Support programmes are helping owners invest in insulation upgrades, energy-efficient equipment, renewable energy systems and building management technologies.

The approach reflects a growing recognition that upgrading existing buildings can deliver significant environmental benefits while preserving valuable urban assets. In many cases, refurbishment projects require fewer resources and generate lower carbon emissions than constructing entirely new buildings.

Several projects across Japan have demonstrated that even older office buildings can achieve high levels of energy performance after renovation. These examples are helping to strengthen investor confidence in retrofit strategies as a viable long-term investment approach.

Carbon Reduction Becomes a Business Priority

Japan has committed to substantial reductions in greenhouse gas emissions over the coming decades, placing increasing pressure on the built environment to improve its environmental performance.

The property sector plays a central role in achieving these objectives. Buildings account for a significant share of energy consumption and carbon emissions, making energy efficiency improvements essential to national decarbonisation efforts.

Investors are responding by incorporating environmental performance metrics into asset selection and portfolio management decisions. Green certifications, energy ratings and sustainability reporting have become increasingly important factors when evaluating investment opportunities.

Research across global real estate markets suggests that sustainable buildings can benefit from stronger tenant demand, lower operating costs and improved rental performance. As a result, environmental upgrades are increasingly viewed not only as a regulatory requirement but also as a means of protecting asset value and enhancing long-term returns.

Insurance and Risk Management Take Centre Stage

Natural disaster exposure remains one of the defining characteristics of Japan’s property market. Earthquakes, typhoons and flooding continue to influence investment decisions, particularly as climate-related risks become more pronounced.

Insurance providers increasingly differentiate between assets based on construction quality, resilience measures and structural performance. Buildings that demonstrate higher levels of earthquake resistance can often benefit from more favourable insurance conditions, creating additional incentives for owners to invest in upgrades.

For institutional investors, resilience has become an essential component of environmental, social and governance strategies. Assessing a building’s ability to withstand future shocks is now considered as important as evaluating its financial performance.

A New Investment Framework

Japan’s real estate market is entering a period in which sustainability and resilience are no longer viewed as optional enhancements. Instead, they are becoming fundamental criteria that influence asset pricing, financing availability and investor demand.

The combination of stricter environmental goals, ageing building stock and ongoing exposure to natural disasters is accelerating the modernisation of the country’s property sector. Investors are increasingly focusing on assets that can meet both decarbonisation objectives and seismic safety expectations, while developers are integrating these considerations into project design from the outset.

As capital continues to flow toward higher-quality, future-ready buildings, resilience and sustainability are expected to become defining characteristics of Japan’s next generation of real estate investment opportunities.

Copyright: CIJ.World Japan Research & Analysis Team

Global Wealth Fuels a New Era for Tokyo’s Luxury Housing Market

Tokyo’s high-end residential sector has become one of the strongest-performing luxury housing markets in the world, supported by growing international demand, limited new supply and Japan’s increasing appeal as a destination for capital preservation. After decades in which residential values showed only modest growth, the city is now attracting attention from global investors, wealthy individuals and international buyers seeking stability amid geopolitical uncertainty and economic volatility elsewhere.

The strength of demand has been particularly evident in Tokyo’s most exclusive neighbourhoods, where competition for premium residences continues to intensify. Buyers from Asia, North America and Europe are increasingly viewing Japan as a secure long-term investment destination, benefiting from political stability, transparent legal structures and comparatively attractive pricing when measured against other leading global cities.

Foreign purchasers are playing a growing role in the market, particularly within Tokyo’s central districts. Industry estimates suggest that international buyers now account for a significant share of transactions involving newly completed luxury apartments in some of the capital’s most sought-after residential areas. This shift is reshaping ownership patterns and reinforcing demand for high-quality developments in prime locations.

Luxury Values Continue to Climb

Tokyo has emerged as one of the strongest performers among major global luxury residential markets. Rising demand, combined with a limited pipeline of available properties in prime locations, has supported sustained growth in capital values across the city’s premium housing sector.

The strongest appreciation has been recorded in the ultra-prime segment, where scarcity and exclusivity remain key drivers. Demand for larger residences, premium amenities and landmark developments has increased substantially, creating a widening gap between luxury and ultra-luxury assets. High-net-worth buyers are increasingly prioritising location, privacy, services and long-term asset preservation over short-term market considerations.

Despite recent price growth, many international investors still view Tokyo as offering relative value compared with luxury residential markets in cities such as London, Hong Kong, Singapore and New York, supporting continued investment activity.

Branded Residences Gain Momentum

A growing number of developers are introducing branded residential concepts to the Japanese market, a segment that remains relatively small but is expanding rapidly. These developments combine private residences with hospitality-inspired services, offering residents access to concierge support, wellness facilities, security and luxury lifestyle amenities associated with internationally recognised hotel brands.

Although branded residences are well established in markets such as Dubai, Miami and Singapore, they remain a relatively new product category in Japan. Industry observers expect the sector to expand significantly over the coming years as developers respond to rising demand from affluent domestic and international buyers.

Several major projects currently under development are expected to introduce a new level of luxury accommodation to Tokyo’s residential market. The combination of limited supply, premium services and prestigious branding is likely to further elevate the city’s position within the global luxury housing sector.

Mixed-Use Redevelopment Reshaping Prime Districts

The transformation of Tokyo’s luxury residential market is closely linked to a broader wave of large-scale urban redevelopment projects. New mixed-use districts are combining residential, office, retail, hospitality and public spaces within integrated environments designed to meet the changing needs of residents and businesses.

Among the most significant examples is the redevelopment of central Tokyo districts into high-density urban destinations that prioritise walkability, sustainability and access to services. These projects are creating entirely new residential ecosystems that appeal to both domestic residents and international buyers.

Large-scale developments are also incorporating substantial green areas, educational facilities, cultural attractions and premium hospitality offerings. This integrated approach is helping to enhance quality of life while maximising land use efficiency in one of the world’s most densely populated urban environments.

Outlook

Tokyo’s luxury residential market has undergone a remarkable transformation over the past several years. Supported by international capital flows, limited supply and a new generation of mixed-use developments, the city has strengthened its position among the world’s leading destinations for wealth-driven real estate investment.

While affordability challenges remain a concern for the broader housing market, the outlook for the premium segment remains positive. Continued redevelopment activity, growing international interest and the expansion of branded residential projects are expected to support further growth in Tokyo’s luxury housing sector.

For investors and developers alike, Tokyo is no longer viewed as a mature market defined by stability alone. It is increasingly becoming one of the most dynamic luxury residential destinations in the Asia-Pacific region, attracting both capital and residents seeking long-term security, quality and global connectivity.

Bucharest Could Be Entering a Supply-Constrained Growth Cycle

Residential prices in Bucharest remain significantly below those seen in regional capitals such as Warsaw, Prague and Budapest, despite Romania recording one of the strongest economic growth stories in Central and Eastern Europe over the past decade. While political uncertainty and permitting challenges have slowed market activity, many investors continue to view the Romanian capital as one of the region’s most compelling long-term residential opportunities.

In a recent interview with CIJ EUROPE, Vlad Musteata, CEO of North Bucharest Investments, the combination of affordability, improving infrastructure and a growing shortage of new housing supply is creating conditions that could support a new phase of market growth.

“If we compare Bucharest with other capitals today, I think it is one of the safest and most affordable cities in Europe,” says Musteata. “Foreign investors come here and are often surprised. They see the quality of the city, especially the northern part of Bucharest, and they realise the economic level is higher than current residential prices suggest.”

His assessment comes at a time when Bucharest continues to trade at a substantial discount to many of its regional peers. While prime residential prices in Prague and Warsaw have moved well beyond €5,000 per sqm in many locations, much of Bucharest’s residential market continues to offer significantly lower entry points, particularly in emerging districts and suburban growth corridors.

According to Musteata, this pricing gap reflects a market that has yet to fully align with its underlying fundamentals.

When international investors compare Bucharest with cities such as Warsaw, Prague or Budapest, Musteata believes many are asking the wrong question.

Rather than comparing Bucharest with where those markets stand today, he argues investors should compare them with where they were ten or fifteen years ago.

Romania remains one of the fastest converging economies in Europe, while Bucharest continues to attract multinational companies, highly skilled talent and foreign investment. For investors, this creates a rare combination of growth potential, attractive rental yields and long-term capital appreciation.

In many mature European capitals, investors are increasingly forced to choose between yield and growth. In Bucharest, both can still be achieved within the same investment.

Buyers Waiting on the Sidelines

One of the defining characteristics of the current market, according to Musteata, is the growing disconnect between buyer demand and transaction activity.

Over the past two years, political uncertainty has encouraged many local buyers to postpone purchasing decisions. Rather than abandoning the market, he believes many households have simply adopted a wait-and-see approach.

“A lot of buyers have the money available, but they are waiting to see what happens politically,” he says. “They continue postponing decisions and telling themselves they will wait a little longer.” The challenge, he argues, is that while demand has slowed, supply has not increased.

When confidence eventually returns, Musteata expects many of these delayed buyers to re-enter the market simultaneously, creating additional pressure on an already constrained residential pipeline.

While some market observers may consider forecasts of rapid price appreciation ambitious, the underlying supply-demand imbalance is becoming increasingly difficult to ignore.

Supply Constraints Are Becoming the Defining Story

Perhaps the most important trend shaping Bucharest’s residential market is not demand, but supply.

Several years ago, developers and consultants began warning that permitting delays and planning restrictions would eventually lead to a shortage of new residential product. According to Musteata, that prediction is now becoming reality.

“We expected a shortage of new buildings in the city, and now it is happening,” he says. “In sectors one and two especially, we see very few new launches.”

The lack of new projects entering the market has become increasingly noticeable in Bucharest’s most sought-after districts. Existing new-build developments continue to attract buyers, while the future development pipeline remains relatively limited.

For investors, this dynamic may prove more significant than short-term fluctuations in sentiment. Limited supply has historically supported pricing even during periods of slower transaction activity, and many market participants believe the current situation could create upward pressure on values over the medium term.

Three Areas Offering Opportunity

While much of northern Bucharest has experienced significant development over the past decade, Musteata still identifies several locations where he believes investors can find attractive value.

One is the Fabrica de Glucoză area, where multiple residential developments have created increased competition among developers. This environment has generated pricing opportunities that he believes may not remain available for long.

Another is the Șoseaua Pipera corridor between Promenada and Pipera, where several major projects are currently competing for buyers.

The third is the Iancu Nicolae district, one of the capital’s most established family-oriented residential locations. Strong demand from residents seeking proximity to international schools continues to support the area’s long-term appeal, while pricing differences between nearby projects can still create investment opportunities.

These locations, according to Musteata, represent areas where buyers can still benefit from the combination of improving infrastructure and relatively attractive pricing.

Infrastructure Could Transform Northern Bucharest

If supply constraints represent one side of the growth story, infrastructure represents the other. Major investments including the M6 metro extension towards Otopeni Airport and the continued development of the A0 Bucharest Ring Road are expected to reshape connectivity across the metropolitan area during the second half of the decade.

For Musteata, these projects could prove transformative for communities located just outside Bucharest’s traditional boundaries.

“Today some areas are underappreciated because infrastructure is not yet complete,” he says. “When the metro and road projects are finished, these communities will effectively become much closer to the city.”

Historically, North Bucharest became the city’s strongest residential market because it successfully combined employment, infrastructure, education and lifestyle.

Looking toward 2030, Musteata believes connectivity will become even more important than geography.

The M6 metro extension, the continued expansion of the A0 Bucharest Ring Road and other transport investments have the potential to create entirely new residential growth corridors across the metropolitan area.

Areas that today appear peripheral may become some of the best-connected locations in the region. Across Europe, accessibility has consistently been one of the strongest drivers of residential value creation, and Bucharest is likely to follow the same pattern.

Locations such as Voluntari, Otopeni and other northern Ilfov districts currently trade at discounts to comparable Bucharest neighbourhoods, largely due to transportation limitations. Improved connectivity could narrow that gap considerably over the coming years.

The result may be the emergence of entirely new residential growth corridors extending beyond the traditional boundaries of northern Bucharest.

Institutional Capital Remains on Hold

Despite the growing maturity of Romania’s residential market, large-scale institutional investment remains relatively limited compared with markets such as Poland or the Czech Republic.

Musteata attributes much of this to geopolitical uncertainty.

Institutional investors tend to be highly risk-conscious, and the war in neighbouring Ukraine has caused many international funds to adopt a cautious approach toward the wider region.

However, he believes that caution has also created an opportunity.

“Our market has been under-financed by large institutional investors,” he says. “When they return, they will find opportunities and returns that are increasingly difficult to achieve in Western Europe.” Rather than targeting individual units, Musteata expects future institutional investors to focus on acquiring entire residential buildings, purpose-built rental schemes and alternative residential sectors such as student housing.

Despite current caution among international funds, Musteata believes Bucharest is significantly closer to attracting institutional residential capital than many market participants realise.

The fundamentals already exist: a large and growing capital city, strong employment, increasing demand for rental housing and residential yields that remain attractive by European standards.

What the market still needs is greater scale, more professionally managed residential assets and a larger stock of institutional-grade product.

“The question is no longer whether institutional capital will come to Bucharest,” he says. “The question is how quickly the market can create the type of opportunities large investors are looking for.”

Several developers are already exploring projects designed specifically to attract long-term capital rather than individual apartment buyers.

The Market Is Growing Up

While pricing remains a central topic, Musteata believes the next phase of Bucharest’s residential evolution will be defined by quality rather than affordability alone.

Compared with projects delivered five years ago, today’s developments increasingly focus on architecture, sustainability, energy performance and lifestyle amenities.

Musteata believes the next phase of Bucharest’s residential evolution will be defined by differentiation.

For many years, demand was strong enough that almost any well-positioned project could attract buyers and investors. Rising incomes, economic growth and supply shortages supported both transaction volumes and price appreciation.

That dynamic is beginning to change.

The market is becoming more sophisticated, capital is becoming more selective and buyers are more informed than ever before.

Location remains important, but location alone is no longer enough.

Investors today analyse infrastructure, connectivity, rental demand, developer credibility, construction quality and long-term positioning.

Technology, branding, ESG performance and community creation will all play important roles, but none of them will be decisive on their own.

The projects that outperform will be those capable of presenting a compelling long-term value proposition and a clear reason why they deserve capital.

Developers are investing more heavily in near-zero energy building standards, improved façades, public spaces and community infrastructure. Schools, kindergartens, healthcare services and retail amenities are becoming essential components of larger residential schemes.

“People no longer want only an apartment,” Musteata says. “They want a complete community.” This shift reflects a broader maturation of the market as buyers become more sophisticated and developers compete through quality rather than simply location or price.

Looking Beyond the Headlines

Political uncertainty continues to dominate public discussion in Romania, and many buyers remain cautious as a result. Yet beneath the headlines, several structural trends are moving in a different direction.

Supply remains constrained. Infrastructure investment is accelerating. Residential quality continues to improve. International investors are becoming increasingly aware of the market, while institutional capital remains largely absent.

Whether the next growth cycle arrives in one year or three, Musteata believes the underlying fundamentals are becoming increasingly difficult to overlook.

Looking further ahead, Musteata believes Bucharest has the potential to evolve beyond a residential growth story and become one of the region’s leading business, technology and lifestyle hubs.

The city already benefits from a strong technology sector, a growing startup ecosystem, major multinational employers and one of the largest pools of highly skilled talent in Central and Eastern Europe.

“If infrastructure continues to improve, Bucharest has every ingredient needed to become one of the most attractive cities in the region for investment, living and doing business,” says Musteata.

For investors willing to take a long-term perspective, Bucharest’s combination of affordability, infrastructure investment and limited supply may represent one of the most compelling residential opportunities currently available in Central and Eastern Europe.

© 2026 CIJ EUROPE

Aequitas Real Estate Launches to Focus on Value-Add and Restructuring Opportunities

Thomas Bergander and Sven-Christian Frank have launched Aequitas Real Estate GmbH, a Munich-based real estate investment manager focused on value-add assets and restructuring situations in Germany.

The new company will target residential and office properties, with a particular focus on complex transactions, including portfolio acquisitions, development site investments, corporate takeovers and restructuring-related opportunities. The founders aim to build an investment portfolio with a volume of approximately €1 billion over the next three to five years.

Aequitas Real Estate will be led by Bergander and Frank as managing partners. Bergander is the owner and managing director of Berlin-based developer Taurecon GmbH, while Frank is a lawyer and former member of the management board of Adler Group.

The company plans to work with external strategic partners on a project-by-project basis. According to Aequitas, these collaborations will provide access to transaction opportunities, financing expertise and legal structuring support without involving equity participation or board appointments.

Among the strategic partners supporting the platform are Michael Zahn, who will assist with deal sourcing and investor relations; Francesco Fedele, CEO of BF.direkt AG, who will advise on financing and debt structuring; and Dr. Kristian J. Heiser, partner at Raschke von Knobelsdorff Heiser, who will support transaction structuring.

Frank said the company aims to combine transaction sourcing, capital access and execution capabilities within a single platform focused on institutional investment opportunities in the German-speaking region.

Bergander noted that the current market environment is creating opportunities in value-add and restructuring situations as property owners continue to face refinancing challenges and investors adopt a more selective approach to acquisitions.

Aequitas Real Estate will focus primarily on opportunities in Germany, while targeting cross-border investors seeking exposure to more complex real estate transactions.

Manova Partners Acquires Industrial and Logistics Property in Nashville

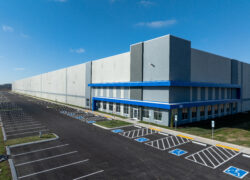
Manova Partners has acquired Gateway 65, a manufacturing and logistics property in the Greater Nashville area of Tennessee, on behalf of a separate account mandate.

The asset, completed in 2025, is fully leased to a company operating as the North American headquarters of an international industrial protection and safety solutions provider. The lease has a remaining term of 10 years. Financial details of the transaction were not disclosed.

Gateway 65 is located within Nashville’s northern I-65 Corridor, a major industrial and logistics submarket situated along Interstate 65, one of the principal transportation routes in the United States.

The property comprises approximately 28,450 sqm of gross floor area and includes manufacturing, distribution and office space. The facility features clear ceiling heights of approximately 11 metres, 10 loading docks and capacity for future expansion through the addition of up to 45 further dock doors.

Christian Göbel, Co-CEO of Manova Partners, said the acquisition forms part of the company’s strategy of targeting logistics and industrial assets in U.S. growth markets.

According to Manova Partners, Nashville continues to benefit from strong population and economic growth. The company cited industrial vacancy rates in the northern Nashville submarket of 5.3 percent, compared with a national average of approximately 8 percent.

Alin Sigheartau, Head of US Transactions at Manova Partners, noted that the acquisition follows the company’s disposal of the Nashville West Shopping Center in March 2026 and represents a renewed investment in the local market.

The transaction expands Manova Partners’ industrial and logistics portfolio in the United States and adds a fully leased asset with long-term income security in one of the country’s established distribution corridors.

front page info
LATEST NEWS