Political Voices Emerge as Spy Allegations and Security Tensions Spread Across Europe

A wave of espionage and security concerns has swept through Europe this week, triggering political fallout from Brussels to Warsaw and stirring debates over trust, transparency and accountability inside the European Union. Allegations of a Hungarian-linked spy network, fresh espionage charges in Poland, and heightened terror alerts in Belgium and the Netherlands have created an atmosphere of heightened vigilance — just as NATO begins one of its most sensitive nuclear security exercises in years.

At the centre of the political storm is Olivér Várhelyi, Hungary’s European Commissioner for Neighbourhood and Enlargement, who is facing scrutiny after reports surfaced of an alleged spy network operating in Brussels during his previous diplomatic posting. The European Commission confirmed that President Ursula von der Leyen intends to raise the matter personally with Várhelyi, as pressure mounts from lawmakers and civil society groups to investigate the extent of the allegations.

“Every commissioner must uphold the highest standards of integrity and accountability,” von der Leyen’s office said in a statement that stopped short of confirming any formal disciplinary steps.

Calls for stronger institutional oversight have grown louder. Transparency International urged the European Parliament to establish a special inquiry committee, warning that if the allegations prove credible, they would represent “a serious breach of public trust and a dangerous precedent for EU governance.” A group of 60 academics from 30 European universities signed an open letter demanding that Parliament assess whether Várhelyi’s continued tenure is compatible with the EU’s ethical standards.

Meanwhile, in Budapest, Hungarian Foreign Minister Péter Szijjártó downplayed the controversy, accusing critics of “politicising routine diplomatic activities.” He did not explicitly deny the reports but framed them as “an extension of Brussels’ bias against Hungary’s independent foreign policy.”

In Warsaw, Polish prosecutors have charged a former city registry employee with allegedly helping Russian operatives obtain false identities. Investigators claim the suspect, identified as Tomasz L., illegally copied civil records between 2017 and 2022. The case, now before the courts, has been presented by Polish officials as part of a wider effort to counter Russian intelligence infiltration in the EU.

Former Interior Minister Mariusz Kamiński described the incident as “proof that Russian espionage remains active in the heart of Europe,” adding that Poland’s security services had been “dismantling networks posing as diplomatic channels.” The Internal Security Agency (ABW) said the compromised data could have been used to create “operational identities” for foreign agents across multiple European states.

In the Netherlands, far-right politician Geert Wilders temporarily suspended campaign events after Belgian authorities arrested suspects allegedly plotting attacks against European politicians. The move reflects rising unease over security coordination within the EU — particularly as cross-border threats intersect with political campaigns. Wilders, who has lived under police protection for nearly two decades, said in a statement that “the threats are constant, but this one feels more organised.”

The timing of these developments has amplified anxiety ahead of NATO’s Steadfast Noon exercise, a two-week nuclear deterrence drill hosted by the Netherlands. The operation will involve over 70 aircraft and new measures focused on protecting nuclear storage facilities amid concerns over foreign surveillance near European bases. NATO insists the exercise “is not directed at any country” but acknowledges that the “security environment is more complex than in past years.”

Together, the espionage allegations and heightened security posture illustrate the shifting geopolitical fault lines within Europe — between transparency and secrecy, sovereignty and shared governance, accountability and denial.

Von der Leyen’s insistence on “clarity and confidence within EU institutions” contrasts sharply with the Hungarian government’s defensive tone, while Poland’s firm rhetoric reinforces its identity as a front-line state in Europe’s hybrid confrontation with Russia.

As investigations unfold in Brussels and Warsaw, and NATO continues its military coordination, European leaders face a difficult balance: reassuring citizens that security and democracy can coexist, while acknowledging that espionage, influence, and mistrust are no longer distant concerns — but part of Europe’s political reality.
UK Motorists Take Carmakers to Court Over Widening Diesel Emissions Scandal

A landmark legal battle has begun in the UK as hundreds of thousands of motorists seek to prove that Volkswagen was not the only car manufacturer to manipulate emissions during testing. The collective lawsuit, one of the largest of its kind in British legal history, targets several global brands accused of using hidden software to make diesel vehicles appear cleaner than they were in real-world driving.

The case builds on the legacy of the 2015 Volkswagen scandal, which exposed the use of so-called “defeat devices” designed to lower nitrogen oxide emissions only during lab testing. While Volkswagen reached a major settlement with UK claimants in 2022, this latest action expands the allegations to include other well-known automakers such as Mercedes-Benz, Ford, Peugeot-Citroën, Renault, and Nissan. The proceedings will determine whether similar systems were used across the industry and, if proven, whether motorists are entitled to compensation.

For consumers, the case touches on both financial and ethical issues — from the potential loss in vehicle value to broader concerns about air pollution and public health. Environmental groups argue that excessive nitrogen oxide emissions from diesel engines have contributed to serious health risks across Europe, while automakers insist they followed the rules in place at the time and that their vehicles were fully approved by regulators.

Industry representatives maintain that the software under scrutiny was designed to protect engines under specific conditions, not to cheat emissions tests. They argue that the rules then in force allowed for certain temperature or load-based adjustments. However, claimants say this explanation does not excuse misleading consumers or undermining environmental standards.

The High Court’s decision is expected to set an important precedent for how emissions cases are handled in Europe. If the court rules in favour of the claimants, the outcome could open the door to billions of pounds in compensation and force manufacturers to confront questions about how they managed compliance with environmental regulations over the past decade. If the carmakers prevail, it would affirm their stance that they operated within a legal grey area created by inconsistent European testing standards.

The case also highlights wider tensions between environmental accountability and industrial power. While the U.S. swiftly imposed heavy fines and vehicle recalls following its own diesel investigations, European regulators have taken a slower, more fragmented approach. Critics say this has allowed carmakers to delay technical changes, while defenders argue that Europe’s approval system was complex and slow to adapt to new realities of emissions science.

Whatever the verdict, the trial marks a pivotal moment in the post–Dieselgate landscape. Nearly ten years after the scandal first erupted, the issue continues to test not only the integrity of global carmakers but also the credibility of regulators and the resilience of consumer protection laws.

CIJ EUROPE View:
The UK case underscores a long-running tension between technological innovation, environmental responsibility, and corporate accountability. It is not only a test of who bears blame for the diesel crisis but also a measure of how far Europe has come in aligning its legal systems with its environmental promises.

Cash Still Rules: Why America’s Payment Revolution Has Stalled

In a country known for innovation and global financial power, it remains surprisingly common for customers to be told they can’t pay by card. Across the United States, small pastry shops, family-run cafés, and local diners continue to rely on cash. The persistence of paper money in one of the world’s most advanced economies reflects deep-seated resistance to change in the American banking system.

The U.S. operates through a network of thousands of regional banks and credit unions, each with its own systems and fees. This decentralised model, while historically tied to local economic independence, has become a major obstacle to modernisation. The Federal Reserve’s FedNow service — created to enable instant money transfers — has seen limited uptake, with only a fraction of banks connected so far. Smaller institutions cite the cost and complexity of upgrading systems as barriers, leaving most payments to move slowly through outdated networks.

For small businesses, card payments have become a costly necessity. Transaction fees charged by card companies have reached record levels, eating into already thin margins. Many business owners say that for low-value purchases — a cup of coffee or a pastry — accepting cards simply doesn’t make sense. In contrast, other parts of the world have reduced transaction costs to almost zero. In Brazil, for example, digital transfers through the national Pix network are nearly instantaneous and inexpensive.

Industry groups representing card providers and payment processors have pushed hard against reforms that could reduce their profits. Proposals to cap transaction fees or require banks to connect to unified systems have faced years of lobbying and delay. Critics argue that this influence has left the United States dependent on an inefficient patchwork of private payment networks that benefit a few large players while holding back innovation.

Meanwhile, other regions are racing ahead. In Europe, instant payments are now a standard feature across much of the continent, supported by regulation that ensures interoperability between banks. In India, a government-backed digital payment platform processes billions of transactions every month, and in China, mobile wallets dominate daily life. Even smaller economies such as Thailand and Kenya have leapfrogged ahead of the U.S. in digital payment adoption.

For American consumers, the result is a slower, more expensive, and often more frustrating experience. Sending money between banks can take several days, and transferring funds abroad can involve multiple intermediaries and high fees. Even popular mobile apps like Venmo or Zelle ultimately depend on the same traditional clearing systems that prevent instant access to cash.

Efforts to reform the system are underway but face an uphill battle. The Federal Reserve hopes to expand its real-time payments network in the next year, and a handful of major banks are experimenting with digital settlement systems that use blockchain technology. Yet without a unified national approach or regulatory push, the transformation of U.S. payments may remain more aspiration than reality.

CIJ EUROPE View: The slow progress of payment reform in the United States shows how innovation can be stifled by fragmentation and entrenched financial interests. While countries across Europe and Asia have embraced digital payments as a public good, the U.S. remains caught between outdated infrastructure and political inertia. Until the system aligns around shared standards, small pastry shops will continue to rely on cash — not because they want to, but because the future of digital payments in America is still stuck in the past.

Slovakia Introduces New Insolvency Register to Improve Transparency and Efficiency

From 1 October 2025, Slovakia has implemented the Register of Pre-insolvency, Liquidation and Insolvency Proceedings, replacing the country’s former Insolvency Register. The reform is a major step in the digital transformation of Slovakia’s business and legal environment, aiming to simplify insolvency procedures, strengthen transparency, and ensure faster access to reliable data for companies and creditors.

The new register, managed by the Ministry of Justice of the Slovak Republic, operates as a single electronic platform containing all relevant information on insolvency, pre-insolvency, and liquidation proceedings. The system consolidates cases that were previously spread across multiple databases and makes them accessible online in real time. To support international users, a limited English-language interface is also available.

The register includes data on bankruptcy and restructuring proceedings, including “small” bankruptcies designed for smaller businesses, as well as preventive and liquidation procedures. Each case entry contains essential details about debtors, creditors, insolvency administrators, courts, and procedural steps such as the registration of claims, the scheduling of creditors’ meetings, and the publication of asset lists. Key documents and court decisions are also available, creating a transparent record of each proceeding.

A notable change is that all published information is now considered public and can be used directly in commercial or legal relations, without the need for additional verification. In most cases, the new register replaces the former practice of publishing insolvency information in the Commercial Journal, reducing duplication and administrative costs.

Supporters of the reform highlight several expected benefits. The centralized and digitized system should make it easier for businesses, financial institutions, and legal professionals to monitor cases and verify the financial health of partners. By offering real-time access to verified data, it helps reduce the risk of fraud, accelerates decision-making, and increases predictability in insolvency processes. At the same time, the integration of asset sales and trustee services within the platform creates a more user-friendly experience for creditors and administrators.

While the launch has been welcomed by the business community, the system’s long-term success will depend on its implementation and maintenance. Ensuring regular updates, training court staff and administrators, and maintaining interoperability with EU systems will be essential for the register to deliver on its promise of speed and efficiency.

The Register of Pre-insolvency, Liquidation and Insolvency Proceedings is one of Slovakia’s most important legal digitalization initiatives in recent years. If successfully adopted, it could strengthen trust in the country’s legal and business environment, making it easier for companies to assess risk and participate in insolvency procedures with greater confidence. Over time, it may also enhance Slovakia’s standing within the EU as a country committed to transparent and predictable commercial practices.

G20 Progress Report: Cross-Border Payment Reform Faces Delays Despite Policy Milestones

The Financial Stability Board (FSB) has released its 2025 Consolidated Progress Report on the G20 Roadmap for Enhancing Cross-Border Payments, showing that although many regulatory and technical milestones have been achieved, practical improvements in cost, speed, transparency, and access remain limited.

The G20 initiative, first launched in 2020, set an ambitious goal to make international payments faster, cheaper, and more transparent by 2027. Five years later, the FSB’s assessment suggests that while the global policy framework is largely in place, real-world impact for consumers and businesses has been modest.

The report highlights notable advances, including efforts by the Financial Action Task Force (FATF) to harmonise anti–money laundering standards and the expansion of ISO 20022 messaging protocols across key payment systems. The Committee on Payments and Market Infrastructures (CPMI) also coordinated measures to extend RTGS system operating hours and reduce cross-border frictions between banks and non-bank payment providers.

However, the FSB notes that the average cost of sending remittances still exceeds the United Nations’ target of 3 percent per transaction. Retail remittance corridors in Africa and South Asia remain among the most expensive, while in many low-income countries access to fast and affordable digital payment options is still limited.

The report attributes the slow progress to inconsistent national regulations, fragmented capital control frameworks, and the limited reach of interoperable payment infrastructure. “Much of the design work is done — implementation now lags behind,” the FSB stated.

Regional Perspectives

In Europe, the push toward real-time payments and harmonisation of financial messaging standards has placed the region among the global leaders in payment system integration. The EU’s Instant Payments Regulation, coupled with the Single Euro Payments Area (SEPA), continues to expand coverage, although cross-border adoption beyond the eurozone remains uneven.

In Asia, rapid advances are being made through regional connectivity projects. Initiatives such as Project Nexus, led by the Bank for International Settlements (BIS) Innovation Hub, are linking national instant payment systems across ASEAN countries. Singapore, Thailand, and Malaysia are already operational under this model, with Japan and India expected to join by 2026.

In Africa, progress has been slower but promising. The Pan-African Payment and Settlement System (PAPSS) — launched under the African Continental Free Trade Area (AfCFTA) — is facilitating cross-border trade in local currencies, reducing reliance on the US dollar. However, inconsistent regulatory environments and weak infrastructure continue to hinder scale.

The Americas present a mixed picture. While the US and Canada have advanced digital clearing systems, cross-border transactions between North and South America remain costly. Latin American countries such as Brazil, through its PIX instant payment system, are now exploring bilateral connections with Mexico and the Caribbean.

Looking Ahead

The FSB points to emerging technologies such as Project Agorá, which explores tokenised central bank money for cross-border settlements, and the World Bank’s FASTT programme, which supports over 60 countries in modernising payment infrastructure. These could become pivotal to bridging current gaps if broadly adopted.

However, the report warns that achieving tangible results requires “national-level action and private sector engagement.” Greater alignment between financial institutions, regulators, and technology providers will be essential to delivering on the G20’s 2027 targets.

By prioritising collaboration and ensuring equitable access to technology, the FSB believes the roadmap could still succeed in transforming how money moves across borders — but only if the next two years deliver visible, measurable change.

EU Advances Financial Supervision Reform Through Data-Driven Regulation

The European Parliament has endorsed a new framework aimed at transforming how financial institutions across the European Union report and share data with regulators. The initiative marks a significant step in harmonising supervisory practices and advancing digitalisation within Europe’s financial sector.

Under the new regulation, data from banks, insurers, and investment firms will be centralised through a unified digital reporting system, reducing redundant submissions and ensuring faster, more accurate oversight. The reform’s purpose is to eliminate fragmentation between national regulators and the European supervisory authorities, while enhancing transparency, efficiency, and the capacity to identify systemic risks across borders.

A key feature of the initiative is the introduction of a “report once” mechanism — a model that allows institutions to submit regulatory data only once through a central platform, after which it becomes accessible to all relevant supervisory bodies. The system will also integrate digital identifiers and standardised formats, simplifying compliance and improving interoperability between national systems.

Initial reactions from the financial community have been cautiously positive. The European Banking Federation (EBF) welcomed the proposal as an essential step toward simplifying reporting obligations, noting that harmonised data flows could significantly reduce compliance costs. However, it warned that smaller institutions may face challenges adapting to the new IT requirements, calling for phased implementation and technical support.

The Association for Financial Markets in Europe (AFME) also praised the reform as “a pragmatic evolution” that brings EU supervision in line with global best practices. It highlighted the importance of consistent coordination between national regulators to prevent uneven application across Member States. Meanwhile, consumer advocacy groups have urged caution, emphasising the need for strict safeguards against data misuse and greater transparency over how anonymised financial information will be handled.

Analysts view the regulation as a milestone in Europe’s broader move toward regulatory technology (RegTech) integration. By digitising and connecting supervisory data across sectors, the EU is expected to gain stronger predictive capabilities for risk management, improved fraud detection, and faster reaction times to market shocks. If successfully implemented, experts estimate that the new system could generate measurable efficiency gains and greater investor confidence by 2030.

The reform also fits within the EU’s larger financial modernisation agenda, alongside the creation of the Anti-Money Laundering Authority (AMLA) and renewed efforts to complete the Capital Markets Union (CMU). By linking supervisory authorities across banking, insurance, and securities under one digital infrastructure, Brussels aims to strengthen Europe’s competitiveness and financial resilience.

Officials have framed the initiative not only as a technological upgrade but as a structural evolution — one that ensures Europe’s financial ecosystem can adapt to crises, technological disruptions, and global competition. As the system rolls out, the EU is positioning itself to set an international benchmark for transparent, data-driven financial governance by the end of the decade.

CIJ EUROPE View: Why This Matters for Investors and Real Estate Finance
For investors and the real estate finance sector, the EU’s new supervisory framework signals more than a technical upgrade — it represents a fundamental shift toward data integrity and regulatory predictability. By improving transparency and synchronising oversight, lenders and institutional investors gain earlier insight into financial system vulnerabilities, credit exposure, and market trends that influence property financing and asset valuation.

A more unified data infrastructure also benefits cross-border capital flows. Real estate investors operating in multiple EU markets — from fund managers to banks — can expect faster due diligence, simplified compliance, and stronger confidence in risk assessments. For developers and borrowers, the reform could translate into more consistent access to financing as banks benefit from lower compliance burdens and greater regulatory clarity.

While implementation challenges remain — particularly for smaller institutions and local regulators — the long-term vision is clear: a single digital ecosystem where transparency drives trust and capital moves more efficiently. As Europe continues to digitalise its financial architecture, these reforms could form the backbone of a more resilient, integrated, and globally competitive investment environment.

CIJ EUROPE will continue to monitor how the new system shapes lending, investment, and capital market trends across the EU — including its downstream effects on real estate development and financing.

Global Insurance Faces a Redefined Future as Market Pressures and Innovation Collide

The insurance sector is entering a period of accelerated change. Deloitte’s latest 2026 Insurance Industry Outlook suggests that the next 18 months will test the industry’s capacity to adapt to new risks, shifting consumer expectations and regulatory pressure, as well as the technological transformation reshaping financial services worldwide.

Across the property and casualty market, profitability remains under strain. Rising claims costs, extreme weather events and higher reinsurance premiums are squeezing margins, even as premiums continue to rise. The strong underwriting results recorded in 2024 are unlikely to repeat, with analysts expecting a modest softening of combined ratios through 2025 and 2026.

Life and annuity businesses face a different challenge. Growth in mature markets has slowed amid consumer caution and complex regulation, while emerging economies still offer expansion opportunities as rising middle-income populations seek protection and savings products. Indexed and flexible annuities continue to attract investors in search of stable long-term returns.

The sector’s transformation is being driven by technology, but Deloitte stresses that real progress depends on how insurers integrate digital tools rather than simply adopt them. Artificial intelligence, automation and data-driven models are now fundamental to pricing, risk selection and claims management. The winners will be those who align AI with human expertise to create faster, more transparent services for policyholders.

Climate risk and sustainability remain at the top of the agenda. Insurers are under pressure to reduce their exposure to climate-related losses and to reorient their investment portfolios toward low-carbon assets. Regulators across the EU, the UK and North America are tightening disclosure rules, making environmental and social governance (ESG) performance a strategic as well as a moral obligation.

At the same time, Deloitte points to a talent dilemma. Demand for skilled underwriters, actuaries and data scientists continues to outpace supply. Firms are experimenting with hybrid work models and new leadership structures to appeal to younger professionals who value purpose and flexibility as much as pay.

Consumer expectations are evolving too. Customers increasingly demand personalised products, clear pricing and digital convenience. The rise of embedded insurance—where coverage is integrated directly into travel, retail or mobility platforms—is redefining how policies are distributed. The traditional broker model is giving way to broader ecosystems linking insurers, service providers and tech firms.

Cybersecurity represents another critical frontier. Insurers not only face growing demand for cyber-risk coverage but must also strengthen their own defences as global digital infrastructure becomes more interdependent and vulnerable to systemic attacks.

Capital management is shifting as well. With interest rates stabilising, many insurers are redirecting funds into private credit, infrastructure and insurance-linked securities. Regulators are paying closer attention to liquidity and transparency as the industry seeks higher yields in alternative markets.

Deloitte’s analysis concludes that insurers cannot rely on incremental change. Success will depend on decisive investments in technology, people and purpose—backed by clear leadership willing to rethink long-established business models. Those able to combine digital precision with human trust, the report says, will shape the next era of insurance.

Cautious Optimism Returns to Global Real Estate

The global commercial property market is slowly finding its footing after several years of instability, according to Deloitte’s latest outlook for 2026. While investor sentiment is improving, the recovery remains uneven and closely tied to the cost of capital, regional economic health, and the industry’s ability to adapt to technology and sustainability demands. Deloitte’s research, based on a survey of hundreds of senior real estate executives worldwide, suggests that most expect modest revenue growth in the coming year but also higher operating costs. Confidence has strengthened from the low points of 2023–2024, yet the industry is still shaped by cautious optimism rather than exuberance.

Market stabilisation is most visible in North America and Western Europe, where investors are cautiously returning to high-quality assets with steady income streams. In contrast, parts of Central and Eastern Europe, along with Asia-Pacific, are seeing stronger rebounds driven by infrastructure spending and renewed cross-border capital flows. Across all regions, investment is becoming more selective, with performance increasingly dependent on asset quality and local demand fundamentals.

Financing remains one of the industry’s most complex challenges. Developers and owners are facing a wave of loan maturities originally priced under pre-inflation conditions. Many are being forced to refinance at significantly higher rates or turn to private credit and alternative lenders, which now represent a growing share of total market funding. This shift marks a broader transformation in how capital is sourced and deployed. Institutional investors continue to favour established, income-producing properties, while speculative and under-leased assets struggle to attract funding.

Technology-driven sectors are emerging as the most resilient areas of real estate. Data centres, logistics hubs, and digital infrastructure are expanding rapidly to meet the surging global demand for cloud storage, AI processing, and connectivity. Health-care-related properties and professionally managed rental housing are also gaining traction for their stable, long-term returns. The office sector remains divided. While some central business districts continue to experience sluggish leasing activity, high-specification and well-located buildings—especially those integrated with mixed-use amenities—are regaining appeal as employers refine hybrid-work strategies.

The report underscores that technology adoption is no longer optional. Companies are investing heavily in AI-driven analytics, digital leasing platforms, and predictive maintenance systems to improve operational efficiency. Deloitte notes that artificial intelligence is already reshaping valuation models, tenant engagement, and portfolio risk management. Operational priorities are also shifting inward. Cost discipline, workforce retention, and tenant experience are now seen as strategic pillars of value creation. At the same time, sustainability continues to move up the agenda, with developers investing in energy-efficient retrofits, low-carbon materials, and certifications that enhance long-term asset performance.

Deloitte concludes that 2026 will reward companies able to balance prudence with reinvention. Real estate leaders who diversify funding sources, embrace data-driven decision-making, and treat innovation as a core part of risk management will be best positioned to capture the next wave of growth. The sector has turned the corner from crisis to recalibration. Yet success will depend less on waiting for a global rebound and more on how effectively investors and operators adapt to a rapidly changing financial and technological environment.

Japan Faces Global Pressure as Matcha Craze Outpaces Supply

Japan’s signature green tea powder, matcha, has become a worldwide sensation — but the country that perfected it is now struggling to keep up. From the cafés of London and New York to wellness brands across Asia, demand for matcha-infused drinks, desserts, and cosmetics has exploded, pushing Japan’s small-scale producers into an unexpected supply crisis.

Over the past two years, exports of powdered green tea from Japan have surged to record levels, far outpacing the capacity of traditional tea-growing regions such as Uji, Nishio, and Kagoshima. Industry data shows shipments have nearly doubled since 2020, while domestic production of tencha — the shaded leaf used to make matcha — has not grown fast enough to match demand. The result has been soaring prices, long waiting lists, and increasing pressure on growers to expand output.

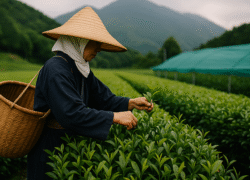
At the heart of the challenge lies Japan’s deep commitment to quality. Matcha production is labor-intensive and time-sensitive: tea bushes must be shaded for weeks before harvest to develop their distinctive flavour and colour, and the leaves are then carefully dried, ground, and stored under tightly controlled conditions. That process cannot be rushed. Many producers warn that scaling up too quickly risks undermining the very standards that made Japanese matcha globally desirable in the first place.

Climate change has compounded the problem. Severe heatwaves and unpredictable weather patterns have damaged tea bushes in key growing areas, cutting yields by as much as a quarter in some plantations. Farmers also face a generational challenge — the average age of tea growers is rising, and few young people are entering the industry. Even with modernisation subsidies and new processing technology, Japan’s tea regions are struggling to recruit and train successors fast enough to secure long-term stability.

Despite these constraints, Japan continues to dominate the global matcha market because of its reputation for purity and consistency. The country’s producers have little competition at the premium end, though rival growers in China, Vietnam, and even India are beginning to experiment with matcha cultivation. Japanese exporters insist the difference in flavour, colour, and ceremonial authenticity still gives them a strong edge.

Policymakers in Tokyo and local prefectures are encouraging selective expansion, including converting low-demand green tea fields into tencha production and supporting new mechanised methods that preserve quality. Yet many industry insiders admit that meaningful change will take years. New tea plants can take up to five years to mature before producing usable leaves, meaning that today’s shortages could persist well into the next decade.

For now, the scarcity is creating both frustration and opportunity. Established tea houses have been forced to ration supply and prioritise long-term partners, while export prices for premium grades continue to climb. At the same time, smaller artisanal producers are finding global buyers eager to pay top rates for guaranteed Japanese origin and craftsmanship.

The global matcha boom shows no sign of slowing — fuelled by social media, health trends, and the search for natural energy alternatives. The question is whether Japan can expand enough to meet the world’s growing appetite without diluting the soul of its centuries-old tradition.

As one Kyoto-based grower put it simply: “We can make more matcha, but it must still taste like Japan.”

Germany Signals Shift Toward EU-Wide Financial Oversight

Germany’s finance ministry has opened the door to a deeper level of European financial integration, marking what could be a turning point in the long-stalled effort to create a genuine capital markets union across the EU. Finance Minister Lars Klingbeil has indicated that Berlin is ready to consider transferring greater supervisory powers from national regulators to the European Securities and Markets Authority (ESMA) — a significant change in tone after years of resistance.

The move reflects growing recognition that fragmented regulation is holding back Europe’s financial competitiveness. Advocates argue that more consistent rules and oversight could help channel investment across borders, giving European companies broader access to funding and investors greater confidence in transparent markets. For Germany — whose economy remains heavily reliant on bank lending rather than equity or bond financing — this could represent both an opportunity and a challenge.

If Berlin follows through, it could revive long-running European efforts to unify capital markets and reduce the continent’s dependence on bank credit. Policymakers believe this would strengthen Europe’s ability to finance innovation, compete with U.S. markets, and support industrial transitions such as decarbonisation and digitalisation.

Yet the proposal also raises complex questions about sovereignty and regulation. Critics warn that centralising power in Brussels may dilute national flexibility and create a “one-rule-fits-all” regime that overlooks the specific structures of local markets. Smaller member states worry that such a shift could erode their competitive niches as financial hubs, while some German voices fear losing democratic control over market supervision.

Beyond the politics, there are practical challenges. Transferring authority from dozens of national regulators to a single European body would require legal changes, new data systems, and clear lines of accountability. Market participants also warn that poorly managed centralisation could slow decision-making or discourage innovation, particularly in fast-moving sectors such as fintech and digital assets.

Still, many analysts see Germany’s change in stance as a necessary step. Without Berlin’s support, progress toward a single European capital market has repeatedly stalled. Now, with the Franco-German axis once again aligned, officials in Brussels believe a breakthrough may finally be within reach.

If implemented carefully, stronger European supervision could make it easier for investors to move capital freely across borders, simplify compliance for international firms, and provide a foundation for a more resilient and competitive financial ecosystem. But success will depend on balance — ensuring that integration strengthens Europe’s collective position without erasing the diversity and adaptability of its individual markets.

For now, Germany’s shift marks more than a policy adjustment. It signals a recognition that the future of European finance will depend less on national boundaries and more on shared trust, unified standards, and a willingness to think — and regulate — at a continental scale.

front page info
LATEST NEWS