Deka Immobilien Acquires Prime Office Building in London’s St James’s

Deka Immobilien has acquired the Stirling Square office building in London’s West End on behalf of the WestInvest InterSelect open-ended real estate fund.

The property was purchased from a fund managed by Tristan Capital Partners and Greycoat. The parties have not disclosed the transaction value.

Located in the St James’s district overlooking Buckingham Palace, the seven-storey office building provides approximately 8,700 sqm of lettable space. Designed by architect Sir James Stirling, the building occupies a rare island site and includes rooftop terraces with views across Buckingham Palace and the surrounding parks.

Originally completed in 1999, the property was refurbished in 2016 and again in 2022. It is fully leased on long-term agreements to four tenants.

St James’s is one of London’s established office and mixed-use districts, combining office buildings with luxury retail, hospitality and cultural institutions. The property is within walking distance of Piccadilly Circus Underground station.

According to Deka Immobilien, the acquisition supports the WestInvest InterSelect fund’s strategy of reinvesting capital generated through investor inflows and asset sales into core properties in established international markets. The company also cited the building’s fully leased status and potential for future rental growth as key factors behind the investment decision.

Škoda Group Wins Uppsala Tram Contract Worth up to €270 Million

Škoda Group has been selected to supply a new fleet of trams for the Swedish city of Uppsala under a contract that could be worth up to €270 million (approximately CZK 6.5 billion), including options and long-term service.

The agreement covers the delivery of 20 bi-directional trams, with an option for a further 18 vehicles. It also includes maintenance, overhauls, technical support and spare parts throughout the vehicles’ operational life.

The new fleet will operate on Uppsala’s planned 17-kilometre tram network, which will comprise 22 stops linking key residential areas, transport hubs, the university and hospital campuses.

The vehicles will be based on the tram platform already operating in Tampere, Finland, allowing Škoda Group to adapt an established design to Uppsala’s requirements while reducing technical risks.

Each tram will be 38 metres long, fully low-floor and capable of carrying up to 186 passengers, including 80 seated. The vehicles will feature three double doors and two single doors on each side to improve passenger boarding and alighting.

The trams will also incorporate several digital safety technologies developed by Škoda Group, including an anti-collision system designed to detect vehicles, pedestrians and obstacles. Additional safety features include an automatic speed control system that adjusts vehicle speed on curves and other designated sections of the network.

The contract includes a 12-year maintenance and overhaul agreement, with an option to extend the service period by a further year. The programme covers both the vehicles and major components, together with technical support and warranty services.

According to Škoda Group, the driver cabs will be developed in cooperation with tram drivers to meet current European standards for ergonomics, visibility and operational safety.

The award further strengthens Škoda Group’s presence in the Nordic market. The company already supplies trams for Helsinki and Tampere in Finland, is modernising Gothenburg’s M31 tram fleet in Sweden, and has previously secured a contract to deliver up to 31 vehicles for Stockholm’s Saltsjöbanan light rail line.

Skanska Wins €29 Million Contract to Build Garmin Facility in Finland

Skanska has signed a contract with Garmin Jyväskylä Oy to construct a new business facility in Jyväskylä, Finland, under a contract valued at €29 million (approximately SEK 310 million).

The project will be included in Skanska’s Nordic order intake for the second quarter of 2026.

The development will comprise an 8,500 sqm business facility designed to achieve the highest energy efficiency classification.

The building will incorporate timber in its façade and selected structural elements, while rooftop solar panels will generate part of the electricity required for the property’s operation.

Construction is scheduled to begin immediately, with completion expected in March 2028.

Retailers Expand Store Networks Across NEINVER’s FACTORY Outlet Centres

NEINVER has reported continued leasing activity across its FACTORY outlet centres in Poland, with a number of retailers expanding existing stores and opening new locations during the first half of 2026.

According to the company, the latest transactions reflect retailers’ efforts to grow their presence in the outlet segment while responding to changing consumer demand.

At FACTORY Poznań, jewellery retailer Apart and fashion accessories brand Guess Accessories have expanded and refurbished their stores. The centre has also welcomed a new Villeroy & Boch outlet, strengthening its homeware offering.

FACTORY Kraków has added a new Venezia store specialising in footwear and accessories, while at FACTORY Gliwice both Puma and menswear retailer Lancerto have increased their retail space.

In Warsaw, Lancerto and Lee Wrangler have expanded their stores at FACTORY Annopol. During the second half of the year, OCHNIK plans to triple its retail space at the centre with a new store concept, while outdoor retailer Mountain Warehouse will also enlarge its premises.

At FACTORY Ursus, BOSS has opened a larger store, and the centre’s food and beverage offering will be expanded this summer with the addition of a Kuchnie Marche restaurant.

Andrea Aburra, Head of Leasing for Poland and Italy at NEINVER, said the recent transactions demonstrate that both existing and new tenants continue to view the FACTORY outlet centres as an effective platform for expanding sales, increasing brand visibility and reaching value-conscious consumers.

According to NEINVER, the leasing activity forms part of its ongoing strategy to strengthen the tenant mix across the FACTORY portfolio and adapt its retail offering to changing shopping trends and retailer expansion plans.

CTP Opens 11,500 sqm Distribution Centre for Saint-Gobain in Česká Lípa

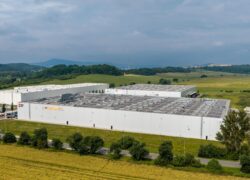
CTP has expanded CTPark Česká Lípa in the Czech Republic with a new 11,500 sqm distribution centre for Sekurit Service, part of the Saint-Gobain Group, strengthening the company’s automotive glass replacement supply chain across Europe.

The new facility will serve as a strategic European logistics hub for replacement automotive glass. Products from Saint-Gobain’s manufacturing plants will be consolidated into full truckloads before being distributed to regional warehouses across Europe and subsequently delivered to customers in the automotive aftermarket.

According to Sekurit Service, the new centre will help reduce delivery times, improve inventory management and increase supply chain efficiency between production facilities and local distribution centres.

Petr Lhoták, General Manager of Sekurit Service, said the company required additional capacity to consolidate shipments from its production plants, primarily located in Eastern Europe, before distributing products efficiently across European markets.

The company selected Česká Lípa because of its location within one of the Czech Republic’s established automotive manufacturing regions. The site provides access to major transport corridors linking Germany and Poland and is within easy reach of Dresden, Wrocław, Liberec and Mladá Boleslav, home to Škoda Auto.

CTPark Česká Lípa currently comprises more than 38,000 sqm of industrial and logistics space and offers additional land for future expansion.

Michal Příb, Senior Business Developer at CTP, said the location has become an important logistics hub for automotive companies serving multiple European markets, benefiting from its transport connections and proximity to manufacturing operations.

Under the Sekurit brand, Saint-Gobain manufactures laminated automotive safety glass for vehicle manufacturers across Europe, including one of its largest production plants in Hořovice, Czech Republic. Sekurit Service distributes replacement automotive glazing products, including heated and anti-reflective windshields, head-up display glass, heat-reflective glazing, acoustic glass and panoramic roof systems.

The new distribution centre is intended to improve delivery speed and strengthen supply reliability for customers across the European replacement parts market.

Skanska Sells Residential Development in Sollentuna for SEK 570 Million

Skanska has agreed to sell its self-developed Traktören 20 residential project in central Sollentuna, Sweden, to the Folksam Group through KPA Pension for approximately SEK 570 million.

The transaction will be recognised by Skanska Commercial Property Development in the second quarter of 2026. Ownership of the completed development is scheduled to transfer during the first quarter of 2029.

The agreement also includes a construction contract worth approximately SEK 320 million, which will be recorded in Skanska Sweden’s order intake for the second quarter of 2026.

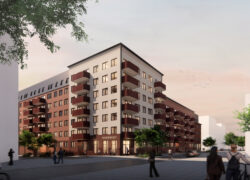
Located in the Tureberg district of Sollentuna, the project will comprise 154 rental apartments with a total lettable area of approximately 8,700 sqm.

The residential development will consist of buildings ranging from five to seven storeys above an underground parking garage. The project has been designed with a focus on efficient apartment layouts and residential quality.

The buildings are targeting Energy Class B and Miljöbyggnad Silver certification. Sustainability measures will focus on reducing environmental impact throughout the building lifecycle, from construction through to long-term operation and management.

Preparatory works have already begun, with full construction scheduled to start during the third quarter of 2026. Completion is expected in the first quarter of 2029.

Germany’s Fuel Tax Relief Ends as Debate Shifts to Long-Term Energy Policy

Germany’s temporary reduction in fuel taxes has come to an end, bringing to a close a two-month measure introduced to cushion motorists from higher energy costs. While the policy helped reduce prices at the pump, economists say its overall impact was limited and raises broader questions about how governments should respond to future energy price shocks.

The tax cut, introduced in May, reduced fuel taxes by approximately €0.17 per litre and represented around €1.6 billion in public support. The government also strengthened oversight of the fuel market, seeking to ensure that lower taxes translated into lower prices for consumers.

According to economic assessments, most of the tax reduction was reflected in retail fuel prices during the programme, although not all of the savings reached motorists. Analysts noted that changes in wholesale fuel prices and market dynamics meant part of the financial benefit remained elsewhere within the supply chain.

As the measure expired on 1 July, fuel prices rose again as normal tax rates were restored. Market observers said the increase reflected both the end of the temporary relief and ongoing developments in international energy markets.

The experience has prompted renewed discussion over the effectiveness of broad fuel tax reductions. Many economists argue that while such measures provide immediate relief, they also require significant public spending and tend to benefit households that consume the most fuel, rather than targeting those most affected by higher living costs.

Researchers also note that temporary tax cuts do little to address structural issues affecting fuel pricing, including competition and pricing mechanisms further up the supply chain. As a result, several experts have suggested that future support should focus more on targeted assistance for vulnerable households while continuing efforts to improve market transparency and competition.

The debate comes as governments across Europe continue to balance inflation, energy affordability and public finances. The German experience is likely to contribute to wider discussions about whether temporary tax reductions remain an effective policy tool during periods of elevated energy prices or whether more targeted forms of support offer better long-term value.

Slovakia’s Economic Sentiment Weakens in June as Business Confidence Declines

Economic sentiment in Slovakia weakened in June after improving during the previous two months, as confidence declined across several business sectors despite a modest improvement in consumer sentiment, according to the Statistical Office of the Slovak Republic.

The Economic Sentiment Indicator (ESI) fell by 2.3 points month-on-month to 97.8. Although sentiment weakened compared with May, it remained 1.8 points above its level a year earlier. The index also remained 7.9 points below its long-term average.

The decline was driven primarily by weaker confidence among businesses in industry, construction and retail, while service sector companies and consumers reported a more positive outlook.

Industrial confidence recorded the sharpest deterioration, falling by 7.3 points to -6.7. Manufacturers reported lower production expectations for the next three months, rising inventories of finished goods and weaker order books. The largest declines were recorded among producers of wood and paper products, transport equipment, and computer and electronic products.

Confidence in the services sector improved by 2.7 points to 9.7. Businesses reported stronger current and expected demand, particularly in administrative and support services, although assessments of recent business conditions weakened compared with the previous survey.

Consumer confidence also improved modestly. The consumer confidence indicator increased by one point to -27.3, although it remained well below its historical average. Households expressed greater optimism about their future financial situation, the broader economy, unemployment and their ability to save.

Retail confidence declined by 3.3 points to -1.3. Businesses reported weaker trading activity over the previous three months and higher inventory levels, particularly among motor vehicle retailers, electronics retailers and fuel stations. Expectations for future business activity remained positive.

Confidence in the construction sector fell by 3.0 points to -4.5. Construction companies reported weaker order books and less favourable expectations for future employment, with the largest deterioration recorded among civil engineering contractors.

Overall, the June survey indicates that while Slovak consumers have become slightly more optimistic, businesses remain cautious as weaker industrial activity and softer order volumes continue to weigh on economic confidence.

CIJ EUROPE Executive Roundtable: Real Estate Leaders Debate the Future of Offices, Residential Value and Market Resilience

As global economic uncertainty, technological disruption and changing occupier behaviour reshape the real estate landscape, senior executives from Romania’s leading developers, consultants and industry professionals shared their perspectives with CIJ EUROPE on the defining challenges facing both the office and residential sectors.

Their responses reveal an industry that is moving beyond simple market cycles toward a far more selective environment, where quality, adaptability and long-term value increasingly determine success.

The Office Market: A Story of Selection, Not Decline

One of the central questions discussed by CIJ EUROPE was whether the industry is honestly underwriting future office demand, particularly as artificial intelligence, hybrid working and workforce optimisation continue to reshape occupier behaviour.

Adinel Tudor, CEO, EVO Properties

Adinel Tudor believes the market should stop treating office demand as a single indicator.

According to Tudor, those still forecasting office absorption using pre-2020 assumptions are ignoring structural changes that have permanently altered workplace requirements. Employee density has increased, hybrid work has become part of normal business operations and artificial intelligence is expected to reduce some traditional office employment over the coming years.

However, he argues that Bucharest demonstrates why simplistic vacancy statistics can be misleading. While the city reports approximately 12 percent overall vacancy, prime CBD assets operate with vacancy levels close to 3 percent, whereas weaker buildings can exceed 30 percent.

“The demand isn’t disappearing,” Tudor explains. “It’s sorting.”

Rather than fearing declining demand, developers should focus on whether their specific buildings remain competitive.

This philosophy has driven EVO Properties’ strategy of investing heavily in repositioning its London & Oslo Office Buildings into highly flexible, multifunctional workplaces featuring renewable energy systems, integrated fitness facilities and mobility-on-demand services rather than relying on traditional leasing assumptions.

Tudor also believes AI creates both opportunities and risks. While automation may reduce some back-office functions, it simultaneously increases the value of collaboration, company culture and human interaction—qualities that continue to favour well-designed offices.

His conclusion is straightforward: the question is no longer whether the office market survives, but which individual buildings will remain relevant.

Office Rents: Looking Beyond Headline Figures

CIJ EUROPE also asked whether office rents are genuinely increasing or whether landlords are quietly supporting occupancy through generous incentives.

Tudor argues that headline rents often conceal the true economics of leasing.

“The headline rent is what you tell the market; the effective rent is what you tell your banker,” he says.

He believes premium buildings in successful sub-markets increasingly require fewer incentives due to limited new supply, while struggling secondary assets continue offering significant concessions simply to maintain occupancy.

In his view, there are effectively two separate office markets operating simultaneously.

Valentin Neagu, Managing Director, Crosspoint Real Estate

Valentin Neagu believes the market risks underestimating the cumulative effect of several structural pressures rather than focusing on any single challenge.

Although financing remains selective and construction costs unpredictable, he believes the larger issue concerns whether today’s developments will remain relevant to tomorrow’s occupiers.

Prime offices continue attracting demand, but occupiers have become considerably more disciplined, evaluating utilisation rates, flexibility, ESG performance and collaboration space instead of simply calculating desks per employee.

Neagu believes developers can no longer rely on assumptions that prevailed before the pandemic.

“The greatest risk lies with secondary stock,” he explains, suggesting that expecting weaker buildings to return to historical occupancy levels may prove unrealistic.

When asked what currently delays office development most, Neagu identifies uncertainty surrounding long-term occupier demand as the critical issue because it directly influences financing, pricing and future investment liquidity.

Residential Real Estate: Marketing Versus Lasting Value

The premium residential sector increasingly promotes wellness, community and lifestyle, but CIJ EUROPE asked whether these concepts genuinely create long-term value or simply represent more sophisticated marketing.

Răzvan Brașla, CEO, Cloud9

Răzvan Brașla believes buyers have become far more sophisticated and increasingly distinguish between branding and genuine functionality.

While amenities such as gyms, cafés and landscaped spaces receive considerable marketing attention, he argues they only become meaningful when integrated into a broader ecosystem that genuinely improves daily life.

For Cloud9 Evolution, this means combining housing with education, retail, services and accessible public spaces that reduce commuting and simplify residents’ routines.

Brașla says buyers increasingly evaluate projects based on how well they will function five or ten years after delivery rather than how impressive they appear during launch.

He believes Romania’s premium market is maturing, shifting away from luxury defined primarily by finishes and prestigious addresses toward integrated communities supported by strong operational quality and trusted developers.

Ultimately, marketing may generate initial interest, but resident satisfaction determines whether projects retain value over time.

Vlad Musteata, CEO, North Bucharest Investments

Vlad Musteata shares a similar perspective, arguing that marketing can only highlight value—it cannot create it.

For him, long-term value remains anchored in location, infrastructure, construction quality and a project’s ability to remain desirable over the next decade or more.

Concepts such as wellness and community have become standard buyer expectations rather than competitive differentiators.

They only become meaningful when embedded into urban planning through green spaces, mixed-use facilities and services that residents genuinely use.

Musteata believes the ultimate test comes after completion.

“If residents stay, demand remains strong and the asset continues appreciating, then it is value—not marketing.”

He adds that the market ultimately corrects itself, rewarding projects built on substance while exposing developments that rely primarily on promotional messaging.

Andreea-Maria Dumitru, Chief Marketing Officer, Hagag

For Andreea-Maria Dumitru, the distinction between marketing and genuine value becomes obvious only after residents move into a project.

Marketing can successfully communicate a vision, she says, but only everyday living validates that promise.

She believes premium buyers increasingly prioritise invisible qualities over visible luxury. Operational excellence, efficient layouts, energy performance, professional property management and seamless technology now matter more than superficial displays of luxury.

Wellness features, community spaces and landscaping only create lasting value when they genuinely improve comfort, privacy and quality of life over many years.

According to Dumitru, emotional branding remains important in luxury residential development, but long-term credibility depends entirely on execution.

Housing Demand: Structural Support Despite Short-Term Headwinds

CIJ EUROPE also explored whether recent market uncertainty signals a lasting slowdown in Romania’s residential sector.

Bogdan Letcă, CEO, Bog’Art Residential

Bogdan Letcă cautions against drawing long-term conclusions based solely on recent market conditions.

Although inflation, higher financing costs, VAT increases and political uncertainty have temporarily weakened buyer confidence, he believes these challenges should be viewed within the context of a decade of steadily improving housing affordability.

He also points to significant growth in household savings through bank deposits and government bonds, indicating that many potential buyers remain financially capable despite delaying purchasing decisions.

Meanwhile, the continued slowdown in planning approvals and building permits—particularly across Bucharest and Ilfov—is likely to reduce future housing supply.

Combined with consistent life-stage demand driven by marriage, family formation and changing lifestyles, Letcă expects the market to remain fundamentally supported.

He also observes increasing residential migration toward Bucharest’s outer districts, where affordability remains stronger.

Given Bucharest’s economic performance and leading GDP per capita among European capitals, he views the current market as experiencing a temporary adjustment rather than entering structural decline.

Simona Guțiu, Equity Notarial Office

Simona Guțiu also believes Romanian homeownership demand remains fundamentally resilient despite slowing market momentum.

While the pace of new ownership may moderate, she argues that Romanians continue viewing property ownership as one of the safest forms of financial security.

Historical experience, combined with current political, financial and geopolitical uncertainty, reinforces the desire for permanent homeownership.

She also notes that Bucharest remains relatively affordable compared with many other European capitals.

Looking ahead, Guțiu highlights proposed legislation introducing an 11 percent reduced VAT rate for eligible first-time buyers under the age of 35 purchasing qualifying new homes, subject to value limits, ownership conditions and minimum holding periods.

If implemented, such measures could further support entry-level residential demand.

A More Selective Market Emerges

Across both office and residential sectors, one theme consistently emerged throughout the CIJ EUROPE discussion: real estate is becoming significantly more selective.

Whether discussing office leasing, residential communities or investment strategy, the panel agreed that success increasingly depends on long-term quality rather than short-term market momentum.

For offices, the future belongs to adaptable, high-performing buildings capable of supporting collaboration, sustainability and changing workplace patterns.

For residential development, lasting value will increasingly be measured not by marketing campaigns or amenity lists, but by the quality of everyday living, operational excellence and sustained demand years after completion.

In both sectors, the market appears to be moving away from broad assumptions toward far greater differentiation, rewarding projects that genuinely deliver long-term value while exposing those unable to evolve with changing occupier and buyer expectations.

© CIJ EUROPE

German Economic Outlook Improves Slightly, Recovery Remains Fragile

Germany’s economic outlook improved modestly in June, although a broad-based recovery has yet to emerge, according to the latest business cycle indicator from the German Institute for Economic Research (DIW Berlin).

The DIW Economic Barometer rose to 96.1 points in June from 94.8 points in May, moving closer to the neutral 100-point level that signals average economic growth.

DIW attributed the improvement partly to the easing of tensions between the United States and Iran, which has reduced immediate geopolitical risks. However, the institute cautioned that uncertainty remains elevated and continues to weigh on economic activity alongside persistent inflation, higher energy costs and disruptions to parts of global supply chains.

The institute also noted that fiscal stimulus introduced by the German government contributed to solid GDP growth during the first quarter of the year, helping to stabilise the economy despite a challenging external environment.

Geraldine Dany-Knedlik, Head of Forecasting at DIW Berlin, said the economy appears to be stabilising but has not yet entered a sustained recovery. She added that stronger momentum is expected only towards the end of the year, provided geopolitical tensions do not intensify again and government stimulus translates into higher investment.

Germany’s manufacturing sector continues to face the greatest challenges. Industrial production remains subdued, while new manufacturing orders fell by 3.8% month-on-month, primarily due to weaker foreign demand. At the same time, the manufacturing Purchasing Managers’ Index remains close to the threshold separating expansion from contraction.

DIW said exports continue to be affected by modest global economic growth, increasing protectionist policies and stronger international competition, particularly from China. Although public investment, including defence spending, may provide some support in the coming months, the institute does not expect a strong industrial recovery in the near term.

The services sector also remains subdued. Retail sales have been weak since the beginning of the year as consumer confidence continues to be constrained by higher fuel prices, a subdued labour market and broader economic uncertainty. While consumer sentiment has shown some signs of improvement, service-sector business surveys remain mixed.

Guido Baldi, economic expert at DIW Berlin, said Germany’s recovery will increasingly depend on domestic investment and structural reforms as geopolitical tensions and protectionist trade policies continue to limit external demand.

front page info
LATEST NEWS