Art-Invest Real Estate secures Hensoldt as anchor tenant for Munich-area Xperience Quartier

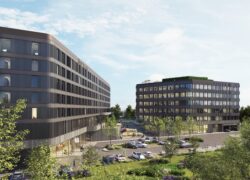
Art-Invest Real Estate has signed a long-term lease agreement with Hensoldt for approximately 12,300 sqm of office space at the Xperience Quartier development in Taufkirchen near Munich.

Construction of the mixed-use project, located on Ludwig-Bölkow-Allee, began in August 2025 with Köster acting as general contractor. The office component is scheduled for completion in the third quarter of 2027, while the hotel section is expected to be delivered in the first quarter of 2028.

Designed by HENN, the Xperience Quartier is being developed opposite the Technical University of Munich’s Space Valley aerospace campus. The site is also close to the headquarters of Airbus and the Jochen Schweizer Arena leisure and events venue.

The development will comprise two 27-metre-high buildings connected by a central plaza and supported by a parking garage. Once completed, the scheme will provide more than 22,000 sqm of office, hotel and conference space alongside 358 parking spaces.

Hensoldt, which specialises in sensor technologies for defence and security applications, will fully occupy one of the two buildings. The new premises will accommodate more than 400 employees and include a dedicated executive area. The company’s current headquarters in Taufkirchen is located around one kilometre from the new development.

Inka Tews, CHRO of Hensoldt, said the relocation would create modern working environments designed to support collaboration and innovation while reaffirming the company’s long-term commitment to Taufkirchen.

Tobias Wilhelm, Managing Director of Art-Invest Real Estate in Munich, said the agreement reflects continued demand for high-quality office environments from companies operating in the technology, defence and aerospace sectors. He added that the project responds to evolving workplace requirements through a hybrid and urban mixed-use concept.

BNP Paribas advised on the lease transaction, while GSK Stockmann acted as legal adviser to the landlord. Financing for the development is being provided by UniCredit through a green loan structure.
Union Investment Signs New Lease with Athena Club at 140 Broadway in New York City

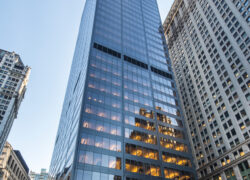
Union Investment has signed a new office leasing agreement at its 140 Broadway property in New York City, with US personal care company Athena Club taking approximately 1,100 sqm of office space for its expanded headquarters operations.

The eight-year lease will commence in June 2026, with Athena Club more than doubling the size of its existing headquarters footprint within the building. The property is held within Union Investment’s UniImmo: Europa open-ended real estate fund portfolio and has been part of the fund since 2004.

According to Union Investment, the transaction reflects continued demand for upgraded office environments in prime locations despite ongoing challenges in the wider office market.

Ulrich Dischler, Head of Asset Management Overseas at Union Investment, said the company has continued investing in the property to strengthen its appeal to occupiers. Recent improvements include the modernisation of the building’s lobby and the creation of a new communal area covering approximately 930 sqm, featuring food and beverage facilities alongside a conference space capable of accommodating more than 100 people.

Located in Manhattan’s financial district, 140 Broadway is among New York City’s most recognisable office towers. Completed in 1967, the approximately 200-metre-high building has undergone multiple renovations over the years. The property is situated close to Wall Street and the One World Trade Center in Downtown Manhattan.

India’s Growth Ambitions Face Increasing Pressure from Climate and Energy Transition Challenges

India’s economic expansion is entering a phase where growth and sustainability are becoming increasingly intertwined. As one of the fastest-growing major economies, the country is attempting to maintain momentum while responding to rising climate risks and accelerating its transition towards cleaner energy.

The balancing act is becoming more complex as climate-related disruptions intensify and energy demand continues to rise alongside industrialisation and urbanisation.

Growth Outlook Remains Resilient

India’s economy continues to demonstrate strong underlying momentum, supported by domestic consumption, infrastructure investment and a growing services sector. Estimates from the Reserve Bank of India and the International Monetary Fund generally place near-term GDP growth in the range of 6–7 percent, with India remaining one of the fastest-growing large economies globally.

While earlier projections above 7 percent have been cited, most current forecasts suggest a more moderate but still robust trajectory, reflecting global economic uncertainty and tightening financial conditions.

Foreign investment inflows and public capital expenditure continue to support growth, although external demand remains uneven.

Climate Risks Intensify

Climate-related challenges are becoming a more visible constraint on long-term growth. Rising temperatures, more frequent heatwaves and increasing instances of flooding are already affecting productivity, infrastructure and urban resilience.

Research cited by institutions such as the World Bank indicates that climate change could have a measurable impact on India’s economic output over time, particularly through reduced labour productivity and disruptions to agriculture and supply chains.

Sectors such as agriculture, coastal infrastructure and urban systems are particularly exposed, with climate risks expected to increase in both frequency and severity over the coming decades.

While specific loss estimates vary widely across studies, there is broad consensus that the economic cost of inaction could be substantial.

Energy Transition Gains Momentum

India has made measurable progress in expanding its renewable energy capacity, driven by policy support and falling technology costs. According to the International Energy Agency, the country is among the fastest-growing renewable energy markets globally.

Non-fossil fuel capacity has increased significantly in recent years, with solar energy leading new installations. Government initiatives such as rooftop solar programmes and green hydrogen development aim to accelerate the transition further.

India has committed to increasing the share of non-fossil fuel capacity to around 50 percent of total installed capacity by 2030. Current progress suggests movement in that direction, although achieving the target will require sustained investment and grid modernisation.

Structural Constraints Remain

Despite progress, India’s energy transition faces structural challenges. Coal continues to play a central role in power generation, reflecting the need to balance energy security with decarbonisation goals.

Financing requirements for the transition are substantial, particularly in areas such as grid infrastructure, storage and industrial decarbonisation. In addition, regulatory complexity and land acquisition issues continue to affect project timelines.

The pace of transition will therefore depend not only on capacity additions but also on improvements in system integration and policy execution.

A Long-Term Balancing Act

India’s development trajectory increasingly depends on its ability to align economic growth with climate resilience and energy transition goals. The direction of policy is clear, but the scale of the challenge remains significant.

While the country is making progress in expanding renewable energy and strengthening climate awareness, the transition will be gradual. Maintaining growth while reducing emissions and adapting to climate risks will require sustained investment, policy consistency and technological advancement over the coming decades.

Source: CIJ.World India Research & Analysis Team

Czech Tourism Posts Solid Growth in Q1 as Winter Season Drives Demand

Tourism activity in the Czech Republic recorded a strong start to 2026, with both domestic and international travel contributing to growth during the winter season, according to data released by the Czech Statistical Office.

In the first quarter of the year, a total of 4.4 million guests were accommodated in collective accommodation establishments, representing a year-on-year increase of 5.2 percent. The number of overnight stays rose by 5.6 percent to reach 11.1 million nights, indicating sustained demand across key tourism segments.

Balanced Growth Across Domestic and International Travel

Both domestic and foreign visitors contributed to the overall increase. Domestic guests accounted for 2.3 million arrivals, while 2.1 million visitors came from abroad. The number of overnight stays by residents rose by 4.1 percent, while non-residents recorded a stronger increase of 7.3 percent, reflecting a continued recovery in international travel.

“In the first quarter of 2026, the growth in arrivals was supported by both domestic and foreign guests,” said Roman Mikula, Head of the Tourism and Environmental Statistics Unit at the CZSO.

Hotels Lead Performance

Hotel-type accommodation continued to dominate the market, with 3.4 million guests staying in hotels during the quarter, up 5.6 percent year-on-year. Overnight stays in hotels increased by 6.3 percent, reaching nearly 8 million nights.

Four-star hotels remained the most popular category, attracting 1.7 million guests who accounted for approximately 4 million overnight stays. In contrast, boarding houses recorded a slight decline in guest numbers, although the total number of nights spent in this segment increased modestly.

Prague and Regional Destinations See Gains

Tourism growth was recorded across all regions. Prague remained the leading destination, with nearly 1.7 million guests and 3.8 million overnight stays.

Other regions also reported solid activity. The Královéhradecký Region attracted around 370,000 visitors, while the Jihomoravský Region, Karlovarský Region and Liberecký Region each recorded more than 250,000 guests.

Domestic tourism remained particularly strong in mountain regions such as Královéhradecký and Liberecký, reflecting the seasonal appeal of winter destinations. International visitors were most concentrated in Prague, followed by Karlovarský and Jihomoravský regions.

Germany Remains Key Source Market

Foreign arrivals reached 2.1 million in the first quarter, an increase of 5.8 percent year-on-year. Germany remained the largest source market, with 474,000 visitors, while Poland, Slovakia, the United Kingdom and Italy each contributed more than 100,000 arrivals.

Overall, the data points to a successful winter season for Czech tourism, with steady growth in both arrivals and overnight stays. The continued recovery of international travel, combined with stable domestic demand, suggests a positive outlook for the sector heading into the peak summer period.

Czech Retail Sales Continue Growth in March, Led by E-commerce and Food

Retail sales in the Czech Republic maintained steady growth in March 2026, supported primarily by strong online trade and food sales, according to the latest data from the Czech Statistical Office.

In real terms, retail sales increased by 4.9 percent year-on-year, while rising 1.2 percent compared to the previous month. Excluding motor vehicles, sales also recorded a 1.2 percent month-on-month increase, reflecting broad-based consumer activity across key segments.

E-commerce and Food Drive Growth

The strongest contribution to annual growth came from online retail and non-specialised food stores. Sales via mail order and internet channels rose by 13.4 percent year-on-year, continuing to outperform traditional retail formats.

Food-related sales also showed solid performance, increasing by 4.8 percent annually and 1.8 percent month-on-month. Non-food goods recorded a 5.5 percent annual rise, while automotive fuel sales grew by 2.6 percent.

“Retail sales adjusted for price effects continued to grow year-on-year in March,” said Jana Gotvaldová, Head of the Trade, Transport and Services Statistics Unit at the CZSO. “Higher sales were recorded across most store categories, with the exception of clothing, footwear and leather goods.”

Mixed Performance Across Segments

Within specialised retail, the strongest gains were recorded in cosmetics and personal care products, which rose by 7.5 percent year-on-year. Pharmaceutical and medical goods increased by 6.8 percent, while cultural and recreational goods posted a more modest 1.4 percent rise.

Sales of household equipment and electronics showed limited growth, rising by 1.0 percent and 0.3 percent respectively. In contrast, clothing, footwear and leather goods saw a slight decline of 0.5 percent compared to the same period last year.

Non-specialised stores, particularly those focused on food, beverages and tobacco, reported a 5.2 percent increase in sales, while other non-specialised retail categories rose by 6.6 percent.

Motor Vehicle Sales Stable

Sales in the automotive segment remained broadly stable on a monthly basis, with no significant change compared to February. On an annual basis, sales in the sector increased by 2.0 percent, driven primarily by a 2.2 percent rise in vehicle sales, while repair and maintenance services grew by 1.2 percent.

Outlook

The March data points to continued resilience in Czech retail, with consumer demand supported by online channels and essential goods. However, weaker performance in discretionary segments such as apparel suggests that spending patterns remain selective amid broader economic conditions.

India’s Startup Ecosystem Gains Scale, but Questions Remain Over Depth and Sustainability

India has consolidated its position as one of the world’s largest technology and startup ecosystems, supported by a combination of demographic scale, digital infrastructure and sustained policy backing. While the country is firmly established as the third-largest startup market globally, the next phase of growth is likely to depend less on expansion in numbers and more on depth, innovation and capital efficiency.

According to Startup India, more than 100,000 startups have been formally recognised under government frameworks, although the broader ecosystem is significantly larger when informal and early-stage ventures are included. The number of unicorns has surpassed 100, reflecting the rapid scaling of venture-backed companies across sectors such as fintech, e-commerce and enterprise technology.

India’s rise has been underpinned by structural drivers that distinguish it from many other emerging markets. A large, young population, increasing internet penetration and the rollout of digital public infrastructure have created favourable conditions for entrepreneurship. At the same time, expanding domestic consumption has enabled startups to scale within the local market before pursuing international growth.

Research output has also increased steadily. Data from UNESCO indicates that India ranks among the leading countries globally in terms of scientific publications. However, the translation of research into commercially viable innovation remains uneven, with gaps between academic output and industrial application.

Funding patterns highlight a shift in the ecosystem’s maturity. After peaking in 2021, venture capital inflows have moderated in line with global trends. Annual funding volumes have stabilised at lower levels, generally within the $10–15 billion range, as investors place greater emphasis on profitability and sustainable growth rather than rapid expansion.

Foreign capital continues to play a central role, with investors from key markets such as the United States and Singapore maintaining active exposure to Indian technology companies. At the same time, domestic capital pools are gradually expanding, although they remain relatively underdeveloped compared to more mature ecosystems.

Geographically, the ecosystem is becoming more diversified. A growing share of startups is emerging from Tier II and Tier III cities, reflecting improvements in digital connectivity and cost advantages outside traditional hubs such as Bengaluru and Delhi-NCR. This trend is contributing to a broader distribution of entrepreneurial activity across the country.

Government policy has acted as a catalyst, particularly through initiatives such as Startup India and targeted funding programmes. Public sector involvement has focused on improving access to early-stage capital and formalising parts of the ecosystem, while private investment continues to drive scale.

Despite this progress, structural challenges remain. Funding volatility, limited depth in deep technology sectors and the need for stronger integration between research and industry continue to constrain the ecosystem’s evolution. India’s ability to move beyond scale and establish itself as a leading centre for innovation will depend on addressing these gaps.

While the country’s startup ecosystem has reached a level of maturity that places it among the global leaders, its long-term influence will be determined by its capacity to convert growth into sustained innovation and globally competitive technology development.

Source: CIJ.World India Research & Analysis Team

AI Begins to Shape the Next Phase of Cyber Attacks, Researchers Warn

Cybersecurity researchers have identified a growing trend in which criminal groups are incorporating artificial intelligence tools into their attack strategies, marking a shift in how digital threats are developed and executed.

According to findings released by Google, investigators observed a coordinated attempt by a cybercrime group to identify and exploit a previously unknown weakness in widely used software. While the attempted breach was detected and contained before it could cause significant disruption, the methods used highlight how attackers are beginning to integrate advanced technologies into their operations.

The case stands out not because of the scale of the attack, but because of the tools involved. Researchers found indications that the group had used AI-based systems to assist in analysing software and identifying potential vulnerabilities more efficiently than traditional methods would allow. Although the attack itself still required human oversight, the use of such tools suggests a shift toward more automated processes within cybercrime.

Experts caution that this development does not yet represent fully autonomous cyber attacks. Instead, artificial intelligence is being deployed as a supporting instrument—enhancing speed, expanding the scope of analysis, and lowering the technical barrier for certain types of operations. In practical terms, this means attackers may be able to test more potential weaknesses in a shorter period of time, increasing the likelihood of finding exploitable gaps.

The use of AI in cyber activity has been gradually expanding across multiple areas, including the creation of malicious code, phishing campaigns and reconnaissance. What is evolving now is the depth of integration, with these systems increasingly embedded into the early stages of attack planning rather than being used solely for execution.

Security analysts note that while such capabilities are still developing, they are likely to become more sophisticated as AI tools improve. This raises concerns about the speed at which vulnerabilities could be discovered and exploited in the future, particularly if defensive measures do not evolve at the same pace.

At the same time, researchers emphasise that current threats remain largely dependent on human direction. Artificial intelligence may accelerate certain processes, but it has not replaced the need for strategic decision-making by attackers.

The incident underscores a broader shift within the cybersecurity landscape, where emerging technologies are beginning to reshape both offensive and defensive capabilities. As organisations continue to adopt digital systems at scale, the ability to respond quickly to increasingly complex and adaptive threats is expected to become a critical factor in maintaining security.

CNB Raises Czech Deficit Forecast to 2.7% as Fiscal Pressures Persist

The Czech National Bank has revised its estimate for the country’s general government deficit in 2026 to 2.7 percent of GDP, up from its previous forecast of 2.5 percent released earlier this year, reflecting a slower pace of fiscal consolidation.

According to the central bank’s latest macroeconomic outlook, the deficit is expected to widen further to 3.1 percent of GDP in 2027. The revision comes amid continued pressure on public finances, despite gradual improvements since the pandemic period.

The CNB estimates that the fiscal shortfall narrowed to roughly the mid-2 percent range of GDP in 2024, with a slight increase in 2025. However, structural imbalances remain a concern. The structural deficit, which adjusts for economic cycle effects, is projected to rise from around 2.1 percent of GDP last year to approximately 2.6 percent in 2026.

Public debt is also expected to continue its upward trajectory. The central bank forecasts that government debt will increase to 45.7 percent of GDP in 2026, up from 44.3 percent a year earlier, before reaching 47.2 percent in 2027. While still below the European Union average, the trend reflects sustained fiscal pressures in the medium term.

On the macroeconomic side, wage growth is expected to remain relatively strong, although moderating compared to previous years. Nominal wages are projected to increase by 6.4 percent in 2026, following growth of over 7 percent in 2025, with real wage growth supported by easing inflation.

Labour market conditions are forecast to soften slightly. The unemployment rate is expected to rise to 4.8 percent in 2026 before edging down marginally in 2027, indicating a gradual cooling from historically tight conditions.

The CNB also anticipates a deceleration in residential property price growth. After a strong rebound in 2025, price increases are projected to slow to 8.3 percent in 2026 and further to 5.6 percent the following year, suggesting a more balanced market environment.

Overall, the central bank’s latest projections point to a period of moderate economic adjustment, with fiscal consolidation progressing more slowly while key macroeconomic indicators gradually stabilise.

India’s Infrastructure Push Tests Its Promise to Reshape Competitiveness

India’s aggressive infrastructure spending is rapidly becoming the defining feature of its economic strategy, but whether it can deliver a lasting boost to competitiveness and logistics efficiency remains a question of execution rather than ambition.

Capex Surge Signals Structural Shift

Public investment has more than doubled in just four years, rising from under ₹6 lakh crore in FY2021–22 to over ₹11 lakh crore in FY2025–26, according to the Ministry of Finance India. This marks a clear pivot toward capital-led growth, with policymakers prioritising infrastructure over consumption-driven expansion.

The scale is significant by emerging market standards, although headline projections for long-term infrastructure pipelines often combine both public and private investment, making direct comparisons less straightforward.

Connectivity Gains Begin to Show

India’s transport backbone has expanded steadily over the past decade. National highways have grown materially, improving freight movement between industrial and consumption centres and reducing transit times.

The impact is increasingly visible. The World Bank ranked India 38th in its 2023 Logistics Performance Index, reflecting progress in infrastructure, customs and shipment reliability.

Ports and rail systems are also undergoing upgrades, while dedicated freight corridors and multimodal logistics hubs are expected to further streamline long-distance cargo movement.

Logistics Reform Still a Work in Progress

Despite improvements, India’s logistics system remains cost-heavy and fragmented. Historically estimated at 12–16 percent of GDP, logistics costs have been a long-standing constraint on competitiveness.

Government initiatives such as the National Logistics Policy and the PM Gati Shakti platform aim to address these inefficiencies through integrated planning and digital coordination. However, independent estimates suggest costs remain above 10 percent of GDP, indicating that meaningful efficiency gains are still evolving rather than fully realised.

Competitiveness Gains Depend on Execution

Improved infrastructure has the potential to reshape India’s economic geography by linking hinterland regions more effectively to ports and industrial corridors. This could lower costs, support manufacturing growth and enhance export competitiveness.

Yet structural challenges persist. Land acquisition, regulatory complexity and uneven execution across states continue to slow project delivery and dilute impact.

A Long-Term Play, Not an Immediate Leap

India’s infrastructure drive represents a genuine structural shift toward investment-led growth. The direction is clear, and early gains are visible, particularly in connectivity and logistics performance.

However, the transformation into a globally competitive logistics and manufacturing platform will be gradual. The real test lies not in the scale of announced spending, but in the consistency and efficiency of delivery over the next decade.

Source: CIJ.World India Research & Analysis Team

China Updates Rules on Punitive Damages in Intellectual Property Cases

China’s Supreme People’s Court has introduced revised judicial guidance on the application of punitive damages in intellectual property infringement disputes, signalling a continued effort to strengthen protection for rights holders and tighten enforcement against repeat or deliberate infringers.

The new judicial interpretation, issued on 20 April 2026 and effective from 1 May 2026, replaces the previous framework introduced in 2021. The updated rules are intended to clarify how courts should handle claims for punitive damages in civil intellectual property disputes and to provide more consistent standards for determining compensation.

According to figures released by the Supreme People’s Court, Chinese courts concluded 1,471 intellectual property cases involving punitive damages between 2021 and 2025. Punitive damages were ultimately awarded in 505 of those cases, with total compensation reaching approximately RMB 1.8 billion in 2025 alone. Authorities said the revised interpretation reflects the growing use of the mechanism and the need to address new forms of infringement.

One of the main procedural changes concerns the timing of punitive damages claims. Under the revised rules, rights holders are generally expected to raise such claims before the end of first-instance oral proceedings. Claims introduced for the first time during appeal proceedings may only proceed through mediation if both parties agree. If mediation fails, courts are instructed to reject the request, and the claimant will not be allowed to file a separate lawsuit based on the same infringement.

The interpretation also narrows the application of punitive damages in unfair competition cases. Courts clarified that punitive damages remain available primarily in trade secret infringement disputes and do not generally apply to other unfair competition matters such as misleading advertising, commercial defamation or acts causing market confusion unless separate legislation specifically provides for it.

The revised framework further expands the circumstances in which courts may determine that infringement was intentional. In addition to previously recognised scenarios such as continued infringement after warnings or cases involving counterfeiting, the interpretation now includes situations where parties resume infringing activity after reaching settlement agreements with rights holders. Courts may also consider attempts to avoid liability through affiliated companies, nominee structures or changes in legal representatives as evidence of intentional misconduct.

Chinese courts were also given more detailed guidance on assessing whether infringement reaches the threshold of “serious circumstances”, a key condition for punitive damages. The new rules specify that infringers who derive most of their income from unlawful activities or effectively operate infringement as their principal business activity should automatically meet the seriousness requirement.

The interpretation additionally refines how damages are calculated. Courts are instructed to base punitive damages on actual losses, illegal gains or profits generated through infringement. Statutory damages may no longer serve as the calculation basis for punitive awards, reflecting an effort to distinguish punitive compensation from standard judicial compensation mechanisms.

In cases where infringement forms part of a company’s primary business activity, courts may use gross profit rather than operating profit as the basis for calculation, potentially increasing the level of compensation awarded.

Another notable revision concerns the multiplier applied to punitive damages. Chinese courts are no longer restricted to whole-number multiples and may apply more flexible calculations depending on the severity of the conduct and the level of fault involved. However, the total award remains capped at five times the calculation base, excluding reasonable enforcement expenses such as legal and notarisation costs.

The Supreme People’s Court said the revised interpretation is intended to improve consistency in judicial practice while strengthening deterrence against deliberate intellectual property violations. Legal observers expect the changes to increase pressure on businesses operating in China to strengthen compliance procedures and manage intellectual property risks more carefully.

Source: CMS

front page info
LATEST NEWS