ARETE Industrial Sees Long-Term Opportunity in CEE Logistics Despite Market Repricing

The logistics real estate sector across Central and Eastern Europe continues to face questions around pricing, liquidity and tenant risk as investors navigate a higher interest-rate environment and slower transaction activity. According to Miroslav Barnáš, however, the region’s underlying fundamentals remain stronger than current market pricing may suggest.

In an interview with CIJ EUROPE, Miroslav Barnáš, Chief Investment Officer of ARETE Industrial, said one of the key questions for investors today is whether the widening yield spread between CEE logistics assets and Western European markets accurately reflects the actual level of risk. While prime logistics assets in Prague and Warsaw currently trade in the low-5 percent to low-6 percent range, comparable properties in Germany and the Netherlands are priced closer to the mid-to-high-4 percent level.

According to Barnáš, this spread reflects factors such as higher financing costs, geopolitical concerns linked to the war in Ukraine and reduced debt market liquidity rather than deterioration in tenant quality or occupational fundamentals. He noted that many logistics parks in CEE are leased to the same international occupiers active in Western Europe, while rents in the region remain significantly lower than in more mature Western markets.

Rather than relying on aggressive yield compression assumptions, ARETE Industrial focuses on acquisitions where pricing already reflects the wider regional spread and where income stability is supported through indexed leases and long-term occupancy.

Although headline occupancy rates across many logistics portfolios remain high, Barnáš acknowledged that effective economic occupancy often tells a different story. While physical occupancy in ARETE Industrial’s portfolio stands at 100 percent, effective occupancy after accounting for incentives and rent adjustments is typically lower across the wider market.

He said many CEE logistics portfolios currently generate effective occupancy levels in the high-80 percent to low-90 percent range once leasing incentives and headline-to-effective rent differences are taken into account. As a result, the company models cash yields conservatively and applies discounts linked to incentive amortisation.

Rather than focusing solely on occupancy metrics, ARETE Industrial closely monitors weighted average unexpired lease terms and reletting risk. Asset management efforts are concentrated on early lease renegotiations, extension strategies and pre-leasing speculative development phases before completion.

Barnáš also highlighted the challenges investors face in assessing liquidity in a market where transaction volumes remain relatively subdued and comparable sales evidence is limited. To assess market conditions, the company combines several indicators including broker pricing guidance, debt market activity, listed market performance and evidence gathered from its own acquisition pipeline.

According to Barnáš, broker pricing expectations and final transaction pricing have become more aligned over the past 18 months, suggesting market stabilisation. He added that financing margins offered by banks active in the region have also narrowed in recent months, while listed European logistics companies with CEE exposure have seen implied yields compress ahead of private market repricing.

Taken together, these indicators suggest to ARETE Industrial that logistics yields in the region may have stabilised, although Barnáš stopped short of calling a definitive market bottom.

On tenant credit risk, Barnáš argued that the market continues to differentiate insufficiently between top-tier occupiers and weaker regional tenants. In his view, logistics assets leased to large international occupiers continue to offer attractive pricing relative to the underlying covenant strength, while lower-tier tenant risk is generally being priced more accurately.

To manage this exposure, ARETE Industrial applies portfolio-level tenant concentration limits and requires additional guarantees or security structures for weaker covenants rather than pursuing additional yield at the expense of credit quality.

Barnáš also described Poland and the Czech Republic as increasingly distinct logistics markets rather than directly comparable competitors.

He characterised Poland as the primary beneficiary of European nearshoring trends, supported by its role as a manufacturing base linked to Germany, its position in e-commerce supply chains and its longer-term strategic relevance for future reconstruction activity related to Ukraine. Poland has continued to absorb large volumes of new logistics development without major rental declines, although rental growth has moderated following sharp increases in 2022.

The Czech market, by contrast, is more mature, more supply constrained and more heavily exposed to the automotive sector. Vacancy rates remain lower than in Poland and rental levels in Prague and Brno are generally higher, contributing to lower volatility and stronger pricing stability.

This distinction is also reflected in market yields, with prime Czech logistics assets currently trading inside Polish yields. Barnáš said the Czech Republic continues to play an important role in portfolio construction as a lower-volatility market even if Poland currently offers stronger growth prospects.

For ARETE Industrial, the investment strategy therefore remains diversified across the region. The company is currently overweight Poland from a growth perspective while maintaining Czech exposure for defensive income stability and selectively evaluating opportunities in Slovakia, Hungary and Southeastern Europe.

© 2026 cij.world
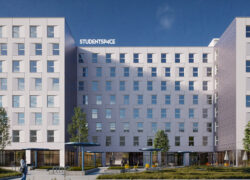
StudentSpace Secures PLN 215.8 Million Financing for Warsaw Student Housing Projects

StudentSpace has secured PLN 215.8 million in financing from PKO Bank Polski to support the development of two student housing projects in Warsaw.

The financing will be used for projects including a development on Wołoska Street, with the two schemes expected to provide around 1,100 student beds in total.

The transaction follows earlier financing obtained for StudentSpace projects in Kraków and forms part of the platform’s broader expansion in Poland’s purpose-built student accommodation (PBSA) sector.

Warsaw remains one of the country’s largest academic centres, while the supply of modern student accommodation continues to lag demand. StudentSpace said the new financing would support the further growth of its Warsaw portfolio alongside its focus on operational management and sustainability standards.

Marek Obuchowicz said the Polish PBSA market continues to develop as institutional investors increase their presence in the sector, supported by demand for modern student housing.

StudentSpace developments are designed to include private rooms and shared amenities such as study areas, gyms, kitchens, workshop spaces and communal facilities intended to support student living and social interaction.

The platform’s current pipeline includes six projects with approximately 2,800 beds across Kraków and Warsaw.

StudentSpace was launched in 2024 as a joint venture between SIGNAL Capital Partners, Griffin Capital Partners and Echo Investment.

Griffin Capital Partners acts as investment and asset manager for the platform. The financing transaction on behalf of StudentSpace was led by Artem Kovtun.

Czech Building Act Amendment Faces Criticism from Professional Groups

Professional organisations in the Czech Republic have raised concerns over proposed amendments to the country’s Building Act, warning that the changes could disrupt the current permitting system rather than accelerate construction activity.

Representatives of municipalities, architects, engineers, public administration officials and environmental groups said during a discussion in the Chamber of Deputies that the proposed legislation contains significant shortcomings and could increase operational costs while creating uncertainty for existing staff within building authorities.

The amendment, which is scheduled for a second reading in parliament this week, would introduce a centralised building administration system. However, critics argue that the proposal was submitted through a parliamentary motion without undergoing a standard consultation process or regulatory impact assessment.

According to Jindra Tužilová, lawmakers are expected to vote on legislation whose final form has not been fully available to the public due to the legislative process used for its submission. She added that making substantial changes to the amendment later in the parliamentary process would be difficult.

Under the proposed timetable, a new central Territorial Development Office would be established in 2027, with the reform expected to be fully implemented from January 2028. However, professional groups argue that the transfer of employees from municipal building authorities to state administration structures remains unresolved.

Jan Holický said municipal employees could face less favourable conditions under the state system, as municipalities are currently able to offer benefits that state institutions cannot provide. He warned that some employees may choose not to remain in the system after the transition.

Professional organisations also questioned the financial implications of the reform, arguing that operating costs for the new structure could exceed those of the current decentralised system.

Jan Kasl said the amendment contains numerous technical and procedural issues. According to Kasl, the broader concern is the risk that the reform could weaken the overall permitting framework during the transition period. He noted that, during implementation, larger projects overseen by the Transport and Energy Building Authority could receive priority attention.

Environmental organisation Arnika also criticised the proposed framework, arguing that it could reduce environmental oversight and weaken public participation in permitting processes. Representatives expressed concern over the concentration of authority within the planned central office structure.

The Confederation of Industry and Transport of the Czech Republic took a more supportive position, stating that a centralised building administration could help accelerate infrastructure development and improve permitting efficiency for strategic projects.

Source: CTK

European Retail Market Shows Stability Despite Economic Uncertainty

Union Investment and NIQ-GfK have reported that Europe remains the world’s most attractive retail region despite continued geopolitical and economic uncertainty.

According to the latest Global Retail Attractiveness Index (GRAI), the EU-15 retail index reached 115 points in the first quarter of 2026, remaining ahead of North America at 99 points and Asia-Pacific at 97 points.

The report indicates that although consumer sentiment and retailer confidence softened slightly over the past two quarters, retail activity across Europe has remained relatively stable. Higher energy prices, geopolitical tensions and broader economic uncertainty have continued to weigh on market sentiment, but retail spending has remained resilient.

Roman Müller said the European retail market is showing signs of stabilisation rather than contraction, supported by steady retail trade and the sector’s ability to adapt to external pressures.

Laura Roll added that Europe’s retail sector continues to benefit from balanced market conditions and comparatively resilient consumer spending patterns.

Among European markets, Poland recorded the highest index score at 136 points in the first quarter, followed by the Czech Republic with 126 points and Portugal with 123 points.

The Czech Republic recorded one of the strongest increases in consumer confidence in Europe, rising by 16.2 points. At the same time, retail confidence in the country declined by 24.5 points, reflecting growing caution among retailers despite improving household sentiment. Nevertheless, the Czech market remained one of the strongest-performing retail markets in Europe overall.

France continued to face weaker conditions, with declining consumer confidence and deteriorating labour market indicators contributing to a fall in its retail index to 109 points. However, retail sales activity in the country remained positive, reflecting broader trends across Europe where consumer spending has continued despite weaker sentiment indicators.

PORR Surpasses EUR 10 Billion Order Backlog in Strong Start to 2026

PORR AG reported a strong first quarter for 2026, with its order backlog exceeding EUR 10 billion for the first time in the company’s history, supported by continued infrastructure demand across Central and Eastern Europe.

The Austrian construction group said its order backlog rose by 13.5 percent year-on-year to EUR 10.0 billion, providing visibility beyond a full year of production output. Order intake increased by 14.7 percent to EUR 1.77 billion, while operating profit (EBIT) climbed 13.1 percent to EUR 14.3 million.

The company maintained its outlook for 2026, expecting moderate growth in output and revenues together with a further improvement in EBIT margin performance.

Chief Executive Officer Karl-Heinz Strauss said the results confirmed the effectiveness of the group’s long-term growth strategy, particularly its focus on civil engineering and selected building construction sectors with strong medium-term demand potential.

Infrastructure continues to be the key growth driver for the group, supported by European Union funding programmes linked to transport and energy projects. Demand for healthcare facilities, industrial developments and data centres also remained resilient during the quarter.

PORR generated production output of EUR 1.3 billion during the first three months of the year, an increase of 2.3 percent compared with the same period in 2025. EBITDA rose 3 percent to EUR 66.8 million, while the EBIT margin improved slightly to 1.1 percent from 1.0 percent a year earlier.

Although revenues declined marginally by 1.5 percent to EUR 1.25 billion due to prolonged winter conditions and a higher share of consortium projects, the group said profitability benefited from cost reductions and strong performances in Poland and the wider CEE region.

Poland delivered some of the strongest growth within the group. Production output in the country rose 22.8 percent to EUR 214 million, while the order backlog increased 22.5 percent to EUR 2.01 billion. Order intake in Poland more than doubled year-on-year to EUR 331 million, driven largely by transport infrastructure contracts.

Among the key projects secured in Poland were sections of the S6 Szczecin western bypass and the DK25 national road between Konin and Rychwał. The company also won a major bridge construction contract for a crossing over the Oder River in Pomorsko.

In Germany, PORR reported signs of improving market activity despite weather-related disruptions early in the year. Order intake in the German business increased 35.7 percent to EUR 418 million, supported by infrastructure and specialist civil engineering projects, including participation in the Fehmarnsund crossing project.

The CEE segment also expanded, with production output rising 8.6 percent to EUR 97 million and the order backlog growing by more than 40 percent to EUR 1.4 billion. New contracts in Romania included water supply and wastewater infrastructure systems in the Cosoba and Săbăreni regions, as well as urban redevelopment works in Timișoara.

PORR said long-term market fundamentals remain supportive despite geopolitical risks linked to the wars in Ukraine and Iran, volatile energy prices and broader economic uncertainty. The company noted that infrastructure investment programmes funded by the EU and national transport and energy operators continue to underpin demand across its core markets.

Residential construction remains more challenging due to financing costs and geopolitical pressures, although the company sees opportunities in affordable housing through its modular construction platform, PORR Living.

Civil engineering currently accounts for around 60.6 percent of the company’s total order backlog, while building construction represents 33.6 percent.

Looking ahead, the group reiterated its long-term target of achieving an EBIT margin of between 3.5 percent and 4 percent by 2030.

Rising Energy Costs Add Pressure to Summer Travel Budgets for Czech Families

Czech households preparing for summer holidays abroad are facing higher transport expenses this year as fuel and aviation costs continue to react to instability in global energy markets. Analysts point to tensions in the Middle East and higher oil prices as key factors increasing the cost of both road and air travel across Europe.

According to market estimates reviewed alongside publicly available energy and inflation data, families driving to popular destinations such as Croatia are likely to spend noticeably more on fuel compared with last summer. Additional increases in motorway tolls and transport-related fees across transit countries including Austria and Slovenia are also contributing to the higher overall cost of travel.

The pressure is not limited to motorists. Airlines are also dealing with higher operating costs linked to aviation fuel markets, although the impact on ticket prices varies depending on destination, booking periods and fuel hedging strategies used by carriers. Industry observers note that some routes to Mediterranean destinations, including Greece, Turkey and Egypt, are already reflecting rising costs through higher fares and fuel-related surcharges.

Recent European energy data supports the broader trend of rising fuel costs. Fuel prices across the EU have increased significantly over the past year, with Czechia recording one of the sharper rises among member states during recent months. Analysts say this has narrowed some of the traditional cost advantages associated with car travel, even though travelling by road remains more economical for larger families compared with flying.

At the same time, economists caution that exchange-rate developments and local inflation continue to influence the final cost of holidays abroad. In some destinations, weaker local currencies have been offset by rising domestic prices, reducing any benefit for foreign tourists. In others, tourism demand itself remains strong enough to keep accommodation and service prices elevated despite softer currencies.

Fuel prices in Croatia have remained comparatively stable due to ongoing government regulation, making the country somewhat less affected by price swings than other European destinations. By contrast, long-distance car journeys to countries such as Spain or Italy are becoming increasingly expensive due to a combination of fuel costs, motorway charges and longer travel distances.

Analysts also note that the structure of a holiday plays an important role in how consumers experience inflation. Independent travellers are more directly exposed to local restaurant, transport and retail prices, while package holidays are influenced more heavily by airline contracts, hotel agreements and tour operator pricing policies.

While oil prices have eased slightly from recent peaks, uncertainty in global energy markets continues to create volatility ahead of the main summer travel season. Economists expect transport costs to remain under pressure throughout the coming months, particularly if geopolitical tensions persist or airlines begin passing a greater share of fuel costs on to consumers in future booking cycles.

Panattoni Completes Panattoni Park Białystok III

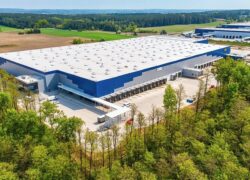
Panattoni has completed construction of Panattoni Park Białystok III, a logistics development comprising more than 32,000 sqm in Choroszcz, near Białystok.

According to the developer, six tenants had already signed leases before the completion of the project. The occupiers represent sectors including courier services, logistics, construction, environmental protection and retail, including electronics and cosmetics. Around 9,400 sqm of warehouse space remains available, which Panattoni states is currently the only Class A warehouse space available in the Podlaskie region.

“The completion of Panattoni Park Białystok III – our third development in the region – confirms the growing importance of the Podlaskie Voivodeship on Poland’s logistics map,” said Dorota Jagodzińska-Sasson.

“The region is increasingly attracting companies operating on a national and international scale. A key factor here is the development of road infrastructure, which strengthens Białystok’s position as a major distribution hub in this part of Europe,” she added.

Panattoni was the first developer to introduce Class A industrial space to the Podlaskie Voivodeship and has now completed three projects in the region with a combined area of approximately 109,000 sqm.

The latest development is located near the Białystok-Zachód junction on the S8 expressway, providing access to the national road network and the Via Carpatia corridor, which is intended to connect Northern and Southern Europe. The site is around 16 km from the centre of Białystok.

The project is targeting a BREEAM Excellent certification and incorporates measures intended to improve energy efficiency and reduce water consumption. The facility will also include electric vehicle charging infrastructure.

Analysis: Asia, Britain and Sweden Offer Better Value for Czech Tourists This Summer

For Czech travellers planning holidays abroad this summer, destinations in Asia, as well as the UK and Sweden, have become relatively cheaper due to exchange rate developments and local price trends, according to an analysis by  XTBAttachment.tiff.

The analysis compared changes in local price levels and the exchange rate performance of the Czech koruna across selected destinations.

Japan and South Korea recorded the largest declines in travel costs from the perspective of Czech consumers. According to the report, the cost of a typical consumer basket in Czech crown terms fell by 13.3 percent in Japan and 11.2 percent in South Korea, mainly due to the weakening of the yen and the won against the koruna.

Other destinations where costs declined included New Zealand, where prices fell by 2.95 percent, followed by the United Kingdom at 2.4 percent, Sweden at 2.2 percent, Taiwan at 2.1 percent, Canada at two percent and the United States at 1.5 percent.

By contrast, some destinations became more expensive for Czech tourists. Travel costs in Hungary rose by 12.4 percent, while Brazil increased by 12.1 percent, Australia by 10.2 percent and Russia by 9.2 percent.

According to Pavel Peterka, exchange rate movements alone do not determine whether holidays become cheaper.

“A textbook example where the weakening of the currency may not reduce prices is Turkey, where the lira weakened by 19 percent against the koruna, but double-digit inflation above 32 percent completely erased the exchange-rate effect,” Peterka said. “As a result, holidays there increased by seven percent year-on-year.”

The analysis also noted that many tourism-related services, including hotels, flights and package holidays, are often priced in euros or US dollars rather than local currencies. This can limit the impact of weaker local currencies on final holiday costs for travellers.

Demand levels also continue to influence prices. According to XTB, strong tourist demand during the summer season can keep accommodation and service prices elevated even in destinations where local currencies have weakened.

The report further highlighted differences between independent travel and package holidays. Individual travellers are more directly exposed to local price levels for restaurants, transport and services, while package holiday prices are more strongly influenced by airline costs, accommodation contracts, tour operator margins and pricing conditions in the Czech market.

Source: CTK

Sonae Sierra Reports Higher Adjusted Net Income in 2025

Sonae Sierra reported adjusted net income of €109.8 million for 2025, up 12.9 percent year-on-year, according to its latest Economic, Environmental and Social (EES) Report.

The company described 2025 as one of the strongest years in its history, supported by growth across its real estate management, asset management and development activities. At the end of the year, assets under management totalled €6.9 billion.

During 2025, Sonae Sierra managed more than 560 assets with a combined gross lettable area of 3.3 million sqm. Across its European shopping centre portfolio, tenant sales increased by 4.6 percent, while occupancy remained at 99 percent.

A key development during the year was the acquisition of the German real estate management business of  Unibail-Rodamco-Westfield. According to the company, the transaction increased the number of managed assets in Germany from six to 18 and strengthened its position in the institutional retail real estate market.

“2025 was one of the best years in Sonae Sierra’s history. The results demonstrate the success of our strategy: We are expanding, investing strategically, and further developing Sonae Sierra into a fully integrated real estate platform,” said Fernando Guedes de Oliveira.

“We will continue to offer strategic and operational excellence to institutional investors in Europe. Building on the solid foundation we have established and driven by our commitment, we are well-positioned to continue creating value across all areas of our business,” he added.

Sustainability remained a central focus of the company’s operations and investment strategy. Sonae Sierra stated that 67 percent of its managed investment properties are now equipped with solar panels, contributing to an estimated avoidance of 630 tonnes of CO₂ emissions during 2025.

The company also reported a 49 percent reduction in Scope 1 and 2 greenhouse gas emissions per square metre compared to 2019 levels, as part of its target to achieve net-zero emissions by 2040.

In addition, two shopping centres within the portfolio achieved the highest BREEAM In-Use certification rating of “Outstanding”, reflecting standards related to environmental performance, operational efficiency and building management.

Alesonor and Medikali Partner on Medical Clinic at Amber Forest Agora

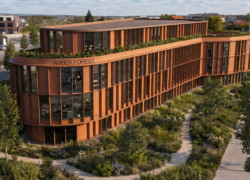
Romanian developer  Alesonor and private healthcare operator  Medikali have signed a partnership agreement for the development of a medical clinic within Amber Forest Agora, the mixed-use facilities area of the Amber Forest residential project near Bucharest.

The medical facilities building is being developed to nZEB standards and will provide approximately 3,000 sqm of space on a plot of around 2,000 sqm. The total investment is estimated at €7 million. Medikali will occupy around 1,000 sqm within the building.

The clinic is scheduled to open in 2028 and will form part of the broader Amber Forest Agora concept, which includes educational, sports, commercial and medical facilities. According to the developers, the project is intended to support the “15-minute city” model, where residents can access key daily services within walking distance.

Medikali said the new clinic will provide multidisciplinary healthcare services for both Amber Forest residents and the wider northern Bucharest area. The facility will include laboratory testing and imaging services, including MRI, ultrasound and mammography, alongside specialties such as cardiology, dermatology, endocrinology, gastroenterology, neurology, pediatrics, orthopedics, psychiatry and gynecology.

Founded in 2022 by Dr. Adina Negoiță, Medikali currently operates a clinic in the Pallady area of Bucharest. The company states that it treats more than 50,000 patients annually through its clinic operations and over 3,000 patients each year through its recovery centre. Its medical team includes more than 80 doctors across 30 specialties.

Amber Forest Agora is planned as the central amenities area of the Amber Forest development and will also include an open-air cinema, co-working facilities and more than 500 parking spaces for visitors. According to Alesonor, the facilities are intended to serve not only project residents but also the wider northern Bucharest area within an approximate 20-minute radius.

Amber Forest is being developed across 31 hectares and includes residential units, green spaces and community facilities. The project has received LEED Platinum v4.1 certification for Communities: Plan and Design. To date, 270 residential units have been delivered, while 580 units have been sold out of a total planned 690 homes.

front page info
LATEST NEWS