Madrid and Barcelona Office Markets Split as Demand Shifts to Modern Buildings

Madrid and Barcelona’s office markets are entering a period in which the amount of vacant space is becoming a less useful measure of market conditions. Both cities still have substantial office availability, yet companies looking for modern buildings in established business districts are finding their choices increasingly restricted. Demand is concentrating on properties offering efficient energy performance, modern technical specifications, strong public transport connections and working environments suited to changing corporate requirements.

The contrast is particularly visible in central Madrid. Availability across the wider market remains considerably higher than in the principal business districts, where good-quality space has become increasingly difficult to secure. Large occupiers seeking substantial contiguous floors can therefore face limited options even though headline statistics suggest plenty of offices remain vacant. Barcelona presents a similar picture, with significant availability across the wider city but much tighter supply of top-quality offices in its most sought-after locations.

Corporate requirements are accelerating this divide. Businesses are paying greater attention to energy consumption, environmental performance, employee experience, accessibility and long-term operating costs. When companies consolidate or relocate, many are using the opportunity to improve the standard of their accommodation rather than simply replacing one office with another. This concentration of demand is contributing to rising prime rents in Madrid and Barcelona, while less competitive buildings cannot necessarily expect to benefit from the same rental growth.

The trend creates a substantial challenge for owners of ageing properties. Research covering Madrid and Barcelona indicates that millions of square metres could require significant modernisation during the coming years if buildings are to remain competitive. Improvements to energy efficiency, building systems, common areas, accessibility and workplace facilities can involve substantial capital expenditure. Owners must therefore decide whether future rents justify refurbishment or whether a different strategy is required.

For some properties, conversion is becoming part of that calculation. Madrid has already seen offices repositioned for residential, hospitality and flexible accommodation, while research suggests that part of the obsolete stock across Madrid and Barcelona could potentially be converted into housing. However, building configuration, planning requirements, location and development economics mean conversion is not a solution for every ageing office. Well-located buildings with suitable structures may instead offer significant opportunities for refurbishment.

The development pipeline adds further pressure. New construction alone is unlikely to resolve the shortage of competitive space, particularly because part of forthcoming supply involves the renovation of existing buildings rather than completely new developments. Investors are consequently paying closer attention to individual asset characteristics. A vacant modern office in a strong location represents a very different investment proposition from an ageing building requiring extensive capital expenditure, even though both properties appear within the same city-wide vacancy statistics.

Madrid and Barcelona are therefore not simply moving from higher vacancy towards lower vacancy. Their office markets are becoming increasingly divided between modern, efficient and well-located buildings attracting concentrated occupier demand and ageing properties facing pressure to improve, reposition or find another purpose. The result is a market where office space can appear plentiful while the buildings companies most want to occupy are increasingly difficult to find.

Source: CIJ.World Research & Analysis Team

UK crypto enforcement reaches London premises ahead of wider regulatory overhaul

Britain’s financial regulator is increasing pressure on unregistered cryptocurrency businesses operating from physical locations as the country prepares for a substantially broader regulatory framework for digital assets. The Financial Conduct Authority, working with HM Revenue & Customs and the Metropolitan Police, visited three locations in London on 10 September as part of an investigation into suspected unregistered peer-to-peer cryptocurrency trading. Operators at each location were instructed to stop activities suspected of falling outside existing registration requirements.

The operation follows an intervention in April, when the FCA and other enforcement bodies visited eight London premises in connection with suspected unregistered peer-to-peer crypto activity. Evidence collected during that operation is being used to support criminal investigations and other enforcement action. Across the two operations, the FCA and its partners have therefore visited 11 London premises during 2026, showing how enforcement against unregistered crypto businesses is increasingly extending beyond online activity to identifiable physical locations.

Peer-to-peer transactions allow buyers and sellers to exchange cryptoassets directly rather than through a conventional centralised exchange. Individuals trading privately are not necessarily subject to registration requirements, but anyone conducting relevant peer-to-peer crypto trading as a business in the UK requires appropriate registration. According to the FCA, there are currently no registered peer-to-peer crypto businesses operating in the country. The regulator is concerned that unregistered operators can provide channels through which illicit funds are moved while avoiding anti-money-laundering controls.

The use of identifiable London premises adds a physical property dimension to an industry generally associated with digital transactions. The FCA has not disclosed the addresses involved or whether the locations were offices, retail units or other forms of commercial accommodation. There is also no indication that landlords or property owners were implicated in the suspected activity. The operations nevertheless demonstrate that enforcement against digital-asset businesses can extend directly to premises from which suspected unregistered operations are conducted.

The September action comes as Britain prepares for a major expansion of crypto regulation. The existing framework principally covers anti-money-laundering requirements and financial promotions, but a broader FCA authorisation regime is scheduled to take effect on 25 October 2027. Applications under the new system are due to open on 30 September 2026, beginning the transition towards a substantially wider regulatory perimeter.

The future system will bring a broader range of activities within financial-services regulation, including crypto trading platforms, intermediaries, custody providers, stablecoin businesses and certain staking activities. Existing registration under anti-money-laundering rules will not automatically provide authorisation under the new framework. Companies entering the regime will face requirements covering areas including financial resources, governance, operational resilience and market conduct, bringing regulated crypto businesses closer to the compliance structures applied across established financial services.

For Britain’s commercial property market, the immediate impact remains limited, but the direction of regulation could become increasingly relevant to landlords, flexible-office operators and property managers. As crypto businesses become more institutionalised, verifying the legal entities occupying premises and understanding the activities conducted there may become more important within tenant due diligence and reputational risk management. The London operations underline a wider point: while cryptocurrency transactions are digital, businesses facilitating them can still depend on physical premises, bringing parts of the commercial property market into an expanding regulatory and enforcement environment.

UK study finds widespread exposure to unwanted content as online rules tighten

More than three-quarters of UK adult internet users say they encountered material they regarded as hateful during the previous year, according to new Ofcom research examining how people experience potentially harmful and distressing content online. The findings arrive as Britain’s communications regulator develops additional requirements for the largest digital platforms under the Online Safety Act.

Ofcom commissioned YouGov to survey 4,443 UK adults in February 2026, with the sample designed to be nationally representative. Among adult internet users, 77% said they had encountered content they considered hateful during the preceding 12 months, while 58% reported seeing such material at least weekly. The research measured respondents’ perceptions rather than determining whether individual examples met the legal definition of illegal hate speech.

Reported exposure was particularly high among some groups. Around 90% of LGBTQ+ respondents and 85% of people from minority ethnic backgrounds said they had encountered material they regarded as hateful. The rate was also 90% among internet users aged 18 to 24. Women and men reported broadly similar overall exposure, although women were more likely to report encountering sexist material.

Much of the content was encountered without users actively looking for it. More than three-quarters of those who had experienced perceived online hate said they came across it while scrolling, while more than half encountered it through comments or replies. The findings place greater attention on personalised feeds, recommendations and other systems that influence what users see rather than focusing solely on material people deliberately search for.

Separate Ofcom research examined adults’ experiences with online material promoting suicide, self-harm and eating disorders. Unlike the larger YouGov survey, this was qualitative research involving 30 adults with direct experience of such material and five professionals working with affected people. Participants described cases in which content they had previously searched for continued to appear through recommendations or automated playback after they no longer wanted to see it. Because of the study’s design and size, these experiences cannot be treated as estimates of how frequently the same patterns occur across the wider UK population.

The research also identified a more complicated attitude towards filtering than simply wanting potentially upsetting material removed. Participants generally supported tools allowing them to block or mute accounts and indicate that they wanted to see less of particular subjects. Some, however, were reluctant to remove categories of content completely because they wanted to remain informed about issues affecting their communities, support other users or continue encountering different perspectives.

Content warnings were another area where participants expressed preferences for greater individual control. Warnings requiring users to make an active decision before opening potentially disturbing material were generally regarded as more useful than notices that disappeared automatically. The findings suggest that some users favour systems that provide information and choice before viewing content rather than automatically preventing access to it.

The research has a direct connection with Britain’s developing online-safety regime. Ofcom says the findings are contributing to its evidence base as it considers additional requirements for Category 1 services, which include some of the country’s largest social-media, video and messaging platforms. The regulator is currently consulting on measures covering user controls, identity verification, complaints, terms of service, privacy and freedom of expression, with the consultation scheduled to close on 2 October.

The regulatory work is progressing while Ofcom faces legal challenges from several technology companies over aspects of the Online Safety Act’s implementation. Meta is contesting the Category 1 classification of Instagram and WhatsApp, while other disputes concern regulatory fees and Ofcom’s information-gathering powers. There is no evidence that the latest research was commissioned specifically in response to those cases, but its findings form part of the evidence being developed as Ofcom determines how the legislation should operate in practice.

The findings ultimately point towards a regulatory challenge that extends beyond deciding which material should remain online. Users reported wanting greater influence over what recommendation systems and feeds place in front of them while retaining the ability to access material they choose to see. As Britain moves into the next phase of implementing its online-safety regime, the balance between protection, individual choice and platform responsibility is likely to remain one of the central issues facing regulators and technology companies.

Meta steps up UK legal fight as online safety rules enter next phase

Meta has expanded its legal dispute with UK communications regulator Ofcom by challenging the classification of Instagram and WhatsApp under the Online Safety Act. The latest appeal concerns Ofcom’s decision to place the services in Category 1, which subjects widely used platforms to additional regulatory requirements. Roblox and Quora have also appealed their classifications. Meta maintains that its challenge concerns how Ofcom is interpreting and implementing the legislation rather than opposition to the Online Safety Act itself.

Ofcom’s current Category 1 register includes Facebook, Instagram, WhatsApp, YouTube, TikTok, X, Reddit, Snapchat, Pinterest, Roblox and Quora, while Messenger and Threads are among services identified as potentially meeting the same thresholds. Category 1 companies face additional requirements covering areas including user controls, identity verification, complaints, terms of service, freedom of expression, privacy and the treatment of certain journalistic and democratic content. Meta argues that some requirements designed for large public platforms are not necessarily appropriate for private conversations and small messaging groups on WhatsApp.

The categorisation case is one of several disputes between Meta and Ofcom. The technology group is also challenging elements of the system used to finance the regulator’s online-safety work, under which qualifying companies contribute towards Ofcom’s costs based partly on qualifying worldwide revenue. Meta argues that the approach places a disproportionate financial burden on the largest international companies. The legislation also gives Ofcom powers to impose substantial penalties for non-compliance, with maximum fines linked to qualifying worldwide revenue.

A separate dispute concerns Ofcom’s powers to obtain information from regulated platforms. Meta, TikTok and X have questioned whether some requests for internal data and documentation extend beyond what is necessary or permitted under the legislation. Ofcom argues that access to appropriate company information is required to determine whether platforms are meeting their responsibilities. One of Meta’s separate challenges is scheduled for a substantive High Court hearing on 13 and 14 October.

The growing volume of litigation has increased scrutiny of how quickly Britain’s online-safety regime can be implemented. Some politicians have argued that legal challenges could delay progress, while technology companies maintain that judicial scrutiny is a legitimate way of determining the boundaries of a complex regulatory framework. There is not yet sufficient evidence to establish how much the court cases themselves have delayed implementation. A House of Lords inquiry is separately examining the effectiveness and implementation of the Online Safety Act, with senior Ofcom officials giving evidence in September.

Significant parts of the regulatory framework are already operating. Ofcom has progressively introduced requirements under the legislation and published its register of categorised services during 2026. Further Category 1 obligations are now being developed covering areas such as user choice, identity verification, complaints and terms of service. Additional compliance deadlines are approaching, including requirements for certain regulated companies to provide updated risk-assessment records to Ofcom and subsequently publish summaries.

The disputes are becoming an important test of how Britain’s regulatory system applies to global technology businesses. The cases are not deciding whether the Online Safety Act should exist, but could clarify how Ofcom categorises services, obtains company information, calculates regulatory costs and applies additional obligations. For international technology companies, the outcome could influence the cost and complexity of operating in the UK as legal resources, compliance systems, internal reporting and regulatory oversight become an increasingly significant part of running large digital platforms.

Greece’s Island Property Boom Is Putting Infrastructure at the Centre of Investment Risk

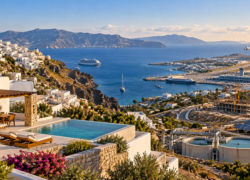
Greece’s islands remain among the country’s most attractive real estate markets, supported by international tourism, hotel investment and continuing demand for holiday homes. Yet the ability of some destinations to accommodate further property development is becoming increasingly connected to something that rising visitor numbers cannot provide: infrastructure. Water supply, electricity networks, wastewater treatment, roads, airports, ports and housing for tourism workers are becoming increasingly important considerations for developers and property owners. The issue is particularly significant on islands, where geography limits the ability to expand infrastructure and where demand can increase dramatically during the summer months.

This creates a different way of looking at Greek island property. Tourism demand can support hotel revenues, residential prices and land values, but it does not necessarily mean that another hotel, villa development or resort can be accommodated easily. Investors increasingly need to consider not only whether customers will come, but whether the destination has the physical capacity to support additional development.

Water is one of the clearest examples. During 2026, Greece continued investing in island water infrastructure as drought and increasing consumption placed pressure on existing systems. A national programme approved dozens of water-supply projects worth more than €75 million, including new and expanded desalination facilities serving island communities. The investment reflects a structural challenge. Tourism demand reaches its highest point during summer, when rainfall is limited and temperatures are high. Hotels, swimming pools, restaurants, landscaping and holiday homes can substantially increase consumption compared with the requirements of the permanent population.

Desalination can provide additional supply, but it does not remove the infrastructure issue. Plants require investment and energy, while water still has to be stored and distributed through local networks. Improving supply therefore frequently requires a combination of desalination, network modernisation, storage and more efficient management. For property investors, these systems exist outside the boundaries of an individual hotel or residential development but can directly affect how reliably the property operates. A project with secure access to sufficient water carries a different development and operating profile from one dependent on future infrastructure improvements.

Electricity creates a similar consideration. Modern hotels consume substantial amounts of power through cooling, kitchens, pools, wellness facilities, lighting and other services. As resorts become more sophisticated and buildings increasingly electrify their operations, electricity requirements can rise even without substantial increases in room numbers. Renewable generation can reduce part of that pressure, particularly given the potential for solar energy across Greece. But generating electricity and delivering it reliably through an island network are different challenges. Connection capacity and local distribution infrastructure remain relevant when evaluating major developments.

Wastewater and solid waste add another dimension. Island systems must accommodate populations that can increase dramatically during the tourism season. Expanding hotel and residential capacity therefore creates continuing requirements beyond the properties themselves, increasing the importance of municipal and regional infrastructure investment. This makes environmental performance unusually practical in island real estate. Sustainability is not simply about obtaining certification for an individual building. Water consumption, energy efficiency, wastewater management and the pressure a development places on local services can influence both operating costs and the long-term acceptability of further construction.

Transport investment illustrates another side of the story. Greece has invested heavily in regional aviation infrastructure. The 14 airports operated by Fraport Greece have undergone extensive modernisation, improving the country’s ability to accommodate international tourism. Additional investment is planned at several airports, including Mykonos and Santorini, as passenger volumes place increasing pressure on existing capacity. Improved airports strengthen property markets by making destinations easier to reach and supporting larger visitor flows. But additional aviation capacity can also increase demands on infrastructure elsewhere on an island. More visitors require transportation, water, electricity, waste services and accommodation, both for tourists and the people employed to serve them.

Crete provides an important comparison with the smaller islands. Construction of the new international airport at Kastelli represents one of Greece’s largest transport infrastructure projects and is intended to replace the existing Heraklion airport. Together with new road connections, the airport will substantially change the aviation infrastructure serving the country’s largest island. Crete’s scale also gives it a different development profile. It contains several important population centres, a broad tourism economy and considerably more land than destinations such as Mykonos or Santorini. That does not mean Crete is free from infrastructure constraints. Water resources, road capacity, environmental considerations and planning remain important across the island. However, the scale and geography of the infrastructure challenge are fundamentally different.

Smaller islands have fewer options for absorbing growth. Mykonos and Santorini demonstrate the relationship particularly clearly. Their limited geography is one reason property scarcity is so valuable, but the same physical limitations make continual expansion difficult. Roads, water networks, waste systems and other infrastructure must accommodate intense seasonal activity within relatively small areas. Paros presents another version of the issue. Rapid tourism and residential growth can increase demand for utilities and public infrastructure considerably faster than permanent population statistics alone would suggest. For investors, understanding seasonal capacity can therefore be more useful than looking only at the number of permanent residents.

These constraints do not necessarily have the same effect on every type of property. For an established hotel, limits on additional construction can potentially become an advantage. If tourism demand remains strong while creating competing hotel supply becomes more difficult, existing high-quality properties may benefit from greater scarcity. Development land faces a different calculation. A site can occupy an exceptional location and still require substantial investment before development becomes possible. Water connections, electricity capacity, wastewater solutions, road access and planning requirements can influence both the cost and timing of a project.

Investors purchasing development land therefore need to distinguish between theoretical development potential and realistically deliverable property. Infrastructure availability can become part of that assessment even when it is not separately reflected in the advertised price of the site. The same distinction applies to operating assets. An existing resort with secure utilities, adequate wastewater infrastructure, established road access and sufficient operational capacity can have a different risk profile from a property requiring major future infrastructure expenditure. It is too early to argue that Greek island property valuations consistently contain a measurable infrastructure premium, but the economics suggest that infrastructure certainty can increasingly influence development risk, operating expenditure and ultimately investment returns.

Labour availability introduces another constraint. Successful tourism destinations require large seasonal workforces, while some of the country’s strongest island property markets also have high housing costs and limited rental availability. Hotels and other tourism businesses can consequently face difficulties accommodating employees during peak periods. Some operators respond by arranging or providing staff accommodation. For property investors, this can become another operating requirement to consider alongside utilities and transport. A resort’s ability to accommodate its workforce can affect recruitment, costs and the practical operation of the asset.

Employee housing should not yet be treated as a standard component of Greek hotel valuation, but it is increasingly relevant to the economics of operating tourism property in expensive island markets. Residential development also interacts with the problem. Holiday homes and tourism accommodation compete for land and infrastructure, while increased demand for residential property can place additional pressure on housing available to permanent residents and seasonal workers.

The result is that investors need to examine island property beyond the boundaries of the individual site. A development may have excellent architecture, an exceptional beachfront location and strong projected demand, but its long-term performance can still depend on infrastructure controlled by municipalities, utility providers and national authorities. That changes the traditional definition of a prime location. Sea views, beach access, proximity to attractive towns and international recognition will remain fundamental to Greek island property values, but access to reliable infrastructure may increasingly differentiate properties within the same destination.

A site with secure water, adequate electricity capacity, established road access and workable wastewater arrangements can present less development uncertainty than an apparently superior location dependent on substantial future infrastructure improvements. For Greece, this does not mean island development must stop. Infrastructure investment can itself create additional real estate capacity. Improvements to water systems, airports, roads, energy networks and waste treatment can allow destinations to accommodate economic growth more efficiently.

The strongest long-term property markets may therefore be those where tourism demand and infrastructure investment advance at broadly compatible speeds. Where infrastructure improves alongside tourism, developers can potentially create additional accommodation while maintaining the quality and environmental characteristics that make the destination attractive. Where property growth substantially outruns infrastructure, development can become more expensive, complicated and politically sensitive.

This creates a different risk map for investors. Larger destinations such as Crete and Rhodes have different infrastructure options from small Cycladic islands. Highly constrained markets such as Mykonos and Santorini may benefit from exceptional scarcity but simultaneously present greater challenges for new development. Rapidly growing islands such as Paros require infrastructure investment to accompany their expanding tourism and residential markets. There is therefore no single Greek island property story.

The investment case depends increasingly on the relationship between demand and physical capacity. Strong tourism can support income and property values, but it cannot by itself expand water supplies, electricity networks, roads or wastewater systems. For existing properties, secure infrastructure may become an increasingly important competitive advantage. For development sites, uncertainty surrounding essential services can add cost, delay and risk.

Greek island real estate has traditionally been valued through scarcity, location and tourism demand. Those factors remain fundamental. But as the country’s most successful destinations accommodate ever greater levels of activity, investors have another question to answer before deciding what a property is worth: not simply how many people want to be there, but how much additional growth the island can actually support.

Source: CIJ.World Research & Analysis Team

As AI Agents Multiply, Governance Is Becoming the Next Enterprise Technology Challenge

Companies are moving rapidly from experimenting with individual AI assistants towards deploying networks of specialised agents capable of accessing corporate systems, delegating tasks and taking actions without continuous human supervision. That transition could bring substantial productivity gains, but it is also creating a new enterprise governance problem: companies increasingly need to know not only what their AI is capable of doing, but exactly what each agent can access, which other agents it can communicate with and who remains responsible when something goes wrong.

Speaking at Ai4 2026 in Las Vegas, Angelik Laboy Torres, Senior Developer Advocate at Retool, argued that governing one AI agent is fundamentally different from controlling a network of them. One agent may have a clearly defined task, a limited group of tools and a relatively understandable set of permissions. Once companies begin deploying multiple agents capable of communicating and delegating work between themselves, they are no longer managing isolated software applications. They are managing an interconnected system.

The challenge is unlikely to come from a deliberate decision by companies to create poorly controlled AI environments. Agent networks can emerge gradually. A marketing department builds an agent for content, finance introduces another for expenses, operations deploys agents to automate internal workflows and developers create specialised systems for support or engineering. Individually, each project may appear manageable. Collectively, however, they can create a growing network of automated systems with different permissions, data access and responsibilities but no single view of how they interact.

The risk increases because multi-agent systems are often designed around specialisation. Rather than asking one general-purpose AI system to complete an entire process, companies can divide the work among several agents. One researches information, another checks it, another prepares a response and another approves or executes an action. An orchestrating agent determines which specialist should perform each task.

This can make AI systems more capable, but the number of relationships increases rapidly. Two agents have only one potential connection between them. Five agents can have ten. Ten agents can create 45 possible relationships before databases, software platforms, APIs and external services are even considered. The governance problem therefore grows faster than the number of agents themselves.

One of the most important risks is permission leakage between systems. An agent might legitimately receive access to a database because it requires specific information to complete a task. If that agent subsequently delegates part of its work to another agent, companies need to ensure that the second system does not automatically inherit access it was never authorised to have.

Traditional enterprise security already operates on the principle that users and applications should receive only the permissions necessary to perform their roles. Agentic AI makes enforcement more complicated because software systems can increasingly initiate actions and delegate work dynamically.

The stronger approach is to give each agent its own clearly defined identity and permissions. An investigative agent may be allowed to read operational metrics but prevented from modifying a customer database. Another agent may be permitted to communicate through collaboration software but prevented from reading engineering systems. The objective is to stop authority from travelling automatically with the task.

This becomes particularly important as AI begins accessing sensitive financial, customer or operational information. A system may need temporary access to specific data without receiving permanent permission to browse an entire corporate database.

The second major challenge is auditability. Conventional business applications usually create relatively predictable records. A user signs into a system, performs an action and leaves a transaction history behind. Agentic systems can be more complicated because one agent may consult several data sources before asking another agent to perform part of the work, which may then invoke further software tools.

When something goes wrong, reconstructing that sequence can become difficult. For regulated businesses in particular, being able to explain that an AI system produced a particular result is not enough. Companies may need to establish which information the system accessed, what action it proposed, which tools it used, whether another agent became involved and who ultimately authorised the decision.

A governed multi-agent system therefore needs centralised observability that records interactions, tool calls, inputs, outputs, approvals and actions. If this information is scattered through separate logs across several applications, the organisation may technically possess records but still struggle to reconstruct what happened.

The third governance problem involves escalation. Most companies agree that certain AI actions should continue to require human approval. The more difficult question is precisely where those boundaries should be drawn and how the approval mechanism works operationally.

An AI system recommending that someone review an invoice creates relatively limited risk. An agent authorised to approve a substantial payment creates a very different level of exposure. The same distinction applies to IT infrastructure. An agent can investigate why a service has failed and recommend rolling back a software deployment. Automatically executing that rollback could potentially create a much larger incident if the AI diagnosis is incorrect.

Torres demonstrated this through a multi-agent system designed around an overnight IT incident. Instead of an engineer manually opening monitoring, incident-management and collaboration tools, specialised agents can gather information, investigate the suspected cause and prepare a recommended response.

The critical point is that the system does not necessarily execute the highest-risk action automatically. It might identify a software deployment as the likely cause of a problem and recommend rolling it back, but a human engineer still provides final approval. This allows AI to perform much of the investigative work without removing human responsibility from decisions capable of causing significant damage.

The concept of human-in-the-loop AI is not new. The operational problem is that many organisations describe human oversight as a principle without designing a specific mechanism for it.

A functioning governance system needs to establish what causes an agent to stop, which person or team receives the escalation, what information they receive and what happens to the workflow while a decision is pending. Otherwise, the system risks moving in one of two undesirable directions. Either agents execute actions beyond the level of authority companies intended to grant them, or automated workflows repeatedly stop because the system cannot determine who should make the next decision.

This means companies may need to classify agent actions according to risk. Low-impact, reversible processes could be automated extensively. Higher-risk activities involving financial transactions, customer information, infrastructure changes or regulatory obligations would require progressively stronger approval mechanisms.

The broader issue is that enterprise AI governance cannot simply be added once a system has reached production. Permissions, auditability and escalation rules should be inherited by agents from a common governance framework rather than recreated separately for every new application.

This becomes increasingly important as businesses deploy dozens or potentially hundreds of agents. If each department builds its own security model, approval system and logging infrastructure, governance can become fragmented in exactly the same way that enterprise data and software systems became fragmented during earlier technology cycles.

A central governance layer provides one alternative. New agents can inherit existing authentication, role-based controls and data-access policies instead of developers rebuilding them for every project.

There is an important commercial consequence to this approach. Security departments are frequently portrayed as barriers to rapid AI deployment because they raise questions about data exposure, permissions and accountability. Properly designed governance could produce the opposite effect.

If security teams can understand exactly what an agent is permitted to do, review its historical activity and stop sensitive actions until a person approves them, organisations may be more comfortable allowing AI systems to operate closer to core business processes. Governance therefore becomes an enabler of adoption rather than simply another compliance requirement.

That is especially important as enterprise AI moves from producing content towards controlling workflows. The risk associated with a chatbot generating an inaccurate paragraph is relatively contained. The risk associated with an autonomous agent changing a database, approving a transaction, modifying production software or sending customer information outside the organisation is considerably greater.

The relevant question consequently changes from whether the model gives good answers to whether the entire system operates inside clearly defined boundaries. That requires companies to understand the identity of every agent, the information it can access, the software tools it can operate and the other agents with which it is permitted to communicate.

It also requires clear accountability. AI systems themselves cannot assume legal or corporate responsibility. Even when decisions are largely automated, responsibility ultimately remains with the organisation deploying the technology and the people who designed the controls around it.

This is likely to become increasingly important for boards, insurers and regulators as AI agents gain greater autonomy. Companies may eventually need an inventory of agents similar to the asset inventories they already maintain for software systems, employees and devices.

Each agent could have an identifiable owner, defined business purpose, approved data access, specified autonomy level and documented escalation path. The organisation would then be able to answer basic questions that may become increasingly important during audits or incidents: which agents were operating, what were they authorised to do, which systems did they access and which human remained accountable for their actions?

The practical governance test can therefore remain relatively straightforward. Businesses should be able to define the data boundaries for every agent, require human approval for sensitive actions, reconstruct agent activity when necessary, apply existing enterprise permissions rather than creating uncontrolled parallel security models and introduce those controls at the beginning of development rather than after deployment.

The technology itself will continue evolving rapidly, and the architecture of agentic systems is unlikely to remain static. But the governance principles are familiar.

Companies have spent decades controlling access to financial systems, databases, industrial infrastructure and confidential information. AI agents introduce a new type of software actor, but they do not eliminate the requirement for permissions, accountability, auditability and human responsibility.

The difference is scale. A company may understand the behaviour of one experimental agent reasonably well. Understanding dozens of agents interacting continuously across hundreds of systems is much harder.

That could make multi-agent governance one of the most important infrastructure questions in the next stage of enterprise AI. The companies that solve it may not necessarily be those deploying the most agents. They could instead be those capable of allowing increasingly autonomous systems to operate without losing visibility over what the machines are doing, what they can reach and who ultimately remains in control.

Source: CIJ.World Research & Analysis Team

AI’s Real Cost Is Moving Beyond Software Budgets and Into the Boardroom

Companies racing to deploy artificial intelligence may be underestimating the full financial cost of the technology. Beyond model subscriptions, computing capacity and software licences, expanding AI adoption is creating new expenditure around cybersecurity, data governance, monitoring, legal risk, intellectual property and operational controls. As AI becomes embedded deeper inside corporate workflows, these costs are increasingly becoming a board-level capital allocation issue rather than something that can be managed entirely within the technology department. That was the central argument presented at Ai4 2026 in Las Vegas by Sandeep Desai, Chief Information Security Officer at the Arizona Department of Education, and Joe Vatican, founder of Atomic Zero, who examined how organisations should translate emerging AI risks into financial exposure that chief executives, chief financial officers and boards can evaluate alongside more familiar investment risks.

The shift is being driven by the speed at which AI is entering companies. Employees are adopting public AI tools, developers are incorporating coding assistants into production workflows and organisations are experimenting with increasingly autonomous agents capable of retrieving information and performing actions across several systems. Each application can potentially increase productivity, but it also expands the number of places where company information can leave controlled environments or where automated actions can create unintended consequences. One of the clearest examples is shadow AI. Employees may use personal or unapproved generative-AI accounts to summarise documents, write code, analyse financial information or process customer data because the tools save time, but confidential information may consequently enter systems over which the company has little visibility.

IBM’s 2025 Cost of a Data Breach research illustrates why that behaviour has become financially relevant. The global average cost of a data breach was approximately $4.44 million, while organisations with significant shadow-AI exposure experienced materially higher breach costs. The lesson is not necessarily that companies should prevent employees from using AI. Attempting to become an organisation that simply says no could drive activity further underground. Instead, companies increasingly need approved alternatives that employees actually want to use, together with clear policies defining what information can be processed, which systems are permitted and what activities require additional controls.

This creates a category of expenditure that can easily be missed when organisations calculate AI budgets. Buying access to a model may be relatively inexpensive compared with the infrastructure required to deploy it securely across a large enterprise. Identity management, access controls, data-loss prevention, audit logs, monitoring, model testing and incident-response capabilities all add to the total cost of ownership. AI agents make the issue more complicated because they do not simply provide information. They may potentially retrieve customer records, update software, communicate with external systems, modify documents or initiate transactions. Every additional permission therefore expands the consequences of an incorrect instruction, compromised account or manipulated input.

The financial question changes as autonomy increases. A chatbot that produces an inaccurate answer creates one level of exposure, while an agent capable of acting across company systems creates another. Boards consequently need to understand not only how much AI their organisation is using but how much authority those systems have been given. This makes inventories increasingly important. Companies should be able to identify which AI systems are operating inside the organisation, which models they rely on, what information they access, who owns them and which actions they are permitted to perform. Without that visibility, it becomes difficult to calculate either their financial benefits or the risks attached to them.

Third-party software adds another layer. Many established cloud and business applications are adding AI functionality into existing products, meaning organisations may begin using AI indirectly without buying a dedicated AI platform. Companies therefore need to understand whether suppliers use customer information to improve models, where that information is processed and whether subcontractors or external model providers become part of the data chain. Vendor management consequently becomes part of AI governance. Traditional procurement reviews concentrating mainly on functionality, price and cybersecurity may no longer be sufficient. Businesses increasingly need to know what models sit underneath an application, how prompts and outputs are retained and whether sensitive information can be reused outside the intended service.

Intellectual property is another potentially significant area of exposure. Generative AI can help employees create code, images, marketing material and documents much faster, but companies need to understand where source material originates and what rights exist over resulting outputs. Litigation surrounding the training of commercial AI models has already demonstrated that copyright and data ownership remain unsettled areas of the AI economy. This does not mean every company using generative AI automatically inherits those liabilities, but boards should recognise that AI introduces legal questions extending beyond conventional technology procurement. Organisations producing valuable intellectual property also need controls preventing employees from inadvertently transferring proprietary information into external systems.

AI spending itself can also be difficult to predict. Conventional enterprise software is often purchased through relatively stable annual licences, whereas generative AI can introduce consumption-based pricing in which expenditure rises with the number of requests, the quantity of information processed and the sophistication of the models being used. Agentic systems can intensify this effect because a single employee request may trigger several automated model calls behind the scenes. One agent may retrieve information, another analyse it, another verify the result and another perform an action. What appears to the user as a single interaction can therefore involve considerably more computing activity.

As adoption scales across thousands of employees, relatively small unit costs can become meaningful operating expenses. Finance departments therefore need better visibility into AI consumption rather than treating model usage as an unlimited resource. One response is to avoid using the most capable model for every task. Routine activities may be handled by traditional software, deterministic rules or smaller models, while more sophisticated systems are reserved for problems requiring greater reasoning capability. This makes AI architecture partly an economic decision rather than a purely technical one.

The same principle applies to security investment. Not every AI application carries equal risk. A system helping employees draft internal meeting summaries does not necessarily require the same controls as one influencing financial transactions, customer decisions or critical infrastructure. Organisations therefore need to concentrate security spending around the systems capable of causing the greatest financial or operational damage. Desai and Vatican argued that AI risk should increasingly be expressed in financial terms. Rather than presenting boards with technical vulnerability scores, companies can estimate the likelihood of an event, the potential impact and the degree to which existing controls reduce that exposure.

The numbers cannot provide perfect predictions, but they can create a common language between cybersecurity teams and financial decision-makers. Companies can begin by identifying which AI-enabled processes affect the greatest amount of economic value. A customer-service assistant handling routine enquiries creates a different exposure profile from an autonomous system capable of changing prices, approving credit or modifying production environments. Management can then determine what additional controls would reduce those risks and compare the cost of those controls with the potential financial loss.

This approach also helps prevent over-regulation. Security departments can sometimes respond to emerging technology by placing restrictions around everything equally. If risk is assessed according to business impact, companies can instead apply stronger controls to high-value systems while allowing lower-risk experimentation to continue. The distinction matters because AI governance needs to enable innovation rather than simply restrict it. Employees who find approved corporate systems too cumbersome may return to consumer AI products, recreating the shadow-AI problem companies were trying to eliminate.

A balanced approach therefore requires both boundaries and accessibility. Organisations need policies defining which information may be processed, role-based permissions controlling access to sensitive systems and technical measures preventing high-risk activities. At the same time, employees need sanctioned AI tools capable of delivering enough value that they do not feel compelled to work around those controls. Existing governance weaknesses are also likely to become more visible as AI adoption expands. Companies with fragmented data estates, weak vendor oversight or inconsistent access controls already carry those vulnerabilities, and AI can amplify them because automated systems can access and process information much faster than individual employees.

In that sense, many of the hidden costs attributed to AI are not completely new. They are partly the cost of fixing longstanding weaknesses that were easier to tolerate when fewer systems could operate autonomously. The NIST AI Risk Management Framework provides one established structure for approaching the problem by encouraging organisations to govern, map, measure and manage AI risks throughout the technology lifecycle rather than treating security as something added after deployment. The urgency of that approach increases as AI systems gain more autonomy and organisations need to monitor what agents actually do rather than assuming they will remain within their original instructions.

For boards, the resulting question is therefore not simply how much money should be allocated to AI. It is how much of the organisation’s revenue, intellectual property, operational continuity and reputation will eventually depend on AI-enabled systems. That requires AI budgets to expand beyond licences and computing capacity. Companies may need to fund governance teams, model inventories, continuous monitoring, cybersecurity testing, identity controls, employee training, third-party assessments and incident-response capabilities alongside the applications themselves.

The organisations that understand those costs early may ultimately be able to deploy AI more aggressively rather than less. Strong controls can allow companies to give automated systems greater access and autonomy because management understands the boundaries and can monitor what happens inside them. The alternative is a cycle familiar from earlier technology transitions: rapid experimentation followed by an unexpected security, cost or compliance problem that causes management to halt programmes across the organisation.

AI adoption is therefore becoming a capital-risk decision. Boards need to understand which uses create genuine economic value, how much the organisation is spending to operate them and how much financial exposure accompanies that value. The companies that manage all three together, return, cost and risk, are likely to be in a stronger position than those that treat AI as simply another technology budget.

Source: CIJ.World Research & Analysis Team

Global Finance and Property Capital Converge Around 20 Leading Cities in 2026

The geography of global finance is increasingly influencing the geography of international real estate investment. During the first half of 2026, the world’s largest financial centres continued to concentrate institutional capital, corporate decision-making and high-value employment, while many of the same cities remained among the most important destinations for commercial property investment.

The Global Financial Centres Index published in March 2026 places New York and London at the head of the international financial system, followed by Hong Kong and Singapore. San Francisco completes the top five, followed by Shanghai, Dubai, Seoul, Shenzhen and Tokyo. The second half of the top 20 comprises Zurich, Los Angeles, Boston, Chicago, Frankfurt, Luxembourg, Washington DC, Geneva, Paris and Amsterdam.

The narrow gap between the four leading centres is particularly notable. New York remains first, but London, Hong Kong and Singapore are positioned immediately behind it. Rather than one financial capital dominating the international market, the ranking points towards a group of highly connected centres competing for investment, companies, talent and financial activity.

This concentration has direct consequences for real estate. Financial centres generate substantial demand for offices, hotels, residential accommodation, data centres and other urban infrastructure. They also contain many of the banks, investment managers, insurers, pension funds, private equity firms and family offices responsible for allocating property capital internationally.

That connection became more visible during the first six months of 2026. Cross-border commercial property investment accelerated significantly compared with the same period of 2025, demonstrating that international capital was becoming more active again even as financing costs, geopolitical uncertainty and differences between individual property sectors continued to affect investment decisions.

Singapore provides one of the clearest examples. The city ranks fourth among global financial centres but emerged as an exceptionally strong destination for international property capital during H1 2026. Approximately $8.7 billion of cross-border commercial real estate investment was directed into Singapore during the period, according to market data reported by Reuters. Its attraction extends beyond investment transactions. Singapore combines a major financial industry with limited land availability, multinational corporate demand and a relatively constrained prime office market. Vacancy among the highest-quality central business district offices remained low during the second quarter, helping support further rental growth.

Tokyo presents a different case. The Japanese capital reached tenth position among global financial centres in the March ranking but has become one of Asia-Pacific’s most sought-after destinations for international property investors. Large transaction opportunities, comparatively attractive financing conditions, corporate restructuring and the depth of the metropolitan economy have helped distinguish Tokyo from several higher-ranked financial centres.

London continues to demonstrate perhaps the strongest European connection between finance and property. Despite the adjustment experienced by UK commercial real estate following the rise in interest rates, London remains one of the world’s deepest markets for institutional property ownership. Its scale, liquidity and concentration of international financial institutions continue to attract capital from Europe, North America, Asia and the Middle East.

The continental European picture is more fragmented. Frankfurt, Luxembourg, Geneva, Paris and Amsterdam all feature among the world’s 20 leading financial centres, but their property markets serve different investor strategies. Frankfurt combines banking and European institutional functions with a major office market. Luxembourg’s financial importance is considerably larger than the physical scale of its property market, while Geneva’s private banking and international institutions support demand within a relatively small and supply-constrained city. Paris operates at a different scale, combining a major financial centre with one of Europe’s largest commercial property markets, although investment conditions have been affected by the repricing of offices and structural differences between prime central locations and more challenged peripheral submarkets. Amsterdam similarly combines financial services, technology and international corporate activity with tight development and planning constraints.

Dubai’s rise is particularly important for global real estate. Its seventh position among financial centres reflects the broader expansion of the UAE as a destination for international wealth, financial businesses and corporate headquarters. That growth has occurred alongside strong development and investment activity across offices, residential property, hospitality and logistics, strengthening Dubai’s role as a bridge between European, Asian and Middle Eastern capital.

Seoul has also moved further into the international financial and investment landscape. South Korea’s capital now sits inside the global financial top ten and has developed into an important institutional real estate market, particularly for offices and logistics. Along with Tokyo and Singapore, it illustrates the increasing depth of Asia-Pacific property markets available to international investors.

China contributes three centres to the global top ten through Hong Kong, Shanghai and Shenzhen. Their functions, however, differ considerably. Hong Kong remains an international gateway for finance and investment, Shanghai combines financial scale with one of mainland China’s largest commercial property markets, while Shenzhen’s strength is closely connected with technology, innovation and the wider Greater Bay Area economy.

The United States remains unusually dominant in the broader top 20. In addition to New York, the ranking includes San Francisco, Los Angeles, Boston, Chicago and Washington DC. Their real estate characteristics range from technology-driven office and data-centre demand in San Francisco to life sciences and education in Boston, entertainment and logistics in Los Angeles, institutional and corporate activity in Chicago, and government-related demand in Washington. New York nevertheless remains in a category of its own in terms of the combination of financial scale and property-market depth. Its office market has undergone substantial adjustment since the pandemic, but Manhattan remains one of the world’s most important destinations for institutional property capital, while demand has increasingly concentrated around modern, well-located buildings.

The 2026 picture also demonstrates why financial-centre rankings should not be treated as property investment rankings. Sydney, Madrid and Milan, for example, can be highly relevant to international real estate investors despite sitting outside the financial top 20. Conversely, a city can have considerable importance in global banking, asset management or private wealth without generating a commercial property market of comparable scale.

The distinction has become more important as investors become increasingly selective about buildings as well as cities. Across major office markets, capital and occupier demand are concentrating on newer, energy-efficient and well-connected assets, while older properties increasingly require refurbishment, conversion or significant repricing. Being located in a leading financial centre therefore no longer guarantees investment liquidity for every building.

At the same time, the expansion of private credit, alternative investment managers, sovereign capital and large family offices is widening the connection between financial hubs and property markets. Capital decisions made in New York, London, Singapore, Hong Kong, Dubai and other financial centres can ultimately determine development and transaction activity thousands of kilometres away.

The first half of 2026 consequently shows two overlapping maps of global capital. One identifies where financial institutions, investors and corporate headquarters are concentrated. The other shows where those institutions are prepared to deploy money into physical assets. The two maps increasingly intersect, but they are not identical.

For commercial real estate, that difference may be more important than the ranking itself. The cities positioned to capture international property capital are not simply those with the largest financial industries. They are those able to combine financial depth with investible assets, market transparency, economic growth, infrastructure, financing availability and sufficient transaction liquidity.

As international property investment recovers, the world’s leading financial centres will therefore remain important not only because of the real estate located within them, but because they serve as command centres from which a significant share of global property capital is raised, managed and deployed.

MitziLinka: Mannequin With Hips and a British Investigation Into Costa Rican Curves

There are moments when travelling when you encounter something so culturally significant, so anthropologically intriguing and so deserving of serious investigation that you have no option but to stop what you are doing and stare at a plastic bottom. This happened to me in San José, Costa Rica.

I was walking through a perfectly ordinary clothing shop when I noticed a mannequin. Normally, mannequins barely register with me. They stand around looking impossibly thin, unusually tall and irritatingly pleased with themselves despite having neither employment nor internal organs. European mannequins in particular often possess the physique of someone who has survived for several months on sparkling water and the occasional almond. This one was different. She had hips. Not apologetic hips. Not the sort of hips requiring you to turn sideways and examine the mannequin carefully to establish whether they actually existed. These were proper, structurally committed hips, accompanied by substantial thighs, a clearly defined waist and a backside that suggested the mannequin factory had finally discovered that the human body continues below the ribcage.

Naturally, being British, rather than simply accepting this and carrying on with my shopping, I began conducting an entirely unsolicited sociological investigation beside the trouser department. The obvious question was whether the mannequin reflected the women who actually shop there. Retailers, after all, are generally interested in selling clothes. Putting trousers on a plastic woman whose proportions bear absolutely no relationship to those of the customers seems a slightly questionable sales strategy. It would be rather like demonstrating a family hatchback using a Formula One driver and then wondering why everybody complains about getting into it.

There is some statistical background to the question. Research has found high levels of overweight and obesity among Costa Rica’s adult population, including women. But before anyone concludes that I have travelled thousands of kilometres to announce that Costa Rican women have large bottoms, science requires us to put the tape measure away. Weight and shape are not the same thing. A woman can have a narrow waist and pronounced hips without being overweight. Another can have relatively narrow hips while carrying more weight elsewhere. BMI tells you remarkably little about whether a pair of trousers is going to stage a rebellion somewhere between your waist and your thighs.

Human beings inconveniently refuse to come in one standard shape. This appears to have taken parts of the fashion industry several decades to discover. For years, the traditional fashion mannequin looked as though it had been designed by somebody who had heard women described over the telephone but had never actually encountered one. Legs became extraordinarily long, hips mysteriously disappeared and waists reached dimensions normally associated with champagne flutes. Then you would take the trousers off the mannequin, enter the changing room and discover an entirely different engineering problem. The trousers that had cascaded elegantly from the mannequin would encounter an actual human thigh and immediately reconsider their career.

That is why the San José mannequin was rather interesting. She wasn’t obviously being presented as a specialist plus-size model. She was simply standing there wearing ordinary clothes with the quiet confidence of a plastic woman who knew exactly where her hips were. And commercially, that makes considerable sense. If many of your customers have fuller hips and thighs, trousers should presumably be displayed on something vaguely resembling them. This isn’t revolutionary body politics. It is merchandising. Customers generally prefer knowing approximately what clothes might look like on a human being before surrendering their credit card.

There is also a cultural dimension. Across parts of Latin America, curvier female silhouettes have often been considerably more visible in mainstream popular culture and fashion than in the traditionally ultra-slim imagery associated with European high fashion. That does not mean there is a standard Latin American woman issued at birth somewhere near immigration control. Costa Rica itself contains enormous variation in ancestry, age, lifestyle and body type. Genetics plays a part in body shape. So do hormones, age, muscle, diet, physical activity and where an individual’s body decides to store fat — a decision the body makes independently and apparently without consulting its owner.

Modern lifestyles complicate things further. Costa Rica, like many countries, has experienced urbanisation, changing diets, more processed foods and increasingly sedentary lifestyles. These changes have contributed to rising rates of overweight and obesity. But again, none of this establishes that Costa Rican women are biologically programmed to possess magnificent hips. What we can establish with considerably greater confidence is that somebody responsible for supplying mannequins to this San José shop looked at the local market and said, effectively, “Give her some thighs.” And nobody panicked.

That is perhaps the most interesting part. Put the same trousers in certain European fashion boutiques and they might be displayed on a mannequin whose legs resemble two drinking straws descending from a coat hanger. In San José, here was a mannequin with an unmistakable waist-to-hip difference, calmly modelling everyday clothing without being labelled “curvy”, “real”, “inclusive” or any of the other marketing terminology normally deployed when the fashion industry discovers a body shape that has existed since the beginning of humanity. She was simply the mannequin. Perhaps that is progress.

Of course, one plastic woman in one San José shop cannot tell us what Costa Rican women look like. That would be terrible science, although admittedly excellent material for a newspaper headline. What she can tell us is what somebody believes customers will recognise. Mannequins are, after all, rather peculiar cultural objects. They don’t eat, age, exercise, become pregnant, develop middle-aged enthusiasm for wine or discover at 48 that carbohydrates have apparently changed the terms and conditions. Yet retailers continually redesign them to resemble the societies standing on the other side of the shop window.

Which means that while economists study consumption figures, sociologists conduct surveys and academics analyse demographic datasets, I may have discovered another indicator of social change: go shopping and inspect the bottoms. San José’s mannequin wasn’t proof that Costa Rican women have larger hips than European women. It was something subtler and arguably more interesting: evidence that at least part of the local fashion industry considers a fuller female silhouette ordinary enough that nobody needs to explain it.

And after decades of fashion mannequins apparently surviving exclusively on cigarettes, mineral water and disappointment, seeing one with a proper backside was strangely refreshing. I didn’t buy the trousers. But I did leave with considerably more respect for the mannequin.

Author: Mitzilinka (Turning grim reality into comic relief-without losing the truth)

Russian intervention brings major logistics and retail networks under external management

Russia has placed businesses connected with Nestlé, Auchan, FM Logistic and the former Leroy Merlin operation under temporary external management, extending state intervention into sizeable manufacturing, retail and logistics platforms. President Vladimir Putin signed the decree on 17 September, appointing Moscow-based L.E.V. Management to oversee the affected corporate interests. The measure transfers management authority but does not currently amount to a formal change of ownership.

The decision has a substantial commercial property dimension because the businesses operate extensive networks of factories, stores and distribution facilities. Nestlé has six production sites in Russia and around 7,000 employees, while Auchan operates around 230 stores across the country. Lemana Pro, the home-improvement retailer created from the former Leroy Merlin Russia operation, has 112 stores in 66 cities.

The largest directly identifiable logistics portfolio belongs to FM Logistic. The company operates 25 warehouse complexes covering approximately 865,000 sqm in Russia and handles around 830,000 transport operations annually, according to Kommersant. This gives the intervention a direct connection with industrial and logistics real estate, with the affected facilities forming part of distribution networks serving manufacturers and retailers across the Russian market.

Nestlé has maintained a reduced presence in Russia since the country’s full-scale invasion of Ukraine in 2022. It suspended new capital investment, advertising and much of its non-essential import and export activity while continuing production in selected food categories. Russia now represents an estimated 1% of the group’s worldwide sales. Following the latest intervention, Nestlé said it was examining its options and intended to protect its interests while maintaining continuity for employees and other stakeholders.

Auchan has remained one of the largest international retailers still operating in Russia. Reuters reported 229 stores and 24,236 employees at the end of 2025, while Russian sources currently give totals ranging from around 230 to 241 locations depending on the formats included. The business generated RUB 127bn in sales during the first half of 2026. Its Russian subsidiary said stores and other facilities continued operating normally following the decree while it sought clarification from the authorities.

The property exposure associated with Auchan has already changed considerably. Ceetrus, the real-estate business linked with the Auchan group, previously disposed of its Russian property assets, separating much of the group’s former shopping-centre ownership from the retail operation now affected by the decree. The latest intervention should therefore be viewed primarily as affecting Auchan’s operating business rather than the same property portfolio historically controlled by the wider group.

Lemana Pro also requires a distinction between its historical and current ownership structure. The business originated from Leroy Merlin’s Russian operation, which French parent Adeo transferred to local management in 2023. Vedomosti reports that almost all of its operating company, Le Monlid, is now held by UAE-registered Scenari Holding LP. The latest measure therefore affects a business with French origins but which is no longer simply a directly French-owned Russian subsidiary.

Temporary administration has become one of the mechanisms used by Russia to intervene in businesses with foreign ownership or connections. It allows an appointed administrator to exercise management powers while ownership formally remains with the existing shareholders. Similar arrangements have previously been applied to companies including Danone, Carlsberg and Fortum. Some businesses subsequently changed hands, while temporary administration has also been lifted in other cases, meaning the mechanism does not automatically result in a sale.

The Kremlin has linked the latest action partly to the companies’ connections with countries Russia considers unfriendly amid the continuing confrontation with Western governments over Ukraine. The specific reasons individual businesses were selected are less certain, however, and Moscow has not announced that the affected companies will be permanently transferred to new owners.

The intervention comes against an increasingly restrictive environment for international companies seeking to reduce or dispose of Russian investments. Foreign-controlled businesses can face government approval requirements, mandatory valuation discounts and additional payments when attempting to leave the market. Reuters reports that a 2025 estimate by Moscow law firm NSP put the value of private assets brought under Russian state control since 2022 at more than $50bn, including property belonging to foreign companies.

For commercial real estate, the significance extends beyond formal property ownership. The value of factories, warehouses and retail facilities is closely connected to the companies operating them, their supply chains and the ability of shareholders to determine investment and disposal strategies. An intervention at corporate level can consequently change effective economic control over substantial operating property even when the title to individual buildings has not been transferred.

The FM Logistic portfolio illustrates the scale of that exposure. Its approximately 865,000 sqm warehouse network alone represents a significant industrial property platform, while the wider group of affected businesses includes Nestlé manufacturing facilities and extensive Auchan and Lemana Pro retail networks. The decree therefore reaches considerably further into Russia’s physical economy than a conventional intervention involving corporate shareholdings alone.

For international investors retaining Russian exposure, the development adds another layer of uncertainty to asset valuation and exit strategies. Temporary administration should not be treated as completed confiscation, and the ultimate ownership of the affected businesses remains unresolved. Previous cases nevertheless demonstrate that effective management control can change well before the final ownership structure is determined, making the distinction between legal title and economic control increasingly important when assessing foreign corporate and real-estate exposure in Russia.

front page info
LATEST NEWS