Q2 2026: Polish residential rental market shows modest improvement, but sentiment remains divided

The Instytut Rynku Najmu (IRN) survey for the second quarter of 2026 indicates that Poland’s residential rental market continued to stabilise, although perceptions differed significantly between market experts and private landlords. Both groups reported generally positive overall sentiment, but landlords remained considerably more cautious in their assessment of current market conditions.

The overall market climate index rose to 17.27 points from the perspective of market experts, compared with 1.80 points among landlords. This represents a moderate improvement from the previous quarter, with landlords moving from negative to positive territory for the first time during the survey period. However, when assessing current market conditions specifically, experts remained optimistic, recording 14.55 points, while landlords reported a negative reading of -6.20 points, suggesting they continue to experience more challenging day-to-day operating conditions.

Looking ahead, both groups expect conditions to improve further. Experts recorded a forward-looking market index of 20.00 points, while landlords reported 9.80 points, indicating cautious optimism for the coming quarter.

Demand indicators also revealed differing views. Experts considered rental demand broadly stable, with a reading of -2.40 points, whereas landlords reported a much stronger increase in tenant demand at 13.20 points. According to the report, this may reflect landlords experiencing stronger demand directly, while experts assess the market within a broader economic context.

Income expectations improved for both groups. Experts recorded a current rental income indicator of 10.91 points, while landlords reported 11.00 points, suggesting continued support from stable demand and constrained housing supply. Future income expectations were also positive, at 18.18 points for experts and 17.20 points for landlords.

Financial conditions presented a more mixed picture. Experts reported worsening financial conditions for both landlords and tenants, with tenant finances falling to -14.55 points and landlords to -3.64 points. By contrast, landlords assessed their own current financial position positively at 21.80 points, highlighting a significant gap between market-wide assessments and individual experience. Experts also expressed greater concern about payment risks, while landlords generally reported stable payment performance.

Regulatory and cost-related challenges remain the principal barriers. Among experts, 77.8% identified weak legal protection for landlords as the biggest obstacle, followed by high maintenance costs (51.9%) and repair expenses (50.0%). Landlords ranked the same issues highest, although with lower intensity. Meanwhile, experts identified high rental costs (83.6%), upfront fees such as deposits and agency commissions (67.3%), the exclusion of some tenant groups (54.6%) and growing income uncertainty (47.3%) as the main challenges facing tenants. The proportion of experts citing unclear and unstable regulations doubled from 23% to more than 46% compared with the previous quarter.

Investment activity remained cautious. Most landlords indicated they intended to maintain their current level of investment, while planned activity focused primarily on minor refurbishments rather than portfolio expansion. Experts identified inflation protection, higher rental yields and stronger rental demand as the main factors likely to encourage future investment in rental housing.

According to the accompanying methodology, the survey follows an approach comparable to business sentiment surveys conducted by Statistics Poland (GUS) and Eurostat, using quarterly questionnaires completed by both market professionals and private landlords to measure current conditions and future expectations across the residential rental market.
Poland’s services production rises 6.6% year-on-year in April

Poland’s services production increased by 6.6% year-on-year in April 2026, according to preliminary data published by Statistics Poland (GUS). Compared with March 2026, however, services output declined by 1.8%, following seasonal patterns.

After seasonal adjustment, services production was 6.4% higher than in April 2025 and 1.3% lower than in March 2026. Compared with the monthly average recorded in 2021, the services production index was 30.1% higher.

Among the largest service sectors, information and communication recorded annual growth of 9.7%, while transportation and storage increased by 6.8%. Real estate activities rose 11.9%, whereas professional, scientific and technical activities increased by 6.0%. Accommodation and food service activities recorded annual growth of 5.5%, while administrative and support service activities edged down 0.4%.

At a more detailed industry level, the strongest annual growth was recorded in publishing activities (23.8%), followed by telecommunications (15.4%) and accommodation (15.3%). The largest declines were reported in public and licence programmes broadcasting (-15.3%), tour operator, reservation and related services (-9.8%) and employment activities (-5.6%).

Compared with March 2026, total services production fell 1.8%. Information and communication services declined 5.6%, while transportation and storage decreased 0.6%. The largest monthly increases were recorded in legal, accounting, bookkeeping and tax consultancy services (8.3%), publishing activities (8.0%) and accommodation (5.4%). The sharpest monthly declines occurred in motion picture, video and television programme production, sound recording and music publishing (-36.7%), computer programming and consultancy (-12.2%) and management consultancy activities (-8.8%).

The services production index covers enterprises employing 10 or more people across sectors including transport and storage, accommodation and food services, information and communication, real estate, professional and technical services, and administrative and support services. The indicator is compiled in line with EU statistical regulations and OECD methodology.

Poland records wider trade deficit as exports and imports continue to grow

Poland’s exports reached PLN 667.5 billion in the first five months of 2026, while imports totalled PLN 679.9 billion, resulting in a trade deficit of PLN 12.5 billion, according to Statistics Poland (GUS). Compared with the same period of 2025, exports increased by 3.5% and imports by 3.4%.

Measured in euros, exports amounted to €157.6 billion and imports to €160.6 billion, leaving a deficit of €2.9 billion, compared with €3.1 billion a year earlier. In US dollar terms, exports totalled $184.8 billion, while imports reached $188.3 billion, producing a deficit of $3.4 billion.

Developed economies remained Poland’s largest trading partners, accounting for 87.3% of exports and 66.1% of imports. The European Union represented 75.0% of exports and 53.2% of imports. Poland recorded a trade surplus of PLN 138.7 billion with EU member states, while trade with developing countries produced a deficit of PLN 168.5 billion.

Germany remained Poland’s largest export destination, receiving goods worth PLN 176.8 billion, equivalent to 26.5% of total exports. The Czech Republic, France, the United Kingdom and the Netherlands completed the top five export markets. Exports to the United States were the only decline among Poland’s major trading partners, falling 3.6% year-on-year.

On the import side, Germany remained the largest supplier with PLN 129.4 billion, representing 19.0% of imports by country of origin. China ranked second with PLN 105.8 billion and increased its share of total imports to 15.6%, followed by the United States, Italy and the Netherlands. Imports from France were the only decline among Poland’s principal suppliers, edging down 0.5%.

Trade with Brazil remained the largest among Mercosur countries. Poland recorded a trade deficit of PLN 4.2 billion with Brazil, as exports fell 11.1% while imports increased 13.4% compared with the first five months of 2025. Polish exports to Brazil were led by machinery and pharmaceutical products, while imports consisted mainly of vehicles and automotive parts, animal feed, ores, tobacco, recovered paper and coffee.

By product category, exports recorded the strongest growth in commodities and transactions not classified elsewhere in the SITC (36.9%) and mineral fuels, lubricants and related materials (15.5%). Imports increased most in commodities not classified elsewhere (22.7%), followed by mineral fuels (10.3%) and machinery and transport equipment (9.0%). Machinery and transport equipment remained the largest category in both exports and imports, accounting for 37.3% and 37.1% of their respective totals.

New Institute for the Rental Market launches in Poland to promote data and industry standards

A new independent research organisation focused on Poland’s residential rental sector has been launched with the aim of improving market transparency, developing industry standards and providing regular market data for landlords, tenants and property professionals.

The Instytut Rynku Najmu (IRN) has been established as an independent think tank dedicated to research, analysis and education relating to Poland’s residential rental market. The organisation says it intends to address what it describes as a lack of consistent market data, common standards and reliable analytical tools for the sector.

The launch coincides with the publication of IRN’s first quarterly rental market sentiment survey, which highlights differing perceptions of current market conditions between industry experts and residential landlords. According to the survey, 27% of market experts believe conditions in the rental market have improved, compared with 13% of landlords.

The survey also identified the main challenges facing the sector. Nearly 78% of industry experts cited inadequate protection for landlords as the market’s biggest obstacle, while more than 83% said tenants are primarily affected by high rental and housing costs. The proportion of experts identifying unclear and unstable regulations as a major barrier doubled over the previous quarter, rising from 23% to more than 46%.

According to Arkadiusz Derkacz, co-founder and chief economist of IRN, the Polish rental market requires more reliable data and consistent standards to support evidence-based policymaking and market development. He said the institute was created to provide research, methodology and market indicators rather than opinion-based assessments.

IRN’s flagship project is a quarterly survey of Poland’s residential rental market based on a methodology modelled on business sentiment surveys conducted by Statistics Poland (GUS). The survey combines the perspectives of market professionals and private landlords to monitor current conditions and expectations for the coming quarter. Alongside the survey, the institute plans to publish market reports, regulatory analysis, forecasts and guidance on rental agreements and industry best practices.

The institute’s first survey for the second quarter of 2026 found a generally positive but moderate market outlook. The overall rental market sentiment indicator reached 17.27 points among experts and 1.80 points among landlords, suggesting improving conditions, although landlords remained considerably more cautious. Experts reported a continued improvement in overall market conditions, while landlords assessed current conditions less positively despite stronger expectations for rental demand and income.

The research also points to growing concerns about tenants’ financial position. The proportion of experts reporting a deterioration in tenants’ financial situation increased from 17% to almost 35% over the quarter, while more than 47% identified uncertainty over household incomes and living costs as an increasing challenge. Initial rental costs, including deposits and agency fees, were cited by more than 67% of respondents as a significant barrier for tenants.

IRN said it plans to publish further research on rental market regulation later this year, together with policy recommendations based on its survey findings. The institute’s founder is simpl.rent, a technology platform specialising in residential rental services.

Tax risks from reclassification of intra-group loans in Romania

Companies with cross-border intra-group financing arrangements should reassess their tax positions as Romanian tax authorities continue to scrutinise whether such loans reflect arm’s-length conditions, according to a new Deloitte Romania tax alert.

The alert focuses on situations where part of a loan granted by a non-resident affiliated company may be reclassified as an equity contribution for tax purposes. Such a reclassification can affect both the deductibility of interest expenses and the withholding tax (WHT) treatment of payments made to the foreign lender, potentially creating uncertainty and increasing the risk of additional tax liabilities.

According to Deloitte, tax authorities are increasingly assessing intra-group financing through transfer pricing and economic substance tests, using indicators such as leverage, debt capacity, interest-to-EBITDA and loan-to-asset ratios. If part of a financing arrangement is treated as equity rather than debt, differences may arise between the corporate income tax treatment of interest and the applicable withholding tax rules. The absence of explicit clarification in Romania’s Fiscal Code could also lead to inconsistent tax treatment, disputes over double tax treaty benefits and potential double taxation.

To reduce these risks, Deloitte recommends that companies review both existing and historical intra-group loans, assess the supporting transfer pricing documentation and verify the tax treatment applied to interest paid or capitalised in favour of non-resident affiliated entities. Companies should also evaluate how interest relating to any reclassified portion of financing would be treated for tax purposes and prepare a documented technical position before a tax audit or, where necessary, during administrative appeals or litigation.

The advisory notes that businesses already subject to tax audits or disputes involving interest deductibility, transfer pricing or withholding tax should carry out a dedicated analysis to support their position. Deloitte says this can help reduce the risk of significant tax adjustments, eliminate cases of double taxation arising from reclassification and improve the consistency of tax treatment across jurisdictions.

Source: Deloitte

Poland’s annual inflation slows to 2.5% in June

Poland’s annual consumer price inflation eased to 2.5% in June 2026, down from 3.1% in May and in line with the preliminary estimate published earlier this month, according to Statistics Poland (GUS). The reading places inflation at the National Bank of Poland’s target of 2.5% ±1 percentage point.

Compared with June 2025, prices for services increased by 5.4%, while goods were 1.3% more expensive. On a monthly basis, the consumer price index fell 0.5%, reflecting a 0.9% decline in goods prices, while services prices rose 0.6%. Statistics Poland also noted that, from 2026, the consumer price index is being calculated using the updated COICOP 2018 international classification.

The largest upward pressure on annual inflation came from housing, water, electricity, gas and other fuels, where prices increased 4.9%, followed by recreation, sport and culture (5.2%), alcoholic beverages and tobacco (6.5%), health (5.0%), restaurants and accommodation services (4.5%) and information and communication (4.0%). By contrast, prices declined for clothing and footwear (-3.1%), food and non-alcoholic beverages (-0.2%) and household furnishings and maintenance (-1.1%), helping to moderate overall inflation.

On a month-on-month basis, the decline in consumer prices was driven primarily by transport, where prices fell 4.4%, followed by food and non-alcoholic beverages (-0.7%) and clothing and footwear (-1.7%). These decreases were partly offset by higher prices for recreation, sport and culture (1.5%), restaurants and accommodation services (0.5%) and alcoholic beverages and tobacco (0.6%).

According to the weighting system used in the consumer price index, food and non-alcoholic beverages remained the largest expenditure category in household consumption, accounting for 25.9% of the basket, followed by housing, water, electricity, gas and other fuels at 20.4% and transport at 10.2%.

Garbe Industrial fully leases new logistics property in Leipheim before completion

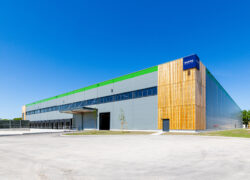
Garbe Industrial has fully leased a newly developed commercial property in Leipheim, Bavaria, shortly before its completion. The approximately 11,900 sq m facility has been leased to a technology group and forms part of a joint venture between Garbe Industrial and Logicenters, the logistics platform owned by Urban Partners.

The lease covers around 11,200 sq m of warehouse space together with nearly 700 sq m of office and social areas. The property includes ten loading bays, a ground-level loading door, parking for 40 cars and two trucks, and has been developed in line with current ESG standards with the aim of achieving DGNB Gold certification.

Mehmed Muhić, Regional Head South/Development at Garbe Industrial, said securing a tenant before completion demonstrates continued demand for well-located, high-quality logistics properties despite the broader economic environment. He also highlighted the role of local authorities, noting that the building permit was issued in less than three months, providing greater planning certainty and enabling faster project delivery.

Wolfgang Ködel, Managing Director and Head of Real Estate Germany at Urban Partners, said the project reflects Logicenters’ strategy of developing modern logistics facilities in strategically located markets. He added that pre-leasing the property confirms the continued demand for functional, specification-driven logistics space.

The development was built on a brownfield site that previously formed part of a military airbase. Following the conversion of the former airfield into the 112-hectare Areal Pro industrial estate, Garbe Industrial and Logicenters acquired the approximately 20,000 sq m site in autumn 2024. Existing structures, including a 30-metre chimney, were demolished before construction began in the second quarter of 2025. The partners invested around €17 million in the project.

Leipheim is located around 30 kilometres northeast of Ulm, with direct access to the A8 motorway, linking the site to Stuttgart, Augsburg and Munich. The nearby A7 motorway provides connections along one of Germany’s principal north-south transport corridors.

The leasing transaction was brokered by BNP Paribas Real Estate.

Stuttgart logistics market rebounds in H1 2026 as large leases return

Stuttgart’s logistics and industrial property market recorded 129,500 sq m of take-up in the first half of 2026, according to REALOGIS Unternehmensgruppe, marking a clear recovery from the subdued activity of recent years. Warehouse space accounted for 118,100 sq m, or 91% of the total, up 191% year-on-year and 36% above the five-year average. Office space contributed 10,600 sq m, while mezzanine space totalled 800 sq m.

The market was driven by the return of larger transactions. Two leases completed by manufacturing companies totalled 45,460 sq m, representing 35% of total take-up. The largest transaction involved an automotive company leasing 31,720 sq m of existing space in the Ludwigsburg district, while another manufacturing occupier leased 13,740 sq m in the Rems-Murr district.

Joel Adam, Managing Director of Realogis Immobilien Stuttgart GmbH, expects the market to continue stabilising during the second half of the year. He said occupier demand remains selective but is being supported by a broader mix of manufacturing and technology-focused businesses, underpinned by the region’s industrial base, innovation capacity and strong network of small and medium-sized enterprises.

Rental growth continued at the top end of the market. Prime rent increased to a record €8.70 per sq m, up 2% compared with both the first half and the end of 2025 and 5% above the five-year average. Average rent remained stable at €7.00 per sq m, also 5% higher than the long-term average.

Leasing activity remained concentrated in existing buildings, which accounted for 127,000 sq m, or 98% of total take-up. Brownfield developments contributed 2,500 sq m, while no transactions were recorded in greenfield projects. The market was entirely tenant-driven during the first six months of the year, with no owner-occupier acquisitions.

Ludwigsburg was the most active submarket with 48,600 sq m of take-up, followed by Rems-Murr with 24,300 sq m, Esslingen with 22,500 sq m and Böblingen with 21,100 sq m. The City of Stuttgart recorded 7,700 sq m, while Göppingen accounted for 5,300 sq m.

Manufacturing remained the dominant source of demand, accounting for 77,600 sq m, or 60% of total take-up. The Supply/Other category followed with 26,100 sq m (20%), ahead of Logistics/Distribution with 21,900 sq m (17%). Retail and wholesale occupiers represented 3,900 sq m, with traditional retailers accounting for the majority of that volume.

The return of larger occupiers was reflected in the size distribution of transactions. Units exceeding 10,000 sq m accounted for 45,460 sq m, or 35% of total take-up, after no transactions in this size category were recorded during the previous two reporting periods. Units between 3,001 sq m and 5,000 sq m represented 22% of activity, followed by units of 1,000 sq m to 3,000 sq m with 20% and 5,001 sq m to 10,000 sq m with 17%. Units below 1,000 sq m accounted for the remaining 6%.

With warehouse demand recovering, larger occupiers returning to the market and rents remaining resilient, Stuttgart entered the second half of 2026 on a firmer footing than in the previous two years.

Economist proposes new approach to limiting systemic corporate concentration

Link Developments launches mixed-use City Walk Abuja project

Link Developments has announced the launch of City Walk Abuja, a privately funded mixed-use development planned within a government-designated Free Trade Zone in Abuja, Nigeria.

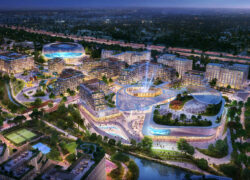
The project will be located on the corridor connecting Abuja’s Central Business District with Nnamdi Azikiwe International Airport. According to the developer, the scheme is intended to combine commercial, residential, hospitality, leisure, cultural and civic uses within a single master-planned development.

Covering more than 200 hectares, City Walk Abuja is planned as a mixed-use district designed to support business activity, residential development and public spaces. Link Developments said the Free Trade Zone location is intended to attract domestic and international investment by offering businesses a base for operations in West Africa.

The masterplan includes proposals for a 450-metre tower, which the developer says would become Africa’s tallest building if completed, as well as a multi-purpose arena with a planned capacity of more than 16,000 seats. The development will also incorporate landscaped public areas, biodiversity corridors, water management systems and pedestrian-friendly streets.

The masterplan was designed by architecture and masterplanning firm Benoy, which has worked on mixed-use developments internationally. According to the company, the design places emphasis on sustainability, public spaces and climate-responsive planning.

Link Developments has appointed Broadgate Developments Group Ltd as development and construction management adviser for the project. Broadgate will provide development management, technical governance and programme oversight throughout the project’s delivery.

Broadgate’s management team has previously been involved in projects including Jabi Lake Mall and Heritage Place in Nigeria, One Airport Square in Ghana and the Douala Airport Business Park in Cameroon.

Peter Young, Chief Executive Officer of Broadgate Developments Group Ltd, said the company will work with Link Developments, Benoy and the wider project team on the delivery of the scheme.

Alex Arkaah, Chief Development Officer and Group Technical Director of Broadgate Developments Group Ltd, said the project provides an opportunity to combine international design, engineering and development expertise in a long-term urban development.

According to Link Developments, City Walk Abuja is intended to support investment, economic diversification and urban development as Abuja continues to expand. The project timeline and construction schedule have not yet been announced.

front page info
LATEST NEWS