Colliers survey: Dedicated workspace and routine key to boosting office attendance

Companies are ramping up efforts to encourage employees to return to the office by implementing hybrid work models and rethinking workspace configurations to better meet today’s workforce needs. According to a July survey conducted by Colliers, which included over 500 respondents, employees with a dedicated workspace and structured routine are more inclined to work from the office regularly. Among the main factors influencing return rates are stability, commute convenience, managerial expectations for in-person presence, and access to designated spaces that cater to diverse work tasks. These aspects, Colliers consultants note, not only support productivity but also foster essential face-to-face interactions and collaboration.

Romania has seen a notable rise in office attendance over the last 18 months, with approximately 55% of employees returning to office spaces in the first half of this year compared to 40% in early 2023. Colliers, Romania’s largest office property management firm, managing nearly 600,000 square meters of office space, attributes this upward trend to increased structure and stability within the workplace.

The survey shows that the number of days employees spend in the office largely depends on the level of autonomy they have in scheduling. Those with a company-set schedule average 3.6 days per week in the office, while those with more flexible, self-determined schedules attend about two days per week. Colliers data indicates that 65% of employees follow a structured schedule, with 46% adhering to company-set hours and 19% following team-agreed schedules, while only one-third have complete autonomy in their work hours.

Many companies have shifted to open-plan workspaces to ensure employees have a spot when they come in. However, the survey finds that employees with assigned workstations are more consistent, working an average of 3.3 days weekly at the office, compared to an average of 1.7 days among those without designated spots. Employees who come into the office at least three days a week often have access to personal workstations, whereas those attending one to two days generally use shared spaces.

“Factors like a consistent schedule, an allocated workspace, and clear expectations from managers positively impact employees’ willingness to come to the office,” explains Daniela Popescu, Director of Tenant Services & Workplace Advisory at Colliers. “While flexibility and autonomy appeal to many, a dedicated workspace fosters stability and ownership, which in turn promotes in-person collaboration. We see that tailored spaces supporting specific work tasks and needs can also be a strong motivator.”

The Colliers survey also finds that office attendance preferences vary across generations, with Millennials and Gen X employees—accustomed to pre-pandemic office culture—attending more frequently, while Gen Z employees, many of whom started their careers remotely, often prefer flexible, hybrid setups.

Company perks play a role in office attendance, with free coffee topping the list, available to 60% of respondents. Free parking and flexible hours are also common. Larger companies, particularly those with over 250 employees, typically offer the most comprehensive benefit packages. Social events, team-building activities, and professional development opportunities are also among the top offerings aimed at enhancing employee engagement.

Commute time remains a notable barrier to full office returns. The survey shows that employees’ one-way commute averages 30 minutes, with public transportation taking roughly 40 minutes and private car commutes about 10 minutes less. In Bucharest, 47% of employees drive to work, with similar numbers relying on public transport. For commutes under 40 minutes, cars are the preferred option, while public transit takes precedence for longer distances.

With hybrid work expected to remain prevalent, the Colliers survey underscores the balance between flexibility and routine in optimizing office attendance. Stability, structured spaces, and supportive benefits appear crucial as companies look to re-engage employees in a post-pandemic workplace.

Source: Colliers
Photo: Daniela Popescu, Director of Tenant Services & Workplace Advisory, Colliers

Growing investment opportunities in Poland’s senior housing and healthcare sector

As Poland faces significant demographic shifts, the market for senior housing and private long-term care services is gaining momentum, drawing keen interest from investors. At the recent “Senior Living & Care Market in Poland” event, hosted by CMS Poland, Savills, and the Senior Housing & Healthcare Association (SHHA), industry experts highlighted the sector’s rising investment potential and the systemic challenges it presents.

Anna Wisniewska, attorney at CMS’s Real Estate and Construction practice, stressed that Poland’s aging population makes senior care a growing necessity. “Demographic and economic changes make it clear that senior care demand will increase significantly,” she stated, noting the importance of investment in both independent and assisted living facilities.

With Poland’s senior population projected to rise to nearly 30% by 2045, demand for elder care is set to surge. Jacek Kalużny, Operational Capital Markets Director at Savills Poland, pointed out that the market for senior facilities remains underdeveloped, with less than 2% availability for those over 80. This nascent sector has tremendous potential for expansion, yet faces challenges including a lack of investment-ready portfolios and qualified operators.

Experts at the event noted that, although the senior care sector in Poland is fragmented, the need for large-scale investments is high. Dr. Andrzej Lejczak, President of the National Chamber of Nursing Homes, pointed to the infrastructure gap, noting that “Poland has immense potential in healthcare real estate, but care facilities are not developing at a matching pace.” In 2023 alone, Poland saw 50 new private care facilities, with additional homes planned to meet growing demand.

Investment interest is also rising for facilities that cater to active senior lifestyles, including projects that offer social, recreational, and medical services. ORIGIN Investments, for instance, provides serviced apartments with comprehensive amenities, as demand grows for residences that support seniors’ active and engaged living.

Challenges remain, notably around operational management, workforce shortages, and regulatory hurdles. “Operational partners are essential for the sector’s growth,” noted Maciej Piotrowicz, head of Nrep’s Polish branch. Meanwhile, Griffin Capital Partners’ Piotr Fijołek stressed the competitive real estate environment, which forces investors to weigh senior care projects against more profitable alternatives.

Looking ahead, experts agree that Poland’s senior care market holds promise, especially if supported by favorable policies and a focus on sustainable, long-term investment models. Beata Leszczynska of emeis Poland concluded, “With proper regulation and tax incentives, Poland could see a boom in this essential sector, benefiting both investors and the growing senior population.”

As Poland’s demographic needs evolve, the senior care sector is poised to play a pivotal role in both the real estate landscape and social infrastructure, offering lucrative opportunities for forward-thinking investors.

Českomoravská Nemovitostní appoints Iveta Valentová as Head of Property Management

Investment group Českomoravská Nemovitostní (ČMN) has strengthened its Property Management team with the appointment of Iveta Valentová as the new Head of Property. With over a decade of experience, Valentová brings a wealth of expertise from her 11 years at CBRE, where she managed a portfolio spanning 700,000 square meters, encompassing office, industrial, logistics, and retail properties.

During her tenure at CBRE, Valentová collaborated with major investment funds, including Raiffeisen, Cromwell, Reico, Immofinance, and Verdion. Her background has equipped her with a comprehensive perspective on property management and sharpened her management and communication skills. Valentová further honed her expertise through an MBA in Real Estate and Valuation from the University of Economics in Prague.

“We are delighted to welcome Iveta to our team,” stated Radek Stacha, Chairman of the Board at ČMN. “Her leadership will be instrumental in driving the growth and success of our Property department.”

Commenting on her new role, Valentová expressed enthusiasm for the opportunity. “After 11 inspiring years at CBRE, I am excited to take on this new challenge at ČMN. The company’s dynamic growth and vision are impressive, and I look forward to working with the team to build a high-quality Property Management business that will enhance the value of our assets under management.”

Valentová’s appointment marks a strategic step for ČMN as it continues to strengthen its presence in the Czech real estate market.

CBRE study reveals retail sector optimism as physical stores thrive in Europe

A new survey from CBRE highlights a resurgence in physical retail as major brands accelerate expansion plans across Europe. The findings from the 2024 European Retail Occupier Survey reveal that nearly three-quarters of participating retailers are poised to increase their portfolio of brick-and-mortar stores, a significant jump from previous years.

According to the study, which gathered insights from over 60 global retailers operating more than 130,000 locations, 71% of respondents are looking to expand their physical store presence in markets where they are already established. This growing emphasis on physical retail is underscored by a notable increase in the desire for larger store formats, with 72% of retailers expressing intentions to enlarge their space—a sharp rise from just 26% in 2022.

The trend towards larger retail spaces is particularly pronounced among fashion and athleisure brands in major urban areas. Interestingly, while luxury retailers are increasingly opting for store ownership over leasing, the mass market remains focused on leasing strategies, with 84% of retailers indicating no plans to purchase properties.

Chris Gardner, Head of European Retail at CBRE, commented on the findings, stating, “Improved consumer confidence is starting to translate into higher spending, giving retailers the confidence to commit to stores in both familiar and new markets. Brand loyalty is often enhanced through in-store experiences, which is driving significant investments in physical retail to showcase brand identities.”

Retail Parks are emerging as the preferred choice for future store locations, with 45% of respondents favoring these formats. The appeal of Retail Parks is bolstered by high foot traffic from local residents, ample free parking, and a concentration of similar retailers, all of which contribute to enhanced store performance.

From a technological standpoint, retailers are currently in an exploratory phase regarding Artificial Intelligence (AI). While 61% of survey participants are investigating AI applications, only 25% have successfully implemented such solutions thus far.

Environmental, Social, and Governance (ESG) considerations are also gaining traction, with 60% of retailers expecting “green” building features to become advantageous in leasing negotiations over the next three years. This marks a 45% increase since 2022, signaling a shift towards more environmentally conscious contracts.

The study underscores the pivotal role of physical stores, with 97% of respondents acknowledging their importance in retail strategy. Retailers agree that brick-and-mortar locations significantly outperform online platforms in terms of consumer engagement, cross-selling opportunities, and overall sales effectiveness.

Carmen Ravon, Head of Retail Occupiers CEE at CBRE, concluded, “The significant desire for larger stores and the appetite for expansion across both new and existing markets bode well for the retail landscape in 2025. The faster retailers can implement AI solutions, the more they will enhance both store profitability and the shopping experience. I extend my gratitude to the retailers in CEE and EMEA who participated in our study; their insights are invaluable as we look towards the future.”

PwC: Ostrava, Prague, and Brno lead Central and Eastern Europe in smart urban transport

Czech cities are making headlines for their top-notch urban transport systems, with Ostrava, Prague, and Brno ranking among the best in Central and Eastern Europe, according to a recent PwC study. Analyzing 25 cities from Central Europe to Almaty, Kazakhstan, PwC ranked Ostrava first, Prague second, and Brno fourth, noting their achievements in traffic management, environmental sustainability, public transport quality, and active mobility.

Ostrava claimed the top spot with robust public transport and exemplary traffic management, while Prague excelled in active mobility initiatives, particularly in creating pedestrian and cycling infrastructure. Brno’s C-ROADS project, which shares real-time traffic data, also stood out, helping it secure fourth place. Tallinn, Estonia, ranked third, breaking the Czech streak at the top of the list.

In the report, PwC highlighted Prague’s efforts to expand electric vehicle charging infrastructure, Ostrava’s “cleanOVA” app for reporting city maintenance issues, and Brno’s C-ROADS system as notable advancements in urban mobility. The study attributes the high public transport usage in Czech cities to affordability, with fares in the Czech Republic being the lowest in the region relative to average wages. Public transport is particularly popular in Ostrava, where it accounts for 69% of all journeys, well above the regional average of 49%.

PwC’s study also delved into air quality and sustainable transit. Prague was listed among the five cleanest cities in terms of dust pollution, whereas Ostrava faced challenges, ranking as the fourth most polluted city in this regard.

Central and Eastern Europe is making strides in promoting active mobility, with cycling rates above the European average, though still lagging behind cities in Germany. Walking to work remains a popular choice, particularly in Kiev, Bucharest, Budapest, and Košice.

With three Czech cities among the top four, the study underscores the Czech Republic’s leadership in urban transport innovation, setting a benchmark for the region.

Source: PwC and CTK

Poland: Negative symptoms in the labor market are intensifying

The Labor Market Index (Wskaźnik Rynku Pracy-WRP), which provides advance information on future changes in the size of unemployment, rose by 0.3 points in October. Excluding the slight correction recorded in June this year, the value of the index has been rising since the beginning of this year, albeit at different rates. It has increased by 4 points since December 2023. Nonetheless, there is no change in the registered unemployment rate, while the BAEL unemployment rate reached a record low of 2.7% at the end of June 2024. However, negative phenomena have been noticeable in the labor market over the past year, such as the low supply of new jobs, low employment opportunities for the unemployed and the significant depreciation of their qualifications, as well as the growing phenomenon of layoffs for reasons attributable to workplaces.

Despite these negative phenomena, it is difficult to expect an increase in the unemployment rate, mainly due to demographic reasons and a shrinking labor pool.

Currently, as was the case a month ago, only two components of the index are acting in the direction of decreasing its value, and thus foreshadowing a decline in the registered unemployment rate. In contrast, five components predict an increase in the value of the index and thus a worsening of the market situation.

In the direction of a decrease in the value of the index, the most influential are changes in the values of variables depicting the basic streams in the labor market: the number of people registering as unemployed and de-registration from the labor office due to taking up employment. In the first case, there was a nearly 8% decline on a monthly basis. In the second case, there was a nearly 8% increase in September compared to August. Interestingly, the increase in the outflow from unemployment to employment occurred despite a downward revision in the number of newly published job offers at labor offices (by about 3%). There are consistently more job offers published than unemployed people who deregister from the office due to taking up employment. In turn, a lower inflow into unemployment should translate into a lower unemployment rate, but if we take into account the relatively low level of employability of unemployed people registered at labor offices on average, the likelihood of matching job offers is relatively low.

More disturbing information comes from a comparison of data on the number of people registered as having been laid off for company reasons. This is a value that is a signal indication of the difficulties of business operations. Although the changes are even creeping, and the total number of such registered unemployed is small (just over 30,000 people), it increased by more than 11% from April to September.

Similarly negative signals are coming from data on the amount of unemployment benefits paid out. Initially, the increases were small and coincided with the valorization of the benefit amount, but they continue to take on a fairly high level. In September, compared to August, a total of 4% more benefits were paid (the total amount of benefits paid), and since April this increase has been more than 25%.

A rather cautious outlook for employment is consistently indicated by the results of the GUS’s economic survey. The negative balance of responses to the question about changes in the number of employees still prevails. Managers of industrial enterprises are more likely to announce plans to reduce the number of employees than new hires. The overall financial assessment of industrial enterprises remains unchanged, negative.

Source: BIEC

Cavatina: Cavare sold the project at Ostrobramska for approx. PLN 59 million for LifeSpot

Cavare from the Cavatina group has signed an agreement to sell the project being created at ul. Ostrobramska in Warsaw with LifeSpot, a long-term rental apartment platform in Poland belonging to a fund managed by Griffin Capital Partners, Cavatina said. The transaction is almost PLN 59 million, and the investment, which is under construction, in the third quarter of 2025 will provide 143 apartments for rent.

“The Ostrobram project will complement LifeSpot’s portfolio with more than 140 apartments with a total net leasable area of 4600 m2. The forward funding transaction consisted of a real estate sale agreement and a DMA (development management agreement) contract for the implementation of a PRS building on the sold plot.

Cavare is a company owned by Cavatina Group. In the coming years, it plans to build and make available for long-term rental of 2,700 apartments in the largest cities in Poland – in the first place, its projects will be built in Warsaw, Wrocław, Gdańsk and Krakow. It wants to act both as an operator of the construction projects and to implement them for the needs of other entities

“The PRS sector in Poland is accelerating, professionalizing the market still dominated by rent from private individuals. The Ostrobramska transaction is the beginning of a good collaboration between Cavare and LifeSpot. We have plans for more joint ventures. The general contractor of the investment is a company from our group, and the project is already in implementation,” said Bartłomiej Wentlandt, Managing Director of Cavare Bartłomiej Wentlandt.

As part of the investment, apartments of different sizes will be made available, with the advantage of studio and 2-room premises, was emphasized.

“We are constantly looking for new investment opportunities to enrich our portfolio. We pay special attention to Warsaw, which is responsible for over 40% of the entire Polish PRS market. The Ostrobramska project fits perfectly into our development strategy, offering an attractive location, the right area and high quality. We systematically increase our presence not only in the capital city, but also in other cities, because our strategic goal is to achieve 6,000 units offered in the next 3 years,” added the senior partner at Griffin Capital Partners Marek Obuchowicz.

LifeSpot is a long-term rental housing platform in Poland owned by funds managed by Ares Management and Griffin Capital Partners.

The Cavatina Holding Capital Group is one of the largest office space developers operating in Poland. It debuted on the main market of the WSE in 2021.

ManpowerGroup Survey: 65% of Polish workers favor 4-day workweek

A recent report from ManpowerGroup reveals that 65% of Polish respondents support the implementation of a four-day workweek. Of those surveyed, 36% expressed strong support for the initiative, while 29% showed moderate support. Conversely, 6% held a negative view of the proposal.

The report highlights that employees in Poland value a positive workplace atmosphere (46%) and a job scope that aligns with their interests (41%). However, despite a desire for greater flexibility, 60% of respondents currently work fully from the office. The survey, titled “The Moods of the Polish Labour Market – The Perspective of Candidates 2024,” indicates a favorable perception of the four-day workweek among Poles, though some concerns remain.

Respondents believe that a shorter workweek could enhance overall wellbeing and help maintain a better work-life balance. However, fears of reduced wages, challenges in time management, and increased workloads linger.

Justyna Mazur, a permanent recruitment manager at Experis, noted that companies across various sectors have demonstrated that a four-day workweek does not necessarily lead to decreased productivity. In some instances, organizations have even reported improvements in efficiency and team satisfaction. “Employees tend to be more focused and motivated, which can lead to maintained or improved business performance,” she explained.

Mazur cautioned that certain sectors, such as customer service and production, may face operational challenges due to reduced employee availability, potentially resulting in customer dissatisfaction.

The survey also found that 68% of employees do not plan to change employers in the near future. While 15% intend to seek new opportunities within the next year, 10% plan to do so within six months. Notably, 7% of respondents are actively pursuing a career change within the next three months.

“Overall, 70% of respondents are not considering job changes, a significant shift from the 59% who expressed willingness to switch jobs last year. This trend could lead to increased challenges in attracting suitable candidates during recruitment,” stated Katarzyna Pączkowska, director of permanent recruitment at Manpower.

The report reveals that Polish workers value a friendly workplace culture above all else, with 46% prioritizing this aspect. Other significant factors include a job scope that aligns with their skills and interests (41%) and the option for remote or hybrid work (25%).

Source: ManpowerGroup and ISBnews

CEZ to acquire stake in Rolls-Royce SMR in multi-billion CZK deal

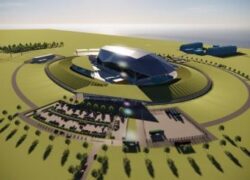
The semi-state energy company ČEZ has announced a strategic partnership with Rolls-Royce SMR to develop modular reactors, marking a significant milestone in the Czech Republic’s energy landscape. As part of the agreement, ČEZ will purchase approximately a 20 percent stake in the British firm for several billion crowns, according to Prime Minister Petr Fiala and representatives from both companies.

The collaboration, which has been in the works for several decades, aims to enable ČEZ to actively participate in the development and global production of new modular reactor technology, rather than merely acquiring pre-made equipment. “This is an important moment to ensure the energy security of the Czech Republic. We have a unique opportunity to not just buy the technology but to be involved in its development and production,” Fiala stated. He emphasized that the partnership would create opportunities for Czech companies to engage in both the development of equipment and supply chains.

The small modular reactors from Rolls-Royce SMR will be pressurized water reactors, incorporating both active and passive safety features. With an expected electrical output of 470 megawatts and a lifespan of at least 60 years, these reactors are seen as a pivotal part of ČEZ’s strategy to build a combined capacity of three gigawatts by 2050. This capacity is in addition to the existing power plants at Dukovany and Temelín, each with a capacity of about two gigawatts.

ČEZ plans to construct these modular reactors primarily for heat supply, targeting sites of existing coal-fired power plants, such as those in Prunéřov and Dětmarovice. According to CEO Daniel Beneš, the price of the modular reactors will be comparable to that of large units, reflecting the lower output of the modular designs. The company is also preparing for the construction of two large reactors, each exceeding 1,000 megawatts, at Dukovany, with one expected to cost around CZK 200 billion based on current prices.

One of the advantages of modular reactors is their potential for mass production in factories, allowing for a more concentrated deployment of units. Nuclear power experts note that while these smaller reactors have lower power outputs compared to traditional nuclear units, they feature faster and simpler construction processes, though their operational characteristics are expected to be similar.

In August, the Czech government signed a safety contract with ČEZ concerning the development of small and medium-sized modular reactors. This agreement aims to safeguard the state’s interests during the selection of future partners for reactor development and construction, ensuring that ČEZ keeps the government informed about contractor selections.

Currently, the Czech Republic operates six nuclear units across two power plants: two units at Temelín in South Bohemia, each with approximately 1,000 megawatts of capacity, and four smaller units at Dukovany in the Třebíč region, each rated at 510 megawatts. Additionally, two more reactors are scheduled for construction at Dukovany by the Korean company KHNP, with the first set to be completed by 2036.

Source: CTK
Photo: Rolls-Royce SMR

Global Mortgage Rates: Analyzing the impact of inflation and income on home buyers

As central banks in major economies begin to cut interest rates, a new analysis reveals that homebuyers in certain countries are enjoying the benefits of low mortgage rates alongside relatively high average incomes. This phenomenon raises questions about the relationship between nominal interest rates, inflation, and the real cost of borrowing.

Radoslaw Jodko, a real estate investment expert with RRJ Group, explains that the concept of real mortgage rates is crucial for understanding this dynamic. “The real mortgage interest rate is calculated as the difference between the nominal interest rate and the inflation rate. By subtracting the inflation rate from the nominal mortgage interest rate—set by banks—we obtain a clearer picture of the actual cost for borrowers and the true profitability for lenders,” he says.

A recent study by the BestBrokers team examined real mortgage rates across 62 countries, taking into account not only the consumer price index (CPI) inflation but also real estate prices relative to local average earnings. The results were striking: Sweden, Switzerland, and Spain all reported negative real mortgage rates after adjusting for inflation. However, Jodko clarifies that this does not imply buyers are free from interest payments. “Rather, it shows that the real cost of loans may have declined compared to nominal rates,” he adds.

Focusing on Poland’s position in the global context, the analysis reveals significant disparities in real mortgage interest rates. As of the third quarter of 2024, developing nations like the Dominican Republic exhibit the highest nominal rates. Among larger economies, Mexico ranks third with a real mortgage rate of 7.48 percent, followed by South Africa at 6.55 percent, and Indonesia at 5.73 percent. Poland’s real mortgage rate stands at 5.1 percent, making it one of the higher rates among European countries.

Despite these rates, the Polish real estate market shows resilience. Eurostat data from the second quarter of 2024 indicates that average apartment prices in Poland have seen substantial growth, outperforming other EU nations. Furthermore, analysis from JLL reveals a 9 percent drop in apartment sales across six major metropolitan areas in the third quarter compared to the previous quarter. However, this slowdown is not indicative of a market collapse; apartments continue to sell, albeit with longer sales cycles. In Warsaw and the Tri-City areas, developers are taking an average of 4-5 quarters to sell their inventory, while markets in Wroclaw and Krakow see sales averaging under six quarters. In contrast, Poznań and Łódź experience longer wait times, exceeding two years.

Jodko observes that the current market dynamics suggest a trend where cash buyers dominate. “Today, we see that primarily cash buyers are purchasing real estate, often for personal use. Interestingly, these purchases are not always for first homes; many buyers are acquiring second properties,” he concludes.

This analysis highlights the intricate relationship between mortgage rates, inflation, and economic conditions, suggesting that while nominal rates may be high in some regions, the overall impact on homebuyers can vary significantly based on local economic factors.

Source: Radoslaw Jodko, RRJ Group

front page info
LATEST NEWS