Saturday, 21 November 2026
India’s expanding cities are facing growing pressure to accommodate housing, commercial development, transport infrastructure and public services within established urban areas. As suitable development sites become harder to secure, government-owned land and buildings are attracting attention as potential opportunities for redevelopment through private investment and joint ventures.
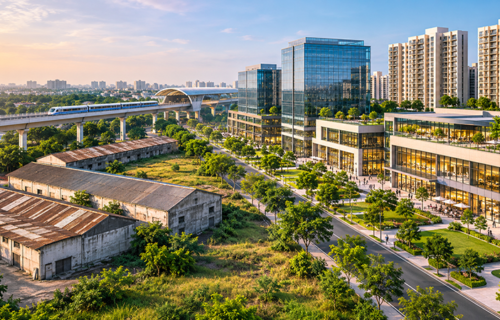
Public authorities control a wide range of properties, including railway land, former industrial sites, municipal markets, transport facilities and buildings held by government departments and public-sector enterprises. Some occupy valuable urban locations but remain subject to operational restrictions, fragmented ownership or unresolved land rights. Redeveloping suitable sites could create additional commercial and residential space while generating revenue for public authorities.
Rather than selling land outright, government agencies can grant private developers long-term leases or development rights while retaining ownership. Investors may contribute financing, construction expertise and property management services in return for rental income, commercial rights or an agreed share of project revenues.
India’s National Monetisation Pipeline provides a policy framework for attracting private capital into publicly controlled assets. Its second phase, published in February 2026, includes certain arrangements involving the further development of government land and buildings, extending beyond the original programme’s emphasis on existing infrastructure.
National Monetisation Pipeline 2.0 sets an indicative asset monetisation target of ₹16.72 lakh crore for FY2026–FY2030, including approximately ₹5.8 lakh crore of anticipated private investment. Around ₹52,000 crore is associated with urban infrastructure and real estate-related assets. These are programme targets across several sectors, rather than confirmed investment in municipal redevelopment.
The framework principally concerns central government ministries and public-sector organisations. Municipal corporations and state authorities operate under separate legal arrangements, requiring individual approvals and contractual structures for their redevelopment projects.
One of the main obstacles is fragmented ownership. Urban properties may fall under municipal corporations, development authorities, railways, transport agencies or other government departments. Coordinating these organisations can involve lengthy negotiations over land rights, planning responsibilities and future revenues.
Incomplete land records, outdated surveys and overlapping ownership claims create additional uncertainty. Sites may also contain established residential communities, informal businesses or public facilities, requiring redevelopment plans to address existing rights and rehabilitation obligations.
Research by the Asian Development Bank and World Bank has highlighted the importance of clear property records, financing arrangements, infrastructure capacity and community participation in urban redevelopment. These factors can determine whether a commercially attractive site is suitable for development.
Public-private joint ventures offer one approach, with government authorities contributing land or development rights and private partners providing capital and construction expertise. Long-term leases provide another option, allowing authorities to retain ownership while receiving upfront payments, recurring rent or revenue linked to the completed development.
The appropriate structure depends on the property’s location, commercial potential and public purpose. Municipal market redevelopment, for example, may require continued accommodation for existing traders, while former industrial land could support residential, commercial or mixed-use development.
SmartCity Kochi in Kerala illustrates the opportunities and risks associated with such partnerships. The project was established between the Kerala government and TECOM Investments, part of Dubai Holding, to develop a technology-oriented business district at Kakkanad.
Under the original agreement, TECOM held an 84% interest in the development company, while the Kerala government held 16%. Approximately 246 acres were made available through long-term land arrangements.
However, implementation delays and contractual disagreements complicated the project. Kerala subsequently pursued arrangements to end its partnership with TECOM and regain control over development. The continuing difficulties demonstrate the importance of enforceable construction schedules, investment obligations and provisions for resolving disputes.
Mumbai’s Dharavi redevelopment represents a different and considerably more complex form of public-private cooperation. The programme involves residential rehabilitation, infrastructure improvements and commercial development within one of India’s most densely populated urban districts.
The development company is structured with an 80% private-sector interest and a 20% Maharashtra government interest. Unlike redevelopment of vacant public land, the project involves extensive obligations concerning existing residents, businesses, land rights and eligibility for rehabilitation.
Dharavi demonstrates that the commercial potential of urban redevelopment must be considered alongside social and legal responsibilities. Its scale and complexity also limit its usefulness as a direct model for smaller municipal projects.
For private investors, government-controlled sites can provide access to established urban locations where conventional land acquisition may be difficult. Transport connectivity, surrounding commercial activity and opportunities for larger developments can make selected properties attractive for offices, housing, retail and mixed-use schemes.
However, these projects carry risks involving planning approvals, contractual enforcement, restrictions on land use and changes in public policy. Where several government bodies are involved, coordination can remain challenging throughout construction and operation.
Public authorities must also assess the financial implications of different arrangements. Upfront payments can provide immediate revenue, while leases and revenue-sharing agreements may generate income over longer periods. Neither approach is automatically preferable, and the outcome depends on valuation, market conditions and contractual safeguards.
Transparent selection procedures, independent valuations and clearly defined responsibilities are essential to protecting public interests. Agreements should establish development milestones, infrastructure obligations, maintenance responsibilities and procedures for addressing delays or non-performance.
Municipal capacity remains another consideration. Smaller authorities may lack the specialist resources required to structure complex property transactions, negotiate financial terms and monitor development performance, increasing the importance of appropriate technical and legal expertise.
India’s public land redevelopment potential is substantial, particularly in cities facing shortages of well-located development sites. Nevertheless, the availability of government-owned property does not automatically make it suitable for commercial redevelopment.
For developers and institutional investors, opportunities will depend on identifying sites with clear legal rights, realistic development potential and commercially viable agreements. For public authorities, the challenge is to attract private capital while retaining appropriate control over valuable urban assets and ensuring that redevelopment delivers lasting economic and public benefits.
Source: © CIJ.World India Research & Analysis Team