Union Investment Secures Long-Term Tenant for Düsseldorf Landmark as Asset Repositioning Continues

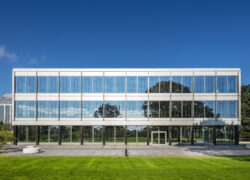
Union Investment has signed a long-term lease for almost 10,000 sqm at its landmark Seestern 3 office building in Düsseldorf, reinforcing demand for high-quality office space in established German business locations while preparing the property for the next phase of its tenant mix.

The new occupier, described as a global technology group, has agreed to lease 9,666 sqm of office space, 179 sqm of storage space and 140 parking spaces under a 10-year agreement that will commence in the second quarter of 2027. Financial terms and the tenant’s identity were not disclosed.

The transaction comes ahead of the planned relocation of Deutsche Telekom, which currently occupies part of the building and is expected to vacate the relevant space during the third quarter of 2027. According to Union Investment, the early commitment from the incoming tenant will allow refurbishment works to begin immediately after the existing occupier moves out, helping to minimise vacancy and maintain the building’s leasing momentum.

Sven Lintl, Head of Asset Management DACH at Union Investment, said the agreement reflects the company’s active asset management strategy, noting that discussions are already underway with additional prospective occupiers for other space that will become available following Deutsche Telekom’s departure.

Seestern 3, located in Düsseldorf’s established Seestern office district on the left bank of the Rhine, comprises approximately 33,000 sqm of lettable space and forms part of the UniImmo: Europa open-ended real estate fund, having been held within the portfolio since 1999.

Originally designed in 1961 by architect Helmut Rhode as the headquarters of the Horten department store group, the building is regarded as one of Germany’s earliest purpose-built open-plan office developments. Union Investment completed an extensive refurbishment between 2013 and 2015, modernising the property while preserving its architectural character.

Today, the LEED Gold-certified office building combines modern workplace standards with landscaped outdoor areas, including private parkland, internal courtyards and terrace space. The building and its surrounding park are protected as a historic landmark.

The leasing transaction highlights continued occupier demand for well-located, sustainable office buildings despite a slower investment market across Germany. While overall office transaction activity remains below long-term averages, modern buildings with strong environmental credentials and flexible workspace continue to attract corporate tenants seeking to consolidate into higher-quality premises.

Cushman & Wakefield advised on the leasing transaction, while RKW Architektur was responsible for planning the tenant fit-out.

Weather Risk Becomes a Core Investment Metric for Global Property Markets

The financial impact of extreme weather is steadily moving from the margins of the real estate industry to the centre of investment decision-making. What was once largely viewed as an environmental concern is increasingly shaping how buildings are financed, insured, valued and managed, with investors paying closer attention to how physical risks could influence long-term returns.

Across commercial property markets, owners are discovering that climate-related events affect far more than repair bills following storms or floods. Rising insurance costs, stricter lending conditions, increasing maintenance requirements and additional spending on building resilience are becoming part of the financial equation for assets expected to perform over decades rather than years.

Recent industry research shows that weather-related losses continue to place growing pressure on insurers, with the value of insured catastrophe claims increasing over the long term. While much of this reflects the rising concentration of valuable buildings and infrastructure in vulnerable locations, reconstruction costs have also climbed sharply, making severe weather events significantly more expensive for both insurers and property owners.

The result is becoming increasingly visible in commercial real estate operating budgets. Insurance, once considered a relatively stable overhead, has become one of the fastest-rising expenses for many property owners. In locations exposed to flooding, hurricanes, wildfires or severe storms, obtaining comprehensive cover is becoming more expensive and, in some cases, more restrictive as insurers reassess the level of risk they are prepared to accept.

This shift is influencing investment decisions well beyond the insurance market. Higher operating expenses reduce the income generated by buildings, while additional spending on resilience measures places further pressure on returns. For investors focused on long-term asset performance, these factors are beginning to influence pricing expectations and portfolio strategy.

Lenders are also adapting their approach. Banks have traditionally concentrated on rental income, occupancy levels and tenant quality when assessing property finance. Increasingly, however, they are examining how physical risks could affect the future performance of an asset. Questions surrounding the availability of insurance, the potential cost of future upgrades and the resilience of surrounding infrastructure are becoming more common during financing discussions, particularly for long-term loans.

As a consequence, climate resilience is emerging as an additional element of investment due diligence. Alongside reviewing leases, rental growth prospects and technical surveys, institutional investors are increasingly assessing flood exposure, extreme heat, water availability, wildfire potential and the reliability of local infrastructure. The objective is not simply to understand today’s risk but to evaluate how an asset may perform throughout the life of the investment.

The growing importance of these assessments reflects the changing nature of weather-related losses. While hurricanes and floods continue to capture headlines, prolonged heatwaves and changing rainfall patterns are creating less visible but equally significant financial pressures. Buildings consume more energy for cooling, mechanical systems operate under greater strain and maintenance requirements increase as temperatures rise. Unlike a single catastrophic event, these costs accumulate gradually and can steadily erode property income over time.

Research from MSCI suggests that chronic climate hazards now account for a significant share of projected financial losses facing listed companies worldwide. The analysis indicates that prolonged exposure to heat and changing weather patterns may ultimately create greater economic consequences than many individual natural disasters, reinforcing the growing interest in location-specific climate analysis across institutional property portfolios.

Flooding provides another example of how weather events can influence financial markets beyond immediate physical damage. European research has found that businesses affected by major floods often require additional financing immediately after an event to maintain operations, but lenders subsequently become more cautious as risks are reassessed. For property investors, this raises important questions about refinancing conditions, borrowing costs and the long-term attractiveness of assets located in vulnerable areas.

The valuation profession is also adapting to this changing landscape. Surveyors have historically relied heavily on comparable market evidence when determining property values. However, as climate exposure becomes a greater consideration for buyers and lenders, valuers are increasingly examining how resilience measures, insurance costs and future adaptation requirements may influence long-term market performance.

Occupiers are contributing to this shift as well. Businesses seeking office, logistics and industrial space are placing greater emphasis on operational continuity, employee safety and infrastructure reliability. A building that can remain functional during extreme weather is increasingly viewed as supporting business resilience as much as environmental performance.

This is encouraging property owners to reconsider how they allocate capital. Investments in flood protection, drainage improvements, resilient power supplies, enhanced cooling systems and stronger building envelopes are increasingly being viewed as measures that protect future income rather than simply satisfying sustainability objectives. In some cases, these improvements may also support lower insurance costs, reduce operational disruption and strengthen the long-term competitiveness of an asset.

The discussion is also expanding beyond individual buildings. Investors are recognising that surrounding transport networks, utilities and public infrastructure can have just as much influence on an asset’s resilience as the building itself. A well-designed property may still face operational and financial challenges if the wider area experiences repeated disruption from flooding, heat or other weather-related events.

For global real estate markets, this represents a significant evolution in investment thinking. Climate resilience is becoming part of mainstream financial analysis rather than a specialist environmental discipline. Investors are increasingly seeking detailed information that helps them understand not only where risks exist, but also how those risks can be managed over the lifetime of an investment.

Rather than dividing the market between sustainable and non-sustainable buildings, the next phase of property investment may be determined by resilience. Assets capable of remaining operational, attractive to occupiers and accessible to insurers and lenders are likely to be better positioned to preserve value, while properties requiring substantial future adaptation may face increasing financial pressure.

As weather patterns continue to evolve, resilience is becoming more than a technical consideration. It is emerging as one of the defining factors influencing investment performance, financing conditions and long-term value across the global real estate industry.

Source: CIJ.World Research & Analysis Team

NEPI Rockcastle Secures €250 Million Green Loan from EBRD to Support CEE Investment Strategy

NEPI Rockcastle has strengthened its long-term funding platform after securing a €250 million green term loan from the European Bank for Reconstruction and Development (EBRD), providing fresh capital to finance environmentally focused investments across its Central and Eastern European retail property portfolio.

The senior unsecured facility will mature in 2034 and remains available for drawdown until the end of March 2027. The financing will be used exclusively for projects that improve the environmental performance of the company’s shopping centre portfolio, supporting its broader sustainability strategy across the region.

The new financing follows NEPI Rockcastle’s Green Finance Framework, under which proceeds are allocated to eligible projects that enhance energy efficiency, reduce carbon emissions and support internationally recognised green building certifications. The framework aligns with established international standards for green finance, ensuring that investments contribute to measurable environmental improvements.

Beyond funding sustainability initiatives, the transaction also enhances the company’s capital structure by diversifying its funding sources, extending its debt maturity profile and strengthening overall liquidity. NEPI Rockcastle said the facility provides additional financial flexibility to continue investing across its growth pipeline throughout the market cycle.

The agreement also includes support for a multi-year employee development programme covering more than 300 staff, focusing on digital skills, artificial intelligence, cybersecurity and environmental management as part of the company’s long-term operational strategy.

Eliza Predoiu, Chief Financial Officer of NEPI Rockcastle, said the financing strengthens the company’s long-term funding base while accelerating an investment programme focused on sustainable retail destinations across Central and Eastern Europe. She added that the transaction reflects confidence in the company’s strategy and provides a solid platform for future growth in the region.

According to the company, the EBRD financing underlines investor confidence in the quality of NEPI Rockcastle’s portfolio and supports its continued expansion across CEE, where it owns, operates and develops shopping centres in eight countries with a property portfolio valued at approximately €8.2 billion.

How National Security and Supply Chain Strategy Are Reshaping Japan’s Real Estate Market

Japan’s real estate market has traditionally been influenced by economic growth, urbanisation, demographic change and infrastructure development. Today, another powerful force is beginning to reshape investment decisions across the property sector. National security, supply chain resilience and defence policy are increasingly influencing where industrial facilities are built, how logistics networks are planned and which regions attract long-term investment.

The turning point came during the COVID-19 pandemic, when global supply disruptions exposed Japan’s dependence on overseas manufacturing for critical goods and industrial components. At the same time, growing geopolitical tensions in East Asia, concerns over the security of shipping routes, North Korea’s missile programme and increasing strategic competition between the United States and China have encouraged Japan to strengthen domestic production capabilities and reduce vulnerabilities in essential supply chains.

These developments have expanded the role of real estate beyond simply supporting economic activity. Industrial land, logistics facilities and technology parks are now viewed as important components of Japan’s broader national resilience strategy.

Greater Scrutiny of Strategic Land

One of the most significant policy changes has been the government’s increased oversight of land located near defence facilities and other strategically important sites. Under legislation introduced to protect national security, authorities are able to monitor the use of land surrounding military bases, nuclear facilities, coast guard installations and remote islands where activities could potentially affect the operation of critical infrastructure.

According to figures published by Japan’s Cabinet Office, approximately 3,500 acquisitions of land and buildings within designated monitoring zones were reviewed during fiscal year 2024, with Tokyo accounting for a considerable proportion of these transactions. Rather than prohibiting foreign ownership, the legislation gives authorities the ability to investigate transactions and land use where there may be concerns about interference with national security or the functioning of important facilities.

For the real estate industry, this introduces an additional factor into investment decisions. Developers and institutional investors must now assess regulatory considerations alongside traditional measures such as location, accessibility and market demand. Properties situated close to strategic infrastructure may require greater due diligence, potentially affecting transaction timelines and future development plans.

Defence Investment Is Creating New Property Demand

Japan’s decision to substantially increase defence spending is also beginning to influence demand within the industrial property market. While much attention has focused on military equipment, a significant proportion of investment is supporting domestic manufacturing, advanced technology development, maintenance facilities and research centres.

As Japanese defence contractors expand production capacity, demand is expected to increase for industrial sites capable of accommodating specialised manufacturing, engineering facilities and research campuses. These developments also generate additional demand for transport infrastructure, utilities, commercial services and residential accommodation for highly skilled workers.

This investment is helping establish new industrial clusters where defence manufacturers, technology companies and research institutions can operate together. As these clusters expand, they create wider opportunities for logistics operators, commercial developers and supporting businesses across surrounding regions.

Supply Chain Resilience Is Driving Industrial Growth

Supply chain security has become one of the defining themes of Japan’s industrial policy. The disruption experienced during the pandemic, combined with the effects of the war in Ukraine and restrictions affecting access to critical minerals and advanced technologies, has reinforced the need to diversify production and strengthen domestic manufacturing capabilities.

Government support for strategic industries, including semiconductors, batteries, pharmaceuticals and advanced manufacturing, is encouraging companies to invest in production facilities within Japan rather than relying exclusively on overseas suppliers.

For the property market, this translates into growing demand for modern industrial developments, distribution facilities and logistics infrastructure located close to major ports, airports and transport corridors. Companies are increasingly seeking facilities that allow them to diversify suppliers, maintain larger inventories and reduce delivery times, making strategically located logistics assets more valuable than ever before.

The rapid growth of semiconductor investment in regions such as Kumamoto illustrates how industrial policy can reshape local real estate markets. Large manufacturing projects create demand not only for factories but also for housing, hotels, offices, retail developments and supporting infrastructure, producing long-term economic benefits for surrounding communities.

Logistics Has Become a Strategic Asset

Warehousing and logistics facilities are no longer viewed simply as commercial real estate. Increasingly, they form part of Japan’s wider resilience strategy by supporting stable supply chains during periods of disruption.

Businesses are placing greater emphasis on maintaining inventory, diversifying transport routes and shortening delivery distances. This has strengthened demand for modern logistics centres capable of serving both domestic markets and international trade while remaining resilient during future supply chain interruptions.

Developers continue to invest in facilities located near ports, airports and major expressway networks, recognising that these locations provide operational flexibility as well as strategic value. As resilience becomes a central objective for both government and industry, logistics assets are likely to remain among the strongest-performing sectors of Japan’s real estate market.

A New Dimension for Real Estate Investment

Japan’s property market continues to be supported by long-term fundamentals such as urban redevelopment, institutional investment and strong demand for modern logistics space. However, national security and geopolitical considerations are adding an entirely new layer to investment decisions.

Developers, investors and occupiers are increasingly evaluating how properties contribute to supply chain resilience, industrial competitiveness and strategic infrastructure. While these considerations will not replace traditional market fundamentals, they are becoming an important influence on the future direction of industrial, logistics and technology-related real estate.

As Japan continues strengthening domestic manufacturing and reducing dependence on vulnerable global supply chains, real estate will play a central role in supporting that transformation. Industrial land, logistics infrastructure and advanced manufacturing facilities are no longer simply economic assets; they are becoming part of the country’s broader strategy to enhance resilience, safeguard critical industries and strengthen long-term economic security.

Source: © CIJ.World Japan Research & Analysis Team

How India’s Airport Expansion Is Creating New Real Estate Growth Corridors

India’s ambitious airport expansion programme is doing far more than improving air connectivity. It is reshaping the country’s real estate landscape by creating new commercial corridors, logistics hubs and urban growth centres around major aviation infrastructure.

Over the past decade, the government and private sector have invested heavily in expanding the aviation network to accommodate rising passenger numbers, strengthen regional connectivity and improve freight movement. As airports become larger and more sophisticated, the surrounding areas are attracting increasing interest from developers, investors and businesses seeking to benefit from improved accessibility.

The result is the emergence of airport-led development, where aviation infrastructure acts as a catalyst for residential, commercial and industrial real estate.

A Rapidly Expanding Airport Network

India has significantly expanded its aviation infrastructure in recent years. The number of operational airports has more than doubled over the past decade, supported by the Regional Connectivity Scheme (UDAN), which has extended air services to many Tier II and Tier III cities.

Passenger traffic has also grown rapidly, driven by rising household incomes, increasing business travel and the expansion of domestic airlines. At the same time, both central and state governments continue to invest in airport modernisation through new terminals, runway expansions and greenfield airport developments.

Major projects such as Noida International Airport at Jewar, Navi Mumbai International Airport and expanding regional airports are expected to improve connectivity while easing congestion at existing metropolitan airports.

Alongside passenger infrastructure, airport operators are increasingly focusing on developing commercial facilities that generate revenue beyond aviation activities, creating entirely new business districts around airport campuses.

Better Connectivity Drives Land Values

One of the most immediate effects of airport development is the improvement in accessibility.

Areas that were previously considered peripheral often become attractive investment destinations once they gain faster access to domestic and international markets. Improved transport links encourage residential development, commercial projects and supporting infrastructure, contributing to higher land values over time.

This pattern has already been observed around several expanding airport regions, where infrastructure upgrades have accelerated urban development and attracted new private investment.

Growing Demand for Hospitality and Services

Rising passenger volumes generate demand well beyond airport terminals.

Hotels, serviced apartments, conference facilities, restaurants and retail developments often emerge to accommodate business travellers, tourists and airline staff. As airports evolve into major transport hubs, surrounding commercial activity becomes increasingly diversified, supporting long-term investment in hospitality and mixed-use developments.

Business parks and flexible office space are also becoming more common near major airports, particularly where companies require frequent domestic and international travel.

Logistics and Industrial Development

Airport expansion also strengthens India’s logistics sector.

Modern airports capable of handling larger cargo volumes create opportunities for warehousing, cold storage, freight terminals and distribution centres. Faster movement of goods is particularly valuable for industries handling pharmaceuticals, electronics, perishables and e-commerce fulfilment.

As supply chains become more sophisticated, logistics developers are increasingly targeting locations close to airports to improve delivery efficiency and reduce transportation times.

The combination of airports, highways and dedicated freight infrastructure is helping establish integrated logistics clusters across several regions.

Housing Demand Around Aviation Hubs

Airport development also creates significant employment opportunities.

Airlines, ground handling companies, maintenance services, hospitality businesses, logistics operators and retail outlets all require a growing workforce. This expansion increases demand for housing across a range of price segments, particularly in areas within convenient commuting distance of airport facilities.

As supporting social infrastructure such as schools, healthcare facilities and shopping centres develops alongside residential communities, many airport districts gradually evolve into self-contained urban centres rather than simply transport locations.

The Rise of Mixed-Use Airport Districts

Today’s airports generate a substantial proportion of their income from non-aviation activities, including retail, hospitality, entertainment, parking, office leasing and commercial real estate.

This shift has encouraged airport operators and developers to plan integrated mixed-use districts that combine business, residential and leisure facilities. Rather than functioning as isolated transport assets, airports are increasingly becoming anchors for wider urban development.

These airport cities, often referred to as “aerotropolis” developments in international markets, have the potential to transform surrounding regions into major economic hubs.

Looking Ahead

India’s airport expansion programme is likely to remain one of the country’s most significant infrastructure initiatives over the coming decade. Continued investment in regional connectivity, modern terminals and cargo capacity will strengthen both passenger travel and economic activity.

For the real estate sector, the opportunities extend well beyond airport boundaries. Improved connectivity, expanding logistics networks, growing employment and increasing commercial activity are creating new investment destinations across residential, industrial, hospitality and office property.

As India’s aviation network continues to expand, airport-led development is expected to play an increasingly important role in shaping the country’s next generation of urban growth corridors.

Source: © CIJ.World India Research & Analysis Team


CIJ.WORLD Announces Africa Expansion as Part of Global Editorial Growth Strategy

CIJ.WORLD has announced the launch of Africa News & Articles, a new monthly editorial section dedicated to one of the world’s most dynamic and rapidly evolving investment regions. Launching in September 2026, the initiative represents the next stage in the publication’s long-term strategy to become a leading global source of commercial real estate, investment and business news.

For more than three decades, CIJ has been recognised for its coverage of Central and Eastern Europe’s commercial property markets. As global investment has become increasingly interconnected, the publication has evolved beyond its regional roots, expanding its editorial focus to provide readers with a broader understanding of the international forces shaping property markets, infrastructure development, capital flows and economic growth.

The launch of Africa follows the successful expansion of CIJ.WORLD’s editorial coverage into Asia, where readers now have access to dedicated articles on India, Japan and other emerging and established economies. This broader perspective allows investors, developers and business leaders to compare opportunities across regions while understanding how global trends influence local markets.

The new Africa section will deliver original reporting and in-depth analysis on commercial real estate, logistics, industrial development, infrastructure, data centres, technology, sustainability, capital markets and economic policy. Rather than focusing solely on transactions, the editorial approach will examine the wider investment landscape, highlighting the structural changes driving growth across the continent and the opportunities emerging for international investors and businesses.

Africa has become an increasingly important destination for global capital as governments continue to invest in transport networks, energy infrastructure, manufacturing, digital connectivity and urban development. Expanding populations, accelerating urbanisation and improving business environments are creating new opportunities across sectors, making the continent an increasingly important part of the global investment conversation.

The expansion comes at a time of strong international growth for CIJ.WORLD. Recent audience figures show more than 30,000 active monthly readers, generating over 100,000 content interactions from readers in more than 100 countries. While Central and Eastern Europe remains the publication’s core market, its readership now extends across Asia, North America, the Middle East and other major investment regions, reflecting the increasingly global nature of commercial real estate and cross-border investment.

Robert Fletcher, CEO and Editor-in-Chief of CIJ.WORLD, said the Africa launch is only one part of a much broader transformation of the publication.

“Commercial real estate is no longer a regional industry – it is a global investment ecosystem. Capital, technology, sustainability and innovation move across borders faster than ever before, and our readers need journalism that reflects that reality. Africa is the next step in our journey, not the final destination.”

He added that CIJ.WORLD’s ambition is to create a platform that enables professionals to follow investment trends across continents rather than through isolated regional publications.

“Over the next twelve months we will continue expanding our editorial footprint, connecting markets, investors and ideas from every major region of the world. Our ambition is to build one of the world’s leading digital platforms for commercial real estate, investment, infrastructure and business intelligence while maintaining the trusted, independent journalism that has defined CIJ for more than three decades. Whether our readers are following opportunities in Warsaw, Tokyo, Mumbai, Johannesburg or New York, they should be able to find reliable, insightful reporting in one place – CIJ.WORLD.”

Looking beyond Africa, CIJ.WORLD has committed to a continuous programme of international expansion over the next twelve months. Additional countries and regional markets will be introduced progressively, creating a publication that offers readers a comprehensive view of commercial real estate and investment opportunities around the world. The objective is not simply to increase geographic coverage but to build a genuinely global editorial platform where professionals can follow the economic, political and market developments influencing investment decisions across multiple continents.

Alongside daily news reporting, CIJ.WORLD will continue to expand its original research, market analysis, executive interviews, conference coverage and sector-focused articles spanning office, industrial, logistics, retail, hospitality, residential, infrastructure, technology, ESG, artificial intelligence, data centres and capital markets. The publication also plans to increase its coverage of economic policy, foreign investment, manufacturing, energy and urban development, recognising that these sectors increasingly influence commercial property markets worldwide.

The addition of Africa represents another important milestone in CIJ.WORLD’s evolution from a respected Central and Eastern European publication into an international business media platform. As investors increasingly look beyond traditional markets and compare opportunities across continents, access to trusted, independent and globally connected reporting has never been more valuable.

With the launch of Africa News & Articles in September and further international expansion planned throughout the coming year, CIJ.WORLD continues its evolution toward becoming a truly global destination for commercial real estate, investment and business news—bringing together regional expertise with worldwide market intelligence for the benefit of investors, developers, financial institutions, governments and business leaders around the globe.

Water Security Is Becoming the Next Big Challenge for India’s Real Estate Market

For decades, India’s real estate market has been shaped by familiar considerations such as location, connectivity, pricing and infrastructure. Today, another factor is steadily moving to the forefront-water security. As rapid urbanisation places increasing pressure on natural resources, the availability of reliable water supplies is becoming a key determinant of where cities grow, how properties are valued and whether developments remain financially sustainable.

Climate scientists have repeatedly warned that water scarcity is no longer a distant environmental concern but an immediate challenge affecting many regions around the world. In India, where urban populations continue to expand rapidly, declining groundwater reserves, shrinking lakes and wetlands, and increasing pressure on municipal water systems are creating new risks for developers, investors and homebuyers alike.

Urban Growth Is Intensifying Water Stress

Many Indian cities have experienced decades of rapid construction with limited attention given to preserving natural water resources. Expansion over lakes, wetlands and recharge zones, combined with extensive concrete development, has reduced the ability of cities to replenish groundwater during the monsoon season.

At the same time, rising populations and growing commercial activity have significantly increased daily water demand. In several metropolitan regions, existing infrastructure is struggling to keep pace, forcing greater dependence on groundwater extraction, water tankers and long-distance supply networks.

This changing landscape means that water availability is becoming an important consideration alongside transport links and neighbourhood amenities when evaluating new residential and commercial developments.

The Financial Impact on Real Estate

Water shortages increasingly affect the economics of property development throughout a project’s lifecycle.

Construction activities require significant quantities of water for concrete production, curing, dust control and other site operations. Where municipal supplies are limited, developers often face additional costs associated with transporting water or arranging temporary supply infrastructure, increasing overall project expenditure.

After completion, buildings located in water-stressed areas may continue to experience higher operating costs. Dependence on tanker deliveries, deeper borewells, water treatment systems and recycling facilities can increase maintenance expenses, reducing the long-term profitability of commercial properties and affecting returns for investors.

Water availability is also becoming an important factor for purchasers and tenants. Residential buyers are placing greater emphasis on reliable water supplies before making purchasing decisions, while businesses increasingly favour office developments that can demonstrate resilient utility infrastructure. Properties with frequent supply interruptions may experience slower sales, reduced occupancy and weaker long-term value growth.

Financial institutions are also beginning to consider environmental risks more closely when assessing property investments. As climate-related risk analysis becomes more sophisticated, developments located in highly water-stressed areas could face greater scrutiny from lenders and insurers, potentially influencing financing costs over the coming years.

Reputation and Regulatory Considerations

Water-related issues can also create legal and reputational challenges for developers.

Projects that affect natural drainage systems, wetlands or existing water bodies may encounter regulatory delays, public opposition or litigation. Growing public awareness of environmental sustainability means that communities increasingly expect new developments to minimise their impact on local water resources rather than adding further pressure to already constrained systems.

As environmental standards continue to evolve, developers may also face stricter requirements regarding water conservation, wastewater treatment and sustainable infrastructure.

Building More Water-Resilient Communities

The industry is gradually recognising that water management must become an integral part of project planning rather than an afterthought.

Developers can improve resilience by conducting detailed water availability assessments before acquiring land and by providing greater transparency regarding long-term water supply strategies. Incorporating rainwater harvesting, groundwater recharge systems, efficient plumbing fixtures and smart water monitoring technologies can significantly reduce overall consumption.

Greywater recycling and on-site sewage treatment plants are becoming increasingly important in larger residential communities and commercial campuses, allowing treated water to be reused for landscaping, cooling systems and other non-potable purposes. Working closely with municipal authorities and surrounding communities can also strengthen local water infrastructure while reducing pressure on public supply networks.

Looking Ahead

Water security is rapidly becoming one of the defining issues for India’s urban future. As cities continue to expand, the ability of developments to secure reliable and sustainable water supplies will play an increasingly important role in investment decisions, project approvals and long-term property values.

For India’s real estate sector, adapting to this reality is no longer simply an environmental responsibility. It is becoming a business necessity. Developers that integrate water-efficient design, sustainable infrastructure and responsible resource management into their projects are likely to be better positioned to meet evolving market expectations while supporting more resilient urban growth in the years ahead.

Source: © CIJ.World India Research & Analysis Team

Jackson Walker uses AI to capture legal expertise and standardise decision-making

Rather than asking lawyers to become expert prompt engineers, Texas law firm Jackson Walker LLP is using artificial intelligence to capture the judgement of experienced partners and turn it into structured workflows that can be reused across the firm.

Speaking at AI4 2026 in Las Vegas, Greg Lambert, Chief Innovation Officer at Jackson Walker LLP, outlined how the firm is moving beyond individual AI prompts towards playbooks that embed legal expertise into repeatable processes.

The session, titled From Prompts to Playbooks: Turning Your Best Lawyers’ Judgement into AI Workflows, focused on how law firms can scale institutional knowledge while maintaining professional oversight.

Jackson Walker is a Texas-based full-service law firm with approximately 550 lawyers and around 380 professional staff. Lambert said the firm’s role is not to replace legal judgement but to make existing expertise easier to apply across matters and practice groups.

AI becomes part of everyday legal practice

The firm currently uses several AI platforms alongside established legal research services.

These include Harvey for drafting, document review and summarisation, Microsoft Copilot integrated with Microsoft 365, legal research platforms Westlaw Precision and Lexis+ AI, as well as pilot projects using Anthropic’s Claude Enterprise to develop more advanced agentic workflows.

Lambert stressed that specialised legal research platforms remain essential despite improvements in general-purpose AI.

“General models are getting better, but they are not legal research tools,” he said, noting that authoritative legal databases remain necessary to reduce the risk of inaccurate citations and hallucinated case law.

Adoption driven by practice groups rather than mandates

Instead of requiring lawyers to adopt AI, Jackson Walker introduced the technology gradually.

The firm initially licensed around 100 Harvey users before expanding adoption incrementally as interest grew.

Today, more than 600 employees have access to Harvey, with approximately 84% using the platform each week, according to figures presented during the session.

Rather than measuring success by the number of users alone, Lambert said the firm identified influential lawyers within each practice group, worked with them to solve specific business problems using AI, and then relied on those early users to encourage wider adoption.

This approach generated demand across the organisation without requiring mandatory implementation.

Converting experience into reusable knowledge

Lambert argued that many experienced lawyers already possess structured decision-making processes built over decades of negotiating contracts, reviewing documents and advising clients.

The challenge is extracting that knowledge in a way that others can use.

Instead of asking lawyers to create AI prompts from scratch, Jackson Walker analyses historical document revisions and identifies recurring legal positions taken by experienced partners.

These patterns are then converted into structured rule sets before being reviewed and edited by the lawyers themselves.

“The playbooks already exist,” Lambert said. “They’re contained in years of document mark-ups and negotiated agreements.”

One example involved a commercial real estate finance partner whose previous loan agreement negotiations were analysed.

The firm reviewed six completed transactions and identified approximately 90 recurring negotiating positions across seven key sections of borrower-side loan agreements.

After review by the partner, those positions were refined into a 49-rule playbook capturing standard negotiating positions, acceptable fallback language and circumstances where the firm would recommend walking away from a transaction.

The completed playbook could then be used by junior lawyers reviewing similar agreements while still allowing experienced partners to exercise judgement where required.

Supporting associates as well as AI

Lambert said the resulting playbooks have also become valuable training resources.

Rather than relying entirely on traditional mentoring, associates can review the reasoning behind common negotiating positions before working on live matters.

The playbooks are written in plain language and integrated into Microsoft Word, allowing lawyers to compare new documents against established guidance and identify clauses that comply with, differ from or fall outside accepted practice.

The same methodology is now being applied across multiple practice areas, including commercial contracts and transactional work.

Document management becomes an AI resource

The firm’s document management systems, including iManage and NetDocuments, have become an important source of institutional knowledge.

AI can search previous work while respecting ethical barriers that prevent lawyers from accessing confidential matters outside their authorised client work.

Lambert described one example where lawyers needed information about a serial litigant.

Instead of relying on firm-wide emails asking whether colleagues had previously encountered the individual, AI searched historical records and identified four lawyers with relevant experience, including one who had already prepared an internal memorandum outlining legal strategies used in earlier cases.

The information was retrieved within minutes rather than requiring manual searches across the organisation.

Measuring outcomes rather than usage

Lambert cautioned that user adoption alone provides only a partial measure of AI success.

While weekly usage statistics indicate whether staff are engaging with the technology, they do not show whether AI is improving business performance.

Instead, Jackson Walker focuses on operational measures including turnaround times, matter progression and revenue generation.

The firm also monitors governance, document access controls and AI operating costs to ensure that automation delivers measurable value rather than simply increasing computing expenses.

Building systems instead of prompts

Looking ahead, Lambert expects legal AI to move away from individual prompting towards structured systems built around established workflows.

Rather than asking lawyers to become increasingly sophisticated AI users, future systems are likely to guide them through familiar legal processes, automatically requesting the documents and information needed for each matter while applying established playbooks behind the scenes.

He also argued that clients are becoming more receptive to AI-assisted legal work, particularly where efficiency enables firms to handle additional matters without compromising quality.

For Lambert, the long-term opportunity lies less in teaching every lawyer to write better prompts than in capturing decades of professional judgement and making it consistently available across the organisation.

The approach reflects a broader shift taking place across professional services, where AI is increasingly being used to standardise expertise and improve knowledge sharing rather than simply automate individual tasks.

© 2026 cij.world

AI boom puts chips, data centres and energy at centre of global infrastructure race

The rapid expansion of artificial intelligence is turning computing capacity, semiconductor production and electricity supply into increasingly important constraints on economic growth, according to a discussion between former Intel chief executive Pat Gelsinger and OpenAI Head of Compute Sachin Katti at AI4 2026 in Las Vegas.

The discussion focused on the physical infrastructure required to support increasingly powerful AI models and the scale of investment needed across semiconductor manufacturing, data centres, electricity generation and communications networks.

AI4 2026 was held at The Venetian in Las Vegas from 4–6 August, bringing together technology companies, investors and corporate executives focused on the commercial development of artificial intelligence. The conference programme identifies Katti as OpenAI’s Head of Compute and Gelsinger as a general partner at Playground Global and former CEO of Intel.

Gelsinger argued that virtually every major development in AI ultimately depends on semiconductor capacity. While software models attract much of the public attention, the computing infrastructure underneath them is becoming one of the industry’s most significant economic and physical requirements.

He described semiconductors as the underlying fuel of an increasingly token-driven digital economy, pointing to the extraordinary technical complexity and capital requirements involved in producing advanced chips.

The challenge is no longer simply designing faster processors. New semiconductor fabrication plants can require investments running into tens of billions of dollars and take years to develop, while the most advanced manufacturing processes depend on highly specialised equipment, materials and supply chains concentrated among a relatively small number of global companies.

Companies such as TSMC and semiconductor-equipment manufacturer ASML have consequently become critical participants in the expansion of AI infrastructure.

Gelsinger argued that semiconductor companies have so far captured a substantial share of the economic value generated by the current AI investment cycle as demand for processors, advanced memory and manufacturing equipment continues to rise.

However, the next stage of the market could increasingly depend on improving efficiency rather than simply adding more computing power.

Current AI systems consume significant amounts of electricity and require enormous quantities of high-bandwidth memory and supporting infrastructure. Gelsinger said today’s generation of graphics processors remains relatively inefficient when measured against the amount of energy required to generate AI workloads.

Future chip designs are therefore likely to focus increasingly on reducing energy consumption, bringing memory physically closer to processing units and improving the amount of useful computing delivered for every watt of electricity consumed.

Katti similarly emphasised that the challenge facing AI companies extends well beyond semiconductor availability.

Building large-scale AI infrastructure requires simultaneous development of data centres, electricity connections, communications networks, cooling systems and computing equipment. Constraints at any one of these points can delay the deployment of new AI capacity.

The availability of power is becoming particularly important.

Gelsinger argued that the potential scale of AI infrastructure investment will ultimately be limited by how much electricity economies can produce and deliver to locations where new computing facilities are being constructed.

“You are fundamentally an energy entity,” he said of the emerging AI economy, arguing that companies cannot install billions of dollars of processors unless sufficient electricity is available to operate them.

That connection between AI and electricity generation is already beginning to reshape investment strategies across the global data-centre market.

Technology companies and data-centre developers are increasingly examining long-term electricity contracts, renewable energy projects, nuclear generation and on-site power solutions as they seek more reliable access to electricity.

For the property industry, this is changing the criteria used when selecting locations for large computing campuses. Land availability remains important, but access to high-capacity electricity networks, fibre infrastructure and cooling resources is increasingly determining where projects can realistically be developed.

Katti also highlighted the time required to bring new infrastructure into operation. Semiconductor development cycles can stretch across several years, while obtaining land, planning approvals and grid connections for large data centres can create additional delays.

Accelerating these development cycles will therefore become an important part of expanding global computing capacity.

At the semiconductor level, Gelsinger expects improvements in architecture and memory integration to significantly reduce the cost of AI inference over time.

Today’s processors frequently face limitations caused not by computing capability itself but by the speed at which information can be transferred between processors and memory. Bringing larger amounts of memory closer to computing units could substantially improve performance while reducing the infrastructure required for individual workloads.

Specialised processors may also become increasingly important, although both speakers cautioned against designing chips too narrowly around today’s AI architectures.

AI models are changing rapidly and semiconductor development cycles remain comparatively long. A processor optimised for a particular generation of models could potentially reach commercial production after the underlying algorithms have already changed.

This creates an unusual investment challenge for both semiconductor manufacturers and data-centre operators: infrastructure with multi-decade investment horizons is being developed for a technology whose underlying architecture can change within months.

The discussion also highlighted the growing strategic importance of semiconductor manufacturing.

Advanced chip production remains concentrated among a small number of companies and locations, creating concerns among governments and technology groups about supply-chain resilience. The complexity of rebuilding semiconductor manufacturing ecosystems means that simply investing additional capital cannot immediately create new production capacity.

Companies such as TSMC and ASML developed their technological positions over several decades, supported by networks of specialised suppliers, engineers and manufacturing expertise.

Nevertheless, the scale of investment now flowing into AI is creating incentives to expand production, develop alternative semiconductor architectures and improve manufacturing techniques.

Gelsinger said the economics of AI infrastructure will ultimately have to improve substantially if the technology is to expand to the scale currently anticipated by the industry.

The amount of capital flowing into processors, data centres and energy infrastructure is already enormous, and he suggested that future AI infrastructure investment could eventually become significant enough to be measured as a share of global economic output.

For real estate and infrastructure investors, the implications extend well beyond the technology industry.

The AI boom is increasingly linking the future of data centres with electricity generation, semiconductor manufacturing, industrial development and communications infrastructure. Markets capable of providing land, power, connectivity and predictable permitting processes are therefore likely to become increasingly competitive locations for new computing investment.

The next phase of AI development may consequently depend as much on factories, electricity networks and real estate as on advances in software.

As Gelsinger and Katti argued in Las Vegas, the race to develop more powerful artificial intelligence is rapidly becoming a race to build the physical infrastructure capable of running it.

© 2026 cij.world

AI Success Depends on Infrastructure, Not Just Adoption, Enterprise Leaders Told

Companies that succeed with artificial intelligence will not necessarily be those that adopt the technology first or impose the strictest controls, but those that build the organisational and technical foundations needed to support it safely, delegates heard during a keynote presentation at AI4 2026 in Las Vegas.

The presentation argued that enterprise AI has entered a new phase in which employees are increasingly deploying generative AI tools to solve business problems, often without formal approval from their organisations. Rather than viewing this trend solely as a governance issue, the speakers suggested it reflects growing demand for faster decision-making and more efficient workflows across large enterprises.

According to findings from a survey of 900 chief executives from companies with annual revenues exceeding USD 500 million across eight countries, 96% believe employees are already using generative AI without formal approval, while 42% said they believe at least half of their workforce is doing so. The survey results were presented by the speakers during the session and were not independently verified.

The keynote compared today’s AI adoption with the widespread introduction of spreadsheet software more than four decades ago. Business users rapidly embraced spreadsheets to solve operational problems before many IT departments had established governance frameworks, a pattern the speakers suggested is now repeating itself with AI agents.

Unlike spreadsheets, however, AI systems increasingly perform actions beyond analysing data. Modern AI agents can communicate with customers, automate workflows, generate reports, access corporate information and interact with enterprise systems, increasing the potential impact of errors or poorly governed deployments.

One demonstration highlighted how a single incorrect data reference in an AI-generated business dashboard could produce convincing visualisations while leading decision-makers to entirely inaccurate conclusions. The example was used to illustrate the growing importance of transparency and verification as organisations expand AI adoption.

The speakers argued that traditional IT operating models, developed when enterprise technology was scarce and highly centralised, are struggling to keep pace with the rapid adoption of AI across business units. Instead of positioning IT primarily as an approval authority, organisations were encouraged to evolve IT into a provider of secure platforms, governance, identity management, access controls and operational oversight.

A central theme of the presentation was that AI ownership should increasingly reside with the business teams responsible for operational outcomes. Under this approach, departments deploying AI agents would also become responsible for measuring productivity, return on investment and ongoing performance, in much the same way they manage human resources and operational budgets.

The keynote also highlighted the growing challenge of AI visibility inside large organisations. One example described a global manufacturer that initially believed it had approximately 40 production AI agents before a broader assessment identified more than 400 operating across different business functions, many without clear ownership or central oversight. While the example was anecdotal, it reflected a broader concern within the enterprise AI sector regarding so-called “shadow AI” deployments.

To address these challenges, the presenters called for organisations to establish enterprise-wide AI management capabilities, including visibility into which agents are operating, who owns them, what systems they can access, how much they cost and how effectively they perform.

The presentation concluded that successful AI strategies will depend less on restricting adoption and more on creating governance frameworks that allow business users to innovate while maintaining security, accountability and operational control.

As enterprise AI adoption accelerates, many organisations are shifting their focus from deciding whether employees should use AI to determining how that use can be managed responsibly, securely and at scale.

© 2026 cij.world

front page info
LATEST NEWS