Czech economy sees modest growth in Q4 2024

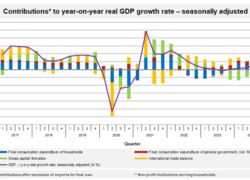
The Czech economy recorded moderate growth in the fourth quarter of 2024, with the gross domestic product (GDP) increasing by 0.7% quarter-on-quarter and 1.8% year-on-year, according to refined estimates. For the full year 2024, GDP rose by 1.0%.

Data from the Czech Statistical Office (CZSO) indicate that, after adjustments for price effects and seasonal factors, GDP in Q4 2024 was 0.7% higher than in the previous quarter and 1.8% higher compared to the same period in 2023.

Sectoral Performance and Gross Value Added

The gross value added (GVA) showed stagnation on a quarterly basis but increased by 1.1% year-on-year. In a quarter-on-quarter comparison, the strongest sectors included manufacturing (+1.0%), trade, transportation, accommodation, and food service activities (+0.4%), and real estate activities (+2.2%).

Year-on-year, the most significant contributors to GVA growth were trade, transportation, accommodation, and food services, which added 0.5 percentage points with a 3.0% increase, and real estate activities, which contributed 0.3 percentage points with a 2.1% rise. Construction also expanded, growing by 2.4% year-on-year. However, the industrial sector negatively impacted GVA growth, reducing it by 0.6 percentage points due to a 2.2% decline.

Demand-Side Factors Influencing Growth

On the demand side, higher household final consumption expenditure and changes in inventories played key roles in the quarter-on-quarter GDP increase. However, gross fixed capital formation and declining external demand had a negative effect, according to Vladimír Kermiet, Director of the National Accounts Department at CZSO.

Year-on-year GDP growth of 1.8% was mainly driven by household final consumption expenditure (+1.9 percentage points), government final consumption expenditure (+0.6 percentage points), and changes in inventories (+1.6 percentage points). Meanwhile, gross fixed capital formation (-0.7 percentage points) and external demand (-1.7 percentage points) contributed negatively.

Household final consumption expenditure increased by 1.5% quarter-on-quarter and 3.2% year-on-year, with non-durable goods purchases leading the growth. Government consumption decreased by 0.3% on a quarterly basis but rose by 3.2% year-on-year.

Gross fixed capital formation declined by 1.5% quarter-on-quarter and 2.4% year-on-year. Year-on-year growth was observed in investments in buildings, structures, and transport equipment, while other asset investments declined. The change in inventories amounted to CZK -79.5 billion, which was CZK 10.5 billion higher than in the same period in 2023.

Trade and Employment Trends

The international trade balance of goods and services at current prices stood at CZK 129.2 billion, an increase of CZK 5.1 billion compared to Q4 2023. Exports decreased by 1.5% quarter-on-quarter but rose by 1.3% year-on-year, driven mainly by electronic and optical products and electrical equipment. In contrast, exports of machinery, equipment, and motor vehicles declined. Imports fell by 1.8% quarter-on-quarter but grew by 3.1% year-on-year.

Regarding price developments in Q4 2024, the total GDP deflator increased by 0.3% quarter-on-quarter and 3.7% year-on-year.

Labour costs rose by 6.6% year-on-year in Q4 2024. Total employment decreased slightly by 0.1% quarter-on-quarter but showed a 0.2% increase year-on-year. The total number of hours worked remained unchanged compared to the previous quarter but grew by 0.5% year-on-year.

The data underscore the Czech economy’s resilience, albeit with challenges in industrial output and investment activity. Growth in household consumption and specific service sectors have helped sustain momentum despite external headwinds.

Source: Czech Statistical Office
ESG reporting deregulation to reduce costs for Polish and European companies

The European Commission has announced exemptions from ESG reporting requirements for more than 80% of companies, significantly reducing the regulatory burden. This decision is expected to bring substantial financial relief, with Polish companies projected to save nearly PLN 500 million in compliance costs. The number of Polish businesses required to report ESG metrics will decline from approximately 3,500 to 500.

At a European Commission conference, Commissioners Valdis Dombrovskis and Maria Luis Albuquerque presented the Omnibus package, which introduces significant ESG reporting deregulation. Under the proposed changes, only the largest companies will remain subject to reporting obligations, reducing the number of businesses covered by the Corporate Sustainability Reporting Directive (CSRD) across the EU from 50,000 to 10,000.

Analyses from Personnel Service indicate that the cost of ESG reporting has been a considerable expense for companies. The Chamber of Commerce of Central Europe estimates that businesses spend an average of EUR 40,000 (approximately PLN 164,000) on compliance. If all 3,500 Polish companies previously required to report had continued under the directive, total costs would have reached PLN 574 million. With the revised regulations, reporting expenses will decrease to PLN 82 million, resulting in estimated savings of PLN 490 million for Polish businesses.

Krzysztof Inglot, founder of Personnel Service, noted that easing ESG reporting obligations represents a financial relief for businesses already facing rising operational costs. While acknowledging the benefits of deregulation, he emphasized that responsible business practices should remain a priority and that reporting regulations should align with companies’ capabilities.

The Omnibus package still requires approval from the European Parliament and the Council before implementation. Once adopted, EU Member States will be required to incorporate the new regulations into their national legal frameworks. Additionally, the European Commission has announced plans to simplify the European Sustainable Development Reporting Standards (ESRS), further reducing compliance expenses for businesses.

Enefit opens electric vehicle charging stations at FORUM Shopping Centre in Gliwice

As of 28 February 2025, electric vehicle drivers can access new Enefit charging stations at the FORUM Shopping Centre in Gliwice. This expansion is part of Enefit’s broader initiative to enhance electromobility infrastructure in Poland. Enefit, a subsidiary of the Estonian energy group Eesti Energia, is one of the largest energy producers in the Baltic States and continues to develop its network of charging stations.

The newly launched charging stations at FORUM Shopping Centre include three units with different capacities: 120 kW, 47 kW, and 22 kW. These options cater to both fast-charging users and those making longer stops. Drivers can make payments via the Enefit Volt app or through a payment terminal, ensuring accessibility and ease of use. The charging stations are powered by energy certified as renewable.

According to Piotr Drożdżyk, Head of E-Mobility Solutions at Enefit, integrating charging stations with commercial facilities is a practical approach to supporting electromobility. By placing charging stations at shopping centres, users can conveniently charge their vehicles while shopping or attending meetings. Enefit has been expanding its public charging infrastructure since last year, with stations already operational in Bielsko-Biała and Zabrze. The Gliwice location marks another step in the company’s development strategy.

Shopping centre owners and managers also benefit from investments in charging infrastructure. Providing charging stations attracts new customers and aligns with sustainability initiatives. Patrycja Duczmal, Director of CH FORUM, noted that the installation of charging stations supports the centre’s ongoing commitment to environmentally friendly solutions.

Enefit currently operates 595 public charging stations across Estonia, Latvia, and Poland. The company aims to acquire locations for over 5,000 charging units by 2028, with half of them planned for installation in Poland.

Commercial property investments in Poland see significant growth in 2024

According to BNP Paribas Real Estate Poland’s report, ‘At a Glance. Investment Market in Poland in the Fourth Quarter of 2024,’ commercial property investment in Poland saw substantial growth, particularly in the final quarter of the year. The transaction volume doubled compared to 2023, reaching over EUR 5.05 billion. Despite ongoing geopolitical risks, the outlook for continued growth remains positive.

The office and retail sectors accounted for the highest share of total investment volume, each representing 32% of transactions. The office property market saw 45 transactions worth EUR 1.64 billion, four times more than the previous year. Meanwhile, investment in retail properties reached EUR 1.6 billion, with an average property size of 22,000 square metres, an increase of 7,500 square metres from 2023.

Industrial and logistics properties represented 25% of the commercial real estate market. Investment in this sector reached EUR 1.26 billion, marking a 30% increase compared to the previous year. U.S. investors were particularly active in this category, investing over EUR 350 million, accounting for nearly 28% of the annual transaction volume.

Interest in the residential sector for commercial rental also increased, with transactions totalling EUR 340 million, representing a 170% rise from the previous year. The strong transaction volume was largely driven by four major deals, including the sale of the Cromwell shopping centre portfolio and the transactions for Magnolia Park in Wrocław and Silesia City Center in Katowice. The sale of the Warsaw Unit office building also contributed significantly to the overall investment volume.

According to Mateusz Skubiszewski, Head of Capital Markets at BNP Paribas Real Estate Poland, while the 2024 results were bolstered by these large transactions, it remains uncertain if similar deals will occur in 2025. However, the market has shown signs of recovery, and increased activity is expected in mid-sized transactions valued between EUR 10 million and EUR 50 million.

Market Outlook for 2025

Analysts from BNP Paribas Real Estate Poland suggest that falling interest rates in the eurozone will encourage further investor activity. There has been an increase in capital inflows from the United States, the Czech Republic, and France. Additionally, Poland’s macroeconomic stability and planned spending under the National Reconstruction Plan for 2025–2026 are expected to support further investment.

Despite geopolitical uncertainties and the potential for trade conflicts, investors are showing interest in smaller properties with long weighted average lease terms (WAULT). While German and Asian capital remains largely inactive, domestic investors are becoming more engaged, and the market is anticipating the passage of the REIT Act, which could further stimulate investment.

By the end of 2024, the commercial property market appeared to have reached a balance between buyers and sellers. Capitalisation rates for key asset classes increased by 25 basis points. Based on current and planned transactions, analysts believe that this phase of the economic cycle has peaked and that investment returns in most asset classes are likely to improve in the coming quarters.

Major Transactions in 2024

In the retail property market, the largest transactions included the acquisition of Silesia City Center (88,000 sqm) and Magnolia Park (100,000 sqm) by NEPI Rockcastle for EUR 405 million and EUR 373 million, respectively. Czech Star Capital Finance acquired the Cromwell portfolio, comprising 219,000 sqm of retail space, for EUR 285 million.

The office property sector saw a resurgence in investor interest. The largest single-asset transaction was the purchase of the Warsaw Unit building by Eastnine AB from Ghelamco for approximately EUR 280 million. Other notable transactions included the acquisition of the P180 office building in Warsaw for EUR 100 million by Investika Real Estate Fund & BUD Holdings and the sale of 49% of the CPI portfolio by Sona Asset Management, covering 315,000 sqm of office space.

In the industrial and logistics sector, the most significant transaction was the purchase of the 7R portfolio for EUR 143 million by the Czech fund Investika. White Star acquired the Diamond Business Parks portfolio in Gliwice, Ursus, and Stryków for EUR 132 million. The most active seller in the sector was Panattoni, accounting for 40% of the total transaction volume, followed by 7R with a 19% market share.

The overall commercial property market in Poland showed strong growth in 2024, with investors demonstrating increased confidence. While uncertainties remain, the positive market outlook, falling interest rates, and stable economic conditions suggest further expansion in the coming year.

Source: BNP Paribas Real Estate Poland

Interview with Jakub Škaloud: Sustainable Innovations in the Construction Sector

This year marks five years since the European Parliament approved the Green Deal for Europe. How is the construction sector adapting to these sustainability goals?

Jakub Škaloud: The construction sector is a significant contributor to global carbon dioxide emissions, accounting for nearly 39%. Decarbonising buildings and improving their energy efficiency require continuous effort, and the pressure to reduce emissions from clients, financial institutions, and regulatory bodies is increasing. At VCES, we see this as an opportunity to innovate and proactively implement sustainability strategies.

What are the key obstacles that prevent some construction companies from adopting sustainable practices?

Jakub Škaloud: Many companies are concerned about high initial investments, the complexity of new technologies, or the lack of institutional support. However, a crucial first step is material selection, which significantly impacts the overall carbon footprint of a project.

How does material choice affect carbon emissions in construction?

Jakub Škaloud: Around 97% of CO2-equivalent emissions in the building sector come from indirect sources. Of these, approximately 55% stem from the operation of finished buildings, while the remainder is linked to construction materials. Since concrete and steel are the most widely used materials with a high carbon footprint, focusing on them can make a substantial difference.

What solutions have been effective in reducing emissions from concrete use?

Jakub Škaloud: The most commonly used cement, CEM I Portland cement, has the highest carbon footprint. By using alternative types like CEM II, CEM III, or CEM V, emissions can be reduced by up to 50%. While certain applications pose structural challenges, careful design allows for the adoption of lower-emission cement in a wide range of projects. At VCES, we have implemented these materials in multiple projects, including Nová Tesla in Pardubice and Tesla Hloubětín in Prague. Since 2021, we have reduced our use of CEM I cement by 99.3% and cut the overall carbon footprint of our concrete mixes by 22.3%.

What advancements are being made in sustainable steel production?

Jakub Škaloud: The production method has a significant impact. Traditional steelmaking involves blast furnaces, but an alternative process using electric arc furnaces can reduce emissions by over 35%. Since 2023, we have sourced 81% of our steel reinforcement from arc furnaces, reducing our steel-related carbon footprint by 28.6%.

Besides materials, what other steps can be taken to reduce the carbon footprint in construction?

Jakub Škaloud: Alternative construction methods, such as using timber structural systems, can lower carbon emissions by 20% compared to traditional reinforced concrete. Timber also improves indoor climate conditions and has health benefits. Recycling construction waste is another key strategy. At VCES, we use recycled concrete aggregate from demolition sites as a base material for new construction, reducing waste and emissions.

Modular construction is gaining traction. How does it contribute to sustainability?

Jakub Škaloud: Prefabricated solutions, such as modular bathrooms and installation shafts, enhance material efficiency and reduce waste. These techniques, common in Western Europe, are being introduced in the Czech market. We successfully implemented modular bathrooms at the Chrudimpark Residence, reducing time, labor, and emissions.

Carbon footprint calculations for buildings will become mandatory in 2028. How is VCES preparing for this?

Jakub Škaloud: We already voluntarily calculate the carbon footprint for every building we construct. The upcoming regulation will require documentation of these calculations for new buildings over 1,000 m2, expanding to all new buildings by 2030. Taking proactive steps now ensures compliance and enhances our competitiveness.

What long-term sustainability commitments has VCES made?

Jakub Škaloud: As part of Bouygues Construction, we have committed to reducing direct greenhouse gas emissions by 40% and indirect emissions by 30% by 2030. These targets align with the Paris Agreement and have been validated by the SBTi initiative. We continue adapting our processes to meet future environmental and client demands while setting an example for other companies in the industry.

Labour shortages in logistics and supply chains impact business operations

A recent study by Descartes Systems Group, titled ‘How Bad Is the Supply Chain and Logistics Workforce Challenge?’ (2024), highlights the ongoing labour shortages affecting the logistics industry. According to the report, 76% of organisations in the sector are facing significant staffing challenges, with 37% categorising the issue as severe or extreme. The study underscores the operational impact of these shortages, particularly in transport and warehouse processes, which are crucial for supply chain efficiency.

Transport operations are among the most affected, with 61% of respondents citing a shortage of professional drivers. Additionally, 56% of organisations report difficulties in maintaining adequate warehouse staff. These shortages not only disrupt daily operations but also hinder businesses’ ability to meet their objectives, especially during peak demand periods such as holiday seasons and promotional events.

The consequences of labour shortages extend beyond internal operations to customer service and financial performance. The report states that 58% of logistics respondents have experienced declines in service quality due to staffing issues. Delays in deliveries, order fulfilment errors, and reduced customer service capabilities have become prevalent challenges. As a result, logistics providers risk losing customer trust and incurring additional costs from complaints and corrective actions.

Jakub Kizielewicz, CEO of the Opteamic Group, a provider of logistics and production process outsourcing, notes that the labour shortages are significantly impacting businesses. He explains that companies reporting severe shortages often need to scale back services, leading to financial losses and reduced market competitiveness.

To address these challenges, many organisations are turning to technological solutions such as automation and robotisation of warehouse processes. Advanced analytics tools are also being integrated to optimise supply chain operations. However, 55% of industry leaders indicate that hiring skilled workers who can operate and manage these technologies remains a major challenge.

Flexible employment solutions are emerging as another strategy to mitigate workforce shortages. Outsourcing logistics processes and employing temporary workers provide businesses with greater adaptability, especially during periods of high demand. According to Kizielewicz, adopting a flexible approach to workforce management enables companies to maintain operational efficiency without committing to permanent staff increases.

The Descartes report underscores the need for a comprehensive response to workforce challenges in supply chains. Businesses must invest in both technological advancements and strategic human resource management to navigate the increasing demands of the market. Collaborating with specialised agencies for process outsourcing and temporary staffing may play a crucial role in building resilience against labour shortages.

Poland’s workforce reaches 15.1 million in September 2024, gender and sector trends revealed

As of September 30, 2024, the total number of employed persons in Poland’s national economy reached 15.1 million, according to data from Statistics Poland. The workforce maintained a mean age of 42.8 years, with a median age of 42.0 years. The age distribution of employment was similar for men and women.

Men represented a larger proportion of the workforce, making up 52.8% of total employment. However, the gender composition varied across age groups. Men were predominant at the early and later stages of working life, while women had a higher representation in the 48-59 age group. Regional disparities were also evident, with a higher proportion of female employment in major cities. The highest share of women (56.4%) was recorded in Lubuskie Voivodship’s Łęknica municipality, whereas Lelkowo in Warmińsko-Mazurskie Voivodship had the lowest share (33.1%).

The structure of employment by economic activity showed that manufacturing employed the largest number of people, accounting for 2.76 million workers (18.2% of total employment). Within this sector, women made up 34.5% of the workforce. Trade and motor vehicle repair followed, employing 14.7% of the workforce, with women comprising over 53% of this category. The most female-dominated sectors were human health and social work activities (82.0% women) and education (79.6% women). Conversely, the most male-dominated sectors were construction and mining, where over 89% of workers were men.

Paid employment accounted for the majority of the workforce, with 78.8% of employed persons classified as employees. The remainder were self-employed or contributing family workers, totaling 3.18 million individuals, or 21.0% of total employment. Self-employment was predominantly male, with men making up 62% of this category. The self-employed workforce was concentrated in various economic activities, particularly those requiring independent business operations.

The study highlights ongoing gender differences in employment distribution, both across industries and geographical regions. The employment figures also suggest a stable labor market, with a clear distinction between traditionally male- and female-dominated sectors. These findings provide valuable insights for policymakers and businesses seeking to understand workforce trends and plan for future economic developments.

Source: Statistics Poland

REICO LONG LEASE acquires prime logistics property in Senec, Slovakia

REICO LONG LEASE, an open-end mutual fund managed by REICO investment company Erste Asset Management, a.s., has acquired a newly built prime logistics property in Senec, Slovakia. The acquisition, valued at approximately EUR 1.625 million, marks the fifth addition to the fund’s portfolio.

The logistics facility, covering a gross lettable area of approximately 69,600 m², is designed with sustainability in mind. It features green certification, infrastructure for electric vehicle charging, and energy-efficient systems such as heat pumps. The roof is also prepared for the installation of solar panels, aligning the property with modern ESG standards.

The facility serves as the Slovak headquarters and a key regional hub for DSV, a global logistics and transportation company. Positioned in a strategic location, the property offers excellent connectivity to major European markets, supporting efficient regional and international distribution.

The acquisition was structured as a sale and leaseback transaction, ensuring the seller’s long-term commitment to the site while providing REICO LONG LEASE with a stable income stream. Jiří Horák, CIO and Vice Chairman of the Board at REICO IS EAM, stated that the investment aligns well with the fund’s strategy, emphasizing location, size, quality, and the financial strength of the tenant. The logistics park is fully occupied, with DSV as its sole tenant.

Dušan Sýkora, Chairman of the Board at REICO IS EAM, highlighted that this is the fund’s first acquisition in Slovakia, further diversifying its portfolio. He also noted that the transaction would enhance the fund’s performance, with returns expected to surpass previous cash investments. The fund plans to continue expanding its portfolio with additional acquisitions in the near future.

The transaction was facilitated by Wilsons, ASB Slovakia, Cushman & Wakefield, and Grinity, who represented the buyer. The seller was advised by iO Partners and legally represented by Kinstellar. Robert Cesnek, Director of Capital Markets at iO Partners, noted that this transaction is the largest sale and leaseback deal in Slovakia since 2018, underscoring strong investor interest in high-quality logistics assets.

With this acquisition, the real estate component of the REICO LONG LEASE fund’s assets has increased to 67%, further enhancing its geographic diversification. The total market value of the fund’s portfolio now exceeds CZK 3.19 billion. As of January 2025, over 47,000 shareholders had invested in the fund, which targets an annual return of approximately 5% once fully stabilized.

Launched in May 2021, REICO LONG LEASE focuses on properties with long-term leases and creditworthy tenants. It serves as a strategic addition to investment portfolios, particularly for conservative and moderately dynamic investors seeking real estate exposure. The fund currently holds five properties, including two in the Czech Republic, two in Poland, and one in Slovakia.

Bitcoin fails as a safe haven investment, DIW Berlin study finds

A new study conducted by the German Institute for Economic Research (DIW Berlin) has determined that Bitcoin is not a viable safe haven asset, as its returns closely mirror those of equities rather than exhibiting the stability expected of a financial hedge. In contrast, gold, which has long been recognized as a traditional safe haven, remains largely independent of market fluctuations, making it a more reliable option for diversification and risk management.

The study, led by Alexander Kriwoluzky, head of the Macroeconomics Department at DIW Berlin, and Christoph Schneider, Professor of Finance at the University of Münster, analyzed the monthly returns of gold, Bitcoin, and US and German stocks and bonds over the past decade. Their findings indicate that Bitcoin’s return trends strongly correlate with those of equities, whereas gold’s performance remains unlinked to the fluctuations of stocks and bonds, especially during financial crises. This key distinction suggests that Bitcoin does not offer the same protective qualities as gold in times of economic uncertainty.

Despite Bitcoin’s meteoric rise in value over recent years, its high volatility and unpredictable swings make it an unreliable asset for risk-averse investors. Many still view Bitcoin as an alternative asset class, but its behavior during market downturns paints a different picture. ‘Unlike gold, however, Bitcoin does not provide a safe haven. It moves in tandem with the stock market, often declining when equities fall,’ explains Kriwoluzky. ‘Additionally, Bitcoin’s exchange rate is highly unstable, making it a far riskier investment than gold, which has long been valued as a stable store of wealth.’

Beyond investment concerns, the study also dismisses Bitcoin’s suitability as a currency reserve for central banks. Given its extreme price fluctuations and lack of intrinsic yield, the cryptocurrency does not compare favorably to government bonds, particularly German government bonds, which offer greater stability for diversification and hedging purposes. The debate over Bitcoin as a currency reserve, which gained traction in the United States with endorsements from figures such as Donald Trump and Elon Musk, is found to be lacking a substantive foundation. Schneider emphasizes this point, stating, ‘This discussion was widely adopted in German-speaking regions without critical evaluation, despite Bitcoin’s clear risks and volatility. As a result, Bitcoin is entirely unsuitable as a currency reserve.’

The study underscores the ongoing debate surrounding Bitcoin’s role in modern finance, challenging widespread narratives that position it as a digital equivalent to gold. While its speculative appeal remains strong, Bitcoin does not currently fulfill the role of a safe-haven asset or a stable reserve currency, leaving investors and institutions to reconsider its long-term value in diversified portfolios.

Source: DIW Berlin

German Office Market in 2025: Navigating challenges amidst signs of stabilization

Germany’s office real estate sector remains under pressure in 2025, with a mixture of challenges and glimmers of hope pointing towards potential stabilization. While commercial property values continue to decline, slight upticks in certain indicators suggest that the worst may be over, though full recovery remains elusive. Investors, landlords, and tenants are cautiously adapting to a transformed landscape, marked by shifting demand patterns, evolving workplace strategies, and macroeconomic uncertainties.

Market Performance and Indicators

According to the latest data from the Association of German Pfandbrief Banks (VDP), commercial property prices recorded a 4.7% decline in the third quarter of 2024 compared to the same period the previous year. However, a marginal 0.7% uptick from the second quarter of 2024 hints at a potential leveling off in market depreciation. Analysts interpret this as an early sign of stabilization but stress that economic fragility and geopolitical tensions continue to weigh on investor confidence.

A key player in Germany’s real estate financing landscape, Deutsche Pfandbriefbank (PBB), reported a slight dip in its annual net profit for 2024, posting €90 million compared to €91 million in 2023. While the decrease appears minor, it underscores the slow and uneven recovery process for commercial real estate. PBB has characterized the current climate as “the greatest real estate crisis” since the 2009 financial downturn, citing ongoing difficulties in both German and international markets.

Despite the subdued recovery, PBB reduced its risk provisions from €212 million to €170 million. This decline is attributed to fewer bad loans associated with U.S. office properties and German real estate developments. However, the bank remains cautious, with CEO Kay Wolf emphasizing that market improvements remain gradual and highly dependent on broader economic shifts, including interest rate policies and corporate sentiment.

Notable Developments

In one of the most significant leasing deals of the year, Commerzbank has committed to a 15-year lease for a new high-rise office in Frankfurt. The new tower, slated for completion by the end of 2028, will accommodate approximately 3,200 employees in a consolidated workspace adjacent to the bank’s primary headquarters. This move signals a strategic shift in corporate real estate decision-making, prioritizing efficiency, employee experience, and long-term cost optimization over excessive office footprints.

The decision also reflects broader trends in the German office sector, where companies are re-evaluating their space requirements in response to hybrid work models. While some firms continue to downsize their physical office presence, others, like Commerzbank, are opting for strategic consolidation—bringing employees together in high-quality, well-located spaces that enhance collaboration while ensuring operational efficiency.

Outlook and Key Considerations

While some market data suggests stabilization, the German office sector remains susceptible to external pressures. High interest rates, ongoing economic sluggishness, and geopolitical tensions continue to impact both occupiers and investors. The European Central Bank’s (ECB) monetary policy decisions in 2025 will be a crucial determinant of market movement, as interest rate cuts could potentially stimulate investment and ease financing costs for property owners and developers.

Moreover, the demand for high-quality, sustainable office spaces remains strong, with companies increasingly prioritizing ESG-compliant buildings. Investors and landlords who adapt to these shifting priorities stand a better chance of maintaining occupancy rates and rental income in an otherwise challenging environment.

Looking ahead, stakeholders should brace for a prolonged adjustment period rather than a swift recovery. The coming months will likely be characterized by continued market fluctuations, with selective opportunities emerging for those positioned to capitalize on shifting demand dynamics. In this uncertain but evolving landscape, strategic adaptability and forward-looking investment decisions will be key to navigating Germany’s office real estate market in 2025.

Source: comp.

front page info
LATEST NEWS