ERSTE Real Estate Fund acquires two HelloParks warehouses in Hungary’s largest industrial deal

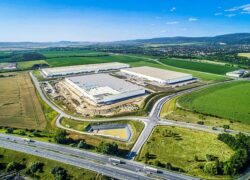
ERSTE Open-Ended Real Estate Investment Fund has acquired two industrial warehouses from HelloParks in Hungary, marking the largest transaction in the country’s industrial real estate market in the past decade. The PT2 and PT3 buildings, located in the HelloParks Budapest West megapark, offer a total of 84,000 square meters of logistics and industrial space. The deal between ERSTE’s Real Estate Fund and Futureal Group’s industrial property division is notable for its size and significance within the sector.

Each warehouse spans 42,000 square meters and has been developed to meet BREEAM New Construction’s Outstanding rating, a sustainability standard achieved by only a small percentage of buildings globally. The properties also comply with EU Taxonomy regulations, making them unique within Hungary’s industrial real estate landscape. The warehouses are occupied by international logistics firms, including Gebrüder Weiss and Transdanubia, and despite the sale, HelloParks will continue to manage their technical operations.

According to Gábor Futó, founder of HelloParks and Futureal Group, the transaction reflects a renewed investor interest in Hungary’s industrial and logistics sector. He highlighted the strong demand for space and rental growth, driven by nearshoring and industrialization trends, while also noting the limited availability of ESG-compliant facilities. Balázs Pázmány, Chairman of the Board at Erste Alapkezelő Zrt., described the acquisition as part of ERSTE’s strategy to expand its industrial real estate portfolio with high-quality, sustainable properties that offer long-term returns. Rudolf Nemes, CEO of HelloParks, pointed to increasing EU regulatory requirements as a factor driving tenant demand for environmentally sustainable warehouses.

The buildings are equipped with advanced systems to optimize energy use and efficiency. They feature heat pump-based cooling and heating, rooftop solar panels that can eliminate primary grid energy consumption for offices, and an intelligent building management system that monitors and adjusts heating, ventilation, air conditioning, and other utilities. A proprietary mobile app allows tenants to control lighting, ventilation, and temperature while tracking energy usage in real time.

The HelloParks Budapest West megapark, located along the M1 motorway in Budapest’s western agglomeration, is a key logistics hub. The 87-hectare site is planned to accommodate 384,000 square meters of industrial space, with 142,000 square meters already completed and an additional 42,000 square meters expected to be delivered this year. In addition to the newly acquired PT2 and PT3 warehouses, the megapark includes the 58,000-square-meter PT1 facility, the largest contiguous modern industrial building in the Budapest metropolitan area. Across the three completed warehouses, occupancy rates are approaching 90%, supporting approximately 550 jobs.

YIT advances Toivo Roztyly project in Prague with sustainable living and strong sales

YIT has completed the rough construction phase of the first stage of the Toivo Roztyly residential project in Prague 11. This phase includes 88 apartments and is expected to be finished by the end of the year. The second phase, set to begin in 2024, will add another 116 apartments. The development features a minimalist architectural style with ecological elements and green spaces.

The first stage consists of four apartment buildings with load-bearing reinforced concrete structures. Ongoing construction includes work on the roofs, facades, and interior spaces. Infrastructure improvements, such as roads and pedestrian pathways, are also underway. According to YIT, progress is on schedule, and over 70% of the units in the first phase have already been sold.

The entire project will offer 204 apartments, ranging from studios to five-room units, with sizes between 29 and 120 square meters. Many apartments include balconies, terraces, or private gardens. The complex will feature basement storage, a carriage house, and facilities for washing bicycles and pets. Outdoor spaces will include a courtyard, a new street with green areas, and a small park.

Sustainability and energy efficiency are central to the project. Stormwater management systems, LED lighting in common areas, and a controlled ventilation system with heat recovery are designed to reduce energy consumption by up to a third. Triple-glazed windows and external shading preparation will also contribute to energy efficiency. The project includes green roofs, tree planting, and bicycle racks, along with garage parking spaces equipped for electric vehicle charging. Green concrete is being used for structural elements, and some units feature modular bathrooms. The development is co-financed by investment group RSJ.

Located on Komárkova Street, Toivo Roztyly is near the Michelský Forest, which connects to Kunratický and Krčský Forests, providing outdoor recreation opportunities. The site offers good transport links, with the Roztyly metro station just 200 meters away and access to bus routes, the D1 motorway, and Prague’s main road network. Shops, schools, medical facilities, and sports centers are within close reach, making the development well-suited for residents seeking convenience and access to green spaces.

BPI Real Estate Poland and SPEEDWELL partner for new residential development in Gdańsk

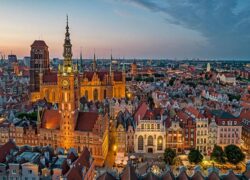
BPI Real Estate Poland and SPEEDWELL have formed a joint venture for a new residential development in Gdańsk. The project, located near the Old Town, will introduce approximately 750 apartments across 36,000 square meters of residential space. Designed to integrate with the city’s historic character, the development will provide a modern living environment while maintaining connections to the surrounding urban and cultural landscape.

The location offers views of the city skyline, including St. Mary’s Church, and is near riverside boulevards and pedestrian pathways. The project aims to balance urban accessibility with a green and peaceful setting. The architectural concept, selected through a competition, emphasizes sustainability and functional design. Apartments will range from studios to four-bedroom units, with green spaces incorporated to enhance the quality of life and encourage an eco-friendly lifestyle.

BPI Real Estate Poland has secured the land and is now working with SPEEDWELL to finalize the design and planning phases. Both companies bring extensive experience in residential development, having completed over 20 projects across Poland and Romania. The first phase of construction is scheduled to begin in the second half of the year.

“We believe in the extraordinary potential of Gdańsk, for which we have a special respect and attraction. The project that we will develop together with our partners at BPI Real Estate Poland will reshape the future of a part of this wonderful city. We will do it with passion, respect, and always with the needs of its inhabitants in mind—offering quality, care for the environment, and a sense of well-being that defines true home living,” said Didier Balcaen, CEO and Co-Founder of SPEEDWELL Development.

“This new investment aligns with our long-term strategy of developing high-quality, well-located residential projects that contribute to the dynamic urban landscape of Poland’s key cities. Together with Speedwell, we are committed to delivering a modern, sustainable development that will enhance the Gdańsk skyline and offer future residents an exceptional living experience,” said Béranger Dumont, General Manager of BPI Real Estate Poland.

Intersport Voswinkel leases 2,000 sqm at Limbecker Platz shopping centre in Essen

Union Investment has secured a new tenant for the Limbecker Platz shopping centre in Essen. Intersport Voswinkel has signed a ten-year lease for 2,000 square meters on the first floor, which is now fully occupied. This marks another step in the re-letting of space previously occupied by Galeria Karstadt Kaufhof, with 50 percent of the former tenant’s area now leased.

Galeria Karstadt Kaufhof had rented approximately 19,000 square meters across four floors before filing for insolvency in January 2024, leading to the termination of its lease. The vacated space is being divided into multiple sections to accommodate different retailers.

Union Investment and ECE have already secured P&C* Düsseldorf, which will occupy 6,400 square meters over two floors. The store is expected to open in spring 2026 with an updated shop design. The redevelopment of the space, carried out in partnership with ECE, represents an investment of approximately EUR 30 million through Union Investment’s open-ended real estate fund, UniImmo: Europa.

Discussions are ongoing with potential tenants from various sectors to fill the remaining vacant areas. Limbecker Platz has recently added new tenants, including Bershka, Pull&Bear, Zara, and the first German store of Japanese brand MINISO.

With over 200 stores, Limbecker Platz is one of Germany’s largest inner-city shopping centres. Designed by architect Gunter Henn, the building features a distinctive metal façade inspired by a Marilyn Monroe dress, decorated with illuminated sequins that change colour at night.

LEG Immobilien SE reports strong 2024 results with stable portfolio valuation and earnings growth

LEG Immobilien SE reported strong financial results for 2024, with AFFO reaching EUR 200.4 million, slightly exceeding the company’s mid-year forecast. The company maintained steady performance, benefiting from strong demand for affordable housing and solid leasing activity. The completion of the majority acquisition of Brack Capital Properties on January 3, 2025, expanded LEG’s portfolio by approximately 9,000 apartments, further strengthening its position in the residential real estate sector.

The company saw improvements in key operational indicators, with the like-for-like vacancy rate decreasing to 2.3 percent and rental income increasing by 3.4 percent. The rise in rental income was driven by the free-market segment, as regulated rental rates in the subsidized housing sector remained stable. The average rent for LEG’s properties now stands at EUR 6.80 per square meter. Throughout the year, the company focused on maintaining cost efficiency, with total investments amounting to EUR 436.5 million, in line with the previous year.

The proposed dividend for 2024 is EUR 2.70 per share, reflecting a full distribution of AFFO in line with the company’s dividend policy. This corresponds to a yield of 3.3 percent based on the share price at the end of 2024. The company’s financial stability was reinforced by the stabilization of portfolio valuation, with a slight increase of 0.4 percent in the second half of the year. At year-end, the valuation of LEG’s residential portfolio averaged EUR 1,629 per square meter, and the gross yield of the portfolio stood at 4.9 percent.

LEG continued its asset management strategy by selling approximately 2,500 apartments for EUR 255 million to strengthen its balance sheet. Additional sales of 1,800 units are expected to generate EUR 62 million in net proceeds. The company remains cautious with acquisitions but continues to assess opportunities in the transaction market. Financing costs averaged 1.49 percent at the end of 2024, supported by the issuance of a EUR 700 million convertible bond and the repayment of higher-interest debt. Net debt declined by 2.2 percent to EUR 8.8 billion, with the loan-to-value ratio improving to 47.9 percent.

Looking ahead to 2025, LEG expects further stability in property values and continued demand for rental housing. AFFO is projected to be between EUR 205 million and EUR 225 million, potentially reflecting a 7 percent increase per share compared to 2024. The company plans to increase investment per square meter for the first time in two years, from EUR 34 to over EUR 35. LEG also aims to integrate sustainability with financial performance, targeting CO2 reductions and long-term revenue contributions from its green business initiatives.

Kamco Invest reports KWD 4.4 million (USD 14.4 million) net profit for 2024

Kamco Invest, a regional non-banking financial services provider, reported a net profit of KWD 4.4 million (USD 14.4 million) for the financial year ending 31 December 2024, a significant increase from KWD 748 thousand (USD 2.4 million) in 2023. Earnings per share rose to 12.72 fils, up from 2.19 fils the previous year.

Total revenue for the year reached KWD 25.4 million (USD 83.1 million), compared to KWD 18.0 million (USD 58.9 million) in 2023. The company’s fee and commission income grew by 15% to KWD 16.9 million (USD 55.3 million), accounting for 66.5% of total income, reinforcing its position as the primary revenue driver. Kamco Invest raised over USD 1.2 billion for various products and transactions and increased its assets under management by USD 1.0 billion, bringing the total to USD 15.9 billion, a 7% growth over the year.

The company’s equity funds and managed portfolios continued to perform strongly. Kamco Investment Fund was ranked the best-performing fund in Kuwait, while Kamco Islamic Fund was the second-best-performing Islamic equity fund, based on data published by Boursa Kuwait.

In alternative investments, which include real estate, private equity, and structured products, the firm distributed USD 58.1 million to clients and assessed new investment opportunities. Kamco Invest also expanded into private debt investments in real estate projects alongside its existing equity investments in real estate assets.

The investment banking division completed 11 transactions worth USD 4.9 billion, including nine bond and sukuk issuances for financial institutions and corporates in Kuwait, Saudi Arabia, the UAE, and Bahrain. The company also managed Kuwait’s largest mandatory tender offer in the insurance sector and an Initial Public Offering (IPO) of an Omani sovereign-owned oil company.

Kamco Invest continued to expand its network and strengthen its global presence, contributing to increased fee-based income. The company’s brokerage arm, First Securities Brokerage Company, grew its client base by leveraging online trading platforms.

The company ended 2024 with KWD 62.3 million (USD 203.9 million) in shareholders’ equity, reflecting a 4.3% increase from the previous year. Capital Intelligence, in its May 2024 review, maintained Kamco Invest’s long-term credit rating at “BBB” and short-term rating at “A3” with a stable outlook.

The Board of Directors has proposed a cash dividend of 5 fils per share, pending shareholder approval at the Annual General Meeting.

Chairman Sheikh Talal Ali Abdullah Al Jaber Al Sabah highlighted the company’s performance despite market challenges, emphasizing its focus on asset management and investment banking as key factors in maintaining its competitive position. He reaffirmed the company’s commitment to expanding in key markets and delivering value to stakeholders.

CEO Faisal Mansour Sarkhou attributed the strong financial performance to business growth across multiple areas, including revenue expansion, managed product performance, and successful transactions. He stressed the importance of fee and commission-based income in sustaining the company’s financial stability, describing it as a differentiating factor in Kamco Invest’s business model.

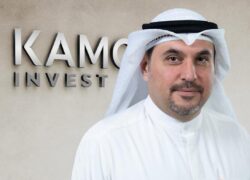
Photo: Faisal Mansour Sarkhou, Chief Executive Officer and Sheikh Talal Ali Abdullah Al Jaber Al Sabah, Chairman of Kamco Investment Company K.S.C

UK planning reforms aim to halve approval time for major Ppojects

The UK government has unveiled a comprehensive overhaul of the national planning system, aiming to speed up approvals for major infrastructure and housing projects. Central to this initiative is the forthcoming Planning and Infrastructure Bill, which seeks to reduce the current average approval time of four years for significant developments such as wind farms and power stations. Housing and Planning Minister Matthew Pennycook has described the reforms as a “radical evolution” designed to streamline processes, boost economic growth, and address the housing crisis.

A key element of the bill is the simplification of bureaucratic processes, which will remove unnecessary administrative hurdles and improve efficiency in planning applications. The reforms also include limitations on judicial reviews, preventing repeated legal challenges from delaying critical projects. In addition, the introduction of a Nature Restoration Fund aims to balance infrastructure growth with environmental sustainability, ensuring that development aligns with long-term ecological goals. These measures support the government’s ambition to generate most of the UK’s electricity from low-carbon sources by 2030 while also delivering 1.5 million new homes over the next five years.

The government is also implementing new strategies to improve the efficiency of local councils in the planning process. Planning officers will be granted greater authority, reducing the reliance on council committees, which often slow decision-making. In addition, mandatory training for councillors involved in planning committees will ensure they make informed and efficient decisions. Another significant measure is the government’s plan to address land banking, a practice where developers hold onto land without proceeding with construction. A “use it or lose it” policy is being considered, which could impose financial penalties or revoke planning permissions for stalled projects, ensuring that housing targets are met.

Environmental considerations are also a crucial aspect of the reforms. Local councils will now be required to review green belt boundaries, particularly areas classified as “grey belt”, which have lower environmental value and could be used for development. This reassessment aims to strike a balance between protecting green spaces and addressing the severe housing shortage. Prime Minister Keir Starmer has emphasized that while environmental protection is essential, housing development must take priority in some areas to meet the country’s growing demand.

The bill outlines an ambitious strategy for national infrastructure development, with the government pledging to fast-track decisions on 150 major projects within the current parliamentary term. This acceleration is expected to double the approvals compared to the previous administration, particularly in sectors such as transportation, energy, and public services. The Justice Secretary has also announced a push to expand prison capacity by securing sites for new facilities, utilizing existing Crown development legislation to bypass previous bureaucratic delays.

Chancellor Rachel Reeves has underscored that these planning reforms are a fundamental part of the government’s economic growth strategy. By making it easier for developers to build, particularly near key transport hubs, the government aims to stimulate investment in housing and infrastructure, improve workforce mobility, and enhance economic competitiveness. This “presumption in favour of building” is expected to create long-term economic benefits, making Britain a more attractive destination for investors.

In summary, the UK’s proposed Planning and Infrastructure Bill represents a significant transformation in how major projects are approved. By halving approval times, empowering local authorities, and balancing development with environmental concerns, the government is aiming to create a more efficient, responsive, and forward-thinking planning system. These reforms signal a major shift in the UK’s approach to urban development, paving the way for more streamlined and sustainable growth.

Source: FT and Times

Romania’s retail sector performance in January 2025: Mixed trends across categories

The retail sector in January 2025 experienced notable fluctuations in turnover, with significant month-on-month declines yet year-on-year growth across key categories. Data from the latest statistical report highlights contrasting trends, where short-term seasonal effects caused sharp decreases in retail sales compared to December 2024, while long-term trends indicated a steady increase from January 2024.

Retail turnover volume, excluding trade in motor vehicles and motorcycles, declined by 19.4% as a gross series from December 2024. However, after adjusting for the number of working days and seasonal variations, the decline was largely mitigated, with a marginal increase of 0.1% on a monthly basis. The drop was primarily driven by lower sales in food, beverages, and tobacco, which fell by 21.3%, while non-food products registered a decline of 20.5%. The retail of automotive fuel in specialized stores also recorded a decrease, though at a lower rate of 12.0%.

On a year-over-year basis, the retail sector presented a more optimistic picture. Compared to January 2024, the total retail turnover volume increased by 4.1% in gross series and by 3.2% in seasonally adjusted terms. This growth was largely driven by a strong performance in non-food retail, which recorded a 7.0% increase. The automotive fuel segment also contributed positively, with a rise of 7.3% in gross series and 1.2% in adjusted terms. Conversely, food, beverage, and tobacco sales declined by 0.9% in gross figures and showed a marginal decrease of 0.2% in seasonally adjusted data.

Breaking down the sector further, food, beverage, and tobacco sales, despite a steep month-on-month drop of 21.3%, showed near stability over the year, reflecting a minor decline in demand. Non-food product sales experienced a sharp monthly decrease but exhibited strong growth over the longer term, with a 5.8% increase in adjusted figures from January 2024. Meanwhile, automotive fuel sales, despite a short-term contraction, maintained resilience in annual performance, growing by 7.3% in gross terms and 1.2% in seasonally adjusted figures.

The contrasting trends in retail performance reflect the typical seasonal effects observed in January, following a peak in consumer spending during the holiday season in December. The sharp month-on-month decline is consistent with historical patterns, where post-holiday spending tightens across retail categories. However, the year-on-year growth suggests a steady expansion in consumer activity, particularly in non-food and fuel sales, which continue to drive overall retail sector performance.

The report also provides insight into the methodological framework used to calculate turnover figures. The retail turnover indices are based on Laspeyres-type indices, which adjust for price fluctuations and maintain comparability over time. The turnover volume is derived by aggregating invoiced revenues from sales while excluding excise duties, subsidies, and non-retail transactions such as land and fixed asset sales.

Looking ahead, analysts will closely monitor whether the retail sector can sustain its year-on-year growth amid economic uncertainties. While the beginning of the year has seen a typical seasonal decline in turnover, consumer demand for non-food products and fuel has shown resilience. If this trend continues, it may indicate stable economic conditions that support further growth in retail trade.

The next retail turnover report is scheduled for release on April 7, 2025, and will provide further insights into consumer spending trends and market conditions in the coming months. For more comparative data across European Union member states, additional reports from Eurostat will complement the national statistics.

Mixed economic trends in Poland: Industry struggles, services resilient in February 2025

Economic sentiment in Poland’s regions showed a mixed picture in February 2025, with negative trends dominating in manufacturing, construction, and wholesale and retail trade. The regional business climate indicator (R-BCI) recorded negative values in most voivodeships for these sectors. However, services, particularly in information and communication, displayed greater resilience, with several regions reporting positive business sentiment.

Compared to the same period in 2024, the overall economic climate improved in the services sector, with at least half of the voivodeships reporting an increase in the R-BCI. Retail trade also experienced an improvement in eight voivodeships, reflecting a modest recovery in consumer confidence.

Month-on-month comparisons indicate a gradual improvement in business sentiment across multiple sectors. At least seven voivodeships reported higher values of the regional business climate indicator in all analyzed economic areas compared to January 2025. Despite this, most entrepreneurs across sectors (except for those in information and communication) anticipated a deterioration in their firms’ economic conditions over the next three months.

Industrial and Construction Sectors Under Pressure

The manufacturing sector remained under strain, with most voivodeships reporting negative business sentiment. The most pessimistic assessments came from the Podlaskie, Łódzkie, and Śląskie voivodeships, where the R-BCI fell to -8.3, -6.9, and -6.4, respectively. These declines were primarily driven by concerns over current economic conditions and uncertainty about the future.

However, some positive signs emerged. Entrepreneurs in Mazowieckie (6.8), Małopolskie (4.9), and Podkarpackie (2.4) voiced more optimism, citing stable business conditions and expectations of gradual improvement.

In the construction sector, economic sentiment was predominantly negative across most regions. The worst assessments came from Pomorskie (-14.5) and Zachodniopomorskie (-13.7), where businesses struggled with declining orders and reduced construction activity. Positive evaluations were rare, with Podlaskie (9.3) and Mazowieckie (0.9) standing out as the only regions where expectations for the industry remained stable or slightly optimistic.

Entrepreneurs in construction indicated a continued decline in new orders and anticipated further reductions in activity over the coming months. While a few regions showed improvements compared to January 2025, overall business sentiment remained weaker than a year ago.

Rising Costs and Uncertainty as Key Barriers for Businesses

The primary constraint on business operations across all regions continued to be rising labor costs. This was particularly burdensome for companies in the accommodation and food services sector, where the percentage of businesses reporting labor costs as a major challenge ranged from over 7% to nearly 93%, depending on the region.

Economic uncertainty was another significant concern, especially for wholesale trade and transport businesses. Entrepreneurs cited unpredictable market conditions and unclear regulatory policies as key issues affecting their operations.

The burden of high state-imposed payments was also a major issue for construction firms, as well as for businesses in accommodation and food services. Despite these challenges, a small percentage of businesses in manufacturing and retail trade reported facing no significant barriers to their operations.

Retail Trade Sees Modest Growth Amid Challenges

Despite the challenging economic environment, the retail sector exhibited moderate signs of recovery. The volume of retail trade in February 2025 increased by 4.7% compared to the same period in 2024, both in raw and calendar-adjusted terms. Growth was recorded across various retail segments, with food sales rising by 4.7%, non-food retail expanding by 5.6%, and fuel sales increasing by 1.9%.

Sales growth was particularly strong in pharmaceutical, medical goods, and cosmetics shops (9.7%), furniture and electrical goods stores (7.8%), and shops selling manufactured goods (6.7%). However, second-hand goods stores and bookshops saw only marginal increases, reflecting a divergence in consumer spending habits.

E-commerce remained a key driver of retail expansion, with mail order and internet retailing growing by 3.9%, accounting for 8.8% of total retail sales. Automotive fuel sales also experienced a slight boost, rising by 1.9%.

Wholesale Trade Struggles Amid Excess Inventory

While retail trade showed some resilience, the wholesale sector faced a more difficult environment. The R-BCI for wholesale trade was negative in most voivodeships, with Zachodniopomorskie (-11.6), Warmińsko-Mazurskie (-8.7), and Pomorskie (-7.4) showing the most pessimistic outlooks.

Businesses in wholesale trade reported declining sales and excess inventory levels as primary concerns. Many also expressed worries about deteriorating financial conditions. Forecasts for the coming months remained cautious, with expectations of continued weak demand and further economic difficulties.

Despite these concerns, business sentiment improved slightly in several regions compared to January, particularly in Lubelskie, where the R-BCI rose by 9.1 points. However, year-on-year comparisons showed a worsening outlook in nine voivodeships, with the sharpest declines recorded in Podkarpackie, Podlaskie, and Zachodniopomorskie.

Services Sector Shows Stronger Performance

In contrast to the difficulties faced by industry and trade, the services sector demonstrated greater resilience. The information and communication sector, in particular, recorded positive business sentiment in most voivodeships. Lubuskie (28.6), Świętokrzyskie (20.2), and Małopolskie (17.7) reported the most optimistic assessments.

Entrepreneurs in this sector expressed confidence in their current economic conditions, though forecasts for the coming months were mixed. In four voivodeships, business owners expected a downturn, while in six others, opinions were evenly split between optimism and pessimism.

Accommodation and food services also showed positive signs, with nine voivodeships reporting an overall optimistic outlook. Lubelskie (37.7) and Podkarpackie (34.2) recorded the highest R-BCI values. However, businesses in Pomorskie, Małopolskie, and Zachodniopomorskie were more cautious about the future, citing concerns over declining demand and financial uncertainty.

Investment Trends in 2025: Stability Over Expansion

An additional survey on investment expectations for 2025 revealed that most businesses anticipate maintaining investment levels similar to those in the previous year. This was especially pronounced in the information and communication sector, where over 70% of entrepreneurs planned to sustain their investment levels.

However, among firms expecting changes, more predicted a decline in investment than an increase. This trend was observed across nearly all economic sectors and regions.

Investment priorities for 2025 remain focused on machinery, equipment, and tools, particularly in manufacturing and construction. In the information and communication sector, companies plan to invest primarily in computer and telecommunications equipment, as well as research and development activities. Transport and storage businesses are expected to focus on upgrading their transportation infrastructure, while employee training remains a key investment area across all industries.

Outlook for the Coming Months

While February 2025 saw some improvement in business sentiment compared to January, economic uncertainty continues to weigh heavily on companies across various sectors. Rising labor costs, concerns about financial stability, and fluctuating demand are among the key challenges facing businesses.

Although the services sector, particularly information and communication, shows signs of resilience, manufacturing, construction, and wholesale trade remain under pressure. Entrepreneurs remain cautious in their outlook for the coming months, with most expecting further economic difficulties.

The investment climate remains stable but lacks strong growth momentum, indicating a wait-and-see approach among businesses. How these trends evolve in the coming months will depend on broader economic developments and policy measures to address business concerns.

Source: GUS

Hungary: Industrial production declines by 3.9% in January, while retail sales show growth

Industrial production in January 2025 fell by 3.9% compared to the same month in the previous year. The working-day adjusted index showed no variation from the unadjusted figures. However, seasonally and working-day adjusted data indicated a 0.8% increase in output compared to December 2024, suggesting a slight month-on-month improvement despite the annual decline.

A decrease in production volume was observed across most manufacturing subsections. Among the largest industrial segments, declines were recorded in the manufacture of transport equipment, electrical equipment, and food products, including beverages and tobacco. However, growth was noted in the production of computer, electronic, and optical products, providing some balance within the sector.

Despite the annual contraction, the industrial sector registered a modest recovery compared to the previous month, with adjusted indices reflecting a 0.8% rise in output. Meanwhile, the retail sector presented a contrasting picture, with sales volumes demonstrating significant growth both on an annual and monthly basis.

Retail trade in January 2025 saw a 4.7% increase compared to the same period in 2024, based on both raw and calendar-adjusted data. Sales expanded across multiple categories, with a 4.7% rise in specialized and non-specialized food shops, a 5.6% increase in non-food retailing, and a 1.9% uptick in automotive fuel retailing. When measured against the previous month, seasonally and calendar-adjusted data showed a 2.2% increase in retail sales, signaling continued consumer demand.

Food retailing, which accounts for a substantial portion of total retail trade, grew by 4.7%. Non-specialized food and beverage stores, making up 76% of the sector, saw a 5.1% rise in sales, while specialized food, beverage, and tobacco stores recorded a 3.2% increase.

Non-food retailing also experienced strong growth, with total sales volumes rising by 5.6%. The most notable increases were observed in pharmaceutical, medical goods, and cosmetics shops, where sales climbed by 9.7%. Furniture and electrical goods stores recorded a 7.8% increase, while non-specialized shops dealing in manufactured goods saw a 6.7% rise. Sales in textiles, clothing, and footwear stores increased by 4.7%, second-hand goods shops by 2.9%, and books, computer equipment, and other specialized stores by 0.3%.

E-commerce and mail-order sales, which represent 8.8% of total retail trade, expanded by 3.9%, reflecting steady consumer engagement in online shopping. The volume of sales at automotive fuel stations also rose, increasing by 1.9%.

Sales in motor vehicles and parts, which are not included in retail trade data, surged by 19% in January, highlighting a robust demand for automotive products.

In total, domestic retail sales for January 2025 amounted to HUF 1,477 billion at current prices. Specialized and non-specialized food shops accounted for 49% of total national retail turnover, while non-food retail trade contributed 35% and automotive fuel stations represented 16%.

While industrial production faced challenges at the start of the year, the steady expansion in retail sales suggests resilient consumer activity, potentially supporting broader economic stability in the coming months.

Source: Hungarian Central Statistical Office

front page info
LATEST NEWS