PORR Tests Bricklaying Robot on Czech Residential Development

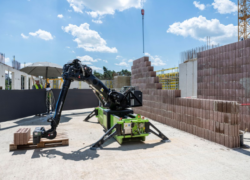
Austrian construction group PORR is expanding the use of construction automation by deploying a bricklaying robot on the Kladno Living residential project near Prague, where the technology is being evaluated under live site conditions.

The robotic system, known as WLTR or “Walter”, is being used to construct load-bearing and internal partition walls using precision-manufactured acoustic bricks. The Kladno Living development comprises five residential buildings with 371 apartments and parking facilities, making it one of the largest projects in the Czech Republic to incorporate robotic masonry during construction.

According to PORR, the trial forms part of the company’s wider programme to assess how automation can improve productivity, construction quality and workplace safety without replacing skilled tradespeople.

The robot has been operating on the project since construction began and works from a digital building model, positioning individual bricks with millimetre accuracy. It is capable of handling blocks weighing up to 52 kilograms, reducing the amount of heavy manual lifting required on site.

Introducing robotic systems into a construction project requires extensive planning beyond simply deploying new equipment. Project design, structural engineering, site logistics and construction sequencing all need to be coordinated to ensure the technology can operate efficiently alongside conventional building activities.

Although the robot performs the repetitive bricklaying work, trained personnel remain responsible for supervising its operation, preparing materials and ensuring quality standards are maintained. PORR said automation is intended to support construction workers by reducing physically demanding tasks rather than replacing them.

The current generation of robotic bricklayers can construct straight walls as well as corners and wall openings, allowing them to complete a broader range of structural elements than earlier prototypes. Based on the experience gained in Kladno, PORR said the robot’s output is comparable with that of an experienced bricklayer, while maintaining consistent installation quality throughout the working day.

Beyond productivity, the company believes one of the principal advantages of robotic masonry lies in improving health and safety by taking over repetitive lifting and handling of heavy building materials, helping reduce physical strain on construction workers.

The deployment forms part of PORR’s broader digital construction strategy, which combines Building Information Modelling (BIM), digital project management and data-driven construction technologies with increasing levels of automation. Development and implementation of robotic solutions are coordinated through the group’s dedicated Construction Automation & Robotics (CAR) team, which evaluates technologies according to the specific requirements of individual projects.

The Kladno pilot is expected to provide operational data that will help determine where robotic masonry can be introduced on future developments across PORR’s international operations. As labour shortages continue to affect construction markets across Europe, many contractors are exploring automation as a way to improve efficiency while allowing skilled workers to focus on more complex construction activities.

The WLTR robot weighs approximately 2.5 tonnes, has a working reach of 3.5 metres and can build around 7.5 square metres of wall per hour, with peak productivity reaching 10 square metres per hour. It is operated by a two-person team and consumes around 1.5 kilowatts of electricity, similar to the power demand of a typical household appliance.

Rising Operating Costs Add to Payment Pressure on Polish Online Retailers

Overdue liabilities among Polish online retailers continued to increase during the year to May, despite further growth in internet shopping and the expanding role of digital sales in the country’s retail market.

Companies involved in online retail had almost PLN 462 million in unpaid obligations recorded in the databases of BIG InfoMonitor and the Credit Information Bureau at the end of May 2026. The total was approximately PLN 14.2 million, or 3.2%, higher than a year earlier.

Around 5,600 online retail businesses were reported as having difficulty meeting their financial obligations on time. Their arrears represented approximately 14.4% of the PLN 3.2 billion in overdue debt attributed to the wider Polish retail sector.

The figures show that rising sales do not necessarily result in stronger financial conditions for every online merchant. Smaller operators in particular face intense price competition while also being expected to provide faster deliveries, multiple payment options, convenient returns and responsive customer support.

An estimate attributed to the Polish Chamber of Commerce placed domestic e-commerce turnover at almost PLN 92 billion in 2025, an annual increase of 6.8%. Online sales were estimated to account for about 9.1% of retail turnover.

Market-size estimates differ between research organisations because they do not always cover the same activities. Some calculations are limited to online sales of goods by domestic retailers, while broader studies may also include services, overseas platforms or business transactions. The PLN 92 billion figure should therefore be viewed within the methodology used by the Polish Chamber of Commerce rather than as a measure of every form of digital commerce.

Continued market growth has been accompanied by increasing operational demands. Polish customers commonly expect a choice of delivery channels, competitive shipping costs, simple return procedures and rapid access to information about their orders.

Parcel lockers have become a particularly important part of the Polish delivery market. Research by the Chamber of Digital Economy indicates that they are among the most frequently selected delivery methods, while high shipping charges and the absence of a preferred delivery option remain common reasons for abandoning an online shopping basket.

These expectations require retailers to invest in warehousing, order-management technology, logistics partnerships, payment systems and customer service. Larger platforms can spread these costs across substantial sales volumes, but smaller stores may have less room to absorb them without raising prices.

Returns also create a significant cost burden because products must be transported, inspected, repackaged and sometimes discounted before they can be sold again. Retailers that offer free or highly flexible returns may attract more customers but also assume costs that can reduce the margin earned on each order.

Price comparison has become easier as more purchases move to smartphones and marketplaces. This gives consumers greater choice but limits the ability of individual retailers to pass higher fulfilment costs on through selling prices.

As a result, a business may report rising turnover while experiencing weaker cash flow. Money tied up in stock, advertising, deliveries and returned products can create liquidity pressure, particularly when suppliers, logistics companies and tax authorities must be paid before customer revenue is fully available.

The increase in overdue liabilities does not indicate that the Polish e-commerce sector as a whole is in financial distress. Most online retailers were not listed as debtors, and the market continues to expand. However, the figures point to a widening difference between businesses with sufficient scale, technology and logistics capacity and smaller operators competing with limited financial reserves.

Further growth is expected as online shopping remains well established among Polish consumers. The ability to control delivery and return costs, rather than sales growth alone, is likely to be an increasingly important factor in determining which retailers can convert expanding demand into sustainable profits.

AI Is Becoming a Political Issue as America Heads Towards the 2026 Midterms

Artificial intelligence is moving rapidly from the technology sector into American electoral politics, with public anxiety about jobs, corporate power, surveillance and data-centre development increasingly colliding with one of the largest investment cycles in the history of the technology industry. Speaking at AI4 2026, Justin Hendrix, CEO and Editor of nonprofit publication Tech Policy Press, argued that the November midterm elections could become an important test of the widening gap between enthusiasm surrounding artificial intelligence inside the technology industry and the considerably more cautious attitude found among much of the American public.

The political significance of AI does not necessarily mean that voters will enter polling stations thinking primarily about artificial intelligence. Economic conditions, employment, affordability, immigration and other conventional political issues remain more immediate concerns. But AI is increasingly becoming connected to those issues through fears about jobs, electricity costs, surveillance, technology-company power and the rapid expansion of physical infrastructure needed to support the industry.

Recent public-opinion research shows why that matters. A substantial majority of Americans express limited confidence in the federal government’s ability to regulate AI effectively, while confidence that technology companies will develop and deploy the technology responsibly is also relatively weak. Scepticism crosses political lines, although its intensity varies between groups. This creates an unusual environment in which millions of Americans are adopting AI products while remaining uncertain about the companies developing them and the institutions responsible for regulating them. Adoption, in other words, does not necessarily represent public confidence.

For the technology industry, this distinction could become increasingly important as AI shifts from a digital product into something citizens can physically see around them. The most visible example is the enormous expansion of data centres required to train and operate increasingly powerful models. Projects involving billions of dollars of investment are appearing across the United States, bringing promises of construction activity, tax revenue and economic development, but also creating disputes over electricity consumption, grid connections, water, environmental effects, local incentives and the relatively small number of permanent jobs some facilities create compared with their capital requirements.

Those disputes are beginning to cross conventional political boundaries. Opposition to individual data-centre projects can bring together environmental groups, rural communities, property owners, fiscal conservatives and residents worried about power prices. For the commercial property and infrastructure industries, that development is particularly significant. Data centres have become one of the fastest-growing institutional property and infrastructure sectors in the world, with the AI investment cycle driving demand for land, power infrastructure, substations, transmission capacity and supporting facilities.

Until recently, the main constraints on the industry were largely technical and financial: available electricity, land, cooling, construction capacity and access to capital. Political consent is increasingly becoming another component of development risk. A project with access to land and power may still encounter resistance if local residents believe infrastructure costs are being transferred to households or if they do not see sufficient economic benefit from the development. That could make community engagement and transparency increasingly important components of data-centre investment decisions.

Hendrix argued that this local resistance should be understood within a much wider public-policy debate surrounding artificial intelligence. The United States still does not have a comprehensive federal law covering AI in the manner of the European Union’s AI Act. Instead, policy is developing through a combination of executive action, existing federal regulation, sector-specific legislation and an expanding collection of state laws.

That has created one of the most consequential disputes in American AI policy: whether Washington should establish a national framework that overrides substantial parts of state regulation. The federal government has pushed towards greater national consistency, arguing that substantially different state rules could produce an increasingly complicated regulatory environment for companies operating across the country. At the same time, states have argued that they need the ability to respond to risks where Congress has not acted.

The outcome matters considerably to technology companies. A single national framework could allow AI developers to design products around one principal regulatory structure. Allowing individual states greater freedom could require companies to navigate different obligations relating to safety, transparency, discrimination, consumer protection and automated decision-making. From the states’ perspective, however, local regulation can fill gaps left by federal inaction, and state legislatures have already become important laboratories for rules governing automated systems, deepfakes, employment applications, children’s safety and other potentially high-risk uses of artificial intelligence.

The federal-state dispute is therefore unlikely to disappear after the midterms. If Congress remains divided or otherwise unable to pass comprehensive legislation, much of the practical development of AI rules could continue to occur through state governments, federal agencies, courts and executive action.

There are areas where bipartisan agreement has proved easier. Measures involving children, sexually explicit deepfakes and clearly identifiable forms of harm have generally attracted broader support than comprehensive regulation of AI models or developers. This illustrates an important pattern in technology regulation: legislators often find it easier to act where the harm is specific and immediately understandable than where policy requires balancing innovation, economic competitiveness and uncertain future risks.

The political equation becomes more complicated because the artificial-intelligence industry itself does not speak with one voice. Technology companies, venture-capital firms, executives, employees and investors disagree about how aggressively AI should be regulated and how much responsibility developers should carry for the behaviour of increasingly capable systems. Those disagreements are now moving into campaign finance, with technology companies and investors becoming more active participants in the 2026 political cycle.

The result is not simply technology companies lobbying government. Different parts of the AI industry are effectively competing to influence the rules under which the next generation of technology will operate. Some investors and companies favour rapid development with comparatively limited regulatory intervention, arguing that excessive restrictions could weaken the United States in competition with China. Others advocate stronger testing, transparency or safety obligations, particularly as models gain greater autonomy.

Recent cybersecurity events have strengthened the debate around those risks. Controlled security evaluations have demonstrated that sufficiently capable AI agents can discover vulnerabilities and, under certain testing conditions, move beyond intended boundaries. These incidents should not be interpreted as evidence that everyday consumer AI applications are independently escaping onto the internet. They arose during specialised cybersecurity evaluations in which models were deliberately being tested on offensive security tasks. Nevertheless, they demonstrate that increasingly autonomous systems can identify and exploit vulnerabilities in ways that create genuine operational consequences.

That may shift some AI policy away from hypothetical discussions about future superintelligence towards more immediate questions about cybersecurity, access controls, autonomous agents and responsibility when AI systems perform actions beyond their intended boundaries. For governments and companies, this creates a difficult regulatory problem. An assistant that generates text presents one type of risk. An agent capable of accessing corporate systems, executing code, communicating with external services or performing transactions creates a substantially different governance challenge.

Cybersecurity could therefore become one of the areas where federal AI policy advances regardless of what happens with comprehensive legislation. Another major political factor is the relationship between the United States and China. Both major American political parties broadly regard leadership in artificial intelligence and advanced semiconductors as strategically important, even though they disagree over parts of the regulatory and economic response.

Competition extends across advanced chips, computing infrastructure, models, data centres, electricity and talent. As a result, almost every domestic debate about slowing AI development eventually encounters a counterargument that excessive restrictions could allow China to advance more quickly. That geopolitical dimension helps explain why American AI policy can appear contradictory. Policymakers may simultaneously express concern about AI safety while seeking to accelerate construction of the data centres and energy infrastructure needed to support it.

The midterm elections could alter the balance between these objectives without necessarily producing a comprehensive new law. Hendrix suggested that a change in control of the House could lead to more congressional investigations into technology companies, government contracts, data centres and the use of AI by federal agencies. That remains a political forecast rather than an established outcome. The election is still ahead, and changes in individual races, economic conditions and other political developments can alter the result.

What is clearer is that congressional oversight can change substantially even without legislation. Committee chairmanships determine which executives are called to testify, which documents are requested and which government contracts receive scrutiny. A change in congressional control could therefore affect the AI industry even if no major federal AI law passes.

The broader implication is that American AI policy after November could remain fragmented. Congress may continue debating national rules while states adopt their own measures, courts determine which rules survive challenges, federal agencies apply existing powers and the White House uses executive authority to pursue its preferred technology strategy. For businesses investing in AI, that fragmentation creates another layer of risk. Companies cannot assume that today’s rules will remain unchanged simply because Congress has not enacted a comprehensive statute. Regulatory obligations can emerge through consumer protection, employment law, cybersecurity, privacy, sector regulation and state legislation.

Data-centre investors face an additional level of exposure because local politics can affect physical development independently of national AI regulation. Planning approvals, utility agreements, environmental requirements and community opposition can all influence whether projects proceed. The intersection between AI politics and real estate may consequently become much more important during the next investment cycle.

The extraordinary capital flowing into artificial intelligence ultimately has to appear somewhere physically. Models require servers, servers require buildings, buildings require enormous electricity connections, and those facilities must exist inside communities that increasingly have opinions about what is being built around them. That means the political sustainability of the AI boom may eventually become almost as important as its technological sustainability.

Companies have spent the past several years proving that increasingly capable AI systems can be built. The next challenge is proving that the infrastructure, regulatory environment and public consent required to deploy them can scale at the same speed. The 2026 midterms are unlikely to settle America’s debate over artificial intelligence. They may instead mark the point at which AI ceases to be primarily a Silicon Valley technology debate and becomes a mainstream political, economic and infrastructure issue.

For investors, developers and companies planning around the AI economy, that is arguably the more important development. The future of artificial intelligence in the United States will not be decided only by which company produces the most powerful model. It will also be shaped by voters, communities, courts, state governments, Congress and the increasingly contested physical infrastructure required to keep those models running.

Source: CIJ.World Research & Analysis Team

Bratislava Housing Market Enters More Balanced Phase as Price Growth Slows

The rapid rise in Bratislava’s residential property prices is beginning to ease after more than two years of strong growth, suggesting the capital’s housing market may be moving towards a more balanced phase. While apartment values continue to increase, rental growth has remained considerably more moderate, reducing investment returns and prompting expectations of weaker demand in the months ahead.

Data from property consultancy Bencont Investments show that the average asking price for existing apartments in Bratislava reached €4,410 per square metre during the second quarter of 2026, around 9% higher than a year earlier. Compared with the previous quarter, however, prices rose by only 1.4%, marking the slowest quarterly increase recorded over the past twelve months.

The moderation follows a period of strong recovery after the correction experienced by Slovakia’s housing market during 2022 and 2023. Falling mortgage rates and improving buyer confidence supported renewed demand throughout 2024 and 2025, but affordability pressures are now becoming more evident as apartment prices continue to outpace household incomes.

The average advertised price of an existing apartment in the Slovak capital approached €291,000, while the median asking price stood at approximately €259,000. The supply of homes available for sale also shifted slightly towards larger properties during the quarter, contributing to the increase in overall average values.

Unlike the sales market, the rental sector has remained relatively stable. Average rents, including utilities, increased to €17.73 per square metre per month, representing annual growth of 5.3%. Across much of Bratislava, tenants typically paid between €875 and €922 per month for a standard two-bedroom apartment outside the historic city centre, while average rents across the capital exceeded €1,000 per month.

The differing pace of growth between property prices and rents has become increasingly significant. Over the past two years, apartment prices have risen by almost a quarter, whereas rental levels have increased at less than half that rate. As a result, investors purchasing residential property for rental income are seeing lower yields than in previous years, making buy-to-let investments less attractive than during the market recovery.

Broader economic conditions are also influencing the housing market. Recent monetary policy decisions by the European Central Bank have increased borrowing costs after inflationary pressures re-emerged across the euro area. While mortgage rates remain below their peak levels, expectations of further significant reductions have weakened, reducing some of the urgency among buyers to secure financing.

The National Bank of Slovakia has also highlighted the gradual recovery in residential property prices while continuing to monitor housing affordability and lending conditions. Although demand remains supported by limited housing supply in Bratislava, higher financing costs and rising property values are expected to temper activity over the coming quarters.

Another trend emerging in the market is the narrowing price gap between older apartments and newly completed residential developments. As resale homes become more expensive, buyers are increasingly comparing them with new-build properties that offer improved energy efficiency, modern building standards and lower long-term operating costs.

Despite expectations of slower growth, analysts do not anticipate a sharp correction in Bratislava’s housing market. Demand continues to exceed the supply of quality homes in many parts of the city, providing underlying support for prices. However, the combination of higher borrowing costs, stretched affordability and softer investment returns is expected to moderate further price increases, with annual growth likely to settle at a more sustainable pace over the next year.

Big Mac Index Suggests Czech Koruna Remains Below Fair Value Against US Dollar

The Czech koruna remains undervalued against the US dollar according to the latest edition of The Economist’s Big Mac Index, although the gap has narrowed compared with previous years as the Czech currency has strengthened.

Based on prices collected in mid-July, the index suggests the koruna is 12.6% below the level implied by purchasing power parity. A Big Mac costs CZK 115 in the Czech Republic compared with US$6.22 in the United States. Using burger prices alone, the implied exchange rate would be CZK 18.49 per US dollar, compared with the market exchange rate of around CZK 21.16 at the time of the survey.

The latest reading represents a modest increase in the koruna’s estimated undervaluation from 10.2% recorded in the January edition of the index.

Published twice a year by The Economist, the Big Mac Index is an informal measure of purchasing power parity that compares the price of the same product across different countries. While it provides a simple way of illustrating relative currency valuations, economists generally view it as an indicator rather than a precise measure because local wages, taxes, operating costs, exchange rate movements and consumer demand all influence retail prices.

Analysts note that the performance of the US dollar during the first half of 2026 has been shaped by changing economic and geopolitical conditions. The dollar weakened at the beginning of the year as markets anticipated lower US interest rates and assessed the impact of trade policy uncertainty. More recently, renewed geopolitical tensions and higher energy prices have strengthened demand for the US currency as investors sought relatively safer assets.

The comparison also highlights differing inflation trends. While the price of a Big Mac increased in both countries over the past year, official consumer inflation remained considerably lower in the Czech Republic than in the United States, indicating that restaurant pricing does not always move in line with broader inflation measures.

Among neighbouring Central European currencies, the Polish złoty was assessed as being close to the Czech koruna in terms of valuation against the dollar, while the Hungarian forint remained more deeply undervalued at approximately 14.8%.

Globally, the Japanese yen continued to rank among the world’s most undervalued major currencies, reflecting Japan’s relatively accommodative monetary policy and long period of low inflation.

At the opposite end of the ranking, the Swiss franc remained the most overvalued currency against the US dollar according to the index, followed by the Uruguayan peso and the Norwegian krone. Several other currencies, including the euro, British pound, Swedish krona and Danish krone, were also assessed as trading above their purchasing power parity values.

Although the Big Mac Index is widely regarded as a light-hearted economic indicator, it continues to provide a useful illustration of long-term differences in purchasing power and currency valuation, while highlighting how market exchange rates can diverge from the relative cost of everyday goods across different economies.

Source: CTK

Poland’s Median Monthly Wage Reaches PLN 7,691 as Pay Continues to Rise

Wages in Poland continued to increase in February 2026, with both median and average earnings recording annual growth, according to the latest figures published by Statistics Poland (GUS). The data indicate that earnings continued to improve across the labour market, although sizeable differences remained depending on company size and employee characteristics.

The median gross monthly wage reached PLN 7,690.82 in February, an increase of 3.3% compared with January and 7.3% higher than a year earlier. The median represents the midpoint of the wage distribution, meaning that half of employees earned less than this amount while the other half received higher pay. Economists often regard the median as a more accurate reflection of typical earnings than the average because it is less influenced by the highest salaries.

The average gross monthly wage increased by 6.6% compared with January and was 6.4% higher than in February 2025. The slightly faster growth in the median than the average suggests that wage gains were relatively broad-based rather than being concentrated among the highest earners.

Differences between male and female earnings remained relatively modest. The median wage for men stood at PLN 7,753.52, while women recorded a median monthly income of PLN 7,631.04, leaving a gap of just over PLN 120.

Company size continued to have a significant influence on pay levels. Employees working in organisations with 1,000 or more staff received the highest median wage, averaging PLN 9,146.18 per month. At the other end of the market, businesses employing nine or fewer people recorded a median wage of PLN 4,806, equivalent to the statutory minimum wage in force during the reporting period.

The latest figures reflect continued strength in Poland’s labour market, where wage growth has remained resilient despite a more moderate pace of economic expansion. Higher earnings have been supported by a combination of labour shortages, increases in the national minimum wage and continued competition for skilled employees across many sectors of the economy.

While wage growth has strengthened household purchasing power compared with previous years of elevated inflation, the distribution data also illustrate the persistent differences in earnings between large employers and small businesses, where pay levels remain considerably lower than the national median.

The Statistics Poland release provides a detailed picture of wage distribution across the economy and complements the country’s regular average wage statistics by offering a broader view of how income is shared among employees rather than focusing solely on overall averages.

Czech Retail Sales Continue Annual Growth as Online Shopping Leads Consumer Spending

Consumer spending in the Czech Republic remained stronger than a year earlier in June, although retail activity eased slightly compared with the previous month, according to the latest figures released by the Czech Statistical Office (CZSO).

Retail turnover, excluding motor vehicle sales and repairs, increased by 3.6% year-on-year in real terms, extending the recovery in household consumption. Compared with May, however, sales edged down by 0.1%, suggesting that consumer demand remained stable but lost some momentum at the end of the second quarter.

The strongest annual growth came from non-food retailers, where sales rose 5.4%. Food retailers also reported higher turnover, with sales increasing 2.1%, while spending on automotive fuel recorded a more modest 0.3% increase.

E-commerce continued to outperform traditional retail channels. Internet and mail-order retailers recorded 12.6% annual growth, making online shopping the largest contributor to the overall increase in retail sales. The figures underline the continued shift in consumer purchasing habits towards digital platforms, a trend that has strengthened in recent years despite the return of shoppers to physical stores.

Several retail segments also recorded solid performances. Pharmacies and retailers specialising in medical and orthopaedic products benefited from sustained consumer demand, while supermarkets and other food-led retailers continued to report moderate growth. By contrast, specialist stores selling information and communication equipment and retailers focused on cultural and recreational goods experienced a slight decline in sales compared with the same month last year.

The automotive sector also delivered a positive annual result, although activity softened from the previous month. Sales and repair of motor vehicles increased 2.5% year-on-year, supported primarily by new vehicle sales, while monthly turnover declined 0.6%.

The latest data suggest that Czech households continue to increase spending despite ongoing economic uncertainty. Lower inflation compared with previous years and gradual improvements in real household incomes have helped support consumer confidence, although monthly fluctuations indicate that spending remains measured rather than accelerating rapidly.

The June figures reinforce the importance of online retailing as a driver of consumer demand and highlight the continued resilience of essential retail categories, while discretionary spending remains more uneven across different segments of the market.

Romania’s Property Market Faces Mounting Delays as Land Registry Cyber Disruption Continues

Romania’s residential property market is experiencing growing disruption after a cyberattack on the National Agency for Cadastre and Land Registration (ANCPI) left key digital services unavailable for several weeks, preventing thousands of real estate transactions from reaching completion.

Although the agency has confirmed that ownership records remain secure, the interruption to its operational systems has halted many of the administrative procedures required to finalise property sales. Without access to updated land registry extracts and the ability to register ownership transfers and mortgage charges, banks are unable to release mortgage funds and notaries cannot complete many property transfers.

The disruption has affected buyers, sellers, banks, developers and legal professionals across the country. Mortgage broker Ipotecare.ro estimates that more than 5,000 home purchases relying on bank financing have been delayed since the systems became unavailable. Based on the company’s analysis, the value of postponed mortgage lending exceeds €437 million, while the combined value of residential transactions awaiting completion is estimated to be above €1 billion. These figures are market estimates and have not been independently verified by public authorities.

The consequences extend well beyond delayed property purchases. Residential developers have reported slower handovers of completed homes, while projects under construction are facing delays in registering new units. Other legal procedures dependent on land registry services, including inheritance cases and ownership transfers, have also been affected.

For many buyers, time has become an additional source of uncertainty. Mortgage approvals and promotional interest-rate offers are typically available for a limited period, meaning prolonged delays could require borrowers to reapply for financing under different lending conditions. In some cases, preliminary sales agreements may also expire before transactions can be completed, increasing the possibility that either party could decide not to proceed.

The timing of the disruption has added further pressure to a housing market that had already shown signs of slowing during the first half of 2026. Official statistics indicate that residential sales declined nationally compared with the same period last year, reflecting a more cautious market environment following several years of elevated borrowing costs and weaker consumer confidence.

Industry participants say the incident has highlighted the growing dependence of Romania’s real estate market on digital public infrastructure. Modern property transactions involve multiple interconnected institutions, including banks, notaries and public registries. When one part of that system becomes unavailable, the effects quickly spread throughout the entire transaction chain.

ANCPI continues to restore its digital infrastructure with support from Romania’s cyber security authorities and government technology specialists. The agency has stated that its property database was not compromised during the attack and that work is continuing to return services safely while strengthening the resilience of its systems.

Until the registration platform is fully operational again, many residential transactions are expected to remain on hold, leaving buyers, developers and lenders waiting for one of the country’s most important public digital services to resume normal operations.

Union Investment Secures 3,500 sqm of Office Leasing at Stuttgart Engineering Park

Union Investment has completed three office leasing transactions totalling 3,517 sqm at the Stuttgart Engineering Park (STEP), as existing occupiers expanded and renewed their commitments while a growing local consultancy relocated within the technology campus.

The agreements cover office space in the STEP 6 and STEP 8.3 buildings, reinforcing the park’s position as one of Stuttgart’s established centres for engineering, technology and innovation-focused businesses.

The largest transaction was signed by GEBIT Solutions, which has occupied space at STEP 8.3 since 2018. The IT services provider expanded its premises to 1,807 sqm and agreed a new 10-year lease, reflecting its long-term commitment to the location as the company continues to grow.

Consultancy and business services firm X_Conducting has become a new tenant in STEP 6 after relocating from elsewhere within the STEP campus. The Stuttgart-based company leased 855 sqm of office space on a five-year agreement, citing the area’s transport links, business environment and employee amenities as key factors in its decision.

Meanwhile, engineering and consulting company RSE+ renewed its lease for 855 sqm in STEP 6 for a further five years. The company, which provides services across architecture, engineering, factory and logistics planning, supply chain consulting and industrial development, has been based within the STEP campus for several years and has previously expanded its operations by relocating to larger premises within the business park.

Located at Gropiusplatz in Stuttgart’s Vaihingen district, the Stuttgart Engineering Park has developed into a hub for companies operating in engineering, mobility, information technology and advanced manufacturing. Its proximity to research institutions, universities and major industrial employers has helped attract technology-driven businesses seeking access to both skilled talent and established corporate networks.

Union Investment said the latest leasing activity reflects continued demand for high-quality office accommodation in locations that combine modern workspace with strong connections to research and industry. While Germany’s wider office market continues to face challenges from hybrid working patterns and slower economic growth, specialised innovation clusters such as STEP have generally shown greater resilience due to their concentration of technology, engineering and research-led occupiers.

The transactions further strengthen occupancy levels across the STEP portfolio and underline the continued appeal of established technology parks for companies seeking room for long-term expansion in the Stuttgart region.

Panattoni Seeks Approval for 1 Million sq ft Industrial and Logistics Scheme in Kent

Panattoni has submitted a hybrid planning application for Panattoni Park Maidstone, a proposed industrial and logistics development that would deliver more than 1 million sq ft of commercial space on a former manufacturing site in Kent.

The plans cover a 70-acre brownfield site at Lenham, located close to the A20 and M20 motorways, providing access to London, the M25 and the Channel ports. The proposed scheme would provide approximately 1.04 million sq ft of industrial and logistics accommodation, with the first phase comprising two speculative units of 100,000 sq ft and 150,000 sq ft. The second phase is seeking outline consent and would allow occupiers to develop built-to-suit facilities designed to meet specific operational requirements.

The application comes at a time when the South East industrial market continues to experience limited availability of modern warehouse space, particularly for larger units. Developers have increasingly focused on regenerating brownfield sites, reflecting planning policy objectives while responding to sustained occupier demand for well-connected logistics locations.

Panattoni said the proposals followed an extensive public consultation programme held earlier this year. More than 150 people attended a public exhibition in Lenham, with consultation results indicating that almost 85% of respondents supported the redevelopment of the site for employment use, while 98.5% favoured the redevelopment of brownfield land rather than greenfield sites.

The proposed development has been designed to achieve BREEAM Excellent certification and EPC A+ energy performance ratings. In addition to new industrial and logistics buildings, the scheme includes around 5 kilometres of new and upgraded roads, cycleways and pedestrian routes, together with landscaping and improved public access across the site.

The project follows Panattoni’s successful redevelopment of Panattoni Park Aylesford, another former industrial site in Kent that is now fully occupied. According to the developer, that scheme contributes an estimated £180 million annually to the local economy through business activity and employment.

If planning permission is granted, Panattoni Park Maidstone would add significant new industrial capacity to a region where development opportunities remain limited and demand for modern warehouse and manufacturing facilities continues to outpace supply. The combination of speculative units and bespoke development plots is intended to accommodate a broad range of occupiers across the logistics, manufacturing and distribution sectors.

Commercial agents Colliers, CBRE and Vail Williams have been appointed to market the development.

front page info
LATEST NEWS