Poland seeks to strengthen industrial investment appeal with extended tax support

Poland is moving ahead with changes to its investment incentive system that could give companies as long as 20 years to use tax benefits attached to qualifying projects. The government-backed legislation was submitted to the Sejm at the beginning of October and could strengthen Poland’s position as it competes for major industrial investment across Central and Eastern Europe.

Under the proposed framework, new investment-support decisions could remain valid for between 15 and 20 years, depending on where a project is located. This compares with periods generally ranging from 12 to 15 years under the existing system. The additional time could be particularly valuable for manufacturers undertaking projects with high upfront costs and long periods before reaching full production.

The reform would also change how companies determine the income connected with supported investments. The intention is to make the system easier to apply where businesses expand existing Polish operations rather than establishing entirely separate facilities. This could benefit manufacturers adding production lines, extending plants or introducing new technologies at established sites.

Large investments would face additional scrutiny. Projects capable of receiving at least PLN 40 million in public assistance would require an assessment from Poland’s National Revenue Administration before support could be granted. The threshold was increased from a lower level considered during an earlier stage of the legislative process.

Employment conditions would also be modified, including limits on how far companies can subsequently reduce commitments made when obtaining support. At the same time, the proposed framework would better accommodate investment in industrial automation, recognising that modern factories can involve substantial spending on machinery, robotics and technology without creating employment on the scale traditionally associated with large manufacturing projects.

For the commercial property market, the changes are significant because incentives form part of the calculations companies make when selecting locations. Poland competes with other CEE countries for factories and production expansions, with businesses weighing tax support alongside labour availability, energy costs, transport infrastructure, development land and access to suppliers.

Regional differences will continue to play an important role. Poland’s investment-support framework varies according to location and the characteristics of individual projects, helping regions outside the country’s strongest industrial centres compete for corporate investment. Longer support periods could therefore influence where future factories and related supplier operations are established.

The reform comes as Poland approaches the end of its historic Special Economic Zone system, with remaining SEZ permits due to expire at the end of 2026. The nationwide Polish Investment Zone will consequently become the country’s central mechanism for supporting new investment. The legislation remains subject to parliamentary approval, but its direction points towards longer investment horizons and greater recognition of increasingly automated, capital-intensive industrial projects.
Rex Concepts secures half of 2027 CEE restaurant sites as expansion accelerates

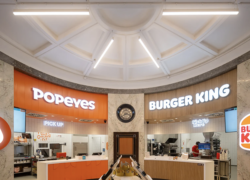
Rex Concepts is building a substantial pipeline of new restaurant locations across Poland, Czechia and Romania as it prepares to accelerate the expansion of its Burger King and Popeyes networks. The company plans more than 80 company-operated openings in 2027, with agreements already completed for around half of the required locations.

The group has opened 44 restaurants since the beginning of 2026, taking its directly operated network to 203 locations. Rex expects to exceed 70 openings by the end of this year, with agreements completed and construction underway for the remaining restaurants included in the 2026 programme.

The expansion is creating demand across several segments of the CEE retail property market. Rex operates restaurants in shopping-centre food courts and conventional retail units as well as standalone drive-through properties. Drive-throughs have accounted for 14 of this year’s 44 openings, increasing the company’s requirement for well-connected plots around retail parks, major roads and densely populated urban areas.

Rex is now concentrating on securing the remainder of its 2027 pipeline. With approximately half of next year’s locations already contracted, maintaining the planned pace of more than 80 annual openings will require another significant round of leases and site agreements over the coming months.

The company sees considerably more room for expansion beyond the current programme. Its assessment of Poland, Czechia and Romania indicates potential for around 1,500 quick-service restaurant locations across the three countries over the longer term. This represents estimated market capacity rather than a portfolio of sites currently controlled by Rex.

Its longer-term strategy envisages growing the network to around 850 restaurants by the end of 2032, including more than 700 directly operated locations alongside restaurants managed by franchise partners. That would require sustained property expansion across all three markets for several years.

Opening a new restaurant typically requires investment of approximately PLN 3 million to PLN 3.8 million, according to information previously provided by the company. The scale of the programme therefore represents a significant capital commitment alongside the property requirement associated with finding, developing and fitting out dozens of new locations each year.

For CEE landlords and developers, Rex’s expansion adds another active occupier to the region’s retail market. Shopping centres remain important to the group’s network, while the growing number of drive-through restaurants creates opportunities for retail parks and roadside developments where accessibility, visibility and vehicle traffic can support standalone food concepts.

With its 2026 pipeline already contracted and a substantial share of the following year’s locations secured, Rex is moving from rapid expansion towards a multi-year property programme. Poland, Czechia and Romania will remain at the centre of that rollout as the company builds the physical network required to support its longer-term growth ambitions.

ZEITRAUM strengthens Polish platform as it targets 5,000 living-sector places

ZEITRAUM has appointed Renata Kusznierska to lead its Polish business as the student housing and serviced-apartment operator prepares for a significant expansion of its Central European portfolio.

As Head of Poland, Kusznierska will oversee the company’s existing properties in Warsaw and Kraków, including their operational performance, leasing and service standards. She will also be involved in evaluating potential acquisitions, developments and new operating opportunities as ZEITRAUM looks to increase its presence in Poland’s largest university cities.

Poland is currently the company’s biggest market. ZEITRAUM operates student accommodation at Solec 22 in Warsaw and Koszykarska 33 and Racławicka 58 in Kraków. The three locations provide a combined 820 student places, according to the company, and the properties are independently listed in ZEITRAUM’s current portfolio.

The latest addition is Racławicka 58, which opened in Kraków in 2025. The mixed-use property combines 289 student places with 182 serviced apartments, allowing the operator to accommodate both academic-year demand and other forms of temporary urban accommodation. Independent student housing data also records 289 beds at the property.

Kusznierska brings more than 20 years of property-sector experience, including senior positions in student and professionally managed residential accommodation. Before joining ZEITRAUM, she worked with Solida Capital, Yugo and CRM Students, following earlier roles at DTZ, Cushman & Wakefield, Savills and Carrefour Property.

Her appointment comes as ZEITRAUM prepares to increase the scale of its business. The company currently operates seven student residences and around 300 serviced apartments across Poland and Czechia, representing more than 2,000 places. It plans to add approximately 1,000 places within the next two to three years and is targeting a portfolio of around 5,000 within five years. These figures represent the company’s growth objectives rather than a committed development pipeline.

Poland is expected to account for an important share of that expansion. ZEITRAUM is examining opportunities particularly in Warsaw, Wrocław, the Tri-City and Poznań, focusing on markets with large student populations and limited professionally managed accommodation.

The Polish PBSA sector continues to attract operators and investors as new projects attempt to close the gap between the country’s university population and purpose-built accommodation. Recent market reporting confirms that private supply has continued to expand, with new properties opening in Warsaw and Kraków during 2025, including ZEITRAUM’s Racławicka project.

ZEITRAUM is also preparing to expand beyond its existing Polish and Czech operations. The company is due to operate a serviced-apartment development of more than 300 places in Bratislava together with Lucron, while Germany and Switzerland are being considered as additional markets.

The expansion strategy places greater emphasis on operating scale as well as property growth. Strengthening the Polish management team gives ZEITRAUM dedicated local leadership as it seeks new projects while maintaining occupancy, operating costs and service standards across its existing portfolio.

India’s Hotel Expansion Is Outrunning the Geography of Investment Capital

India’s hotel market is entering a new investment cycle, supported by rapidly expanding domestic travel, rising room rates and the spread of branded accommodation beyond the country’s largest cities. Hotel transactions are increasing and institutional investors have become more active, but capital is not following the industry’s geographical expansion at the same speed. The emerging divide is between where hotel operators see future demand and where investors are currently most comfortable owning the underlying real estate.

Domestic travel provides a powerful foundation for the sector. India recorded approximately 4.29 billion domestic tourist visits in 2025, an increase of 45.6% from the previous year. International travel followed a different trajectory. International tourist arrivals, which include both foreign visitors and non-resident Indians, reached around 20.1 million in 2025, slightly below 2024. Foreign tourist arrivals alone declined to approximately 9.15 million. India’s current hotel expansion is therefore being supported primarily by the scale and growth of its domestic travel market rather than depending on a complete recovery in overseas tourism.

Hotel operators are responding with aggressive expansion. More than 51,600 branded hotel rooms were signed across 424 agreements during 2025, with approximately 71% of those rooms located in Tier-II and Tier-III cities. The expansion reaches well beyond traditional business centres and includes leisure destinations, pilgrimage locations, industrial cities, airport corridors and emerging regional commercial hubs. Other industry research similarly shows that the majority of newly signed branded rooms are now being planned outside India’s Tier-I markets.

Investment capital is growing quickly but remains more concentrated. Hotel transactions reached approximately $567 million across 28 deals in 2025, up 67% from the previous year. Institutional and private-equity investors represented the largest individual buyer group, accounting for around 35% of transaction value. Momentum continued into 2026, with approximately $185 million of hotel transactions recorded during the first quarter, 58% higher than in the equivalent period a year earlier. JLL expects annual hotel investment volumes could approach $1 billion by 2028 if the market continues to deepen.

The composition of transactions also reveals where investors are most comfortable taking risk. Operational hotels accounted for approximately 69% of 2025 investment volume, while properties under construction represented around 18% and land about 13%. Luxury and upscale hotels together attracted roughly 83% of transaction value. Investors are therefore concentrating heavily on established or relatively advanced assets with visible operating performance rather than taking development exposure across the entire hotel pipeline.

The geographical difference is even more striking. Although Tier-II and Tier-III cities accounted for around 71% of branded rooms signed in 2025, they received only about 40% of hotel investment transaction value. Tier-I markets continued to capture approximately 60% of capital. Hotel companies can enter a new city relatively quickly through management or franchise agreements without purchasing the property, while institutional investors acquiring the real estate need clear ownership, reliable financial reporting, sufficient scale, established operating performance and a credible future exit. This allows hotel brands to move into emerging destinations considerably faster than property capital.

Another constraint is the availability of hotels that investors can actually acquire. Strong trading conditions can encourage owners of successful properties to retain them, limiting the number of institutional-quality assets coming to market. India’s fragmented ownership structure can further reduce the investable pool, particularly where smaller properties lack the financial records, governance standards or ownership structures expected by institutional buyers. Development and operating requirements also vary between states and cities, adding another layer of due diligence for investors entering less familiar markets.

India’s next hotel investment cycle may therefore depend less on whether capital is available and more on whether the property market can produce enough suitable assets for that capital to buy. Tourism demand and hotel brands are already moving deep into regional India, while institutional ownership remains concentrated in a smaller universe of premium and established properties. If more hotels in Tier-II and Tier-III markets mature into professionally operated, transparent and tradeable assets, institutional investment could begin to follow the geographical transformation already taking place across India’s hospitality industry.

Source: © CIJ.World India Research & Analysis Team

Cosmopolis adds A3 access as major Bucharest residential expansion advances

Cosmopolis has added a new road connection towards the A3 Bucharest–Ploiești motorway, improving access to the large residential development in northern Ilfov as Opus Land Development moves forward with its next phase of expansion.

The new route was developed with Ștefăneștii de Jos municipality and represents the third main road connection serving the community. Municipal investment documents confirm works for a link between Cosmopolis and the A3 as well as a separate project connecting local public roads with the motorway’s western exit infrastructure.

Residents can now choose between the new A3 route, the existing connection with Bucharest’s DNCB ring road and the road towards Tunari. Cosmopolis was already located approximately 800 metres from the Bucharest–Ploiești motorway, but the latest infrastructure provides a more direct connection with the motorway network.

Access to the A3 also improves the development’s connection with the A0 motorway being built around Bucharest. As further sections of the orbital motorway become operational, the network is intended to provide faster links between the principal motorway corridors around the Romanian capital while diverting through-traffic away from the existing urban road system.

The additional access comes as Opus Land Development advances Cosmopolis Evolia, a major extension of the existing residential district. The project covers approximately 270,000 sqm of land adjoining Cosmopolis and is planned for development over roughly ten years, with an estimated investment exceeding EUR 200 million.

The initial Evolia construction programme comprises around 250 houses and 200 apartments. Earlier this year, the developer reported that more than 60% of the houses in the first phase had already been contracted, with the first homes scheduled for delivery during 2026. The longer-term plan envisages approximately 350 residential units being completed annually.

The new road is therefore being introduced ahead of a substantial increase in the number of homes adjoining the established Cosmopolis community. Alongside residential construction, the wider development already includes retail, education, healthcare and leisure facilities, increasing the importance of connections between the district, Bucharest’s northern employment areas and the regional motorway network.

For large residential developments around Bucharest, transport capacity is becoming an increasingly important component of expansion planning. In the case of Cosmopolis, the new A3 route provides additional road capacity before the next generation of housing is fully occupied, linking further residential growth with improvements to the surrounding transport infrastructure.

Japan’s Property Market Enters a New Financing Reality

Japan’s real estate market is moving into a financial environment that few active investors have experienced during their careers. Interest rates are rising, government bond returns have climbed sharply and the era in which exceptionally cheap capital could almost be taken for granted is coming to an end. Despite this shift, property investment, rents and land values have remained remarkably firm.

The Bank of Japan raised its policy rate to 1.25% in September 2026, reaching its highest level in more than three decades. The change has been even more visible in the bond market. The yield on 10-year Japanese government debt has moved above 3%, while longer maturities have exceeded 4%.

For real estate, this matters because government debt provides a reference point against which property returns are assessed. When government bonds produced very little income, investors could accept comparatively low yields on Japanese buildings. As returns from government securities increase, that calculation becomes more difficult.

The adjustment has yet to trigger a broad retreat from property.

Commercial real estate transactions reached around ¥1.12 trillion during the second quarter of 2026, 17% more than a year earlier. Overseas investors have also remained active, demonstrating that international capital has not been deterred by Japan’s changing interest-rate environment.

At the same time, some of Tokyo’s most valuable buildings continue to trade on exceptionally tight returns. Expected yields for prime offices in Otemachi have been around 3.1%, leaving little difference between the initial income available from top-quality property and the return available from benchmark government debt.

That narrowing gap is becoming one of the most important issues facing Japan’s investment market.

Property carries risks that government debt does not. Buildings require management and capital expenditure, tenants can leave and values can fluctuate. Investors normally expect additional returns to compensate for those risks. If government bond yields remain elevated, pressure could eventually build for property prices to adjust or for real estate income to grow faster.

For the moment, rising rents are helping to support valuations.

Tokyo’s office recovery has strengthened during 2026, particularly in high-quality buildings in central locations. Limited availability and healthy occupier demand have allowed landlords to increase rents, improving the income generated by existing properties.

This is important because stronger rental income can partly absorb higher borrowing costs. Investors may therefore remain willing to purchase buildings at relatively high valuations when they believe rents have further room to increase.

The same resilience can be seen elsewhere in the market. Prime residential property in Tokyo continued to record strong price growth during the first half of 2026, supported by limited supply and demand from both domestic and international buyers.

Official land-price data also show that the wider property cycle remains positive. Nationwide land values increased for a fifth consecutive year in 2026, with gains extending across residential, commercial and industrial locations. Tokyo and Osaka continued to benefit from particularly strong demand, while tourism and redevelopment supported selected regional markets.

The result is an increasingly unusual market.

Japan now combines significantly higher interest rates with rising property values, growing rents and substantial investment activity. These conditions can coexist while property income continues improving, but they also increase the importance of asset selection.

Buildings capable of generating rental growth should be better placed to withstand higher financing costs. Modern offices in supply-constrained districts, well-located residential properties, successful hotels and strategically positioned logistics facilities may continue attracting capital even if monetary conditions tighten further.

Older or weaker assets could face a more difficult adjustment. Buildings requiring significant investment, properties in locations with limited rental growth and assets carrying large amounts of debt may become increasingly exposed as financing costs rise.

Refinancing is likely to be particularly important.

Many property loans were arranged when Japanese interest rates were exceptionally low. As those facilities mature, borrowers will increasingly have to refinance under very different conditions. A property that remains operationally successful could therefore produce a lower return to its owner simply because the cost of servicing its debt has increased.

This could gradually create a wider separation between investors with strong balance sheets and those whose strategies depended heavily on inexpensive leverage.

Banks will play an important role in determining how quickly that adjustment occurs. Real estate lending has remained available, helping maintain transaction liquidity. However, continued increases in policy rates would eventually feed through to lending terms and influence how much investors are prepared to borrow and pay for assets.

Japan is therefore approaching a more revealing stage of its property cycle.

The market has already demonstrated that the end of ultra-low rates does not automatically translate into falling real estate prices. Strong rental growth, scarce supply in important locations and continued investor demand have provided significant support.

The bigger test comes if borrowing costs continue rising while rental growth begins to moderate.

Under those circumstances, investors would have to decide whether current property valuations still offer sufficient compensation compared with increasingly attractive returns elsewhere in the financial markets.

After decades dominated by exceptionally inexpensive money, Japan’s real estate market is beginning to operate under a different set of rules. The transition may not end the property cycle, but it is likely to expose a growing divide between assets supported by genuine income growth and those whose valuations relied more heavily on cheap financing.

That distinction could become one of the defining themes of Japanese real estate in 2027.

Source: © CIJ.World Japan Research & Analysis Team

Czech property funds gain investment power as retail capital inflows continue

Czech real estate funds are accumulating greater investment capacity as retail investors continue committing new money to property strategies, reinforcing the growing importance of domestic capital in the Czech and wider Central European real estate markets.

INVESTIKA realitní fond illustrates the scale of the trend. At the end of August 2026, the fund had approximately CZK 29.8 billion of fund capital and total assets of CZK 30.6 billion. Its portfolio comprises 65 properties across six European countries, with Poland and the Czech Republic representing its two largest markets.

Fresh capital continued to enter the fund during September. Its principal CZK class recorded subscriptions of approximately CZK 311.6 million and redemptions of CZK 172.5 million, producing net inflows of about CZK 139 million. Another CZK-denominated investment class added more than CZK 86 million on a net basis, while the euro class received around EUR 419,000 more in subscriptions than was withdrawn.

The pattern has persisted for several months. Net inflows into the main CZK class reached approximately CZK 147 million in August, CZK 144 million in July and CZK 129 million in June. Across those four months alone, the class therefore attracted more than CZK 550 million of net new capital.

INVESTIKA’s portfolio is predominantly invested in commercial real estate. Offices account for close to half of its property exposure, followed by logistics and retail. Poland represents the largest geographical concentration, while Czech assets form the second-largest part of the portfolio.

Other retail-oriented Czech property funds have also expanded. NEMO reported assets of approximately CZK 4.6 billion in August, while ATRIS Realita had assets of around CZK 7.4 billion. Wider market data published during 2026 indicate substantial growth in the amount of capital held by Czech retail property funds.

The increase is relevant beyond the fund-management industry because these vehicles have become an important source of acquisition capital. As their assets grow, Czech managers have greater capacity to acquire larger offices, shopping centres, logistics facilities and mixed commercial portfolios at home and elsewhere in Central Europe.

This coincides with a broader shift in the ownership of regional commercial property. Domestic investors have taken an increasingly prominent role in transactions, including acquisitions from international institutions adjusting their Central European portfolios. Capital collected through investment funds is one component of that change alongside Czech private investment groups, family capital and institutional investors.

For individual investors, collective property funds offer exposure to portfolios that would otherwise require substantially greater amounts of capital to access directly. For the real estate market, however, the cumulative effect is considerably larger: thousands of relatively small investments can ultimately provide managers with billions of crowns for property acquisitions.

Continued inflows therefore have implications for competition over investment assets across Central Europe. As Czech property funds become larger and maintain access to fresh retail capital, their ability to participate in significant regional transactions is also increasing.

INVESTIKA’s latest figures provide another indication of this transformation. What begins as household investment flows is increasingly being converted into institutional-scale capital capable of influencing ownership patterns across the Central European commercial property market.

CEE growth model faces reset as energy costs, labour shortages and AI reshape investment

Central and Eastern Europe is facing a more demanding economic environment as weaker European demand, high energy costs and demographic pressures challenge some of the advantages that powered the region’s expansion over the past two decades. At the same time, artificial intelligence and automation are opening another route to growth by allowing companies to increase output without relying on continually expanding workforces.

The World Bank’s latest assessment of Europe and Central Asia, released on 6 October, points to weaker conditions across the region as businesses contend with uncertainty and a less supportive European economy. The slowdown is particularly relevant for Central Europe, where manufacturing, exports and investment remain closely connected to demand from Germany and other major EU economies.

The European Commission is also expecting subdued expansion this year, forecasting growth of around 1.1% for the EU and 0.9% for the euro area. Energy remains an additional concern. Central and Eastern European economies are particularly exposed to changes in electricity and fuel costs, affecting household spending as well as the competitiveness of manufacturing and other energy-intensive industries.

For commercial real estate, these economic pressures are changing how companies evaluate locations. Industrial occupiers increasingly have to consider not only rents, transport connections and labour costs but also electricity availability, grid capacity and the long-term operating efficiency of buildings. These factors are becoming especially important for advanced manufacturing, logistics, data centres and technology-related investments.

Labour represents another constraint. Ageing populations and shrinking working-age cohorts mean that the region cannot depend indefinitely on expanding employment to generate economic growth. Employers have already responded through automation and digitalisation, and the next stage could involve much wider adoption of AI across manufacturing, services, logistics and corporate operations.

World Bank research indicates that greater use of digital technologies and AI-enabled tools could generate meaningful productivity improvements in countries including Poland, Romania, Bulgaria and Croatia. The significance for CEE is considerable: companies able to produce more with the same or smaller workforces could partially compensate for worsening demographics while maintaining the region’s competitiveness as wages converge towards Western European levels.

However, the transition also creates a new infrastructure requirement. AI needs computing power, and computing power requires electricity, data centres and high-capacity digital networks. Greater automation in factories similarly depends on reliable energy, modern buildings and skilled technical employees. Technology therefore does not remove CEE’s infrastructure challenges; in many cases it makes solving them more urgent.

That could gradually alter investment patterns across the region. Cities and industrial locations offering available power, strong grids, digital connectivity and skilled labour may gain an advantage over locations competing primarily through inexpensive land and lower wages. For developers, access to electricity could increasingly become as important as motorway access was during the previous generation of logistics and industrial expansion.

The shift also creates opportunities across real estate. Demand for data centres and supporting infrastructure is expanding the relationship between property and energy, while manufacturers investing in automation require increasingly sophisticated production facilities. Modern offices may also benefit as companies seek buildings capable of supporting technology-intensive operations while competing for a smaller pool of highly skilled workers.

CEE is therefore confronting more than a temporary economic slowdown. The region’s traditional growth formula, competitive labour, manufacturing investment, European integration and nearshoring, is evolving. Energy security, infrastructure capacity and productivity are becoming more important determinants of where capital is deployed.

AI will not remove the economic pressures facing Central and Eastern Europe, but it could help companies operate more productively in an increasingly labour-constrained market. For property investors and developers, the resulting transition could be equally important: the next generation of CEE investment may increasingly follow power, connectivity and technological capacity rather than cheap labour alone.

Erste completes REICO merger and consolidates CEE real estate funds

Erste Asset Management has completed the absorption of REICO’s investment management operations, bringing a property fund business with more than CZK 55 billion of assets into its wider Czech asset management platform.

The transaction took effect on 1 October 2026 and follows REICO’s transfer into Erste Asset Management ownership at the end of 2024. While REICO continued to operate as a separate investment company following that earlier change, the latest step completes its corporate integration into the Erste structure.

Management responsibilities for REICO NEMOVITOSTNÍ, REICO LONG LEASE, REICO EPB I and Dostupné bydlení ČR SICAV have moved to Erste Asset Management. The specialist real estate team responsible for the portfolios has transferred as part of the process.

The funds themselves remain separate investment vehicles and their underlying strategies have not been combined. For investors, the main change is therefore at management-company level rather than within the individual portfolios. Erste has indicated that continuity will be maintained in the operation of the funds.

REICO has been active in property investment since 2006 and has developed a portfolio extending beyond the Czech Republic into Poland and Slovakia. By late 2025, the business reported more than CZK 55 billion under management, giving the integration significance beyond a routine corporate restructuring.

The transaction also brings together different parts of Erste’s investment activities in the Czech market. Its Czech asset management operation reported approximately CZK 302 billion under management at the end of 2025, before REICO’s full integration. Real estate investment expertise will now sit directly alongside the group’s broader fund management activities.

REICO will nevertheless remain visible to investors. The name continues to be used for its established property funds, meaning the completion of the merger does not amount to the disappearance of the REICO investment brand. What has ended is REICO’s position as a standalone management company.

The move reflects a wider trend towards consolidation in European asset management, where larger financial groups are bringing specialist investment businesses onto common platforms while retaining established product identities. In Erste’s case, the transaction creates a more unified structure for managing a sizeable Central European property investment business covering commercial real estate and residential strategies.

Cybersecurity enters an AI arms race as businesses confront new vulnerabilities

Artificial intelligence is pushing corporate cybersecurity into a new phase as companies face the challenge of protecting AI systems while simultaneously adopting the technology to strengthen their own defences. Research published during 2026 points to rising security budgets and greater use of automation, but also significant weaknesses in data protection, governance and preparedness.

The scale of concern is evident in PwC’s latest Global Digital Trust Insights research, covering 3,934 business and technology leaders across 71 countries. Half of security leaders placed attacks directed at AI systems among the five cyber threats their organisations are least prepared to manage. Cloud-related risks were selected by 40%, third-party breaches by 34% and ransomware by 33%.

The findings are consistent with the World Economic Forum’s Global Cybersecurity Outlook 2026, which found that 94% of respondents expected AI to be the most important factor changing cybersecurity. The proportion of organisations assessing the security of AI tools had also risen from 37% to 64%, suggesting that businesses are beginning to apply more scrutiny to technology that has often been deployed faster than security frameworks surrounding it.

The nature of the threat is also changing. PwC found that 53% of security and risk leaders placed autonomous botnets among the AI-enabled attacks for which they felt least prepared. Attempts to manipulate AI models through their inputs and efforts to compromise them through corrupted training data were each selected by 52%. These results measure executives’ assessment of preparedness rather than the prevalence of such attacks, but they indicate where security teams expect some of their most difficult future challenges to emerge.

Microsoft’s 2026 threat research provides evidence that AI is already becoming more important to attackers. The technology is being applied across activities including reconnaissance, vulnerability discovery, social engineering and malware development, potentially allowing parts of an attack to be completed faster and at greater scale. However, complex cyber operations continue to require substantial human involvement, meaning fully autonomous sophisticated attacks should not yet be regarded as the dominant threat.

Businesses are increasing spending in response. PwC found that 84% of security and finance leaders expect cybersecurity budgets to rise during the coming year, compared with 78% in the previous survey. AI ranked among the main investment priorities for 58% of security leaders. Despite that increased spending, only 39% of security, risk and operations executives said their organisations had fully established and integrated continuity arrangements specifically addressing cyber disruption.

AI is meanwhile becoming an increasingly important defensive technology. Half of PwC’s security respondents included threat detection and alerting among their five main priorities for applying AI to cyber defence over the next 12 months. Fraud detection followed at 43%, phishing detection and response at 42%, while incident prioritisation and vulnerability scanning were each selected by 41%. IBM’s 2026 research provides a financial dimension to the trend, finding substantially lower average breach costs among organisations making extensive use of AI and automation in security.

Companies remain much less willing to hand complete control to machines. Only 22% of PwC respondents would allow AI agents to execute defensive actions without human approval. Another 38% would permit limited autonomy, while 36% preferred people to remain responsible for execution with AI providing assistance. Concerns about reliability, accountability and the ability to explain automated decisions are therefore limiting how far businesses are prepared to automate security operations.

The underlying quality of corporate data controls could become an equally important constraint. PwC found that organisations had fully implemented an average of only three of seven surveyed data-risk measures across their businesses. Enterprise-wide data classification was in place at 49% of respondents and comprehensive controls against information leaving through important channels at 48%. Only 5% reported full implementation of all seven measures.

Shortages of specialist expertise are also creating opportunities for managed-security providers. AI was among the five leading areas for external cyber services for 53% of relevant PwC respondents, followed by cloud security at 49%, data protection and trust at 42% and threat management at 39%. The figures suggest that businesses increasingly expect outside specialists to supplement internal teams in areas where technology and risks are changing particularly quickly.

Beyond AI, companies are beginning to prepare for another technological transition. PwC found that 21% were implementing quantum-resistant security measures and 31% were testing or piloting them. Another 34% were investigating the issue without having moved into implementation, indicating that preparations to replace vulnerable cryptographic systems remain at an early stage for much of the corporate sector.

The result is an emerging contest in which AI is accelerating both sides of cybersecurity. Greater investment and more sophisticated defensive systems can help companies identify threats sooner, but adding AI agents and models to corporate infrastructure also creates systems that themselves require protection and oversight. The decisive issue for businesses may therefore be less about how quickly they adopt AI than whether security, data governance and human controls can develop at the same pace.

front page info
LATEST NEWS