YIT Begins Construction on Kalevala Residential Development in Brno

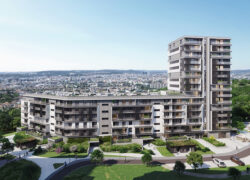
YIT has launched the first phase of its new Kalevala residential project on the border of Brno’s Vinohrady and Židenice districts. The development, created in partnership with RSJ Investment Group, will transform a former brownfield site into a modern urban neighbourhood with a focus on sustainability and community living.

The initial stage, named Ukko, will include 196 apartments and studios along with ground-floor commercial space. Construction is already underway, with completion planned for the second quarter of 2028. The full Kalevala complex will be developed in nine phases, delivering approximately 750 housing units by mid-2031.

The project aims to revitalise a five-hectare site into a mixed-use district integrating housing, services, and public areas. Energy-efficient design features will include photovoltaic panels, green roofs, and rainwater retention systems, complemented by landscaped areas and tree-lined paths.

“This is our first project in South Moravia, and we want to create a new residential district that connects the Vinohrady and Židenice areas in a natural way,” said Marek Lokaj, CEO of YIT Stavo. “Our focus is on sustainable housing that combines modern urban living with environmental awareness.”

Lukáš Musil, board member of RSJ Investment Group, added that Brno’s location and growing demand make it a key market for residential development. “We want to create a place where people will not only live but also spend time and build community.”

YIT has opened a new Brno office at Magnum Palace to manage the project and future regional acquisitions. The team will oversee construction and sales while expanding YIT’s presence beyond Prague in line with the company’s long-term growth strategy.

The Ukko building — named after the Finnish god of thunder — will feature apartments ranging from 27 to 105 square metres, most with balconies, terraces, or small gardens. Amenities will include parking, storage rooms, stroller and bike facilities, and a dedicated space for washing bicycles and pets. Selected units will offer air conditioning and underfloor heating.

Architecturally, Ukko will consist of two connected sections — a seven-storey base and a fifteen-storey tower — designed to follow the area’s natural slope. The tower will serve as a visual focal point and provide communal areas for residents.

Located between Viniční, Šedova, and Líšeňská streets, the site offers proximity to schools, healthcare, shops, and public transport links. The Brno-Židenice train station is within five minutes, and nearby green spaces such as Bílá hora and Stránská skála provide opportunities for recreation.

When completed, Kalevala will add a new chapter to Brno’s ongoing urban renewal efforts — creating a functional, energy-efficient neighbourhood designed for long-term residents and families.

Kamco Invest Strengthens Saudi Ties During FII 2025 Week

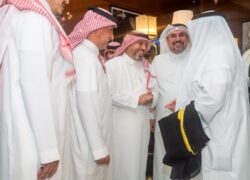
Regional investment firm Kamco Invest marked its growing presence in the Saudi market with a high-level client reception in Riyadh that coincided with the Future Investment Initiative (FII) 2025, held from 27 to 30 October under the patronage of the Saudi leadership.

The gathering brought together leading figures from Kuwait and Saudi Arabia’s financial and business communities, along with Kamco Invest executives and board members. The company said the event aimed to deepen bilateral investment cooperation and explore opportunities aligned with Saudi Vision 2030.

Kamco Invest, which recently relocated its Saudi operations to the King Abdullah Financial District (KAFD), reaffirmed its long-term commitment to the Kingdom’s market and ongoing expansion strategy. Its Riyadh-based arm manages what the company describes as the Kingdom’s largest conventional equity strategy, valued at around SAR 1.2 billion, alongside Sharia-compliant equity and money-market funds and a new pre-IPO technology fund focused on Gulf startups.

Chief Executive Officer Faisal M. Sarkhou said that participation in this year’s FII reflects the firm’s regional ambitions. “The forum provides a valuable opportunity to build strategic partnerships that support our aspirations at Kamco Invest to expand our regional presence and contribute to the development of the investment environment in the Kingdom and the region,” he noted.

While no independent media statement has yet confirmed the full details of the Riyadh reception or official patronage, Kamco Invest’s attendance at the FII 2025 and its relocation to KAFD are documented on the company’s official channels.

The event capped a week of investor dialogues in Riyadh focused on innovation, private-market growth, and cross-border collaboration—areas central to both Kuwait’s and Saudi Arabia’s evolving investment strategies.

GCC Equity Markets Sustain Momentum Amid Rate Cuts and Robust Sector Gains

The Gulf Cooperation Council (GCC) equity markets extended their positive streak into October 2025, with the MSCI GCC index rising 1.2% month-on-month, marking the second consecutive month of gains. The region’s performance reflected stronger global investor sentiment, progress in trade negotiations, and monetary easing following synchronized rate cuts by the US Federal Reserve and most GCC central banks — with Kuwait as the only exception.

Oman, Bahrain, and Dubai Lead Regional Gains

Oman emerged as the best-performing market, surging 8.3% and securing its fourth straight monthly advance. The rally, supported by sustained economic diversification and steady corporate earnings, placed Muscat’s bourse second in the GCC for year-to-date growth at 22.6%, just behind Kuwait’s 22.7%. Bahrain followed closely with a 5.9% rise, while Dubai climbed 3.8% on the back of strong performances in real estate and banking shares.

Kuwait continued to dominate regional benchmarks, with the All Share Index up 2.7% in October and breaching the symbolic 9,000-point threshold for the first time this year. Gains were driven largely by mid- and small-cap stocks, especially within financial services and energy. Saudi Arabia’s Tadawul posted a modest 1.3% gain as third-quarter earnings lifted sentiment, despite large-cap banks facing pressure over ongoing foreign ownership policy discussions.

Sector Snapshot: Diversified Financials, Energy, and Retail Drive Growth

Sector performance across the region tilted towards the upside. Diversified Financials led with a 6.6% increase, followed by Retail (+6.4%) and Utilities (+4.8%). Energy stocks benefited from higher oil prices and strong quarterly results, gaining 3.8%, while banks saw smaller advances at 0.7%. Consumer-facing industries such as apparel and hospitality lagged, recording declines between 2% and 10%.

Regional Market Highlights

In Abu Dhabi, the FTSE ADX Index rose 0.9%, buoyed by gains in financials and telecoms, even as real estate and utilities underperformed. Dubai’s Financial and Real Estate indices rose sharply, helped by strong corporate activity and continued inflows into property. The Qatar Exchange was the only market to end lower (-0.9%), dragged down by large-cap financials and real estate stocks despite solid 9M earnings from the banking sector. Bahrain’s All Share Index advanced 5.9%, supported by Aluminium Bahrain’s 22% surge and steady gains across non-oil sectors.

Meanwhile, Oman’s Muscat Stock Exchange delivered a standout performance as all sectors — led by services and financials — finished in positive territory. Rising trading volumes and the expansion of industrial activity reflected growing investor confidence.

Macroeconomic Backdrop and Policy Moves

Rate adjustments across the GCC largely mirrored the US Federal Reserve’s 25-basis-point cut in late October. Saudi Arabia’s central bank reduced its repo rate to 4%, while other regional regulators followed suit to support liquidity and maintain currency pegs. Economic data released by the IMF and national statistics agencies pointed to sustained non-oil growth across the Gulf, with Abu Dhabi’s GDP projected to rise by 6% in 2025 and Oman’s non-oil output up 4% year-on-year.

Outlook

Kamco Invest’s latest analysis underscores continued optimism for GCC equity markets heading into 2026, driven by supportive monetary policies, fiscal expansion, and improving corporate earnings. However, analysts caution that geopolitical risks, uneven oil demand recovery, and global inflation trends could influence near-term volatility.

Source: Kamco Invest, GCC Markets Monthly Report – October 2025.

EU Enlargement: Europe’s Next Generation of Members Faces a Long Road Ahead

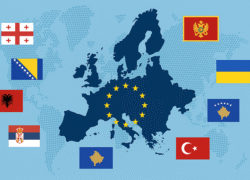
Europe is preparing for its most ambitious wave of expansion in decades, with ten nations from the Western Balkans to the Black Sea seeking to join the European Union. Their motivations are clear — stability, growth, and security within Europe’s political framework — but their progress remains uneven. Each country faces its own reform challenges, while the EU itself must confront internal doubts about its readiness to absorb new members.

Albania has emerged as one of the most determined reformers in the Western Balkans. Its government has launched a string of anti-corruption and digital governance measures, but the rule of law remains fragile. The EU continues to push for visible results in prosecuting high-level corruption and strengthening judicial independence. Despite progress, deep-rooted governance issues and uneven public trust in institutions still stand in the way of membership.

North Macedonia’s path has been blocked by political disputes that have overshadowed years of reforms. A constitutional amendment recognising the Bulgarian minority — a key precondition set by the EU — remains stalled in parliament. The deadlock has frustrated citizens who supported the country’s long-standing pro-European orientation and believe it has already delivered on most technical reforms.

Montenegro is widely seen as the closest to joining. It has opened nearly all negotiation chapters and provisionally closed several, but political instability and unfinished judicial reforms continue to slow its progress. Brussels sees Montenegro as a test case for whether the Western Balkans can deliver real change and whether the EU can keep enlargement momentum alive.

Serbia’s membership talks have lost momentum. Concerns over media freedom, judicial independence, and close ties with Russia have drawn criticism from Brussels. The EU insists that Serbia must align more closely with its foreign policy and normalise relations with Kosovo before meaningful progress can be made. Without these shifts, its accession track risks indefinite delay.

Bosnia and Herzegovina remains paralysed by internal divisions and an unwieldy power-sharing structure that makes nationwide reform difficult. Despite cooperation with the EU on border management and migration, real institutional reform remains elusive. Until the state functions more cohesively, the country’s European path will remain largely symbolic.

Moldova, on the other hand, has surprised observers with its rapid reform drive. Since being granted candidate status, it has launched judicial restructuring and anti-corruption measures while trying to reduce dependence on Russian energy. Yet its limited administrative capacity and exposure to geopolitical pressures pose ongoing risks. The EU has praised Moldova’s determination but warns that momentum must translate into measurable results.

Ukraine’s path to membership is exceptional — it is pursuing structural reform in the middle of a war. Even under extreme pressure, Kyiv has strengthened anti-corruption institutions and pursued regulatory alignment with EU standards. The challenge now is to sustain reform while defending the country militarily. EU officials link future funding and accession milestones to continued governance progress, knowing that Ukraine’s success will shape Europe’s credibility as a geopolitical actor.

Georgia’s accession hopes have dimmed. Once seen as a frontrunner, the country has drifted away from democratic norms, with its government accused of undermining media freedom and civil society. Brussels has urged Georgian leaders to return to the reform path laid out in their initial roadmap, warning that political backsliding could halt progress entirely.

Turkey’s membership process remains effectively frozen. The EU continues to cite major concerns about human rights, press freedom, and judicial independence. While cooperation on trade and migration persists, full membership is no longer viewed as a realistic prospect under current conditions.

Kosovo’s path is complicated by a lack of universal recognition. Five EU member states still do not formally recognise its independence, which makes the accession process legally and politically difficult. The EU continues to press for dialogue between Pristina and Belgrade, seeing reconciliation as essential for both countries’ European aspirations.

For Brussels, enlargement is as much a political question as a technical one. Every new member must be approved by all existing 27 states, leaving the process vulnerable to national vetoes and political bargaining. At the same time, the EU must ensure it can function effectively once new members join — a concern frequently raised by larger states wary of overextension.

The geopolitical context has made enlargement a renewed priority. Russia’s war in Ukraine and growing Chinese influence in the Balkans have transformed what was once a slow bureaucratic process into a strategic race for influence. Yet the balance remains delicate: candidate countries must prove genuine reform, and the EU must show that its promises are credible.

Europe’s future enlargement will test both sides. The candidates need to demonstrate that they can uphold European values in practice, not just on paper. The EU, for its part, must show that its door remains open in more than rhetoric. Whether this new wave of enlargement becomes another success story or another stalled process will depend on a single question — can Europe deliver on its own vision before momentum fades once again?

Foreign Workers Now Essential to Growth Across Central Europe

Central European economies are increasingly shaped by the presence of foreign labour. From factories in the Czech Republic to construction sites in Romania, international workers are helping to fill persistent staffing shortages and keep growth on track. Yet public attitudes toward their role remain mixed, reflecting a tension between economic necessity and social caution.

In Poland, the contribution of foreign employees—particularly from Ukraine—has become indispensable. Analysts estimate that their work accounts for nearly three percent of national output, a figure that underscores how deeply migrant labour is embedded in the economy. Surveys suggest that roughly half of Poles recognise this positive influence, though enthusiasm has cooled compared with the early years of the war in Ukraine. Many respondents now express more neutral or cautious views, shaped by broader European debates over migration.

The situation in Czechia is even more pronounced. Nearly one in five people employed there now comes from abroad, with Ukrainians, Slovaks, and Vietnamese among the largest groups. The country’s tight labour market means foreign workers are crucial for sustaining production, particularly in manufacturing and logistics. While employers praise their reliability, public opinion remains divided. Polling shows that Czechs are pragmatic—accepting migration as economically necessary, but wary of its social effects.

In Slovakia, foreign labour plays a smaller but increasingly visible role. The domestic workforce is ageing, and thousands of young Slovaks have moved abroad for work. Employers have turned to neighbouring countries and to refugees from Ukraine to close the gap. Many of these newcomers are now active in industrial and service sectors, helping to stabilise output. Nonetheless, surveys show that Slovaks remain among the most skeptical publics in the region when it comes to migration, reflecting a wider unease about rapid demographic change.

Romania, once known mainly as a source of emigrants, has in recent years become a destination for workers from South and Southeast Asia. Labour shortages, especially in construction, hospitality, and transport, have forced the government to expand work-permit quotas to record levels. While foreigners still make up a small share of the total workforce, their numbers are rising sharply, and employers say they are vital for keeping large projects on schedule.

Despite differences in scale, the pattern is clear across Central Europe. Tight labour markets, low unemployment, and demographic decline have created a growing need for foreign employees. Governments are adapting by simplifying permit procedures and promoting integration schemes, though some are simultaneously increasing fees and administrative hurdles.

Public sentiment, meanwhile, remains divided. Older generations and residents of smaller towns tend to be more skeptical, while younger people and those in large cities are more open. Experts note that social acceptance often follows economic experience—workplaces where Poles, Czechs, Slovaks, and Romanians collaborate with foreign colleagues tend to report more positive views over time.

The region’s reliance on migrant workers is no longer a temporary fix but a structural feature of its economies. While it would be an exaggeration to say that these economies are “based” on foreign labour, they are undeniably being sustained by it. Without continued inflows of international workers, many businesses would struggle to meet demand, and growth across Central Europe would be considerably weaker.

Source: PersonalService, CSO, GUS, UNHCR, accace and CIJ EUROPE analysis.

Dubai’s Housing Boom Enters a New Phase as Foreign Sellers Retain Full Freedom to Repatriate Funds

Dubai’s property market is entering a more balanced phase after several years of rapid expansion. Analysts expect growth to remain solid through 2027, even as new supply begins to catch up with the city’s strong population growth and investor appetite. For many European buyers — including those from Poland, the Czech Republic, and Slovakia — this new stage of maturity also brings greater clarity and confidence when it comes to selling and repatriating investment capital abroad.

Sales of newly launched developments continue to drive Dubai’s housing sector in 2025. Off-plan transactions have climbed sharply, while demand for completed properties has steadied. Prices for new projects are still rising, but more slowly than in previous years, suggesting that Dubai’s residential cycle is shifting from a surge to a sustainable rhythm. Population growth remains one of the city’s most powerful market engines. Dubai’s resident base expanded by nearly 6 percent in 2024, and the government’s investor-friendly visa programs continue to draw professionals, entrepreneurs, and high-net-worth individuals. Initiatives such as the first-home buyer program are also steering the market toward genuine end-user ownership rather than speculative trading.

Developers are now delivering a large pipeline of apartments and villas through 2027. While this may cap price acceleration, most analysts expect the new units to be absorbed steadily, with the villa segment still under-supplied due to high demand for family and lifestyle-oriented housing. The luxury and branded residence segment continues to lead in value and global visibility. International hotel and fashion brands have deepened their partnerships with Dubai’s major developers, helping to solidify the city’s reputation as a preferred global address for wealthy investors and second-home buyers.

Policy innovation remains a major strength of Dubai’s real estate ecosystem. The ten-year “golden” residency visa tied to property investment continues to attract long-term investors, while the digital Real Estate Tokenization Project opens opportunities for smaller investors to participate through fractional ownership. Together, these measures broaden access, deepen liquidity, and enhance transparency. Developers are also adapting to the changing environment by offering flexible payment plans and more compact, affordable units tailored to young professionals. Despite heavy construction, most large firms, including Emaar, Damac, and Omniyat, maintain strong balance sheets and high levels of pre-sales, underscoring their financial resilience.

A persistent misconception among some foreign investors is that money from a Dubai property sale cannot be taken out of the UAE. This is false. The UAE has no capital-transfer or foreign-exchange restrictions on foreign investors, and funds can be freely remitted abroad once the correct process is followed. The key procedural update in 2025 concerns how funds are received. Under new Dubai Land Department (DLD) regulations, sale proceeds must be paid into a UAE bank account held in the seller’s own name. Third-party payments and Power of Attorney transfers are no longer permitted. After the proceeds are credited, sellers can transfer the money internationally via standard banking channels to any foreign account. The change is part of broader anti–money-laundering safeguards, not a limitation on capital movement. With proper documentation — such as the sale contract, title deed, and DLD transfer receipt — the process is straightforward and compliant with international standards.

For Central European sellers, the process of repatriating funds remains practical and transparent. Polish residents can freely receive proceeds from the UAE, as Poland imposes no currency or transfer restrictions. Gains from property held for five full calendar years after purchase are exempt from capital gains tax, while shorter holdings are taxable and must be declared on the PIT-38 form. Czech residents can also transfer proceeds home without limitation. Property owned for more than five years, or occupied as a main residence for at least two years, qualifies for tax exemption, while shorter ownerships are taxed at 15 or 23 percent depending on income. Slovak owners enjoy similar treatment. Property gains are exempt after five years of ownership; if sold earlier, gains are taxed at 19 or 25 percent, plus a small health levy. In all three countries, banks may request documentation confirming the legitimacy of the sale, such as the title deed, sale receipt, and SWIFT confirmation, as part of standard anti–money-laundering checks.

In practical terms, sellers should ensure that they maintain a UAE bank account in their name before the sale, collect all DLD-issued documents including the title deed and transfer receipt, and request a “purpose of transfer” note from their bank specifying that the funds are property-sale proceeds. Declaring the transaction in the home-country tax return, even when exempt, is also recommended. Keeping records such as SWIFT confirmations and currency-conversion slips provides transparency and simplifies later verification by local authorities.

Dubai’s approach to property regulation — balancing open investment with responsible oversight — has helped it become one of the most transparent and globally connected real estate markets in the world. Investors from across Europe continue to view the emirate as both a safe haven and a profitable long-term destination. Looking ahead, Dubai’s housing sector appears poised for steady growth rather than speculative spikes. Population expansion, innovative ownership models, and investor-friendly policies should sustain demand through the next decade.

For Central European owners, the message is reassuring: selling property in Dubai and repatriating the proceeds abroad remains fully permitted, practical, and protected. There are no legal barriers to moving funds out of the UAE, only procedural checks to ensure compliance. Once completed, the proceeds can be safely transferred to Poland, the Czech Republic, or Slovakia, where only local capital-gains tax rules may apply.

In short, Dubai’s housing market is maturing into a phase of sustainable growth, supported by strong fundamentals and transparent rules. For investors from Central Europe, it remains one of the few global destinations offering both high real estate returns and full freedom to repatriate gains securely.

Sources: S&P Global, UAE Central Bank, OECD/EU and CIJ.World analysis.

EU Households Still Under Pressure as Energy Prices Ease but Living Costs Stay High

Across the European Union, the start of 2025 has brought mixed signals for household budgets. New Eurostat figures show that while gas and electricity prices have edged down from last year’s peaks, many families continue to struggle with overall living costs.

In the first half of 2025, gas prices for households fell by just over eight percent compared to late 2024, marking the sharpest decline since the energy crisis began to subside. Electricity bills also dipped slightly, but only marginally, and taxes now make up a larger share of final prices than before. That means the benefits of lower wholesale costs are not always reaching consumers in full.

The differences between member states remain striking. Sweden continues to record the highest household gas prices, while Hungary enjoys the lowest. For electricity, German consumers pay among the most in Europe, whereas households in Malta and Bulgaria face some of the lowest rates.

For non-residential users such as factories and offices, electricity and gas prices have stabilised, bringing modest relief to business energy costs after several turbulent years. Yet rising tax components and the gradual withdrawal of government subsidies could limit these gains.

At the same time, the broader financial picture for European households remains fragile. Survey data for 2024 show that more than four in ten EU households still found it difficult to make ends meet. Although this is a slight improvement from the year before, it underscores that many families have yet to recover fully from the combined impact of inflation, high rents, and elevated energy bills.

In countries across Central and Eastern Europe — including Poland, Romania, Hungary, and Czechia — household energy costs remain a major concern, particularly in lower-income regions where purchasing power lags the EU average. Even as governments scale back crisis-era subsidies, households in these areas remain highly sensitive to small changes in energy tariffs or taxes.

For policymakers, the latest figures highlight the fine balance between fiscal restraint and social protection. Energy costs may be cooling, but the persistent strain on household budgets shows that the broader cost-of-living challenge across Europe is far from over.

Source: Eurostat

Several EU Capitals Compete to Host New European Union Customs Authority

The race to host the headquarters of the new European Union Customs Authority (EUCA) has officially begun, with five countries — Poland, France, Spain, Portugal, and the Netherlands — declaring their interest in housing the agency. The EUCA is set to become a key institution in the bloc’s ongoing reform of the customs union, coordinating digital data systems and managing customs risk across all Member States.

According to the European Council, applications to host the agency opened in October 2025, with final submissions expected in early 2026 and a decision anticipated by mid-year. The EUCA will be responsible for operating the EU Customs Data Centre, overseeing cross-border customs cooperation, and supporting the protection of the single market. The authority is expected to begin operations between 2026 and 2028, employing roughly 250 staff.

Warsaw enters the race

Poland formally launched its candidacy on 31 October 2025, with Finance and Economy Minister Andrzej Domański announcing Warsaw’s bid during a press conference at the Ministry of Finance. The Polish government argues that Warsaw’s position on the EU’s external border, existing infrastructure, and experience hosting Frontex make it an ideal location for the new agency. Deputy Minister Marcin Łoboda, Head of the National Tax Administration (KAS), emphasised Poland’s strong record in customs digitisation and integrated border management.

Competing cities across Europe

France has nominated Lille, citing its proximity to Brussels and established logistics infrastructure. Spain entered the competition in September 2025 with Málaga, positioning the southern port city as a growing European logistics and innovation hub. Portugal has proposed Porto, pointing to its maritime economy and modern technology base, while the Netherlands — likely proposing either The Hague or Rotterdam — has expressed interest, leveraging its trade expertise and existing EU agency presence.

Evaluation criteria and selection timeline

The European Council and Commission will assess candidate cities based on accessibility to Brussels, quality of office facilities, security standards, data-centre capacity, housing and schooling options for staff, and synergies with other EU institutions. Shortlisted bids are expected to be announced in spring 2026, followed by a ministerial vote before mid-year.

Regional balance a key factor

Observers note that the decision may balance regional representation across the EU. With most EU agencies currently based in Western Europe, a successful Polish bid could reinforce the EU’s commitment to greater geographic diversity. Warsaw’s proposal to host EUCA alongside Frontex — both agencies focused on border and customs security — highlights its ambition to position Poland as a regional centre for EU operational institutions.

Regardless of the outcome, the establishment of the EUCA marks a milestone in the modernisation of the customs union — an initiative aimed at strengthening trade oversight, combating smuggling and counterfeit goods, and improving the resilience of the EU’s single market.

Source: European Council; Ministry of Finance of the Republic of Poland; French Ministry of Economy and Finance; Sur in English; Lusa News; Xinhua; CIJ EUROPE analysis.

Poland’s Mortgage and Consumer Lending Surge in September 2025

Poland’s credit market recorded strong growth in September 2025, driven by a surge in mortgage and cash loans, according to the latest data from Biuro Informacji Kredytowej (BIK). The increase comes amid improving creditworthiness, lower interest rates, and steady household income growth.

Compared with September 2024, banks and credit unions issued 52.4% more housing loans and 18.8% more cash loans, while installment lending and credit card issuance both declined slightly. In value terms, the market saw an even sharper rise — housing loan volumes climbed 62.8%, cash loans 21.3%, and credit cards 5.1%. Installment loans were the only category to show a modest contraction of 0.6% year-on-year.

Housing loans set a new record

The value of new housing loans reached PLN 10.67 billion in September, setting a historic monthly record and surpassing the previous peak from January 2024, during the “Safe Credit 2%” programme. The average mortgage size rose 6.8% year-on-year to PLN 448,900, reflecting higher property values and increased borrower capacity.

According to Prof. Waldemar Rogowski, BIK’s chief analyst, the record results reflect the impact of lower interest rates and rising real wages on household creditworthiness. “These favourable conditions could continue to stimulate demand, although a rise in uncertainty or global volatility could weaken momentum,” he said.

Strong growth in cash loans

The number and value of cash loans continued to expand sharply, supported by larger loan sizes and greater consumer confidence. The average cash loan amounted to PLN 26,379, up 2.1% from a year earlier. Prof. Rogowski noted that borrowers are increasingly opting for higher-value loans above PLN 50,000, helped by extended repayment periods and reduced borrowing costs. Between January and September, the total value of cash loans exceeded PLN 90 billion, raising expectations for a record annual total.

Weakness in installment lending

Installment loans, however, showed persistent weakness. BIK reported an 8.9% year-on-year drop in the number of such loans in September and a 7.1% decline in their total value for the first nine months of the year. Rogowski attributed this to a contraction in low-value retail financing and the transfer of some deferred payment (BNPL) liabilities from non-bank firms into bank portfolios.

Credit quality remains stable

Despite a slight month-to-month weakening in repayment indicators, BIK’s Quality Indexes remained at safe levels across all loan types, with improvements year-on-year for housing and cash loans. “Credit risk remains low, and further interest rate reductions and rising wages are likely to support stability,” Rogowski said.

The September results highlight the contrast between a rapidly expanding mortgage and consumer credit sector and a more subdued retail-finance market. Analysts suggest that if macroeconomic conditions remain stable, Poland could close 2025 with one of its strongest lending performances in recent years.

Source: Biuro Informacji Kredytowej (BIK) – Newsletter kredytowy Wrzesień 2025, published 29 October 2025.

ECB Holds Rates Steady as Economists Urge Clearer Guidance on Future Cuts

The European Central Bank (ECB) opted to keep interest rates unchanged at its latest meeting, maintaining a cautious stance amid growing signs of economic weakness across the eurozone. The decision leaves borrowing costs at their current level, with the deposit rate remaining at 2 percent, as policymakers continue to weigh slow growth against easing inflation.

While the ECB described its approach as data-driven, some economists argue that the bank missed an opportunity to reassure investors and businesses about its readiness to act should conditions worsen. Marcel Fratzscher, President of the German Institute for Economic Research (DIW Berlin), said the central bank should have sent a clearer message that it stands ready to cut rates if necessary to support the economy.

“The ECB continues to act very cautiously,” Fratzscher noted, adding that multiple risks — from trade tensions and the ongoing war in Ukraine to political instability in parts of Europe — could weigh heavily on output and confidence. He warned that tighter financing conditions are beginning to affect businesses and households, suggesting that the current policy stance may be overly restrictive.

Economic data from across the euro area point to a weaker recovery than expected earlier in the year. Business investment remains subdued, and credit surveys show only limited lending appetite despite moderating inflation. Analysts say that while the ECB’s decision to hold rates steady reflects prudence, stronger forward guidance could have eased uncertainty in financial markets and improved access to financing.

For now, the ECB insists that future moves will depend on incoming data, keeping its options open for either prolonged stability or potential easing in 2026. But with growth forecasts being revised downward, pressure is likely to build on the central bank to act sooner rather than later if the slowdown deepens.

Source: DIW Berlin

front page info
LATEST NEWS