Czech Mortgage Rates Hold Steady at 4.91 Percent in November

Mortgage rates in the Czech Republic remained unchanged at the start of November, continuing to hover just below the five-percent mark. According to the latest Swiss Life Hypoindex, the average offered rate for home loans stayed at 4.91 percent, the lowest level recorded since the spring of 2022.

Market observers note that the current stability reflects both cautious pricing by banks and uncertainty surrounding the broader economic outlook. Three-year fixed-rate mortgages remain the most attractive option, averaging slightly above 4.5 percent, while five-year fixes stand just under 4.8 percent. Longer ten-year loans and one-year fixes continue to be priced closer to 5.4 percent.

Despite a modest recovery in new lending compared with last year, borrowing volumes remain far below the highs seen during the pandemic era, when cheap credit fuelled record demand. High property prices and households’ reluctance to take on long-term debt are still weighing on overall activity.

Analysts suggest that financial institutions are unlikely to make major rate adjustments in the near term. With both domestic and international markets facing persistent uncertainty, lenders appear to prefer maintaining stable pricing. At the same time, refinancing activity is rising as many borrowers who secured loans at below 2 percent between 2020 and 2021 now face renewals at more than double their original rate. For a standard 30-year mortgage of CZK 3 million, the shift translates into a monthly payment increase from around CZK 10,900 to CZK 15,900.

The current figures underscore the gradual normalisation of the Czech housing finance market, where interest rates have eased from last year’s peaks but remain challenging for many households seeking to buy or refinance a home.

Source: CTK

HIH Projektentwicklung to Refurbish Cologne Office Building with Focus on ESG and Design

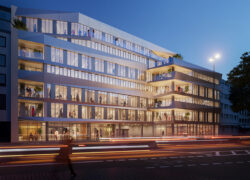
HIH Projektentwicklung has been appointed by an institutional investor to redevelop and reposition an office property on Zeughausstraße in Cologne’s city centre. The scheme aims to transform the existing structure into a high-quality, multi-tenant building offering around 6,600 square metres of modern workspace, with completion scheduled for the fourth quarter of 2028.

The project will convert currently vacant offices into flexible and efficient working environments, supported by extensive upgrades to the entrance and ground floor areas. Plans also include the addition of a new floor, landscaped inner courtyards, extra balconies, and a rooftop terrace offering views of Cologne Cathedral.

“The refurbishment follows a holistic ESG approach. Preserving the existing structure significantly reduces grey energy consumption and helps cut CO₂ emissions,” said Jens Fieber, Managing Director of HIH Projektentwicklung. “A comprehensive energy strategy featuring an innovative façade, advanced ventilation and cooling systems, insulated roofs, and modern glazing will ensure maximum efficiency. The result will be a sustainable and future-proof building.”

The Cologne project reflects HIH Projektentwicklung’s ongoing strategic focus on sustainable real estate transformation and the expansion of its third-party development business.

Cresco Real Estate Presents Q by Cresco, a Landmark Development on the Danube Waterfront in Bratislava

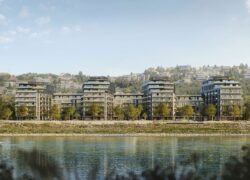
Developer Cresco Real Estate has revealed new details about its long-awaited riverfront project on the left bank of the Danube in Bratislava. The development, now officially branded Q by Cresco, will introduce premium residential housing to one of the last undeveloped sites along the city’s central waterfront.

The project has received a building permit, which is still awaiting legal finality, allowing preliminary work to begin once the process is complete. According to the developer, construction is expected to start between 2026 and 2027, with completion planned roughly three years after ground-breaking.

Designed by the London-based Bogle Architects, the project emphasises openness and light. The four-building composition will be positioned perpendicular to the river, ensuring that each apartment has a direct or partial view of the Danube or the city’s skyline. The layout also aims to maximise daylight throughout the interiors and create generous outdoor spaces.

Plans include 256 apartments and serviced units distributed across the buildings, complemented by extensive underground parking and shared amenities. Residents will have access to a private wellness area with a swimming pool and saunas, a fitness centre, and co-working and leisure zones.

A key feature of the design is its integration with the surrounding public realm. The project will extend the existing Danube promenade and include a landscaped inner courtyard accessible to the public, as well as a new square intended for community and cultural activities. The development is part of the ongoing transformation of the city’s central riverfront, near the site of the former PKO cultural complex.

Cresco Real Estate said the project aims to blend contemporary architecture with the natural and cultural character of the Danube. “We see Q as a continuation of Bratislava’s riverfront renewal,” a company spokesperson noted. “The focus is on high-quality housing and public space that opens the waterfront to residents and visitors alike.”

Once completed, Q by Cresco will join neighbouring large-scale developments, including JTRE’s River Park and future extensions of the promenade, further redefining Bratislava’s riverbank as a new urban district combining residential, leisure, and cultural uses.

McDonald’s faces increasing scrutiny across Europe as sexual-harassment allegations surface beyond the UK

The widening fallout from sexual-harassment allegations at McDonald’s has moved beyond the UK and is now drawing the attention of unions, regulators and workers’ organisations across Europe. What began as a domestic investigation by British media has evolved into a broader European issue as testimony, legal filings and union complaints reveal a similar pattern of alleged misconduct and inadequate protections at restaurants in several countries.

The most advanced regulatory action remains in the United Kingdom. In February 2023, McDonald’s UK signed a legally binding agreement with the Equality and Human Rights Commission (EHRC) after the watchdog intervened over concerns that young workers, some under 18, were facing sexual harassment and that internal systems were not sufficiently protecting them. By late 2024, the volume of new reports had not slowed. The EHRC confirmed that it had received around 300 submissions relating to harassment or abuse. The BBC received more than 160 additional reports, with workers describing unwanted touching by managers, sexual comments, explicit messages sent via social media and fear of retaliation when raising complaints. Earlier this year, the regulator strengthened its intervention, requiring McDonald’s to introduce more advanced training for managers, independent oversight of complaint handling, and new safeguarding measures tailored to a workforce that is predominantly young.

That level of regulatory oversight is rare for a multinational corporation in Europe and unprecedented in the UK fast-food industry. But what is increasingly clear is that the allegations are not isolated to Britain.

In France, the fast-food chain has faced a growing number of complaints from workers claiming harassment and inappropriate behaviour in restaurants. In 2020, French restaurant staff submitted more than one hundred formal testimonies documenting sexual harassment and abuse, according to the International Union of Food Workers, which represents workers in hospitality and catering sectors across Europe. These accounts were collected at a time when union activity intensified following high-profile global scandals involving US-based fast-food workers. The European Federation of Food, Agriculture and Tourism Trade Unions, which works across EU member states, later supported a cross-border complaint filed through the OECD National Contact Point mechanism, alleging that McDonald’s had failed to prevent a culture of harassment and gender-based misconduct in several countries, including France. That complaint, backed by unions representing millions of workers globally, also referenced concerns in the Netherlands, the United Kingdom and additional European jurisdictions.

The OECD procedure is not a court process and does not result in fines. Instead, it requires multinational companies operating across borders to meet due-diligence and human-rights standards. The fact that the case was accepted for review was notable: the mechanism is used only when complainants present evidence that a corporation may not be respecting obligations under the OECD Guidelines for Multinational Enterprises. The unions’ argument is that a franchising model, where restaurants are operated by independent business owners but carry the brand, creates structural gaps in accountability, particularly when safeguarding involves vulnerable or young employees.

While France and the UK represent the most visible European cases, the issue has also attracted attention from labour organisations in other EU markets. In the Netherlands, worker representatives have raised concerns about harassment allegations in franchise restaurants. In Spain and Italy, unions have echoed warnings that the prevalence of teenage workers in fast-paced environments may increase vulnerability when there is insufficient managerial oversight or training. In each instance, the challenge is the same: responsibility is distributed between the corporate headquarters, which sets standards, and franchise owners, who manage day-to-day staffing and supervision. That separation can leave staff unsure who to approach when a serious complaint arises and can slow responses during internal investigations.

McDonald’s maintains that it has made significant improvements to its processes and that the strengthened EHRC oversight in the UK will reinforce changes already underway across Europe. The company points to training programmes, new reporting channels and a “Speak Up” platform designed to allow staff to report concerns anonymously. It also notes that in the UK, twenty-nine employees were dismissed within a year following harassment investigations.

Critics argue that training and technology will only go so far if the underlying issue is cultural rather than procedural. Worker testimonies in the UK and France describe experiences where staff did not feel safe speaking up because the alleged perpetrators were shift managers or supervisors who controlled scheduling and performance reviews. Union representatives across Europe have repeatedly stated that corporate policies have limited effect if local management does not enforce them.

The growing number of allegations across multiple European markets suggests a systemic challenge for McDonald’s. Regulators are increasingly focused not only on whether companies have the right written policies in place, but whether those policies translate into a workplace culture where young employees feel secure. If additional European labour or equality authorities decide to follow the UK’s approach and introduce formal oversight mechanisms, the company may face further regulatory obligations in the EU.

For now, the decisive test is not whether new policies exist, but whether workers experience meaningful change inside restaurants. As one trade union representative in France put it when asked about McDonald’s reforms, “Policies are not safety. Practice is safety.”

The European regulatory environment has shifted. McDonald’s now finds itself at the centre of that shift.

Estonia’s Office Market Steadies in 2025 as Tallinn Absorbs New Supply

Estonia’s office property sector remained largely stable through the third quarter of 2025, balancing an influx of new space with moderate leasing activity and firm rents in the capital.

The latest figures indicate that the average vacancy in modern Tallinn offices held at around nine percent, reflecting both the steady pace of completions and a cautious approach from occupiers. Two new developments — including the Golden Gate complex near the Old Port and the smaller Ankur project — were completed during the quarter, adding roughly 17,000 square metres of new space to the market. These deliveries expanded the city’s prime office stock, offering tenants access to modern, energy-efficient workplaces at a time when sustainability and flexibility remain top priorities.

Demand softened slightly in the summer months. Leasing volumes were down from earlier in the year, yet transactions continued in core locations, particularly for compact, high-quality premises. Tenants remain selective, with many favouring properties that meet high environmental standards and offer adaptable layouts to accommodate hybrid work models.

Prime headline rents for top-tier offices in Tallinn’s central business areas stayed broadly unchanged at around €24 per square metre per month, while secondary properties continued to trade within the lower mid-teens range. This stability has persisted despite increased competition between landlords, who often use incentives or fit-out contributions to secure long-term tenants.

Developers and investors are now watching closely how quickly the market absorbs new projects. Roughly 100,000 square metres of additional space are still under construction across the city, including major schemes in Ülemiste City and the new Talsinki/SEB headquarters. While this pipeline underscores developer confidence, it also heightens pressure to differentiate buildings through design, amenities and ESG performance.

In the investment market, sentiment remains cautious but steady. Prime office yields in Estonia are estimated at around 6.75 percent, largely unchanged over the past year, reflecting both higher financing costs and investor preference for assets with secure income.

Across the Baltic region, analysts describe 2025 as a year of normalisation rather than expansion. Tallinn continues to outperform smaller cities, benefiting from its diversified occupier base and ongoing infrastructure improvements. Yet, as construction costs stabilise and borrowing remains expensive, developers are expected to slow new project starts in favour of completing and leasing existing schemes.

Overall, Estonia’s office market enters the final quarter of 2025 with stable fundamentals: limited rental movement, contained vacancy, and a cautious but functioning investment climate. While tenants now enjoy greater choice and negotiating power, high-quality, sustainable buildings in strategic locations continue to draw steady demand — ensuring that Tallinn’s commercial core remains one of the most resilient in the Baltic region.

Source: Newsec, Colliers, CBRE and CIJ EUROPE Analysis Team

Skanska Reports Strong Q3 2025 Results, Driven by Construction and Sustainability Gains

Swedish construction and development group Skanska AB reported a robust third quarter of 2025, supported by strong Construction margins, improved profitability in Residential Development, and continued progress on sustainability goals.

Group revenue totalled SEK 43.7 billion (≈ EUR 3.77 billion), compared to SEK 42.8 billion (≈ EUR 3.69 billion) in the same quarter last year. Adjusted for currency effects, this represented an 8 percent increase. Operating income rose by 13 percent to SEK 1.4 billion (≈ EUR 121 million), while earnings per share climbed to SEK 3.07 (≈ EUR 0.26) from SEK 2.28 (≈ EUR 0.20) in Q3 2024.

Although order bookings in Construction fell to SEK 39.9 billion (≈ EUR 3.44 billion) from SEK 50.8 billion (≈ EUR 4.39 billion)** year-on-year, Skanska maintained a strong order backlog of SEK 264 billion (≈ EUR 22.8 billion) — equivalent to around 19 months of production. The Construction segment’s operating margin reached 4.2 percent, exceeding the company’s 3.5 percent target.

In Project Development, operating income stood at SEK –0.3 billion (≈ – EUR 26 million), reflecting property impairments of SEK 0.7 billion (≈ EUR 60 million) in the US. Residential Development returned to profit, achieving SEK 131 million (≈ EUR 11 million) in operating income, while Commercial Property Development reported a SEK 397 million (≈ EUR 34 million) loss due to write-downs in the US portfolio. The Investment Properties division contributed SEK 143 million (≈ EUR 12 million), supported by a revaluation gain of SEK 53 million (≈ EUR 4.6 million).

Group return on equity reached 10 percent, with return on capital employed in Project Development at 1.4 percent. Skanska ended the quarter with adjusted net cash of SEK 9.3 billion (≈ EUR 0.80 billion) and an equity ratio of 37.7 percent — underscoring its strong balance sheet.

“Construction delivered strong margins in the third quarter, reflecting the quality of our backlog and the competence of our teams,” said Anders Danielsson, President and CEO. “We are maintaining performance stability and focusing on selective project starts while positioning for a market recovery.”


Segment Highlights

Construction

Revenue rose to SEK 42.2 billion (≈ EUR 3.64 billion), a 7 percent increase in local currencies, with all key geographies contributing. Operating income improved to SEK 1.77 billion (≈ EUR 153 million), resulting in a rolling 12-month margin of 3.9 percent.

Residential Development

Revenue reached SEK 1.76 billion (≈ EUR 152 million), with an operating margin of 7.4 percent. Strong sales in Central Europe — notably Poland and the Czech Republic — offset subdued demand in the Nordics.

Commercial Property Development

Revenue increased to SEK 1.75 billion (≈ EUR 151 million). However, impairments in the US weighed on earnings. The company started three new projects, including the Solna Link phase two development in Stockholm, and signed major leases for H2Offices in Budapest and the first phase of Solna Link.

Investment Properties

Revenue amounted to SEK 120 million (≈ EUR 10 million) and operating income reached SEK 143 million (≈ EUR 12 million). Portfolio valuation stood at SEK 8.2 billion (≈ EUR 0.71 billion) with an 83 percent occupancy rate.


Cash Flow and Investment Activity

Operating cash flow from operations was SEK 40 million (≈ EUR 3.5 million), significantly lower than the SEK 6.2 billion (≈ EUR 0.54 billion) recorded a year earlier due to working-capital changes and ongoing project investments. Total net investments amounted to SEK –1.3 billion (≈ – EUR 112 million).


Market Outlook

Skanska expects the US civil infrastructure sector to remain robust, while European and Nordic construction markets will rely increasingly on infrastructure, industrial, and defence investments. Central Europe’s residential and office markets are showing improvement, but the Nordic housing sector remains subdued amid slower economic recovery and high borrowing costs.


Sustainability Performance

Skanska achieved significant progress toward its 2030 climate goals. Combined scope 1 and 2 emissions were 38,000 tonnes CO₂e, down from 47,000 tonnes last year — 64 percent below 2015 levels. Renewable electricity represented 98 percent of total consumption, and renewable fuels reached 34 percent of total fuel use.

The company also maintained strong safety results, with a lost-time accident rate (LTAR) of 2.1 and 1,871 executive site safety visits completed during the quarter.


Outlook and Events

Skanska reaffirmed its disciplined approach to project selection and capital management. The company will present its forward-looking strategy at the Capital Markets Day in Seattle, USA, on 18 November 2025, focusing on growth opportunities and value creation in North America.


Key Q3 2025 Figures (with EUR equivalents)

  • Revenue: SEK 43.7 bn ≈ EUR 3.77 bn

  • Operating income: SEK 1.36 bn ≈ EUR 117 m

  • Earnings per share: SEK 3.07 ≈ EUR 0.26

  • Order bookings: SEK 39.9 bn ≈ EUR 3.44 bn

  • Operating margin (Construction): 4.2 %

  • Return on equity: 10 %

  • Adjusted net cash: SEK 9.3 bn ≈ EUR 0.80 bn

  • CO₂ reduction vs 2015: –64 %


Note: Conversions use an approximate Q3 2025 average exchange rate of 1 EUR = 11.6 SEK (European Central Bank benchmark for the period).


Credit Card Usage Rising in Poland as Borrowers Tap Into Limits More Aggressively

Credit cards issued by non-bank lending institutions are gaining ground in Poland’s consumer finance market, according to the latest data from the Polish Credit Information Bureau (BIK). The report shows that both the number of users and the total value of credit card limits have grown sharply this year, with loan-company cards seeing far more active use than those issued by banks.

Over the first nine months of 2025, the value of credit limits granted by loan institutions increased by nearly a quarter compared with the same period last year. Total outstanding balances on these cards were around 70% higher year-on-year, with more than 200,000 customers now using such products.

In contrast, the traditional banking sector has seen only minimal growth in credit card borrowing. Total debt on bank-issued cards rose by just a fraction, while the value of new limits granted during the first three quarters increased by about 7%. The number of bank credit card holders continues to decline, standing at roughly 4.4 million people.

Data suggest that clients of loan institutions are drawing down their limits much more rapidly and extensively than bank customers. On average, users of these cards spend more than four-fifths of their available credit, and for smaller limits – around PLN 2,000 – that share rises to over 90%. In many cases, nearly all of the credit line is used within days of activation and remains heavily drawn in subsequent months.

By comparison, bank credit card users tend to be more cautious. The average utilisation rate for active bank cards is below half of the available limit, and new cards typically see only about one-quarter of their balance used shortly after being issued.

The data also show a significant difference in repayment discipline. Around 14% of customers using credit cards from loan institutions have payments overdue by more than three months, compared with less than 8% among bank card users. Broader indicators of financial stress reveal that one in four holders of loan-institution cards is behind on other obligations in the wider financial system, while this share is closer to 6% among bank card users.

Market analysts point out that the rapid rise in loan-company credit cards reflects both consumer appetite for quick access to funds and the sector’s aggressive approach to building customer relationships. However, the high rate of limit utilisation and repayment delays raise concerns about potential overextension among some borrowers.

Experts emphasise that preventing excessive borrowing and ensuring borrowers fully understand the costs of revolving credit should remain a joint responsibility of lenders, regulators, and consumers.

Source: BIK

CTP Reports Strong Third Quarter 2025 Results Driven by Rental Growth and Development Deliveries

CTP N.V., the Amsterdam-listed industrial and logistics real estate developer and operator, reported solid financial and operational growth for the first nine months of 2025. The company’s latest results show increases across rental income, earnings, and portfolio value, reflecting steady tenant demand and disciplined expansion across its Central and Eastern European markets.

CTP’s net rental income rose by 15.4% year-on-year to €549 million, while like-for-like rental growth reached 4.5%. Total gross rental income for the period amounted to €562 million. The group maintained an occupancy rate of 93% and a rent collection rate of 99.8%, underscoring the resilience of its tenant base.

By the end of September, annualised rental income stood at €778 million, and EPRA NTA per share increased to €19.98, up 10.5% since the start of the year. CTP’s gross asset value grew by 10.6% to €17.7 billion, supported by project completions and positive portfolio revaluations.

In the first nine months of 2025, CTP delivered 553,000 sqm of new space at a yield on cost of 10.3%, all of which was fully leased upon completion. Developments under construction total 2.0 million sqm, representing a potential rental income of €165 million once fully let. The company remains on track to deliver between 1.3 million sqm and 1.6 million sqm of new space in 2025.

CTP’s CEO Remon Vos said the results confirm the company’s strategic direction:

“CTP continues to demonstrate the strength of its platform and strategy with over 1.5 million square metres of new leases signed this year — 6% more than in the same period last year. With annualised rental income of €778 million and 2 million square metres under construction, we are well positioned to reach our target of €1 billion in annualised rental income by 2027.”

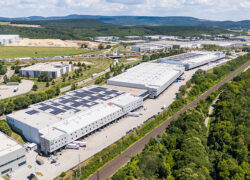
The company’s landbank of 25.7 million sqm secures future growth, with 90% of it located near existing business parks. This provides capacity for an estimated 13 million sqm of additional space, supporting the company’s long-term ambition to reach 30 million sqm by 2030.

CTP’s renewable energy segment continued to expand, with 149 MWp of photovoltaic capacity installed, of which 123.5 MWp is operational. Revenues from renewable energy doubled year-on-year to €12.4 million, reflecting growing tenant demand for sustainable energy solutions.

Financially, profit for the period increased by 17.1% to €862.8 million, while company-specific adjusted EPRA earnings rose by 13.1% to €305.2 million. The EPRA EPS stood at €0.64, putting the company on track to meet its full-year guidance of €0.86–€0.88 per share.

CTP’s balance sheet remains strong, with a loan-to-value ratio of 45.2% and liquidity of €2.4 billion, including €1.1 billion in cash and €1.3 billion in undrawn credit facilities. The company issued a new €600 million green bond in October 2025, following earlier funding rounds totalling €1.7 billion.

Recent credit rating upgrades by S&P (BBB stable) and Moody’s (positive outlook) underline investor confidence in the group’s financial structure and growth prospects.

Looking ahead, CTP expects continued growth supported by high tenant demand, limited new supply, and its extensive development pipeline. The company reaffirmed its commitment to its dividend policy of distributing 70–80% of adjusted earnings, with the option for shareholders to receive payouts in cash or shares.

Czech Economy Shows Mixed Momentum in September: Exports Strengthen While Industry Levels Off

The latest monthly data from the Czech Statistical Office reveal a varied picture of the national economy in September, with export activity improving, construction output rising, and industrial performance showing only limited gains.

Trade Surplus Expands

Czech exporters ended September with a higher trade surplus compared with the same month last year. The improvement came largely from stronger sales of cars and machinery, which more than offset increased imports of electronic components. Trade with other EU member states remained the key driver of this positive balance, while the deficit with non-EU partners widened slightly.

Over the first nine months of 2025, total exports grew modestly, supported by steady foreign demand, while imports rose at a similar pace. Analysts note that despite a year-to-date surplus, the pace of export growth has slowed compared to 2024, reflecting a more challenging environment for manufacturers.

Industry Holds Steady

Industrial production edged up only slightly from last year’s levels, pointing to a stabilisation after several months of uneven performance. Growth was recorded in machinery, electrical equipment, and rubber manufacturing, while production in energy and automotive sectors weakened. Orders for future industrial output increased, especially from foreign markets, but overall employment in the sector continued to decline.

Manufacturers continue to face rising costs and a slower recovery in some key export destinations, limiting broader expansion. However, improved order books suggest the sector may see more activity in the final quarter of the year.

Construction Remains a Bright Spot

Construction output increased sharply compared to the same month of 2024, driven by both building and infrastructure projects. Civil engineering activity – including roads and public works – contributed most of the growth. However, a drop in new permits and fewer housing starts indicate that some of this strength could ease in the coming months.

Despite these warning signs, the completion of housing projects surged, suggesting that developers are focusing on finalising ongoing work before committing to new ones.

Outlook

September’s data highlight a resilient but uneven Czech economy. Stronger exports and a buoyant construction sector contrast with slower industrial growth and declining employment in manufacturing. Economists suggest that while external demand continues to support overall performance, domestic investment and labour dynamics will determine whether growth can regain momentum toward the end of 2025.

Source: CSO – All figures are preliminary and subject to revision.

OECD: Inflation Holds Steady Across Member Economies in September 2025

Inflation across OECD countries remained largely unchanged in September 2025, with consumer prices rising by around 4.2% year on year, according to the latest update from the Organisation for Economic Co-operation and Development. The figure reflects a marginal increase from August’s 4.1%, suggesting that while headline inflation has stabilised, underlying pressures persist.

Energy costs were the main contributor to the slight acceleration, as the annual rate of energy inflation rose to roughly 3.1%, compared with just 0.8% in August. The OECD attributed this to base effects, with energy prices in many member states having been unusually low a year earlier. Food inflation remained elevated at approximately 5%, continuing to erode household purchasing power.

Core inflation, which excludes food and energy, showed a minor decline to about 4.2%, hinting that broader price pressures may be gradually easing but remain far above the levels targeted by most central banks. Across the OECD’s 38 member economies, inflation rose in 17 countries, fell in seven, and was broadly stable in the rest. Among G7 economies, the average annual inflation rate held at around 2.8%.

Economists note that the persistence of inflation near 4% indicates that the disinflationary trend observed earlier in 2025 has stalled. With energy prices fluctuating and service-sector inflation remaining strong, policymakers are likely to maintain a cautious approach to monetary easing. The report emphasises that despite the absence of a renewed surge, inflation is proving resistant to a rapid decline.

The OECD warned that the outlook depends heavily on global energy and food markets. The rebound in oil prices and agricultural commodities could further delay progress toward price stability, especially in economies where wages are growing faster than productivity.

The next release, covering October data, will clarify whether the September figures mark a turning point or a temporary pause in the downward trajectory. For now, inflation across the advanced economies remains well above central-bank targets, underscoring that price stability remains an unfinished task.

Source: OECD – Consumer Prices, Updated 5 November 2025.

front page info
LATEST NEWS