Union Investment agrees sale of Torre Oriente office tower in Lisbon

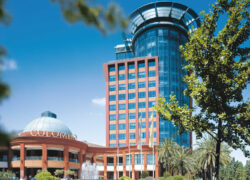
Union Investment has signed a binding agreement to sell the Torre Oriente office tower in Lisbon to a joint venture formed by Sonae Sierra and Bankinter Investment. While the sale price was not disclosed, the company confirmed that it exceeds the property’s most recent expert valuation. The transaction is expected to complete by the end of 2025.

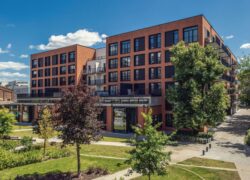
Torre Oriente forms part of the UniImmo: Global open-ended real estate fund. The 14-storey tower, completed in 2009, provides around 27,600 sqm of lettable space and is currently 95.3% let on an income basis. It is situated in north-west Lisbon and, together with the neighbouring Torre Occidente, forms a complex adjacent to the Colombo Shopping Centre.

“Since its acquisition in 2009, Torre Oriente has generated stable cash flows and positive value growth for UniImmo: Global,” said Martin Schellein, Head of Investment Management Europe at Union Investment. “The sale allows us to take advantage of a market opportunity in Portugal’s recovering investment market, increase fund liquidity and further rejuvenate the portfolio.”

Union Investment was advised by law firm Perez Llorca.

Behind Poland’s High Electricity Bills: What’s Really Driving the Costs?

Poland continues to record some of the highest electricity costs in the EU when adjusted for purchasing power, according to the latest Eurostat dataset for the first half of 2025. Prices for households rose by around 20% year-on-year, placing Poland among the fastest-growing electricity markets in the bloc. When expressed in PPS terms, Poland ranked second-highest in the EU—just behind Czechia and followed closely by Italy.

Industry analysts note that the issue extends beyond the price of energy itself. Polish consumers pay for a wide range of regulated surcharges that together make up a substantial portion of their final bills. These include the capacity fee, renewable energy (OZE) fee, cogeneration fee, transition fee, steadily rising distribution charges, and full VAT. While each component supports part of the national energy system, they also act as quasi-fiscal instruments, increasing household burdens regardless of wholesale price movements.

Recent regulatory developments suggest that these charges will rise further in 2026. Draft regulations published by the energy ministry indicate that the cogeneration fee will increase from PLN 3.00/MWh to PLN 4.36/MWh—a rise of roughly 45%. At the same time, the Energy Regulatory Office (URE) has approved substantial increases in the capacity fee for 2026, with analysts describing the adjustment as one of the steepest seen since the mechanism was introduced. Other regulated surcharges, including elements of the RES-support system, are also expected to increase next year based on preliminary regulatory signals.

Against this backdrop, President Karol Nawrocki has put forward a high-profile legislative package titled “Tani Prąd –33%” (Cheap Electricity –33%), which aims to reduce electricity bills for household and small-business customers. The bill, submitted to parliament, is structured around four pillars:

  1. Elimination of selected fees – the capacity fee, RES fee, cogeneration fee and the transitional fee.

  2. Reform of the certificates-of-origin system, reducing the cost burden placed on consumers.

  3. Lower distribution fees, achieved by reducing the allowed rate of return for grid operators.

  4. A VAT cut on electricity from 23% back to 5%.

According to the President’s Office, the reductions would be financed largely through revenues from the EU Emissions Trading System (ETS), which currently contribute several billion zloty annually to the state budget. Independent commentators, however, note that the reform could absorb a significant portion of these funds, raising questions about available financing for network upgrades, renewable capacity, and Poland’s upcoming nuclear investments.

A broader concern among market observers is that reducing regulated returns for distribution operators may limit their ability or incentive to invest in grid modernisation. With electrification accelerating and renewable capacity expanding, delays in upgrading lines, transformers and system flexibility could ultimately increase long-term costs.

Yet the proposal has brought clarity to one central point: high Polish electricity bills stem less from raw energy prices and more from layers of regulated charges built up over many years. The President’s initiative acknowledges this structure directly and places political emphasis on reducing the non-market components of electricity pricing.

Whether the programme becomes law—and whether its financing model proves sustainable—remains to be seen. For now, the debate underscores a structural challenge within Poland’s energy economy: balancing affordability, investment needs and stability in a sector undergoing rapid transformation.

Source: WEI

Poland’s Construction Price Growth Holds at 2.9% in October

Poland’s construction and assembly production prices rose by 2.9% year-on-year in October 2025, according to preliminary data from Statistics Poland. The monthly index increased by 0.8%, marking one of the strongest month-on-month adjustments this year. 

Across the main segments, building construction and civil engineering each posted a 0.8% monthly rise, while specialised construction activities grew by 0.6%. On an annual basis, civil engineering recorded the highest increase at 3.0%, followed by building construction at 2.8% and specialised activities at 2.6%. 

The data continues a broader trend of easing cost pressures: annual construction price growth has steadily declined from above 7% in early 2024 to levels closer to 3% this autumn. Charts included in the report show relative month-to-month stability throughout 2025, before the sharper uptick recorded in October. 

Since December 2023, cumulative price movements remain most pronounced in civil engineering, where costs have increased by 7.2%. Building construction and specialised activities followed at 6.7% and 6.3%, respectively. 

The figures were published by Statistics Poland on 24 November 2025 and include revised data for September.

ANCPI issues over 2.2 million documents online in 2025

The National Agency for Cadastre and Real Estate Advertising (ANCPI) released more than 2.2 million documents online between January and October 2025 through its Myeterra.ancpi.ro and epay.ancpi.ro platforms.

Between June and October, owners downloaded 390,766 free land book extracts and cadastral plan extracts via Myeterra.ancpi.ro. During the first ten months of the year, 1,883,561 documents were issued online through epay.ancpi.ro. By comparison, in the same period of 2024, ANCPI issued 1,938,029 online documents of this type.

In October 2025 alone, ANCPI—an institution under the Ministry of Development, Public Works and Administration—provided 119,463 free land book extracts and 18,932 cadastral plan extracts to owners via Myeterra.ancpi.ro. During the same month, the epay platform delivered 154,060 land book extracts and 22,927 cadastral plan extracts to paying users.

Land book and cadastral plan extracts are available free of charge to property owners both online and at ANCPI counters. Other users can obtain the documents online at a cost of 20 lei for a land book extract and 15 lei for a cadastral plan extract.

Usage of the epay platform continued to grow, with 8,323 new users in October generating 133,928 online orders. Documents already available in electronic format are delivered within minutes, while records not yet digitised are issued within two working days.

More than 27.1 million properties are currently registered in ANCPI’s integrated cadastre and land register system, making extracts for these properties accessible for quick online download. Digital documents issued by ANCPI, even without handwritten signatures, are accepted by public authorities, banks, lawyers, and notaries.

Crestpoint Project Partners Enters the Market with a New Integrated Project Management and Advisory Platform

Crestpoint Project Partners announces the launch of a new project management and advisory company founded to deliver high-quality, technically strong and transparent support across the entire real estate and construction lifecycle.

The launch of Crestpoint Project Partners follows the strategic partnership formed earlier this year between Petr Houska, MRICS, and Tomáš Jandík, CFA, MRICS under Crestpoint Capital Partners. Building on their combined decades of experience in development, project management, investment oversight and construction consultancy, the new platform expands the group’s service capabilities for clients throughout the real estate sector.

“Our mission is simple: to provide all-round, trustworthy and technically sound support to developers, investors and organisations working with real estate assets,” says Petr Houska, Founding Partner. “We understand the need for hands-on leadership, transparent processes and full accountability in today’s construction and investment environment.”

Crestpoint Project Partners will offer an integrated range of services including:

  • Project Management
  • Fit-out Management and Tenant Coordination
  • Cost Management and Procurement Advisory
  • Construction and Development advisory
  • Technical and Quality supervision
  • Technical Due Diligence and Development monitoring
  • Sustainability & ESG Advisory

The platform will serve all major property sectors — including office, retail, industrial/logistics, residential, hospitality and mixed-use schemes. From new developments to refurbishments, fit-outs and investment-driven technical audits, the company aims to bring transparency, confidence and consistency to every project entrusted to its team.

“We are combining deep real estate expertise with robust technical capabilities,” adds Tomáš Jandík, Co-Founder. “Our goal is to deliver services that genuinely protect investor interests and support the successful delivery of high-quality, sustainable assets.”

Crestpoint Project Partners is now fully operational and ready to engage with clients across the Czech Republic and the wider CEE region.

HIH Invest leases 3,600 sqm to EDEKA for new supermarket in Goslar

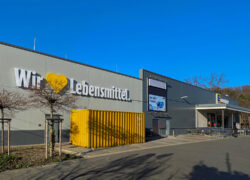
HIH Invest Real Estate has signed a long-term lease with EDEKA Minden-Hannover for a retail property on Hildesheimer Straße in Goslar. The food retailer plans to open a new EDEKA Centre on 27 November 2025, occupying around 3,600 sqm in the former Kaufland premises.

The new supermarket will replace the existing 1,500 sqm EDEKA store located across the street, which will close when the new unit begins operations. All employees from the current store have been offered positions at the new centre, and additional jobs have been created.

The property was built in 2016 and has stood vacant since Kaufland left the site last year. EDEKA Minden-Hannover will operate the new store independently, introducing a modern layout that includes service counters, self-service checkouts, scan-and-go technology, and a refurbished checkout zone with a café and supplementary retail space.

“After the previous tenant withdrew, our goal was to maintain the attractiveness of the location and secure the local supply in this part of Goslar. With EDEKA Minden-Hannover, we have found a reliable partner who is revitalising the property with a modern concept and reaffirming its commitment to the region,” said Milan-Kristoffer Otte, Head of Asset Management Retail & Logistics at HIH Invest Real Estate.

The EDEKA store across the street, operated by retailer Tim Plöger, will close as part of the relocation. “Our customers will see many familiar faces in the new supermarket. We have also expanded the team and created additional jobs,” added Dominik Lampe, Sales Manager at EDEKA Minden-Hannover.

The building forms part of the open-ended special AIF HIH Perspektive Einzelhandel: Fokus Nahversorgung, which holds 26 assets with a total value of around €520 million. The fund focuses on retail parks and local shopping centres, with more than 80% of its rental space dedicated to retail in established suburban or district locations. Current occupancy for retail use across the portfolio exceeds 90%.

CPI Europe acquires Czech residential portfolio of around 12,000 units

CPI Europe AG has completed the purchase of a Czech residential property portfolio known as “CPI BYTY”, comprising nearly 12,000 apartments located primarily in the regions of Ústí nad Labem and Liberec, as well as in Třinec and Prague. 

The transaction, announced in August 2025 and now finalised, includes the operational and management platform associated with the portfolio. In 2024, the portfolio generated gross rental income equivalent to approximately €38 million. 

Independent valuers placed the portfolio’s value at around €892 million as of 30 June 2025. After accounting for liabilities, capital-gains tax adjustments and other factors, the total consideration paid by CPI Europe is approximately €605 million. Half of this sum will be paid in cash immediately, with the remainder financed via a multi-year vendor loan from the seller, a subsidiary of the parent group. 

The company said the acquisition supports its strategic priorities of long-term growth, diversification and exposure across asset classes and geographies within the affiliated CPI Property Group. 

CPI Europe emphasised that the portfolio offers “positive rent-reversion opportunities”, with like-for-like rental growth estimated at about 9 % in the first half of 2025. 

Boutique training centre to open in SOHO by Yareal in 2026

BABA Body & Social Club will open a new studio in SOHO by Yareal, the mixed-use development in Warsaw’s Kamionek district. The concept will occupy a ground-floor unit in the KARDAN building, opposite the Warszawa Wschodnia by Mateusz Gessler restaurant. The opening is planned for spring 2026.

The studio will provide Pilates (reformer and mat), personal training and massage services, and the space will also include a café and lounge area. The unit covers nearly 230 m² and has been leased on a long-term basis.

According to the operator, the venue is intended to combine exercise and recovery with social functions, offering areas for meetings and relaxation. Yareal states that the addition of BABA Body & Social Club aligns with its broader approach to mixing retail, services and leisure functions within the SOHO complex.

SOHO by Yareal is designed as a local urban hub with residential, retail, office and leisure uses, incorporating both new buildings and refurbished post-industrial structures. The complex includes more than 11,300 m² of retail and service space distributed across several dozen units.

Recent additions to the retail component include Waszyngton x Soho café, beauty services, a Carrefour “300” grocery store and a therapeutic clinic. Further openings planned for 2026 include a Green Caffè Nero outlet, a bakery, Ramenownia and a food hub in a renovated historic building featuring concepts such as Bułkę przez Bibułkę, Pollypizza Neapolitan and Baken.

The final residential buildings in the project—SOHO 10, SOHO 12 and NEFRYT—have recently been completed. The next phase of the development will focus on completing the commercial section, including new buildings, the renovation of historic structures and delivery of Class A office space and a PRS component.

M1 Radom adds new tenants as HalfPrice opens and CCC extends lease

M1 Radom has expanded its tenant mix with the addition of HalfPrice, while CCC has renewed its lease for several more years. According to EPP, which manages the centre, recently signed new and extended agreements cover more than 2,100 sq m.

HalfPrice is the largest of the new tenants, taking nearly 1,600 sq m. The retailer offers a mix of clothing, homeware, sports accessories and pet products from various brands. Other additions include SpecLed, a lighting specialist, and Poczta Polska, which increases the centre’s service offering.

CCC has extended its lease for a unit of over 500 sq m, continuing its long-standing presence at the centre. The retailer offers a broad footwear range for different customer groups.

EPP says the leasing decisions reflect ongoing adjustments to the centre’s offer in response to consumer demand in the region.

CBRE: Black Week launches peak retail trading period as Czech market enters pre-Christmas surge

Czech retail has entered its strongest trading period of the year with the start of Black Week, culminating in Black Friday on 28 November. According to CBRE, which manages a large portfolio of shopping and retail centres across the Czech Republic and tracks performance through its Shopping Centre Index, November promotions together with the Advent period form a critical phase for both offline and online retail.

CBRE notes that Singles’ Day, a fast-growing event in the Czech market, is increasingly extending the pre-Christmas demand cycle. The combination of earlier discounting, longer promotional campaigns and strengthening omnichannel behaviour is contributing to higher overall market activity. Retailers expect stronger turnover year-on-year, supported by wider product ranges and more coordinated campaigns.

The autumn trading calendar has now evolved into a clear sequence. Singles’ Day serves as the first demand trigger, affecting mainly fashion, beauty and small electronics, and is still driven primarily by online channels. This is followed by Black Week and Black Friday, which deliver the broadest discounts and the highest weekly traffic across both online and brick-and-mortar retail. The subsequent Advent weekends shift consumer attention from heavy discounting to gift shopping, winter assortments and experiential offerings in shopping centres.

Performance expectations vary by segment. Fashion retailers continue to see Black Friday gaining influence, while Advent remains stronger for Christmas and party collections. Footwear sales typically peak during Black Friday rather than Advent. Electronics retailers rely heavily on Black Friday to drive sales, but December often delivers greater turnover due to a shift in product mix. Beauty retailers report their strongest sales in December, with volumes significantly above standard months. Nutrition and supplements benefit from extended Black Friday and Advent campaigns, while the online share of Black Friday continues to expand across most categories.

Shopping centre footfall reflects this phased dynamic. Singles’ Day acts as the first signal of increased activity, though still more visible online. Visitor numbers rise markedly from the start of Black Week, peaking on Black Friday when major centres typically record double-digit increases compared with average Fridays. Footfall growth then continues into December, with the last Advent week remaining the high point of the season.

CBRE expects this year’s Christmas traffic to be broadly in line with 2024. The company notes a slight improvement in customer sentiment in the second half of the year, supported by rising real household incomes. December traditionally accounts for around 9–11% of total annual shopping centre traffic, with the final days before Christmas now representing the most intense period—a shift from pre-pandemic patterns, when the third Advent week usually dominated.

front page info
LATEST NEWS