Solida Capital Europe enters Romanian real estate market with acquisition of Victoria Center

On February 28, 2025, investment company Solida Capital Europe announced its entry into the Romanian real estate market with the acquisition of the Victoria Center office building from Manova Partners, formerly Macquarie Group. Colliers acted as the buyer’s advisor in the transaction.

Victoria Center is located on Calea Victoriei in the heart of Bucharest’s business district. The property offers approximately 8,600 square meters of premium office space and holds a BREEAM In-Use certification with an Excellent rating, reflecting its modern and sustainable design. It is home to leading tenants from the legal, IT, and financial services sectors, including Aon Romania, nShift, Botezatu Estrade & Asociații, and Eversheds Lina & Guia. Additionally, the Embassy of the United Mexican States in Romania recently selected the building as its headquarters. The Central Business District continues to be the most sought-after location in Bucharest, experiencing a nearly 20% rise in rental rates over the past two years, the highest increase in the city.

Joao Saracho, Managing Director of Solida Capital Europe, emphasized the strategic importance of this acquisition, describing it as part of the company’s broader plan to expand its real estate portfolio in Central and Eastern Europe. He noted that the investment aligns with Solida’s mission to capitalize on growth opportunities in dynamic markets and create value through asset management expertise. This transaction, the company’s first in Bucharest, signals further expansion opportunities in the region.

Colliers played a key role in facilitating the transaction, providing advisory services from the initial stages through to completion. Robert Miklo, Head of Capital Markets at Colliers, highlighted Solida Capital’s well-planned entry into the Romanian market and expressed confidence in the investment’s potential. He also emphasized Colliers’ anticipation of Solida’s continued expansion in the country. Stefania Baldovinescu, Senior Partner for Asset Services at Colliers, welcomed Solida Capital to the market and announced that Colliers would be providing property management services for Victoria Center.

The Romanian real estate investment market concluded 2024 with a total transaction volume of EUR 750 million, recording the highest transactional activity growth among the six largest economies in Central and Eastern Europe, including Bulgaria, the Czech Republic, Hungary, Poland, and Slovakia. Colliers consultants predict a strong performance for 2025, supported by an active transaction pipeline. Ongoing negotiations, valued at approximately EUR 500 million, suggest that investment volumes this year may surpass those of 2024.
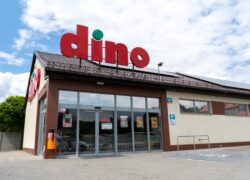
Dino Polska reports strong growth and expansion in 2024

Dino Polska concluded 2024 with remarkable growth, reporting a total revenue of PLN 29.3 billion, reflecting a 14.1% increase compared to the previous year. The company continued its rapid expansion, closing the year with 2,688 stores across Poland, demonstrating its strong market presence. To support its ongoing development, Dino allocated PLN 1.6 billion in capital expenditures while creating 8,000 new jobs, bringing the total workforce to 49,900 employees.

The fourth quarter of 2024 saw the opening of 116 new stores, contributing to a total of 283 new outlets throughout the year. With its distinctive red logo, Dino stores have become a trusted part of the Polish retail landscape, offering consumers a uniform shopping experience and easy access to essential groceries and daily necessities. By the end of the year, the total selling area of Dino stores expanded to 1,061.2 thousand square meters, marking a 12% growth from the previous year.

Capital investments in Dino’s development over the past five years reached PLN 6.6 billion, underlining the company’s commitment to long-term expansion. Fresh products remained a major revenue driver, accounting for nearly 40% of total sales. The category includes fruit, vegetables, bread, and fresh meat supplied by the Agro-Rydzyna meat processing plant. Dino’s well-structured logistics ensure that fresh products are delivered to stores every morning. The like-for-like (LfL) sales growth in stores operating for more than a year reached 5.3% in 2024.

In line with its sustainability efforts, Dino Polska continued to prioritize renewable energy, equipping newly opened stores with photovoltaic (PV) installations. By the end of 2024, 2,476 stores, representing 92% of the entire network, were outfitted with PV installations. The total renewable energy capacity within the Dino Group reached 98.9 MW, with 86.6 GWh of solar power sourced in 2024, marking a 30.5% increase from the previous year.

Dino Polska’s continued focus on expansion, efficiency, and sustainability reinforces its position as one of Poland’s leading retail chains, catering to growing consumer demand while advancing its environmental initiatives.

Polish microenterprise loan market in 2024: Challenges and Outlook for 2025

The microenterprise loan market in Poland faced significant challenges in 2024, with businesses grappling with high interest rates, rising energy costs, and increasing wage levels. By the end of December 2024, the value of the loan portfolio for microenterprises stood at PLN 74 billion, accounting for 14% of the total loan portfolio of enterprises and local governments. Despite a 6.2% increase in investment loans, the overall loan growth for microenterprises declined by 3.8%.

According to the Central Registration and Information on Business (CEIDG), approximately 2.5 million microenterprises were registered in Poland at the end of 2024. These small businesses, primarily operating in construction, services, trade, and production, faced an economic environment marked by inflation and shifts in consumer behavior. With individuals prioritizing savings over spending, lending to small businesses saw a decline. Moreover, Poland’s micro-companies continue to exhibit a low level of indebtedness, with only 17% of active businesses utilizing bank credit.

Microenterprise Loan Market Performance

At the close of 2024, microenterprise loan values reached PLN 74 billion, reflecting a 2.1% year-on-year increase. The debt structure was dominated by working capital loans (33.9%) and overdrafts (25.5%), indicating that nearly 70% of microenterprise debt was used for short-term financing. Investment loans, aimed at business development, accounted for only 23.8% of total debt. Service companies (41.0%) and commercial enterprises (29.4%) led in terms of loan allocation, making up more than 70% of microenterprise debt, followed by manufacturing (14.9%) and construction (13.0%).

Despite a rise in investment loan value, microenterprise lending declined by nearly 4% in 2024. Businesses secured loans worth PLN 22.0 billion, marking a 3.8% contraction. Investment loans grew by 6.2% in value, but the number of loans issued fell by 29.2%. Meanwhile, working capital loans and overdraft facilities saw declines of 9.9% and 8.9%, respectively, compared to 2023.

Sectoral Analysis: Service Sector Leads in Lending

Microenterprise lending patterns varied across industries. The service sector emerged as the top borrower, securing 72,800 new loans totaling PLN 8.5 billion, reflecting a 3% year-on-year increase. Rising electricity and gas prices significantly impacted the profitability of service-oriented businesses such as catering, hospitality, and beauty salons. However, the growing demand for experience-based services and increased income in this sector partially offset these challenges.

Commercial enterprises ranked second, receiving 33,700 loans amounting to PLN 5.72 billion, an 11.8% year-on-year decline. The sluggish retail sector, with sales increasing by just 2.7%, led consumers to cut discretionary spending, reducing the financial activity of micro-entrepreneurs in trade.

Manufacturing firms secured 15,200 loans worth PLN 3.16 billion, marking a 6.3% decline in loan count and a 7.3% drop in value. Rising labor costs, energy prices, supply chain disruptions, and a German economic slowdown posed significant challenges to Polish micro-manufacturers.

The construction industry, after years of high profitability, entered a slowdown in 2024. Loan values in this sector declined by 2.9% year-on-year to PLN 4.21 billion, with only 26,000 loans issued—a 3.7% drop. Workforce availability emerged as a key challenge, with competition for skilled labor driving up costs and pressuring margins.

Loan Repayment Quality and Risks

The quality of microenterprise loan repayments deteriorated, particularly for investment loans. At the end of 2024, 22% of investment loans were overdue by more than 90 days, an increase of 2.9 percentage points from the previous year. Investment loans became the second-most challenging loan type for micro-entrepreneurs to repay, after working capital loans (24.4% delinquency rate).

Conversely, slight improvements in loan repayment quality were observed in commercial, manufacturing, and construction sectors. The BIK Quality Index improved for commercial loans (+0.21), manufacturing loans (+0.32), and construction loans (+0.58), while the service sector experienced a marginal decline (-0.07).

Looking ahead to 2025, the microenterprise lending market remains uncertain, influenced by economic conditions, consumer confidence, and regulatory policies. While certain sectors show resilience, the broader market continues to face challenges in credit availability and repayment sustainability.

Source: BIK

Slovakia: Producer prices see varied trends in January 2025

The start of 2025 saw an acceleration in agricultural product price growth, while industrial producers continued to sell goods at lower prices compared to the previous year. Meanwhile, construction work prices increased at the slowest pace in more than three and a half years, marking the slowest growth since June 2021.

In January, agricultural producers experienced a significant rise in product prices, exceeding 7%, the highest increase since April 2023. In contrast, industrial producers sold goods at prices nearly 3% lower than a year ago.

Industrial Producer Prices

The prices of industrial producers for the domestic market were 2.5% lower year-on-year in January 2025. Only six of the 16 monitored industry sectors maintained lower prices. A significant factor in the overall decline was the 7.7% drop in energy prices. The production of coke and petroleum products also fell by 3.2%, while the prices in vehicle and metal production declined by 0.7%. On the other hand, water supply prices saw a 7.9% increase, and rubber and plastic production prices rose by 4.8%. In a month-on-month comparison, industrial producer prices for the domestic market increased by 0.4%.

For exports, industrial producer prices recorded a year-on-year increase of 1.4% and a month-on-month rise of 0.7%.

Agricultural Product Prices

In January 2025, agricultural product prices grew significantly by 7.6% year-on-year, with vegetable product prices increasing by 5.3%. Notably, cereals rose by 10.9%, pulses by 11.5%, and fruits and nuts by 14.3%. However, oilseeds and fruits experienced a slight decrease of 1.5%, while potato prices fell by 7.6%. Vegetable prices recorded a double-digit decline of 15.9%.

Animal product prices surged by 10.9% year-on-year, driven by increases in beef for slaughter, including calves (+6%), chicken eggs (+14%), and cow’s milk (+8.1%).

Construction Producer Prices

Construction work prices at the beginning of 2025 were 3.3% higher year-on-year and increased by 0.3% compared to December 2024. The cost of materials used in construction saw a month-on-month rise of 0.2% and was 1.9% higher year-on-year.

The data reflect mixed economic conditions, with agricultural and construction prices continuing their upward trajectory, while industrial producer prices remain under pressure from reduced energy and manufacturing costs.

Source: Statistical Office of the SR

Czech economy sees modest growth in Q4 2024

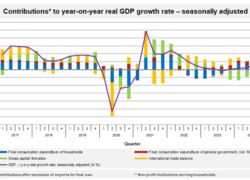
The Czech economy recorded moderate growth in the fourth quarter of 2024, with the gross domestic product (GDP) increasing by 0.7% quarter-on-quarter and 1.8% year-on-year, according to refined estimates. For the full year 2024, GDP rose by 1.0%.

Data from the Czech Statistical Office (CZSO) indicate that, after adjustments for price effects and seasonal factors, GDP in Q4 2024 was 0.7% higher than in the previous quarter and 1.8% higher compared to the same period in 2023.

Sectoral Performance and Gross Value Added

The gross value added (GVA) showed stagnation on a quarterly basis but increased by 1.1% year-on-year. In a quarter-on-quarter comparison, the strongest sectors included manufacturing (+1.0%), trade, transportation, accommodation, and food service activities (+0.4%), and real estate activities (+2.2%).

Year-on-year, the most significant contributors to GVA growth were trade, transportation, accommodation, and food services, which added 0.5 percentage points with a 3.0% increase, and real estate activities, which contributed 0.3 percentage points with a 2.1% rise. Construction also expanded, growing by 2.4% year-on-year. However, the industrial sector negatively impacted GVA growth, reducing it by 0.6 percentage points due to a 2.2% decline.

Demand-Side Factors Influencing Growth

On the demand side, higher household final consumption expenditure and changes in inventories played key roles in the quarter-on-quarter GDP increase. However, gross fixed capital formation and declining external demand had a negative effect, according to Vladimír Kermiet, Director of the National Accounts Department at CZSO.

Year-on-year GDP growth of 1.8% was mainly driven by household final consumption expenditure (+1.9 percentage points), government final consumption expenditure (+0.6 percentage points), and changes in inventories (+1.6 percentage points). Meanwhile, gross fixed capital formation (-0.7 percentage points) and external demand (-1.7 percentage points) contributed negatively.

Household final consumption expenditure increased by 1.5% quarter-on-quarter and 3.2% year-on-year, with non-durable goods purchases leading the growth. Government consumption decreased by 0.3% on a quarterly basis but rose by 3.2% year-on-year.

Gross fixed capital formation declined by 1.5% quarter-on-quarter and 2.4% year-on-year. Year-on-year growth was observed in investments in buildings, structures, and transport equipment, while other asset investments declined. The change in inventories amounted to CZK -79.5 billion, which was CZK 10.5 billion higher than in the same period in 2023.

Trade and Employment Trends

The international trade balance of goods and services at current prices stood at CZK 129.2 billion, an increase of CZK 5.1 billion compared to Q4 2023. Exports decreased by 1.5% quarter-on-quarter but rose by 1.3% year-on-year, driven mainly by electronic and optical products and electrical equipment. In contrast, exports of machinery, equipment, and motor vehicles declined. Imports fell by 1.8% quarter-on-quarter but grew by 3.1% year-on-year.

Regarding price developments in Q4 2024, the total GDP deflator increased by 0.3% quarter-on-quarter and 3.7% year-on-year.

Labour costs rose by 6.6% year-on-year in Q4 2024. Total employment decreased slightly by 0.1% quarter-on-quarter but showed a 0.2% increase year-on-year. The total number of hours worked remained unchanged compared to the previous quarter but grew by 0.5% year-on-year.

The data underscore the Czech economy’s resilience, albeit with challenges in industrial output and investment activity. Growth in household consumption and specific service sectors have helped sustain momentum despite external headwinds.

Source: Czech Statistical Office

ESG reporting deregulation to reduce costs for Polish and European companies

The European Commission has announced exemptions from ESG reporting requirements for more than 80% of companies, significantly reducing the regulatory burden. This decision is expected to bring substantial financial relief, with Polish companies projected to save nearly PLN 500 million in compliance costs. The number of Polish businesses required to report ESG metrics will decline from approximately 3,500 to 500.

At a European Commission conference, Commissioners Valdis Dombrovskis and Maria Luis Albuquerque presented the Omnibus package, which introduces significant ESG reporting deregulation. Under the proposed changes, only the largest companies will remain subject to reporting obligations, reducing the number of businesses covered by the Corporate Sustainability Reporting Directive (CSRD) across the EU from 50,000 to 10,000.

Analyses from Personnel Service indicate that the cost of ESG reporting has been a considerable expense for companies. The Chamber of Commerce of Central Europe estimates that businesses spend an average of EUR 40,000 (approximately PLN 164,000) on compliance. If all 3,500 Polish companies previously required to report had continued under the directive, total costs would have reached PLN 574 million. With the revised regulations, reporting expenses will decrease to PLN 82 million, resulting in estimated savings of PLN 490 million for Polish businesses.

Krzysztof Inglot, founder of Personnel Service, noted that easing ESG reporting obligations represents a financial relief for businesses already facing rising operational costs. While acknowledging the benefits of deregulation, he emphasized that responsible business practices should remain a priority and that reporting regulations should align with companies’ capabilities.

The Omnibus package still requires approval from the European Parliament and the Council before implementation. Once adopted, EU Member States will be required to incorporate the new regulations into their national legal frameworks. Additionally, the European Commission has announced plans to simplify the European Sustainable Development Reporting Standards (ESRS), further reducing compliance expenses for businesses.

Enefit opens electric vehicle charging stations at FORUM Shopping Centre in Gliwice

As of 28 February 2025, electric vehicle drivers can access new Enefit charging stations at the FORUM Shopping Centre in Gliwice. This expansion is part of Enefit’s broader initiative to enhance electromobility infrastructure in Poland. Enefit, a subsidiary of the Estonian energy group Eesti Energia, is one of the largest energy producers in the Baltic States and continues to develop its network of charging stations.

The newly launched charging stations at FORUM Shopping Centre include three units with different capacities: 120 kW, 47 kW, and 22 kW. These options cater to both fast-charging users and those making longer stops. Drivers can make payments via the Enefit Volt app or through a payment terminal, ensuring accessibility and ease of use. The charging stations are powered by energy certified as renewable.

According to Piotr Drożdżyk, Head of E-Mobility Solutions at Enefit, integrating charging stations with commercial facilities is a practical approach to supporting electromobility. By placing charging stations at shopping centres, users can conveniently charge their vehicles while shopping or attending meetings. Enefit has been expanding its public charging infrastructure since last year, with stations already operational in Bielsko-Biała and Zabrze. The Gliwice location marks another step in the company’s development strategy.

Shopping centre owners and managers also benefit from investments in charging infrastructure. Providing charging stations attracts new customers and aligns with sustainability initiatives. Patrycja Duczmal, Director of CH FORUM, noted that the installation of charging stations supports the centre’s ongoing commitment to environmentally friendly solutions.

Enefit currently operates 595 public charging stations across Estonia, Latvia, and Poland. The company aims to acquire locations for over 5,000 charging units by 2028, with half of them planned for installation in Poland.

Commercial property investments in Poland see significant growth in 2024

According to BNP Paribas Real Estate Poland’s report, ‘At a Glance. Investment Market in Poland in the Fourth Quarter of 2024,’ commercial property investment in Poland saw substantial growth, particularly in the final quarter of the year. The transaction volume doubled compared to 2023, reaching over EUR 5.05 billion. Despite ongoing geopolitical risks, the outlook for continued growth remains positive.

The office and retail sectors accounted for the highest share of total investment volume, each representing 32% of transactions. The office property market saw 45 transactions worth EUR 1.64 billion, four times more than the previous year. Meanwhile, investment in retail properties reached EUR 1.6 billion, with an average property size of 22,000 square metres, an increase of 7,500 square metres from 2023.

Industrial and logistics properties represented 25% of the commercial real estate market. Investment in this sector reached EUR 1.26 billion, marking a 30% increase compared to the previous year. U.S. investors were particularly active in this category, investing over EUR 350 million, accounting for nearly 28% of the annual transaction volume.

Interest in the residential sector for commercial rental also increased, with transactions totalling EUR 340 million, representing a 170% rise from the previous year. The strong transaction volume was largely driven by four major deals, including the sale of the Cromwell shopping centre portfolio and the transactions for Magnolia Park in Wrocław and Silesia City Center in Katowice. The sale of the Warsaw Unit office building also contributed significantly to the overall investment volume.

According to Mateusz Skubiszewski, Head of Capital Markets at BNP Paribas Real Estate Poland, while the 2024 results were bolstered by these large transactions, it remains uncertain if similar deals will occur in 2025. However, the market has shown signs of recovery, and increased activity is expected in mid-sized transactions valued between EUR 10 million and EUR 50 million.

Market Outlook for 2025

Analysts from BNP Paribas Real Estate Poland suggest that falling interest rates in the eurozone will encourage further investor activity. There has been an increase in capital inflows from the United States, the Czech Republic, and France. Additionally, Poland’s macroeconomic stability and planned spending under the National Reconstruction Plan for 2025–2026 are expected to support further investment.

Despite geopolitical uncertainties and the potential for trade conflicts, investors are showing interest in smaller properties with long weighted average lease terms (WAULT). While German and Asian capital remains largely inactive, domestic investors are becoming more engaged, and the market is anticipating the passage of the REIT Act, which could further stimulate investment.

By the end of 2024, the commercial property market appeared to have reached a balance between buyers and sellers. Capitalisation rates for key asset classes increased by 25 basis points. Based on current and planned transactions, analysts believe that this phase of the economic cycle has peaked and that investment returns in most asset classes are likely to improve in the coming quarters.

Major Transactions in 2024

In the retail property market, the largest transactions included the acquisition of Silesia City Center (88,000 sqm) and Magnolia Park (100,000 sqm) by NEPI Rockcastle for EUR 405 million and EUR 373 million, respectively. Czech Star Capital Finance acquired the Cromwell portfolio, comprising 219,000 sqm of retail space, for EUR 285 million.

The office property sector saw a resurgence in investor interest. The largest single-asset transaction was the purchase of the Warsaw Unit building by Eastnine AB from Ghelamco for approximately EUR 280 million. Other notable transactions included the acquisition of the P180 office building in Warsaw for EUR 100 million by Investika Real Estate Fund & BUD Holdings and the sale of 49% of the CPI portfolio by Sona Asset Management, covering 315,000 sqm of office space.

In the industrial and logistics sector, the most significant transaction was the purchase of the 7R portfolio for EUR 143 million by the Czech fund Investika. White Star acquired the Diamond Business Parks portfolio in Gliwice, Ursus, and Stryków for EUR 132 million. The most active seller in the sector was Panattoni, accounting for 40% of the total transaction volume, followed by 7R with a 19% market share.

The overall commercial property market in Poland showed strong growth in 2024, with investors demonstrating increased confidence. While uncertainties remain, the positive market outlook, falling interest rates, and stable economic conditions suggest further expansion in the coming year.

Source: BNP Paribas Real Estate Poland

Interview with Jakub Škaloud: Sustainable Innovations in the Construction Sector

This year marks five years since the European Parliament approved the Green Deal for Europe. How is the construction sector adapting to these sustainability goals?

Jakub Škaloud: The construction sector is a significant contributor to global carbon dioxide emissions, accounting for nearly 39%. Decarbonising buildings and improving their energy efficiency require continuous effort, and the pressure to reduce emissions from clients, financial institutions, and regulatory bodies is increasing. At VCES, we see this as an opportunity to innovate and proactively implement sustainability strategies.

What are the key obstacles that prevent some construction companies from adopting sustainable practices?

Jakub Škaloud: Many companies are concerned about high initial investments, the complexity of new technologies, or the lack of institutional support. However, a crucial first step is material selection, which significantly impacts the overall carbon footprint of a project.

How does material choice affect carbon emissions in construction?

Jakub Škaloud: Around 97% of CO2-equivalent emissions in the building sector come from indirect sources. Of these, approximately 55% stem from the operation of finished buildings, while the remainder is linked to construction materials. Since concrete and steel are the most widely used materials with a high carbon footprint, focusing on them can make a substantial difference.

What solutions have been effective in reducing emissions from concrete use?

Jakub Škaloud: The most commonly used cement, CEM I Portland cement, has the highest carbon footprint. By using alternative types like CEM II, CEM III, or CEM V, emissions can be reduced by up to 50%. While certain applications pose structural challenges, careful design allows for the adoption of lower-emission cement in a wide range of projects. At VCES, we have implemented these materials in multiple projects, including Nová Tesla in Pardubice and Tesla Hloubětín in Prague. Since 2021, we have reduced our use of CEM I cement by 99.3% and cut the overall carbon footprint of our concrete mixes by 22.3%.

What advancements are being made in sustainable steel production?

Jakub Škaloud: The production method has a significant impact. Traditional steelmaking involves blast furnaces, but an alternative process using electric arc furnaces can reduce emissions by over 35%. Since 2023, we have sourced 81% of our steel reinforcement from arc furnaces, reducing our steel-related carbon footprint by 28.6%.

Besides materials, what other steps can be taken to reduce the carbon footprint in construction?

Jakub Škaloud: Alternative construction methods, such as using timber structural systems, can lower carbon emissions by 20% compared to traditional reinforced concrete. Timber also improves indoor climate conditions and has health benefits. Recycling construction waste is another key strategy. At VCES, we use recycled concrete aggregate from demolition sites as a base material for new construction, reducing waste and emissions.

Modular construction is gaining traction. How does it contribute to sustainability?

Jakub Škaloud: Prefabricated solutions, such as modular bathrooms and installation shafts, enhance material efficiency and reduce waste. These techniques, common in Western Europe, are being introduced in the Czech market. We successfully implemented modular bathrooms at the Chrudimpark Residence, reducing time, labor, and emissions.

Carbon footprint calculations for buildings will become mandatory in 2028. How is VCES preparing for this?

Jakub Škaloud: We already voluntarily calculate the carbon footprint for every building we construct. The upcoming regulation will require documentation of these calculations for new buildings over 1,000 m2, expanding to all new buildings by 2030. Taking proactive steps now ensures compliance and enhances our competitiveness.

What long-term sustainability commitments has VCES made?

Jakub Škaloud: As part of Bouygues Construction, we have committed to reducing direct greenhouse gas emissions by 40% and indirect emissions by 30% by 2030. These targets align with the Paris Agreement and have been validated by the SBTi initiative. We continue adapting our processes to meet future environmental and client demands while setting an example for other companies in the industry.

Labour shortages in logistics and supply chains impact business operations

A recent study by Descartes Systems Group, titled ‘How Bad Is the Supply Chain and Logistics Workforce Challenge?’ (2024), highlights the ongoing labour shortages affecting the logistics industry. According to the report, 76% of organisations in the sector are facing significant staffing challenges, with 37% categorising the issue as severe or extreme. The study underscores the operational impact of these shortages, particularly in transport and warehouse processes, which are crucial for supply chain efficiency.

Transport operations are among the most affected, with 61% of respondents citing a shortage of professional drivers. Additionally, 56% of organisations report difficulties in maintaining adequate warehouse staff. These shortages not only disrupt daily operations but also hinder businesses’ ability to meet their objectives, especially during peak demand periods such as holiday seasons and promotional events.

The consequences of labour shortages extend beyond internal operations to customer service and financial performance. The report states that 58% of logistics respondents have experienced declines in service quality due to staffing issues. Delays in deliveries, order fulfilment errors, and reduced customer service capabilities have become prevalent challenges. As a result, logistics providers risk losing customer trust and incurring additional costs from complaints and corrective actions.

Jakub Kizielewicz, CEO of the Opteamic Group, a provider of logistics and production process outsourcing, notes that the labour shortages are significantly impacting businesses. He explains that companies reporting severe shortages often need to scale back services, leading to financial losses and reduced market competitiveness.

To address these challenges, many organisations are turning to technological solutions such as automation and robotisation of warehouse processes. Advanced analytics tools are also being integrated to optimise supply chain operations. However, 55% of industry leaders indicate that hiring skilled workers who can operate and manage these technologies remains a major challenge.

Flexible employment solutions are emerging as another strategy to mitigate workforce shortages. Outsourcing logistics processes and employing temporary workers provide businesses with greater adaptability, especially during periods of high demand. According to Kizielewicz, adopting a flexible approach to workforce management enables companies to maintain operational efficiency without committing to permanent staff increases.

The Descartes report underscores the need for a comprehensive response to workforce challenges in supply chains. Businesses must invest in both technological advancements and strategic human resource management to navigate the increasing demands of the market. Collaborating with specialised agencies for process outsourcing and temporary staffing may play a crucial role in building resilience against labour shortages.

front page info
LATEST NEWS