Sunday, 20 September 2026
Singapore’s office market is developing a widening gap between the amount of space technically available and the type of space businesses increasingly want to occupy. At the end of the second quarter of 2026, the islandwide office vacancy rate stood at 11%, up slightly from 10.8% in the first quarter, yet availability among the best buildings in the central business district was only a fraction of that level. The headline increase did not signal a broad retreat by office users: occupied space actually increased by a net 8,000 sqm during the quarter, while completed stock expanded by 19,000 sqm. The addition of Shaw Tower also affected the figures because the property entered the completed inventory before all committed occupiers had finished their interiors and moved in.
At the premium end of the market, conditions are considerably tighter. CBRE measured vacancy in its Core CBD Grade A portfolio at 3.3% in the second quarter, while Colliers reported the same rate for the premium and Grade A properties included in its central business district research. Other advisers use different building samples and definitions: Cushman & Wakefield placed CBD Grade A vacancy at 4.7%, with Marina Bay considerably tighter at 2.1%. Rather than contradicting one another, these figures demonstrate how significantly availability changes according to the quality and location of the buildings being measured.
Corporate requirements are helping to create this divide. Companies searching for premises are increasingly concentrating on properties combining central locations with efficient floors, modern technical systems, strong environmental performance, convenient public transport and facilities suited to contemporary working practices. As demand becomes concentrated within this narrower group of buildings, a substantial portion of Singapore’s vacant office stock is competing for a different pool of tenants from the newest and best-positioned properties.
The imbalance is increasingly visible in rents. CBRE recorded Core CBD Grade A rents at S$12.50 per sq ft per month in the second quarter, an increase of 0.8% from the previous three months. Colliers measured rents in its premium and Grade A central portfolio at S$12.23, representing quarterly growth of 1.9%, while other major advisers also reported increases. Limited construction could maintain this pressure, with relatively little major prime office space scheduled for the remainder of 2026 and during 2027. Newport Tower is among the limited additions expected next year, while more substantial developments sit further out in the pipeline.
The other side of this trend is becoming increasingly important for investors. Older offices lacking modern specifications, efficient layouts, strong transport accessibility or competitive sustainability performance risk losing tenants to newer alternatives. Instead of benefiting automatically from an otherwise healthy Singapore office market, these properties increasingly have to demonstrate why businesses should remain when leases come up for renewal. Owners may therefore need to invest in building systems, environmental performance, common areas and workplace facilities simply to maintain their competitive position.
For some ageing properties, refurbishment will be sufficient, but others may require much deeper intervention. Where structural limitations make it difficult or uneconomic to meet current occupier expectations, redevelopment or conversion could become more attractive. Singapore’s planning strategy is already encouraging renewal in older parts of the CBD, providing opportunities for qualifying commercial properties to be substantially redeveloped and, in certain circumstances, combined with residential, hotel or other uses. Robinson Road, Shenton Way, Cecil Street, Anson Road and Tanjong Pagar are among the areas where this transformation could become increasingly visible.
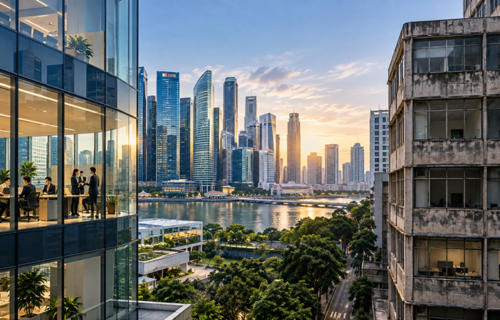
Singapore consequently has two office-market stories unfolding simultaneously. At the broad market level, around 11% of office space is vacant, suggesting ample availability. At the premium end, however, businesses face a much smaller selection of suitable space while rents continue to rise and immediate new supply remains constrained. The widening distance between these markets suggests that Singapore’s next office challenge will not simply be producing additional buildings, but determining how to reposition the substantial stock that increasingly struggles to meet what modern occupiers want.
Source: CIJ.World Research & Analysis Team